
 Global Polyurethane Dispersions Market | 2026-2036
Global Polyurethane Dispersions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyurethane Dispersions Market Foresight
Modular formulation kits that bundle base resins with tailored crosslinkers and additives are restructuring how mid-sized coatings buyers configure their procurement. Covestro AG leverages its backward integration into isocyanate precursors to sustain margin control across waterborne grades. Wanhua Chemical Group Co. Ltd. anchors volume supply for Asia-Pacific adhesives producers. BASF SE differentiates through specialty dispersions targeting automotive OEM color-match requirements.
Polyurethane dispersions are aqueous colloidal suspensions of polyurethane particles, typically 0.01–10 microns in diameter, stabilized by internal ionic groups or external surfactants, synthesized through prepolymer emulsification or acetone process routes. These systems serve as film-forming binders delivering abrasion resistance, flexibility, and adhesion in coatings, adhesives, and textile finishing without volatile organic carrier solvents. Waterborne dispersions occupy the dominant value share as environmental compliance tightens across formulated product sectors. UV-curable dispersions represent the fastest-expanding technology segment, capturing margin pools in high-throughput furniture and flooring lines where instant cure offsets capital investment. Solventborne grades retain niche positions in specialty textile laminates where hydrolysis resistance demands exceed aqueous system capabilities.
EPA VOC regulations for architectural and industrial maintenance coatings restrict solvent content, directly accelerating waterborne polyurethane dispersion substitution in US formulations. REACH restrictions on isocyanate monomer exposure, supplemented by EU Green Deal carbon-border adjustments, reshape import competitiveness and domestic production economics for European coating compounders. China's MEE enforcement of GB standards on industrial coatings emissions drives domestic reformulation toward low-VOC aqueous systems. Stakeholders must monitor regulatory divergence between jurisdictions to align product registration strategies and avoid stranded formulation assets.
Market Dynamics
Waterborne polyurethane dispersion technology is modularizing across coating formulation workflows, compressing batch customization cycles and forcing solvent-based system obsolescence under tightening VOC mandates in automotive and furniture finishing.
Growth Catalysts
- EPA VOC regulations for architectural coatings:Federal emission ceilings for industrial maintenance formulations accelerate aqueous polyurethane substitution in US manufacturing.
- Automotive interior finishing:OEM sustainability mandates phase out solvent carriers, pulling waterborne dispersion demand for dashboards and seating applications.
- UV-curable dispersion chemistry:Instant-cure technology captures high-throughput furniture lines where capital investment offsets energy and floor-space costs.
Market Restraints
- Isocyanate feedstock concentration:Tight supply of aliphatic diisocyanate precursors concentrates in Chinese and German chemical clusters, exposing compounders to input volatility.
- Hydrolysis performance ceiling:Aqueous systems fail textile laminate specifications requiring prolonged moisture resistance, ceding share to solventborne grades in outdoor apparel.
- REACH authorization timelines:ECHA substance evaluation delays for novel crosslinker chemistries extend product registration cycles for European formulators.
Strategic Opportunities
- India industrial coatings reformulation:BIS adoption of low-VOC standards for automotive and protective coatings creates first-mover positioning for waterborne dispersion suppliers.
- Modular kit distribution:Pre-configured base resin and additive bundles enable mid-sized coatings buyers to bypass technical service bottlenecks.
- EU Green Deal carbon-border adjustments:Import levies on high-carbon coating imports favor domestic European polyurethane dispersion production.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in colloidal stability and film-formation kinetics concentrates at large multinationals, constraining mid-tier R&D expansion.
- Legacy equipment retrofit costs:Converting solvent-based spray lines to aqueous-compatible drying and curing infrastructure demands capital outlays that strain smaller coaters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyurethane Dispersions Market |
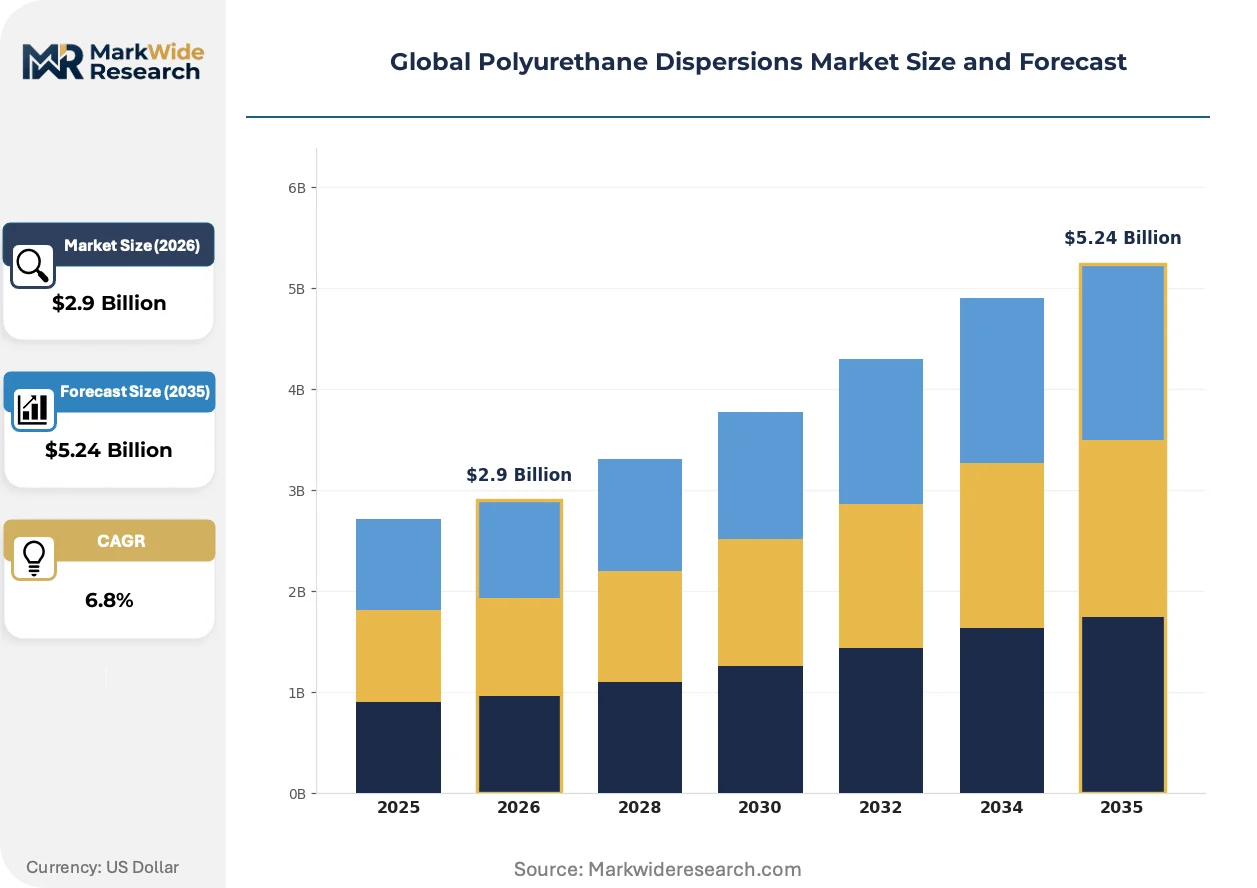
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.24 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterborne Dispersions, Solventborne Dispersions, UV-Curable Dispersions, Hot Melt Dispersions End Use Industry: Coatings, Adhesives, Textiles, Construction Application: Automotive Interiors, Flooring, Furniture, Consumer Goods Technology: Micro-Encapsulation, Spray Coating, Roller Coating, Extrusion |
| Companies Covered | Covestro AG, BASF SE, Dow Inc., Lubrizol Corporation, Mitsui Chemicals Inc., Alberdingk Boley GmbH, Wanhua Chemical Group Co. Ltd., Huntsman Corporation, Coim Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyurethane Dispersions Market Shifts & Advancements
Formulation technology is fragmenting into configurable component systems while regulatory pressure compresses permissible solvent content and procurement patterns favor suppliers offering integrated technical service.
Prepolymer emulsification routes are modularizing into standardized building blocks that compounders combine with tailored crosslinkers and rheology modifiers at point-of-use. Automotive refinish shops and mid-sized industrial coaters adopt these kits to reduce inventory SKUs and accelerate color-matching turnaround. This architecture compresses technical service dependencies and shifts margin capture toward base resin producers with backward integration into isocyanate precursors.
China's MEE enforcement of GB standards on industrial coatings emissions forces domestic reformulation toward aqueous polyurethane systems. Provincial environmental inspections in Jiangsu and Guangdong shutter non-compliant solvent-based operations, consolidating demand among certified waterborne suppliers. Export-oriented Chinese adhesive producers now source dispersions domestically rather than importing European grades, reshaping Asia-Pacific trade flows.
Coatings procurement is consolidating around suppliers offering embedded formulation support and regulatory documentation packages. Large automotive OEMs and furniture manufacturers bypass distributors to contract directly with dispersion producers capable of certifying compliance across multiple jurisdictions. This disintermediation is most visible in Germany and the United States, where tier-one suppliers demand REACH and EPA pre-registration data as table stakes for contract consideration.
Global Polyurethane Dispersions Market Segmentation
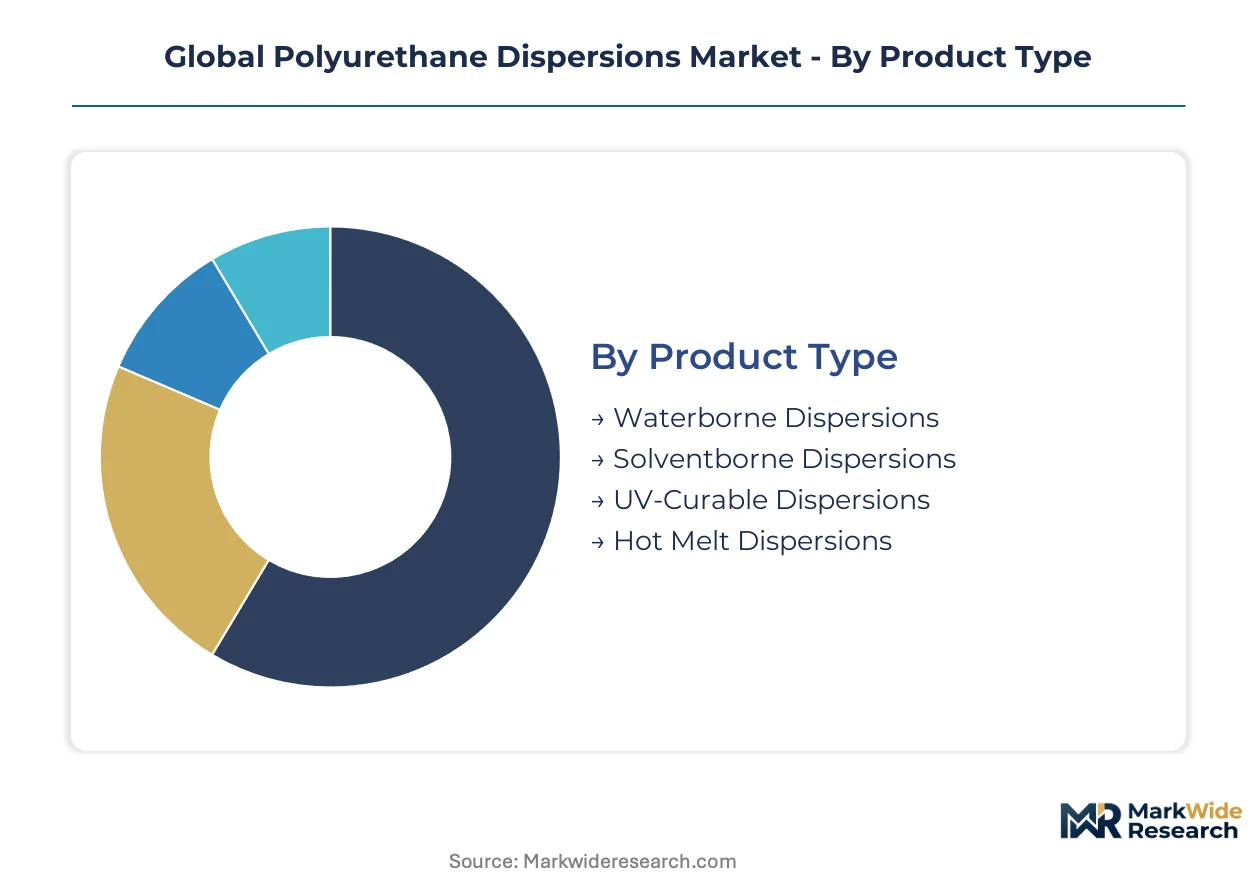
Polyurethane dispersions fragment across four structural dimensions that determine formulation economics and regulatory compliance pathways. Each segmentation axis carries distinct certification burdens, margin profiles, and supply chain requirements that reshape procurement decisions for compounders and end-users.
Product Type:
EPA VOC ceilings for architectural coatings and REACH substance authorizations impose divergent compliance costs across aqueous, solvent, and radiation-cure systems. Waterborne grades face GB standard enforcement in China and EPA emission limits in the United States, while UV-curable chemistries navigate novel crosslinker registrations under ECHA evaluation timelines.
- Waterborne Dispersions:Aqueous colloidal suspensions stabilized by internal ionic groups or external surfactants, delivering abrasion resistance and flexibility without volatile organic carriers. Demand concentrates in automotive interior coatings across Germany, China, and the United States as OEMs phase out solvent-based systems under tightening VOC mandates. EPA and MEE enforcement accelerate substitution in manufacturing formulations.
- UV-Curable Dispersions:Photoinitiator-functionalized systems enabling instant cure under UV/LED exposure, capturing high-throughput furniture and flooring lines where energy and floor-space savings offset capital investment. ECHA authorization timelines for novel photoinitiators extend registration cycles for European compounders seeking to deploy these chemistries.
- Solventborne Dispersions:Retain niche positions in specialty textile laminates where hydrolysis resistance demands exceed aqueous system capabilities, particularly in outdoor apparel specifications.
- Hot Melt Dispersions:Reactive systems applied in molten state without solvent carriers, serving adhesive applications requiring immediate green strength and thermal processing compatibility.
Waterborne dispersions sit at the top of the volume ranking, with UV-curable grades climbing the fastest as furniture manufacturers prioritize throughput economics.
End Use Industry:
Application-specific performance requirements drive tiered pricing structures across coating, adhesive, and textile segments, with construction applications commanding premium formulations for durability specifications.
- Coatings:Film-forming binders for automotive, industrial, and decorative finishes where abrasion resistance and aesthetic durability determine specification. Chinese provincial environmental inspections in Jiangsu and Guangdong consolidate demand among certified waterborne suppliers.
- Adhesives:Bonding systems for flexible packaging, footwear, and assembly applications where peel strength and heat resistance balance formulation cost. Export-oriented Chinese producers now source dispersions domestically rather than importing European grades.
- Textiles:Finishing treatments for apparel and technical fabrics requiring soft hand feel combined with wash durability, with outdoor segments retaining solventborne share for hydrolysis performance.
- Construction:Sealants, membranes, and protective coatings where weathering resistance and substrate adhesion justify higher formulation investment in commercial and infrastructure projects.
Coatings generate the largest absolute volume, while construction applications expand most quickly on infrastructure spending acceleration.
Application:
End-use specifications fragment by curing infrastructure, color-matching complexity, and regulatory exposure, with automotive and furniture segments driving modular kit adoption.
- Automotive Interiors:Dashboard, seating, and trim coatings where OEM sustainability mandates phase out solvent carriers and demand precise color-match capabilities across multiple substrate types. Tier-one suppliers in Germany and the United States contract directly with dispersion producers capable of certifying compliance across jurisdictions.
- Flooring:Wood, resilient, and textile floor coverings where UV-curable dispersions enable high-throughput finishing lines with instant cure reducing work-in-process inventory.
- Furniture:Residential and contract furniture finishing where mid-sized coaters adopt pre-configured base resin and additive bundles to reduce inventory SKUs and accelerate color-matching turnaround.
- Consumer Goods:Electronics housings, personal care packaging, and sporting equipment where abrasion resistance and aesthetic properties balance cost constraints in high-volume manufacturing.
Automotive interiors command premium positioning, with flooring applications gaining share fastest on UV-cure technology diffusion.
Technology:
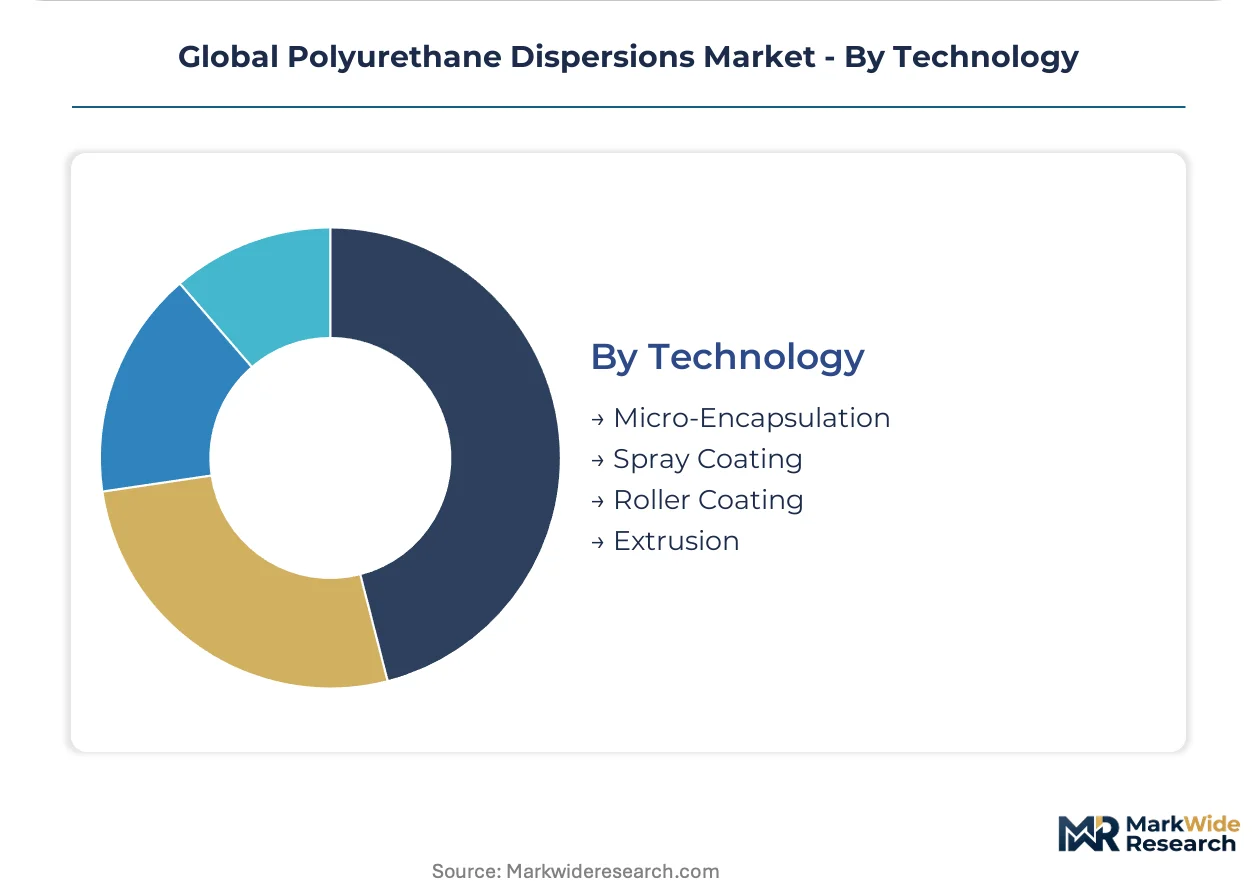
Process selection determines capital intensity, film thickness control, and substrate compatibility, with spray and roller methods dominating coating workflows while extrusion serves adhesive compounding.
- Micro-Encapsulation:Core-shell particle architectures enabling controlled release of active ingredients or phase-change materials, extending dispersion utility beyond conventional film-forming into functional coatings.
- Spray Coating:Atomized application for complex three-dimensional substrates and automotive interior components where uniform coverage across contours determines quality acceptance.
- Roller Coating:Direct transfer methods for flat panel furniture and flooring substrates where high deposition efficiency and minimal overspray reduce material waste.
- Extrusion:Continuous processing for hot melt adhesive compounding and reactive system preparation, integrating dispersion into pressure-sensitive and structural adhesive manufacturing.
Spray coating retains the highest volume position, with micro-encapsulation demonstrating the steepest expansion trajectory on functional coating development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial polyurethane chemistry in the 1930s, establishing the technical foundation that spread to North American and Asian production bases. Today formulation demand concentrates in manufacturing clusters where automotive OEMs and industrial coaters operate under tightening emission ceilings.
United States
Automotive interior finishing drives aqueous dispersion demand as Detroit-area OEMs phase out solvent carriers for dashboards and seating. EPA VOC regulations for architectural and industrial maintenance coatings accelerate substitution in Midwest manufacturing formulations. Coatings procurement in Michigan and Ohio consolidates around suppliers certifying REACH and EPA pre-registration data.
Germany
Tier-one automotive suppliers in Baden-Württemberg and Bavaria contract directly with dispersion producers for color-match capabilities across multiple substrates. REACH restrictions on isocyanate monomer exposure reshape domestic production economics for coating compounders. The Rhine-Ruhr chemical cluster anchors European supply of aliphatic diisocyanate precursors.
China
Provincial environmental inspections in Jiangsu and Guangdong shutter non-compliant solvent-based operations, consolidating demand among certified waterborne suppliers. MEE enforcement of GB standards on industrial coatings emissions forces domestic reformulation toward low-VOC aqueous systems. Export-oriented adhesive producers in the Yangtze River Delta now source dispersions domestically rather than importing European grades.
India
BIS adoption of low-VOC standards for automotive and protective coatings creates first-mover positioning for waterborne dispersion suppliers. Maharashtra and Gujarat industrial coaters face accelerating reformulation timelines as emission norms tighten. Mumbai-Pune automotive corridor demand pulls technical service investment from multinational suppliers.
Japan
Precision electronics and automotive component finishing sustain premium-grade dispersion demand in the Kanto and Kansai industrial belts. METI chemical management frameworks push low-emission formulation adoption in Osaka-area manufacturing. Japanese adhesive producers source specialized grades for flexible packaging applications.
Global Polyurethane Dispersions Market Competitive Landscape
Premium-margin players sit above commodity-margin players across backward integration depth and technical service bundling. The vendor base separates into three tiers: multinational chemical conglomerates with captive isocyanate supply, regional specialists with formulation expertise, and commodity traders distributing standard grades. Dominant competitive moves include capacity expansion in Asia-Pacific manufacturing hubs and strategic partnerships embedding regulatory documentation into supply contracts.
Among German-headquartered chemical conglomerates, Covestro AG and BASF SE exemplify premium-tier positioning through upstream control over isocyanate precursors. Wanhua Chemical Group Co. Ltd. anchors volume supply for Asia-Pacific adhesives producers from its Chinese manufacturing base. These three entities represent distinct archetypes: backward-integrated multinational, specialty dispersion differentiator, and scale-driven regional supplier.
| Leading Market Players |
|---|
| Covestro AG |
| BASF SE |
| Dow Inc. |
| Lubrizol Corporation |
| Mitsui Chemicals Inc. |
| Alberdingk Boley GmbH |
| Wanhua Chemical Group Co. Ltd. |
| Huntsman Corporation |
| Coim Group |
| Others |
Supply & Pricing Matrix
Backward-integrated chemical conglomerates in Germany and China anchor supply discipline through captive isocyanate production, translating feedstock control into pricing power over mid-sized compounders lacking upstream integration. This ownership pattern compresses margin capture toward resin producers while forcing independent formulators into cost pass-through vulnerability during aliphatic diisocyanate tightness.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with automotive OEM color-match specifications commanding substantial premiums over generic industrial grades. Price differentiation hinges on REACH pre-registration documentation and backward integration depth, with pricing pressure intensifying as Chinese domestic capacity expansion erodes import parity for European grades. Mid-sized furniture coaters exhibit highest price sensitivity due to legacy equipment retrofit burdens, while tier-one automotive suppliers prioritize compliance certification over unit cost.
Supply Chain Analysis
Reverse-logistics flows for solvent recovery and crosslinker returns remain underdeveloped, concentrating circular economy risk with forward-only material movement from German and Chinese precursor hubs. Geographic supply concentration centers on the Rhine-Ruhr chemical cluster, Jiangsu province manufacturing corridors, and US Gulf Coast isocyanate assets. Raw material dependencies draw from MDI, TDI, and specialty polyol feedstocks, with single-source vulnerability in aliphatic diisocyanate precursors exposing compounders to input volatility. Distribution runs through direct OEM contracts disintermediating traditional distributors, particularly in Michigan and Baden-Württemberg automotive corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA VOC ceilings and REACH authorization timelines continuously force formulation refresh cycles, converting compliance burden into sustained demand for certified waterborne grades.
For Market Incumbents: Lock in tier-one automotive contracts through embedded technical service and multi-jurisdiction regulatory documentation, defending against modular kit suppliers eroding technical service dependencies. Prioritize capacity addition in Jiangsu province to capture Chinese domestic reformulation demand while deepening backward integration into specialty isocyanate precursors to sustain margin control.
For New Entrants and Emerging Players: E-commerce-enabled modular kit distribution offers direct access to mid-sized furniture coaters bypassing incumbent technical service bottlenecks. Target Indian industrial coatings reformulation as BIS low-VOC standards create first-mover positioning, leveraging domestic compounding partnerships to shortcut registration timelines.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with formulation expertise but lacking isocyanate backward integration, presenting consolidation targets for chemical conglomerates seeking Asia-Pacific footprint. Long-term viability centers on regulatory divergence management capabilities; monitor ECHA substance evaluation delays and MEE enforcement intensity as inflection indicators for European versus Chinese demand trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Precursors | Captive MDI supply insulates Covestro and Wanhua from feedstock volatility affecting independent compounders. |
| Modular Formulation Kit Expansion | Pre-configured base resin bundles reduce inventory SKUs for mid-sized coaters in furniture finishing. |
| China Domestic Capacity Buildout | Jiangsu province expansion captures reformulation demand from shuttered solvent-based operations under MEE enforcement. |
| REACH Pre-Registration Data Packaging | Embedded regulatory documentation enables direct OEM contracts disintermediating distributors in Germany. |
| UV-Curable Dispersion Technology Licensing | Photoinitiator-functionalized systems penetrate high-throughput flooring lines seeking instant cure economics. |
Research Methodology
Multiple input streams — formulation chemist interviews, procurement lead surveys, and regulatory filing analysis — were reconciled against customs trade data and SEC chemical segment disclosures to construct demand estimates. Primary fieldwork engaged technical R&D directors at dispersion producers, procurement managers at tier-one automotive suppliers, plant managers at Chinese adhesive compounders, and distribution channel partners across European coating workflows. Secondary validation drew from EPA VOC rulemaking dockets, ECHA substance evaluation timelines, MEE GB standard enforcement records, and Cefic industry statistics. Bottom-up volume estimates by application and grade tier were cross-checked against top-down chemical consumption models.
Historical volume trajectories were cross-referenced against panel input from industry participants to anchor growth assumptions across the projection horizon. The analytical framework modeled segmentation dimensions spanning product type, end-use industry, application, and technology, with additional resolution by regional production hub and certification tier. CAGRs were derived from regression analysis of historical substitution patterns and regulatory enforcement intensity, incorporating isocyanate precursor supply elasticity and OEM sustainability mandate adoption curves as industry-specific forecast inputs.
Feedstock price volatility, regulatory enforcement timing shifts, and modular kit adoption acceleration are the dominant revision risks to demand projections. Practitioners should monitor aliphatic diisocyanate spot market tightness and provincial environmental inspection intensity in Jiangsu and Guangdong for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
C9 Resin Market
Polymers & Resins
Rosin Resin Market
Polymers & Resins
Global Polymer Dispersion Market
Polymers & Resins
Global Cyanate Ester Resins Market
Polymers & Resins
Global Bio Based Polyurethane Market
Polymers & Resins
Plastic Calendering Resins Market
Polymers & Resins
PVDF Resin Market
Polymers & Resins
Cathodic Acrylic Market
Polymers & Resins
Isosorbide-Based Engineering Polymer Monomers Market
Polymers & Resins
Polyisobutylene (PIB) Market
Polymers & Resins
Global Microcellular Polyurethane Foam Market
Polymers & Resins
Extruded Polystyrene Market
Polymers & Resins
Polybutene-1 Market
Polymers & Resins
Middle East and Africa Polyurethane Market
Polymers & Resins
Cross-Linked Polyethylene (XLPE) Market
Polymers & Resins
Global Acrylic Solid Surface Market