
 North America Polymer Emulsion Market | 2026-2036
North America Polymer Emulsion Market Size, Share, and Industry Trends Forecast 2026-2036
North America Polymer Emulsion Market Analytics
A capital-intensity divergence between integrated petrochemical giants and specialty chemical operators is redrawing competitive boundaries in North America. BASF leverages its backward integration into acrylic monomers to sustain margin stability across coating-grade emulsions. Dow anchors its position through large-scale vinyl acetate-ethylene capacity along the US Gulf Coast, while Arkema differentiates via high-performance waterborne polyurethane dispersions for automotive refinishing.
Polymer emulsion denotes a colloidal dispersion of polymer particles, typically 50-500 nanometers in diameter, stabilized by surfactants in a continuous aqueous phase and manufactured through free-radical emulsion polymerization at 60-90°C. These systems serve as binders in water-based coatings, adhesives, and sealants, replacing solvent-borne alternatives to meet air-quality mandates. Acrylic emulsions dominate architectural coatings due to exterior durability and UV resistance, while polyurethane dispersions command premium positioning in automotive and textile lamination where flexibility and chemical resistance prove critical. Vinyl acetate emulsions occupy high-volume, cost-sensitive construction adhesive segments with mature growth profiles.
EPA VOC regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based formulation options, redirecting R&D investment toward waterborne and hybrid systems. Health Canada and the PMRA enforce parallel chemical substance restrictions that affect cross-border product registration and labeling requirements. Stakeholders must monitor evolving state-level air-quality mandates in California and New York that frequently precede federal standards, while positioning formulation portfolios for anticipated tightening of formaldehyde and residual monomer limits.
Market Dynamics
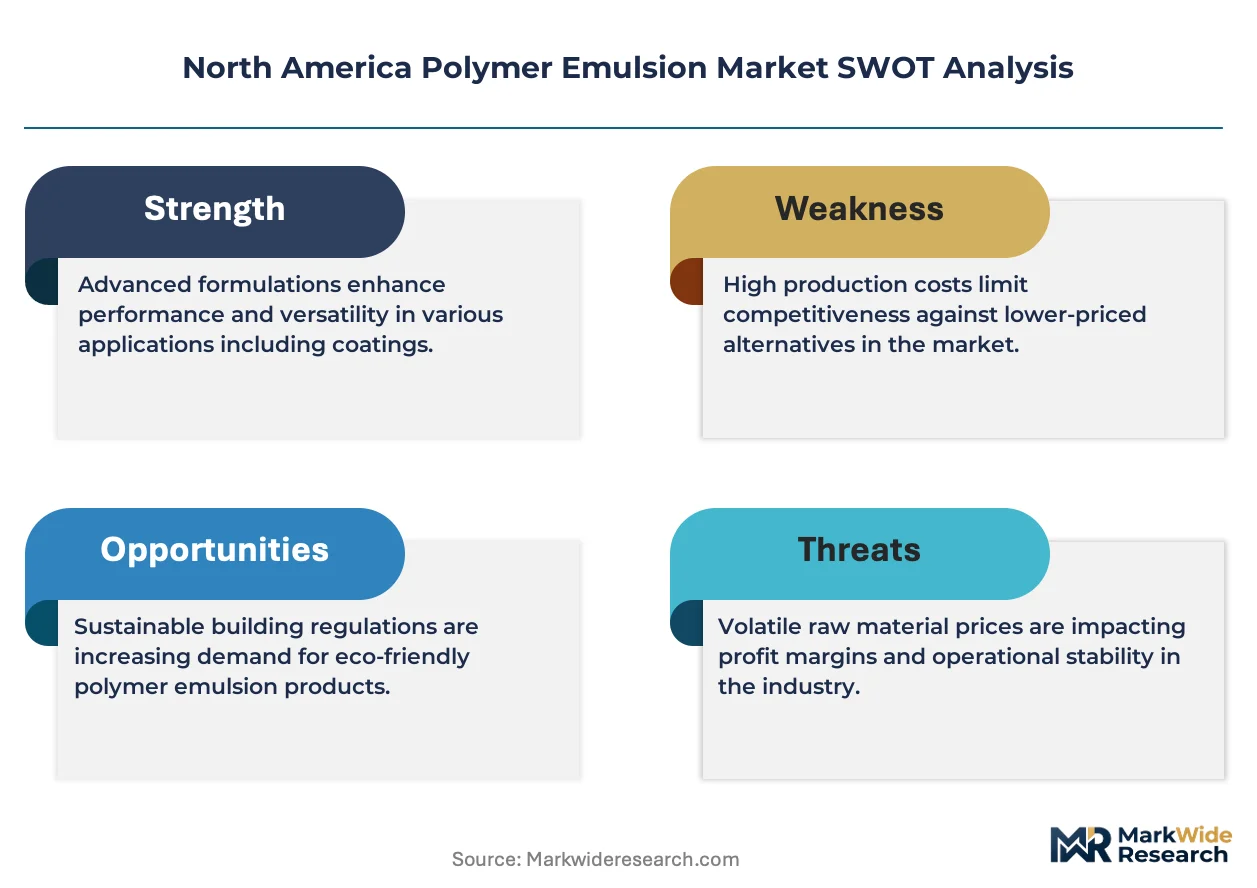
EPA VOC restrictions under the National Emission Standards for Hazardous Air Pollutants are forcing formulators to abandon solvent-borne systems faster than raw material substitution economics would otherwise dictate.
Growth Catalysts
- California Air Resources Board mandates:Builders in Los Angeles and San Francisco metro areas now specify low-VOC architectural coatings for commercial projects, pulling waterborne acrylic demand ahead of federal minimums.
- Automotive refinishing waterborne transition:Collision repair shops across Ontario and Quebec face Health Canada enforcement of workplace chemical exposure limits, accelerating polyurethane dispersion adoption for basecoat applications.
- Vinyl acetate-ethylene capacity expansion:Integrated producers along the Texas Gulf Coast have added emulsion-grade VAM output, improving regional supply security for construction adhesive compounders.
Market Restraints
- Propylene and acrylic acid feedstock volatility:Gulf Coast monomer pricing swings directly compress margin stability for non-integrated emulsion manufacturers.
- Freeze-thaw stability technical ceiling:Waterborne systems still fail performance thresholds for exterior wood coatings in Minnesota and Manitoba winter exposure cycles.
- Cross-border registration friction:Health Canada PMRA and EPA divergent residual monomer testing protocols force dual compliance spend for suppliers serving both markets.
Strategic Opportunities
- Mexico construction chemicals underpenetration:Waterborne coating share in Mexican residential construction remains below US levels, offering expansion runway for regional formulators.
- Hybrid epoxy-acrylic technology convergence:Industrial maintenance contractors seek single-coat systems combining corrosion resistance with application ease, opening formulation white space.
- US Inflation Reduction Act efficiency incentives:Commercial building envelope retrofits qualifying for tax credits specify high-performance air barrier coatings, creating specification pull for advanced emulsions.
Industry Challenges
- Emulsion polymerization process control talent scarcity:Operating free-radical reactors at scale requires expertise that has not kept pace with capacity expansion in the US Gulf Coast corridor.
- Green chemistry certification timeline compression:EPA Safer Choice and USDA BioPreferred label attainment now demands 18-24 month validation cycles that outpace product development calendars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Polymer Emulsion Market |
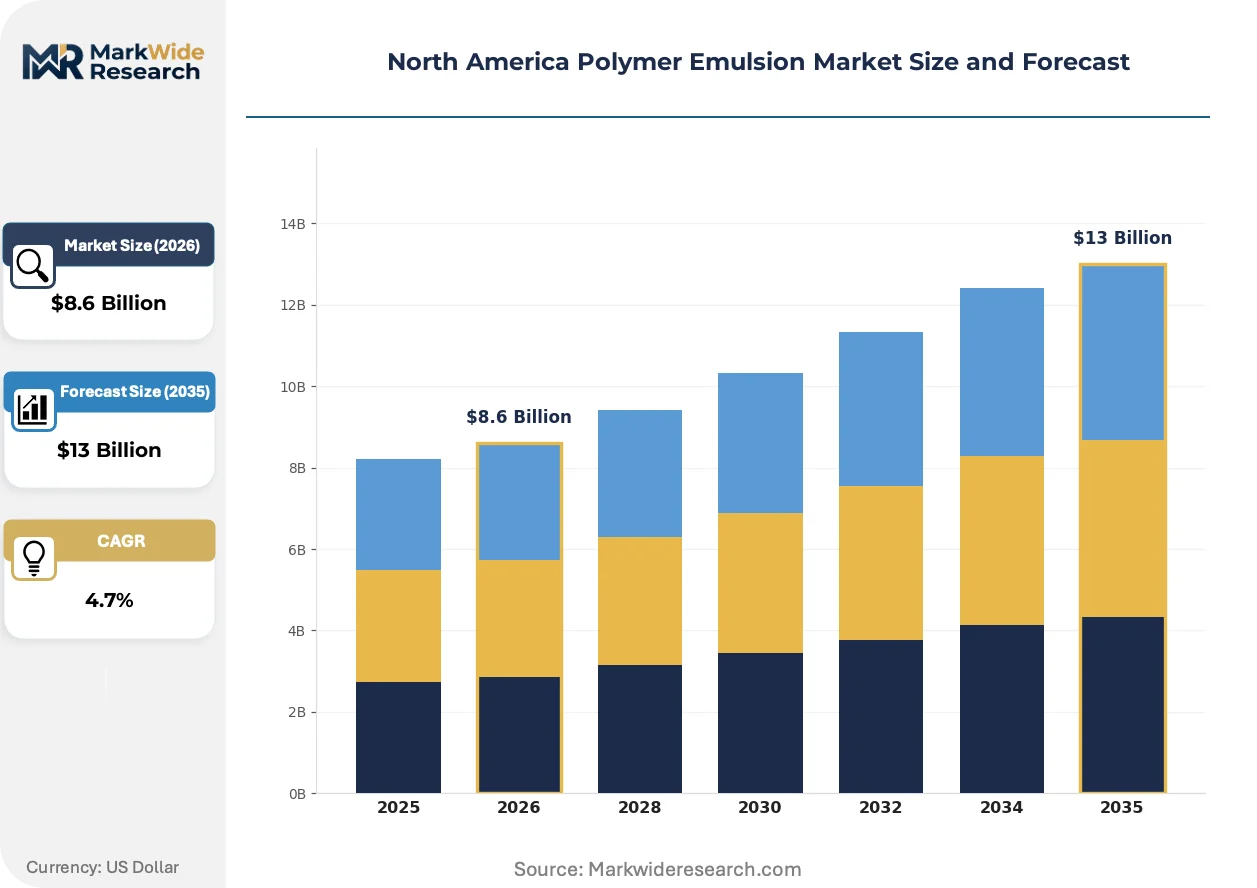
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylics, Vinyl Acetate, Styrene-Butadiene, Polyurethane End Use Industry: Construction, Automotive, Textile, Coatings Technology: Batch Process, Continuous Process, Emulsion Polymerization, Solution Polymerization Formulation: Water-Based, Solvent-Based, Hybrid Systems, Pigmented |
| Companies Covered | BASF, Dow, Arkema, Celanese Corporation, Wacker Chemie AG, Synthomer PLC, Lubrizol, 3M, Akzo Nobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Polymer Emulsion Market Evolving Landscape
Waterborne technology platforms are fragmenting into specialized performance tiers as end-users reject one-size-fits-all formulations. Formulators now compete on application-specific durability metrics rather than generic VOC compliance alone.
Self-crosslinking acrylic technology is decomposing the traditional trade-off between block resistance and flexibility in wood furniture coatings. Cabinet manufacturers in North Carolina and Quebec are adopting these systems at pace, eliminating the need for separate primer-topcoat sequences. This convergence is decomposing established SKU architectures and compressing distributor inventory positions.
EPA's residual monomer testing expansion under TSCA Section 5 is forcing reformulation of legacy architectural emulsions. The industrial consequence is accelerated R&D spend on controlled-release polymerization initiators. Exterior house paint lines serving the US Northeast and Upper Midwest are most affected, with suppliers now pre-testing to California Proposition 65 thresholds as a defensive specification strategy.
Specification authority is migrating from general contractors to building envelope consultants who demand substrate-specific warranty terms. Distributor sales forces serving commercial construction in Texas and Florida now employ certified technical representatives rather than traditional relationship managers. This shift is most visible in healthcare and education verticals where liability exposure concentrates decision-making with specialized consultants.
North America Polymer Emulsion Market Segmentation
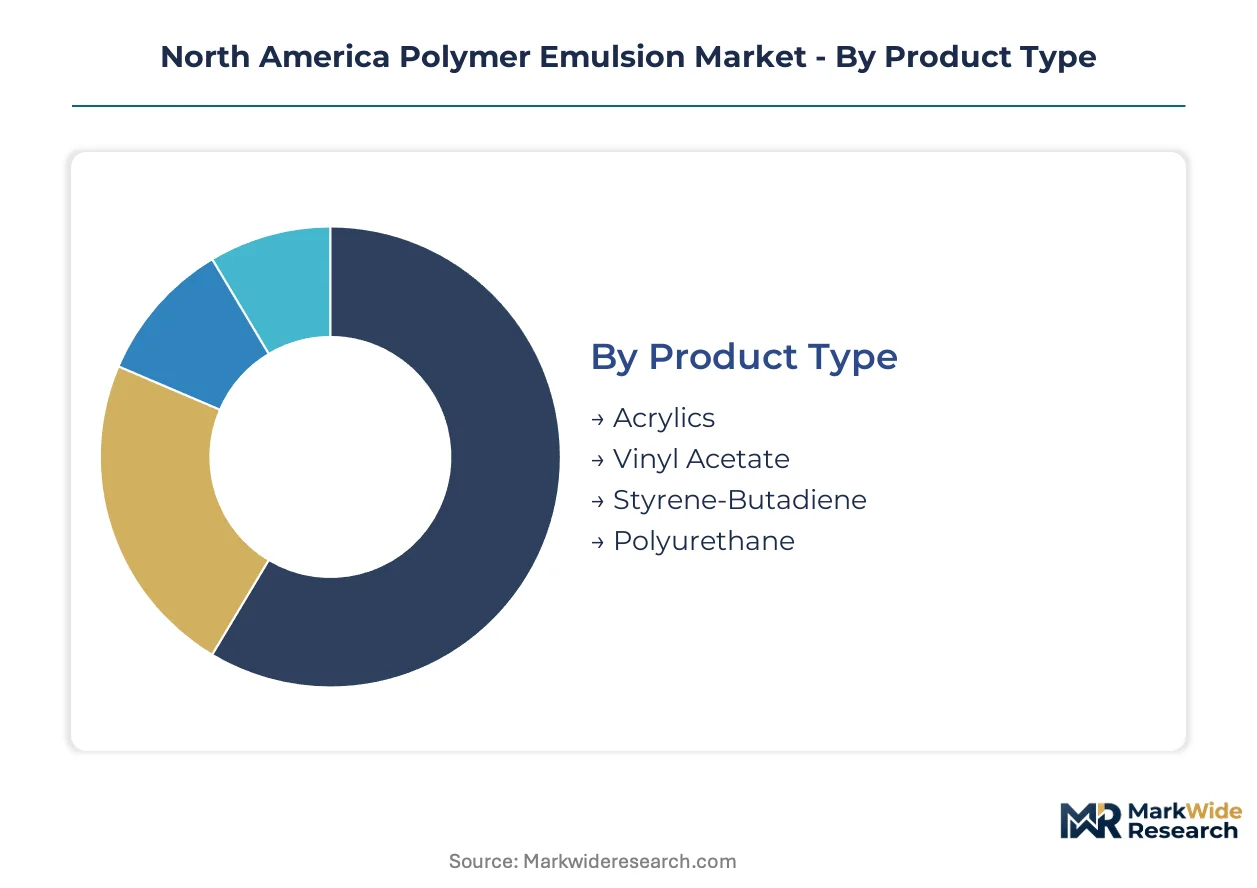
Segmentation in the North America polymer emulsion market reveals how product specifications diverge across regulatory jurisdictions and end-use performance requirements. Understanding these divisions helps suppliers align formulation investments with geographic demand concentration and compliance pathways.
Product Type:
Acrylics and vinyl acetate emulsions dominate domestic production volumes along the US Gulf Coast, while polyurethane dispersions serve more export-oriented specialty applications into Canada and Mexico.
- Acrylics:Waterborne acrylic emulsions combine methacrylate and acrylate monomers into thermoplastic particles with exterior durability and UV stability. Demand concentrates in California and Texas architectural coatings markets where CARB and municipal low-VOC mandates exceed federal minimums. EPA residual monomer testing expansion under TSCA Section 5 is forcing reformulation of legacy architectural lines.
- Vinyl Acetate:Vinyl acetate-ethylene copolymers and homopolymers offer cost-effective adhesion for high-volume construction applications. Demand clusters in the US Southeast residential construction corridor where integrated VAM capacity along the Texas Gulf Coast improves supply security for adhesive compounders. Freeze-thaw stability limitations constrain exterior wood coating applications in northern climates.
- Styrene-Butadiene:SB latex provides carboxylated binder systems for carpet backing and paper coating applications with mature growth profiles.
- Polyurethane:Waterborne polyurethane dispersions deliver premium flexibility and chemical resistance for automotive refinishing and textile lamination segments.
Acrylics holds the largest share; momentum sits with polyurethane dispersions as collision repair shops across Ontario and Quebec face Health Canada workplace chemical exposure enforcement.
End Use Industry:
Construction applications command the highest volume throughput, while automotive and textile segments operate on specification-driven margin tiers that reward technical differentiation.
- Construction:Emulsion binders serve architectural coatings, adhesives, sealants, and waterproofing membranes across residential and commercial building envelopes. Demand concentrates in Texas, Florida, and California metro areas where building code evolution and efficiency retrofit incentives under the US Inflation Reduction Act pull specification toward high-performance air barrier systems. Self-crosslinking acrylic technology is eliminating primer-topcoat sequences in cabinet manufacturing.
- Automotive:Waterborne polyurethane and acrylic dispersions provide basecoat and clearcoat systems for OEM and refinishing applications with exacting durability requirements. Automotive refinishing demand clusters in Ontario and Quebec collision repair markets where Health Canada enforcement of workplace chemical exposure limits accelerates waterborne transition ahead of US pace.
- Textile:Polyurethane dispersions enable fabric lamination and coating with wash durability and hand-feel specifications.
- Coatings:Industrial maintenance and protective coatings represent a cross-cutting application spanning multiple resin chemistries.
Construction commands volume dominance; automotive coatings are expanding most quickly as regulatory enforcement tightens across Canadian provinces.
Technology:
Process selection determines capital intensity and product consistency, with batch systems dominating specialty grades and continuous processes serving commodity scale.
- Batch Process:Discontinuous reactor operations enable rapid formulation switching for specialty emulsions with low-volume, high-margin profiles. Batch capacity concentrates with non-integrated manufacturers serving regional construction coating compounders who require customized particle size distributions.
- Continuous Process:Steady-state reactor configurations deliver consistent quality at scale for high-volume architectural emulsion production. Continuous lines anchor integrated petrochemical operations along the US Gulf Coast where captive monomer supply secures margin stability.
- Emulsion Polymerization:Free-radical aqueous dispersion at 60-90°C produces the colloidal particle architecture defining waterborne performance.
- Solution Polymerization:Organic solvent-based chain growth enables precise molecular weight control for subsequent dispersion steps.
Continuous process holds the largest share; batch process is gaining share fastest as specification fragmentation rewards formulation agility.
Formulation:
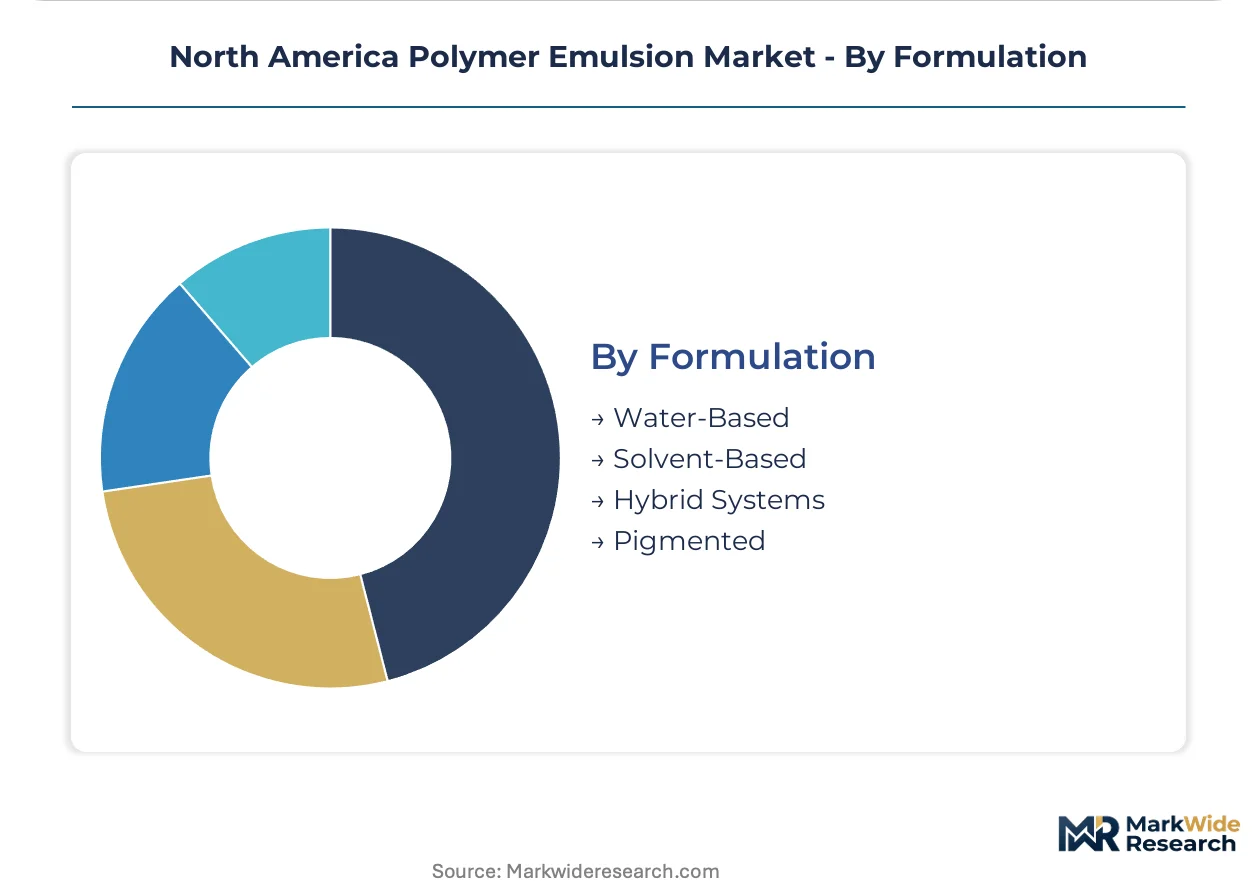
Water-based systems now dominate regulatory-compliant segments, while hybrid architectures capture performance gaps that pure waterborne chemistry cannot bridge.
- Water-Based:Aqueous continuous phase formulations eliminate solvent emissions and enable compliance with EPA NESHAP VOC restrictions. Waterborne systems now specify across California commercial projects and Ontario automotive refinishing, though freeze-thaw stability failures persist for exterior wood coatings in Minnesota and Manitoba winter cycles.
- Solvent-Based:Organic carrier systems retain niche positioning where waterborne performance ceilings and rapid drying requirements override regulatory pressure.
- Hybrid Systems:Epoxy-acrylic and polyurethane-acrylic combinations merge corrosion resistance with application ease for industrial maintenance contractors seeking single-coat warranty terms.
- Pigmented:Pre-dispersed colorant integration reduces field mixing variability and supports just-in-time distributor inventory models.
Water-based formulations hold the largest share; hybrid systems are climbing the fastest as industrial maintenance specifications converge on multi-property performance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across North America, with the United States driving high-performance architectural specifications, Canada accelerating automotive waterborne transitions, and Mexico presenting underpenetrated construction adhesive opportunities.
United States
California and Texas metro areas dominate architectural coating demand as CARB mandates exceed federal VOC minimums. EPA residual monomer testing under TSCA Section 5 forces reformulation of legacy exterior house paints serving the Northeast and Upper Midwest. The US Gulf Coast petrochemical corridor anchors integrated acrylic and vinyl acetate production, with new emulsion-grade capacity improving supply security for regional compounders.
Canada
Ontario and Quebec collision repair markets drive polyurethane dispersion adoption as Health Canada enforces workplace chemical exposure limits ahead of US pace. The PMRA maintains divergent residual monomer testing protocols that impose dual compliance costs on cross-border suppliers. Toronto and Montreal industrial zones concentrate automotive refinishing demand, with specification authority migrating to building envelope consultants in healthcare and education verticals.
Mexico
Waterborne coating penetration in residential construction trails US levels, creating expansion runway for regional formulators targeting adhesive and sealant compounders. Mexico City and Monterrey construction corridors exhibit specification pull from multinational contractors applying California-tier environmental standards. The Bajío Region automotive assembly plants generate secondary demand for high-performance coating systems, though local emulsion manufacturing capacity remains limited.
North America Polymer Emulsion Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence redrawing competitive boundaries across the region. Petrochemical majors leverage captive monomer supply to sustain margin stability in coating-grade emulsions, while specialty operators differentiate through application-specific performance tiers. Three archetypes dominate: backward-integrated resin producers, formulation-technology licensors, and regional distribution-focused compounders. Capacity expansion along the US Gulf Coast and strategic partnerships for hybrid epoxy-acrylic technology represent the dominant competitive vectors.
Within the integrated tier, BASF and Dow exemplify divergent strategic positions—BASF through acrylic monomer integration, Dow through vinyl acetate-ethylene scale. Arkema occupies a specialist position representing high-performance polyurethane dispersion capabilities for premium automotive and textile applications. These three anchors illustrate how competitive positioning stratifies across commodity volume, integrated margin stability, and technical differentiation.
| Leading Market Players |
|---|
| BASF |
| Dow |
| Arkema |
| Celanese Corporation |
| Wacker Chemie AG |
| Synthomer PLC |
| Lubrizol |
| 3M |
| Akzo Nobel N.V. |
| Others |
Value Network & Pricing Analysis
Vinyl acetate monomer substitution for solvent-borne alkyd resins in architectural coatings is redrawing supply geography toward the US Gulf Coast while compressing pricing power for non-integrated compounders dependent on spot acrylic acid markets.
Pricing Analysis
Long-term offtake contracts dominate procurement between integrated petrochemical producers and large coating compounders, insulating volume buyers from Gulf Coast monomer volatility that punishes spot-market purchasers. Price differentiation rests on captive monomer supply and EPA Safer Choice certification tier, with backward-integrated suppliers commanding premium positioning over toll manufacturers. Pricing pressure intensifies in construction adhesive grades where vinyl acetate-ethylene capacity expansion erodes margins. Residential construction compounders exhibit highest price sensitivity, while automotive refinishing shops prioritize performance guarantees over unit cost.
Supply Chain Analysis
The United States anchors acrylic and vinyl acetate monomer production through integrated complexes along the Texas and Louisiana Gulf Coast, while Canada and Mexico remain import-dependent for specialty polyurethane dispersions. Raw material flows draw from propylene, ethylene, and acrylic acid feedstocks with pricing tethered to regional petrochemical economics. Single-source vulnerability concentrates in emulsion-grade vinyl acetate monomer where capacity additions lag demand swings in residential construction cycles. Distribution runs through regional chemical distributors serving compounders, with technical service capabilities increasingly determining supplier selection in specification-driven automotive and industrial maintenance segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among building envelope consultants and national coating formulators, fragmenting procurement authority away from general contractors and redrawing negotiation leverage across the value chain.
For Market Incumbents: Compound defensive positioning through captive acrylic monomer supply and EPA pre-certification to TSCA Section 5 residual monomer thresholds ahead of federal enforcement expansion. Accelerate hybrid epoxy-acrylic R&D to capture industrial maintenance specification migration toward single-coat systems, while building technical sales capabilities to serve consultant-driven procurement in healthcare and education verticals.
For New Entrants and Emerging Players: Technical service gaps in substrate-specific warranty support create entry pathways for regional compounders targeting cabinet manufacturers adopting self-crosslinking acrylic technology. Mexico's underpenetrated waterborne construction coating market offers the most penetrable geography, with Monterrey and Mexico City corridors exhibiting specification pull from California-tier environmental standards. Lead with distributor technical representative certification programs to bypass incumbent relationship networks.
For Investors and Strategic Acquirers: The market sits at a regulatory-enforcement acceleration phase that favors backward-integrated producers with compliance infrastructure already deployed. Long-term viability centers on Gulf Coast manufacturing footprints with captive monomer supply and hybrid technology licensing capabilities. Monitor Health Canada PMRA residual monomer protocol convergence with EPA standards as the inflection signal for cross-border supplier consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomers | Captive propylene derivative supply insulates margin stability against Gulf Coast feedstock volatility. |
| Hybrid Epoxy-Acrylic Technology Licensing | Industrial maintenance contractors seeking single-coat corrosion resistance drive formulation premium capture. |
| EPA Safer Choice Pre-Certification | Eighteen-month validation cycles favor early movers ahead of anticipated formaldehyde limit tightening. |
| Mexico Distribution Partnership Expansion | Waterborne coating penetration gaps in residential construction create volume runway for regional formulators. |
| Technical Service Capability Buildout | Building envelope consultants now control specification authority in healthcare and education verticals. |
Research Methodology
Operator-level perspectives from emulsion polymerization plant managers, procurement leads at architectural coating compounders, distribution channel partners, and technical R&D directors anchored the qualitative base. Primary interview insights combined with secondary validation from EPA NESHAP regulatory filings, ACC industry reports, SEC 10-K disclosures from integrated petrochemical producers, and customs trade data. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic drivers across the North American construction and automotive sectors.
Sensitivity analysis tested forecast robustness across feedstock price volatility scenarios, regulatory enforcement timing variations, and substitution elasticity between waterborne and hybrid systems. Segmentation dimensions modeled include resin chemistry tier, end-use industry concentration, formulation technology type, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for capacity expansion announcements and enforcement schedule shifts. Industry-specific inputs incorporated CARB mandate adoption curves and Health Canada workplace exposure limit implementation pacing.
Material uncertainties — feedstock price shocks, regulatory protocol divergence between EPA and PMRA, and freeze-thaw performance breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding enforcement consistency and capacity completion timelines. Recalibration cycles align with material shifts in EPA residual monomer testing expansion and Gulf Coast petrochemical project commissioning schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Semi-Crystalline Polymers Market
Polymers & Resins
Global Polyethylene (PE) Foam Market
Polymers & Resins
Global Alpha Olefins Market
Polymers & Resins
Global Water-Based Resins Market
Polymers & Resins
Medical Styrenic Polymers Market
Polymers & Resins
Poly(P-Phenylene Ether) (PPE) Market
Polymers & Resins
Polymer Binders Market
Polymers & Resins
Global Acrylic Emulsions Market
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
North America Geopolymer Market
Polymers & Resins
Polymer Foam Market
Polymers & Resins
Canada Bioresorbable Polymers Market
Polymers & Resins
Polyolefin (PO) Market
Polymers & Resins
Global Synthetic Polymers Market
Polymers & Resins
Nylon-6 Market
Polymers & Resins
India Epoxy Resins Market