
 Epoxy Resin Reactive Diluent Market | 2026-2036
Epoxy Resin Reactive Diluent Market Size, Share, and Industry Trends Forecast 2026-2036
Epoxy Resin Reactive Diluent Market Insights
Aliphatic glycidyl ethers is broadening the addressable market for epoxy formulators seeking to replace conventional solvents with reactive species that become chemically bound in the cured network. BASF SE leverages its integrated petrochemicals platform to secure backward integration into key epichlorohydrin feedstocks. KUKDO Chemical Co., Ltd. anchors its position through dedicated capacity in South Korea serving Pacific Rim electronics and coatings customers. Evonik Industries AG differentiates via specialty cycloaliphatic grades engineered for low-color, high-performance automotive clearcoats.
Epoxy resin reactive diluents are low-viscosity mono- or multi-functional epoxy compounds, typically containing one or more oxirane rings per molecule, that reduce formulation viscosity while participating in crosslinking reactions with polyamine or anhydride curatives. Their primary purpose is to enable high-solids or solvent-free application of epoxy systems in protective coatings, structural adhesives, and fiber-reinforced composites without sacrificing cured mechanical properties. Aliphatic diluents dominate volume consumption in industrial maintenance coatings where cost-efficient viscosity reduction remains paramount. Cycloaliphatic diluents command premium positioning in electrical encapsulation and LED potting applications requiring thermal stability and minimal yellowing. Composites application growth in wind energy and aerospace is pulling demand for low-volatility grades that maintain laminate void content below critical thresholds.
EPA regulations on hazardous air pollutants from coatings operations and REACH restrictions on Substances of Very High Concern are forcing reformulation toward lower-emission, non-carcinogenic diluent architectures in the United States and European Union. China's MEE enforcement of GB standards on industrial VOC emissions is tightening compliance requirements for domestic formulators exporting to regulated markets. Formulators and raw material suppliers must monitor evolving substance restrictions under the EU Green Deal chemical sustainability strategy and align product development pipelines with anticipated restrictions on CMR-classified chemistries.
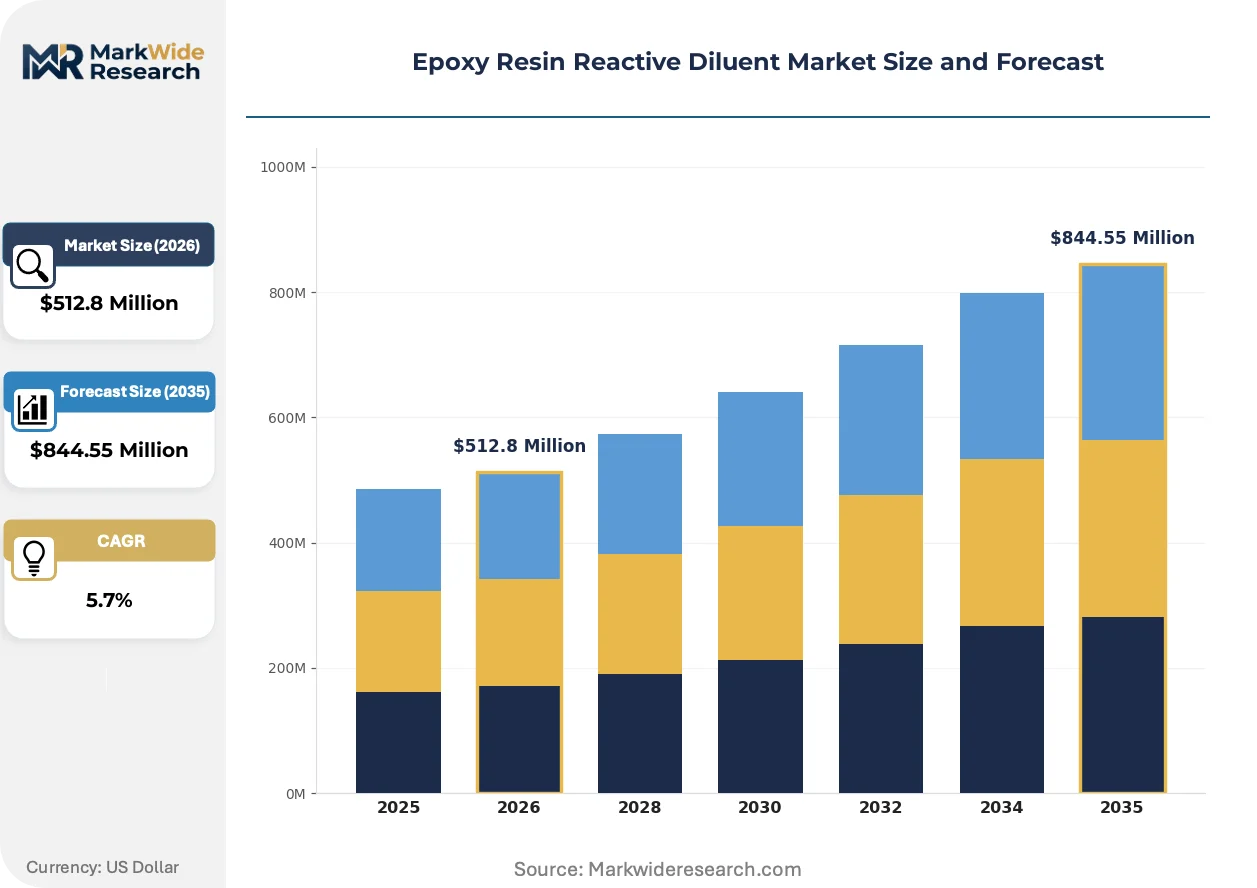
Market Dynamics
REACH and EU Green Deal mandates on volatile organic compound emissions are forcing formulators to abandon conventional aromatic diluents for cycloaliphatic and bio-based architectures, restructuring procurement priorities across coatings and electronics supply chains.
Growth Catalysts
- Aerospace composite demand:Manufacturers of advanced carbon-fiber structures require lower-viscosity formulations that enable void-free laminate infusion. Wind turbine blade producers in China, Germany, and the United States are scaling procurement of high-purity grades accordingly.
- EPA hazardous air pollutant rules:Coatings operations in the United States face compliance deadlines that favor reactive diluents over solvent-based viscosity reducers. This regulatory pressure accelerates solvent-to-reactive substitution in industrial maintenance applications.
- LED potting expansion:Electronics manufacturers specify cycloaliphatic chemistries for thermal stability and minimal yellowing in encapsulation. The shift toward high-lumen-density lighting architectures pulls demand for premium-grade materials.
Market Restraints
- Epichlorohydrin feedstock volatility:Petrochemical price swings directly compress margin structures for glycidyl ether producers. Integrated players with captive epichlorohydrin supply enjoy defensive positioning against this input cost risk.
- South Korean supply concentration:Dedicated capacity serving Pacific Rim electronics customers creates geographic vulnerability. Disruption at Busan-area production clusters would constrain regional availability for semiconductor encapsulation grades.
- Bio-based performance gaps:Plant-derived alternatives struggle to match the color stability and thermal resistance of petroleum-based cycloaliphatics. Formulators in automotive clearcoat applications retain petroleum dependency pending molecular engineering advances.
Strategic Opportunities
- India industrial coatings penetration:BIS standards alignment and domestic manufacturing incentives under the PLI scheme create entry pathways for reactive diluent suppliers. Local formulators seek technical partnerships to replace imported solvent systems.
- Dual carbon goals in China:MEE enforcement of GB standards on industrial VOC emissions accelerates domestic reformulation. Bio-based diluent architectures qualify for preferential treatment under national carbon neutrality procurement guidelines.
- Digital formulation platforms:AI-driven viscosity prediction tools enable remote technical service and accelerated customer qualification. Specialty chemical distributors are building these capabilities to displace traditional field-based sales engineering.
Industry Challenges
- Cross-functional formulation expertise:Reactive diluent suppliers must field chemists fluent in both epoxy kinetics and composite processing parameters. Talent scarcity in rheology-structural mechanics convergence limits technical service scalability.
- REACH SVHC notification timelines:Substances of Very High Concern classification creates multi-year product sunset windows. Suppliers face parallel portfolio maintenance costs while developing replacement chemistries under confidentiality constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epoxy Resin Reactive Diluent Market |
| Market Size in 2026 | $512.8 Million |
| Market Size in 2035 | $844.55 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aliphatic Diluents, Aromatic Diluents, Cycloaliphatic Diluents, Others End User: Construction, Aerospace, Automotive, Marine Application: Coatings, Adhesives, Composites, Sealants Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | KUKDO Chemical Co., Ltd., BASF SE, Olin Corporation, Westlake Epoxy, Mitsubishi Chemical Group Corporation, Evonik Industries AG, Cargill, Incorporated, Aditya Birla Chemicals, Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epoxy Resin Reactive Diluent Market Trends and Innovations
Reactive diluent technology is fragmenting into application-specific architectures as formulators abandon universal grades in favor of performance-optimized molecular designs tailored to thermal, optical, or mechanical requirements.
Bio-based glycidyl ether synthesis from epoxidized vegetable oils is modularizing supply chain configurations for sustainability-focused formulators. European coatings manufacturers are piloting these materials in decorative and protective applications where color stability requirements are less stringent. The technology is modularizing procurement decisions by enabling region-specific feedstock sourcing that reduces transport emissions and qualifies for EU Green Deal circular economy credits.
China's MEE enforcement of updated GB standards on industrial VOC emissions is tightening compliance verification for domestic formulators exporting to regulated markets. Inspection protocols now require documented diluent reactivity ratios and cured-film emission testing. Export-oriented coatings producers in Guangdong and Jiangsu provinces are accelerating substitution programs to maintain EU and US market access.
Specification authority is migrating from formulator R&D departments to OEM material qualification teams in wind energy and aerospace verticals. Tier-one blade manufacturers and airframe assemblers now mandate approved diluent grades through controlled purchase agreements. This concentration is most visible in Denmark and Spain, where Vestas and Airbus suppliers face consolidated technical requirements that override traditional distributor relationships.
Epoxy Resin Reactive Diluent Market Segmentation
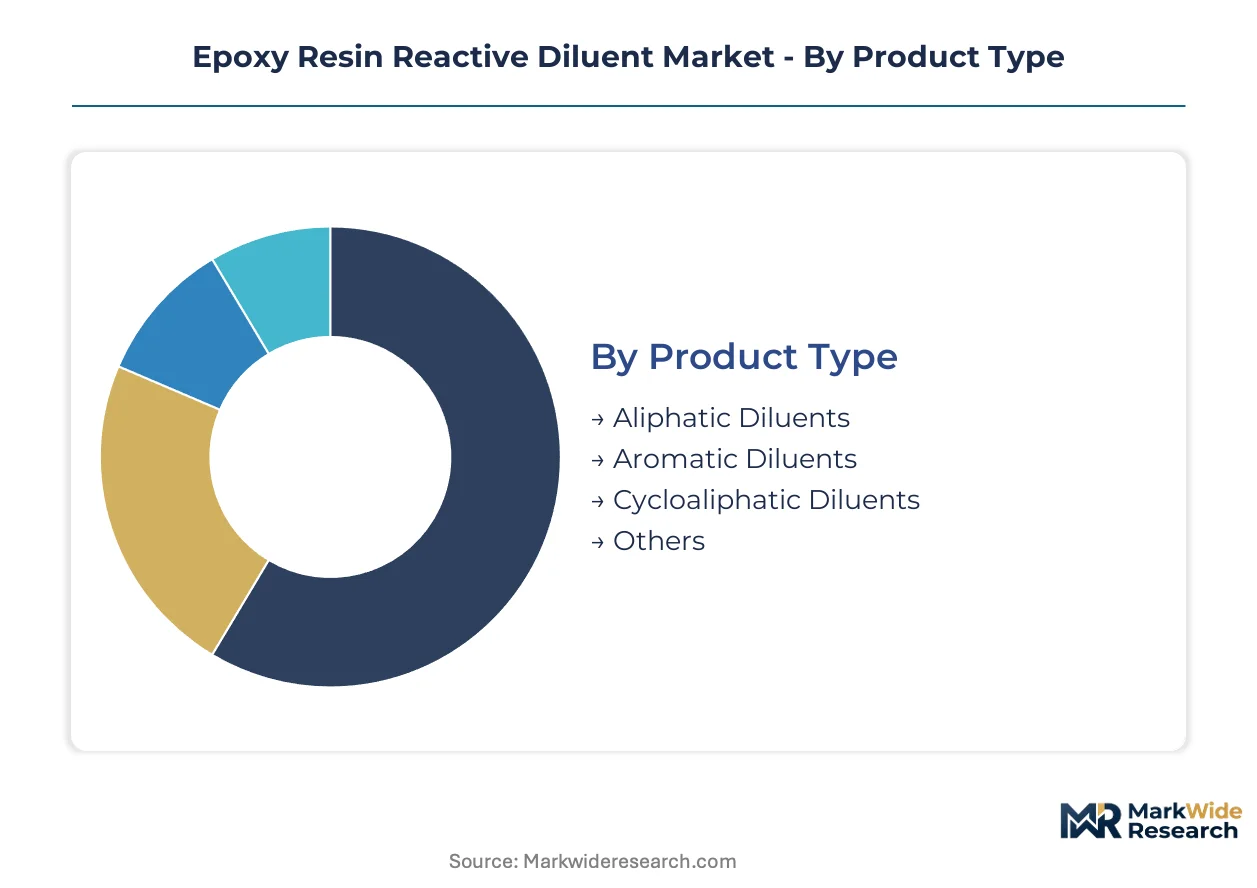
Epoxy resin reactive diluent procurement decisions hinge on viscosity reduction targets, cured-film performance requirements, and regulatory compliance obligations across distinct end-use verticals. Formulators align segment selection with specific processing constraints rather than adopting universal-grade architectures.
Product Type:
Cost efficiency versus thermal stability trade-offs dominate buyer evaluation when selecting reactive diluent chemistries for specific formulation portfolios.
- Aliphatic Diluents:Glycidyl ether architectures derived from C12-C14 alcohols deliver cost-efficient viscosity reduction in industrial maintenance coatings. Demand concentrates in Germany and the United States where EPA and REACH compliance deadlines accelerate solvent-to-reactive substitution in protective coatings.
- Cycloaliphatic Diluents:Rigid ring structures provide exceptional thermal stability and minimal yellowing in electrical encapsulation applications. LED potting manufacturers in South Korea and Japan specify these grades for high-lumen-density lighting modules where color retention is critical.
- Aromatic Diluents:Benzyl glycidyl ether variants offer intermediate cost-performance positioning but face regulatory pressure from ECHA Substances of Very High Concern classifications.
- Others:Bio-based epoxidized vegetable oil derivatives qualify for EU Green Deal circular economy credits in decorative coatings.
Aliphatic diluents lead on scale; cycloaliphatic diluents lead on momentum.
End User:
Application severity and certification requirements determine grade specification authority across industrial verticals.
- Construction:Protective coatings for infrastructure assets drive volume consumption of standard-grade aliphatic diluents. Chinese formulators serving Belt and Road projects in Southeast Asia prioritize cost-efficient viscosity reduction for steel protection systems.
- Aerospace:Advanced carbon-fiber composite manufacturing mandates low-volatility grades that maintain laminate void content below critical thresholds. Airbus suppliers in Spain and Germany enforce approved-material lists that override traditional distributor relationships.
- Automotive:Clearcoat applications demand cycloaliphatic chemistries with color stability specifications that bio-based alternatives currently fail to match.
- Marine:Anticorrosive coatings for shipbuilding require high-solids formulations compliant with IMO environmental regulations.
Construction leads on scale; aerospace leads on momentum.
Application:
Processing methodology and cure kinetics dictate mono-functional versus multi-functional diluent selection.
- Coatings:High-solids and solvent-free protective systems represent the dominant consumption channel. Industrial maintenance formulators in the United States leverage reactive diluents to meet EPA hazardous air pollutant compliance deadlines.
- Composites:Vacuum infusion and resin transfer molding processes require ultra-low viscosity for void-free laminate production. Wind turbine blade manufacturers in China and Denmark specify high-purity grades through controlled purchase agreements.
- Adhesives:Structural bonding applications balance viscosity reduction with preserved mechanical properties in cured joints.
- Sealants:Construction joint sealing demands flexible cured networks achieved through aliphatic glycidyl ether incorporation.
Coatings lead on scale; composites lead on momentum.
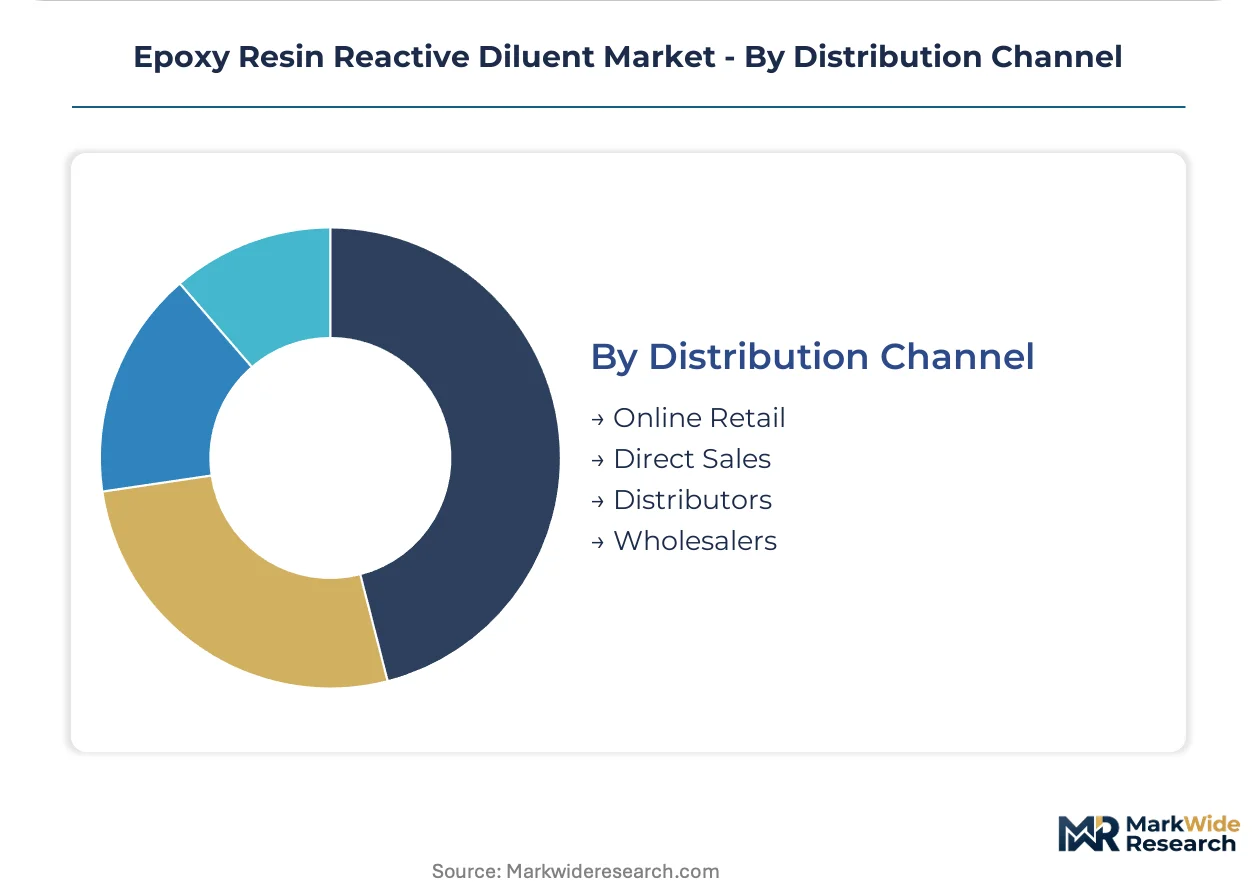
Distribution Channel:
Technical service intensity and order scale determine channel preference across customer segments.
- Distributors:Regional chemical distributors dominate mid-volume procurement by providing formulation technical support and inventory consolidation. Specialty distributors in Guangdong province serve export-oriented coatings producers with documented reactivity ratio certifications.
- Direct Sales:Large-volume composite manufacturers and multinational coatings formulators negotiate directly with producers for dedicated supply agreements and custom specification development.
- Online Retail:Small-scale formulators and research laboratories procure standard grades through digital platforms with reduced technical service.
- Wholesalers:Bulk volume aggregation serves secondary manufacturing regions with limited direct producer presence.
Distributors lead on scale; direct sales leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Busan-area production clusters anchor supply-side capacity for Pacific Rim electronics encapsulation, while procurement activity concentrates in three manufacturing corridors serving wind energy, aerospace, and automotive verticals.
China
Wind turbine blade manufacturers in Guangdong and Jiangsu provinces drive demand for high-purity grades through controlled purchase agreements. MEE enforcement of updated GB standards on industrial VOC emissions tightens compliance verification for export-oriented coatings producers. The Yangtze River Delta houses the largest concentration of domestic formulators replacing solvent systems with reactive architectures.
Germany
Airbus suppliers in Hamburg and Bremen enforce approved-material lists for advanced carbon-fiber composite manufacturing. REACH restrictions on Substances of Very High Concern accelerate reformulation away from aromatic diluent chemistries. The North Rhine-Westphalia chemical corridor hosts integrated producers with captive epichlorohydrin supply chains.
United States
Industrial maintenance coatings formulators leverage reactive diluents to meet EPA hazardous air pollutant compliance deadlines in Gulf Coast petrochemical facilities. The IRA supports domestic manufacturing incentives for high-solids protective systems. Houston-area procurement offices negotiate direct supply agreements with multinational producers for infrastructure protection projects.
South Korea
LED potting manufacturers in the Seoul Capital Area specify cycloaliphatic grades for high-lumen-density lighting modules where color retention is critical. Domestic capacity serving Pacific Rim semiconductor encapsulation creates geographic concentration risk. Busan-Ulsan production clusters supply dedicated grades to electronics customers requiring thermal stability specifications.
India
BIS standards alignment and PLI scheme incentives create entry pathways for reactive diluent suppliers targeting industrial coatings penetration. Maharashtra and Gujarat formulators seek technical partnerships to replace imported solvent systems. Domestic manufacturing of high-solids protective coatings accelerates in the Delhi-NCR corridor for infrastructure steel protection.
Epoxy Resin Reactive Diluent Market Competitive Landscape
Global majors compete with regional champions across feedstock integration and specialty formulation capabilities. The vendor base stratifies into three tiers: integrated petrochemical conglomerates with backward control over epichlorohydrin, mid-scale regional specialists serving electronics clusters, and sustainability-focused innovators developing bio-based architectures. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing dedicated supply agreements for wind energy and aerospace qualification programs.
Within the integrated petrochemical tier, BASF SE and Evonik Industries AG exemplify European-based producers leveraging captive feedstock advantages and specialty cycloaliphatic development. KUKDO Chemical Co., Ltd. anchors the Asia-Pacific regional specialist position through dedicated capacity serving Pacific Rim electronics customers. These three entities represent distinct archetypes: the backward-integrated global major, the premium-grade specialty developer, and the geography-focused cluster supplier.
| Leading Market Players |
|---|
| KUKDO Chemical Co., Ltd. |
| BASF SE |
| Olin Corporation |
| Westlake Epoxy |
| Mitsubishi Chemical Group Corporation |
| Evonik Industries AG |
| Cargill, Incorporated |
| Aditya Birla Chemicals |
| Huntsman Corporation |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in South Korea and Germany maintain pricing discipline through dedicated capacity serving electronics and automotive OEMs, while their limited financing flexibility constrains aggressive expansion into cycloaliphatic grades. This ownership pattern concentrates supply-side bargaining power among integrated petrochemical conglomerates with captive epichlorohydrin production, compressing margin structures for non-integrated formulators.
Pricing Analysis
Epichlorohydrin feedstock volatility passes directly into glycidyl ether pricing, with integrated producers capturing margin advantage during petrochemical price spikes. Three-tier pricing structure across premium, standard, and economy levels separates cycloaliphatic grades for LED potting from aliphatic variants for industrial coatings. Cost compression in standard aliphatic tiers is intensifying because Chinese formulators are scaling domestic capacity under MEE compliance pressure. Wind turbine blade manufacturers show least price sensitivity due to qualification lock-in, while decorative coatings formulators in Southeast Asia drive hardest bargain on volume tenders.
Supply Chain Analysis
Container freight rates from Busan to Hamburg and Shanghai to Rotterdam directly impact landed costs for European coatings formulators sourcing Asian cycloaliphatic grades. Manufacturing concentrates in China, South Korea, and Germany, with each hub feeding distinct end-use verticals. Supply chains draw from epichlorohydrin, C12-C14 alcohol feedstocks, and hydrogenation catalysts as critical inputs. Single-source vulnerability runs through South Korean electronics-grade capacity, where disruption would cascade through semiconductor encapsulation supply. Distribution runs through specialty chemical distributors with formulation technical service capabilities in Guangdong, North Rhine-Westphalia, and Texas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where specification authority migration toward OEM material qualification teams favors suppliers with proven aerospace and wind energy track records over commodity aliphatic producers.
For Market Incumbents: Hedge epichlorohydrin exposure through backward integration or long-term offtake agreements with propylene oxide suppliers, as feedstock volatility threatens margin compression in standard glycidyl ether tiers. Secure dual qualification status with Vestas and Airbus suppliers before REACH SVHC sunset windows force portfolio restructuring, locking in premium cycloaliphatic volumes that bio-based alternatives cannot yet displace. For New Entrants and Emerging Players: Small-scale wind energy subcontractors in India and Southeast Asia present the most penetrable entry point, as these buyers lack direct supply relationships with BASF or Evonik and prioritize technical partnership over brand recognition. Target BIS-aligned formulators in Maharashtra seeking solvent replacement guidance, offering AI-driven viscosity prediction tools that incumbent distributors have not yet deployed to displace field-based sales engineering. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale regional specialists with cycloaliphatic development pipelines but limited geographic diversification beyond single-country production clusters. Five-to-ten year viability hinges on successful navigation of EU Green Deal chemical sustainability timelines and bio-based performance gap closure. Monitor ECHA SVHC notification timelines as the critical inflection signal—accelerated substance classifications would force distressed portfolio sales from non-compliant producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epichlorohydrin | Captive feedstock supply insulates BASF and Olin from propylene oxide price volatility. |
| Capacity Expansion in Yangtze River Delta | Proximity to Guangdong wind blade manufacturers reduces logistics costs for high-purity grades. |
| Green Manufacturing Transition | Bio-based glycidyl ether synthesis qualifies Cargill for EU Green Deal circular economy credits. |
| Long-term Supply Agreement with Airbus Tier-1s | Controlled purchase agreements override distributor relationships in Hamburg and Bremen procurement. |
| Joint Venture for LED Potting Grades | Collaboration with Seoul Capital Area electronics clusters secures thermal stability specifications. |
Research Methodology
Direct dialogue with epoxy formulators, procurement leads at wind turbine OEMs, technical R&D directors at coatings manufacturers, and distribution channel partners in Guangdong and North Rhine-Westphalia grounded qualitative assessment of specification migration trends. Secondary validation drew from customs/trade data, ECHA SVHC notifications, SEC 10-K filings from disclosed chemical producers, and MEE enforcement bulletins on GB standard compliance. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Segmented projections by product type, end-use vertical, and regional production hub generated volume and value trajectories over the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating aerospace composite build rates, wind energy installation forecasts, and LED lighting module production indices. Modeled scenarios weighted REACH regulatory timelines and bio-based substitution curves as key forecast sensitivity inputs.
Underlying measurement precision varies by segment; cycloaliphatic and aerospace-grade volumes carry tighter precision than bio-based alternatives where pilot-scale production data remains sparse. Forecasts reflect assumptions about MEE enforcement intensity and ECHA classification timelines that could shift with political or administrative changes. Stakeholders should weight assumptions against their own operating context and qualification pipeline visibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Modified Alkyd Resin Market
Polymers & Resins
Biopolymer Tubes Market
Polymers & Resins
Polyglycerol Polyricinoleate Market
Polymers & Resins
Scleroglucan Market
Polymers & Resins
1-Hexene Based Polyethylene Market
Polymers & Resins
Polyether Amine Market
Polymers & Resins
Orthophthalic Resins Market
Polymers & Resins
Polyurethane (PU) Microspheres Market
Polymers & Resins
Global Polyamide 6 Market
Polymers & Resins
United Kingdom Engineering Plastics Market
Polymers & Resins
Global Chromatography Resin Market
Polymers & Resins
Synthetic Polymer Waxes Market
Polymers & Resins
Liquid Polybutadiene [LPBD] Market
Polymers & Resins
Europe Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Methacrylate Monomers Market
Polymers & Resins
Polybutene-1 Market