
 Carbon Thermoplastic Composites Market | 2026-2036
Carbon Thermoplastic Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Thermoplastic Composites Market Outlook
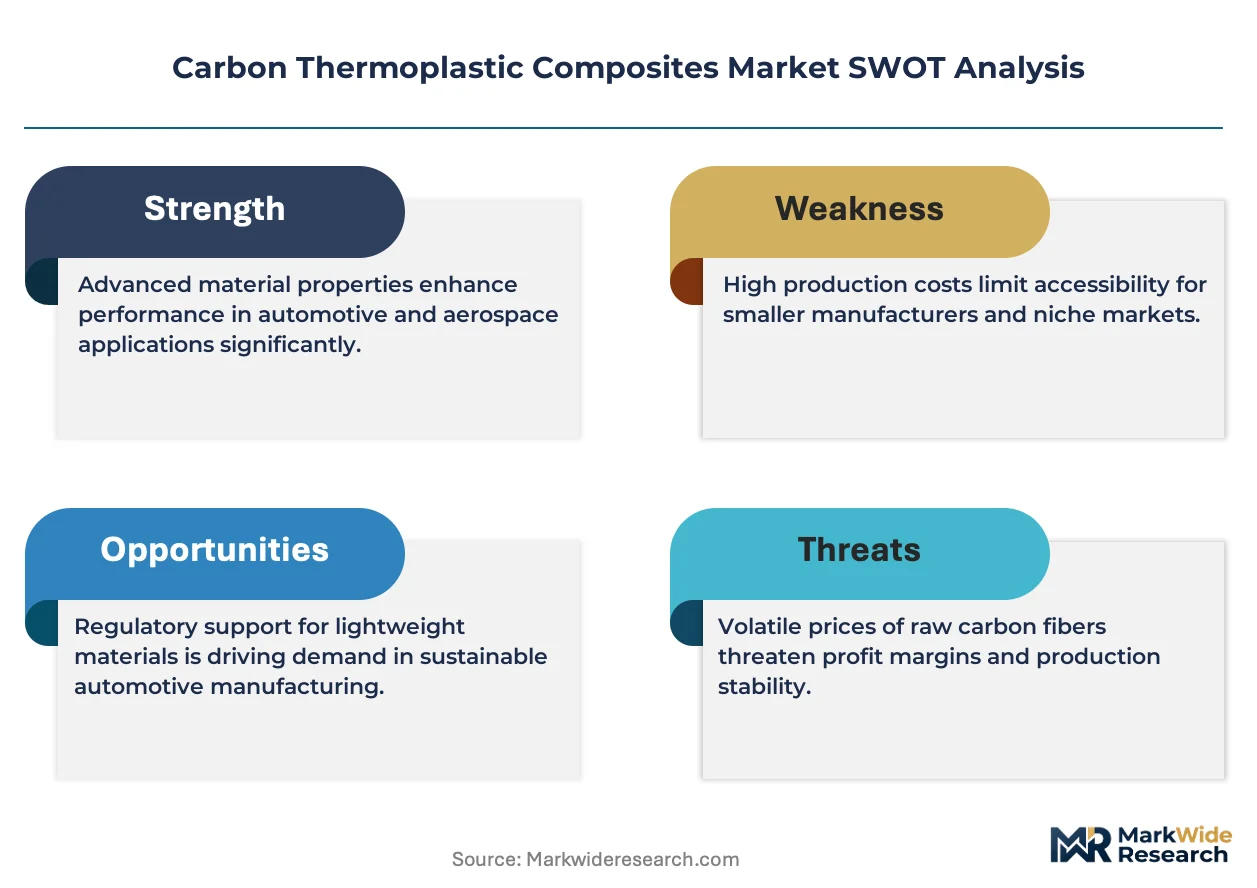
Buyer concentration among aerospace OEMs and Tier-1 automotive suppliers is shifting as electric vehicle platforms fragment procurement across new EV-native manufacturers. Toray Industries Inc. leverages its PAN precursor verticality to anchor supply security for high-modulus grades. Solvay SA differentiates through specialty polyamide chemistry tailored to aircraft interior fire-smoke-toxicity standards. Hexcel Corporation competes on thermoplastic tape placement automation, sustaining throughput advantages in aerostructures.
Carbon thermoplastic composites combine continuous carbon fiber reinforcement with thermoplastic matrices such as polyamide, polypropylene, or polycarbonate, processed via injection molding, compression molding, or automated fiber placement to yield weldable, recyclable parts with fracture toughness superior to thermoset alternatives. Their primary purpose centers on lightweight structural substitution in load-bearing applications where damage tolerance and production cycle time matter. Polyamide grades dominate aerospace interiors and under-hood automotive for their thermal and chemical resistance, while polycarbonate blends gain ground in consumer electronics housings where impact resistance and electromagnetic shielding converge. Compression molding occupies the margin-rich tier for large aerostructure components, whereas 3D printing remains emergent, constrained by fiber alignment control but attracting R&D investment for topology-optimized brackets.
EMA's MDR framework and REACH substance restrictions govern material biocompatibility and chemical disclosure for European medical and industrial applications, while FAA certification standards shape allowable damage tolerance thresholds for US commercial aviation. EPA and OSHA rules on volatile organic compound exposure during thermoplastic processing push manufacturers toward closed-loop heating systems. Stakeholders must weigh capital allocation between polyamide capacity expansion and next-generation recycling infrastructure as regulatory clarity on end-of-life responsibility solidifies.
Market Dynamics
Aerospace OEMs now mandate thermoplastic airframe structures to cut production cycle times, while EU REACH compliance tightens material traceability across the value chain. This dual pressure compresses supplier qualification timelines and rewards vertically integrated precursor-to-tape producers.
Growth Catalysts
- EU Green Deal decarbonization mandates:Binding emission targets for commercial aviation drive airframe lightweighting programs. Airlines face penalties for exceeding fleet-average carbon intensity thresholds.
- Automotive platform electrification:Battery enclosure weight reduction requirements from EV-native manufacturers in Germany's Stuttgart corridor accelerate polyamide composite adoption for structural battery housings.
- Automated fiber placement maturation:Robotic tape laying systems achieve aerospace-grade repeatability at automotive-scale throughput, collapsing the cost gap between thermoset and thermoplastic processing.
Market Restraints
- Acrylonitrile price volatility:PAN precursor production ties directly to petrochemical feedstock costs, exposing margin structures to crude oil derivative fluctuations without long-term offtake hedges.
- Japanese precursor concentration:Three suppliers control over seventy percent of aerospace-grade PAN global capacity, creating single-source vulnerability for high-modulus carbon fiber qualification programs.
- Thermoset incumbent lock-in:Established autoclave infrastructure and certified epoxy resin systems delay thermoplastic substitution in primary aerostructures despite performance advantages.
Strategic Opportunities
- India PLI scheme for advanced materials:Production-linked incentives for composite component manufacturing attract tier-1 suppliers to establish tape laying and compression molding capacity near Bengaluru's aerospace cluster.
- Medical device radiolucency demand:Carbon fiber polyamide composites replace aluminum in imaging table structures, leveraging the material's X-ray transparency and biocompatibility under EMA MDR frameworks.
- Hydrogen storage vessel filament winding:Type IV pressure vessel manufacturing for fuel cell vehicles converges thermoplastic liner technology with continuous fiber overwrapping, opening new tonnage demand outside traditional aerospace.
Industry Challenges
- Welding parameter certification backlog:FAA and EASA lack harmonized standards for ultrasonic and induction welding of thermoplastic joints, forcing dual-track qualification programs that extend program timelines by eighteen to thirty-six months.
- Recycling infrastructure capital intensity:Pyrolysis and solvolysis systems for end-of-life composite recovery require forty to sixty million dollar facility investments with unproven feedstock economics at commercial scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Thermoplastic Composites Market |
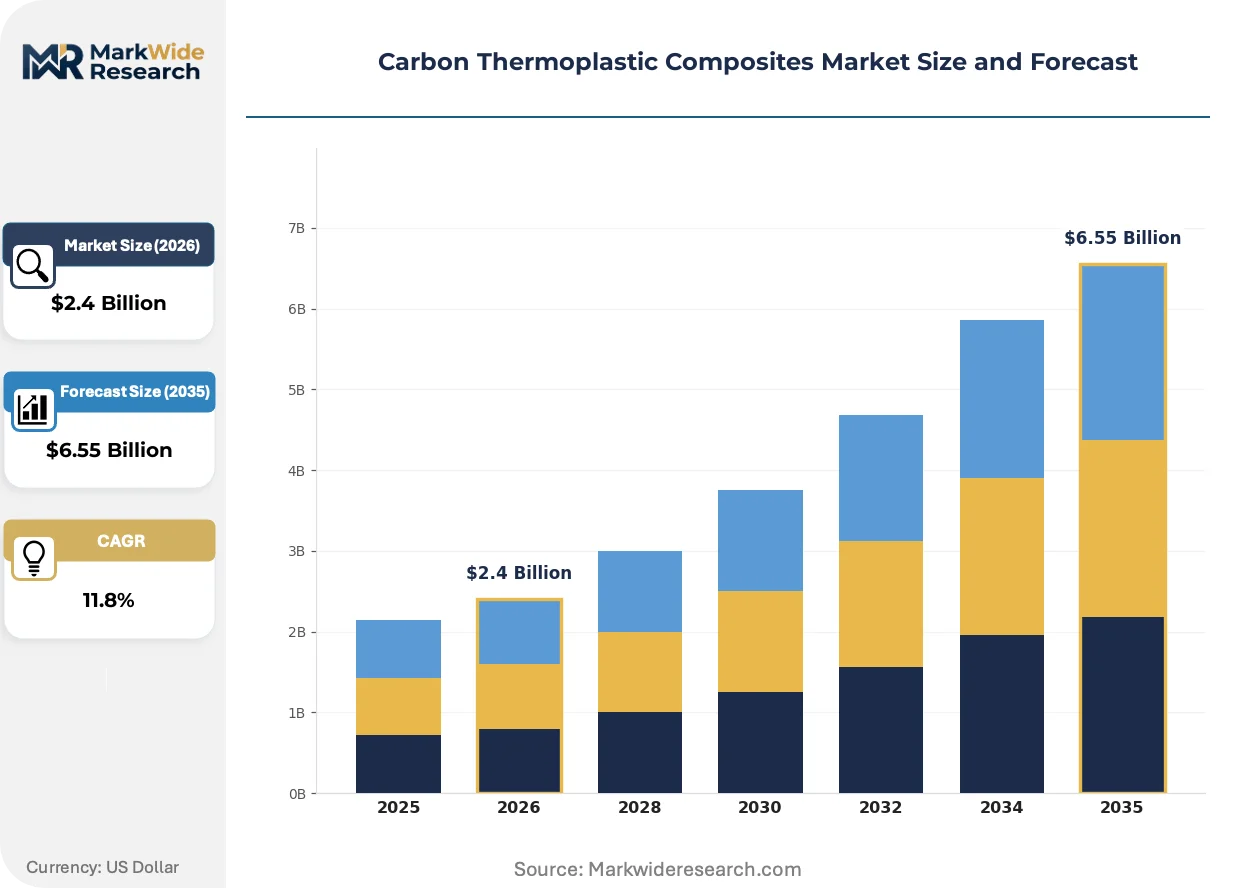
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.55 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyamide, Polycarbonate, Polyester Application: Aerospace, Automotive, Consumer Goods, Industrial Equipment End User: OEMs, Tier-1 Suppliers, Manufacturers, Distributors Production Method: Injection Molding, Compression Molding, Filament Winding, 3D Printing |
| Companies Covered | Toray Industries Inc., Solvay SA, Teijin Ltd., Hexcel Corporation, SGL Carbon SE, BASF SE, Avient Corporation, Celanese Corporation, DowAksa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Thermoplastic Composites Market Strategic Shifts
Thermoplastic composite processing is fragmenting across distributed manufacturing nodes, collapsing the traditional centralized autoclave model. Three convergent developments define this shift: equipment miniaturization, regulatory pressure on logistics emissions, and buyer demand for regional supply security.
Induction welding is decentralizing aerostructure assembly by eliminating autoclave size constraints. Bombardier and Gulfstream adopt mobile welding cells for business jet control surface joining. This compresses capital requirements from centralized billion-dollar facilities to modular million-dollar cell deployments, enabling tier-2 suppliers to enter primary structure fabrication.
REACH substance restrictions on isocyanates and bisphenol-A derivatives accelerate thermoplastic substitution in aircraft interiors. ECHA's 2023 restriction proposal targets flame-retardant thermoset resins used in seating and paneling. Cabin component suppliers in France and Germany pivot to polyamide and PEEK matrices to preempt compliance-driven obsolescence of incumbent materials.
Long-term material service agreements now displace spot purchasing for aerospace programs. Tier-1 aerostructure suppliers lock ten-year carbon fiber tape supply contracts with fixed-price escalators. This concentrates procurement leverage with Toray and Hexcel while squeezing compounders without backward PAN integration, visible most acutely in Germany's Munich engineering corridor where BMW and Airbus procurement teams co-locate supplier negotiation functions.
Carbon Thermoplastic Composites Market Segmentation
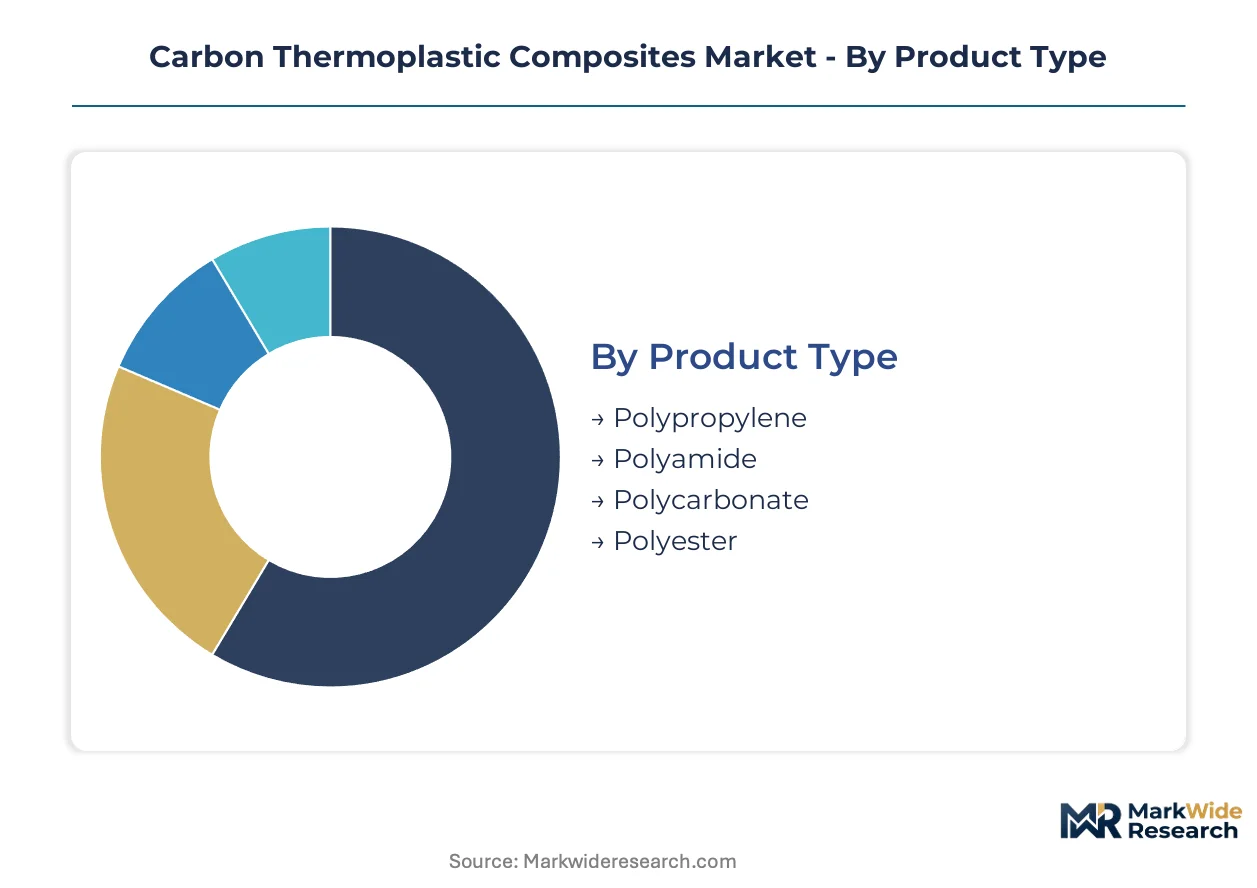
Carbon thermoplastic composites fragment across matrix chemistry, forming technique, and supply chain position. Each axis carries distinct margin structures and qualification barriers that shape competitive entry.
Product Type:
Matrix selection governs thermal ceiling, chemical resistance, and weldability in finished components.
- Polyamide:Semi-crystalline nylon matrices deliver 150°C continuous service temperature and excellent hydrocarbon resistance. Demand concentrates in Germany's Stuttgart automotive corridor for structural battery housings, driven by EV platform weight targets and REACH compliance on flame-retardant additives.
- Polycarbonate:Amorphous engineering thermoplastics provide optical clarity and electromagnetic shielding when loaded with carbon fiber. Growth is accelerating in consumer electronics housings for laptops and tablets, where impact resistance and thin-wall moldability converge.
- Polypropylene:Low-density olefin matrices offer cost positioning for non-structural industrial applications with moderate thermal demands.
- Polyester:Saturated thermoplastic polyesters balance mechanical properties with processing ease in compression-molded industrial components.
Mature deployment sits with polyamide in aerospace interiors and under-hood automotive. Newer deployment is concentrated in polycarbonate blends for electronics shielding applications.
Application:
End-use sector determines certification burden, lot traceability requirements, and acceptable payback period for capital equipment.
- Aerospace:Primary and secondary airframe structures, interior panels, and control surfaces subject to FAA and EASA damage tolerance standards. Procurement concentrates with Boeing and Airbus supply chains, where automated fiber placement achieves cycle time compression versus thermoset autoclave curing.
- Automotive:Structural battery enclosures, seat frames, and front-end carriers targeting 30-50% mass reduction. BMW and Mercedes-Benz procurement teams in Munich drive polyamide composite specifications for EV-native platforms.
- Consumer Goods:Sporting equipment, luggage, and personal electronics where surface finish and impact resistance justify premium positioning.
- Industrial Equipment:Robot arms, conveyor components, and chemical processing hardware requiring corrosion resistance and fatigue durability.
Established volume sits with aerospace qualification programs. Fastest expansion is occurring in automotive structural electrification.
End User:
Supply chain position dictates technical capability requirements and contract tenure.
- OEMs:Airbus, Boeing, and automotive final assemblers specify material grades and wield direct qualification authority over composite suppliers.
- Tier-1 Suppliers:Aerostructure fabricators and automotive module integrators manage tape laying and welding operations under long-term material service agreements.
- Manufacturers:Compounders and converters without backward PAN integration face margin compression from raw fiber cost volatility.
- Distributors:Regional stockists serve maintenance-repair-overhaul channels and small-batch industrial applications with limited technical support.
Contract concentration rests with tier-1 suppliers. Emerging leverage is shifting toward OEM direct material agreements.
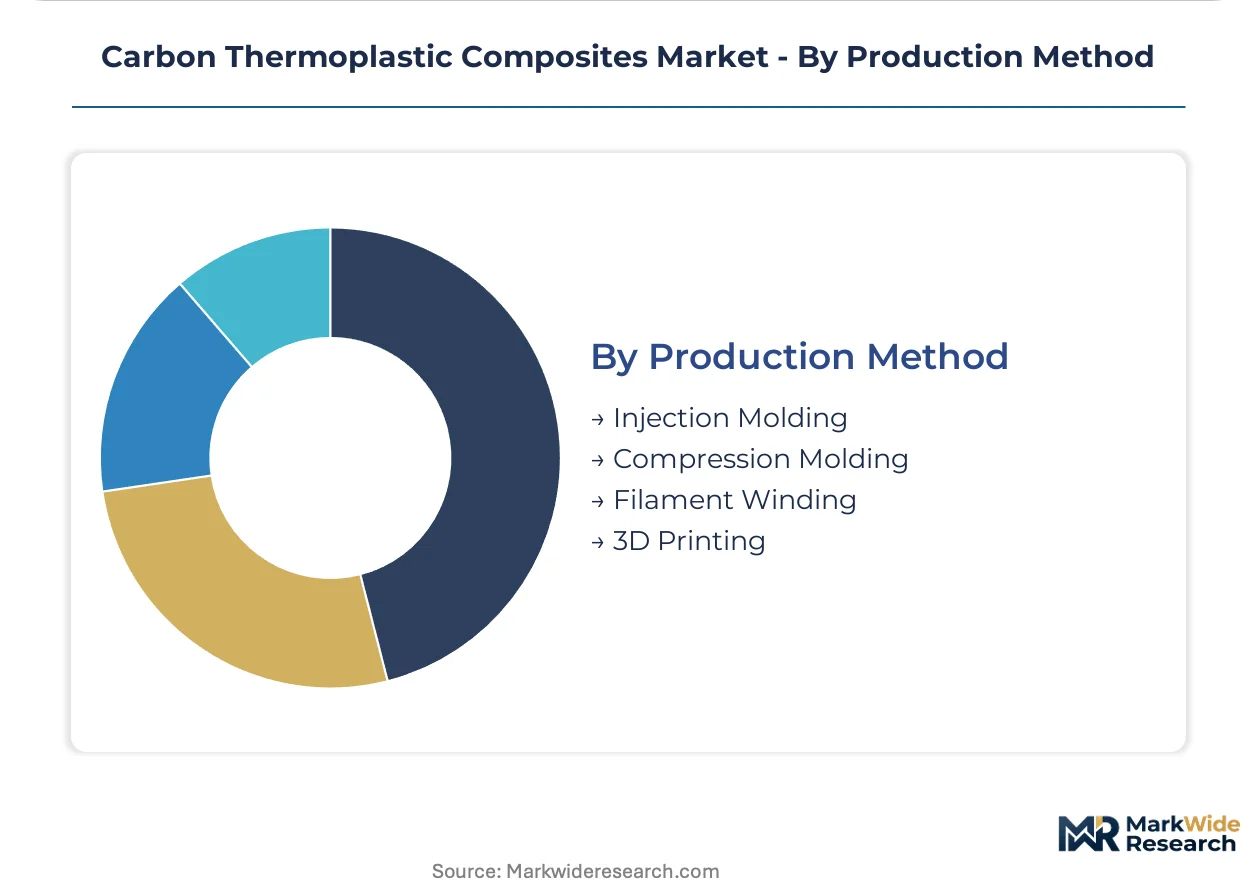
Production Method:
Process technology selection determines fiber volume fraction, geometric complexity, and economic batch size.
- Injection Molding:Short-fiber compounds processed at automotive-scale throughput for complex geometries with moderate structural demands.
- Compression Molding:Long-fiber or unidirectional preforms consolidated in heated matched-die tools for large aerostructure components.
- Filament Winding:Continuous fiber deposition around mandrels for pressure vessels and cylindrical structures, gaining traction in hydrogen storage Type IV vessel manufacturing.
- 3D Printing:Fused filament fabrication with continuous fiber in-situ consolidation remains emergent, constrained by fiber alignment control and deposition speed limitations.
Qualified volume centers on compression molding for primary aerostructures. Steepest investment growth is targeting filament winding for alternative fuel infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace OEM procurement and automotive electrification programs concentrate demand across three continents, with regulatory frameworks in each jurisdiction reshaping supplier qualification timelines and material specifications.
Germany
EV-native manufacturers in Stuttgart and Munich drive polyamide composite specifications for structural battery housings. EU REACH compliance tightens flame-retardant additive disclosure requirements for automotive interiors. The Baden-Württemberg engineering corridor hosts concentrated tape-laying and compression-molding capacity serving BMW and Mercedes-Benz procurement teams.
United States
FAA damage tolerance standards govern commercial aviation adoption of thermoplastic airframe structures, while EPA volatile organic compound rules push processors toward closed-loop heating systems. The Pacific Northwest and Southeast aerospace clusters anchor automated fiber placement investment for Boeing supply chains.
Japan
METI industrial policy supports carbon fiber precursor capacity expansion amid aerospace-grade PAN supply concentration. JIS standards shape material qualification protocols for domestic automotive and electronics applications. Tokyo-Osaka industrial corridors host integrated precursor-to-tape producers serving export markets.
India
The PLI scheme for advanced materials attracts tier-1 suppliers to establish tape laying capacity near Bengaluru's aerospace cluster. CDSCO biocompatibility frameworks govern medical device radiolucency applications. Gujarat and Maharashtra industrial zones see emerging compression molding investment for industrial equipment segments.
China
MIIT dual carbon goals accelerate lightweighting mandates across commercial aviation and new energy vehicle platforms. GB standards for composite structural certification evolve alongside SAMR market supervision. The Yangtze River Delta concentrates filament winding capacity for hydrogen storage vessel manufacturing.
Carbon Thermoplastic Composites Market Competitive Environment
Japanese and European producers anchor the precursor and specialty chemistry tier; North American fabricators hold automation and qualification advantages. The vendor base splits between consolidated PAN suppliers and fragmented compounders facing margin compression. Three archetypes dominate: backward-integrated fiber producers, specialty polymer formulators, and automated processing equipment specialists. Capacity expansion and long-term material service agreements represent the dominant competitive vectors.
Within the backward-integrated tier, Toray Industries Inc. and Teijin Ltd. occupy positions defined by captive PAN precursor supply. Solvay SA exemplifies the specialty chemistry archetype through polyamide formulations tailored to regulatory standards. Hexcel Corporation anchors the North American fabrication segment, representing automation-driven throughput advantages in aerostructure qualification programs.
| Leading Market Players |
|---|
| Toray Industries Inc. |
| Solvay SA |
| Teijin Ltd. |
| Hexcel Corporation |
| SGL Carbon SE |
| BASF SE |
| Avient Corporation |
| Celanese Corporation |
| DowAksa |
| Others |
Value Chain & Pricing Dynamics
Aerospace OEM mandates for thermoplastic airframe qualification are compressing supplier timelines and forcing tape producers to absorb certification costs upfront, tightening margin structures for non-integrated compounders while rewarding backward-integrated fiber suppliers with pricing power anchored in captive PAN precursor supply.
Pricing Analysis
High-volume automotive polyamide compounds trade at thinner margins than aerospace-grade unidirectional tape, where qualification barriers sustain premium positioning. Three-tier pricing structure across aerospace-certified, industrial-performance, and commodity grades separates segments by fiber modulus and lot traceability depth. Pricing pressure stems from acrylonitrile feedstock volatility transmitting through PAN precursor costs. Tier-1 automotive suppliers in Germany's Stuttgart corridor exhibit highest price sensitivity, while FAA-certified aerostructure programs accept cost premiums for damage-tolerant grades.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States consolidate tape inventory for just-in-time delivery to aerospace clusters, compressing working capital requirements for tier-1 fabricators. Raw material flows draw from Japanese PAN precursor capacity, European specialty polyamide resin production, and Chinese carbon fiber expansion. Single-source vulnerability concentrates in aerospace-grade PAN supply, where three producers anchor global capacity. Distribution runs through long-term material service agreements that displace spot purchasing for qualified programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a technology-transition phase where automated fiber placement and induction welding displace thermoset autoclave curing, rewarding capital deployment toward robotic tape laying and modular welding cells.
For Market Incumbents: Cement backward integration into PAN precursor production or lock long-term offtake agreements to defend against raw material volatility. Invest in welding parameter certification capacity to preempt FAA-EASA harmonization delays that threaten program timelines. Prioritize automated fiber placement throughput advantages as thermoset incumbents delay conversion. For New Entrants and Emerging Players: Capture white-space in medical device radiolucency applications and hydrogen storage vessel filament winding, where qualification barriers remain lower than primary aerostructures. India's PLI scheme for advanced materials offers the most penetrable geography for tape laying capacity establishment. Pursue joint development agreements with EV-native manufacturers seeking structural battery enclosure suppliers outside established German supply chains. For Investors and Strategic Acquirers: The window for entry favors specialty polymer formulators with EMA MDR and FAA certification track records, positioned for medical and aerospace demand convergence. Long-term viability hinges on recycling infrastructure deployment as REACH end-of-life responsibility clarifies. Watch for welding standard harmonization between FAA and EASA as the signal for accelerated thermoplastic substitution in primary structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PAN Precursor | Captive acrylonitrile supply secures margin stability against petrochemical volatility for high-modulus grades. |
| Automated Fiber Placement Scale-Up | Robotic tape laying achieves aerospace repeatability at automotive throughput, collapsing thermoset cost advantages. |
| Long-Term Material Service Agreements | Ten-year contracts with fixed-price escalators concentrate procurement leverage with integrated fiber-to-tape producers. |
| Induction Welding Certification Investment | Mobile welding cells eliminate autoclave constraints, enabling tier-2 entry into primary aerostructure fabrication. |
| Recycling Infrastructure Deployment | Pyrolysis and solvolysis capacity addresses REACH end-of-life mandates while securing feedstock for circular production. |
Study Parameters
Multi-period observation of aerospace OEM procurement patterns, automotive platform electrification timelines, and regulatory standard evolution anchored the trend analysis, supplemented by interviews with tier-1 aerostructure procurement directors, composite plant managers, EMA regulatory affairs leads, and automated fiber placement equipment specialists. Secondary validation drew from FAA certification databases, ECHA substance restriction proposals, SEC filings of listed fiber producers, and customs trade data for carbon fiber precursor flows. Bottom-up segment sizing triangulated against top-down aerospace and automotive production forecasts.
Input-output matrices modeled demand across matrix chemistry, forming technique, and supply chain position dimensions, with value outputs derived from price-volume relationships across the projection horizon. CAGRs were computed from segment-level growth trajectories weighted by end-use exposure. Forecast inputs incorporated EV platform battery enclosure specifications, hydrogen storage vessel adoption curves, and medical device radiolucency substitution rates without year-specific milestones.
The model holds under continued FAA-EASA regulatory convergence and stable acrylonitrile feedstock availability; deviation in welding standard harmonization timelines or Japanese PAN supply disruption would shift volume trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Laminar Composites Market
Composite Materials
Wood Plastic Composite (WPC) Market
Composite Materials
Europe Composites Market
Composite Materials
Graphite Felt Market
Composite Materials
Ultra-Lightweight Cement Composites Market
Composite Materials
Thermoplastic Prepreg Market
Composite Materials
Synthetic Rope Market
Composite Materials
Phenolic Panel Market
Composite Materials
Global Carbon Graphite Bushings Market
Composite Materials
Fiber Reinforced Plastic (FRP) Panels and Sheets Market
Composite Materials
Asia-Pacific Molded FRP Grating Market
Composite Materials
Global Lightweight Construction Material Market
Composite Materials
Global Carbon Fiber Reinforced Plastic Market
Composite Materials
Structural Composites Market
Composite Materials
GCC Decorative Laminates Market
Composite Materials
Carbon Composites Market