
 South America Engineering Plastics Market | 2026-2036
South America Engineering Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
South America Engineering Plastics Market Analytics
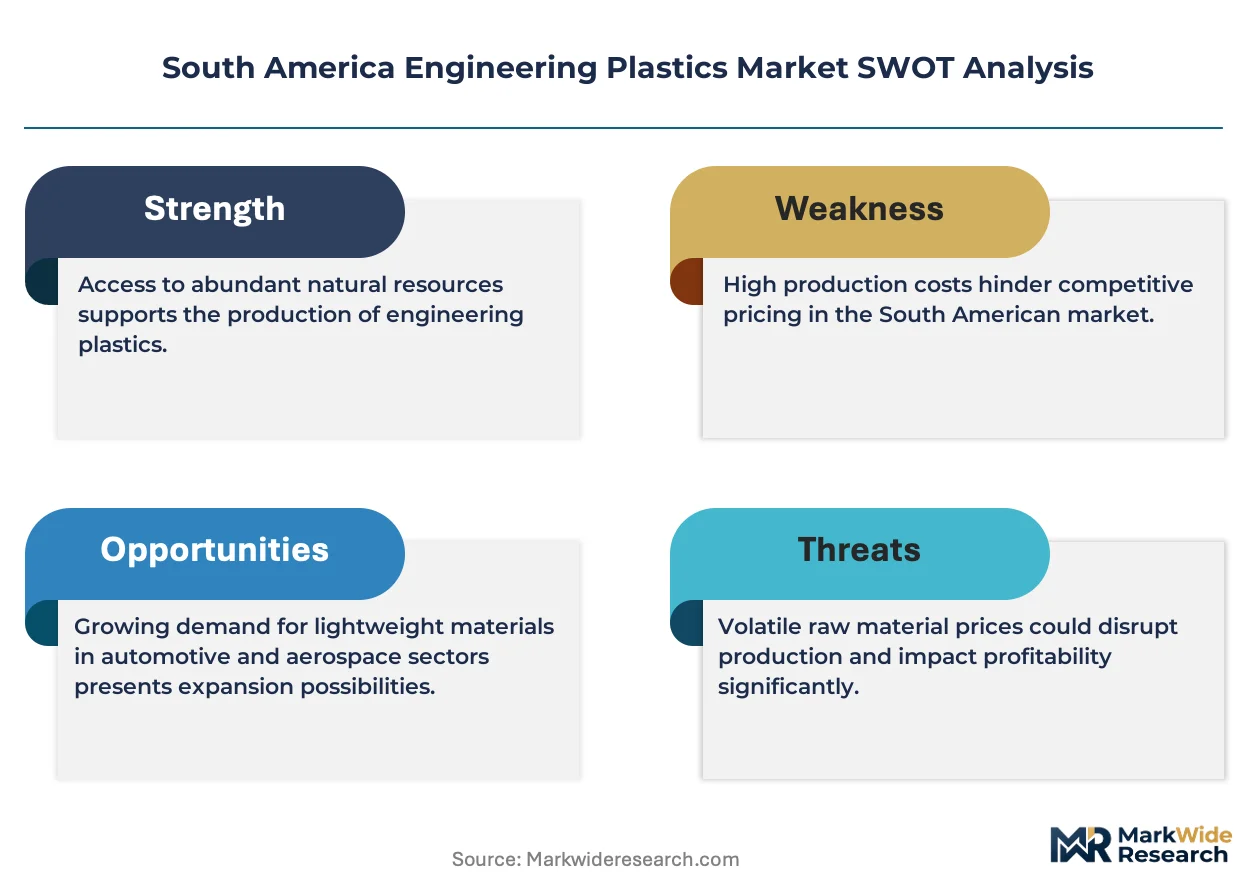
Asset-light leasing models for polymer compounding lines is narrowing the capital barrier for mid-tier processors entering the South America Engineering Plastics Market. Braskem leverages its captive petrochemical feedstock to dominate polyethylene and polypropylene precursor supply. LANXESS sustains specialty polyamide production from its Brazilian manufacturing base. Celanese Corporation anchors regional acetal copolymer supply through localized compounding operations.
South America engineering plastics encompass thermoplastic polymers engineered to withstand mechanical loads above 100 MPa tensile strength while maintaining dimensional stability across temperature ranges from minus 40°C to 150°C. These materials substitute metal in precision components where weight reduction and corrosion resistance deliver operational cost savings. Polyamide leads product type demand due to established automotive under-hood specifications and tire cord applications. Polycarbonate competes aggressively in electrical housings and LED luminaire lenses where optical clarity meets flame retardance. Polyoxymethylene occupies precision gear and conveyor system niches requiring low friction coefficients and fatigue endurance.
Brazil's ANVISA enforces biocompatibility protocols for medical device polymers, while INMETRO certification governs electrical and electronic material flame retardance across Mercosur trading zones. Argentina's national chemical regulator mandates incremental recycled content disclosures for packaging-grade engineering plastics entering consumer goods supply chains. Stakeholders must monitor evolving Mercosur technical regulations and sub-national environmental licensing timelines to align capacity investments with compliance windows.
Market Dynamics
Automotive OEMs in Brazil are accelerating metal-to-polymer substitution in powertrain components, creating a structural pull for high-heat polyamide and PPS grades that withstand continuous operating temperatures above 130°C.
Growth Catalysts
- ANVISA biocompatibility mandates:Brazil's medical device regulator is tightening implant-grade resin standards, forcing domestic compounders to upgrade purification and traceability systems for surgical polymer supply.
- Lightweighting specifications:Automotive under-hood applications in São Paulo's industrial corridor are specifying glass-filled polyamide for intake manifolds and cooling modules to meet fuel efficiency targets.
- LED luminaire expansion:Electrical manufacturers across Mercosur trading zones are specifying flame-retardant polycarbonate for housing and lens applications in commercial lighting retrofits.
Market Restraints
- Caprolactam import dependency:Polyamide 6 precursor supply concentrates in Asian petrochemical complexes, exposing Brazilian compounders to freight cost volatility and currency fluctuation risk.
- INMETRO certification timelines:Electrical material flame-retardance testing for Mercosur compliance extends 14-18 months, delaying new grade commercialization and freezing formulation flexibility.
- Recycled content verification:Argentina's national chemical regulator mandates incremental post-consumer resin disclosures that lack standardized testing protocols, creating audit friction for cross-border shipments.
Strategic Opportunities
- Asset-light leasing models:Polymer compounding line rentals are narrowing capital barriers for mid-tier processors in Colombia and Chile seeking entry without full ownership burden.
- Medical device localization:ANVISA's tightening biocompatibility protocols favor domestic compounders with validated cleanroom operations over import-dependent distributors.
- Renewable feedstock integration:Braskem's bio-based polyethylene pipeline creates precedent for sugarcane-derived engineering plastic precursors in sustainable automotive specifications.
Industry Challenges
- Compounder talent scarcity:Formulation chemists with expertise in glass-fiber interface optimization and heat-stabilizer packages remain concentrated in São Paulo, constraining regional expansion.
- Sub-national licensing fragmentation:Environmental permits for compounding facilities vary across Brazilian states, with São Paulo's CETESB requiring 8-12 additional months versus Minas Gerais timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Engineering Plastics Market |
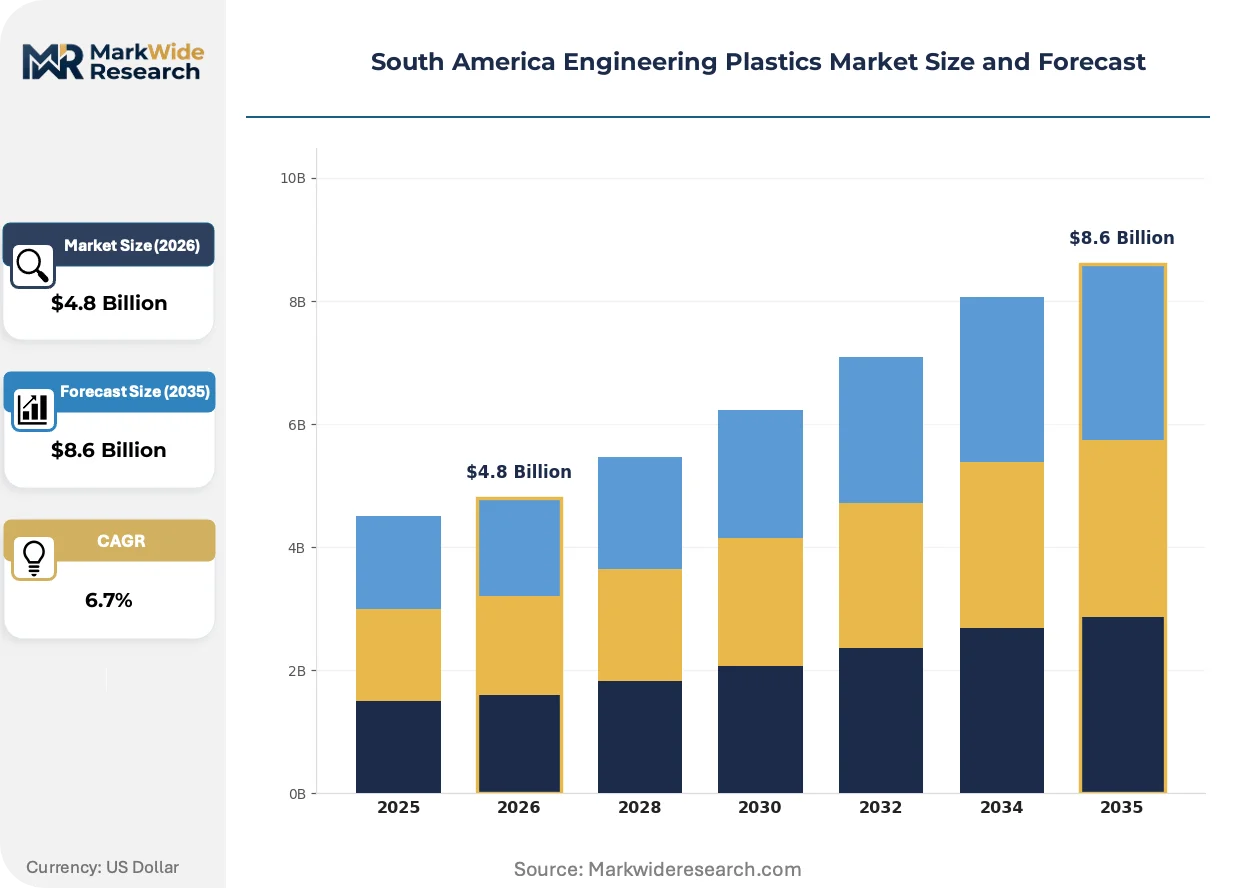
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Polyamide, Polyoxymethylene, Acrylic End User: Automotive OEMs, Electrical & Electronics, Packaging, Medical Devices Application: Aerospace Components, Consumer Goods, Industrial Equipment, Construction Materials Form: Sheets, Films, Rods, Tubes |
| Companies Covered | Celanese Corporation, LANXESS, Braskem, Mitsubishi Chemical Corporation, SABIC, Unigel Plastico, Covestro AG, Alfa S.A.B. de C.V., BASF SE, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Engineering Plastics Market Evolving Landscape
Digital process control and regulatory convergence are compressing development cycles for engineering plastics across South American manufacturing clusters, with compounders investing in real-time viscosity monitoring and predictive quality systems.
Real-time rheology monitoring is digitizing quality assurance workflows in Brazilian compounding operations. Automotive Tier 1 suppliers in São Paulo's ABC region are mandating batch-to-batch melt-flow consistency data streams for just-in-time delivery contracts. This sensor integration is digitizing supplier qualification processes and compressing incoming inspection timelines from weeks to hours.
REACH-equivalent substance restrictions are migrating into Mercosur technical regulations through bilateral alignment protocols. Brazil's INMETRO and Argentina's IRAM are adopting EU SVHC screening methodologies for electrical and electronic material certifications. Polybrominated flame retardant grades are losing formulation share to phosphorus-nitrogen synergists in connector and housing applications.
Buyers are consolidating resin procurement through compounder-direct contracts that bypass traditional distributor markups. Automotive OEMs in Brazil's industrial south are negotiating annual volume commitments with LANXESS and Celanese for standardized polyamide and acetal grades. This channel compression is most visible in tire cord and precision gear supply chains where specification stability reduces switching costs.
South America Engineering Plastics Market Segmentation
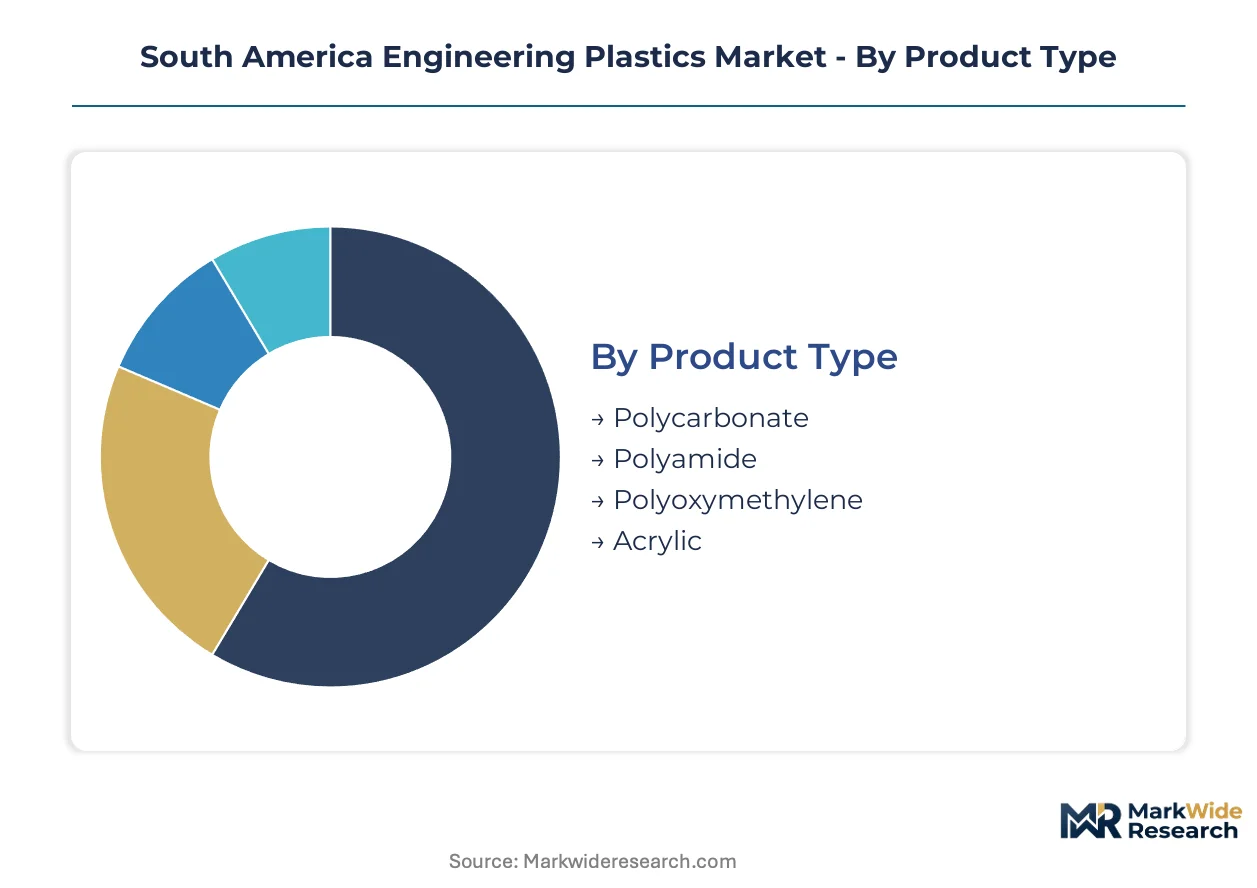
Engineering plastics in South America fragment across multiple technical dimensions that determine procurement patterns and margin structures. Each segmentation axis reveals distinct supply chain configurations and regulatory exposure profiles that shape compounder strategy.
Product Type:
Mature commodity grades dominate volume flows while specialty formulations capture expanding specification premiums across Brazilian automotive and medical channels.
- Polyamide:Glass-reinforced and heat-stabilized grades withstand continuous operating temperatures above 130°C in powertrain housings. Demand concentrates in São Paulo's industrial corridor where automotive Tier 1 suppliers mandate batch-to-batch melt-flow consistency for just-in-time intake manifold delivery.
- Polycarbonate:Optical-grade clarity combined with flame-retardant formulations serves LED luminaire lenses and electrical housing applications. Mercosur electrical manufacturers specify INMETRO-certified grades for commercial lighting retrofits across Brazil and Argentina.
- Polyoxymethylene:Low-friction acetal copolymers occupy precision gear and conveyor system niches requiring fatigue endurance and dimensional stability.
- Acrylic:Transparent thermoplastic sheets compete in signage and lighting diffuser segments where UV resistance and weatherability justify premium positioning over commodity alternatives.
Polyamide handles the majority of throughput; Polycarbonate is the fastest mover on share.
End User:
Customer concentration varies sharply across buyer sophistication tiers, with regulatory compliance capabilities determining supplier qualification barriers.
- Automotive OEMs:Metal-to-polymer substitution accelerates in under-hood components as Brazilian fuel efficiency targets tighten. OEMs negotiate direct compounder contracts bypassing traditional distributor markups for standardized polyamide and acetal grades.
- Medical Devices:ANVISA biocompatibility mandates for implant-grade resins force domestic compounders to upgrade purification and traceability systems. Surgical polymer supply favors validated cleanroom operations over import-dependent channels.
- Electrical & Electronics:Flame-retardant specifications dominate procurement with REACH-equivalent substance restrictions migrating into Mercosur technical regulations through bilateral alignment protocols.
- Packaging:Argentina's national chemical regulator mandates incremental recycled content disclosures creating audit friction for cross-border shipments of engineering-grade films and containers.
Automotive OEMs anchor volume commitments; Medical Devices is expanding most quickly on specification premiums.
Application:
Performance requirements diverge across load-bearing, optical, and environmental exposure use cases that dictate resin selection and additive packages.
- Industrial Equipment:Bearing surfaces, pump housings, and conveyor components specify POM and filled polyamide grades where wear resistance and chemical inertness reduce maintenance intervals.
- Consumer Goods:Durable appliance housings and power tool bodies balance impact strength with surface aesthetics through PC/ABS blends and reinforced polyamide.
- Aerospace Components:Interior cabin applications specify flame-retardant polycarbonate and PEEK grades meeting smoke-toxicity protocols for regional aircraft manufacturing.
- Construction Materials:Glazing panels, roofing membranes, and structural profiles utilize polycarbonate sheets and acrylic rods where weatherability and light transmission replace glass and metal.
Industrial Equipment commands the deepest formulation expertise; Construction Materials is climbing the fastest on infrastructure investment cycles.
Form:
Processing method and downstream fabrication economics determine form factor selection across extrusion, injection molding, and machining value chains.
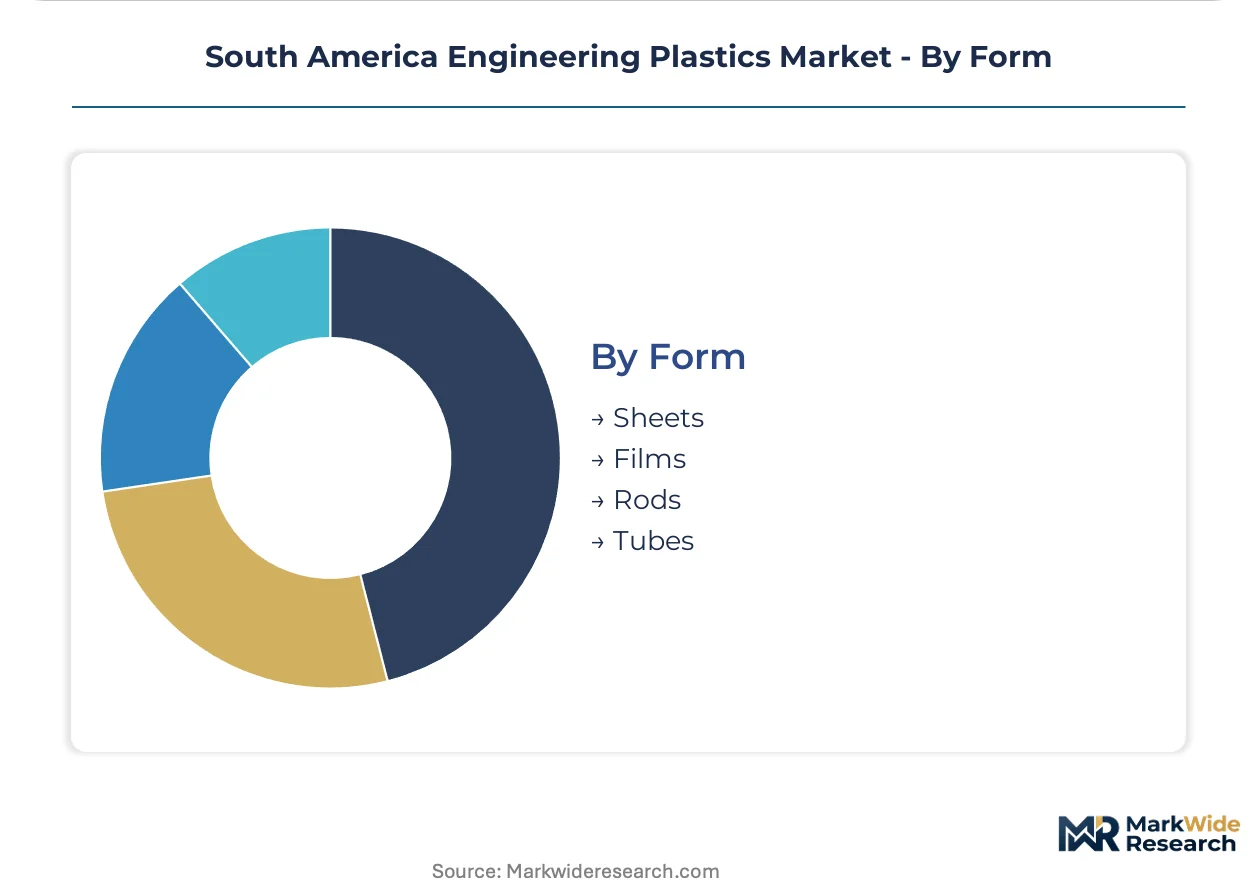
- Sheets:Flat extruded panels serve thermoforming operations for equipment housings, aircraft interior panels, and architectural glazing where thickness tolerance and optical clarity are specified.
- Films:Thin-gauge extruded and cast films package medical devices and electrical insulation with barrier properties and sterilization compatibility.
- Rods:Solid cylindrical stock feeds precision machining operations for gears, bearings, and custom mechanical components where tight tolerances exceed extrusion capabilities.
- Tubes:Hollow extruded profiles convey fluids and protect wiring harnesses across automotive and industrial equipment assemblies.
Sheets generate the broadest application coverage; Films is gaining share fastest on medical device localization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in São Paulo's industrial corridor while Colombian and Chilean processors absorb freight premiums on imported caprolactam. Brazilian compounders leverage ANVISA-validated cleanrooms to capture medical-grade premiums that Argentine suppliers forfeit to cross-border certification delays.
Brazil
Automotive OEMs in São Paulo's ABC region specify glass-filled polyamide for intake manifolds and cooling modules under tightening fuel efficiency mandates. ANVISA enforces biocompatibility protocols for implant-grade resins that favor domestic compounders with validated purification systems. Braskem anchors polyethylene and polypropylene precursor supply from its captive petrochemical complex in the industrial southeast.
Argentina
Electrical manufacturers specify INMETRO-certified flame-retardant grades for LED luminaire retrofits across Buenos Aires manufacturing zones. The national chemical regulator mandates incremental recycled content disclosures for packaging-grade engineering plastics entering consumer goods supply chains. Mendoza's industrial parks host compounders serving Andean mining equipment demand for wear-resistant POM bearings.
Chile
Asset-light leasing models for polymer compounding lines narrow capital barriers for mid-tier processors in Santiago's manufacturing belt. The country's national mining regulator drives specification of fatigue-resistant polyamide in conveyor systems for copper extraction operations. Antofagasta's mineral processing clusters import precision-machined acetal gears from Brazilian suppliers.
Colombia
Packaging converters in Bogotá's industrial corridor adopt polycarbonate sheets for thermoformed medical device housings. The national standards body aligns technical regulations with Mercosur protocols to facilitate cross-border resin shipments. Medellín's precision manufacturing base sources flame-retardant PC/ABS blends for appliance housings through distributor-direct contracts.
South America Engineering Plastics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on formulation expertise. The South America Engineering Plastics Market structures around three tiers: petrochemical majors with captive feedstock, regional compounders with validated cleanroom operations, and import-dependent distributors serving spot demand. Strategic archetypes include backward-integrated resin producers, specialty polyamide formulators, and medical-grade certification specialists. Competitive moves center on direct OEM contract negotiation bypassing traditional distribution and ANVISA cleanroom validation investment.
Among petrochemical majors with regional manufacturing presence, Braskem anchors polyethylene and polypropylene precursor supply from its Brazilian base. LANXESS occupies the specialty polyamide tier with localized production serving automotive under-hood specifications. Celanese Corporation exemplifies the precision polymer archetype through regional acetal copolymer compounding operations.
| Leading Market Players |
|---|
| Celanese Corporation |
| LANXESS |
| Braskem |
| Mitsubishi Chemical Corporation |
| SABIC |
| Unigel Plastico |
| Covestro AG |
| Alfa S.A.B. de C.V. |
| BASF SE |
| Others |
Value Network & Pricing Analysis
São Paulo's industrial corridor concentrates compounding capacity for glass-filled polyamide and flame-retardant polycarbonate, giving validated compounders pricing leverage over import-dependent distributors serving Andean markets. ANVISA certification timelines and INMETRO testing windows create structural premiums for domestic medical-grade and electrical-grade supply, while freight-inflated caprolactam costs compress margins for non-integrated processors.
Pricing Analysis
Configured-to-order pricing for implant-grade resins commands spreads of 40-60% above standard polyamide grades due to ANVISA cleanroom validation and batch traceability requirements. Three-tier pricing structure across premium, standard, and economy levels segments by certification tier and volume commitment, with automotive OEMs locking annual contracts to bypass distributor markups. Pricing pressure stems from Asian caprolactam cost volatility transmitted through import-dependent compounders. Medical device manufacturers show lowest price sensitivity given regulatory switching costs, while packaging converters face acute margin compression from Argentina's recycled content audit requirements.
Supply Chain Analysis
Contract manufacturing concentrates with Braskem's captive petrochemical complex in Brazil's industrial southeast, LANXESS's specialty polyamide operations, and Celanese's regional acetal compounding facilities. Raw material flows draw from Asian petrochemical complexes for caprolactam, Middle Eastern feedstock for polyethylene precursors, and domestic sugarcane ethanol for bio-based polyethylene pipelines. Single-source vulnerability runs through polyamide 6 precursor supply concentrated in Asian complexes. Distribution runs through compounder-direct contracts with automotive OEMs and medical device manufacturers, bypassing traditional distributor networks for standardized grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for formulation optimization and regulatory filing support are expanding faster than resin volume, creating recurring revenue layers that compounders can attach to base polymer supply. This service-attach dynamic favors players with ANVISA-validated cleanrooms and INMETRO-certified testing capabilities.
For Market Incumbents: Insulate margin position by deepening backward integration into bio-based feedstock streams following Braskem's sugarcane-derived polyethylene precedent, and by locking multi-year technical service contracts with automotive Tier 1 suppliers in São Paulo's ABC region. Threat substitution from metal-to-polymer conversion reversals under fuel efficiency mandate delays demands defensive capacity reallocation toward medical-grade certification tiers. For New Entrants and Emerging Players: Build out asset-light leasing models for compounding lines in Colombia and Chile where capital barriers have excluded mid-tier processors from specification-driven automotive and medical supply chains. The most penetrable white-space sits in Santiago's manufacturing belt serving Antofagasta mining equipment demand with fatigue-resistant polyamide conveyor components. Go-to-market leverage rests on ANVISA cleanroom partnerships with established Brazilian compounders rather than greenfield certification timelines. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because ANVISA biocompatibility mandates and INMETRO certification windows are structurally extending domestic compounder moats against import-dependent distributors. Acquisition targets should screen for validated cleanroom operations and existing OEM direct-contract relationships. The signal to watch is Mercosur technical regulation alignment velocity, which would either consolidate Brazilian regulatory advantages or dilute them through mutual recognition protocols.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Cleanroom Validation Investment | Captures implant-grade resin premiums that import-dependent distributors forfeit to cross-border certification delays. |
| Backward Integration into Bio-Based Feedstock | Replicates Braskem's sugarcane-derived polyethylene precedent for sustainable automotive specifications. |
| Asset-Light Compounding Line Leasing | Narrows capital barriers for mid-tier processors entering Colombian and Chilean specification-driven markets. |
| Direct OEM Contract Negotiation | Bypasses traditional distributor markups in São Paulo automotive and medical device supply chains. |
| Technical Service Contract Expansion | Attaches recurring formulation optimization revenue to base polymer volume in just-in-time delivery relationships. |
Research Methodology
Cross-validation between primary interviews with compounder plant managers, automotive Tier 1 procurement leads, ANVISA regulatory affairs specialists, and medical device biomedical engineers anchors the qualitative findings against secondary validation through customs/trade data, SEC 10-K filings of listed petrochemical majors, and INMETRO certification databases. Bottom-up resin volume modeling triangulates with top-down end-use industry consumption estimates across automotive, medical, and electrical segments.
Calibration against historical capacity utilization rates and ANVISA approval timelines refines the analytical framework across the projection horizon. Segmentation dimensions include product grade tier, end-use industry vertical, certification status, and regional production hub. CAGRs derive from elasticity-adjusted demand projections incorporating fuel efficiency mandate trajectories and LED luminaire retrofit cycles.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian petrochemical majors establishing regional compounding footprints would shift outcomes beyond modeled ranges. Quarterly review of ANVISA certification queue lengths and Mercosur technical regulation alignment protocols is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market
Polymers & Resins
Microcellular Plastics Market
Polymers & Resins
Acrylic Monomers Market
Polymers & Resins
Thermoplastic Polyamide Elastomer (TPE) Market
Polymers & Resins
Melamine Formaldehyde Resin Powder Market
Polymers & Resins
Soft PVC Sealing Strip Market
Polymers & Resins
Polyisobutylene (PIB) Market
Polymers & Resins
Amorphous Polyethylene Terephthalate (APET) Market
Polymers & Resins
Polymer Modified Bitumen (PMB) Market
Polymers & Resins
Tie Layer Resin Market
Polymers & Resins
North America Polypropylene Copolymer Market
Polymers & Resins
Epoxy Resin Market
Polymers & Resins
Asia-Pacific Polyethylene Wax Market
Polymers & Resins
Bio-Based Polymer Market
Polymers & Resins
PEKK Market
Polymers & Resins
Dispersant Polymer Market