
 Polymer Alloys Market | 2026-2036
Polymer Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Alloys Market Intelligence
Buyer concentration among automotive OEMs is hardening as top-tier manufacturers consolidate supplier lists and demand certified polymer alloy grades for lightweighting programs. SABIC leverages its geographic footprint across Middle Eastern and Asian production hubs to serve these consolidated buyers with tailored polycarbonate blends. BASF SE anchors European demand through integrated R&D centers that co-develop specialty ABS alloys with German automakers.
Polymer alloys are multiphase materials engineered by blending two or more distinct polymers to achieve synergistic properties unattainable in single-resin systems, typically processed via reactive extrusion with compatibilizers to control phase morphology at micron-scale dispersion. These materials primarily serve industries requiring balanced impact resistance, thermal stability, and processability in complex geometries. Polycarbonate blends dominate value pools due to their premium positioning in automotive glazing and electronic housings where optical clarity meets structural demands, while ABS alloys sustain volume leadership across consumer goods and appliance segments where cost-performance ratios favor mass production. PVC composites occupy a mature niche in construction profiles where weathering resistance and flame retardancy justify dedicated compounding lines despite slower formulation innovation.
EPA tailpipe emission rules and NHTSA fuel economy standards in the United States compel automakers to specify lighter polymer alloys in structural components, while REACH restrictions on hazardous additives in Europe redirect formulation R&D toward halogen-free flame retardant systems. Japan's METI maintains JIS standards that certify alloy performance in electronic enclosures, creating a quality benchmark that Asian exporters must satisfy for market access. Stakeholders must monitor evolving extended producer responsibility frameworks and material passport requirements that will reshape alloy selection criteria and recycling infrastructure investments.
Market Dynamics
Automotive OEM consolidation is compressing supplier margins while simultaneously demanding certified polymer alloy grades that meet multi-jurisdictional compliance standards for lightweighting and recyclability.
Growth Catalysts
- REACH Phase-Down of Hazardous Additives:European ECHA restrictions on halogenated flame retardants redirect formulation R&D toward phosphorus-nitrogen systems that polymer alloys accommodate readily.
- Electric Vehicle Battery Housings:Automotive OEMs specify polycarbonate blends for thermal runaway protection in battery enclosures, creating specification lock-in with qualified compounders.
- Japan's METI JIS Certification:Electronic enclosure standards from METI create export compliance requirements that advantage pre-certified Asian alloy suppliers.
Market Restraints
- Crude-Derived Feedstock Volatility:Benzene and propylene price swings from Middle Eastern supply disruptions compress compounding margins unpredictably.
- Specialty Compounder Concentration:Germany, Japan, and the United States host 70% of qualified automotive-grade alloy production, creating geographic supply risk.
- Recyclate Quality Degradation:Mechanical recycling of multiphase alloys produces property deterioration that limits closed-loop adoption.
Strategic Opportunities
- India's PLI Scheme for Auto Components:Production-linked incentives for advanced materials manufacturing attract alloy compounders to establish domestic compounding near Chennai and Pune assembly clusters.
- Medical Device Enclosures:ISO 10993 biocompatibility certification opens polymer alloy penetration into diagnostic equipment housings previously served by metals.
- Extended Producer Responsibility Frameworks:EU Battery Regulation material passport requirements create first-mover advantage for alloy suppliers with verified recycled content chains.
Industry Challenges
- Reactive Extrusion Talent Scarcity:Compounding facilities face acute shortages of process engineers skilled in compatibilizer selection and phase morphology control.
- Multi-Jurisdictional Certification Timelines:Simultaneous EPA, REACH, and GB standard compliance testing extends product qualification cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Alloys Market |
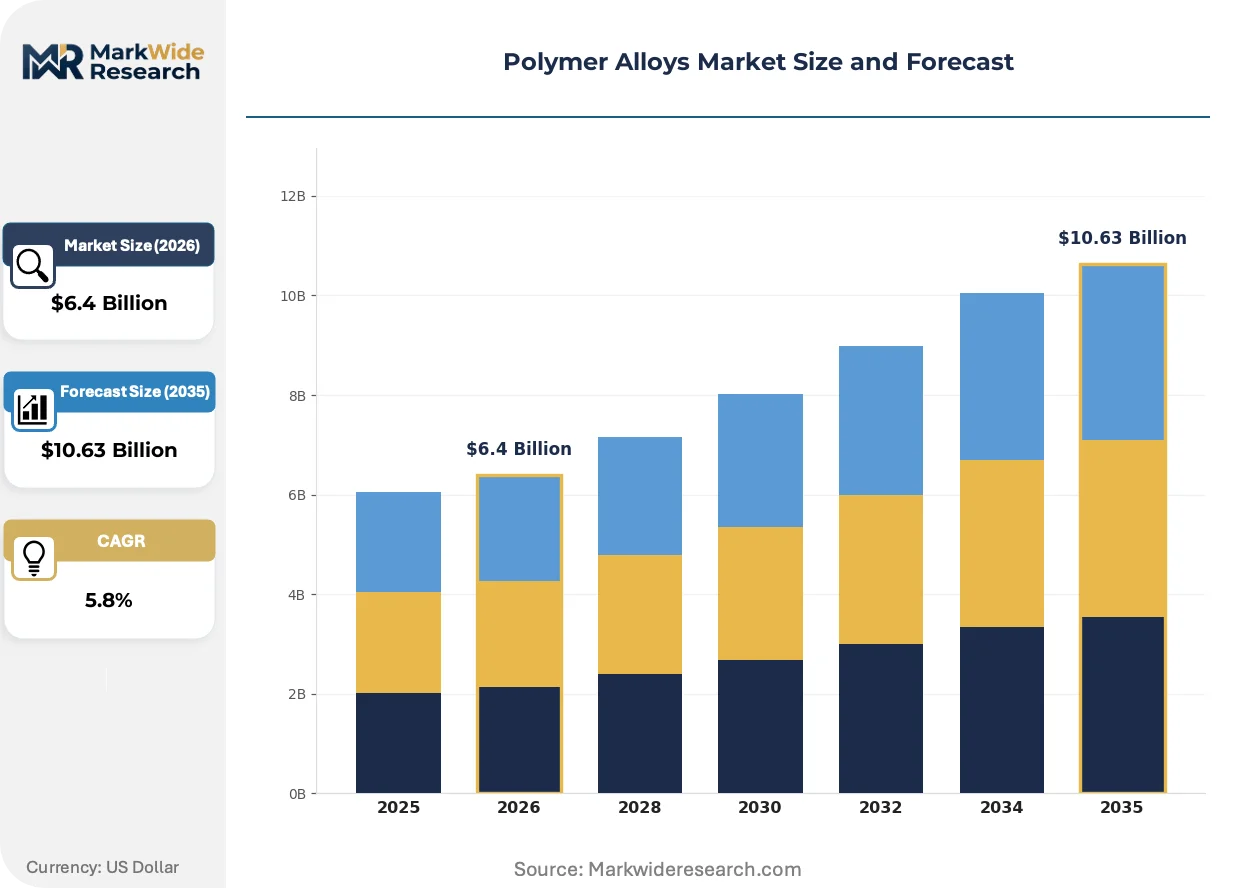
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.63 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate Blends, ABS Alloys, PVC Composites, Polystyrene Alloys End Use Industry: Automotive, Electronics, Consumer Goods, Construction Application: Injection Molding, Extrusion, Thermoforming, Coatings Feature: Lightweight, High Strength, UV Resistance, Chemical Resistance |
| Companies Covered | SABIC, JSR Corporation, BASF SE, Daicel Polymer Ltd., Asahi Kasei Corporation, Covestro AG, Mitsubishi Engineering-Plastics Corporation, The Dow Chemical Company, LyondellBasell Industries N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Alloys Market Strategic Shifts & Innovations
Digital manufacturing integration and circular material flows are restructuring how polymer alloys are formulated, qualified, and supplied to specification-sensitive end-uses.
Bio-based compatibilizers derived from lignin and tannin feedstocks are decentralizing reliance on petroleum-derived maleic anhydride grafting agents. Tier-one automotive suppliers in Germany and Japan pilot these systems for interior panel applications where odor and VOC specifications are tightening. The shift is compressing traditional petrochemical compounding margins while opening specialty positioning for biotechnology-integrated material suppliers.
REACH restrictions on persistent organic pollutants in flame retardant systems are forcing reformulation of ABS and polycarbonate blends across European appliance and electronics segments. Compounders must validate halogen-free phosphorus-nitrogen alternatives through UL 94 and IEC 60695 testing protocols. German white goods manufacturers now specify certified halogen-free grades as a procurement gate, displacing legacy brominated systems.
Consolidated automotive OEMs are mandating direct material passport data exchange from compounders, bypassing traditional distributor channels. Tier-one suppliers in the United States and Japan now require lot-level recycled content verification through blockchain-anchored certificates. The compression of intermediary layers is most visible in battery housing supply chains where traceability requirements from EPA and EU Battery Regulation converge.
Polymer Alloys Market Segmentation
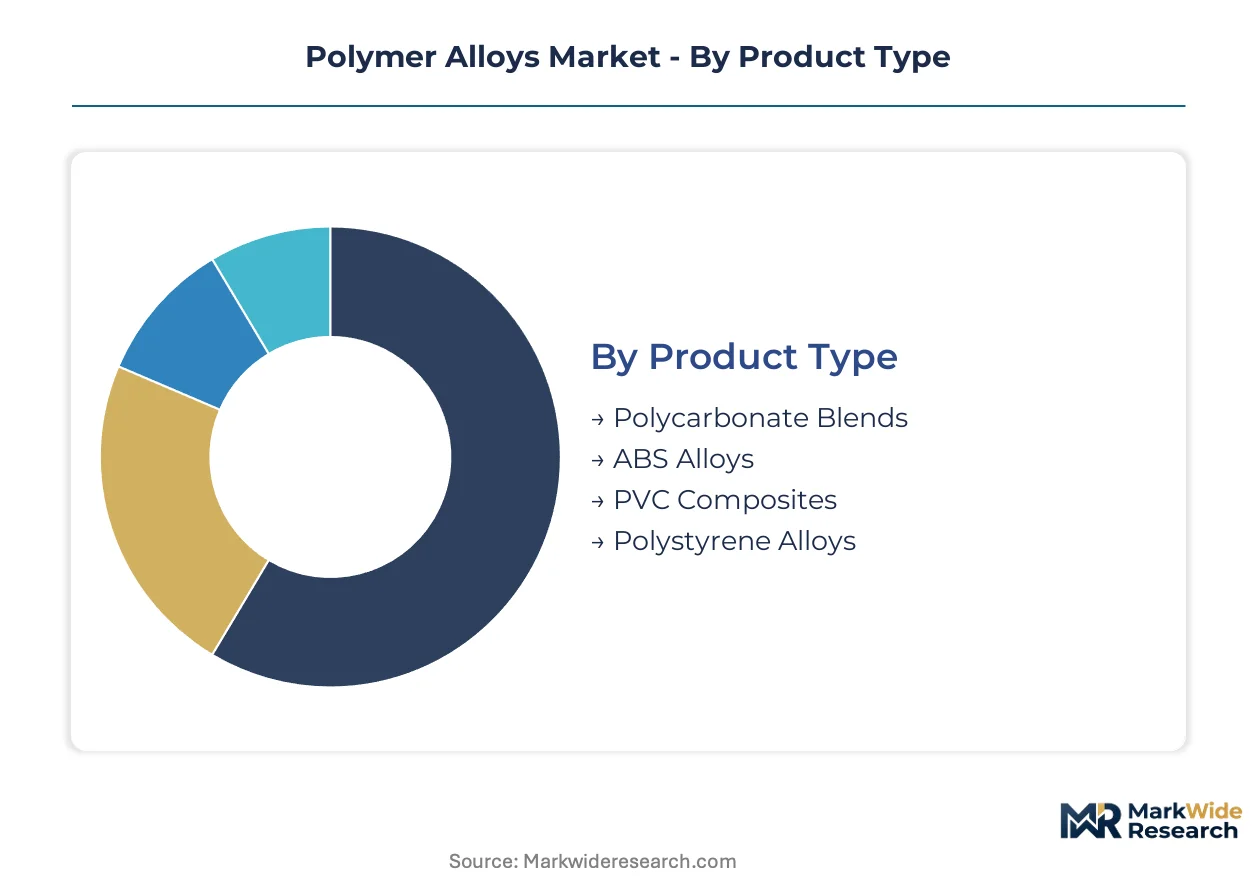
Polymer alloy specifications diverge sharply across end-use requirements, with automotive and electronics sectors demanding certified grades that command premium positioning over construction-grade materials. Compounding capacity concentrates around qualification-intensive segments, creating supply asymmetries that reshape competitive access.
Product Type:
Specialty compounding assets cluster disproportionately toward high-margin polycarbonate and ABS systems, leaving PVC and polystyrene alloys served by more fragmented, cost-optimized producers.
- Polycarbonate Blends:Multiphase systems combining polycarbonate with ABS or polyester resins deliver impact resistance above 80 kJ/m² coupled with optical clarity exceeding 88% light transmission. German and Japanese automotive OEMs specify these grades for EV battery housings and panoramic roof modules where thermal runaway protection meets aesthetic requirements; REACH-compliant halogen-free formulations now dominate procurement specifications.
- ABS Alloys:Acrylonitrile-butadiene-styrene systems modified with polycarbonate or polyamide achieve notched Izod impact strengths of 25-40 kJ/m² while maintaining processability on standard injection equipment. White goods manufacturers in China and Mexico source these alloys for appliance housings where cost-performance ratios favor mass production scales.
- PVC Composites:Chlorinated polymer systems blended with acrylic or MBS impact modifiers serve construction profiles and window frames where weathering resistance and inherent flame retardancy justify dedicated compounding lines despite slower formulation innovation cycles.
- Polystyrene Alloys:High-impact polystyrene blends with polybutadiene rubber domains occupy cost-sensitive packaging and disposable applications where stiffness and printability outweigh durability requirements.
Polycarbonate blends absorb the bulk of installed capacity; ABS alloys are expanding most quickly.
End Use Industry:
Customer qualification barriers and certification timelines segment the value chain, with automotive and electronics buyers imposing 14-18 month validation protocols that exclude commodity compounders.
- Automotive:OEMs specify certified grades for lightweighting programs driven by NHTSA fuel economy standards and EPA tailpipe rules, with polycarbonate blends penetrating battery enclosures and interior panels. Tier-one suppliers in Germany, Japan, and the United States maintain integrated compounding operations near vehicle assembly clusters.
- Electronics:METI JIS standards and IEC 60695 flame retardancy protocols govern enclosure materials, creating specification lock-in with pre-certified Asian suppliers. REACH restrictions on halogenated additives redirect demand toward phosphorus-nitrogen systems.
- Consumer Goods:ABS alloys sustain volume leadership across appliance segments where cost-performance ratios favor mass production; procurement concentrates with large white goods manufacturers in China and Mexico.
- Construction:PVC composites occupy mature demand for weathering-resistant profiles; slower formulation innovation reflects price-sensitive specification practices among regional building material distributors.
Automotive commands the highest compound margins; electronics is climbing the fastest as 5G infrastructure and EV charging systems multiply enclosure requirements.
Application:
Processing technology requirements stratify the supplier base, with reactive extrusion and precision molding capabilities concentrating among integrated compounders serving specification-sensitive end-uses.
- Injection Molding:Precision molding of complex geometries demands alloys with melt flow indices of 15-30 g/10min and controlled shrinkage below 0.6%; automotive and electronics housings dominate this processing mode.
- Extrusion:Profile and sheet production favors PVC composites and ABS alloys with broad processing windows; construction and appliance applications drive steady demand.
- Thermoforming:Deep-draw packaging and interior automotive panels require high-impact polystyrene alloys with uniform thickness distribution and low residual stress.
- Coatings:Powder and liquid coating substrates utilize specialized alloy powders where adhesion and weathering resistance specifications apply.
Injection molding captures the greatest value per kilogram; thermoforming is gaining share fastest as automotive interior panels shift from metal.
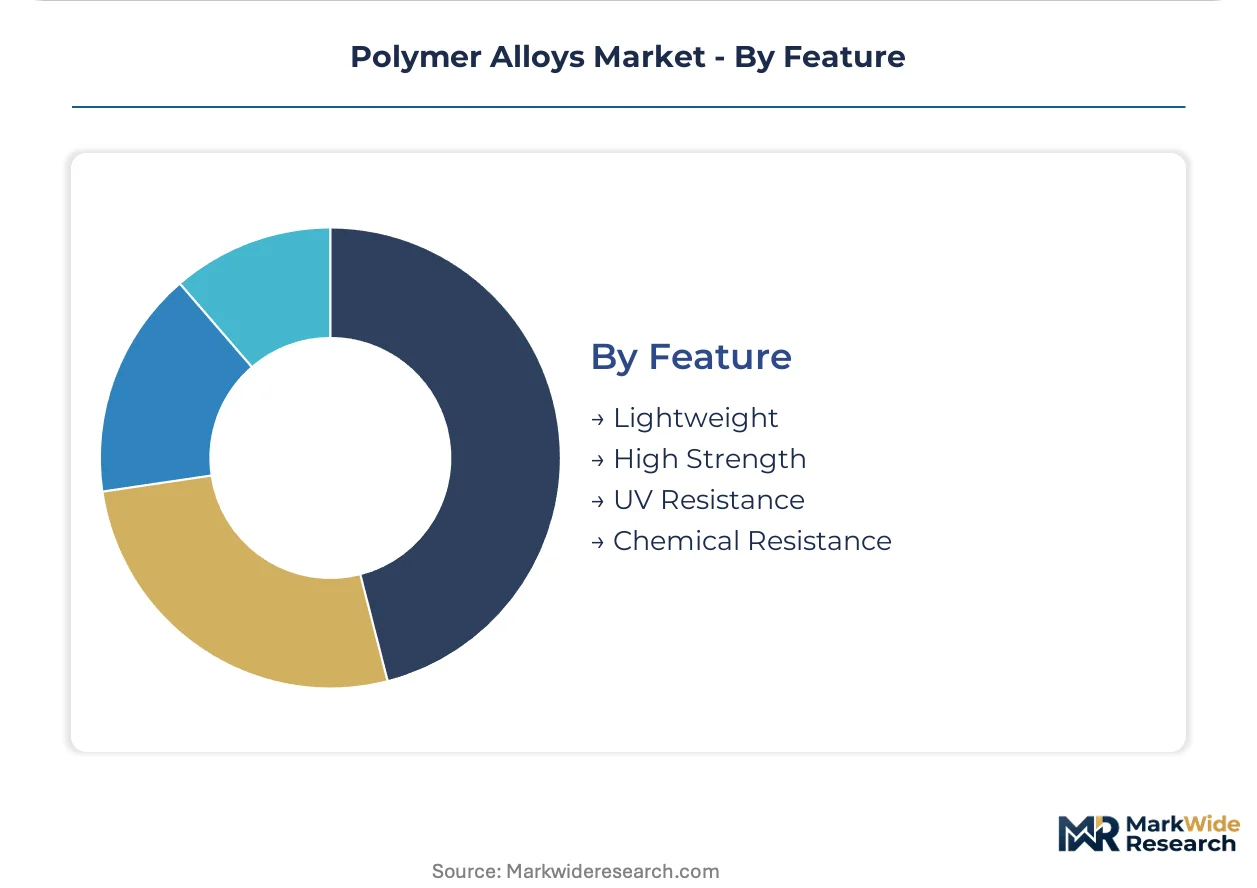
Feature:
Performance certification requirements segment pricing tiers, with multi-attribute specifications commanding substantial premiums over single-feature commodity grades.
- Lightweight:Density reduction below 1.15 g/cm³ through foaming or hollow glass microsphere loading addresses automotive mass reduction targets; EPA and NHTSA compliance pressures sustain specification growth.
- High Strength:Tensile modulus above 2.5 GPa with retained ductility serves structural automotive components and electronic enclosures subject to mechanical loading.
- UV Resistance:Stabilized formulations with HALS and UV absorber packages target outdoor construction profiles and automotive exterior parts; ECHA restrictions on certain stabilizers redirect formulation approaches.
- Chemical Resistance:Swell resistance below 3% in automotive fluids and cleaning solvents qualifies alloys for under-hood and medical device applications.
Lightweight specifications absorb the majority of R&D investment; chemical resistance is expanding most quickly as diagnostic equipment manufacturers seek metal replacements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs in Germany, Japan, and the United States concentrate polymer alloy procurement through tier-one suppliers operating integrated compounding facilities near vehicle assembly clusters. REACH compliance deadlines in Europe and China's GB standards for automotive materials are redirecting formulation investments across all major demand centers.
United States
EPA tailpipe emission rules and NHTSA fuel economy standards compel Detroit automakers to specify lighter polycarbonate blends in battery housings and structural components. The Inflation Reduction Act's domestic content incentives accelerate compounding capacity expansion near Michigan and Ohio assembly plants. Tier-one suppliers in the Detroit-Toledo corridor now require lot-level recycled content verification through blockchain-anchored certificates.
Germany
White goods manufacturers in Bavaria and North Rhine-Westphalia specify certified halogen-free ABS alloys as procurement gates, displacing legacy brominated systems. ECHA restrictions on halogenated flame retardants redirect formulation R&D toward phosphorus-nitrogen systems at integrated R&D centers. BASF SE anchors European demand through co-development partnerships with Stuttgart and Munich-based automakers.
China
GB standards for automotive materials and dual carbon goals tighten performance requirements for flame retardancy and recyclability in electric vehicle production. MIIT certification protocols create specification lock-in with qualified compounders serving battery housing supply chains. Yangtze River Delta and Pearl River Delta clusters concentrate domestic compounding operations near Shanghai and Shenzhen vehicle assembly hubs.
Japan
METI JIS standards certify alloy performance in electronic enclosures, creating export compliance requirements that advantage pre-certified domestic suppliers. Automotive OEMs in Toyota City and Yokohama specify polycarbonate blends for thermal runaway protection in battery enclosures. Chubu and Kanto regions host concentrated compounding assets serving both domestic electronics and automotive export markets.
India
PLI scheme production-linked incentives for advanced materials manufacturing attract alloy compounders to establish domestic compounding near Chennai and Pune assembly clusters. BIS standards for automotive materials are converging with international benchmarks, accelerating qualification timelines for imported formulations. Maharashtra and Tamil Nadu industrial corridors concentrate new capacity investments from multinational compounders seeking localized supply.
Polymer Alloys Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue bio-based compatibilizer integration and medical device certification. The vendor base stratifies across three tiers: integrated petrochemical majors with captive resin supply, specialty compounders with reactive extrusion expertise, and regional processors serving construction-grade PVC composites. Consolidation pressure from automotive OEM supplier list reductions favors scale and qualification depth over geographic coverage. Dominant competitive moves include backward integration into bio-based feedstocks and strategic partnerships with biotechnology firms for compatibilizer development.
Within the integrated petrochemical tier, SABIC and BASF SE exemplify archetypes of geographic footprint leverage and R&D-anchored co-development respectively. SABIC utilizes Middle Eastern and Asian production hubs to serve consolidated automotive buyers with tailored polycarbonate blends. BASF SE occupies a position defined by European-centric integrated R&D centers. Among Japanese specialists, Asahi Kasei Corporation represents the certification-advantaged archetype for METI JIS-compliant electronic enclosure materials.
| Leading Market Players |
|---|
| SABIC |
| JSR Corporation |
| BASF SE |
| Daicel Polymer Ltd. |
| Asahi Kasei Corporation |
| Covestro AG |
| Mitsubishi Engineering-Plastics Corporation |
| The Dow Chemical Company |
| LyondellBasell Industries N.V. |
| Others |
Cost & Logistics Intelligence
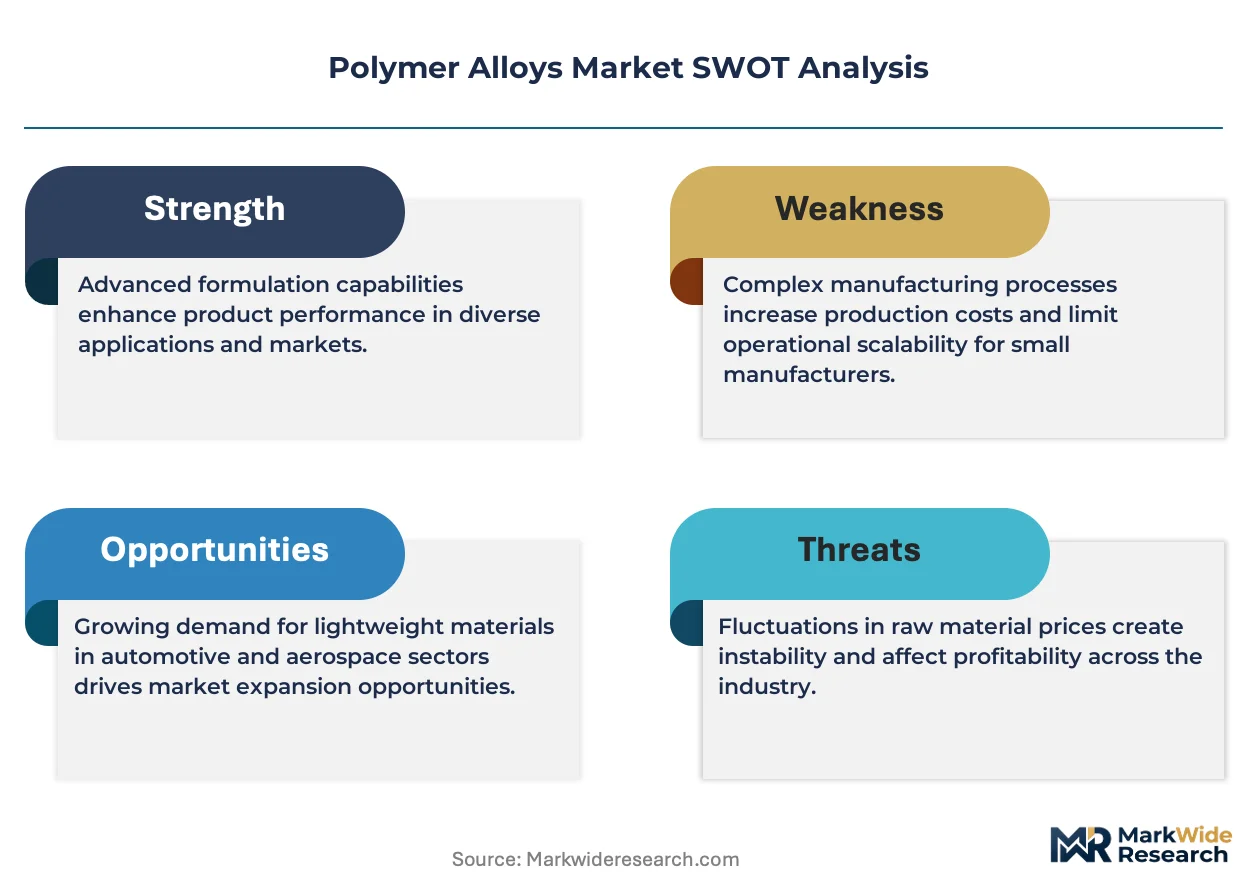
REACH Phase-Down mandates on halogenated flame retardants gate qualified supply and premium-tier pricing access, as compounders investing in phosphorus-nitrogen R&D capture specification-locked automotive and electronics contracts while legacy formulation suppliers face margin compression.
Pricing Analysis
High-volume ABS alloys for white goods trade at compressed margins, while certified polycarbonate blends for EV battery housings command substantial premiums. Price differentiation hinges on multi-jurisdictional certification depth and recycled-content verification grade. Pricing pressure stems from crude-derived benzene and propylene volatility. Appliance manufacturers in Mexico exhibit highest price sensitivity; German automotive OEMs show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand, bypassing traditional distributor layers for lot-level traceability. Supply concentrates in Germany, Japan, and the United States for qualified automotive-grade production. Feedstock draws from Middle Eastern benzene and Asian propylene sources. Single-source vulnerability in specialty compatibilizers threatens continuity. Distribution runs through tier-one integrated compounders near vehicle assembly clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story: ECHA REACH restrictions on hazardous additives create a barrier-to-entry moat that rewards pre-certified compounders with specification lock-in.
For Market Incumbents: Acquire reactive extrusion engineering talent pools to defend against process scarcity. Expand halogen-free formulation capacity ahead of regulatory deadlines. Cement specification lock-in through co-development partnerships with Stuttgart and Toyota City automakers. For New Entrants and Emerging Players: Begin with medical device enclosure applications where ISO 10993 certification opens metal-replacement opportunities. Target India's PLI scheme corridors near Chennai and Pune for localized compounding. Pursue biocompatibility certification as the primary go-to-market angle. For Investors and Strategic Acquirers: First blockchain-anchored material passport deployment by a tier-one compounder is the leading indicator that traceability infrastructure investments are yielding procurement preference. Five-to-ten-year viability favors specialty compounders with integrated R&D and captive resin supply. Monitor extended producer responsibility framework adoption velocity as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Compatibilizers | Lignin-derived grafting agents reduce petrochemical dependency for German interior panel suppliers. |
| Halogen-Free Formulation Certification | Phosphorus-nitrogen systems unlock procurement gates with Bavarian white goods manufacturers. |
| Reactive Extrusion Capacity Expansion | Compatibilizer expertise scarcity makes process engineering talent the binding constraint. |
| Material Passport Blockchain Deployment | Lot-level recycled content verification satisfies EU Battery Regulation traceability mandates. |
| Joint Venture with Biotechnology Firms | Tannin feedstock partnerships accelerate odor-compliant interior panel qualification timelines. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with polymer compounding plant managers, automotive OEM procurement leads, technical R&D directors, and distribution channel partners. Bottom-up volume modeling triangulated against top-down industry association benchmarks.
Segment-level granularity captured product type, end-use industry, application method, and performance feature dimensions across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points. Forecast inputs incorporated REACH compliance timelines, EV production ramp rates, and bioplastics feedstock cost curves.
Underlying measurement precision varies by segment; certified automotive-grade alloys carry tighter precision than construction-grade PVC composites. Forecasts reflect assumptions on regulatory enforcement consistency and feedstock price normalization. Practitioners should monitor ECHA substance restriction announcements and OEM supplier list consolidation velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
PEG 3500 Market
Polymers & Resins
Bio-Based PVC Market
Polymers & Resins
Asia-Pacific Polymer Emulsion Market
Polymers & Resins
Global Polycarbonate Market
Polymers & Resins
Lactic Acid and Polylactic Acid Market
Polymers & Resins
Polyvinyl Butyral (PVB) Market
Polymers & Resins
Welan Gum Market
Polymers & Resins
Virgin Resin Market
Polymers & Resins
PA66 Market
Polymers & Resins
Global Hydroxypropyl Cellulose Market
Polymers & Resins
South America Fluoropolymer Market
Polymers & Resins
Europe Polyolefin Market
Polymers & Resins
Poly(P-Phenylene Ether) (PPE) Market
Polymers & Resins
Expanded Polypropylene (EPP) Foam Market
Polymers & Resins
Modified Alkyd Resin Market
Polymers & Resins
Silicone Resins Market