
 Neoprene Market | 2026-2036
Neoprene Market Size, Share, and Industry Trends Forecast 2026-2036
Neoprene Market Analysis
Multi-source procurement among compounders is hardening as chloroprene supply reliability becomes a strategic priority. Denka Company Limited leverages captive acetylene feedstock to sustain vertical integration across chloroprene monomer and polymer production. ARLANXEO anchors European supply through its Leverkusen manufacturing complex, while Lanxess competes on technical rubber grades for high-performance automotive specifications. Covestro differentiates through tailored liquid rubber formulations serving industrial coating applications.
Neoprene denotes a family of polychloroprene synthetic rubbers produced via emulsion polymerization of chloroprene monomer, yielding materials with operational temperature ranges from minus 40 degrees Celsius to 120 degrees Celsius and inherent resistance to oils, ozone, and weathering degradation. Sheet and foam grades occupy the largest volume positions, with sheet dominating industrial gasket and sealing applications while foam captures margin pools in sporting goods and protective equipment where cushioning performance commands premium positioning. Liquid rubber represents the fastest-growing form factor as manufacturers adopt spray-applied and castable systems for complex geometries in medical device and aerospace component fabrication.
EPA oversight of chlorinated solvent emissions shapes polymerization plant siting and abatement investment in the United States, while REACH registration requirements in Europe constrain non-European suppliers seeking direct market access. China's SAMR enforces GB standards on rubber product quality that influence export-oriented compounder certification strategies. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with diverging chemical safety and performance certification pathways.
Market Dynamics
Chloroprene monomer supply concentration in Japan and Germany is forcing compounders to build redundant sourcing architectures as geopolitical friction disrupts just-in-time raw material flows.
Growth Catalysts
- Automotive electrification:Battery pack sealing and thermal management systems in electric vehicles require neoprene's flame resistance and dielectric stability. OEMs specify polychloroprene for coolant hose assemblies.
- REACH substance restrictions:The EU's phased limitations on short-chain chlorinated paraffins redirect formulation investment toward compliant polymerization catalysts and post-processing purification.
- Construction sector expansion:China's infrastructure stimulus programs elevate consumption of neoprene bearing pads and bridge expansion joint seals in high-speed rail and highway projects.
Market Restraints
- Acetylene feedstock volatility:Chloroprene production depends on carbide-based acetylene or petroleum-derived naphtha cracking, exposing margins to natural gas and calcium carbide price swings.
- Supplier geographic concentration:Over half of global chloroprene monomer capacity sits in Japan and Germany, creating single-point-of-failure risk for compounders without dual-source contracts.
- Styrene-butadiene substitution:Cost-sensitive automotive hose manufacturers substitute SBR compounds where oil resistance requirements permit, compressing neoprene volume in economy-tier specifications.
Strategic Opportunities
- India industrialization:The PLI scheme for automotive components and BIS certification harmonization create entry pathways for specialty elastomer compounders serving domestic OEMs and defense contractors.
- Liquid rubber spray systems:Castable and spray-applied neoprene formulations enable complex geometry coating in aerospace ducting and medical device fabrication without compression molding tooling.
- EU Green Deal procurement mandates:Public infrastructure tenders increasingly require Environmental Product Declarations, favoring suppliers with lifecycle-assessed polymer grades and renewable energy manufacturing footprints.
Industry Challenges
- Polymerization process engineering expertise:Emulsion polymerization of chloroprene demands precise temperature and surfactant control that few compounders maintain in-house, constraining quality consistency.
- REACH registration timelines:New polymer grades require 18-24 month substance dossier preparation and member state evaluation, delaying product launches for non-European suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neoprene Market |
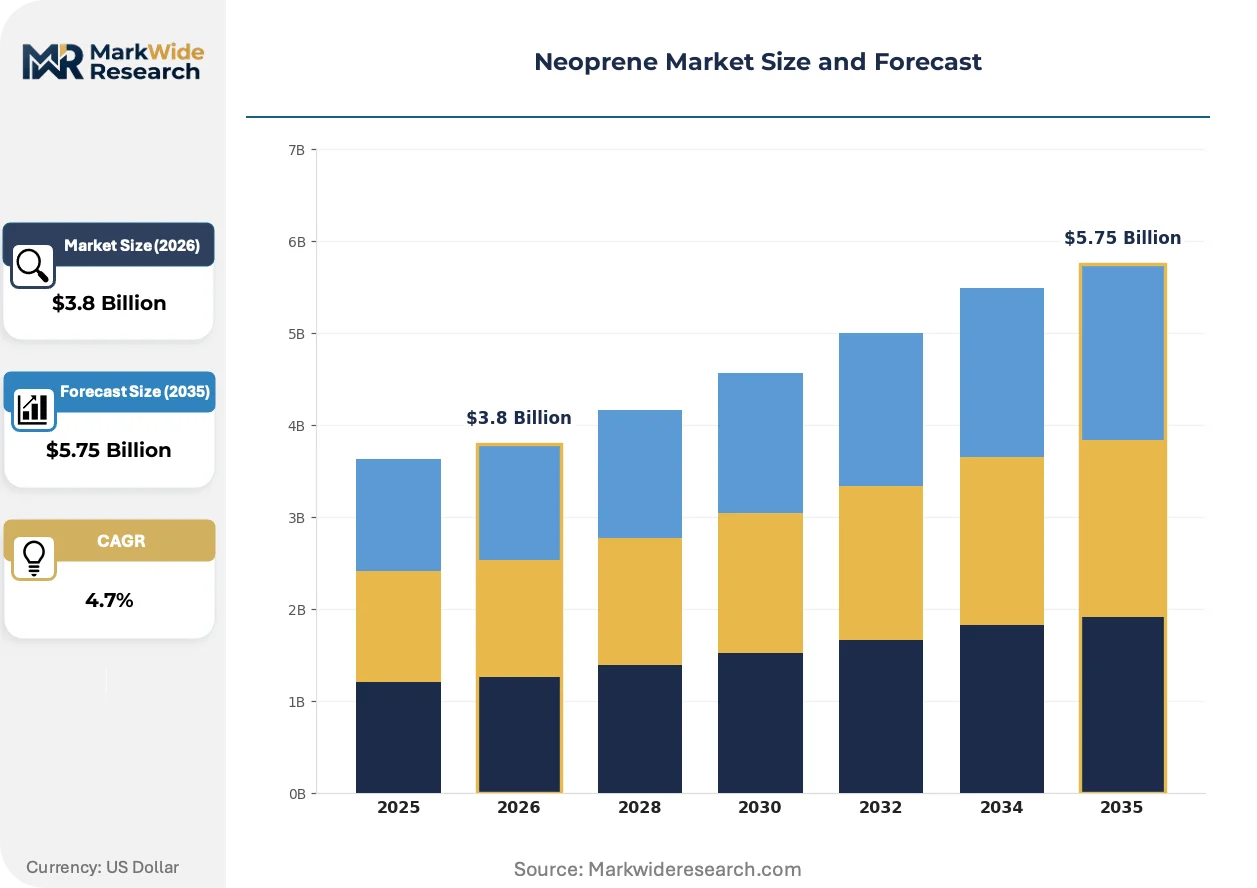
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet, Foam, Coated Fabric, Liquid Rubber Application: Automotive, Sporting Goods, Medical Devices, Aerospace End User: Manufacturers, Retailers, Distributors, Contractors Form: Solid, Liquid, Gasket, Adhesive |
| Companies Covered | Denka Company Limited, ARLANXEO, Tosoh Corporation, Lanxess, Covestro, 3M, Sundow Polymers, China National Bluestar, Showa Denko, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neoprene Market Emerging Trajectories
Formulation science is diverging along performance-versus-sustainability axes as regulatory pressure and end-use technical requirements pull compounders toward specialized development tracks.
Water-based neoprene adhesives is modularizing industrial bonding applications by eliminating solvent recovery infrastructure. Furniture and footwear manufacturers adopt these systems to comply with EPA Maximum Achievable Control Technology standards for hazardous air pollutants. The shift compresses capital requirements for small and mid-scale compounders entering coating markets.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in rubber articles force reformulation of carbon black-reinforced neoprene grades. Compounders substitute low-PAH furnace blacks or precipitated silica to maintain tensile properties while achieving consumer product safety certification. German automotive suppliers lead this transition due to KBA type-approval requirements for under-hood components.
Direct compounder-to-OEM technical service relationships are displacing distributor-led specification selling in automotive and aerospace segments. Buyers demand application engineering support for finite element analysis of seal designs and accelerated aging validation. This pattern concentrates in Germany and Japan where tier-one suppliers maintain in-house materials laboratories.
Neoprene Market Segmentation
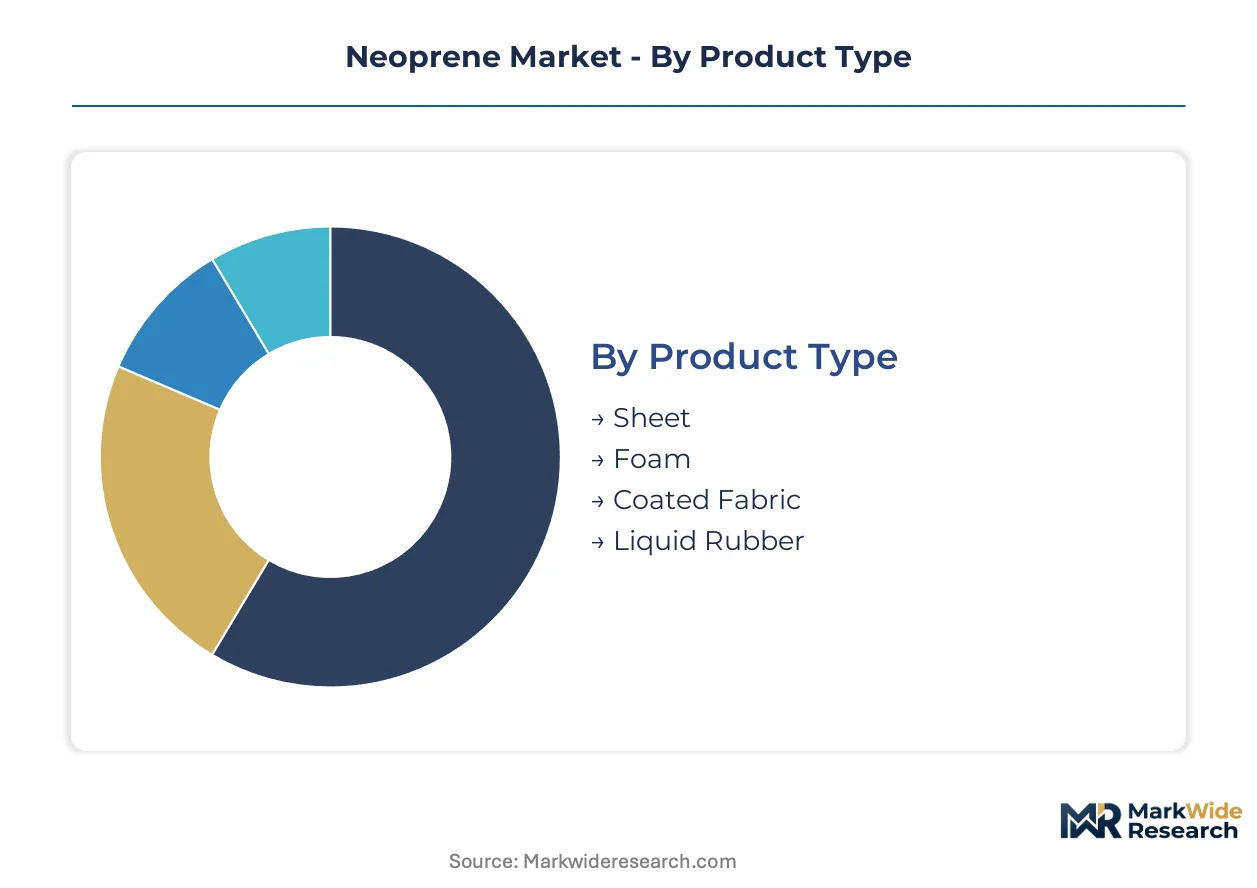
Neoprene segmentation reveals divergent capital requirements across form factors and end-use specifications. Compounders allocate equipment investment toward high-volume sheet production while reserving flexible batch systems for specialty liquid rubber grades.
Product Type:
Sheet production demands the heaviest fixed capital outlay for calendering lines and vulcanization ovens, while liquid rubber requires lower equipment intensity but higher formulation R&D spend.
- Sheet:Continuous calendered rolls serve industrial gasket and automotive under-hood sealing with thickness tolerances down to 0.1 millimeters. Demand concentrates in China's high-speed rail expansion where bridge bearing pads require compression set resistance under dynamic loads.
- Foam:Cellular structures manufactured via gas-blowing agents capture premium positioning in protective equipment and wetsuit applications where cushioning density and thermal insulation drive specification. Sporting goods manufacturers in Japan specify closed-cell grades for diving and surfing equipment.
- Coated Fabric:Laminated textile substrates serve inflatable structures and protective apparel with tear strength requirements.
- Liquid Rubber:Low-viscosity prepolymers enable spray-applied and castable systems without compression molding tooling investment.
Sheet absorbs the bulk of installed capacity; liquid rubber is expanding most quickly.
Application:
Cost tier stratification separates specification-grade automotive and aerospace demand from price-sensitive sporting goods volume.
- Automotive:Battery pack sealing and thermal management systems in electric vehicles require flame resistance and dielectric stability validated to OEM specifications. German tier-one suppliers specify polychloroprene for coolant hose assemblies under KBA type-approval protocols.
- Aerospace:Castable formulations coat complex ducting geometries where compression molding is impractical, with FAA certification requirements governing smoke and toxicity emissions.
- Sporting Goods:Foam grades dominate wetsuit and protective equipment manufacturing with margin pools tied to brand positioning rather than technical specification.
- Medical Devices:Biocompatible liquid rubber grades serve catheter and seal applications requiring US FDA and EU MDR compliance.
Automotive commands the highest per-kilogram pricing; aerospace is gaining share fastest.
End User:
Customer type determines technical service intensity and contract structure, with manufacturers requiring embedded application engineering.
- Manufacturers:Direct compounder relationships demand finite element analysis support and accelerated aging validation, particularly among German and Japanese tier-one suppliers with in-house materials laboratories.
- Distributors:Stock-and-sell intermediaries serve fragmented construction and maintenance markets with lower service requirements.
- Retailers:Consumer-facing channels for sporting goods and DIY applications concentrate in North American and European markets.
- Contractors:Project-based procurement for infrastructure sealing applications follows public tender specifications with Environmental Product Declaration requirements under EU Green Deal mandates.
Manufacturers absorb the bulk of technical service resources; contractors are expanding most quickly.
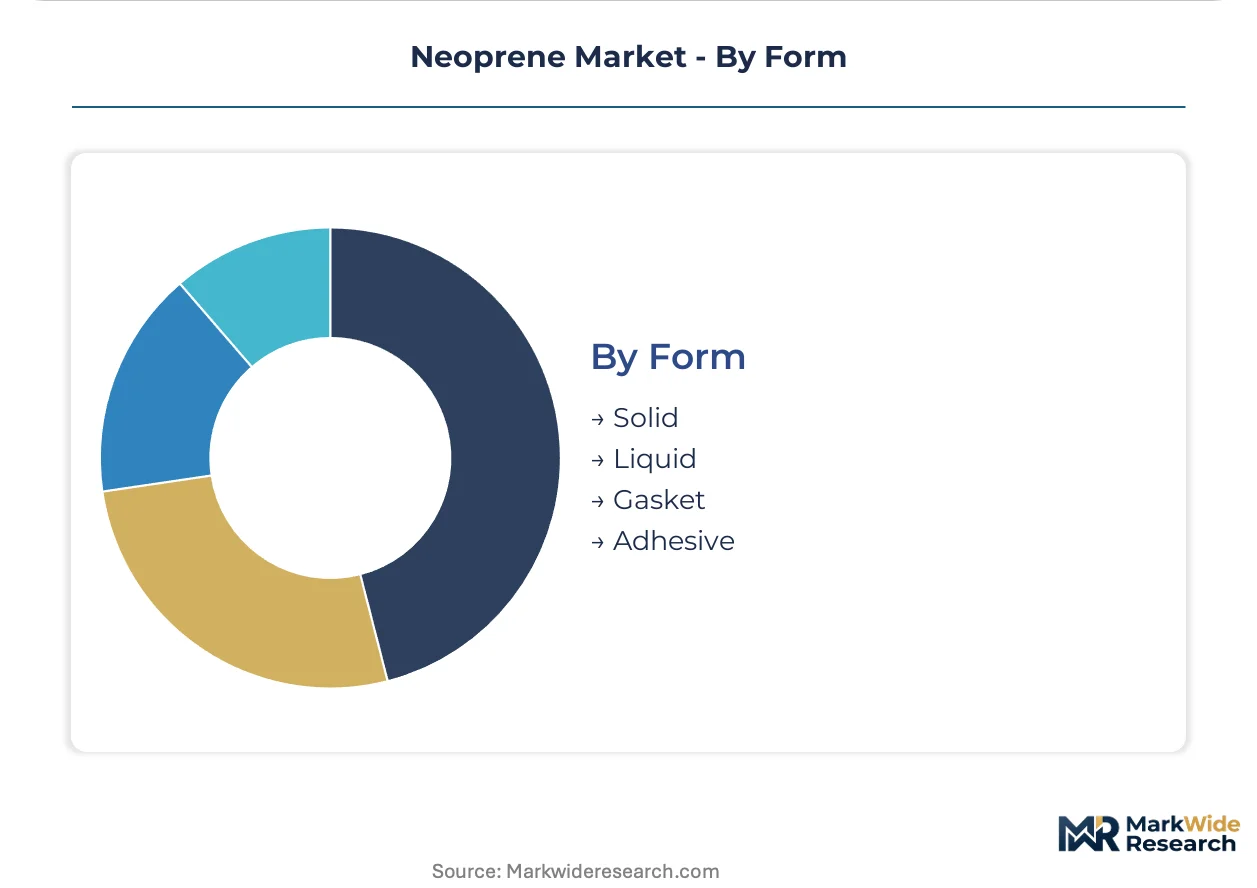
Form:
Supply concentration differs by physical state, with solid grades consolidating around large-scale polymerization assets and liquid forms enabling distributed compounding.
- Solid:Baled and pelletized grades feed extrusion and molding operations with established supply chains through industrial distributors.
- Liquid:Low-viscosity prepolymers suit spray and cast applications in aerospace ducting and medical device fabrication where tooling costs prohibit compression molding.
- Gasket:Die-cut and water-jet processed components serve flange sealing with tight thickness tolerances for chemical processing equipment.
- Adhesive:Water-based and solvent-borne formulations bond footwear, furniture, and industrial assemblies with EPA Maximum Achievable Control Technology compliance driving solvent system phase-out.
Solid forms absorb the bulk of polymerization capacity; liquid forms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates demand for neoprene as automotive and construction sectors expand specialty elastomer consumption, while supply reliability concerns push compounders toward redundant sourcing architectures across multiple geographies.
China
High-speed rail infrastructure and electric vehicle battery sealing drive volume consumption under GB standards enforced by SAMR. The country's dual carbon goals accelerate scrutiny of chloroprene polymerization emissions. Yangtze River Delta compounders serve domestic OEMs with die-cut gasket specifications for bridge bearing pads.
Germany
Automotive tier-one suppliers specify polychloroprene for coolant hose assemblies requiring KBA type-approval. REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons force carbon black reformulation in rubber articles. Leverkusen manufacturing complexes anchor European chloroprene monomer supply for export-oriented compounders.
United States
EPA Maximum Achievable Control Technology standards phase out solvent-borne adhesive systems in favor of water-based neoprene formulations. Battery pack thermal management in electric vehicles requires flame-resistant sealing validated to OEM specifications. Gulf Coast petrochemical corridors face siting constraints from chlorinated solvent emission oversight.
Japan
Captive acetylene feedstock integration sustains chloroprene monomer production for domestic polymerization. METI industrial standards govern sporting goods foam grades for diving and surfing equipment. Osaka-based compounders supply closed-cell neoprene to premium wetsuit manufacturers with tight density tolerances.
India
PLI scheme incentives for automotive components create entry pathways for specialty elastomer compounders. BIS certification harmonization accelerates domestic OEM qualification timelines. Maharashtra and Gujarat industrial corridors attract compounder investment to serve defense contractors and infrastructure projects.
Neoprene Market Vendor Landscape
Backward integration into acetylene feedstock dominates the current landscape as compounders seek supply security against geopolitical friction. The market structure consolidates around integrated chloroprene producers and specialized compounders with formulation expertise. Three archetypes prevail: captive monomer producers, technical grade specialists, and application-focused compounders. M&A activity and capacity expansion represent the primary competitive vectors as firms defend margin positions against feedstock volatility.
Among integrated Japanese producers, Denka Company Limited exemplifies the captive feedstock archetype through in-house acetylene production. ARLANXEO anchors European supply positioning from German manufacturing assets. Lanxess occupies the technical rubber grade tier serving automotive specifications with precise performance validation. Covestro represents the formulation innovation vector through tailored liquid rubber systems for industrial coating applications.
| Leading Market Players |
|---|
| Denka Company Limited |
| ARLANXEO |
| Tosoh Corporation |
| Lanxess |
| Covestro |
| 3M |
| Sundow Polymers |
| China National Bluestar |
| Showa Denko |
| Others |
Supply Flow & Price Mechanics
Acetylene feedstock benchmarks from calcium carbide and naphtha cracking operations cascade through chloroprene monomer production into three distinct pricing tiers for sheet, foam, and liquid rubber grades. Compounders without backward integration into acetylene supply face margin compression when energy costs spike, while integrated producers in Japan and Germany capture pricing power through captive feedstock control.
Pricing Analysis
Volume-absorbing sheet grades trade at compressed margins against specification-validated automotive and aerospace liquid rubber tiers that command 40-60% premiums. Price differentiation rests on REACH registration status and KBA type-approval certification for under-hood components, with unregistered Asian imports facing exclusion from EU tenders. Pricing pressure stems from styrene-butadiene substitution in economy-tier hose specifications. Tier-one automotive OEMs exhibit lowest price sensitivity due to performance validation requirements, while construction contractors in developing markets drive hard volume negotiations.
Supply Chain Analysis
India's PLI scheme domestic-content mandates for automotive components are redirecting compounder investment toward Maharashtra and Gujarat industrial corridors, reshaping traditional East Asian sourcing patterns. Chloroprene monomer production concentrates in Japan and Germany, with acetylene feedstock drawing from carbide-based and petroleum-derived routes. Single-source vulnerability runs through Denka's captive acetylene integration and ARLANXEO's Leverkusen complex. Distribution runs through technical service-direct relationships with German and Japanese tier-one suppliers, bypassing traditional distributor channels for specification-grade material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neoprene market participation demands sustained compliance investment as REACH Annex XVII substance restrictions and GB standards enforcement erect capital-intensive barriers that favor incumbent compounders with established registration dossiers and in-house polymerization expertise.
For Market Incumbents: Hedge acetylene feedstock exposure through dual-source contracts with Japanese and German monomer producers while expanding liquid rubber formulation capacity in aerospace and medical device segments. Denka's captive integration model offers template for supply security against geopolitical friction. Reinforce technical service teams for finite element analysis support to defend automotive OEM relationships against SBR substitution. For New Entrants and Emerging Players: Enter via India's PLI scheme corridors for automotive components and BIS certification pathways, where domestic-content rules disadvantage unregistered imports. White-space concentrates in spray-applied liquid rubber systems for medical device contract manufacturers seeking FDA-compliant castable alternatives to compression molding. Pursue direct technical partnerships with tier-two aerospace fabricators lacking in-house materials laboratories. For Investors and Strategic Acquirers: The window for entry favors compounders with existing REACH registration portfolios and demonstrated emulsion polymerization process control. Long-term viability hinges on regulatory compliance moats widening as EU Green Deal procurement mandates and SAMR emission scrutiny intensify. Watch for chloroprene monomer capacity announcements in India as inflection signal for supply diversification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetylene Feedstock | Captive supply from calcium carbide operations insulates margins against natural gas volatility in Japanese and German production clusters. |
| REACH Registration Investment | Eighteen-month dossier preparation secures EU market access against non-registered Asian competitors seeking direct compounder relationships. |
| Liquid Rubber Capacity Expansion | Spray-applied systems capture aerospace ducting and medical device fabrication where compression molding tooling costs prohibit incumbent supply. |
| India Manufacturing Footprint | Maharashtra and Gujarat facilities qualify for PLI scheme incentives while satisfying BIS certification requirements for domestic OEM supply. |
| Water-Based Adhesive Formulation Transition | EPA Maximum Achievable Control Technology compliance eliminates solvent recovery infrastructure for furniture and footwear manufacturer customers. |
Methodological Framework
Trade publications, customs databases, and SEC 10-K filings formed the secondary backbone, supplemented by primary interviews with chloroprene plant managers, automotive tier-one procurement leads, technical R&D directors at compounders, and distribution channel partners across Germany, Japan, China, and India. Bottom-up volume modeling from polymerization capacity and end-use consumption patterns was cross-validated against top-down market sizing from elastomer trade association reports.
Bottom-up segment analysis triangulated against top-down macroeconomic drivers across the analysis window. Segmentation dimensions included product form factor, application industry, end-user type, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating electric vehicle battery sealing content per vehicle and high-speed rail infrastructure expansion rates. Forecast inputs included acetylene feedstock cost curves and REACH registration timeline assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained acetylene price volatility or accelerated SBR substitution in automotive hose specifications. Forecasts reflect documented assumptions regarding polymerization capacity expansion timelines and regulatory enforcement intensity across jurisdictions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Emulsion PVC Market
Polymers & Resins
Synthetic Latex Polymers Market
Polymers & Resins
Global Barrier Resins Market
Polymers & Resins
Cross-Linked Polyethylene (XLPE) Market
Polymers & Resins
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market
Polymers & Resins
Wood Coating Resins Market
Polymers & Resins
Indonesia Flooring Resins Market
Polymers & Resins
South America Polymer Emulsion Market
Polymers & Resins
Polybutylene Succinate (PBS) Market
Polymers & Resins
Middle-East and Africa Thermoplastics Market
Polymers & Resins
Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Vinyl Acetate Monomer (VAM) Market
Polymers & Resins
Glycolide Polymers Market
Polymers & Resins
Polyacrylamide Market
Polymers & Resins
North America Polycarbonate (PC) Market
Polymers & Resins
Propylene Terpolymer Market