
 Asia-Pacific Urea-Formaldehyde Glues and Resins Market | 2026-2036
Asia-Pacific Urea-Formaldehyde Glues and Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Urea-Formaldehyde Glues and Resins Market Outlook
Asset-light leasing arrangements for formaldehyde reaction vessels are reshaping capital barriers for mid-tier resin producers. Hexion leverages its technology leadership in low-emitting formulations to anchor premium positioning across East Asian markets. Kanoria Chemicals & Industries Ltd sustains manufacturing scale through backward integration into methanol supply chains. Mitsubishi Gas Chemical Company, Inc. differentiates via specialized catalyst systems that reduce free formaldehyde residuals in finished resins.
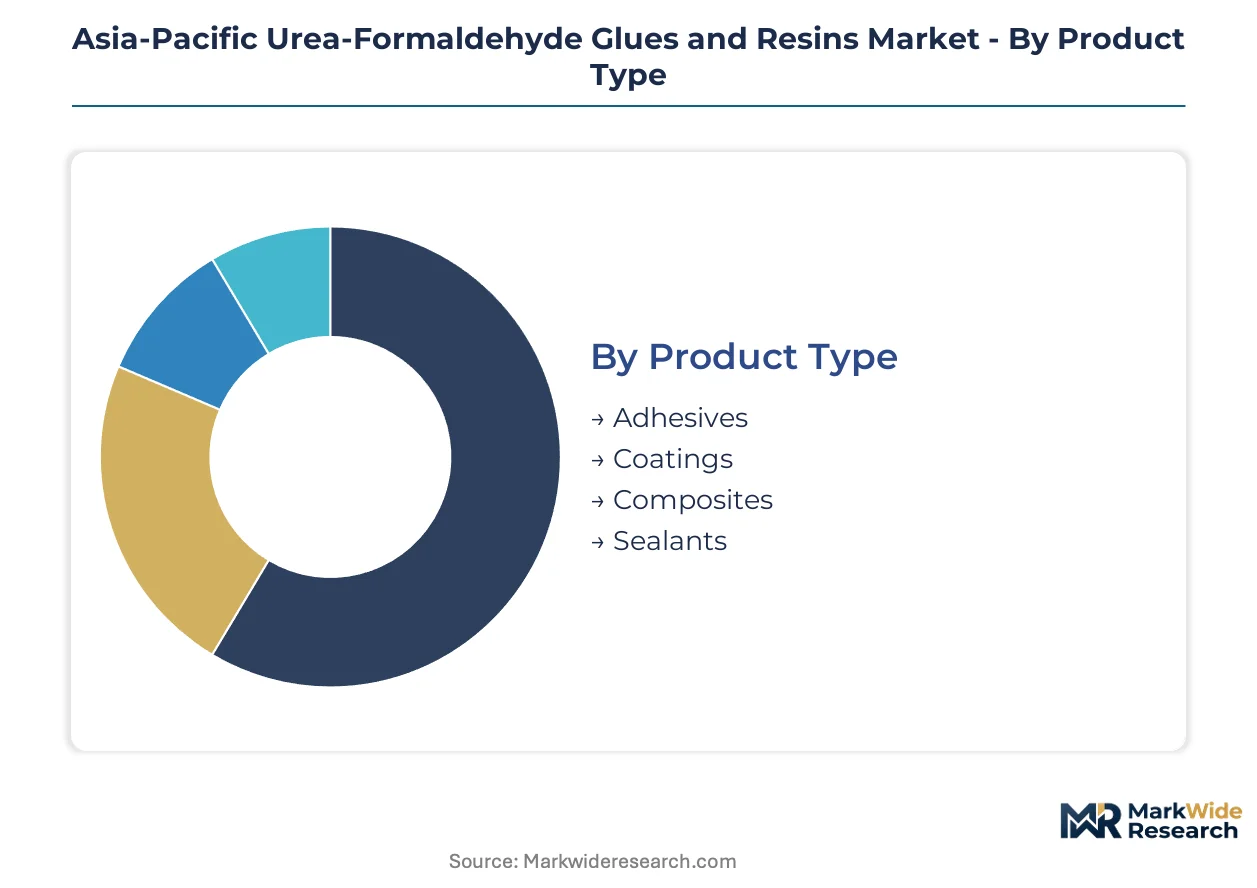
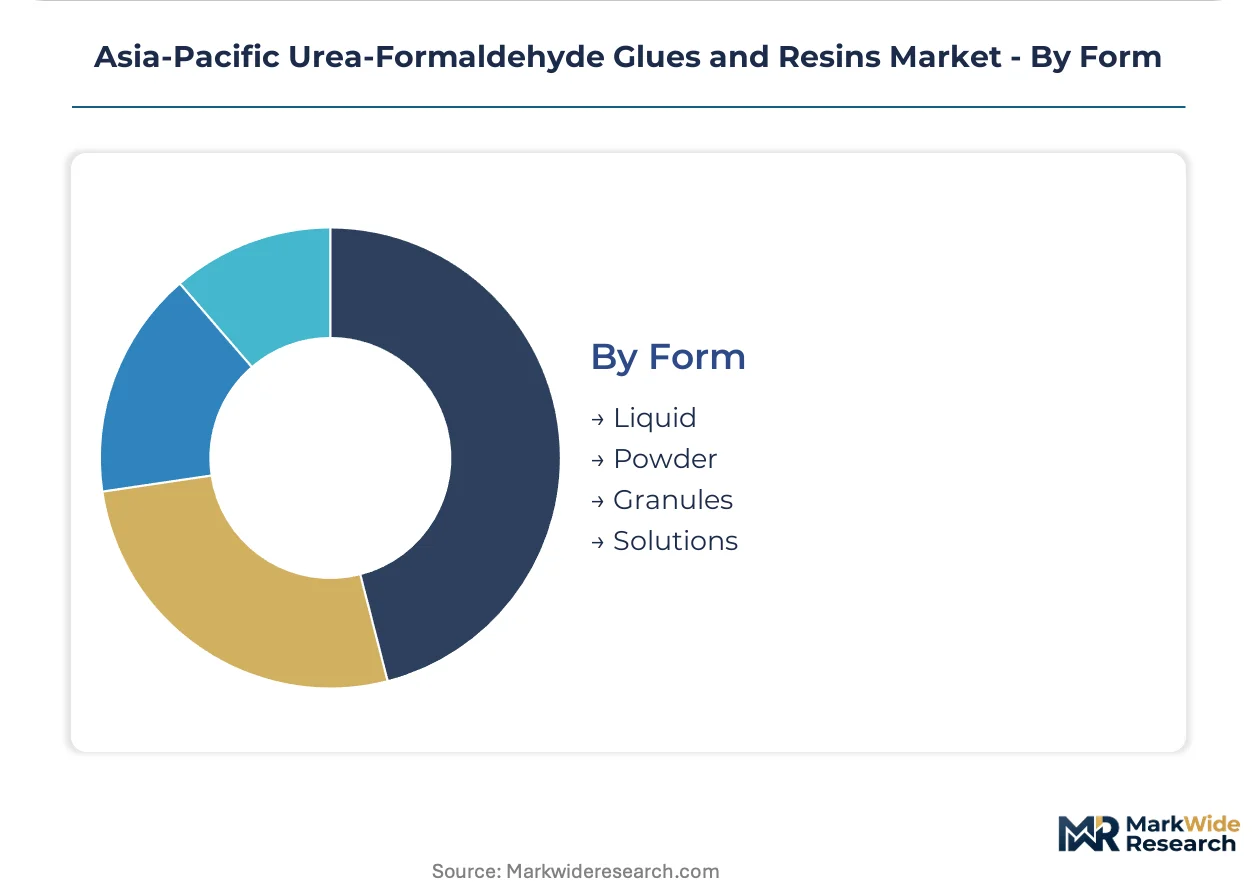
Urea-formaldehyde glues and resins constitute thermosetting amino polymers synthesized from urea and formaldehyde condensation, typically exhibiting molar ratios between 1.0 and 2.0 depending on intended cure speed and water resistance requirements. These binders primarily serve as cost-effective adhesives for wood-based panels where high bond strength under dry conditions remains essential. Among product type segments, adhesives occupy the dominant volume position due to sustained particleboard and medium-density fiberboard output across the region, while coatings applications are expanding fastest as furniture exporters adopt pre-finished panel strategies to reduce on-site labor. The liquid form segment leads value capture because bulk tanker logistics and automated metering systems align with continuous production lines at major panel mills.
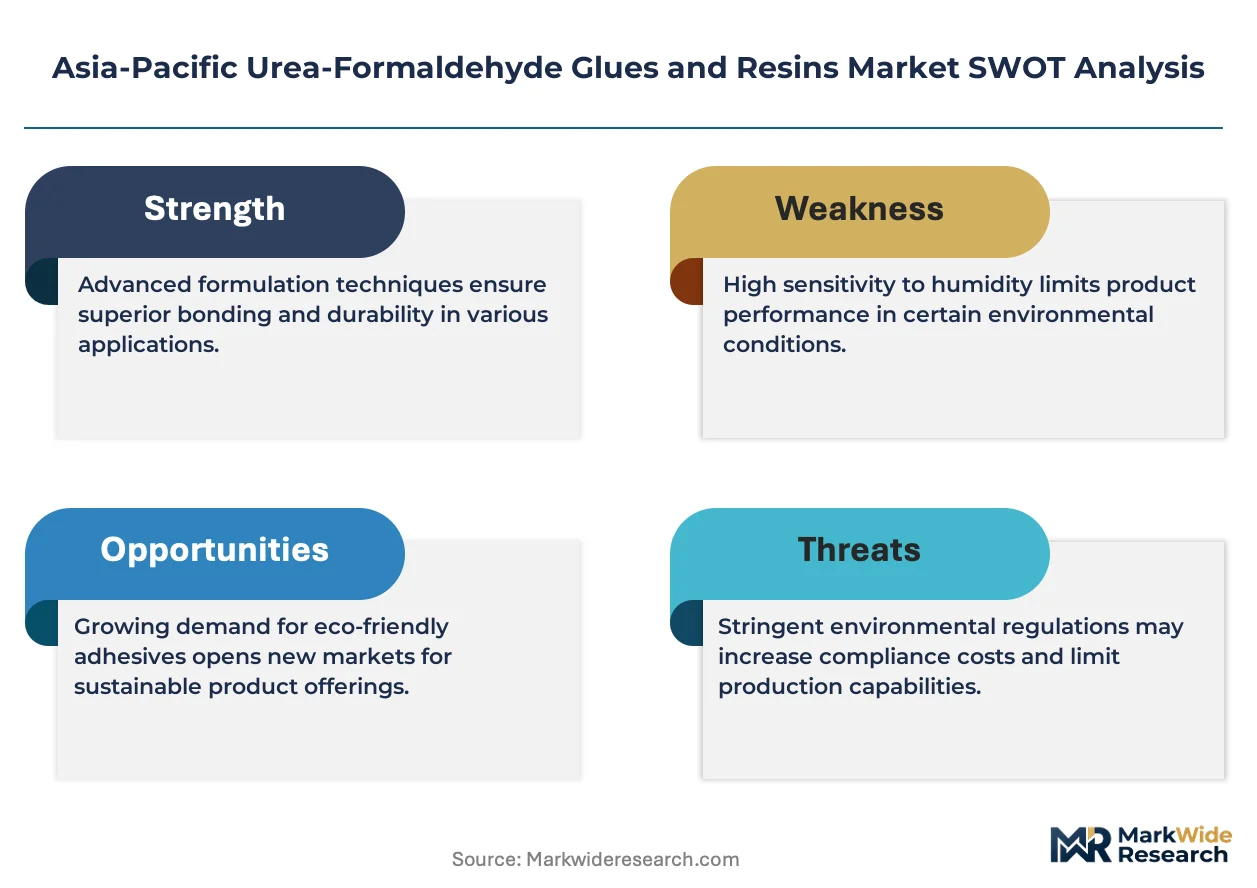
China's SAMR enforces GB 18580 standards that cap formaldehyde release from interior wood products, directly limiting conventional UF resin formulations in residential construction applications. Japan's METI maintains JIS standards for structural plywood adhesives that mandate accelerated weathering performance, creating specification tiers that filter market access. India's BIS certification requirements for plywood bonding quality are extending coverage to imported resin systems, reshaping procurement patterns for domestic laminators. Stakeholders must monitor regulatory divergence between emission-focused standards in Northeast Asia and performance-based specifications in South Asia when configuring regional product portfolios.
Market Dynamics
Formaldehyde emission caps across Northeast Asian building codes are compressing conventional resin formulations while accelerating low-emitting substitute development. China's GB 18580 standard revisions and Japan's JIS structural plywood specifications are forcing reformulation investments that reshape competitive economics for regional producers.
Growth Catalysts
- India's BIS certification expansion:Mandatory quality standards for imported resin systems are redirecting procurement toward domestic laminators in Gujarat and Maharashtra, stimulating local capacity additions.
- Pre-finished panel strategies:Furniture exporters across Vietnam and Indonesia are adopting coated particleboard to eliminate on-site finishing labor, accelerating coatings-grade resin demand.
- Western industrial corridor concentration:Plywood and medium-density fiberboard mills from Ahmedabad to Pune are clustering procurement volumes, creating scale efficiencies for adhesive suppliers.
Market Restraints
- Methanol feedstock volatility:Natural gas price swings and coal-to-chemical policy shifts in China transmit directly to urea-formaldehyde production economics, compressing margin predictability for non-integrated manufacturers.
- Formaldehyde substitution pressure:Polyurethane and soy-based adhesives are capturing share in specialty furniture and exterior-grade applications where moisture resistance requirements exceed conventional UF capabilities.
- Emission standard fragmentation:Divergent testing protocols between China's SAMR, Japan's METI, and India's BIS create compliance duplication costs for multi-market suppliers.
Strategic Opportunities
- Philippines construction acceleration:Government infrastructure programs and residential building codes that currently lack stringent formaldehyde limits present near-term volume expansion potential before anticipated regulatory tightening.
- Catalyst system specialization:Advanced acid-cure formulations that reduce free formaldehyde residuals below 0.1 percent enable premium positioning in Japanese and South Korean export-oriented panel production.
- Asset-light vessel leasing:Formaldehyde reactor leasing arrangements lower capital barriers for mid-tier Indian and Indonesian producers seeking capacity expansion without full ownership exposure.
Industry Challenges
- Reformulation technical talent scarcity:Polymer chemists capable of balancing cure speed, water resistance, and emission reduction are concentrated among established Japanese and Chinese producers, constraining new entrant R&D velocity.
- Legacy equipment retrofit costs:Continuous press lines at older Southeast Asian panel mills require synchronized adhesive metering system upgrades to handle modified resin viscosities, extending payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Urea-Formaldehyde Glues and Resins Market |
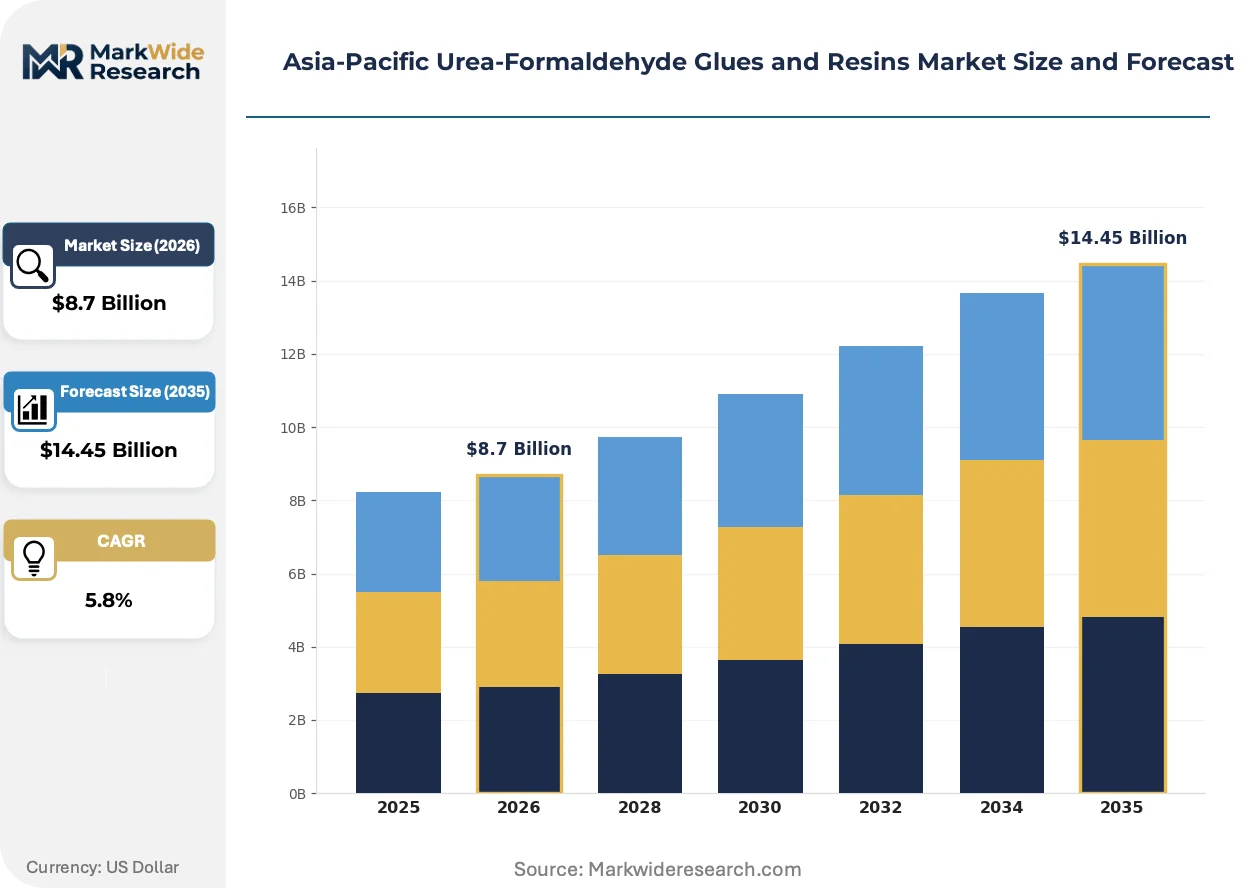
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesives, Coatings, Composites, Sealants Application: Furniture, Construction, Automotive, Electronics End User: Manufacturers, Contractors, Distributors, Consumers Form: Liquid, Powder, Granules, Solutions |
| Companies Covered | BASF SE, Hexion, Kanoria Chemicals & Industries Ltd, ARCL Organics Ltd, Huaqiang Chemical Group, Mitsubishi Gas Chemical Company, Inc., Perstorp, Achema, JNC Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Urea-Formaldehyde Glues and Resins Market Strategic Shifts
Digital process control and low-emission chemistry are converging to transform how urea-formaldehyde resins are formulated, monitored, and certified across Asia-Pacific manufacturing networks. These shifts are compressing development cycles while raising technical barriers to market participation.
Real-time spectroscopic monitoring of resin condensation reactions is virtualizing quality control protocols that previously relied on offline laboratory testing. Major Chinese and Japanese panel producers are installing inline near-infrared systems to adjust molar ratios dynamically during production. This virtualization of quality assurance is reducing batch rejection rates while enabling just-in-time resin customization for varying substrate requirements.
Japan's METI has accelerated JIS A 5908 structural plywood standard revisions to incorporate accelerated weathering performance tiers that exceed conventional urea-formaldehyde capabilities. Manufacturers serving earthquake-resistant construction segments must now qualify alternative amino resin formulations or hybrid systems. South Korean exporters to Japanese construction markets are investing in modified melamine-urea copolymers to maintain specification compliance.
Long-term supply agreements with fixed-price methanol clauses are displacing spot-market purchasing among large Indian and Thai panel mills. Procurement teams at western India laminators are negotiating eighteen to twenty-four month formaldehyde supply contracts indexed to regional natural gas benchmarks rather than volatile methanol spot prices. This contract structure shift is most visible among Maharashtra-based medium-density fiberboard producers seeking margin stabilization against feedstock swings.
Asia-Pacific Urea-Formaldehyde Glues and Resins Market Segmentation
Segmentation reveals how urea-formaldehyde resin specifications diverge across pressure-sensitive bonding applications versus surface finishing requirements. Each dimension—product chemistry, downstream use-case, customer procurement behavior, and physical state—carries distinct margin profiles and technical compliance burdens that reshape supplier positioning across Asia-Pacific manufacturing networks.
Product Type:
Applications span structural bonding through protective surface modification, with chemistry formulations calibrated to cure speed, water resistance, and emission thresholds.
- Adhesives:Thermosetting amino polymers with urea-formaldehyde molar ratios between 1.0 and 2.0 deliver cost-effective bonding for wood-based panels where high dry-strength performance remains essential. Wood-panel manufacturers across Southeast Asia are expanding orders for low-emission adhesive systems as China's GB standards tighten formaldehyde emission caps in building materials.
- Coatings:Pre-finished panel strategies adopted by furniture exporters across Vietnam and Indonesia are accelerating coatings-grade resin demand to eliminate on-site finishing labor. This segment is expanding most quickly as laminated surface requirements proliferate in export-oriented manufacturing.
- Composites:Reinforced resin matrices serving engineered wood products and fiber-reinforced applications where dimensional stability under cyclic loading is prioritized.
- Sealants:Gap-filling formulations with extended tack time for construction assembly applications requiring moisture barrier properties alongside adhesive function.
Established volume favors adhesives; emerging adoption favors coatings.
Application:
End-use concentration determines formulation priorities, with construction-grade specifications imposing the most stringent weathering and emission compliance requirements.
- Furniture:Particleboard and medium-density fiberboard output across the region drives sustained adhesive consumption for flat-panel furniture assembly. India's western industrial corridor from Gujarat through Maharashtra is clustering procurement volumes for laminators serving domestic and export furniture markets.
- Construction:Structural plywood applications must satisfy Japan's METI JIS standards for accelerated weathering performance, creating specification tiers that filter market access for conventional formulations. Reformulation investments are reshaping competitive economics for regional producers serving earthquake-resistant building segments.
- Automotive:Interior trim bonding and acoustic panel applications where low-emission characteristics align with cabin air quality specifications.
- Electronics:Encapsulation and insulation uses in electrical components requiring flame-retardant resin modifications.
Construction commands premium pricing for certified grades; furniture drives aggregate tonnage.
End User:
Procurement scale and technical capability determine whether customers specify custom formulations or accept standard resin grades.
- Manufacturers:Major panel mills with continuous production lines utilize automated metering systems and bulk tanker logistics that favor liquid resin delivery at scale. Real-time spectroscopic monitoring of resin condensation reactions is virtualizing quality control protocols among major Chinese and Japanese producers.
- Contractors:On-site assembly operations requiring portable adhesive systems with adjustable cure speeds for varying ambient conditions.
- Distributors:Inventory-holding intermediaries serving fragmented downstream users with packaged resin products and technical support services.
- Consumers:Retail-scale purchases for small-scale woodworking and repair applications representing minimal volume but brand visibility value.
Manufacturers concentrate procurement power; distributors mediate access to fragmented demand.
Form:
Physical state selection aligns with production automation levels, storage constraints, and transportation economics across diverse manufacturing footprints.
- Liquid:Bulk tanker logistics and automated metering systems align with continuous production lines at major panel mills, capturing dominant value share through supply chain integration. Maharashtra-based medium-density fiberboard producers are negotiating long-term supply agreements with fixed-price methanol clauses to stabilize margins against feedstock volatility.
- Powder:Extended shelf stability and reduced shipping weight favor remote manufacturing locations with intermittent resin requirements or limited cold storage infrastructure.
- Granules:Controlled dissolution rates for batch processing environments where precise molar ratio adjustment is performed at point of use.
- Solutions:Pre-dispersed formulations with catalyst pre-addition for customers lacking in-house blending capabilities or technical personnel.
Liquid forms dominate value capture; powder formats serve geographic extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB standards on formaldehyde emissions are tightening product specifications across the region. India's BIS certification expansion redirects procurement toward domestic laminators. Japan's METI maintains accelerated weathering performance tiers that filter market access.
China
Wood-panel furniture manufacturers across Southeast Asia are expanding orders for low-emission adhesive systems. SAMR enforces GB 18580 standards that cap formaldehyde release from interior wood products. The Yangtze River Delta clusters major panel mills with continuous production lines utilizing automated metering systems.
India
Demand concentrates in the western industrial corridor from Gujarat through Maharashtra. BIS certification requirements for plywood bonding quality extend coverage to imported resin systems. Ahmedabad to Pune hosts clustering plywood and medium-density fiberboard mills creating scale efficiencies for adhesive suppliers.
Japan
Structural plywood applications must satisfy METI JIS standards for earthquake-resistant construction segments. JIS A 5908 revisions incorporate accelerated weathering performance tiers exceeding conventional capabilities. Kanto and Kansai regions drive reformulation investments among export-oriented panel producers.
Vietnam
Furniture exporters adopt pre-finished panel strategies to eliminate on-site finishing labor. Coatings-grade resin demand accelerates as laminated surface requirements proliferate in export manufacturing. Ho Chi Minh City industrial zones concentrate procurement for European and North American export markets.
South Korea
Exporters to Japanese construction markets invest in modified melamine-urea copolymers. MFDS-aligned emission protocols shape domestic specification compliance. Seoul Capital Area panel producers deploy real-time spectroscopic monitoring for dynamic molar ratio adjustment.
Asia-Pacific Urea-Formaldehyde Glues and Resins Market Competitive Environment
Channel-controlling players compete with product-specialist players across formulation tiers and geographic coverage. The market structure consolidates around integrated chemical conglomerates with captive methanol supply and specialized resin formulators with catalyst expertise. Strategic archetypes include backward-integrated methanol producers, technology-licensing specialists, and regional toll manufacturers. Dominant competitive moves encompass long-term supply agreements with fixed-price methanol clauses and catalyst system specialization for emission reduction.
Among Germany-based chemical conglomerates, BASF SE exemplifies scale-driven positioning through integrated petrochemical networks. Hexion and Mitsubishi Gas Chemical Company, Inc. occupy positions within the technology-specialist tier, with the former anchoring premium low-emitting formulations and the latter representing advanced catalyst system capabilities. Kanoria Chemicals & Industries Ltd sits within the regional integrated manufacturer archetype, sustaining manufacturing scale through upstream control over methanol supply chains.
| Leading Market Players |
|---|
| BASF SE |
| Hexion |
| Kanoria Chemicals & Industries Ltd |
| ARCL Organics Ltd |
| Huaqiang Chemical Group |
| Mitsubishi Gas Chemical Company, Inc. |
| Perstorp |
| Achema |
| JNC Corporation |
| Others |
Value Chain & Pricing Dynamics
China's coal-to-chemical methanol concentration anchors cost structures for urea-formaldehyde resin producers throughout Asia-Pacific, concentrating margin capture among backward-integrated manufacturers while compressing returns for non-integrated toll processors dependent on spot methanol purchases.
Pricing Analysis
Certification level creates the primary spread across product tiers, with GB 18580-compliant low-emission formulations commanding substantial premiums over conventional grades in Chinese residential construction applications. Volume scale differentiates contract pricing for Maharashtra-based medium-density fiberboard mills negotiating eighteen to twenty-four month supply agreements indexed to natural gas benchmarks. Methanol feedstock volatility transmits directly to margin compression for Indonesian and Thai producers lacking captive supply, rendering spot-market purchasers most price-sensitive while integrated chemical conglomerates maintain pricing power.
Supply Chain Analysis
Extended payment terms from formaldehyde reactor lessors are lowering capital barriers for mid-tier Indian and Indonesian producers seeking capacity expansion without full ownership exposure. Methanol supply concentrates in China, Iran, and Trinidad and Tobago, with Chinese coal-based production dominating Asia-Pacific feedstock flows. Urea sourcing draws from Middle Eastern and Chinese fertilizer export streams, exposing non-integrated resin manufacturers to commodity price volatility and currency fluctuation risks. Distribution runs through bulk tanker logistics serving continuous press lines at major panel mills, with liquid resin commanding dominant value share through supply chain integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across emission standard regimes between Northeast Asia and South Asia creates niche positioning opportunities for formulation specialists capable of bridging regulatory divergence with tailored product portfolios.
For Market Incumbents: Harden technology leadership in low-emitting catalyst systems to anchor premium positioning as Japan's METI accelerates JIS A 5908 weathering performance tiers beyond conventional urea-formaldehyde capabilities. Deepen backward integration into methanol supply chains to stabilize margin predictability against feedstock volatility threatening non-integrated competitors. Prioritize certification investments for BIS compliance in India's western industrial corridor where procurement is redirecting toward domestic laminators. For New Entrants and Emerging Players: Philippines construction acceleration presents white-space expansion potential before anticipated formaldehyde emission limits replicate Northeast Asian standards, with government infrastructure programs driving near-term volume growth. Vietnam's pre-finished panel export manufacturing offers penetrable coatings-grade resin demand as furniture exporters eliminate on-site finishing labor. Pursue asset-light vessel leasing arrangements to enter Indonesian and Indian markets without capital-intensive reactor ownership. For Investors and Strategic Acquirers: Capital is best deployed toward catalyst-system specialists with demonstrated free formaldehyde reduction below 0.1 percent, positioning for premium capture in Japanese and South Korean export-oriented panel production. Long-term viability across the analysis window favors integrated manufacturers with captive methanol supply and regional toll processors with established BIS certification pathways. Monitor JIS standard revision implementation velocity as inflection indicator for reformulation investment cycles and alternative amino resin substitution thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol | Captive supply chains insulate margin predictability against coal-to-chemical policy shifts in China. |
| Catalyst System Specialization | Advanced acid-cure formulations enable premium positioning in METI-regulated Japanese structural plywood segments. |
| Long-term Supply Agreement | Fixed-price methanol clauses stabilize procurement economics for Maharashtra-based medium-density fiberboard producers. |
| Asset-light Vessel Leasing | Formaldehyde reactor leasing lowers capital barriers for mid-tier Indonesian resin manufacturers seeking capacity expansion. |
| BIS Certification Investment | Quality standard compliance redirects procurement toward domestic laminators in Gujarat and Maharashtra industrial corridors. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from listed chemical conglomerates, and industry association reports from ACC and Cefic. Interviews with plant managers at Chinese and Indian panel mills, procurement leads at downstream furniture manufacturers, distribution channel partners, and technical R&D directors at catalyst specialists informed demand-side and supply-side assessments. Bottom-up volume modeling triangulates against top-down market sizing derived from methanol consumption patterns and urea-formaldehyde resin trade flows.
Forecast inputs incorporate product chemistry segmentation across adhesives, coatings, composites, and sealants alongside application dimensions in furniture, construction, automotive, and electronics. End-user procurement behavior distinguishes manufacturers with automated metering systems from contractor and distributor channels. Physical state segmentation captures liquid, powder, granule, and solution format economics. CAGRs derive from regression analysis of historical methanol price elasticity, panel production capacity expansion timelines, and regulatory implementation schedules across SAMR, METI, and BIS jurisdictions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by backward-integrated Chinese producers or accelerated melamine-urea copolymer substitution in Japanese earthquake-resistant construction would shift outcomes. Macroeconomic deviation in natural gas pricing, unanticipated BIS certification scope expansion, or breakthrough soy-based adhesive performance thresholds would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Adhesives Market
Adhesives & Sealants
North America Bone Glue Market
Adhesives & Sealants
Global Engineering Adhesives Market
Adhesives & Sealants
Flexible Packaging Adhesive Market
Adhesives & Sealants
Global Construction Adhesives Market
Adhesives & Sealants
Germany Adhesives Market
Adhesives & Sealants
North America Sealants Market
Adhesives & Sealants
Asia-Pacific Contact Adhesives Market
Adhesives & Sealants
Isobornyl Acrylate Market
Adhesives & Sealants
Fabric Adhesive Market
Adhesives & Sealants
Water Based Adhesive Market
Adhesives & Sealants
North America Flock Adhesives Market
Adhesives & Sealants
Global Methyl Acrylate Market
Adhesives & Sealants
Tissue Sealants and Tissue Adhesive Market
Adhesives & Sealants
Construction Adhesives and Sealants Chemical Market
Adhesives & Sealants
Polysulfide Sealants Market