
 Water-Borne Resins Market | 2026-2036
Water-Borne Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Water-Borne Resins Market Analytics
European specialty chemical producers is pivoting toward water-borne resin capacity expansions as environmental compliance tightens across industrial coatings. BASF SE leverages its integrated polyurethane precursor network to secure feedstock advantages for water-borne dispersions. Dow anchors its position through acrylic emulsion technology leadership in architectural and industrial applications. Covestro AG differentiates via high-performance water-borne polyurethane systems targeting automotive clearcoat segments.
Water-borne resins are polymer dispersions or solutions in which the continuous phase is water rather than organic solvent, typically formulated with particle sizes between 0.01 and 5.0 micrometers and volatile organic compound content below regulatory thresholds. These materials serve as film-forming binders in coatings, adhesives, and sealants where reduced solvent emissions and simplified cleanup operations provide industrial value. Acrylic emulsions command the largest volume share in architectural coatings due to cost-performance balance and exterior durability. Polyurethane dispersions represent the fastest-expanding category as automotive and furniture manufacturers pursue premium finish properties without solvent-based systems. Epoxy water-borne formulations occupy specialized industrial maintenance and protective coatings where corrosion resistance requirements dominate specification decisions.
EPA VOC regulations, REACH substance restrictions, and China's MEE emission standards collectively mandate solvent reduction across coatings value chains, directly steering resin procurement toward water-borne alternatives. CE marking and ISO 11890 test methods establish performance benchmarks that determine market access for imported formulations. Buyers and formulators must track regulatory divergence between jurisdictions to avoid compliance gaps in cross-border supply arrangements.
Market Dynamics
Automotive OEM coating specifications are forcing a platform shift from solvent-borne to water-borne systems as EPA VOC limits and REACH substance restrictions tighten simultaneously across major manufacturing jurisdictions.
Growth Catalysts
- REACH substance restrictions:ECHA's evolving candidate list of substances of very high concern is eliminating legacy solvent-borne options from EU industrial coatings procurement, redirecting formulation R&D budgets toward water-borne polyurethane dispersions.
- Automotive clearcoat demand:Premium vehicle manufacturers in Germany and the US are specifying water-borne polyurethane systems for scratch-resistant finishes, creating specification pull through the tier supply chain.
- China's MEE emission standards:Provincial environmental enforcement in Jiangsu and Guangdong is shuttering solvent-based coating facilities, consolidating demand toward compliant water-borne resin suppliers with domestic production assets.
Market Restraints
- Propylene oxide cost volatility:Polyurethane dispersion feedstock pricing fluctuates with propylene derivative markets, compressing margin stability for specialty resin producers without backward integration into polyol precursors.
- Freeze-thaw stability limitations:Water-borne epoxy formulations suffer performance degradation below 5°C during storage and transport, restricting deployment in northern climate industrial maintenance applications without climate-controlled logistics.
- Application equipment retrofit requirements:Converting solvent-borne spray lines to water-borne systems demands capital expenditure on humidity-controlled booths and modified atomization technology, slowing adoption among small-batch industrial coaters.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Production-linked incentives for domestic chemical manufacturing are attracting water-borne resin capacity investments to serve accelerating automotive and furniture coating demand in Maharashtra and Tamil Nadu.
- UV-water-borne hybrid convergence:Combining ultraviolet cure speed with water-borne low-VOC bases enables single-coat industrial wood finishing, opening specification opportunities in European kitchen cabinetry and flooring segments.
- Direct-to-applicator digital distribution:E-procurement platforms for industrial coatings raw materials are disintermediating traditional distributor networks, allowing resin producers to capture margin and capture formulation data from mid-size applicators.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in colloidal stability and particle size engineering for water-borne dispersions concentrates among aging technical workforces in Germany and Japan, constraining new facility staffing.
- ISO 11890 certification timelines:VOC testing protocol variability across notified bodies delays market entry for reformulated products, extending product launch cycles by 8-14 months for multi-jurisdiction registrations.
- Legacy solvent-borne inventory amortization:Coatings manufacturers with substantial solvent-based raw material positions face stranded asset risk and internal resistance to accelerated water-borne transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water-Borne Resins Market |
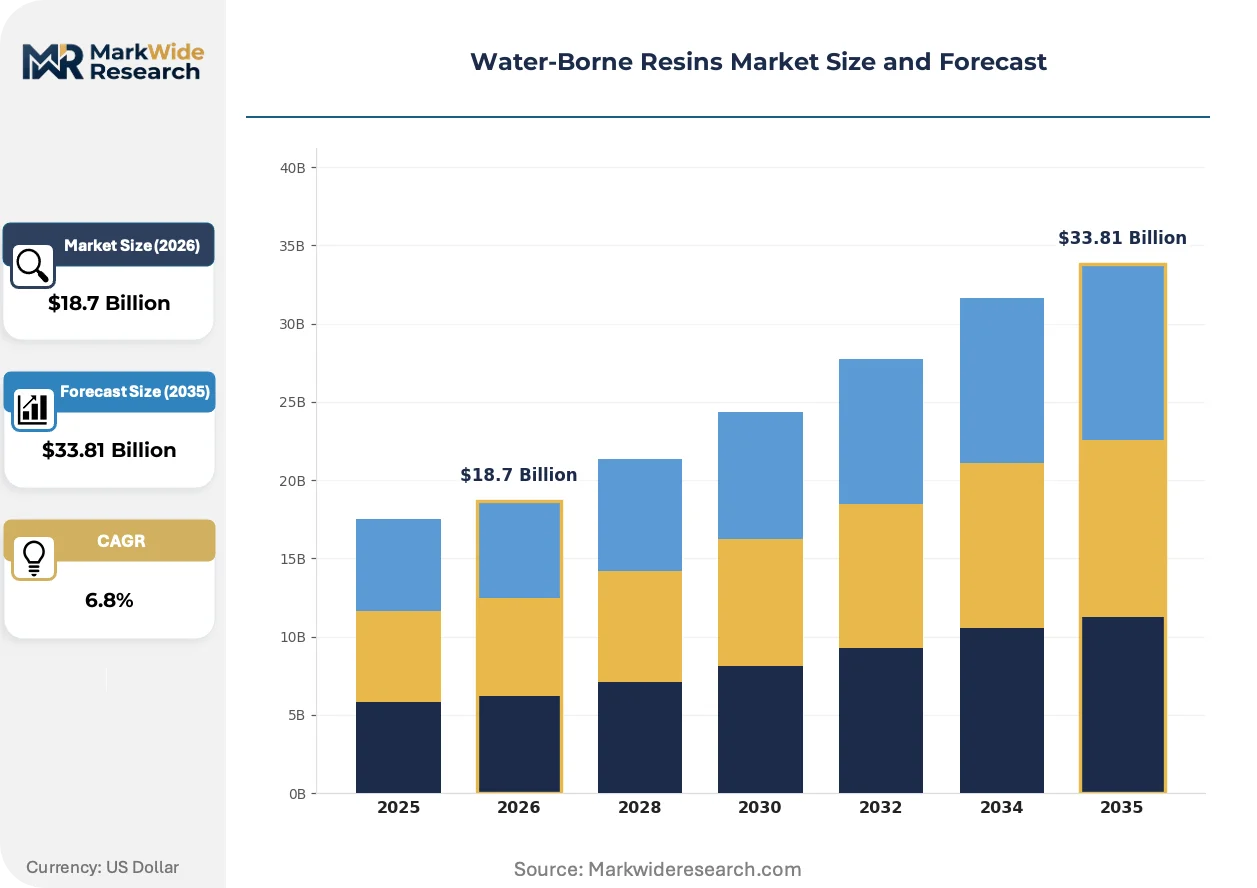
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Acrylic, Epoxy, Vinyl Ester End Use Industry: Construction, Automotive, Aerospace, Furniture Application: Coatings, Adhesives, Inks, Sealants Grade: Industrial, Commercial, Decorative, Others |
| Companies Covered | BASF SE, Dow, Lubrizol Corporation, Covestro AG, Arkema, Allnex GMBH, DIC Corporation, Westlake Corporation, ADEKA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water-Borne Resins Market Evolving Landscape
Continuous reactor technology for emulsion polymerization is compressing batch cycle times and particle size distribution variance, reshaping production economics for acrylic dispersion suppliers serving high-volume architectural segments.
Self-optimizing process control systems using real-time particle size analyzers and automated viscosity adjustment are automating quality consistency in water-borne resin manufacturing. German and US specialty chemical producers are deploying these systems at greenfield polyurethane dispersion facilities to reduce off-specification rates and labor intensity. The technology is automating the displacement of manual sampling protocols that previously required 15-20 minute batch holds, enabling continuous operation modes that lift effective capacity without reactor expansion.
EPA's National Emission Standards for Hazardous Air Pollutants for coating manufacturing is tightening residual solvent limits in water-borne resin production facilities. The rule's 2024 compliance deadline is forcing capital expenditure on thermal oxidizers and carbon capture systems at US-based acrylic emulsion plants. Automotive OEMs sourcing from affected suppliers are accelerating dual-qualification programs with European and Asian resin producers to secure supply continuity during facility upgrade shutdowns.
Specification authority is migrating from coatings formulators to end-use OEM engineering departments as environmental compliance accountability shifts upstream. Automotive and furniture manufacturers are establishing approved material lists that pre-qualify water-borne resin chemistries, compressing formulator discretion and favoring suppliers with direct OEM technical relationships. This concentration of buying influence is most pronounced in German automotive supply chains and US residential construction product segments where ESG reporting requirements demand supply chain transparency.
Water-Borne Resins Market Segmentation
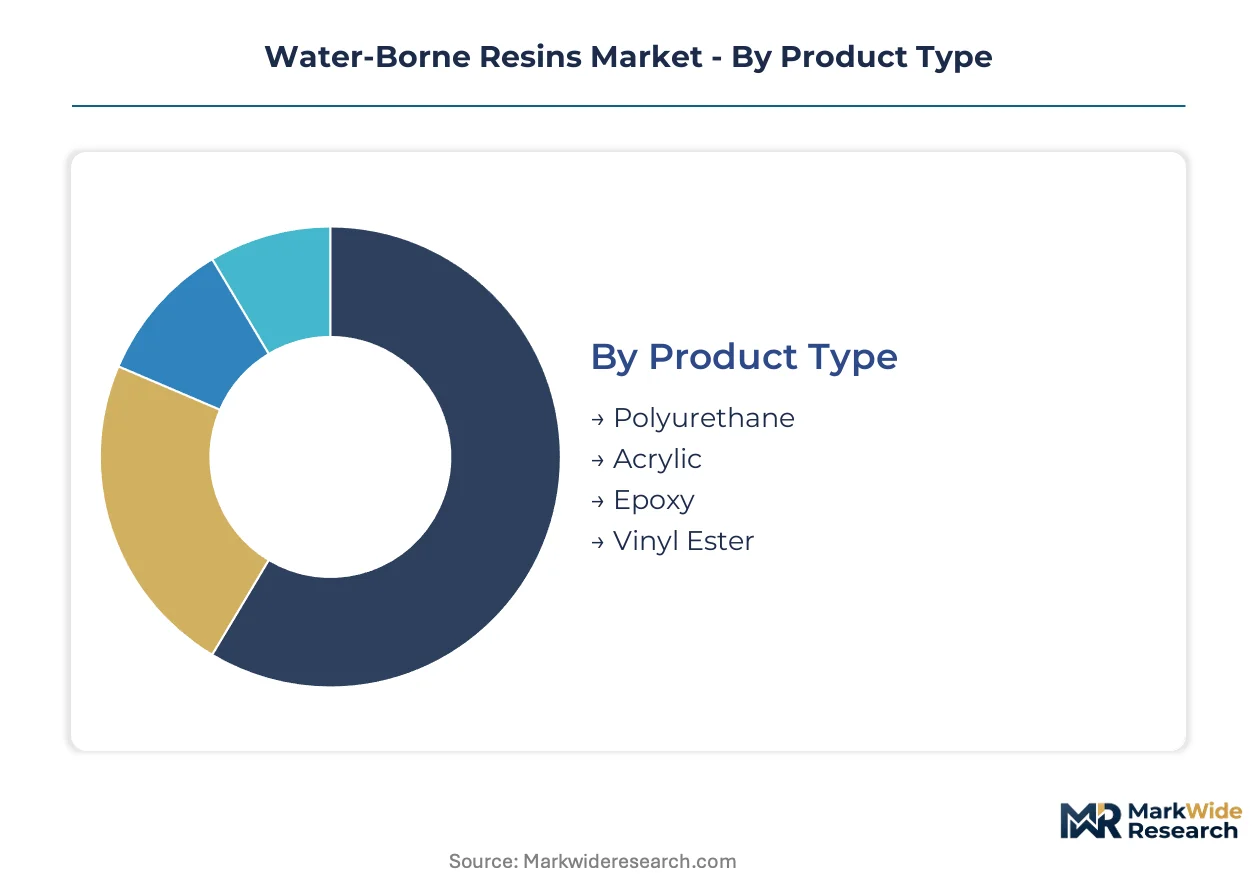
Water-borne resin procurement decisions diverge sharply across end-use specifications, regulatory exposure, and performance requirements. Formulators select chemistries based on VOC compliance thresholds, film property needs, and application equipment compatibility rather than commodity pricing alone.
Product Type:
Buyers in this category prioritize scratch resistance, chemical durability, and drying speed depending on whether they serve automotive OEMs, furniture manufacturers, or industrial maintenance contractors.
- Polyurethane:High-performance dispersions form tough, flexible films through phase-separated hard and soft segments. Automotive clearcoat specifications in Germany and premium furniture finishing in Italy are concentrating demand as manufacturers abandon solvent-borne two-component systems under REACH pressure.
- Acrylic:Emulsion polymers built from methacrylate and acrylate monomers deliver cost-effective exterior durability with UV resistance. Architectural coatings for residential construction in the US and China absorb the largest volumes, driven by EPA VOC limits and China's MEE enforcement in Jiangsu province.
- Epoxy:Water-dispersed epoxy resins and amine curing agents provide corrosion protection for industrial maintenance. Application concentrates in marine and infrastructure protective coatings where salt spray resistance dominates specifications.
- Vinyl Ester:Hybrid systems combining vinyl functionality with ester backbone chemistry offer chemical resistance at moderate cost. Demand localizes in industrial tank lining and chemical processing equipment coatings.
Acrylic emulsions lead volumes today; polyurethane dispersions are gaining share fastest.
End Use Industry:
Volume concentration tracks construction activity cycles, automotive production schedules, and aerospace MRO intervals across major manufacturing economies.
- Construction:Architectural coatings for residential and commercial buildings represent the foundational demand base. Exterior wall paints and roof coatings in China and the US absorb emulsion volumes as urbanization and renovation activity persist.
- Automotive:OEM coating systems for body-in-white, primer, basecoat, and clearcoat layers are converting to water-borne platforms. German and US manufacturers specify polyurethane clearcoats for scratch resistance and gloss retention.
- Aerospace:MRO coating operations for commercial aircraft exteriors require qualified water-borne systems meeting OEM repair specifications. Application concentrates in maintenance facilities near major hubs in the US and France.
- Furniture:Wood finishing for kitchen cabinetry, flooring, and office furniture drives demand for fast-drying, low-odor systems. Italian and German manufacturers lead specification authority for premium finishes.
Construction absorbs the largest tonnage; automotive applications are expanding most rapidly.
Application:
Formulation viscosity, solids content, and drying mechanism requirements separate buyers by application method and production line speed.
- Coatings:Decorative and protective films applied by spray, dip, or roller methods constitute the dominant application mode. Industrial OEMs and architectural contractors specify water-borne systems for compliance with EPA and REACH emission limits.
- Adhesives:Bonding formulations for packaging, woodworking, and footwear assembly require tailored tack, open time, and shear strength. Converters in Germany and China are shifting from solvent-based contact cements.
- Inks:Flexographic and gravure printing applications for flexible packaging demand low-viscosity dispersions with fast resolubility. Food packaging safety regulations in the US and EU drive migration-resistant formulations.
- Sealants:Elastomeric joint fillers for construction and transportation applications require movement accommodation and weathering resistance. Specifications concentrate in commercial building envelopes and automotive seam sealing.
Coatings dominate current offtake; adhesives are climbing the fastest.
Grade:
Performance tier and certification requirements separate procurement budgets, with industrial specifications commanding premium pricing over decorative alternatives.
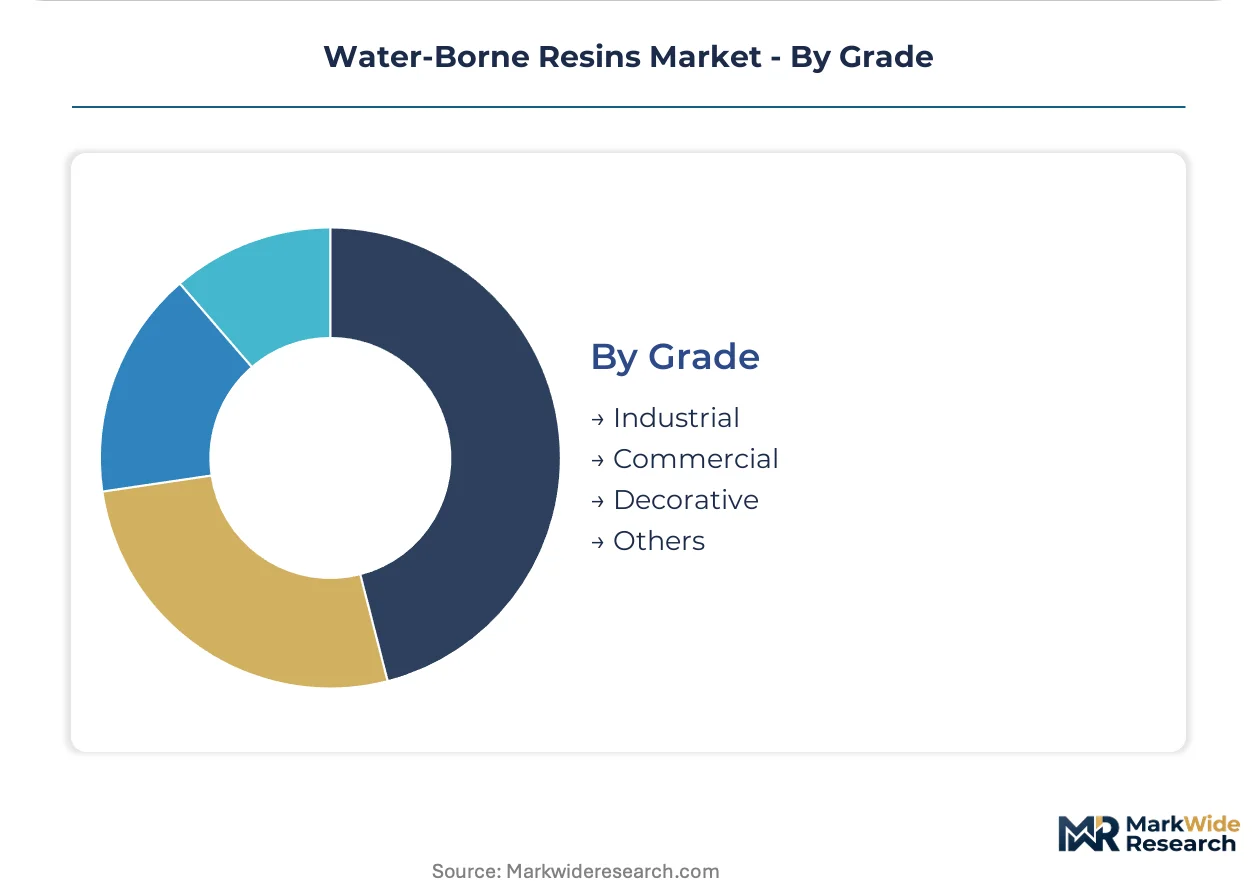
- Industrial:High-performance grades meeting OEM specifications for chemical resistance, durability, and process compatibility. Automotive and aerospace qualified materials carry extensive testing documentation and supply chain audit requirements.
- Commercial:Mid-tier products balancing performance and cost for professional applicators and mid-volume manufacturers. Architectural contractors and furniture producers specify these grades for consistent batch-to-batch properties.
- Decorative:Consumer-facing grades prioritizing application ease, low odor, and color consistency for DIY and residential professional use. Retail distribution channels in the US and Europe stock these formulations.
- Others:Specialty grades including food-contact compliant, medical device, and electronics coating formulations with niche certification requirements.
Industrial grades command the highest value per kilogram; commercial grades move the largest absolute volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps are redirecting water-borne resin production capacity toward jurisdictions with streamlined environmental enforcement and accessible feedstock networks. Manufacturers are arbitraging between EPA-mandated US upgrade costs and China's consolidated MEE-driven demand concentration.
China
Jiangsu and Guangdong provincial authorities are shuttering solvent-based coating facilities under MEE emission standards, consolidating procurement toward domestic water-borne resin producers with captive acrylic emulsion capacity. Shanghai and Ningbo chemical parks host expanding polyurethane dispersion plants serving automotive OEMs. Yangtze River Delta coatings clusters are absorbing redirected investment as environmental compliance costs rise in competing jurisdictions.
Germany
Automotive clearcoat specifications from Stuttgart and Munich OEMs are concentrating demand for water-borne polyurethane systems with REACH-compliant chemistries. ECHA substance restrictions are eliminating legacy solvent-borne alternatives from industrial procurement. BASF's Ludwigshafen integrated site anchors polyurethane precursor supply for dispersion producers serving premium furniture and automotive finishing segments.
United States
EPA National Emission Standards for Hazardous Air Pollutants are forcing thermal oxidizer investments at acrylic emulsion plants in Texas and Ohio. Automotive OEMs in Michigan and Tennessee are accelerating dual-qualification programs with Asian and European suppliers during facility upgrade shutdowns. Architectural coatings demand in California and Florida sustains high-volume emulsion offtake despite production cost pressures.
India
PLI scheme incentives for specialty chemicals are attracting water-borne resin capacity to Maharashtra and Tamil Nadu serving accelerating automotive and furniture coating demand. BIS standards for VOC content are tightening compliance requirements for imported formulations. Pune and Chennai industrial corridors are consolidating as preferred locations for greenfield dispersion facilities targeting domestic OEM supply chains.
Japan
Formulation chemist scarcity concentrates among aging technical workforces in Osaka and Nagoya, constraining new facility staffing for water-borne dispersion production. METI industrial standards are aligning with ISO 11890 VOC test protocols for coatings raw materials. Kansai-region chemical producers are maintaining specialized epoxy water-borne capacity for marine protective coatings serving domestic shipbuilding.
Water-Borne Resins Market Competitive Landscape
German producers anchor the integrated precursor tier; Japanese and US specialists hold positions in high-performance dispersion segments. The vendor structure concentrates around diversified chemical conglomerates with backward integration into polyol and acrylic monomer supply, alongside focused resin specialists competing on formulation expertise. Three archetypes dominate: integrated petrochemical majors with captive feedstock, regional dispersion specialists with OEM technical relationships, and Asian scale producers serving high-volume architectural segments. Competitive dynamics center on capacity expansion in China and India, plus strategic partnerships to secure qualified supply positions with automotive OEM approved material lists.
Among Germany-based chemical conglomerates, BASF SE and Covestro AG exemplify the integrated precursor archetype, leveraging polyurethane technology networks for water-borne dispersion supply. Dow represents US-based acrylic emulsion leadership with architectural and industrial application coverage. These three companies occupy positions where direct OEM technical relationships and feedstock integration determine specification authority in automotive and furniture finishing segments.
| Leading Market Players |
|---|
| BASF SE |
| Dow |
| Lubrizol Corporation |
| Covestro AG |
| Arkema |
| Allnex GMBH |
| DIC Corporation |
| Westlake Corporation |
| ADEKA Corporation |
| Others |
Value Network & Pricing Analysis
Propylene oxide feedstock costs cascade through polyurethane dispersion production into tiered pricing for automotive clearcoat specifications, with volatility in Asian derivative markets compressing margins for non-integrated European and North American suppliers serving REACH-compliant OEM procurement.
Pricing Analysis
Distributor margin layers absorb 12-18 percentage points between resin producer ex-works pricing and formulator landed cost, with direct-to-OEM supply agreements commanding 8-15 point discounts for volume commitments above 5,000 metric tons annually. Three-tier pricing structure across premium, standard, and economy levels separates qualified automotive grades with ISO 11890 certification from commercial architectural emulsions and unbranded decorative alternatives. Pricing pressure stems from propylene oxide cost volatility and MEE-driven capacity expansion in China flooding mid-tier segments. Small-batch industrial coaters exhibit highest price sensitivity due to capital constraints on spray line retrofits, while German automotive OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs mandate multi-supplier qualification for polyurethane dispersions, with BASF Ludwigshafen and Covestro Leverkusen serving as primary anchors alongside qualified Asian alternatives. Geographic supply concentrates in Germany, China, and the United States, with acrylic emulsion production clustering in Jiangsu province and Ohio River Valley chemical corridors. Raw material dependencies center on propylene oxide, methacrylate monomers, and amine curing agents sourced from integrated petrochemical complexes. Single-source vulnerability persists in specialty polyol precursors where backward integration concentrates among three German producers. Distribution runs through regional chemical distributors serving formulator clusters, with direct rail and tanker truck delivery dominating high-volume architectural segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-borne resins function as a stable compounder anchored by irreversible regulatory displacement of solvent-borne systems across automotive and industrial coatings procurement.
For Market Incumbents: Acquire polyurethane precursor assets in the Yangtze River Delta to secure feedstock advantage as Chinese MEE enforcement consolidates domestic demand. Lock in automotive OEM approved material list positions before dual-qualification programs mature, while investing in continuous reactor technology to compress batch cycle times and defend margin position against Asian scale entrants. For New Entrants and Emerging Players: Industrial coating applicators in India's Maharashtra and Tamil Nadu corridors represent the most penetrable entry point, with PLI scheme incentives reducing capital barriers for greenfield dispersion facilities. Target mid-tier furniture manufacturers in European kitchen cabinetry segments with UV-water-borne hybrid formulations, leveraging specification gaps left by incumbent focus on automotive clearcoat dominance. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation chemist scarcity constrains new facility staffing and aging technical workforces in Germany and Japan approach retirement. Five-to-ten year viability favors integrated producers with captive polyol supply and direct OEM technical relationships over pure-play dispersion specialists. Watch for propylene oxide price spikes as inflection indicators accelerating acquisition premiums for backward-integrated targets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Precursors | Captive propylene oxide supply insulates margin stability from derivative market volatility. |
| Continuous Reactor Technology Deployment | Real-time particle size automation reduces off-specification rates at greenfield polyurethane dispersion facilities. |
| Automotive OEM Approved Material List Qualification | Direct technical relationships with Stuttgart and Munich manufacturers secure specification authority. |
| UV-Water-Borne Hybrid Formulation Launch | Single-coat wood finishing opens European kitchen cabinetry and flooring specification opportunities. |
| Direct-to-Applicator Digital Distribution | E-procurement platforms disintermediate traditional distributors and capture formulation data from mid-size coaters. |
Research Methodology
Direct dialogue with resin plant managers, automotive OEM procurement leads, coatings formulator R&D directors, and regional chemical distributors grounded qualitative assessment, combined with secondary validation from customs trade data, ACC and Cefic industry reports, SEC 10-K chemical segment disclosures, and EPA enforcement action records. Bottom-up capacity and utilization estimates triangulated against top-down demand modeling from construction spending indices and automotive production schedules.
Bottom-up volume builds aggregated segment-level consumption across construction, automotive, furniture, and aerospace end uses, while top-down approaches cross-checked against macro coatings production data across the analysis window. Segmentation dimensions modeled include chemistry type, performance grade tier, end-use industry, and regional regulatory cluster. CAGRs derived from regression analysis of historical volume trajectories against enforcement timeline milestones and OEM specification conversion rates, with propylene oxide price elasticity and MEE compliance cost curves as key industry-specific inputs.
Revisions become necessary when REACH substance restriction expansions, EPA NESHAP enforcement intensity shifts, or propylene derivative supply disruptions materialize beyond baseline assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Middle East Fluoropolymer Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Market
Polymers & Resins
Rigid Spray Polyurethane Foam Market
Polymers & Resins
China Engineering Plastics Market
Polymers & Resins
Biobased Thermosetting Polymers Market
Polymers & Resins
Polyethylene Furanoate (PEF) Barrier Resin Market
Polymers & Resins
Global Polyolefin Resins Market
Polymers & Resins
Polyimides Market
Polymers & Resins
Neoprene Market
Polymers & Resins
Middle-East and Africa Thermoplastics Market
Polymers & Resins
BMI Resins Market
Polymers & Resins
Europe Polymer Emulsion Market
Polymers & Resins
India Epoxy Resins Market
Polymers & Resins
Ethylene Vinyl Acetate (EVA) Market
Polymers & Resins
Polyacrylamide Market
Polymers & Resins
Middle East and Africa Polyurethane Market