
 Resin Intermediate Market | 2026-2036
Resin Intermediate Market Size, Share, and Industry Trends Forecast 2026-2036
Resin Intermediate Market Analytics
The split between specification-grade and commodity resin intermediates is realigning contract structures and margin capture across the value chain. BASF SE leverages its Ludwigshafen Verbund complex to sustain integrated phenol and polyamide feedstock economics. Dow Chemical anchors North American epoxy resin supply through its Freeport, Texas operations and bisphenol A backward integration. Sinopec Corporation dominates Asia-Pacific aromatics supply, positioning its Yangtze River Delta refineries as gatekeepers for regional phenolic and polyester intermediate pricing.
Resin intermediates comprise reactive chemical building blocks—typically oligomers or prepolymers with molecular weights between 500 and 10,000 Daltons—synthesized through condensation or addition polymerization and subsequently cured or chain-extended into final thermoset or thermoplastic matrices. Epoxy intermediates based on diglycidyl ether of bisphenol A (DGEBA) with epoxide equivalent weights of 170–200 g/eq serve as the backbone for high-performance adhesives, composites, and protective coatings across automotive and electronics applications. Polyester intermediates lead volume consumption in construction-grade reinforced composites and powder coatings, while polyamide intermediates such as caprolactam and adipic acid command premium positioning in automotive underhood and electrical insulation segments where thermal resistance thresholds exceed 150°C continuous service temperature.
REACH in Europe, EPA TSCA in the United States, and China's MEE emission standards collectively restrict free phenol and residual monomer content in finished intermediates, forcing reformulation investments and supplier requalification cycles. The EU F-Gas Regulation and evolving state-level PFAS restrictions in California and Michigan are additionally narrowing acceptable curing agent chemistries for epoxy systems. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and secure multi-region product registrations before specification lock-in by downstream OEMs.
Market Dynamics
Automotive lightweighting mandates in Germany and Japan are compressing specification cycles for epoxy and polyamide intermediates, forcing suppliers to synchronize R&D with OEM platform timelines rather than traditional commodity contracting rhythms.
Growth Catalysts
- REACH compliance deadlines:ECHA's tightening residual monomer limits for bisphenol A derivatives are accelerating qualification of high-purity DGEBA grades among European coatings formulators.
- China's dual carbon goals:MEE emission standards for phenol-acetone complexes are consolidating capacity around Shanghai and Ningbo, concentrating supply chain leverage with integrated operators.
- EV battery encapsulation:Thermal management requirements for lithium-ion modules are pulling specialty epoxy formulations into automotive electronics at volumes previously reserved for industrial adhesives.
Market Restraints
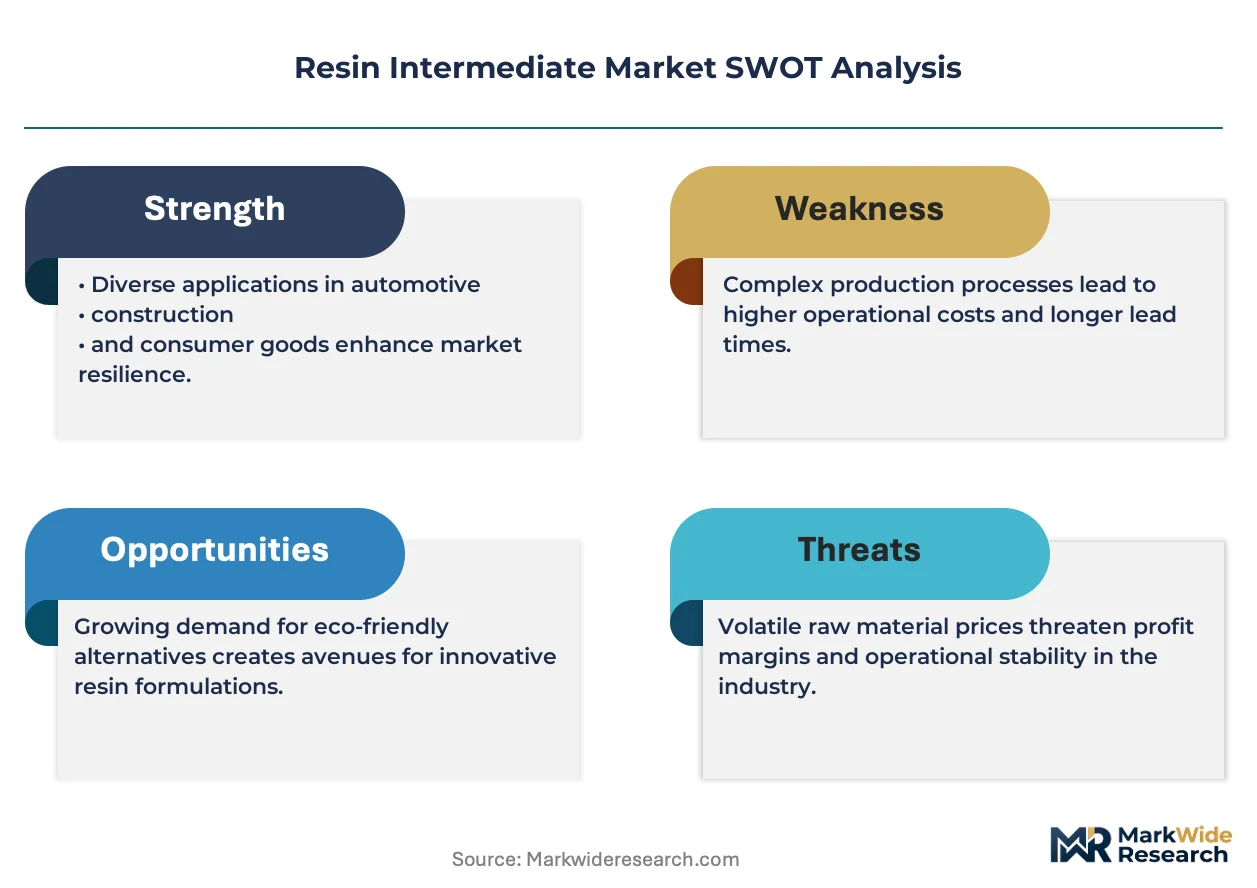
- Propylene-benzene feedstock volatility:Crude-linked aromatics pricing transmits directly to phenol and acetone contract structures, compressing margin predictability for non-integrated compounders.
- East China supply concentration:Over 60 percent of Asia-Pacific bisphenol A capacity sits within 200 kilometers of Ningbo, creating geographic single-point vulnerability for regional epoxy resin supply.
- PFAS substitution timelines:California and Michigan state-level restrictions on fluorinated curing agents are forcing reformulation of high-performance epoxy systems before qualified alternatives achieve scale.
Strategic Opportunities
- India's PLI scheme for advanced chemicals:Domestic caprolactam and adipic acid production incentives are opening import-substitution pathways for polyamide intermediates serving automotive and electrical segments.
- Wind blade recycling infrastructure:Decommissioned turbine composite waste streams are creating feedstock arbitrage for chemical recyclers targeting recovered epoxy and polyester intermediates.
- ISO 14001-integrated supplier certification:Downstream OEMs are consolidating procurement around dual-certified environmental management systems, favoring compounders with documented lifecycle data.
Industry Challenges
- Process analytical chemistry talent scarcity:Real-time quality control for epoxide equivalent weight specifications requires hybrid skill sets combining spectroscopy and statistical process control that remain underrepresented in manufacturing regions.
- Multi-jurisdiction registration synchronization:Divergent timelines between EPA TSCA Section 5 notifications and EU REACH authorization processes are extending product launch windows by 18-24 months for novel curing agent chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resin Intermediate Market |
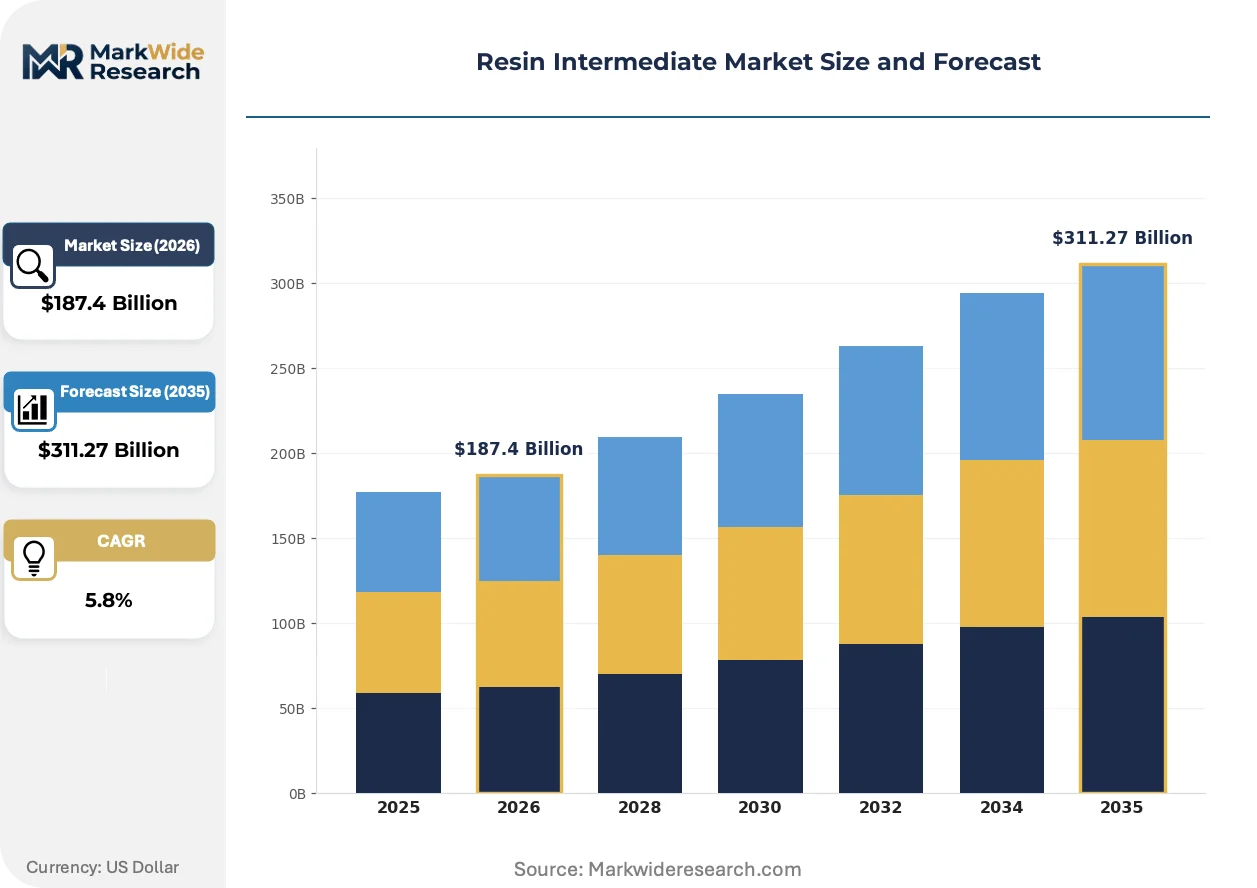
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Epoxy, Polyamide, Phenolic End Use Industry: Automotive, Construction, Electronics, Coatings Form: Liquid, Powder, Granule, Flake Technology: Batch Processing, Continuous Processing, Thermosetting, Thermoplastic |
| Companies Covered | Sinopec Corporation, Olin Corporation, 3M, DIC Corporation, Westlake Epoxy, BASF SE, SABIC, Dow Chemical, Hexion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resin Intermediate Market Evolving Landscape
Bio-based feedstock substitution and digital process control architectures are converging to redefine cost structures and qualification protocols across thermoset intermediate supply chains.
Continuous flow reactor technology for bisphenol A epoxidation is decentralizing capital requirements for mid-scale epoxy intermediate production. Regional compounders in Texas and Rotterdam are piloting skid-mounted systems that slash batch cycle times from 12 hours to 90 minutes. This distributed manufacturing model is compressing logistics costs for coatings formulators serving construction and marine end-uses.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon blowing agents is forcing rigid polyurethane and epoxy foam manufacturers toward water-blown and hydrocarbon alternatives. Formulators serving cold-chain insulation and appliance segments are requalifying entire product lines ahead of 2027 quota reductions. German appliance OEMs are accelerating supplier audits to lock in compliant intermediate sources before specification windows close.
Automotive Tier 1s are unbundling material specification from volume contracting, creating dual-track procurement where resin intermediate suppliers compete separately on technical qualification and commercial terms. This bifurcation is visible most acutely in Germany's supplier parks, where epoxy and polyamide compounders now maintain parallel engineering and commercial relationships with the same OEM platform teams.
Resin Intermediate Market Segmentation
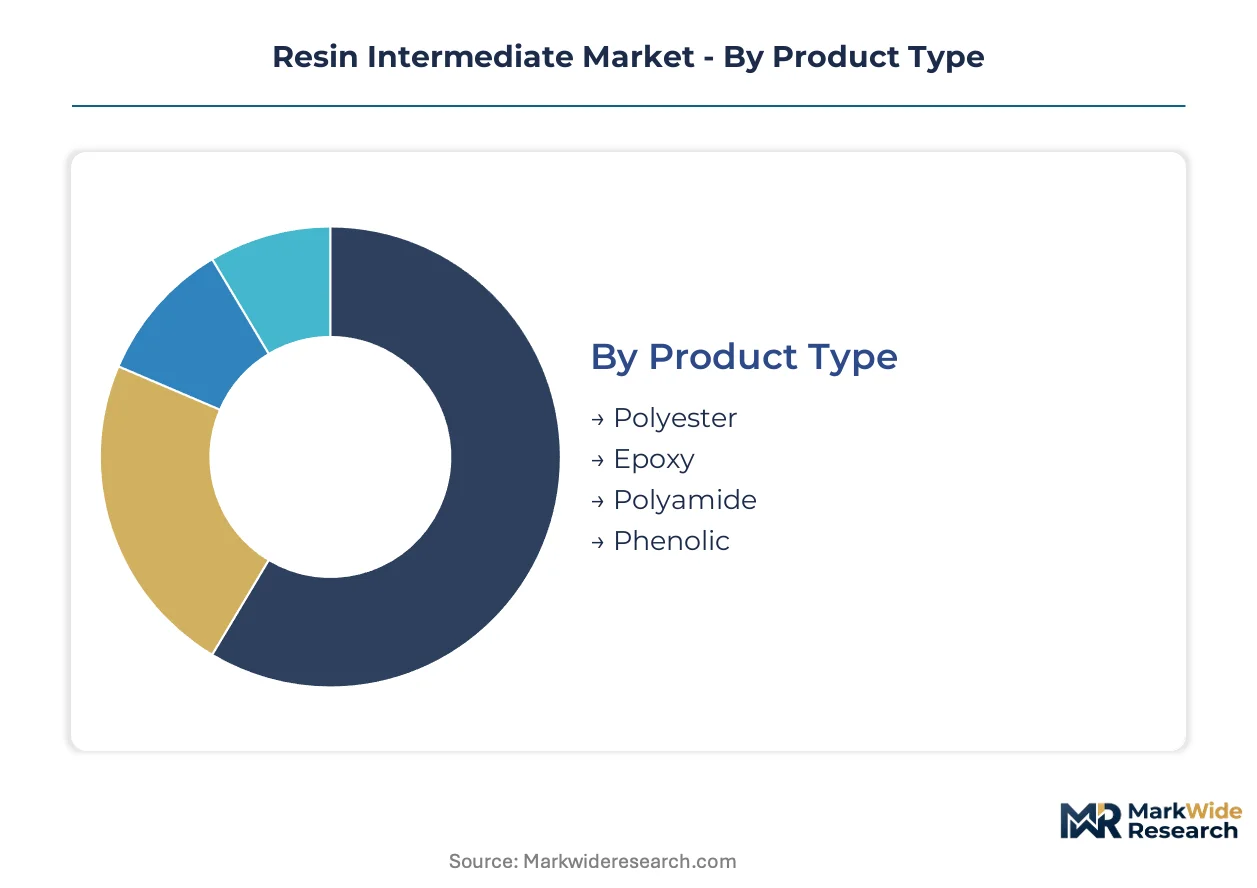
Resin intermediate procurement increasingly bifurcates between specification-driven automotive and electronics segments and cost-sensitive construction applications. Segmentation by product chemistry, end-use requirements, physical form, and manufacturing technology determines margin capture, regulatory burden, and supplier qualification protocols across the value chain.
Product Type:
REACH authorization for bisphenol A derivatives and China's MEE emission standards impose divergent compliance burdens across chemistries, with epoxy and polyamide intermediates facing the most stringent residual monomer limits.
- Epoxy:Diglycidyl ether of bisphenol A (DGEBA) intermediates with epoxide equivalent weights of 170–200 g/eq dominate high-performance adhesives and composite matrices. German automotive OEMs are compressing qualification cycles for low-viscosity grades serving EV battery encapsulation, where thermal management specifications exceed 150°C continuous service.
- Polyamide:Caprolactam and adipic acid intermediates command premium positioning in automotive underhood and electrical insulation segments. Japan's METI efficiency standards are accelerating consumption of heat-stabilized grades in hybrid powertrain components.
- Polyester:Unsaturated and saturated polyester intermediates lead volume consumption in construction-grade reinforced composites and powder coatings across China and India.
- Phenolic:Novolac and resole intermediates serve high-temperature friction materials and electrical laminates, with formaldehyde emission regulations tightening feedstock specifications in Europe and North America.
Polyester sits at the top of the volume ranking, with polyamide climbing the fastest.
End Use Industry:
Customer procurement patterns separate into platform-integrated automotive supply chains and spot-market construction purchasing, with electronics and coatings occupying intermediate positions on contract duration and specification intensity.
- Automotive:Lightweighting mandates in Germany and Japan are pulling specialty epoxy and polyamide formulations into structural composites and underhood applications. Tier 1 suppliers now maintain dual-track engineering and commercial relationships with resin compounders.
- Construction:Reinforced composites and powder coatings consume the largest absolute volumes of polyester intermediates, with procurement concentrated around East China chemical clusters and US Gulf Coast distribution hubs.
- Electronics:Thermal management requirements for lithium-ion battery modules are displacing industrial adhesive volumes with automotive-grade epoxy formulations.
- Coatings:Marine and protective coatings formulators in Rotterdam and Texas are piloting continuous flow reactor outputs to compress logistics costs and batch cycle times.
Construction maintains the largest installed demand base, while automotive electronics is expanding most quickly.
Form:
Physical state determines handling infrastructure, shelf-life constraints, and compatibility with downstream compounding equipment across regional supply chains.
- Liquid:Low-viscosity epoxy and polyester intermediates dominate automated dispensing systems in automotive and electronics manufacturing. German appliance OEMs are locking in compliant sources ahead of F-Gas Regulation quota reductions.
- Powder:Solid epoxy and polyester grades serve powder coating applications, with particle size distribution specifications tightening for thin-film automotive finishes.
- Granule:Polyamide intermediates in pellet form feed injection molding and extrusion lines serving electrical connectors and underhood components.
- Flake:Solid phenolic and specialty epoxy intermediates support manual blending operations in construction and marine repair segments.
Liquid forms hold the highest shipment volumes, with powder gaining share fastest in automotive coating applications.
Technology:
Process architecture separates integrated petrochemical operators from regional compounders, with capital intensity and batch size flexibility determining competitive positioning.
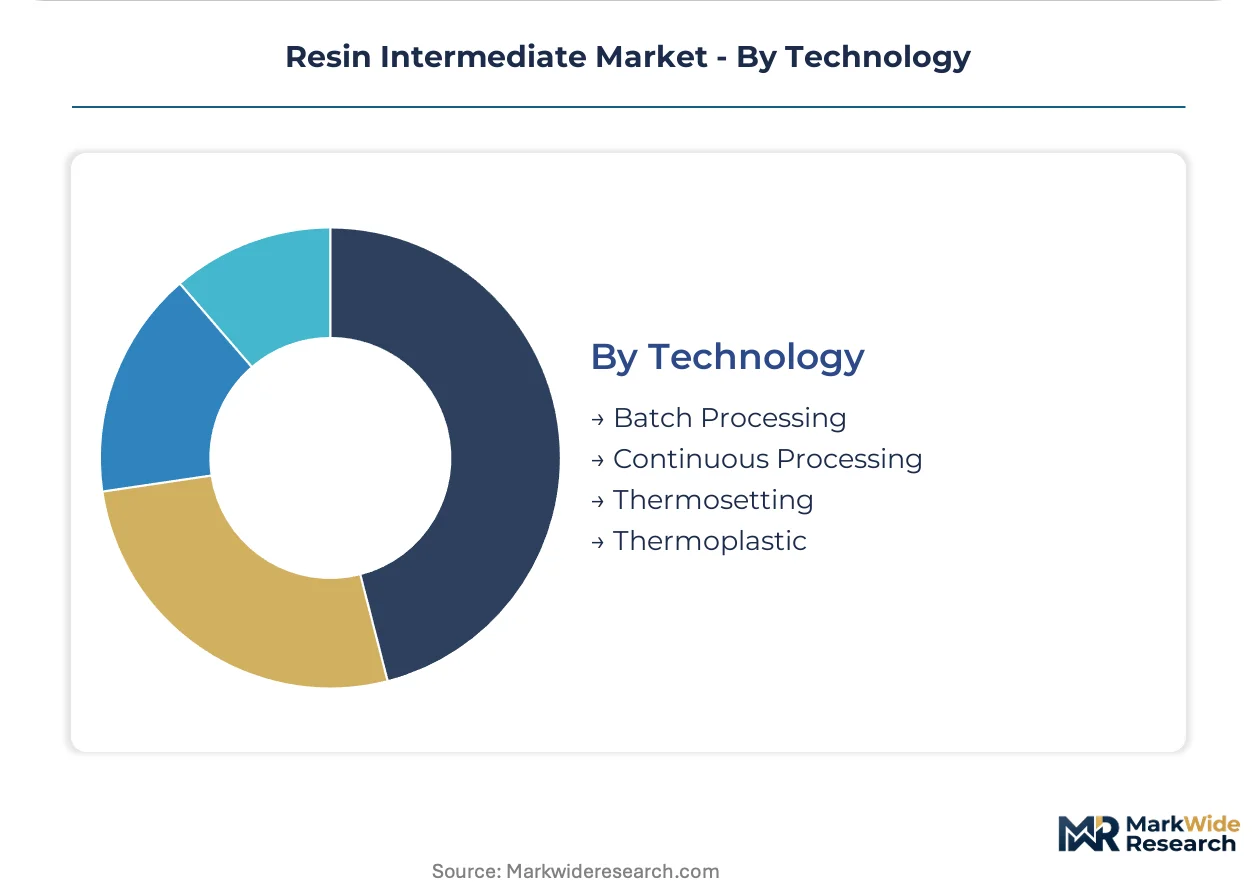
- Batch Processing:Traditional vessel-based epoxidation and condensation systems serve custom formulation requirements with 12-hour cycle times. Mid-scale compounders in Texas and Rotterdam are maintaining this infrastructure for specialty grades.
- Continuous Processing:Skid-mounted flow reactors are decentralizing capital requirements and compressing cycle times to 90 minutes for standard epoxy intermediates.
- Thermosetting:Irreversible cure chemistry dominates structural composites and adhesives, with formulation locked in at the intermediate stage.
- Thermoplastic:Reversible melt processing characterizes polyamide intermediates, enabling regrind and recycling in automotive and electrical applications.
Batch processing retains the largest installed base, with continuous systems climbing the fastest among new capacity investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized process chemists and polymer engineers cluster around integrated petrochemical hubs in Germany, China, Japan, and the United States, anchoring regional innovation capacity for advanced resin formulations.
Germany
Automotive lightweighting mandates from KBA drive specification-grade epoxy and polyamide consumption for structural composites. REACH authorization timelines for bisphenol A derivatives compress supplier qualification windows. The Ludwigshafen chemical complex sustains captive phenol-acetone and polyamide feedstock integration.
China
EV battery encapsulation demand pulls specialty epoxy formulations into automotive electronics at industrial adhesive volumes. MEE emission standards consolidate phenol-acetone capacity around Shanghai and Ningbo chemical clusters. Yangtze River Delta refineries anchor regional bisphenol A pricing power.
Japan
METI efficiency standards accelerate heat-stabilized polyamide consumption in hybrid powertrain components. JIS certification requirements tighten residual monomer specifications for electrical insulation grades. Nagoya and Osaka manufacturing corridors concentrate automotive Tier 1 supplier parks.
United States
EPA TSCA Section 5 notification requirements extend launch windows for novel curing agent chemistries. Freeport, Texas operations anchor North American epoxy resin supply through bisphenol A backward integration. Gulf Coast distribution hubs serve construction-grade polyester intermediate demand.
India
PLI scheme incentives for advanced chemicals open import-substitution pathways for caprolactam and adipic acid production. BIS quality standards reshape supplier qualification for automotive and electrical segments. Gujarat and Maharashtra chemical corridors attract greenfield polyamide intermediate investments.
Resin Intermediate Market Competitive Landscape
Capital-heavy integrated petrochemical operators compete with asset-light regional compounders for specification-grade contract volumes. The market structure tiers between global aromatics giants with captive feedstock, mid-scale epoxy and polyamide specialists, and distributed continuous flow reactor pilots. Strategic differentiation centers on backward integration depth and qualification speed for automotive platform timelines. Capacity consolidation and dual-track procurement unbundling represent the dominant competitive moves reshaping supplier-OEM relationships.
Within the integrated aromatics tier, Sinopec Corporation and BASF SE occupy positions as gatekeepers for regional phenolic and polyamide intermediate pricing. Dow Chemical exemplifies the North American epoxy backbone through its Texas Gulf Coast operations. Among specialty compounders, Hexion and Westlake Epoxy sit within the mid-scale qualification-focused segment serving coatings and construction applications.
| Leading Market Players |
|---|
| Sinopec Corporation |
| Olin Corporation |
| 3M |
| DIC Corporation |
| Westlake Epoxy |
| BASF SE |
| SABIC |
| Dow Chemical |
| Hexion |
| Others |
Value Network & Pricing Analysis
Captive phenol-acetone integration at Ludwigshafen and Yangtze River Delta refineries anchors both supply security and pricing power for specification-grade epoxy and polyamide intermediates. BASF SE and Sinopec Corporation leverage this backward control to buffer margin volatility while regional compounders absorb feedstock cost transmission without equivalent leverage.
Pricing Analysis
The unbundling of material specification from volume contracting separates technical qualification premiums from commercial spot pricing across automotive procurement. Three-tier pricing structure across specification-grade, contract-standard, and spot-market economy levels tracks certification intensity and residual monomer compliance. Cost compression in commodity polyester intermediates intensifies as East China capacity expansions outpace construction demand growth. Construction-grade buyers exhibit highest price sensitivity, while German automotive OEMs prioritize qualification speed over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with East China phenol-acetone concentration, where over sixty percent of Asia-Pacific bisphenol A capacity clusters within two hundred kilometers of Ningbo. Feedstock draws from Saudi aromatics, US Gulf Coast propylene, and regional Chinese refinery output. Tariff exposure on phenol imports into India and Europe threatens margin structures for non-integrated compounders. Distribution runs through Rotterdam and Texas Gulf Coast hubs for Atlantic markets, with direct pipeline feeds to German automotive supplier parks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH authorization deadlines and China's MEE emission standards drive qualification demand for high-purity grades.
For Market Incumbents: To counter PFAS substitution timelines compressing curing agent alternatives, BASF SE and Dow Chemical should accelerate joint development agreements with epoxy formulators ahead of California and Michigan enforcement dates. Captive phenol production at Freeport and Ludwigshafen remains the priority lever for margin defense against propylene-benzene volatility. For New Entrants and Emerging Players: Continuous flow reactor technology offers a technology-first wedge into mid-scale epoxy intermediate production serving marine and construction coatings in Texas and Rotterdam. India's PLI scheme for caprolactam presents the most penetrable white-space target for polyamide import substitution. Qualification partnerships with German Tier 1 supplier parks provide the essential go-to-market angle for specification-grade entry. For Investors and Strategic Acquirers: Consolidation pressure builds where batch processing assets face stranded cost risk from continuous flow reactor scale economics. Five-to-ten year viability favors compounders with ISO 14001-integrated certification and documented lifecycle data for OEM procurement consolidation. The signal to watch is dual-track procurement unbundling spreading from Germany to Japanese automotive supplier parks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol-Acetone | Captive feedstock at Ludwigshafen and Yangtze Delta insulates margin from crude-linked aromatics volatility. |
| Continuous Flow Reactor Deployment | Skid-mounted systems in Texas and Rotterdam compress batch cycles from twelve hours to ninety minutes. |
| REACH Pre-Registration Investment | Early ECHA filing locks specification windows ahead of residual monomer limit tightening. |
| ISO 14001 Dual Certification | Documented lifecycle data satisfies OEM procurement consolidation around environmental management systems. |
| India PLI Scheme Participation | Domestic caprolactam production incentives open import-substitution pathways for automotive polyamide supply. |
Research Methodology
Coverage spans Germany, China, Japan, the United States, and India, with primary inputs from each market cluster combining interviews with plant managers, automotive Tier 1 procurement leads, coatings formulator technical directors, and distribution channel partners. Secondary validation draws from ECHA REACH filings, US EPA TSCA notifications, China MEE emission disclosures, and ACC trade data. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates across the analysis window.
Rate-of-change decomposition separates volume growth from price-mix effects across chemistry type, end-use industry, physical form, and regional production hub. CAGRs derive from segment-level elasticity modeling against automotive production forecasts and construction activity indices. Key inputs include EV battery encapsulation volume trajectories, wind blade installation schedules, and F-Gas Regulation phase-down timelines for rigid foam applications.
The model holds under stable regulatory enforcement timelines and intact propylene-benzone spread relationships; deviation in crude volatility spikes or accelerated PFAS restrictions would shift intermediate pricing power toward integrated operators. Forecasts reflect documented assumptions about OEM platform launch schedules and chemical cluster capacity commissioning. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Low Density Polyethylene Market
Polymers & Resins
India Epoxy Resins Market
Polymers & Resins
PET Foam Core Market
Polymers & Resins
Asia-Pacific Super Absorbent Polymers (SAP) Market
Polymers & Resins
Cast Polymers Market
Polymers & Resins
Silyl Acrylate Polymer (SAP) Market
Polymers & Resins
Global UV Curable Resins Market
Polymers & Resins
Semi-Crystalline Polymers Market
Polymers & Resins
Global Polymer Stabilizer Market
Polymers & Resins
Polyamide 11 & 12 Market
Polymers & Resins
South America Polycarbonate (PC) Market
Polymers & Resins
North America Polypropylene Copolymer Market
Polymers & Resins
Copolyesters Market
Polymers & Resins
Resorbable Polymers Market
Polymers & Resins
Polyether Ketone (PEK) Market
Polymers & Resins
Global Polyol and Polyurethane Market