
 Carbon Molecular Sieves Market | 2026-2036
Carbon Molecular Sieves Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Molecular Sieves Market Outlook
The gap between pharmaceutical-grade and industrial-grade carbon molecular sieves is repositioning procurement patterns across the value chain. Osaka Gas Chemicals leverages its resin precursor expertise to dominate high-purity nitrogen generation for electronics manufacturing. Cabot Corporation anchors North American supply through specialized pellet production for pressure swing adsorption units. Zeochem AG differentiates via Swiss-engineered bead formulations targeting medical oxygen concentrators.
Carbon molecular sieves are microporous carbonaceous materials engineered with pore diameters between 3 and 5 angstroms, manufactured through controlled pyrolysis of polymeric precursors such as polyacrylonitrile or phenolic resins, functioning primarily as adsorbent media for kinetic gas separation based on molecular size and shape. Pellet formulations command the largest volume share due to their structural integrity in high-pressure PSA columns, while powder grades attract emerging interest in membrane hybrid systems for hydrogen purification. Gas separation applications, particularly nitrogen generation from air, generate the dominant revenue pool, though CO2 capture installations are gaining traction as industrial emitters retrofit existing amine scrubbers with adsorption-based alternatives.
EPA emissions standards for industrial facilities in the United States are tightening allowable nitrogen oxide and volatile organic compound thresholds, directly expanding demand for on-site nitrogen generation systems employing CMS technology. REACH registration requirements in Europe mandate comprehensive substance safety documentation, elevating compliance costs for imported carbon molecular sieves while favoring established regional producers with existing dossiers. Stakeholders must monitor evolving carbon border adjustment mechanisms and their interaction with domestic clean hydrogen production subsidies, as these policy instruments will determine regional manufacturing economics and sourcing strategies for gas separation media.
Market Dynamics
The EU Green Deal's industrial decarbonization mandates are compressing adoption timelines for carbon capture applications, while nitrogen generation demand from food packaging and electronics manufacturing pulls capacity toward kinetic gas separation systems.
Growth Catalysts
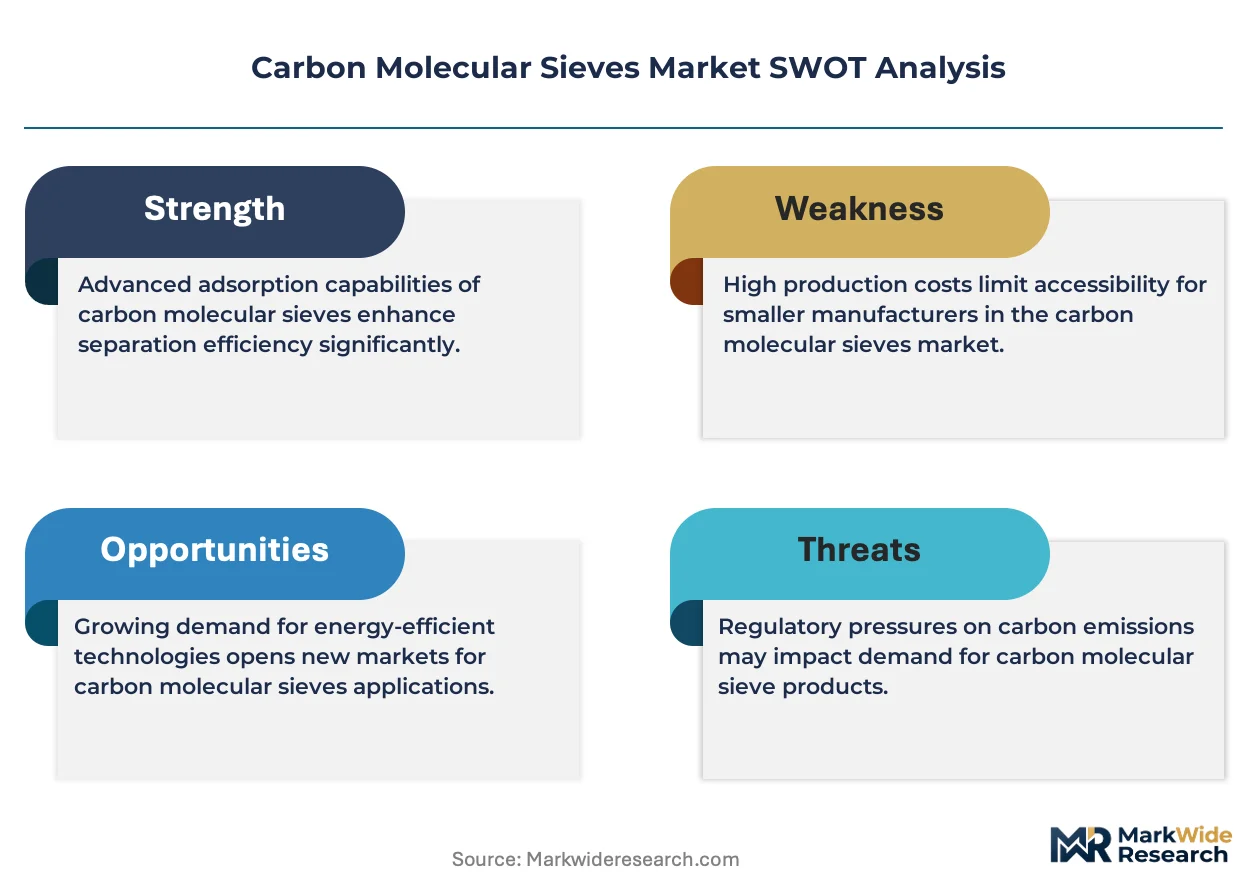
- REACH registration requirements:European chemical safety documentation elevates compliance barriers for imported carbon molecular sieves, reinforcing established regional producers with existing dossiers.
- Food packaging nitrogen flushing:Modified atmosphere packaging specifications for fresh produce and ready-to-eat meals expand on-site nitrogen generation deployments.
- Germany's chemical corridor clustering:Integrated gas separation facilities operated by BASF and Linde concentrate technical expertise and procurement volume in the Rhine-Ruhr region.
Market Restraints
- Precursor resin volatility:Polyacrylonitrile and phenolic resin feedstock prices fluctuate with petrochemical cycles, compressing margin predictability for CMS manufacturers.
- High-purity production concentration:Pharmaceutical-grade and electronics-grade sieve fabrication remains concentrated among Japanese and Swiss specialty carbon producers.
- Amine scrubber incumbent base:Existing carbon capture infrastructure using solvent-based systems creates switching friction for adsorption-based retrofits.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Production-linked incentives for advanced materials manufacturing attract greenfield CMS pellet and bead production capacity.
- Hydrogen purification membrane hybrids:Convergence of pressure swing adsorption units with polymeric membrane systems creates demand for powder-grade sieve formulations.
- US Inflation Reduction Act carbon capture credits:Section 45Q tax incentives accelerate industrial emitter retrofits with adsorption-based CO2 separation trains.
Industry Challenges
- Pyrolysis furnace operator scarcity:Controlled carbonization of polymeric precursors demands specialized thermal process engineering expertise that outpaces vocational training pipelines.
- Medical oxygen concentrator certification timelines:FDA 510(k) and EU MDR conformity assessment procedures for healthcare-grade sieves extend product commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Molecular Sieves Market |
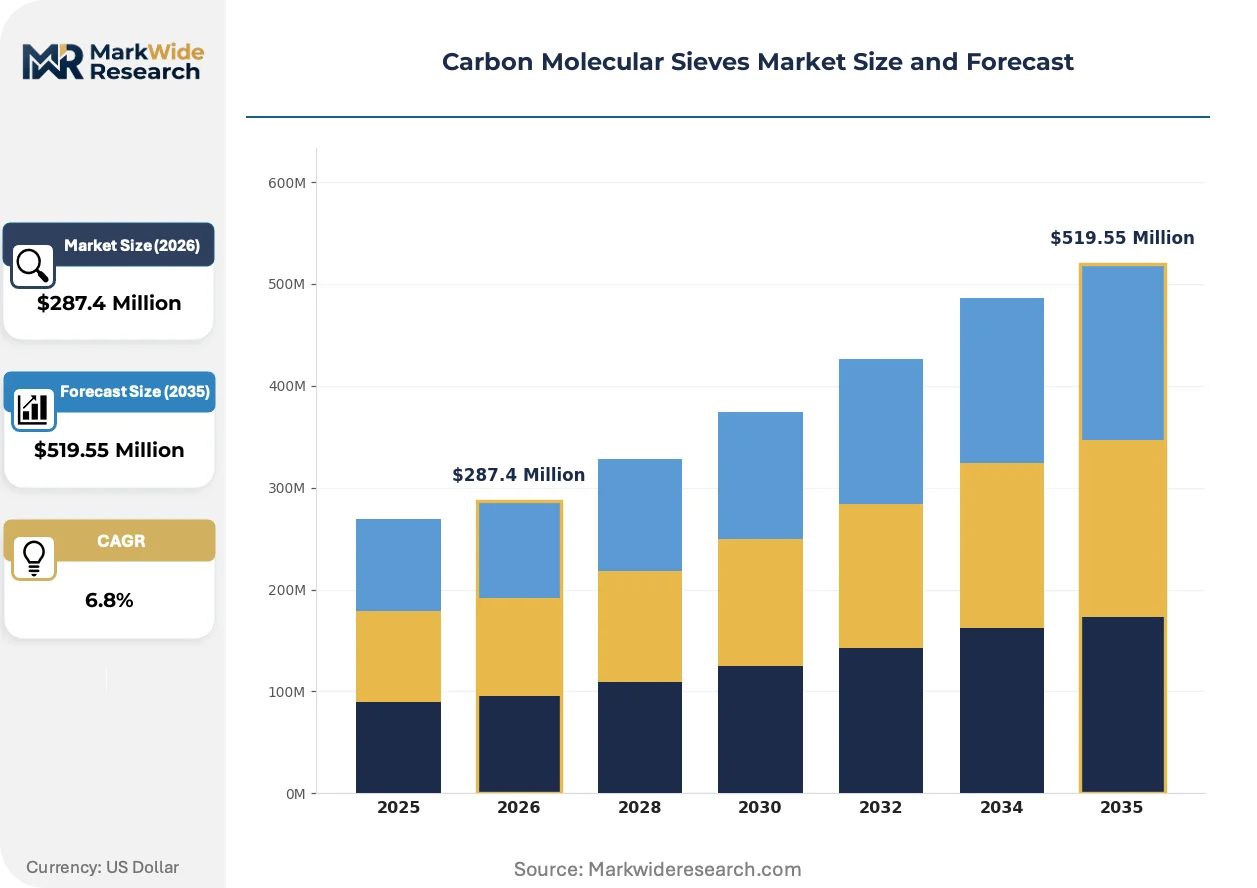
| Market Size in 2026 | $287.4 Million |
| Market Size in 2035 | $519.55 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Granules, Powder, Beads Application: Gas Separation, Air Purification, CO2 Capture, Hydrogen Production End User: Industrial, Automotive, Chemical, Energy Distribution Channel: Direct Sales, Online Retail, Distributors, Others |
| Companies Covered | Honeywell International Inc., Osaka Gas Chemicals, BASF SE, Arkema Group, Zeochem AG, Tosoh Corporation, Kuraray, Cabot Corporation, Air Products and Chemicals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Molecular Sieves Market Strategic Shifts
Automation of gas separation system commissioning and real-time performance optimization is compressing operational expertise requirements while expanding addressable end-use markets beyond traditional chemical processing.
Machine learning algorithms integrated into pressure swing adsorption control systems are automating cycle time optimization and pressure setpoint adjustments. Food packaging nitrogen generators and small-scale electronics manufacturing facilities adopt these self-tuning units fastest. The technology is automating field service dependencies and reducing the minimum viable scale for profitable on-site gas production.
The EU F-Gas Regulation phase-down of hydrofluorocarbon refrigerants is redirecting industrial cooling system maintenance toward inert gas alternatives. Cold chain logistics operators and pharmaceutical storage facilities now specify nitrogen-based cooling retrofits. Medical oxygen concentrator and electronics manufacturing segments in Germany and Switzerland respond with accelerated CMS procurement for backup nitrogen systems.
Specification-driven procurement now dominates large-volume nitrogen generation tenders, with buyers unbundling equipment supply from long-term maintenance contracts. Industrial gas distributors and original equipment manufacturers face margin compression as end-users source sieves directly from carbon specialists. This pattern concentrates most visibly in the US Gulf Coast petrochemical complex and Japan's Kansai electronics manufacturing belt.
Carbon Molecular Sieves Market Segmentation
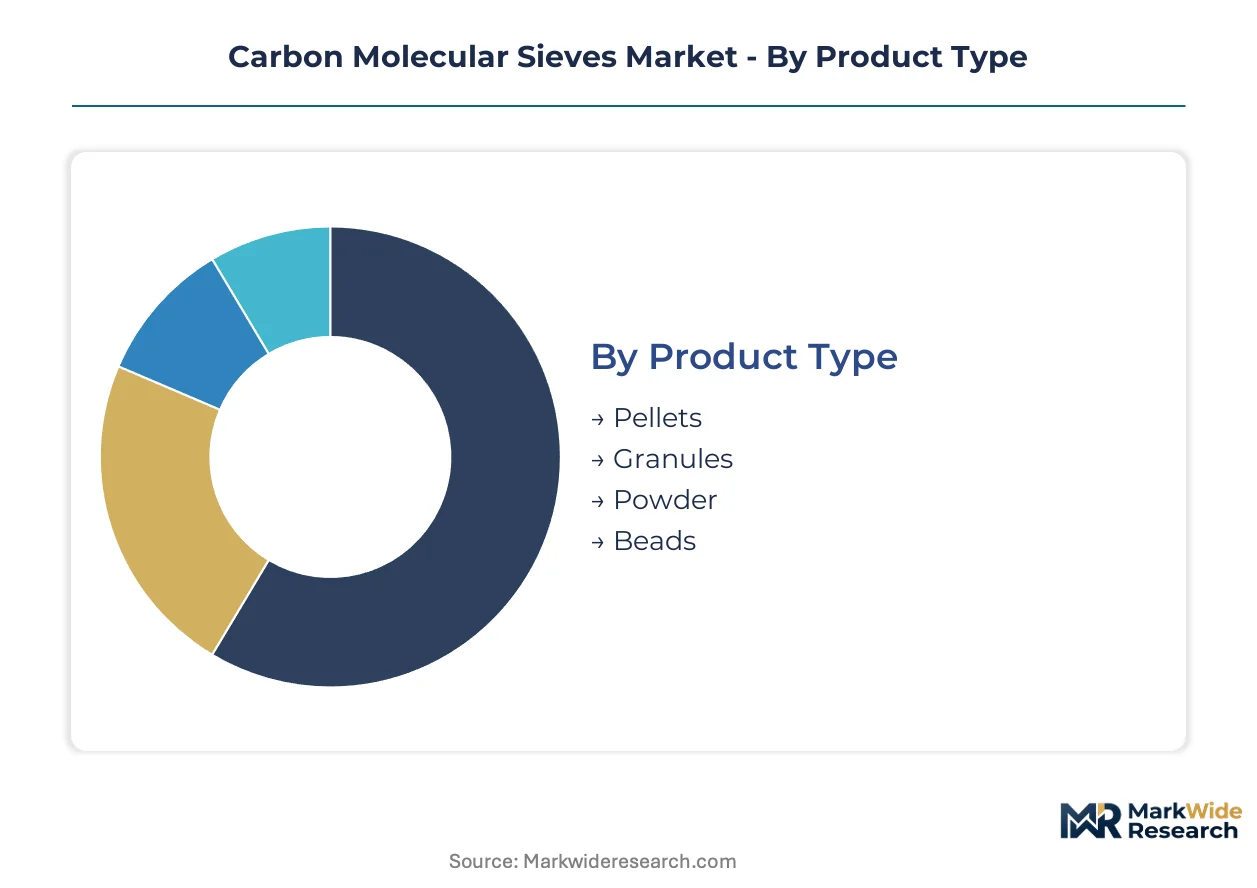
Segmentation in carbon molecular sieves reveals how manufacturing capabilities and end-use specifications create distinct procurement channels. Buyers select formulations based on pressure vessel compatibility, purity requirements, and regeneration cycle demands.
Product Type:
Supply concentration in pellet and bead production favors established carbon processors with controlled pyrolysis infrastructure, while powder grades attract emerging membrane hybrid applications.
- Pellets:Cylindrical extrusions of carbonized polymeric precursors offer structural integrity under cyclic pressure loading in PSA columns. Demand concentrates in Germany's chemical corridor where BASF and Linde operate integrated nitrogen generation facilities, driven by REACH-registered domestic supply chains that reduce import documentation burdens.
- Beads:Spherical formulations engineered through suspension polymerization yield uniform particle size distribution for medical oxygen concentrators. Swiss-engineered bead specifications from Zeochem AG dominate procurement in European healthcare device manufacturing, constrained by EU MDR certification timelines that extend commercialization cycles.
- Granules:Irregular carbonized particles serve fixed-bed adsorption systems with lower pressure requirements. Industrial air purification deployments in US Gulf Coast petrochemical complexes favor this grade for cost-sensitive bulk separations.
- Powder:Micronized carbon sieve material enables membrane casting and composite formulation. Hydrogen purification membrane hybrids in Japan's Kansai electronics belt represent the fastest-expanding demand pocket for this grade.
Today's leader: Pellets. Tomorrow's challenger: Powder.
Application:
Cost tier differentiation separates high-purity gas separation systems from commodity air treatment, with carbon capture retrofits commanding premium pricing amid policy-driven acceleration.
- Gas Separation:Kinetic discrimination of oxygen from nitrogen in pressure swing adsorption units generates the dominant revenue pool. Food packaging nitrogen flushing specifications across US, EU, and Japanese modified atmosphere packaging lines sustain volume demand.
- CO2 Capture:Adsorption-based separation trains retrofit existing industrial emitters. US Section 45Q tax credits and EU Green Deal industrial decarbonization mandates compress adoption timelines for this application.
- Air Purification:VOC and moisture removal in compressed air systems serves automotive painting and electronics manufacturing. This segment climbs the fastest as EPA emissions standards tighten allowable thresholds.
- Hydrogen Production:PSA purification of reformer output and electrolysis byproduct streams. India's PLI scheme for specialty chemicals attracts greenfield capacity targeting this emerging demand.
Volume concentration: Gas Separation. Steepest expansion trajectory: CO2 Capture.
End User:
Customer type determines specification stringency, with pharmaceutical and electronics buyers demanding pharmaceutical-grade sieves while industrial processors prioritize regeneration efficiency.
- Industrial:On-site nitrogen generation for metal heat treatment, chemical blanketing, and packaging spans the broadest specification range. Procurement concentrates through direct sales relationships with carbon specialists.
- Chemical:Process gas purification and solvent recovery applications require high-purity formulations. Osaka Gas Chemicals leverages resin precursor expertise to serve Japanese electronics chemical manufacturers.
- Energy:Natural gas processing and hydrogen infrastructure deployments. US Gulf Coast LNG facilities and German hydrogen pipeline projects drive specification development.
- Automotive:Tire inflation systems and fuel cell hydrogen purification. This segment remains nascent with concentrated pilot deployments in South Korea and Germany.
Specification intensity peaks: Chemical. Scale potential: Energy.
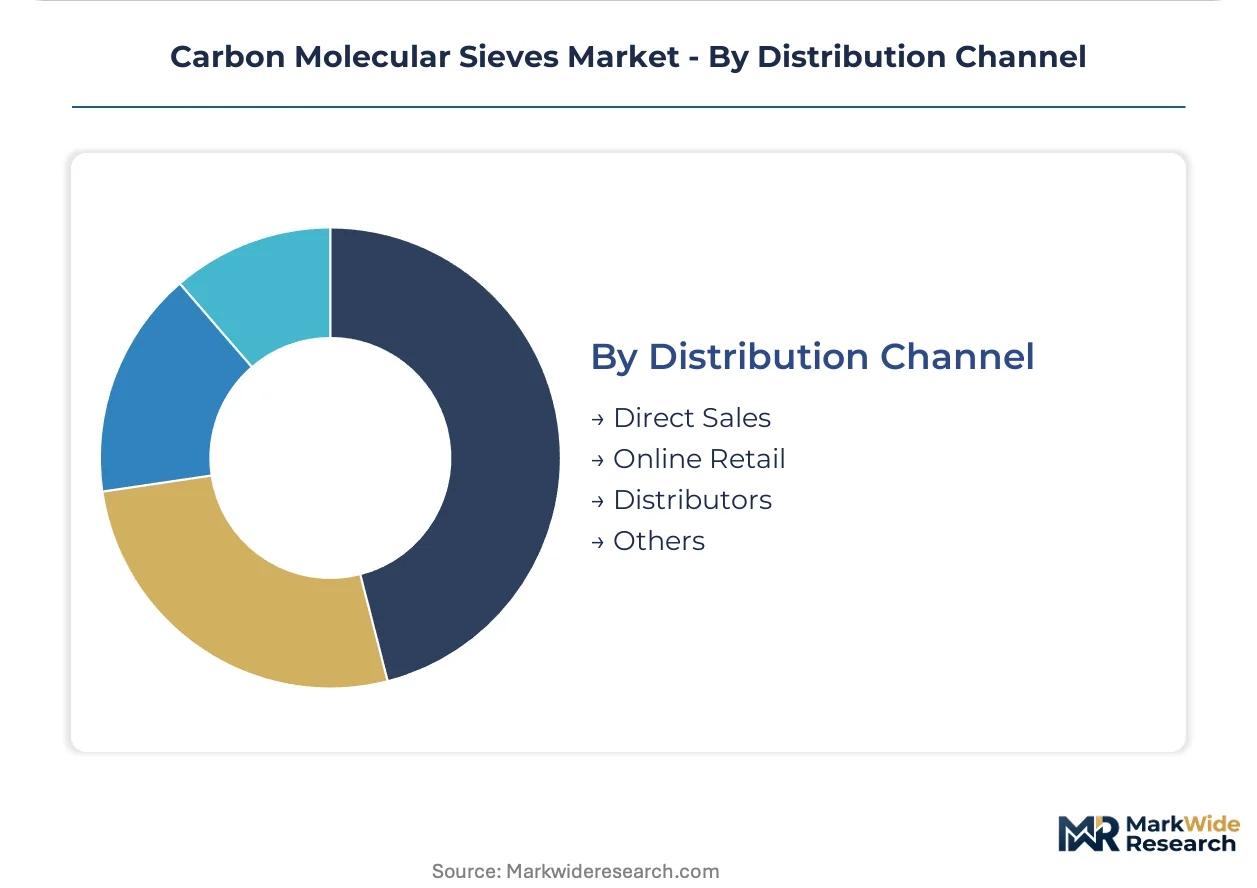
Distribution Channel:
Margin structure varies sharply across channels, with direct sales capturing high-specification contracts while distributors serve maintenance replenishment demand.
- Direct Sales:Large-volume nitrogen generation tenders unbundle equipment supply from long-term sieve supply agreements. Cabot Corporation anchors North American supply through this channel for PSA original equipment manufacturers.
- Distributors:Industrial gas distributors stock standard pellet and bead grades for field service replenishment. This channel faces margin compression as end-users source directly from carbon specialists.
- Online Retail:Small-scale nitrogen generators for food packaging and laboratory applications. Machine learning-integrated self-tuning units expand addressable markets through this channel.
- Others:Maintenance contract bundling and toll manufacturing arrangements. Regional gas separation system integrators in India's specialty chemicals corridor utilize these structures.
Revenue concentration: Direct Sales. Fastest channel shift: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates integrated gas separation infrastructure while the United States leverages tax incentives to accelerate carbon capture retrofits. Japan maintains dominance in high-purity electronics-grade sieve fabrication. India attracts greenfield capacity through production-linked incentives. China's dual carbon goals reshape industrial gas processing procurement.
Germany
BASF and Linde operate integrated nitrogen generation facilities along the Rhine-Ruhr chemical corridor. EU Green Deal industrial decarbonization mandates compress adoption timelines for carbon capture applications. REACH registration requirements elevate compliance barriers for imported sieves, reinforcing domestic producers with existing dossiers in the North Rhine-Westphalia cluster.
United States
EPA emissions standards tighten allowable nitrogen oxide thresholds for industrial facilities across the Gulf Coast petrochemical complex. Section 45Q tax credits under the Inflation Reduction Act accelerate adsorption-based CO2 separation train deployments. Houston-area nitrogen generation system integrators source pellets directly from carbon specialists, bypassing traditional distributor channels.
Japan
Electronics manufacturers in the Kansai belt demand pharmaceutical-grade sieves for ultra-high-purity nitrogen generation. METI industrial policy supports advanced materials supply chain security. Osaka Gas Chemicals leverages resin precursor expertise to serve domestic semiconductor chemical producers concentrated in the Osaka-Kyoto corridor.
India
Specialty chemicals manufacturers in Gujarat and Maharashtra expand on-site gas separation capacity for pharmaceutical and agrochemical processing. PLI scheme incentives for advanced materials manufacturing attract greenfield pellet and bead production investments. Mumbai-Pune industrial corridor gas distributors face margin compression as end-users establish direct procurement relationships.
China
Dual carbon goals drive retrofit demand at steel and cement facilities in the Yangtze River Delta. MEE emissions enforcement tightens allowable industrial pollutant discharge standards. Shanghai-area hydrogen infrastructure projects specify powder-grade sieve formulations for membrane hybrid purification systems.
Carbon Molecular Sieves Market Competitive Environment
Top-tier vendors anchor high-purity nitrogen generation for electronics and pharmaceutical applications, while mid-scale fabricators serve industrial PSA equipment OEMs. The vendor base stratifies across three strategic archetypes: resin precursor specialists, integrated carbon processors, and gas separation system integrators. M&A activity concentrates on backward integration into polymeric precursor supply. Technology licensing agreements expand geographic reach without capital-intensive greenfield construction.
Within the resin precursor specialist tier, Osaka Gas Chemicals and Kuraray occupy positions leveraging polymer chemistry expertise into high-specification sieve fabrication. Cabot Corporation anchors North American supply through pellet production for pressure swing adsorption units. Zeochem AG exemplifies Swiss-engineered precision in bead formulations targeting medical oxygen concentrator certification requirements.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Osaka Gas Chemicals |
| BASF SE |
| Arkema Group |
| Zeochem AG |
| Tosoh Corporation |
| Kuraray |
| Cabot Corporation |
| Air Products and Chemicals, Inc. |
| Others |
Value Chain & Pricing Dynamics
Pyrolysis furnace operator scarcity in Japan's Kansai industrial belt and Germany's North Rhine-Westphalia cluster widens labor-cost differentials between pharmaceutical-grade and industrial-grade sieve production, compressing margins at the standard tier while premium formulations sustain pricing power through EU MDR and FDA certification barriers.
Pricing Analysis
Bundled equipment-plus-maintenance contracts are unbundling into separate sieve supply agreements and field service arrangements. Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and commodity-grade levels reflects certification intensity and regeneration cycle guarantees. Price differentiation stems from REACH registration dossier completeness and pyrolysis precision control. Cost compression in industrial-grade pellets is intensifying because Gulf Coast petrochemical buyers are sourcing directly from carbon specialists, bypassing distributor markups. Food packaging nitrogen generator operators show highest price sensitivity; semiconductor chemical manufacturers show lowest.
Supply Chain Analysis
Polyacrylonitrile and phenolic resin feedstock supply rests on Japanese petrochemical producers, German specialty chemical manufacturers, and US Gulf Coast polymer suppliers. Controlled pyrolysis infrastructure, precision grinding equipment, and inert atmosphere packaging constitute critical production inputs. Single-source vulnerability concentrates in high-purity resin precursor supply from Osaka-Kyoto corridor producers. Distribution runs through direct sales relationships for large-volume nitrogen generation tenders and industrial gas distributors for maintenance replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon molecular sieve production is a margin-expansion story as specification-driven procurement shifts buyer willingness-to-pay toward certified pharmaceutical-grade formulations, while automation of PSA control systems reduces field service cost-to-serve.
For Market Incumbents: Extend certification coverage into EU MDR and FDA 510(k) pathways for medical oxygen concentrator applications before Japanese resin precursor specialists backward integrate into finished sieve fabrication. Anchor position through captive pyrolysis capacity additions in India's PLI-subsidized specialty chemicals corridor. Prioritize machine learning-integrated control system partnerships that compress commissioning expertise requirements and expand addressable markets beyond traditional chemical processing. For New Entrants and Emerging Players: Enter via hydrogen purification membrane hybrid applications in China's Yangtze River Delta, where powder-grade sieve demand outpaces domestic supply capability. Target food packaging nitrogen generator retrofits for cold chain logistics operators responding to EU F-Gas Regulation phase-downs. Pursue toll manufacturing arrangements with established carbon processors to bypass capital-intensive pyrolysis furnace construction. For Investors and Strategic Acquirers: Resin precursor specialists are the most active acquirer in this space, seeking downstream integration into finished sieve fabrication. Five-to-ten year viability hinges on carbon capture retrofit acceleration under US Section 45Q and EU Green Deal mandates. Acquisition target archetype: mid-scale pellet producers with REACH-registered dossiers and established relationships with PSA original equipment manufacturers. Watch US EPA emissions standard tightening timelines as inflection indicator for on-site nitrogen generation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Precursor Supply | Osaka Gas Chemicals and Kuraray leverage polymer chemistry expertise to capture margin upstream. |
| EU MDR Certification Investment | Zeochem AG extends commercialization timelines to secure medical oxygen concentrator market positioning. |
| Machine Learning-Integrated PSA Control | Self-tuning nitrogen generators reduce field service dependencies for food packaging deployments. |
| Greenfield Capacity in India PLI Corridor | Gujarat and Maharashtra attract pellet and bead production investments for pharmaceutical processing. |
| Long-term Supply Agreement with Hydrogen Infrastructure | German pipeline projects and Shanghai-area electrolysis facilities specify powder-grade formulations. |
Study Parameters
Direct dialogue with pyrolysis furnace operators, PSA system commissioning engineers, pharmaceutical procurement managers, and industrial gas distribution channel heads grounded qualitative findings in operational reality. Secondary validation drew from ECHA REACH registration databases, EPA emissions enforcement records, SEC 10-K filings of listed carbon processors, and customs trade data tracking polyacrylonitrile precursor flows. Bottom-up triangulation across plant-level capacity assessments and top-down reconciliation against end-use demand vectors ensured methodological robustness.
Bottom-up modeling of pellet, bead, granule, and powder grade production capacity across Germany, United States, Japan, India, and China fed into top-down demand segmentation by gas separation, CO2 capture, air purification, and hydrogen production applications throughout the forecast period. CAGRs were derived from regression analysis of historical capacity utilization against policy-driven retrofit timelines and electronics manufacturing capital expenditure cycles. Industry-specific forecast inputs included EU Green Deal industrial decarbonization mandate implementation rates and US Inflation Reduction Act Section 45Q credit qualification thresholds.
Inputs from ECHA registration databases and METI industrial policy disclosures were available through the study window; gaps in private company pyrolysis yield data introduce uncertainty bands around cost curve positioning. Forecasts reflect documented assumptions regarding REACH compliance cost trajectories and resin precursor price volatility. Regulatory enforcement intensity at MEE and EPA, plus PLI scheme disbursement velocity in India, constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
6-KT Mother Liquor Market
Industrial Chemicals
Emulsifiable Metalworking Fluid Market
Industrial Chemicals
Fluidizers in Plasterboard Market
Industrial Chemicals
Glycidyl Ether Market
Industrial Chemicals
Potassium Acetate Market
Industrial Chemicals
Butadiene Extraction Market
Industrial Chemicals
Global Chemical Mechanical Planarization Market
Industrial Chemicals
Deoxidant Market
Industrial Chemicals
Singapore Sealants Market
Industrial Chemicals
2,3-Butanediol Market
Industrial Chemicals
Middle East Refrigerants Market
Industrial Chemicals
Non-Corrosive Fluxes Market
Industrial Chemicals
US Anhydrous Hydrogen Fluoride Market
Industrial Chemicals
Reconditioned Drums Market
Industrial Chemicals
Molecular Sieves Market
Industrial Chemicals
Lime Market