
 Global Water-Based Resins Market | 2026-2036
Global Water-Based Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Global Water-Based Resins Market Foresight
Market Context
The premium-coating grade segment is consolidating around high-solid acrylic and polyurethane dispersions while commodity alkyd emulsions face margin compression from Asian imports. BASF leverages its integrated monomer-to-dispersion footprint in Ludwigshafen to control feedstock quality for automotive clearcoats. Covestro AG anchors its position through backward integration into polycarbonate polyols for 2K waterborne polyurethane systems. Dow competes on scale, operating multi-kiloton emulsion plants across Texas and Michigan that supply furniture makers with vinyl acetate-ethylene copolymers.
Technical Definition and Segment Structure
Water-based resins comprise polymeric binders dispersed or dissolved in aqueous media, typically at 40-60% solids content, that form continuous protective films through coalescence or crosslinking after water evaporation. These resins serve as the primary adhesion and barrier-forming component in coatings, adhesives, and sealants where volatile organic compound emissions must meet regulatory thresholds. Acrylic dispersions lead volume due to their cost-performance balance in architectural paints, while polyurethane segments capture disproportionate margin pools from automotive and industrial maintenance specifications. Epoxy waterborne systems represent the fastest-growing chemistry as marine and protective coatings manufacturers replace solvent-borne amine-cured systems in European and East Asian shipyards.
Regulatory Frame and Outlook
REACH restricts residual monomer content and mandates Substance of Very High Concern disclosure across imported resin formulations, while EPA NESHAP standards enforce maximum achievable control technology at U.S. coatings manufacturing facilities. China's MEE enforces GB standards for VOC content in architectural coatings that effectively bar non-compliant imports from Southeast Asian suppliers. Stakeholders must monitor evolving carbon border adjustment mechanisms and bio-based content certification schemes that will reshape raw material qualification protocols and regional sourcing decisions.
Market Dynamics
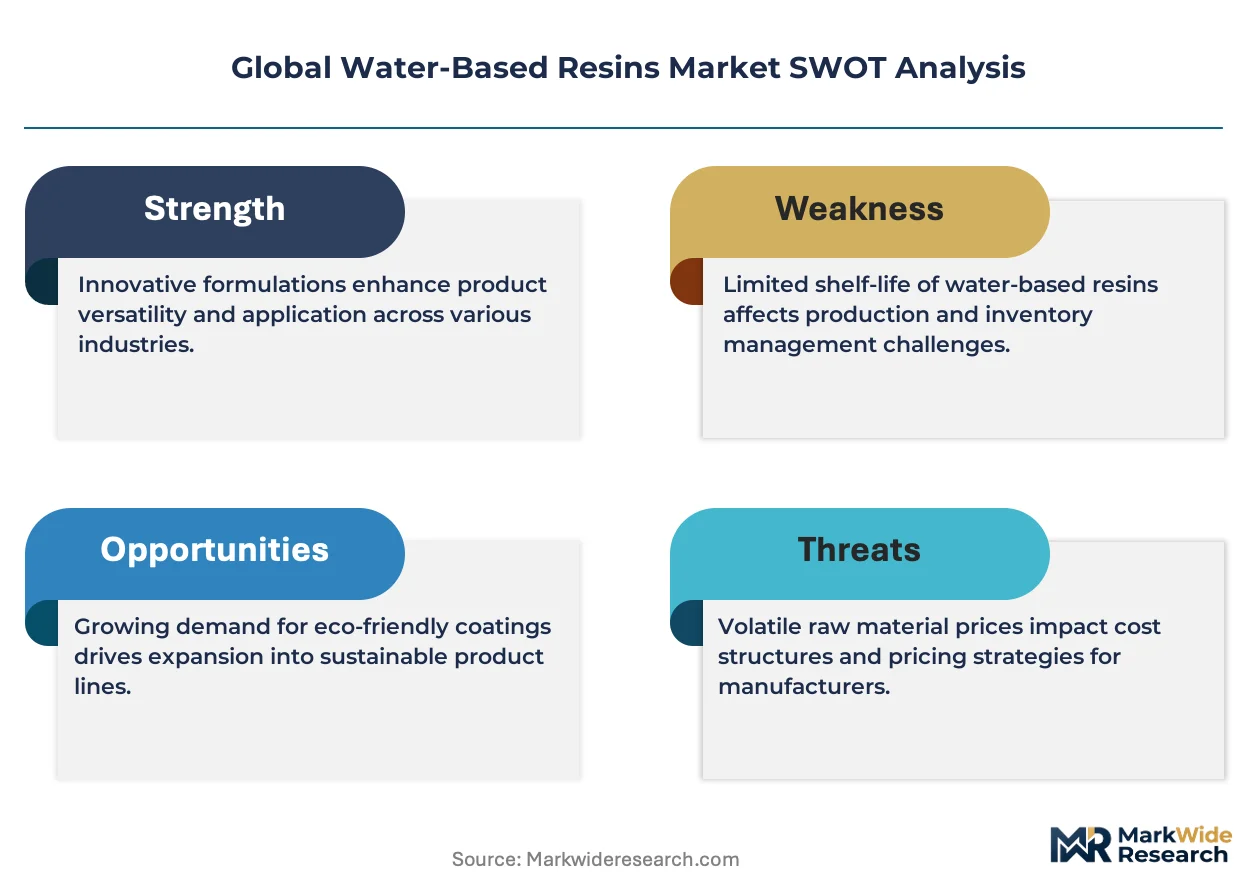
REACH and the EU Green Deal are compressing formulation windows for European coatings manufacturers, forcing simultaneous retooling of solvent-based production lines and qualification of new resin supply chains across multiple geographies.
Growth Catalysts
- REACH VOC thresholds:German and French architectural coatings producers must reformulate by 2027, pulling demand for compliant acrylic dispersions and polyurethane emulsions.
- Marine coatings electrification:East Asian shipyards in South Korea and Japan are specifying waterborne epoxy systems for newbuild vessels to meet port authority emissions protocols.
- Automotive OEM mandates:Tier-1 suppliers to German and U.S. carmakers face binding low-VOC commitments in clearcoat and primer contracts.
Market Restraints
- Propylene oxide volatility:Polyurethane dispersion producers face margin compression from petrochemical feedstock swings that aqueous systems cannot pass through contractually.
- Chinese alkyd oversupply:Commodity emulsion imports from Shandong and Jiangsu provinces depress pricing for European mid-tier producers.
- Amine blush sensitivity:Waterborne epoxy curing in humid climates creates surface defects that limit adoption in tropical marine maintenance applications.
Strategic Opportunities
- Indian architectural coatings:BIS enforcement of VOC limits in Maharashtra and Gujarat creates first-mover advantage for qualified resin suppliers.
- Bio-based content certification:EU Green Deal bioeconomy targets reward formulations with renewable carbon content, opening premium positioning for plant-derived polyols.
- Digital color-matching integration:Resin suppliers embedding spectrophotometric compatibility into dispersions capture specification control from hardware retailers.
Industry Challenges
- Formulation chemist scarcity:European coatings manufacturers compete for talent capable of balancing coalescent selection with freeze-thaw stability in hybrid systems.
- Legacy line conversion capex:Solvent-based spray booths and drying ovens require complete replacement rather than retrofit for waterborne compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Water-Based Resins Market |
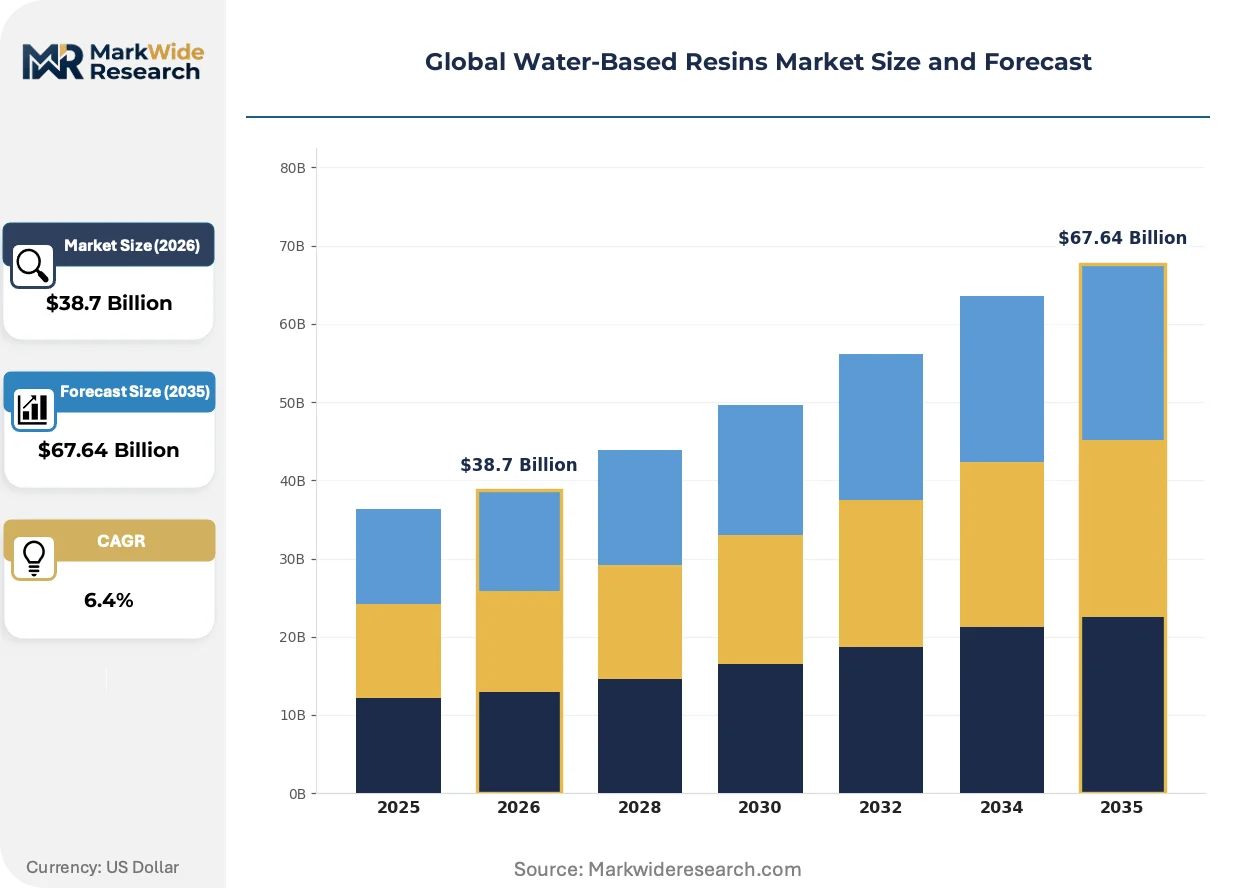
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Polyvinyl Acetate, Epoxy, Alkyd Application: Adhesives, Coatings, Textile Finishes, Construction Sealants, Paper Coatings End User Industry: Packaging Manufacturers, Furniture Makers, Paint Producers, Textile Producers, Paper Converters Packaging Type: Drums, Pails, Carboys, Bulk Containers, Jerricans |
| Companies Covered | Allnex GMBH, Covestro AG, Dow, ADEKA Corporation, DIC Corporation, BASF, Arkema, Olin Corporation, The Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Water-Based Resins Market Shifts & Advancements
Formulation science is converging with process control systems to enable real-time quality assurance and batch consistency that solvent-based lines never required.
Self-optimizing dispersion reactors are automating particle size distribution control through in-line dynamic light scattering feedback loops. German automotive coatings suppliers are retrofitting Ludwigshafen and Stuttgart facilities with these systems to reduce batch rejection rates. The technology is automating quality assurance labor out of high-volume clearcoat production while compressing qualification timelines for new resin grades.
EPA NESHAP standards for coatings manufacturing facilities are tightening residual solvent capture requirements at U.S. production sites. The rule forces capital expenditure on thermal oxidizers and carbon adsorption systems that raise fixed costs for smaller compounders. Waterborne specialty producers in Michigan and Ohio are absorbing this burden fastest, consolidating toll-manufacturing relationships with architectural brands.
Specification authority is migrating from coatings manufacturers to end-user procurement departments with embedded sustainability targets. Facility managers at German commercial construction firms and U.S. healthcare systems now mandate EPD-certified resin content in maintenance contracts. This shift concentrates volume with dispersion suppliers holding third-party verified LCA data, displacing traditional distributor-driven selection in North American and European project channels.
Global Water-Based Resins Market Segmentation
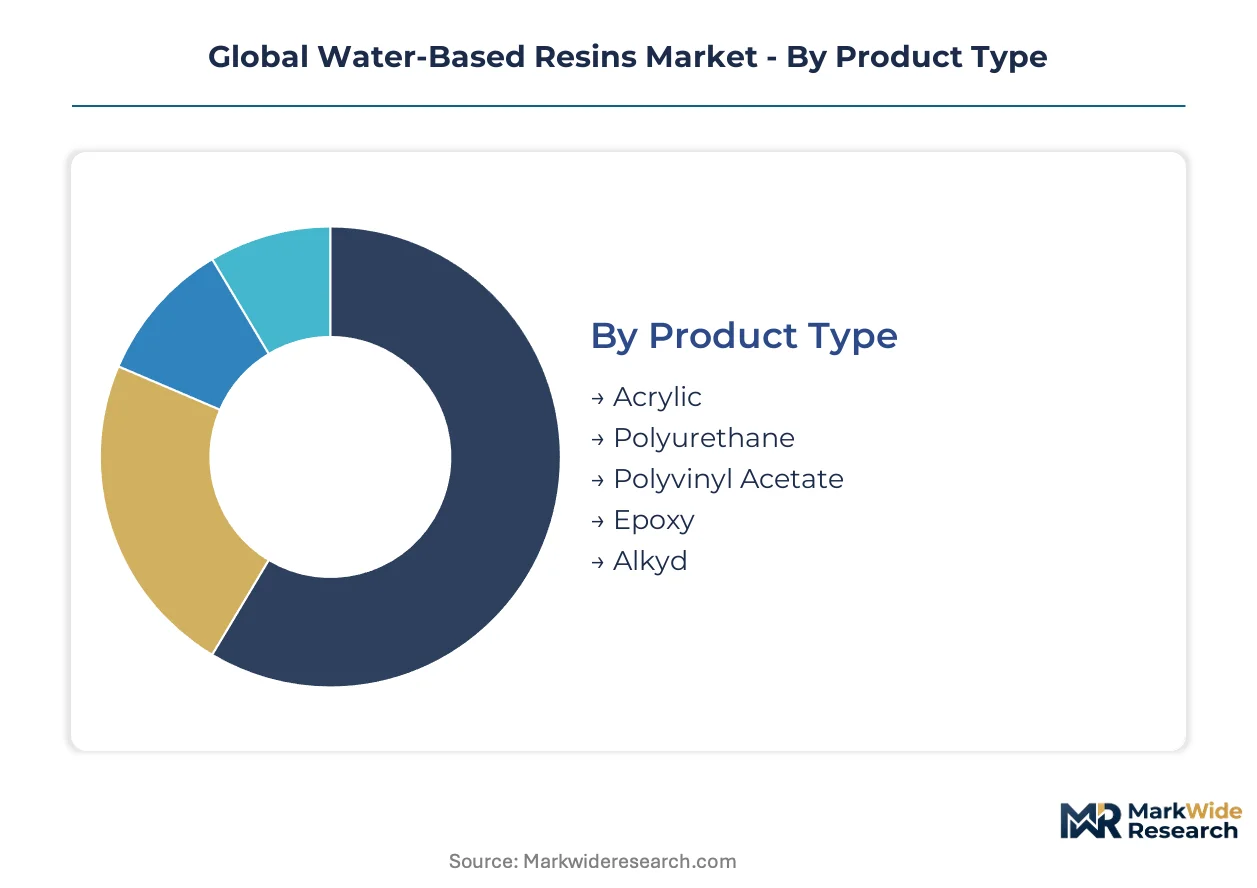
Water-based resins serve heterogeneous demand profiles that reward specialized manufacturing footprints. Each segment carries distinct formulation complexity, regulatory exposure, and margin structure that shapes supplier investment priorities.
Product Type:
Capital intensity varies sharply across chemistries, with polyurethane dispersion plants requiring multi-reactor trains and acrylic facilities scaling through continuous emulsion polymerization.
- Acrylic:These dispersions combine methacrylate and acrylate monomers in free-radical polymerization to yield 40-60% solids colloids. German and Chinese architectural coatings manufacturers specify low-MFFT grades for exterior masonry, driven by REACH VOC thresholds and GB standards compliance deadlines. Acrylic absorbs the bulk of installed capacity; epoxy is expanding most quickly.
- Polyurethane:Aliphatic and aromatic polyether or polyester polyols chain-extend with isocyanates in aqueous phase inversion processes. Automotive OEM clearcoat contracts in Stuttgart and Detroit specify 2K waterborne polyurethane for scratch resistance, though propylene oxide feedstock volatility compresses margins unpredictably.
- Polyvinyl Acetate:Vinyl acetate homopolymer and VAE copolymer emulsions bond porous substrates at low cost. Furniture assembly plants in Michigan and Guangdong specify these for woodworking adhesives under EPA NESHAP and MEE emission rules.
- Epoxy:Bisphenol-A or bisphenol-F resins disperse into water with amine-functional curing agents. South Korean and Japanese shipyards specify these for newbuild marine coatings to satisfy port authority emissions protocols.
- Alkyd:Modified drying oil fatty acids condense with polyols and dibasic acids into oxidatively curing emulsions. Shandong and Jiangsu province oversupply depresses pricing for European mid-tier producers serving decorative maintenance markets.
Acrylic and polyurethane together command premium pricing power; alkyd faces persistent margin erosion from Asian import competition.
Application:
Volume concentration tracks regulatory enforcement intensity, with coatings and adhesives absorbing compliance-driven retrofit demand across multiple geographies.
- Adhesives:Pressure-sensitive, laminating, and construction adhesives rely on tackified acrylic or VAE emulsions. Packaging manufacturers in Germany and the United States specify these for food-contact compliance under BfR and FDA indirect additive regulations.
- Coatings:Architectural, automotive, and industrial maintenance films form through coalescence or crosslinking of dispersed polymers. Paint producers across France and Italy are retrofitting solvent-based lines to meet EU Green Deal targets, pulling demand for compliant resin grades.
- Textile Finishes:Soft hand modifiers and durable press resins bind to cellulose and synthetic fibers. Textile producers in Maharashtra and Gujarat specify waterborne acrylics as BIS enforces VOC limits in Indian manufacturing zones.
- Construction Sealants:Elastomeric joint fillers accommodate substrate movement in building envelopes. German commercial construction firms now mandate EPD-certified resin content in maintenance contracts.
- Paper Coatings:Barrier and printability layers apply to food packaging and label stock. Paper converters in Ohio and Michigan absorb EPA NESHAP compliance costs through toll-manufacturing consolidation.
Coatings dominates absolute volume; textile finishes is climbing the fastest as Indian regulatory enforcement accelerates.
End User Industry:
Procurement sophistication varies by industry, with paint producers and packaging manufacturers driving specification authority toward sustainability-certified grades.
- Packaging Manufacturers:Flexible film laminators and corrugated board producers specify food-grade emulsions with residual monomer limits. These buyers prioritize migration testing documentation under EU 10/2011 and FDA 21 CFR compliance frameworks.
- Furniture Makers:Woodworking facilities in Texas and Michigan consume vinyl acetate-ethylene copolymers for edgebanding and assembly. Dow's multi-kiloton emulsion plants supply this segment through distributor relationships.
- Paint Producers:Architectural and industrial coatings compounders blend dispersions with pigments and additives. German and French producers face binding reformulation deadlines that compress qualification timelines for new resin grades.
- Textile Producers:Fabric finishers apply binders and hand modifiers to woven and knitted goods. Maharashtra and Gujarat state enforcement creates first-mover advantage for qualified resin suppliers entering Indian markets.
- Paper Converters:Coated paper and board manufacturers apply barrier layers to food-contact substrates. U.S. facilities absorb capital expenditure on thermal oxidizers to meet residual solvent capture requirements.
Paint producers absorb the bulk of formulation R&D investment; packaging manufacturers are expanding specification authority fastest through embedded sustainability targets.
Packaging Type:
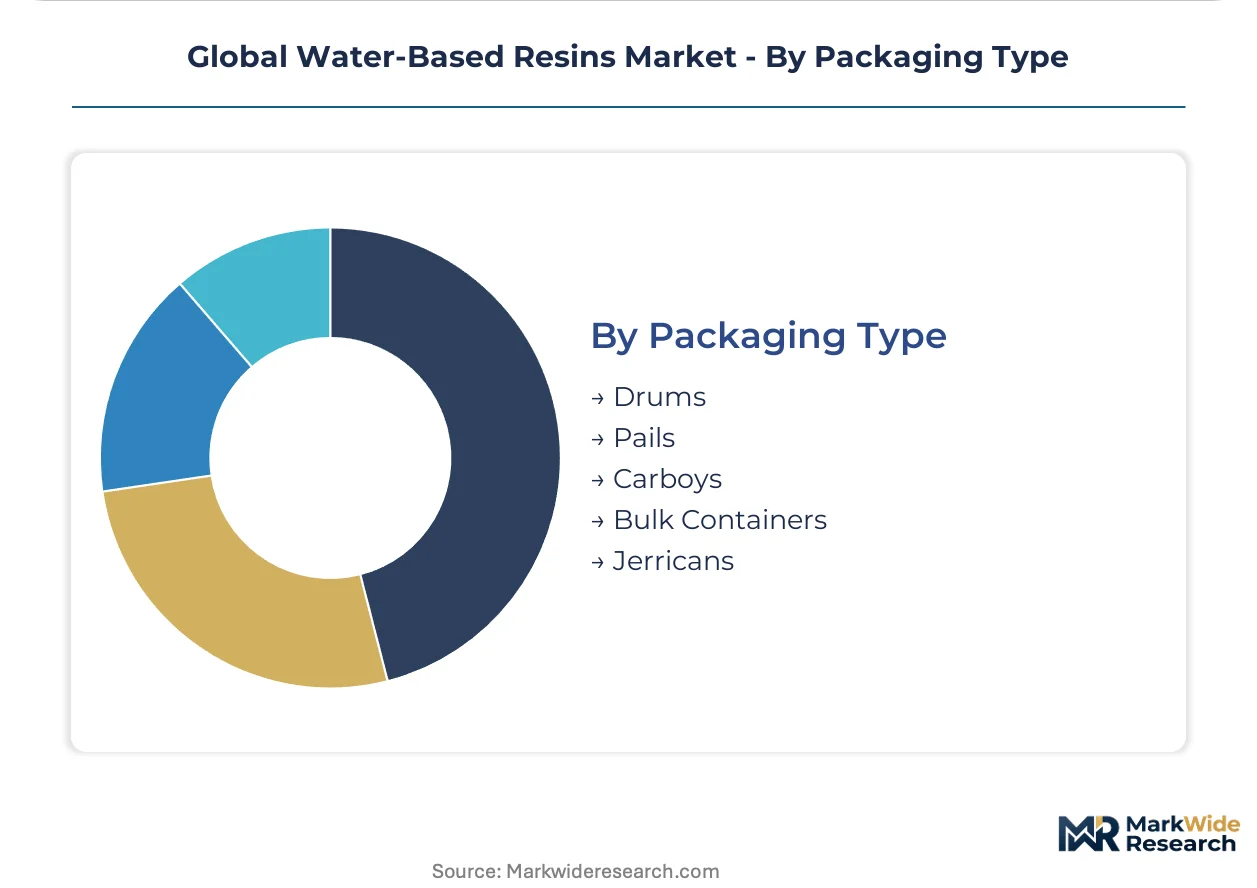
Logistics economics favor bulk for high-volume consumers, while drums and pails serve fragmented downstream compounders with diverse grade requirements.
- Drums:Steel and fiber drums contain 200-liter volumes of standardized dispersion grades. German automotive coatings suppliers receive polyurethane clearcoat resins in returnable drum programs to minimize handling contamination.
- Pails:Open-head plastic pails serve mid-volume coatings compounders with color-matching operations. Hardware retailers in North American project channels specify these for just-in-time inventory management.
- Carboys:Glass or plastic carboys contain high-purity specialty grades for laboratory and pilot-scale formulation. These packages protect against contamination for epoxy curing agent components.
- Bulk Containers:Tank trucks and ISO tanks deliver unpigmented base resins to high-volume architectural coatings plants. Covestro and BASF leverage integrated Ludwigshafen logistics for automotive clearcoat supply.
- Jerricans:Rectangular plastic containers suit adhesive and sealant compounders with limited storage footprint. Furniture assembly plants in Guangdong specify these for woodworking adhesive procurement.
Bulk containers absorb the bulk of tonnage movement; pails are expanding most quickly as distributor-driven specification fragments across smaller compounders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ludwigshafen anchors European resin manufacturing through integrated petrochemical corridors that feed dispersion plants serving automotive clearcoat specifications across the continent.
United States
Automotive OEM mandates in Detroit and Dearborn pull polyurethane dispersions for clearcoat contracts under EPA NESHAP enforcement. Michigan and Ohio coatings facilities absorb capital expenditure on thermal oxidizers to meet residual solvent capture requirements. Dow operates multi-kiloton emulsion plants across Texas supplying furniture makers with vinyl acetate-ethylene copolymers.
Germany
Architectural coatings producers in Stuttgart and Cologne face binding reformulation deadlines by 2027 under REACH VOC thresholds. The EU Green Deal compresses formulation windows, forcing simultaneous retooling of solvent-based production lines. BASF leverages its integrated Ludwigshafen footprint to control feedstock quality for automotive applications.
China
GB standards enforcement by MEE bars non-compliant resin imports from Southeast Asian suppliers in architectural coatings. Shandong and Jiangsu provinces generate commodity alkyd emulsion oversupply that depresses European mid-tier pricing. Guangdong furniture assembly plants specify VAE copolymers for woodworking adhesives under emission rules.
India
BIS enforcement of VOC limits in Maharashtra and Gujarat creates first-mover advantage for qualified resin suppliers entering Indian markets. Textile finishers in Surat and Mumbai apply waterborne acrylics as state regulators accelerate compliance timelines. The country's national environmental regulator tightens standards across manufacturing zones.
South Korea
East Asian shipyards in Busan and Ulsan specify waterborne epoxy systems for newbuild vessels to satisfy port authority emissions protocols. Marine coatings electrification drives specification shifts away from solvent-borne amine-cured systems. Korean automotive suppliers face parallel low-VOC commitments in primer and clearcoat contracts.
Global Water-Based Resins Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a market that rewards integrated feedstock control. The structure consolidates around three tiers: petrochemical majors with monomer-to-dispersion footprints, specialized polyurethane houses with polyol backward integration, and regional emulsion compounders serving fragmented adhesive demand. Strategic moves concentrate on capacity expansion in automotive corridors and qualification partnerships with coatings manufacturers facing regulatory deadlines.
Among German chemical conglomerates, BASF and Covestro AG exemplify integrated archetypes controlling upstream polyol and monomer supply. Dow represents scale-driven North American positioning through multi-site emulsion manufacturing. These three anchor competitive positioning across premium automotive and architectural segments where feedstock quality and batch consistency determine specification authority.
| Leading Market Players |
|---|
| Allnex GMBH |
| Covestro AG |
| Dow |
| ADEKA Corporation |
| DIC Corporation |
| BASF |
| Arkema |
| Olin Corporation |
| The Lubrizol Corporation |
| Others |
Supply & Pricing Matrix
Self-optimizing dispersion reactor adoption across German automotive coatings facilities simultaneously compresses batch rejection costs and concentrates specification authority with resin suppliers holding real-time quality assurance capabilities. This technology shift feeds back into supply chain restructuring as smaller compounders lose volume access to tier-1 clearcoat contracts.
Pricing Analysis
Automotive OEM clearcoat performance anchors value-based pricing for polyurethane dispersions, with scratch resistance and weatherability metrics determining contract premiums. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified automotive grades from commodity architectural emulsions and oversupplied alkyd imports. Cost compression in commodity alkyd segments is intensifying because Shandong and Jiangsu province oversupply depresses spot pricing. Mid-tier European decorative coatings producers exhibit highest price sensitivity, while German automotive suppliers prioritize batch consistency over unit cost.
Supply Chain Analysis
Propylene oxide supply rests on integrated petrochemical corridors in Germany, the United States, and China that feed polyurethane dispersion plants. Aqueous resin manufacturing draws from acrylic monomer, aliphatic polyol, and amine curing agent feedstocks with divergent geographic sourcing patterns. Single-source vulnerability concentrates in specialty amine hardeners for waterborne epoxy systems serving East Asian shipyards. Distribution runs through bulk tanker deliveries to high-volume architectural coatings plants, supplemented by drum and pail shipments to fragmented adhesive compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH VOC thresholds and the EU Green Deal have erected a cost-of-compliance barrier that favors incumbent resin suppliers with qualified formulation libraries and integrated monomer access.
For Market Incumbents: Lock in long-term offtake agreements with German and French architectural coatings producers facing binding reformulation deadlines. Deepen backward integration into polycarbonate polyols to defend margin position against propylene oxide feedstock volatility threatening polyurethane dispersion profitability.
For New Entrants and Emerging Players: Indian textile finishers in Surat and Mumbai represent an underserved buyer archetype as BIS enforcement accelerates VOC compliance timelines. Capture first-mover advantage through bio-based acrylic dispersions certified under EU Green Deal bioeconomy targets, leveraging plant-derived polyol positioning to command premium specification.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap dispersion specialists with automotive clearcoat qualifications and captive polyol supply. Long-term viability favors producers with integrated Ludwigshafen-scale manufacturing footprints and third-party verified LCA data. Watch for carbon border adjustment mechanism implementation as inflection indicator for raw material qualification protocol shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyols | Covestro's captive polycarbonate polyol supply secures 2K polyurethane system margins against feedstock volatility. |
| Long-term Supply Agreement | BASF leverages Ludwigshafen integration to lock in automotive clearcoat contracts with Stuttgart OEMs. |
| Green Manufacturing Transition | Bio-based content certification opens premium positioning for plant-derived dispersions under EU Green Deal targets. |
| Capacity Expansion | Dow's multi-kiloton Texas emulsion plants capture furniture adhesive volume under EPA NESHAP enforcement. |
| Joint Venture | Regional toll-manufacturing partnerships consolidate fragmented architectural coatings supply in Michigan and Ohio. |
Research Methodology
Independent corroboration across coatings formulators, automotive procurement leads, and petrochemical plant managers underwrites the qualitative findings presented in this study. Primary fieldwork with technical R&D directors at dispersion manufacturers, distribution channel partners serving adhesive compounders, and regulatory affairs specialists navigating REACH compliance was validated against customs and trade data, SEC 10-K filings from integrated chemical majors, and Cefic industry reports. Bottom-up resin grade volume estimates triangulate against top-down coatings production statistics.
Rate-of-change decomposition across the analysis window separates volume growth from mix shift toward higher-value polyurethane and epoxy chemistries. The forecast framework models grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs were derived through iterative convergence of demand-side retrofit timelines and supply-side capacity expansion announcements. Feedstock cost trajectories and regulatory enforcement intensity curves serve as industry-specific forecast inputs.
Revisions become necessary when carbon border adjustment mechanisms, bio-based certification scheme revisions, or propylene oxide supply disruptions materialize. Forecasts reflect assumptions regarding REACH timeline adherence and MEE enforcement consistency. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
North America Polypropylene Copolymer Market
Polymers & Resins
Organosilicon Polymers (Polysiloxane) Market
Polymers & Resins
High Density Polyethylene (HDPE) Market
Polymers & Resins
N-Vinylformamide Market
Polymers & Resins
United States Polymer Emulsion Market
Polymers & Resins
Bio-Based PU Market
Polymers & Resins
South America Polyvinyl Chloride (PVC) Market
Polymers & Resins
Vinyl Acetate Ethylene Copolymer Powder Market
Polymers & Resins
Middle-East and Africa Fluoropolymers Market
Polymers & Resins
Poly (1-Decene) Market
Polymers & Resins
Welan Gum Market
Polymers & Resins
Polymer Foam Market
Polymers & Resins
Middle East Fluoropolymer Market
Polymers & Resins
Global Polyethylene (PE) Foam Market
Polymers & Resins
PP Homopolymer Market
Polymers & Resins
Polybutene-1 Market