
 Global Resin Market | 2026-2036
Global Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Resin Market Outlook
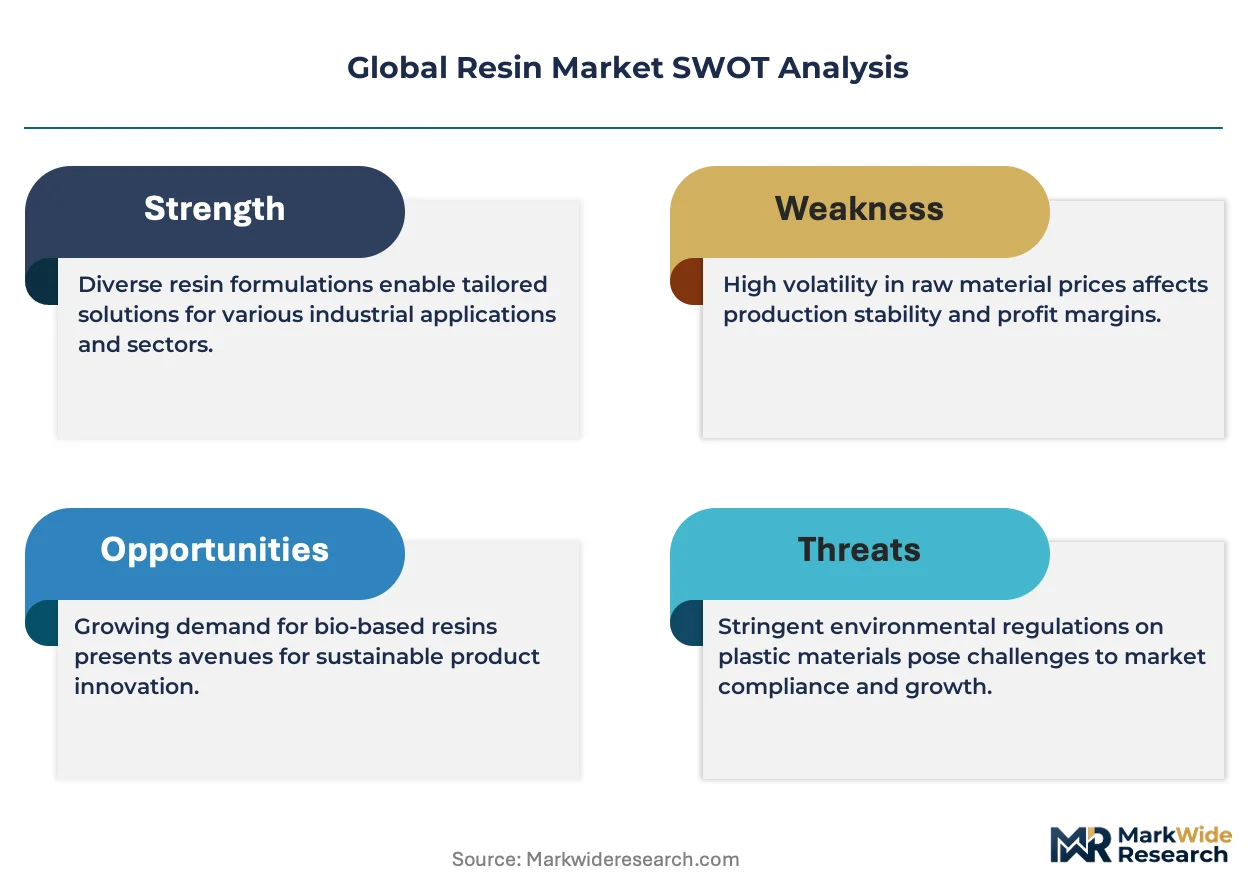
Modular resin formulations is pivoting buyer choice away from one-size-fits-all grades toward application-specific bundles that combine base polymers with curated additives and curing agents. BASF SE leverages its integrated Verbund sites to sustain cost advantages across epoxy and polyurethane value chains. DuPont anchors its position in high-performance acrylic resins for electronics and transportation coatings. SABIC competes through petrochemical feedstock control and scale in polyethylene terephthalate and polyolefin derivatives.
Resins comprise synthetic or naturally derived polymerizable substances that harden through cross-linking reactions, thermal curing, or catalytic activation, typically exhibiting viscosity ranges from water-thin liquids to high-solid pastes depending on molecular weight and additive loading. Their primary commercial purpose centers on binding, coating, encapsulating, or reinforcing substrates across manufacturing industries. Polyester resins dominate volume in marine and construction composites where cost sensitivity outweighs performance premiums, while epoxy resins command margin pools in electronics encapsulation and aerospace adhesives where thermal stability and dielectric properties justify higher pricing. Polyurethane resins extend across flexible and rigid foam applications, with fastest expansion occurring in automotive seating and insulation sealants as OEMs pursue weight reduction targets.
REACH in Europe restricts phthalate plasticizers and certain isocyanates in consumer-facing applications, while China's MEE enforces dual carbon caps on coal-to-chemical complexes that supply aromatic feedstocks. The EPA in the United States regulates volatile organic compound emissions from coatings and adhesive formulations, pushing manufacturers toward waterborne and powder resin technologies. Stakeholders must monitor regulatory divergence across these jurisdictions to determine where reformulation investments will yield durable market access versus stranded product registrations.
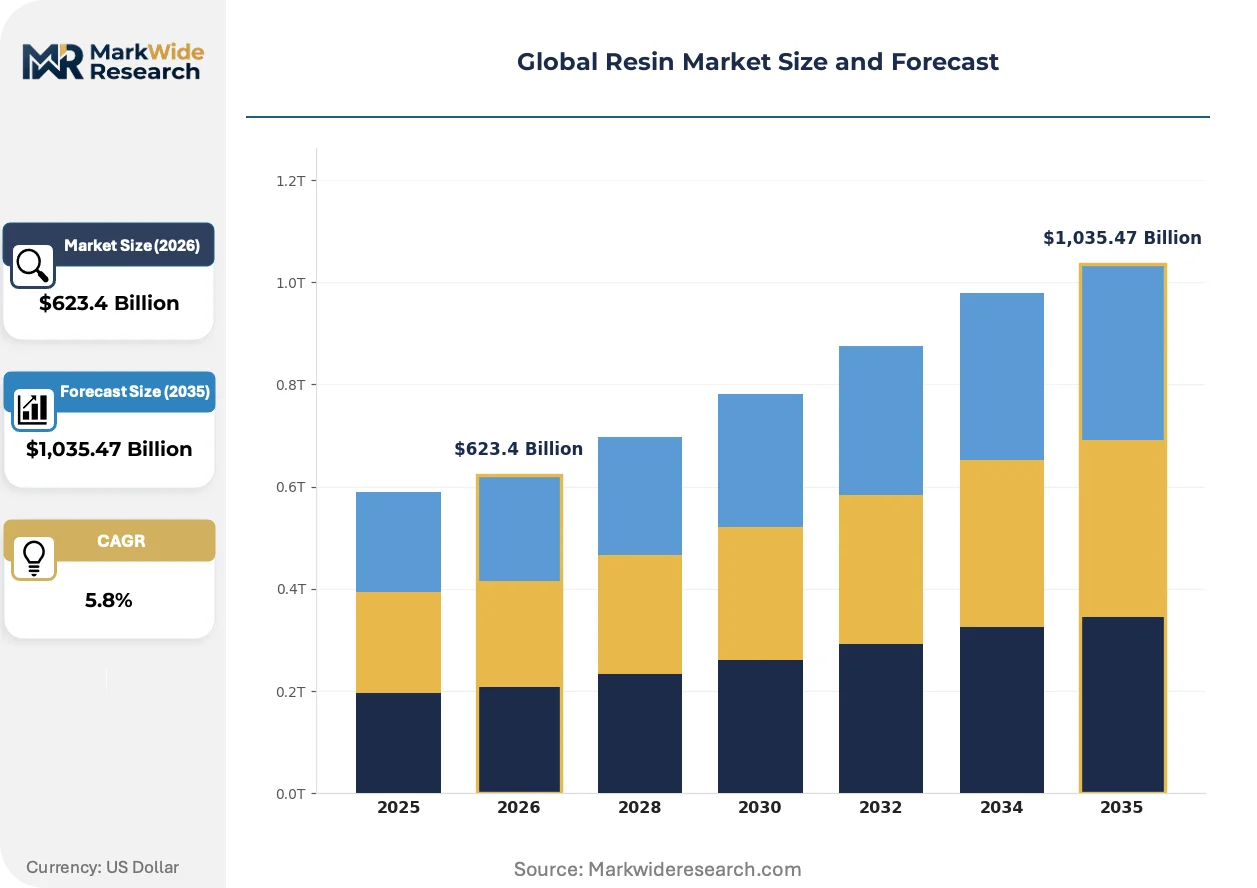
Market Dynamics
Automotive lightweighting mandates and China's dual carbon caps are compressing feedstock availability while simultaneously accelerating demand for high-performance thermosets in electric vehicle battery enclosures and structural composites.
Growth Catalysts
- Automotive electrification:Battery pack manufacturers specify flame-retardant epoxy formulations for thermal runaway protection, pulling resin volumes into EV supply chains faster than conventional ICE applications.
- REACH phthalate restrictions:ECHA's ongoing plasticizer bans in consumer goods force reformulation toward bio-based alternatives, expanding addressable market for non-phthalate polyester and polyurethane systems.
- Wind turbine blade scaling:Offshore wind OEMs in Germany and Denmark specify longer glass-reinforced epoxy blades, concentrating resin demand among certified aerospace-grade suppliers.
Market Restraints
- Aromatic feedstock concentration:China's MEE carbon caps on coal-to-chemical complexes tighten benzene and xylene availability, transmitting volatility into unsaturated polyester and epoxy resin input costs.
- Isocyanate supply oligopoly:Three producers control over 80% of global MDI capacity, exposing polyurethane formulators to rationing risk during force majeure events.
- Recyclability ceiling:Thermoset cross-linking chemistry prevents melt reprocessing, blocking circular economy claims that brand owners increasingly require for ESG compliance.
Strategic Opportunities
- India's PLI scheme for chemicals:Domestic manufacturing incentives attract epoxy and phenolic resin investments to serve automotive and electronics clusters in Gujarat and Maharashtra.
- Waterborne coating conversion:EPA VOC regulations push architectural and industrial coatings toward emulsion-based acrylics, opening formulation partnerships between resin houses and regional paint distributors.
- Digital twin integration:Convergence of materials informatics with curing simulation software enables predictive formulation design, compressing R&D cycles for custom resin development.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in rheology control and additive synergy is concentrating at integrated majors, constraining mid-tier compounders' innovation velocity.
- Multi-jurisdiction registration burden:Separate REACH, EPA TSCA, and China MEE new chemical notifications extend product launch timelines by 18-36 months for novel bio-based monomers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Resin Market |
| Market Size in 2026 | $623.4 Billion |
| Market Size in 2035 | $1,035.47 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Epoxy, Polyurethane, Acrylic Application: Coatings, Adhesives, Composites, Sealants End User: Automotive, Construction, Electronics, Consumer Goods Form: Liquid, Solid, Powder, Gel |
| Companies Covered | BASF SE, DuPont, Arkema, LyondellBasell, INEOS Holdings Ltd., SABIC, Mitsui Chemicals, Hexion, Toray Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Resin Market Strategic Shifts
Resin markets are fragmenting along performance tiers as application-specific bundles displace commodity grades, with formulation chemistry and digital specification tools determining supplier selection.
Bio-epoxy systems derived from lignin and plant-based phenols are unifying sustainability credentials with processing characteristics that match petroleum-derived equivalents. Furniture and flooring manufacturers in Western Europe specify these grades for LEED certification compliance. This unification is compressing the green premium that bio-based resins previously commanded, forcing conventional producers to accelerate their own biorefinery partnerships or absorb margin erosion.
REACH authorization requirements for diisocyanates now mandate industrial user training and exposure monitoring across EU member states. Coating and adhesive formulators face reformulation deadlines or costly compliance infrastructure. Automotive seating suppliers in Germany and Czechia are responding fastest, shifting procurement toward pre-polymer systems with reduced free isocyanate content.
Specification authority is migrating from procurement departments to application engineering teams who demand validated performance data packages. Regional distributors in China and India are building technical service capabilities to capture this decision-making shift. This pattern is most visible in electronics encapsulation, where semiconductor packaging houses now require resin suppliers to co-develop thermal management solutions rather than supply off-the-shelf grades.
Global Resin Market Segmentation
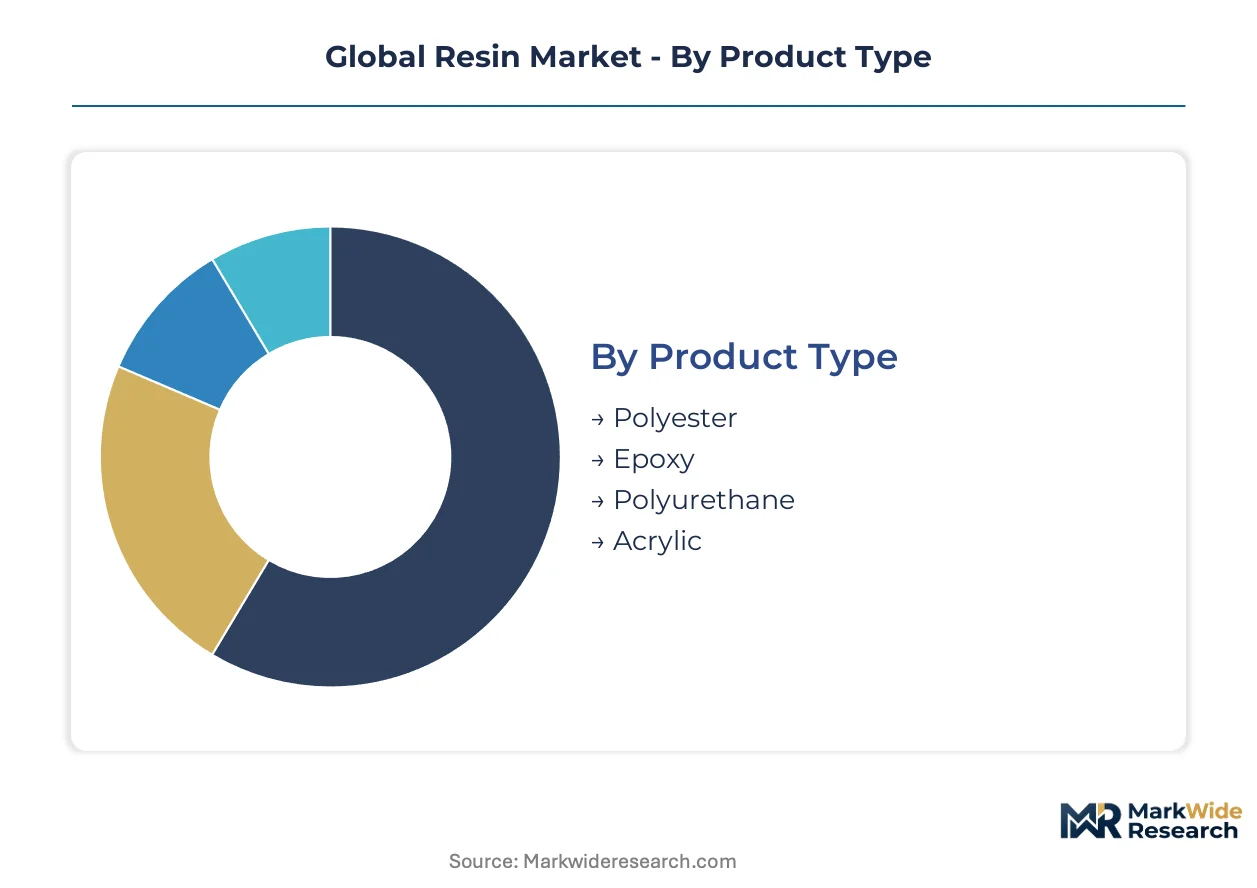
Resin markets fragment along performance-cost axes where thermoset chemistry, curing requirements, and end-use certification standards determine supplier selection. Buyers in automotive and electronics prioritize thermal stability and flame retardancy over commodity pricing, while construction and consumer goods segments optimize around application efficiency and regulatory compliance.
Product Type:
Buyers differentiate primarily by thermal performance thresholds and cross-linking density requirements rather than base polymer cost alone.
- Polyester:Unsaturated formulations dominate marine hull fabrication and construction panel lamination where styrene emission controls and open-mold processing economics outweigh premium performance needs. Demand concentrates in Gujarat shipyards and Turkish construction composites as regional manufacturers seek alternatives to epoxy cost structures.
- Epoxy:Bisphenol-A and novolac systems command specification authority in semiconductor encapsulation and aerospace structural adhesives where glass transition temperatures above 150°C and dielectric constants below 4.0 justify 3-5x commodity premiums. German automotive OEMs and South Korean battery pack manufacturers drive fastest volume expansion through thermal runaway protection mandates.
- Polyurethane:Flexible foam systems serve seating and insulation applications; rigid variants penetrate appliance and construction sealant markets under MDI supply constraints.
- Acrylic:Thermoplastic emulsions and UV-curable oligomers anchor architectural coatings and optical display films; waterborne grades gain share under EPA VOC enforcement.
Polyester leads volumes today; epoxy is gaining share fastest through electrification-driven specification upgrades.
Application:
Application selection hinges on substrate compatibility, cure speed requirements, and finished durability specifications across industrial and consumer use cases.
- Coatings:Architectural, automotive OEM, and industrial maintenance formulations represent the largest addressable application, with powder and waterborne technologies displacing solvent-borne systems under multi-jurisdiction VOC regulations. Chinese automotive plants and Indian infrastructure projects concentrate demand growth for high-solids epoxy and polyurethane topcoats.
- Adhesives:Structural bonding in electric vehicle battery modules and wind turbine blade assembly requires toughened epoxy and polyurethane systems with lap shear strengths exceeding 25 MPa and service temperatures spanning -40°C to 150°C. Danish offshore wind OEMs and Czech automotive seating suppliers specify certified grades with full traceability documentation.
- Composites:Glass- and carbon-fiber reinforced systems serve transportation and construction where specific strength targets dictate resin selection and fiber sizing compatibility.
- Sealants:Construction expansion joints and automotive seam sealing drive polyurethane and silicone-modified acrylic demand through elasticity retention and UV resistance requirements.
Coatings maintains volume leadership; adhesives demonstrates the steepest expansion trajectory through transportation electrification.
End User:
End-user procurement authority varies by sector maturity, with automotive and electronics buyers exercising the most stringent qualification protocols.
- Automotive:Lightweighting mandates and battery enclosure fire safety regulations pull high-performance thermosets into EV platforms faster than conventional ICE applications. German and Chinese OEMs specify flame-retardant epoxy prepregs for floor pans and battery housings, while seating suppliers shift toward low-free-isocyanate polyurethane systems under REACH diisocyanate authorization.
- Construction:Infrastructure rehabilitation and green building certification drive demand for low-VOC coatings and structural composite reinforcement in India and the Middle East. LEED compliance in Western Europe specifies bio-based epoxy content thresholds for flooring and panel applications.
- Electronics:Semiconductor packaging and PCB protection require ultra-pure epoxy molding compounds with ionic contamination below 10 ppm and coefficient of thermal expansion matching copper traces.
- Consumer Goods:Furniture, sporting equipment, and packaging applications prioritize cost efficiency and aesthetic finish over engineering performance specifications.
Construction leads current volumes; automotive climbs fastest through electrification-driven material substitution.
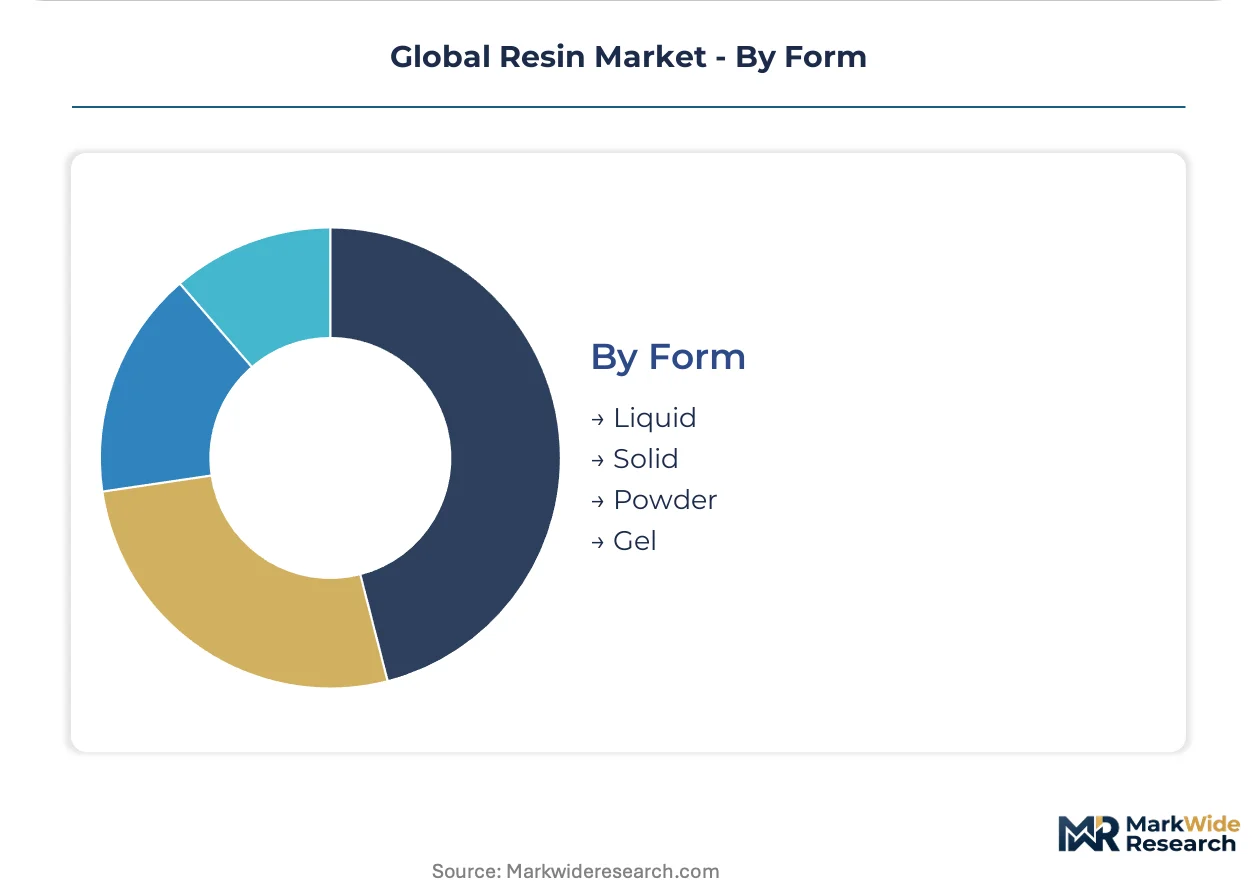
Form:
Physical form selection determines processing equipment requirements, storage logistics, and application method compatibility across manufacturing environments.
- Liquid:Low- and high-viscosity formulations serve spray coating, hand lay-up, and injection molding processes where pot life control and thixotropic behavior determine shop floor throughput. Marine and construction composites in Turkey and Southeast Asia rely heavily on promoted unsaturated polyester liquids for open-mold fabrication.
- Solid:Pelletized thermoplastics and B-stage thermoset prepregs enable automated compression molding and filament winding with precise charge weight control and minimal volatile emissions.
- Powder:Electrostatic spray and fluidized bed coating technologies eliminate solvent handling entirely, expanding fastest in Chinese appliance and Indian architectural metal finishing under tightening environmental enforcement.
- Gel:Thixotropic systems for vertical surface coating and potting applications where sag resistance and self-leveling balance govern formulation design.
Liquid formulations dominate present volumes; powder is expanding most quickly through coating technology conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic resin chemistry originated in German industrial laboratories during the early twentieth century, with Bayer and BASF scaling phenol-formaldehyde and urea-formaldehyde production for electrical insulation and molded goods. This German foundation established thermoset formulation expertise that persists in European specialty resin supply today.
China
Coal-to-chemical complexes in Shandong and Jiangsu provinces supply aromatic feedstocks for unsaturated polyester and epoxy resin production. The Ministry of Ecology and Environment enforces dual carbon caps that constrain benzene and xylene availability from coal gasification routes. Qingdao and Ningbo chemical parks concentrate epoxy resin capacity serving domestic wind turbine blade and electric vehicle battery enclosure manufacturers.
Germany
Automotive OEMs in Stuttgart and Munich specify flame-retardant epoxy prepregs for EV battery housings and structural floor pans. The European Chemicals Agency REACH authorization requirements for diisocyanates mandate industrial user training and exposure monitoring across coating and adhesive formulators. The Ruhr Valley and Ludwigshafen chemical corridors anchor polyurethane and epoxy resin production integrated with petrochemical feedstock supply.
United States
The Environmental Protection Agency regulates volatile organic compound emissions from coatings and adhesive formulations, pushing manufacturers toward waterborne and powder resin technologies. Texas and Louisiana host integrated petrochemical complexes supplying propylene and benzene derivatives for acrylic and polyester resin production. Gulf Coast resin producers serve automotive assembly plants in Tennessee and Kentucky with just-in-time thermoset deliveries.
India
The Production Linked Incentive scheme for chemicals attracts epoxy and phenolic resin investments to serve automotive and electronics clusters in Gujarat and Maharashtra. Bureau of Indian Standards certification requirements for construction materials create compliance thresholds for imported resin formulations. Mundra and Hazira industrial zones concentrate new resin compounding capacity targeting domestic composite and coating applications.
Japan
Semiconductor packaging houses in Kyushu and Chubu regions specify ultra-pure epoxy molding compounds with ionic contamination below ten parts per million. The Ministry of Economy, Trade and Industry promotes advanced materials development through technology roadmaps for high-performance thermosets. Osaka and Nagoya metropolitan areas concentrate resin formulation expertise serving electronics and automotive precision component manufacturers.
Global Resin Market Competitive Environment
The competitive structure tilts toward integrated petrochemical majors with captive feedstock supply and regional specialists with formulation customization capabilities. Three producer groups control the majority of global methylene diphenyl diisocyanate capacity, exposing polyurethane formulators to supply rationing risk. Strategic archetypes include integrated petrochemical conglomerates with Verbund site economics, specialty chemical houses with application-specific formulation libraries, and regional compounders with technical service proximity to end-users. Dominant competitive moves encompass backward integration into bio-based monomer feedstocks and partnerships with coating distributors for waterborne technology conversion.
Among German-integrated chemical conglomerates, BASF SE exemplifies the Verbund site archetype with cost advantages across epoxy and polyurethane value chains. DuPont occupies a position within the high-performance specialty tier, anchoring acrylic resin supply for electronics and transportation coatings. SABIC represents the petrochemical feedstock control archetype, leveraging scale in polyethylene terephthalate and polyolefin derivatives. These three companies illustrate the strategic positioning spectrum from commodity scale to specialty performance that defines supplier selection criteria across automotive, electronics, and construction end-uses.
| Leading Market Players |
|---|
| BASF SE |
| DuPont |
| Arkema |
| LyondellBasell |
| INEOS Holdings Ltd. |
| SABIC |
| Mitsui Chemicals |
| Hexion |
| Toray Group |
| Others |
Value Chain & Pricing Dynamics
Epoxy-to-polyester grade bifurcation separates thermal-runaway-certified formulations from open-mold commodity systems, with this divergence manifesting in both supply chain routing and pricing power concentration. Premium epoxy grades draw from Shandong and Ludwigshafen chemical parks under long-term automotive offtake agreements, while unsaturated polyester volumes trade on spot benzene pricing from Turkish and Indian compounders serving cost-sensitive marine hull fabricators.
Pricing Analysis
Three-tier pricing structure across aerospace-grade, automotive-certified, and construction-commodity levels governs resin transactions. Price differentiation hinges on REACH diisocyanate authorization compliance and glass transition temperature certification, with German automotive OEMs paying substantial premiums for thermal runaway protection documentation. Cost compression in unsaturated polyester intensifies because Chinese MEE carbon caps constrain coal-to-chemical benzene availability. Construction composite buyers in Turkey and India exhibit highest price sensitivity, while semiconductor packaging houses in Japan and South Korea prioritize ionic purity over unit economics.
Supply Chain Analysis
Reverse-logistics flows for thermoset materials remain negligible because cross-linked chemistry prevents melt reprocessing, blocking circular economy recovery pathways that brand owners increasingly demand for ESG compliance. Primary supply concentrates in China, Germany, and the United States, with benzene derivatives and MDI isocyanates anchoring input dependencies. Single-source vulnerability runs through the MDI oligopoly where three producers control majority capacity. Distribution runs through regional compounding facilities co-located with automotive and wind turbine assembly clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Resin markets function as a regulatory compounder where REACH phthalate restrictions and China's dual carbon caps are restructuring feedstock access and reformulation investment requirements. ECHA's ongoing plasticizer bans in consumer goods force systematic product redesign toward bio-based alternatives.
For Market Incumbents: Cement specification authority in EV battery enclosure applications through captive supply of flame-retardant epoxy prepregs certified above 150°C glass transition temperatures. Secure backward integration into lignin-derived bio-phenol feedstocks before green premium compression erodes specialty margins. Threats from regional Indian compounders under PLI scheme incentives require preemptive technical service investments in Gujarat and Maharashtra.
For New Entrants and Emerging Players: Direct-to-formulator digital platforms bypass established distributor markups in waterborne coating conversion segments where EPA VOC enforcement accelerates specification shifts. White-space targets include bio-based polyurethane systems for furniture and flooring manufacturers seeking LEED compliance in Western Europe. Most penetrable entry point sits with pre-polymer isocyanate systems for automotive seating suppliers responding to REACH diisocyanate authorization deadlines.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional compounders possessing technical service capabilities adjacent to Chinese wind turbine and Indian electronics manufacturing clusters. Long-term viability favors acquisition targets with formulated product libraries rather than commodity resin capacity, given thermoset recyclability ceilings and circular economy compliance pressures. Monitor MDI force majeure announcements and Chinese MEE carbon cap enforcement intensity as inflection indicators for input cost volatility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Lignin and plant-based phenol partnerships secure sustainability credentials before green premium erosion accelerates. |
| Long-Term Supply Agreement | Automotive OEM offtake contracts for flame-retardant epoxy prepregs lock in volume through EV platform ramp-ups. |
| Capacity Expansion | Indian PLI scheme incentives attract epoxy compounding investments to serve Gujarat automotive clusters. |
| Joint Venture | Regional paint distributor partnerships accelerate waterborne acrylic conversion under EPA VOC enforcement. |
| Green Manufacturing Transition | Coal-to-chemical carbon cap compliance in Shandong and Jiangsu provinces requires process reconfiguration. |
Study Parameters
Bottom-up automotive and electronics demand modeling reconciled against top-down benzene derivative and isocyanate supply tracking forms the analytical core of this study. Primary interviews with plant managers at German Verbund sites, procurement leads at South Korean battery pack manufacturers, distribution channel partners in Indian coating markets, and technical R&D directors at specialty resin houses combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and REACH registration databases. Triangulation across these sources reconciles volume estimates.
Historical trendline analysis of grade-specific pricing and specification adoption patterns anchored the projection framework across the analysis window. Segmentation dimensions modeled include resin chemistry tier, end-use industry vertical, curing system requirements, and regional production hub classification. CAGRs derived from fitted trend extrapolation adjusted for regulatory milestone impacts. Industry-specific forecast inputs encompass automotive electrification content per vehicle trajectories and wind turbine blade scaling specifications from German and Danish offshore OEMs.
The model assumes a particular technology adoption path; alternative pathways for thermoplastic resin substitution in select composite applications would alter the outlook. Forecasts reflect stated policy implementation assumptions including REACH authorization timelines and Chinese dual carbon enforcement intensity. Practitioners should monitor MDI supply rationing events, bio-epoxy cost parity achievement, and semiconductor packaging material qualification shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyolefin Foam Market
Polymers & Resins
EVA Resins and Films Market
Polymers & Resins
Copolyesters Market
Polymers & Resins
Co-Polymer Resin Market
Polymers & Resins
PA66 Market
Polymers & Resins
Middle East Engineering Plastics Market
Polymers & Resins
Ethylene-Vinyl Alcohol Copolymer (EVOH) Market
Polymers & Resins
Global Polymer Market
Polymers & Resins
Polymethacrylimide Foam Market
Polymers & Resins
Polypropylene Copolymer Market
Polymers & Resins
Polyacrylamide Market
Polymers & Resins
Plastic Resins Market
Polymers & Resins
Polypropylene Powder Market
Polymers & Resins
Optically Clear Resin Market
Polymers & Resins
North America Engineering Plastics Market
Polymers & Resins
North America Polyisoprene Market