
 Global Encapsulation Resins Market | 2026-2036
Global Encapsulation Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Global Encapsulation Resins Market Foresight
Automotive-grade thermal cycling specifications is bifurcating the competitive landscape into suppliers capable of meeting OEM validation protocols versus general industrial formulators. Henkel AG & Co. KGaA leverages its adhesive technology heritage to cross-sell encapsulation systems into powertrain electronics. Dow Inc. anchors its position through backward integration into silicone monomer production, capturing margin upstream. Shin-Etsu Chemical Co., Ltd. dominates high-purity silicone resin output for LED and photovoltaic applications across Asian manufacturing corridors.
Encapsulation resins are thermosetting polymer systems formulated to provide electrical insulation, environmental sealing, and mechanical protection for sensitive components, typically cured through thermal or UV-initiated crosslinking reactions with glass transition temperatures engineered between minus forty and plus two hundred degrees Celsius. Their primary industrial purpose centers on isolating microelectronic assemblies from moisture, thermal shock, and chemical ingress to ensure operational reliability across mission-critical applications. Epoxy resins command the largest value share due to their balanced adhesion, chemical resistance, and cost profile in printed circuit board and sensor applications. Silicone resins capture premium positioning in LED encapsulation and photovoltaic modules where optical clarity and UV stability define performance thresholds. Polyurethane resins occupy a specialized niche in flexible, low-modulus formulations for automotive sensors subject to vibration and thermal expansion mismatches.
REACH in Europe, RoHS directives, and China's GB standards collectively restrict halogenated flame retardants and heavy metal stabilizers in electronic-grade formulations, forcing reformulation investments and supply chain recertification cycles. The US EPA and FDA maintain parallel oversight for encapsulants used in medical devices and aerospace applications, adding compliance layers for cross-border suppliers. Stakeholders must monitor evolving dual carbon goals in China and the EU Green Deal's embodied carbon tracking requirements, as these frameworks will progressively favor low-VOC curing technologies and bio-based feedstock pathways over conventional petrochemical resin systems.
Market Dynamics
Semiconductor miniaturization below ten-nanometer nodes is forcing reformulation of encapsulation resins to manage heat dissipation in denser architectures, compressing traditional material specifications and elevating thermal conductivity requirements across supplier qualification protocols.
Growth Catalysts
- Automotive electrification mandates:NHTSA safety standards and EPA emissions targets in the United States are accelerating resin demand for battery management system protection in electric powertrains.
- REACH substance restrictions:ECHA's phased halogenated flame retardant bans are redirecting formulation R&D toward phosphorus-nitrogen synergist systems in European electronics supply chains.
- Photovoltaic module expansion:China's dual carbon goals are driving silicone encapsulant consumption for junction box sealing in domestic solar manufacturing clusters.
Market Restraints
- Epichlorohydrin feedstock volatility:Epoxy resin production faces margin compression from propylene-derived precursor cost swings tied to crude oil benchmarks.
- High-purity silicone concentration:Asian monomer producers control over seventy percent of semiconductor-grade silicone resin precursor supply, creating geographic single-source risk.
- Thermal cycling specification divergence:Automotive OEM validation protocols now demand five-thousand-cycle endurance testing that general industrial formulators cannot meet without capital-intensive equipment upgrades.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and PCB fabrication are creating virgin demand for imported encapsulation resin grades in Gujarat and Tamil Nadu production corridors.
- UV-LED curing convergence:Mercury-free photoinitiator systems paired with 395-nanometer LED arrays are opening energy-cured formulations for temperature-sensitive flexible substrates.
- Medical device reclassification:FDA's updated biocompatibility ISO 10993 testing pathways are streamlining approval timelines for implantable sensor encapsulants.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in thermoset rheology and filler dispersion for miniaturized electronics is concentrated among retiring technical staff in Japanese and German material science programs.
- Multi-jurisdiction certification lag:Simultaneous REACH, RoHS, and GB standard compliance testing extends product launch timelines by fourteen to eighteen months for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Encapsulation Resins Market |
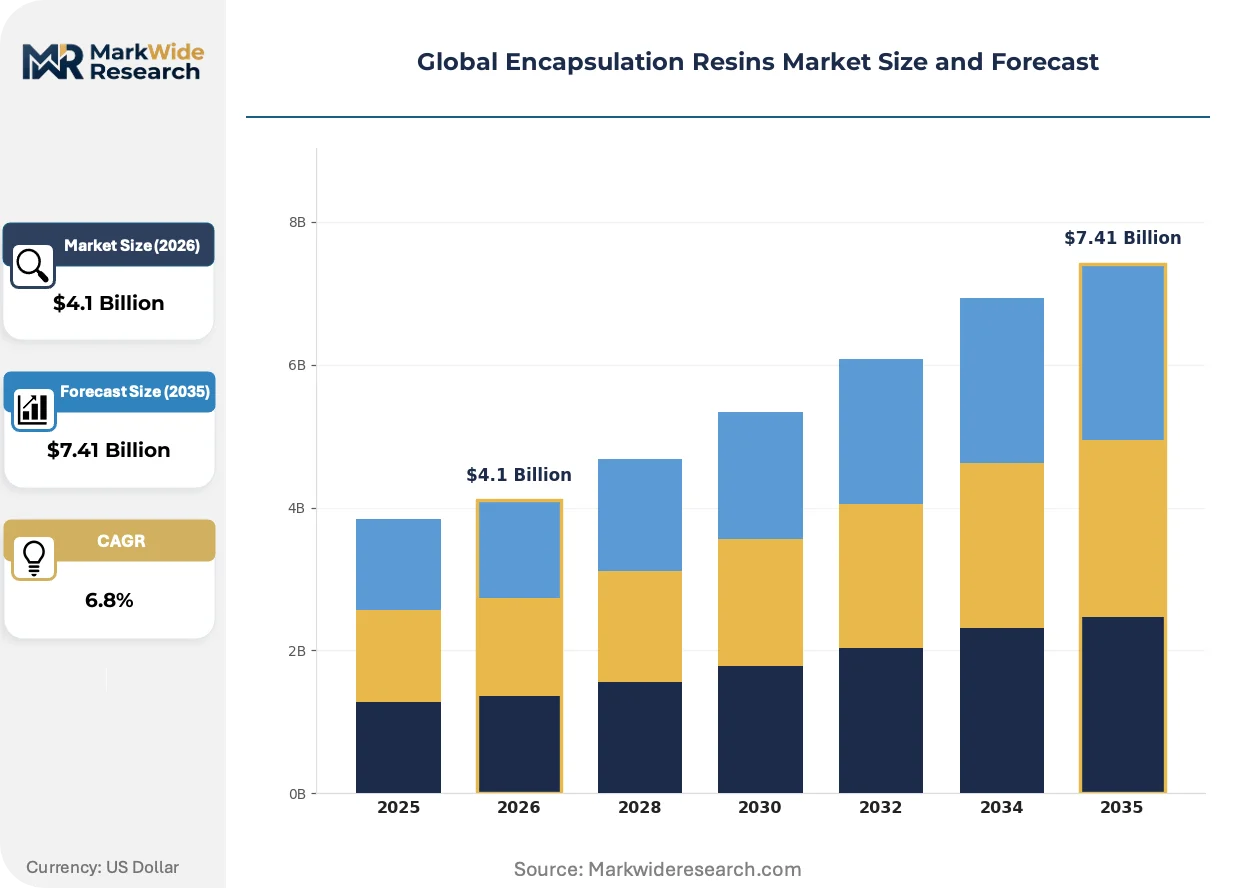
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy Resins, Silicone Resins, Polyurethane Resins, Acrylic Resins, Polyester Resins Technology: UV Curing, Thermosetting, Thermoplastic, Hot Melt, Solvent-Based End User: Electronics Manufacturers, Telecommunications Firms, Consumer Appliances, Aerospace Suppliers, Defense Contractors Application: Microelectronics Protection, LED Encapsulation, Printed Circuit Boards, Photovoltaic Modules, Automotive Sensors |
| Companies Covered | Henkel AG & Co. KGaA, Dow Inc., BASF SE, Huntsman Corporation, ELANTAS GmbH, Shin-Etsu Chemical Co., Ltd., H.B. Fuller Company, Hitachi Chemical Co., Ltd., Master Bond Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Encapsulation Resins Market Shifts & Advancements
Thermal management architectures and regulatory substance bans are jointly compressing legacy epoxy dominance while elevating silicone and hybrid material platforms in next-generation electronics protection.
Boron nitride-doped epoxy systems is fragmenting the thermal interface material landscape by delivering six-watt-per-meter-kelvin conductivity in underfill applications. Automotive power module manufacturers in Germany and Japan are qualifying these formulations for silicon carbide inverter protection. The technology is fragmenting supplier tiers between commodity epoxy blenders and specialized thermal filler compounders with dispersion process patents.
EU Green Deal embodied carbon tracking requirements are mandating lifecycle assessment disclosure for electronic-grade resin imports into European customs territories. Formulators must now document Scope 3 emissions from petrochemical feedstock extraction through crosslinking cure energy. LED encapsulant producers serving Dutch and Italian lighting OEMs are accelerating bio-based epichlorohydrin pilot programs to preempt border adjustment mechanism exposure.
Direct material qualification by tier-one automotive electronics suppliers is compressing traditional distributor channel roles in resin procurement. Bosch, Continental, and Denso technical teams now specify exact filler loadings and cure kinetics rather than accepting standard grade portfolios. This pattern is most pronounced in Bavarian and Stuttgart engineering centers where powertrain electrification programs demand application-specific validation batches rather than catalog formulations.
Global Encapsulation Resins Market Segmentation
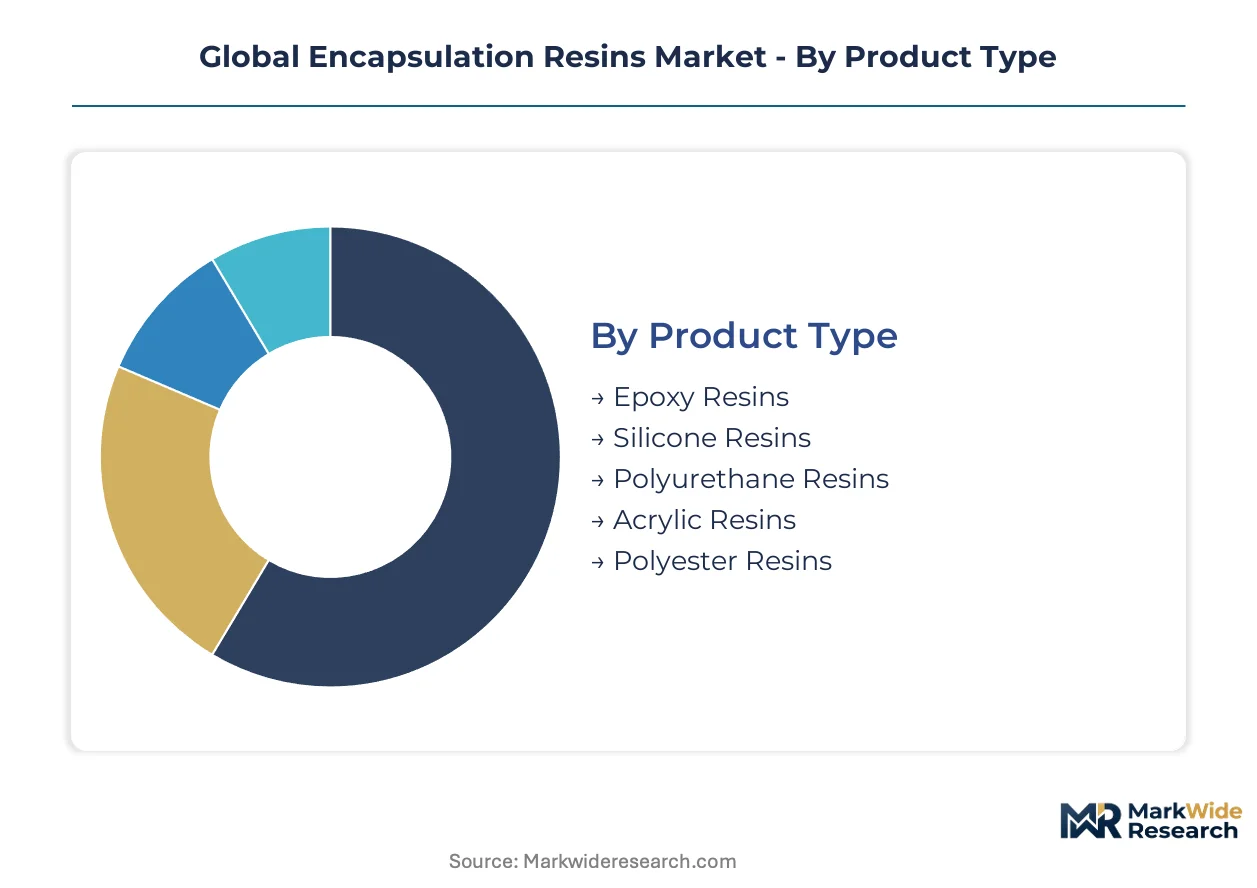
Encapsulation resin suppliers configure product portfolios around curing chemistry, thermal performance thresholds, and end-use certification requirements. Segmentation clarity determines pricing architecture and regional distribution strategies across electronics manufacturing corridors.
Product Type:
Domestic production clusters in China and Germany anchor epoxy and silicone supply, while polyurethane and specialty grades flow through export-dependent formulation networks in Japan and the United States.
- Epoxy Resins:Bisphenol-A and novolac-based thermoset systems deliver dielectric strength above fifteen kilovolts per millimeter with glass transition temperatures tunable between eighty and one hundred eighty degrees Celsius. Demand concentrates in German automotive sensor manufacturing and Chinese PCB fabrication, where REACH-compliant halogen-free formulations command price premiums over standard industrial grades.
- Silicone Resins:Dimethyl and phenyl silicone polymers provide optical clarity above ninety percent transmission in the four hundred to seven hundred nanometer range with thermal stability exceeding two hundred fifty degrees Celsius. Japanese LED encapsulant producers and Chinese photovoltaic manufacturers drive volume consumption, with high-purity semiconductor-grade material facing supply constraints from concentrated Asian monomer production.
- Polyurethane Resins:Flexible aliphatic formulations service vibration-dampening applications in automotive wheel speed sensors.
- Acrylic Resins:UV-curable systems target rapid-processing consumer electronics assembly lines in South Korean smartphone manufacturing.
- Polyester Resins:Unsaturated formulations occupy cost-sensitive industrial motor insulation segments in Indian and Brazilian manufacturing.
Epoxy resins hold the largest share; momentum sits with silicone resins.
Technology:
Cost tiers separate capital-intensive thermal curing infrastructure from lower-barrier UV and hot melt alternatives favored by contract electronics assemblers.
- UV Curing:Photoinitiator-activated systems polymerize in seconds under three hundred ninety-five nanometer LED arrays, enabling temperature-sensitive flexible substrate processing. South Korean display manufacturers and German medical device suppliers are qualifying mercury-free formulations to meet EU Green Deal embodied carbon tracking requirements.
- Thermosetting:Heat-activated crosslinking with amine or anhydride hardeners dominates high-reliability automotive and aerospace applications requiring thermal cycling endurance beyond five thousand cycles.
- Thermoplastic:Reprocessable systems service repairable industrial equipment in North American heavy machinery markets.
- Hot Melt:Solvent-free application suits high-volume consumer appliance wire bonding in Chinese and Mexican assembly plants.
- Solvent-Based:Declining share due to VOC regulations under China's MEE standards and US EPA air quality mandates.
Thermosetting technology captures the dominant volume position; UV curing systems are climbing the fastest as LED source costs decline.
End User:
Application maturity varies sharply, with automotive and defense procurement demanding eighteen-month qualification cycles versus six-month turnaround for consumer appliance specifications.
- Electronics Manufacturers:Tier-one semiconductor packaging houses in Taiwan and South Korea specify ultra-low alpha particle emission grades for advanced node protection. Procurement concentrates through direct technical qualification rather than distributor channels, with Bosch and Continental engineering teams dictating filler loadings and cure kinetics for powertrain modules.
- Telecommunications Firms:Base station and fiber optic component producers in Finland and Sweden prioritize moisture resistance for Nordic climate exposure.
- Consumer Appliances:White goods assemblers in China and Turkey drive high-volume, specification-tolerant demand.
- Aerospace Suppliers:FAA and EASA flame-smoke-toxicity certification requirements restrict qualified suppliers to specialized formulators with NADCAP accreditation.
- Defense Contractors:ITAR and national security supply chain restrictions fragment procurement across domestic-only sources in the United States, United Kingdom, and France.
Electronics manufacturers hold the largest share; defense contractors represent the steepest expansion trajectory as sovereign chip protection programs accelerate.
Application:
Volume concentration tracks semiconductor fabrication geography, while premium positioning follows LED and photovoltaic manufacturing technology leadership.
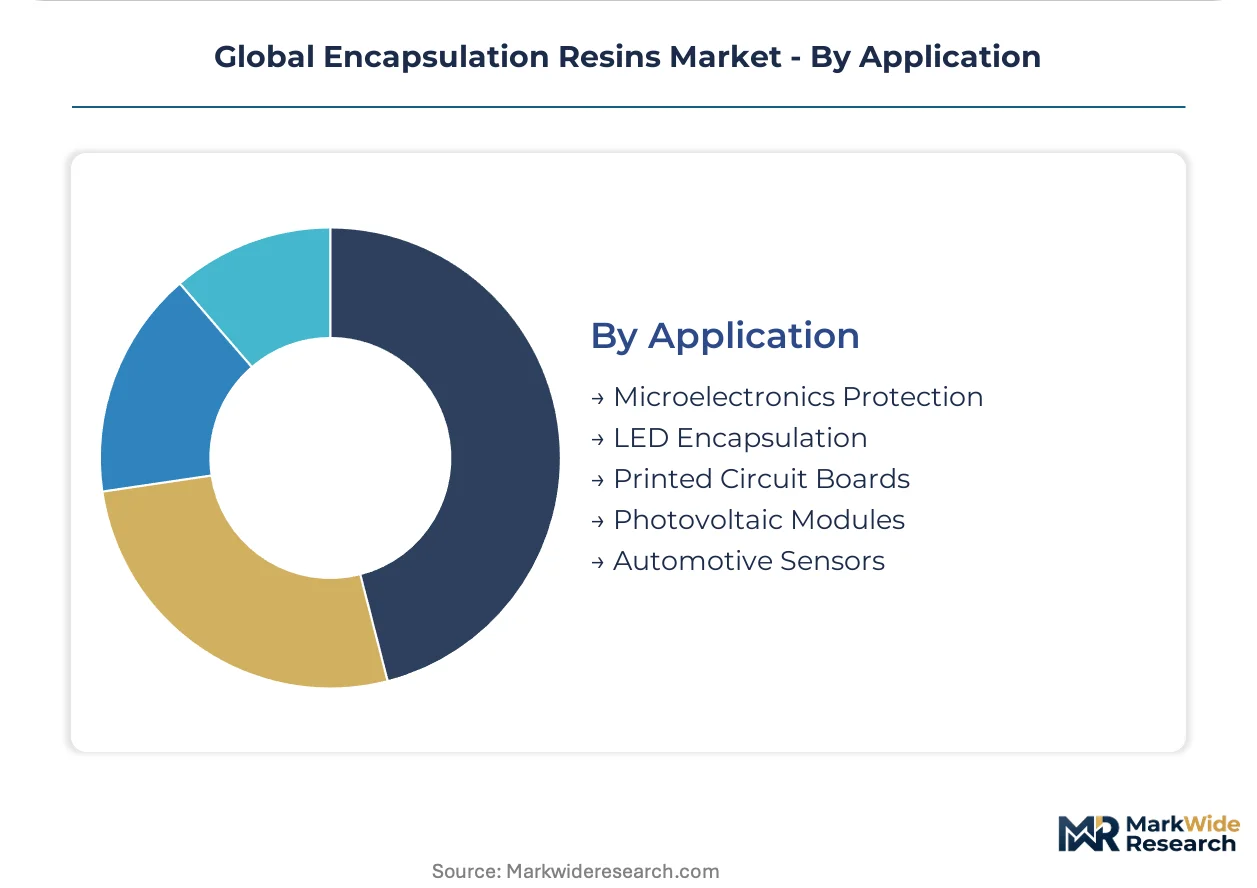
- Microelectronics Protection:Underfill and dam-and-fill formulations for flip-chip and wafer-level packaging require matched coefficient of thermal expansion below twenty parts per million per degree Celsius. Taiwanese OSATs and Intel's Arizona and Oregon facilities drive qualification of boron nitride-doped thermally conductive grades for ten-nanometer and below nodes.
- LED Encapsulation:High-refractive-index silicones with platinum-catalyzed addition cure chemistry dominate general lighting and automotive headlamp applications. Dutch and Italian lighting OEMs are accelerating bio-based feedstock pilots to preempt EU carbon border adjustment exposure.
- Printed Circuit Boards:Conformal coating and potting compounds service industrial control and medical device boards in German and Swiss manufacturing.
- Photovoltaic Modules:Junction box sealing and backsheet lamination in Chinese solar manufacturing clusters consume standard-grade silicone and EVA alternatives.
- Automotive Sensors:Wheel speed, pressure, and LiDAR module protection requires combined thermal shock and chemical fluid resistance validation under OEM-specific protocols.
Microelectronics protection holds the largest share; LED encapsulation is gaining share fastest as solid-state lighting penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German epoxy resin exports supply automotive sensor manufacturers across Bavaria and Stuttgart, while Chinese silicone producers feed LED encapsulant demand in Dutch and Italian lighting assembly plants.
China
Domestic PCB and LED production clusters in Guangdong and Jiangsu provinces drive volume consumption of epoxy and silicone encapsulant grades. GB standards and MEE regulations restrict halogenated flame retardants in electronic-grade formulations. Yangtze River Delta manufacturing corridors host concentrated junction box sealing operations for photovoltaic module exporters.
Germany
Automotive powertrain electrification programs in Bavaria and Baden-Württemberg demand application-specific validation batches with five-thousand-cycle thermal endurance. REACH compliance requirements tighten material specifications and phase out hazardous substances. Bosch and Continental engineering centers in Stuttgart specify exact filler loadings and cure kinetics for resin procurement.
United States
Battery management system protection for electric powertrains accelerates resin demand under NHTSA safety standards and EPA emissions targets. FDA and EPA maintain parallel oversight for medical device and aerospace encapsulants. Intel's Arizona and Oregon facilities drive qualification of thermally conductive grades for advanced semiconductor nodes.
Japan
High-purity silicone resin output for LED and photovoltaic applications concentrates among specialized formulators. METI industrial policy supports domestic material science programs training formulation chemists in thermoset rheology. Kyushu and Kanto manufacturing corridors supply Asian electronics assembly networks with semiconductor-grade encapsulants.
South Korea
Display manufacturers and smartphone assembly lines in Seoul Capital Area qualify mercury-free UV-curable formulations. MFDS and national standards govern electronic material imports for consumer electronics production. Busan-Ulsan chemical processing hubs export encapsulant precursors to Taiwanese OSAT operations.
Global Encapsulation Resins Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and certification depth. The supplier base separates into consolidated chemical conglomerates with backward integration into monomer production and specialized formulators holding NADCAP or automotive OEM validation credentials. Three archetypes dominate: integrated resin producers controlling upstream feedstock, application-specific compounders with dispersion process patents, and regional distributors facing compression from direct technical qualification. Competitive moves center on captive supply of high-purity silicone precursors and portfolio expansion into thermally conductive filler systems.
Among diversified chemical conglomerates, Henkel AG & Co. KGaA and Dow Inc. exemplify integrated positioning through adhesive technology cross-selling and silicone monomer production respectively. Shin-Etsu Chemical Co., Ltd. occupies a specialist tier focused on high-purity output for optoelectronic applications. These three anchors demonstrate how geographic concentration of technical expertise in German, US, and Japanese material science programs shapes competitive access to qualified formulation chemists.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Dow Inc. |
| BASF SE |
| Huntsman Corporation |
| ELANTAS GmbH |
| Shin-Etsu Chemical Co., Ltd. |
| H.B. Fuller Company |
| Hitachi Chemical Co., Ltd. |
| Master Bond Inc. |
| Others |
Supply & Pricing Matrix
Phosphorus-nitrogen flame retardant substitution for banned halogenated systems simultaneously concentrates European formulation expertise in German and Swiss specialty chemical corridors while compressing margin structures for commodity epoxy blenders unable to absorb REACH-driven R&D recertification costs.
Pricing Analysis
Three-tier pricing structure across automotive-grade premium, industrial standard, and consumer economy levels separates qualified suppliers with OEM validation credentials from general formulators. Price differentiation rests on thermal cycling certification tier and captive silicone monomer supply. Cost compression in industrial epoxy grades is intensifying because propylene-derived epichlorohydrin feedstock volatility feeds through to spot pricing. Consumer appliance assemblers in China and Turkey exhibit highest price sensitivity; automotive powertrain electronics teams in Stuttgart and Bavaria prioritize performance validation over unit cost.
Supply Chain Analysis
China and Japan anchor high-purity silicone resin precursor output for LED and photovoltaic encapsulant downstream processing. Raw material flows draw from Asian monomer production, German specialty hardener synthesis, and US photoinitiator manufacturing. Single-source vulnerability concentrates in semiconductor-grade dimethyl silicone supply from Kyushu manufacturing corridors. Distribution runs through direct technical qualification channels where Bosch and Continental engineering centers specify exact filler loadings rather than accepting catalog formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where material qualification databases and automotive OEM validation protocols are becoming interoperable ecosystems, compressing distributor roles and elevating direct technical engagement as the dominant procurement interface.
For Market Incumbents: Compound captive supply advantages in high-purity silicone monomer production through backward integration into phenyl silicone precursor manufacturing. Deepen automotive OEM validation credentials by investing in five-thousand-cycle thermal endurance testing infrastructure. Defend against emerging thermal interface material specialists by patenting boron nitride dispersion process IP.
For New Entrants and Emerging Players: Technical service gaps in Indian PLI scheme electronics manufacturing corridors offer white-space entry where incumbent distributors lack localized formulation support. Target Gujarat and Tamil Nadu semiconductor packaging clusters with rapid-customization resin blending capabilities. Pursue qualification partnerships with domestic PCB fabricators seeking REACH-compliant halogen-free alternatives.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap formulators holding NADCAP accreditation and automotive OEM validation credentials with defensible thermal filler dispersion patents. Long-term viability favors suppliers positioned at the intersection of electrification mandates and regulatory substance restrictions. Monitor ECHA substance restriction announcements as inflection indicators for reformulation-driven M&A activity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Monomer Production | Dow Inc. and Shin-Etsu Chemical Co. capture upstream margin and supply security. |
| Automotive OEM Validation Credentialing | Henkel AG secures specification control at Bosch and Continental engineering centers. |
| Phosphorus-Nitrogen Flame Retardant Formulation Pivot | ELANTAS GmbH preempts REACH substance bans with qualified halogen-free systems. |
| UV-LED Curing Technology Convergence | H.B. Fuller Company addresses EU Green Deal embodied carbon tracking requirements. |
| Regional Distribution Channel Compression | Master Bond Inc. builds direct technical qualification relationships with tier-one electronics suppliers. |
Research Methodology
A spread of perspectives from resin formulation chemists, automotive electronics procurement leads, LED encapsulant technical directors, and photovoltaic module manufacturing engineers converged on the working assumptions. Primary fieldwork combined with secondary validation from SEC 10-K filings, customs and trade data, ECHA substance restriction registers, and ACC industry reports. Bottom-up demand modeling across curing chemistry tiers and top-down macroeconomic triangulation anchored volume and value estimates.
Segmentation dimensions modeled include resin chemistry type, curing technology platform, end-use certification tier, thermal performance threshold, and regional production hub concentration. CAGRs were derived from regression analysis against semiconductor fabrication capacity expansion and automotive electrification program announcements. Forecast inputs incorporated REACH substance restriction timelines, Chinese dual carbon policy implementation, and UV-LED source cost decline curves.
Forecasts assume regulatory continuity in EU REACH, China GB standards, and US EPA oversight; material policy shifts would require re-modeling across the projection horizon. Specific risks include ECHA accelerated flame retardant bans, Asian monomer supply disruptions, and automotive OEM thermal cycling specification divergence. Recalibration cycles align with material shifts in regulatory substance restrictions and semiconductor node advancement announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Tie Layer Resin Market
Polymers & Resins
Polycarbonate Diols Market
Polymers & Resins
Oman PVC Products Market
Polymers & Resins
Paste PVC Resin Market
Polymers & Resins
Semi-Rigid Spray Polyurethane Foam Market
Polymers & Resins
Polymer Colloids Market
Polymers & Resins
South America Fluoropolymer Market
Polymers & Resins
Polyphenylene Sulfide (PPS) Resin Market
Polymers & Resins
Poly(P-Phenylene Ether) (PPE) Market
Polymers & Resins
Styrenics Market
Polymers & Resins
Thailand Plastics Market
Polymers & Resins
Global Polymer Dispersion Market
Polymers & Resins
Global Polyether Ether Ketone (PEEK) Market
Polymers & Resins
Global High Performance Polyethylene Market
Polymers & Resins
PEKK Market
Polymers & Resins
North America Polyamide Market