
 Biobased Biodegradable Plastics Market | 2026-2036
Biobased Biodegradable Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Biobased Biodegradable Plastics Market Analysis
Compost-grade resin certification is reorganizing procurement priorities across European and North American supply chains. NatureWorks LLC leverages its Blair, Nebraska production complex to anchor polylactic acid supply for food-contact applications. BASF SE competes through its Ecoflex and Ecovio platforms, sustaining a position in certified compostable film and coating segments. TotalEnergies Corbion differentiates via its Thailand-based lactide-to-PLA integration, controlling a vertically aligned feedstock chain that reduces lot-to-lot variability for high-clarity packaging.
Biobased biodegradable plastics comprise polymers derived from annually renewable biomass feedstocks that mineralize to carbon dioxide, water, and biomass under managed composting or anaerobic digestion conditions, with ASTM D6400 and EN 13432 serving as the dominant certification benchmarks for industrial compostability. Polylactic acid dominates current installed capacity due to its melt-processability and optical clarity, though polyhydroxyalkanoates occupy the fastest-expanding niche as marine-degradable specifications gain traction in coastal regulatory jurisdictions. Starch blends lead unit economics in emerging markets where cost parity with conventional polyethylene remains the decisive procurement criterion.
The European Chemicals Agency enforces REACH registration and restriction protocols for monomer inputs, while the U.S. Federal Trade Commission polices environmental marketing claims under its Green Guides to prevent biodegradability greenwashing. ASTM International and ISO 17088 provide the technical scaffolding that determines which formulations qualify for compostable labeling in municipal organic waste streams. Stakeholders must monitor how fragmented state-level extended producer responsibility laws in the United States reshape collection infrastructure economics and, by extension, the effective addressable market for certified compostable packaging.

Market Dynamics
The EU Single-Use Plastics Directive is compressing demand timelines for certified compostable alternatives, forcing converters to requalify resin grades ahead of 2030 phase-out deadlines for conventional food-service items.
Growth Catalysts
- Industrial Composting Infrastructure:Germany's expanded anaerobic digestion capacity creates guaranteed offtake pathways for EN 13432-certified packaging. Municipal operators in Bavaria and North Rhine-Westphalia now mandate compostable collection bags.
- Marine Degradability Specifications:Coastal regulatory jurisdictions in Italy and Spain are adopting ASTM D6691 testing protocols for aquaculture gear. Polyhydroxyalkanoate formulations meeting these standards command procurement preference.
- Food-Contact Compliance Pathways:EFSA positive opinions on polylactic acid migration limits unlock shelf-stable dairy and ready-meal applications previously blocked by thermal resistance concerns.
Market Restraints
- Feedstock Price Volatility:Corn starch and sugarcane bagasse costs fluctuate with Brazilian ethanol policy and Midwest grain futures, compressing margin visibility for PLA compounders.
- Thailand-Centered Lactide Supply:Over 60% of global lactide capacity concentrates in Southeast Asian petrochemical corridors, exposing buyers to shipping rate spikes and currency hedging costs.
- Performance Gap in High-Barrier Films:Oxygen transmission rates in biobased biodegradable multilayers remain 3-5x higher than EVOH-nylon structures, limiting meat and cheese packaging conversions.
Strategic Opportunities
- Underpenetrated Medical Device Packaging:Sterilizable PLA trays for single-use surgical kits remain undeveloped in Germany despite existing ISO 10993 biocompatibility frameworks.
- Extended Producer Responsibility Tailwinds:France's AGEC law mandates plastic packaging reduction quotas with compostable alternatives qualifying for bonus credits in producer fee calculations.
- Agricultural Mulch Film Convergence:Soil-biodegradable standards under EN 17033 create overlap between starch-polyester blends and conventional oxo-degradable replacements facing regulatory bans.
Industry Challenges
- Composting Facility Contamination Protocols:Municipal operators in the Netherlands report 12-18 month validation cycles for new resin formulations, delaying volume ramp timelines.
- Reactive Extrusion Scale-Up Complexity:Starch-polyester alloy production requires twin-screw configurations with residence time control that few European toll compounders possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biobased Biodegradable Plastics Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polylactic Acid, Starch Blends, Polyhydroxyalkanoates, Polybutylene Succinate Application: Packaging, Agriculture, Consumer Goods, Textile End User: Food Industry, Retail, Agriculture Sector, Medical Field Distribution Channel: Online Retail, Specialty Stores, Wholesalers, Direct Sales |
| Companies Covered | NatureWorks LLC, BASF SE, Mitsubishi Chemical Group Corporation, TotalEnergies Corbion, Novamont S.p.A., Biome Bioplastics, Braskem, Arkema S.A., Danimer Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biobased Biodegradable Plastics Market Emerging Trajectories
Biodegradation certification is becoming a procurement gate rather than a marketing claim, with buyers demanding chain-of-custody documentation from biomass origin through industrial composting verification.
Polyhydroxyalkanoate copolymers with tailored crystallization kinetics are displacing conventional thermoformed polystyrene in chilled food trays. German retail chains Aldi and Lidl have accelerated PHA pilot programs across their private-label produce lines. The structural consequence is a compression in polystyrene recycling economics as food-contact rPS demand erodes.
REACH registration requirements for novel lactide comonomers are tightening submission timelines under ECHA's 2023 updated guidance on polymer substance identification. Specialty compounders face six-figure dossier preparation costs for modified PLA grades. Small and mid-sized converters in Northern Italy are consolidating formulation development through shared testing consortia to distribute compliance burdens.
Certification-driven specification is fragmenting procurement hierarchies within multinational food brands. Unilever and Nestlé operating companies in France now maintain separate approved supplier lists for EN 13432-certified versus home-compostable-labeled materials. The Netherlands represents the most advanced testbed, where Albert Heijn's private-label requirements have created dual-track qualification pathways that smaller brands struggle to navigate simultaneously.
Biobased Biodegradable Plastics Market Segmentation

Biobased biodegradable plastics procurement diverges sharply across certification grades and composting infrastructure availability. ASTM D6400 and EN 13432 compliance pathways reshape resin selection by end-use, while feedstock origin traceability now filters distributor relationships.
Product Type:
REACH registration thresholds under ECHA guidance differentiate polymer categories by monomer complexity and dossier burden.
- Polylactic Acid:Derived from corn starch or sugarcane lactide through ring-opening polymerization. Food-contact applications in Germany and France dominate offtake, though thermal resistance below 60°C restricts hot-fill packaging conversions.
- Starch Blends:Thermoplastic starch compounded with aliphatic polyesters. Emerging markets in India and Brazil absorb volume where cost parity with polyethylene drives procurement decisions; moisture sensitivity limits shelf-stable applications.
- Polyhydroxyalkanoates:Bacterial fermentation polymers with marine biodegradability certification. Coastal regulatory jurisdictions in Italy and Spain mandate ASTM D6691 compliance for aquaculture gear.
- Polybutylene Succinate:Fermentation-derived succinic acid polymerized with butanediol. Japan's METI bioplastics procurement guidelines favor PBS for agricultural mulch film where soil biodegradability per EN 17033 is required.
Established volume favors Polylactic Acid; emerging adoption favors Polyhydroxyalkanoates.
Application:
Composting facility access density determines addressable market size by application vertical.
- Packaging:Flexible films, thermoformed trays, and injection-molded cutlery. Municipal organic waste streams in the Netherlands and Belgium mandate EN 13432 certification for food-contact items.
- Agriculture:Mulch films, planting trays, and twine. Soil-biodegradable standards create overlap with banned oxo-degradable alternatives in France and Italy.
- Consumer Goods:Disposable tableware, personal care containers, and waste bags. German retail chains Aldi and Lidl pilot PHA-based produce packaging.
- Textile:Nonwoven fabrics and fiber applications. Limited industrial composting infrastructure for post-consumer textile collection constrains volume scaling.
Packaging commands the deepest certification infrastructure; Agriculture climbs the fastest as soil-biodegradable standards displace conventional mulch films.
End User:
Migration limit approvals from EFSA and national food safety agencies gate polymer selection by end-user category.
- Food Industry:Dairy, ready-meals, and fresh produce packaging. EFSA positive opinions on PLA migration limits unlock shelf-stable applications previously blocked by thermal resistance concerns.
- Retail:Private-label packaging and carrier bags. France's AGEC law mandates plastic reduction quotas with compostable alternatives qualifying for bonus credits.
- Agriculture Sector:Mulch films, silage wrap, and planting containers. Bavarian and North Rhine-Westphalian operators mandate compostable collection bags.
- Medical Field:Sterilizable trays and single-use surgical kits. ISO 10993 biocompatibility frameworks exist but sterilizable PLA trays remain underdeveloped in Germany.
Food Industry holds the most advanced compliance pathways; Medical Field offers the steepest expansion trajectory given underpenetration.
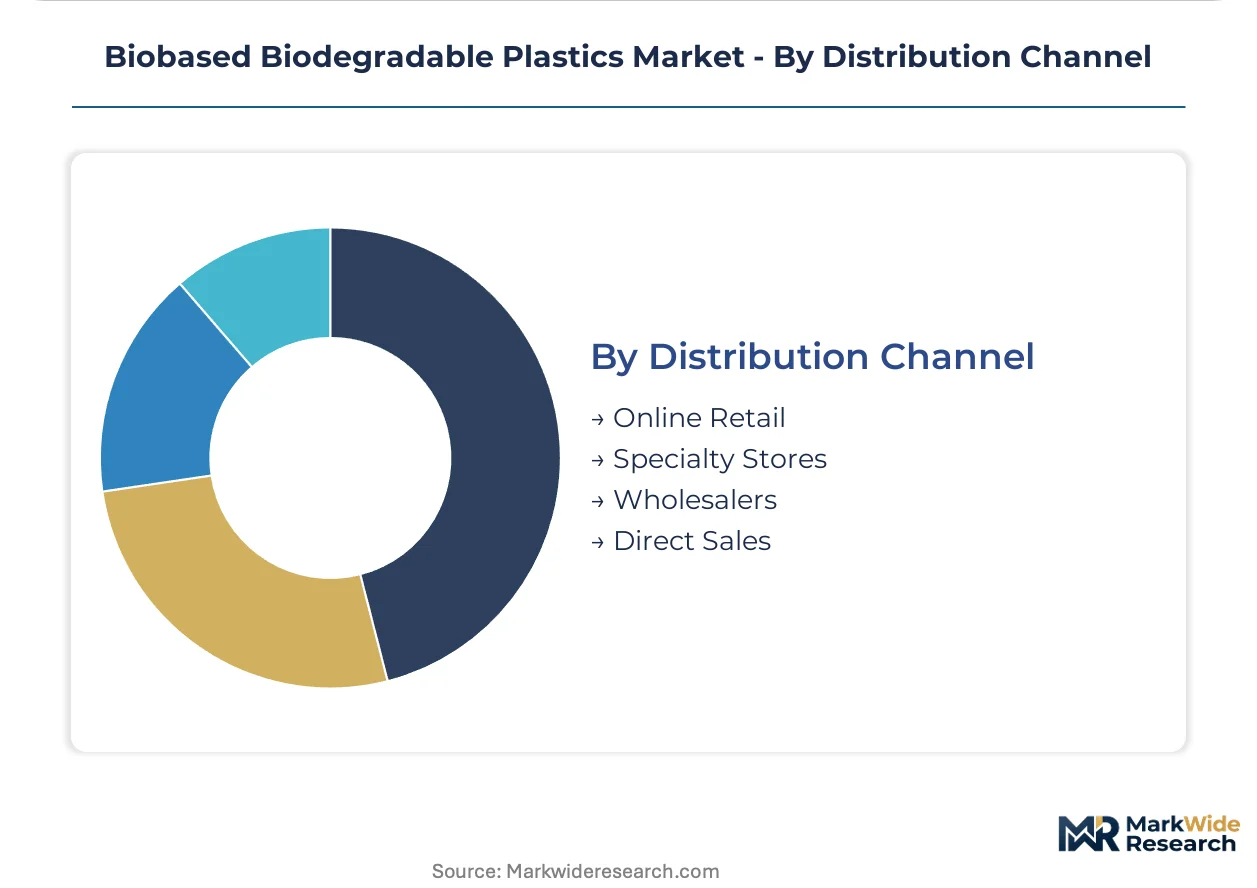
Distribution Channel:
Resin lot-to-lot consistency requirements and technical service intensity shape channel selection.
- Online Retail:E-commerce platforms for standardized grades and small-volume orders. Limited technical support constrains food-contact qualification assistance.
- Specialty Stores:Regional compounders with formulation development capabilities. Northern Italian converters consolidate through shared testing consortia to distribute REACH dossier costs.
- Wholesalers:Volume distributors for commodity starch blends. Price volatility in corn starch and sugarcane bagasse compresses margin visibility.
- Direct Sales:Captive relationships for certified compostable film and coating segments. BASF and TotalEnergies Corbion maintain direct technical service teams for converter qualification.
Direct Sales anchors premium certified grades; Online Retail gains share fastest in standardized consumer goods applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand exports lactide feedstock to European and North American compounders, creating a trade-flow corridor that concentrates supply risk in Southeast Asian petrochemical corridors while downstream demand clusters in Germany, France, and the Netherlands.
Germany
Industrial composting infrastructure in Bavaria and North Rhine-Westphalia guarantees offtake for EN 13432-certified packaging. The country's national packaging regulator enforces extended producer responsibility quotas that favor compostable alternatives. Berlin-Brandenburg hosts pilot programs for PHA-based food trays in retail chains.
France
AGEC law mandates plastic packaging reduction with compostable materials qualifying for bonus credits in producer fee calculations. EFSA migration limit approvals unlock shelf-stable dairy applications for PLA. The Île-de-France region concentrates converter qualification activity for multinational food brands.
Netherlands
Albert Heijn's private-label requirements created dual-track qualification pathways for certified versus home-compostable materials. Municipal organic waste streams mandate EN 13432 certification for food-contact items. The Randstad cluster validates new resin formulations through 12-18 month contamination protocol cycles.
Italy
Coastal regulatory jurisdictions adopt ASTM D6691 testing protocols for aquaculture gear, favoring PHA procurement. Soil-biodegradable standards under EN 17033 displace banned oxo-degradable mulch films in Emilia-Romagna. Northern Italian converters consolidate REACH dossier costs through shared testing consortia.
United States
The Federal Trade Commission polices environmental marketing claims under Green Guides to prevent biodegradability greenwashing. Fragmented state-level extended producer responsibility laws reshape collection infrastructure economics. Nebraska anchors polylactic acid production for food-contact applications.
Biobased Biodegradable Plastics Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and feedstock integration. The vendor base clusters around three tiers: integrated petrochemical majors with captive lactide supply, independent compounders with formulation development capabilities, and regional starch blenders serving cost-sensitive emerging markets. Two dominant competitive moves are shaping positioning: backward integration into fermentation-derived monomers and geographic expansion of composting certification partnerships.
Within the integrated petrochemical tier, NatureWorks LLC and BASF SE exemplify divergent feedstock strategies. TotalEnergies Corbion occupies a position bridging European demand with Southeast Asian production gravity. Among specialty fermentation players, Danimer Scientific represents the marine-degradability vector that coastal regulatory jurisdictions increasingly favor. Novamont S.p.A. anchors the starch-polyester alloy segment where soil-biodegradable agricultural applications concentrate.
| Leading Market Players |
|---|
| NatureWorks LLC |
| BASF SE |
| Mitsubishi Chemical Group Corporation |
| TotalEnergies Corbion |
| Novamont S.p.A. |
| Biome Bioplastics |
| Braskem |
| Arkema S.A. |
| Danimer Scientific |
| Others |
Supply Flow & Price Mechanics
Thailand's concentrated lactide capacity at 60% of global supply creates asymmetric scale economies that compress price floors for European and North American compounders while elevating margin capture for integrated Southeast Asian producers. This geographic concentration forces buyers to absorb currency hedging costs and shipping rate volatility that directly feed into resin pricing structures.
Pricing Analysis
Current-generation polylactic acid commands premium positioning against starch blends and next-generation polyhydroxyalkanoates still scaling fermentation yields. Three-tier pricing structure across EN 13432-certified premium grades, standard industrial compostable resins, and economy starch-polyester blends reflects certification depth and lot-to-lot consistency guarantees. Pricing pressure stems from corn starch and sugarcane bagasse cost volatility tied to Brazilian ethanol policy swings. Emerging market converters in India and Brazil exhibit highest price sensitivity, while German food-contact buyers prioritize certification compliance over unit cost.
Supply Chain Analysis
Just-in-time lactide procurement dominates European compounders seeking to minimize working capital exposure to Thai petrochemical corridor disruptions, though strategic stockpiling of corn starch feedstock persists among Midwestern US producers. Supply concentrates in Thailand for lactide monomers, Germany for compounding and certification testing, and Italy for starch-polyester alloy toll manufacturing. Raw material dependencies include fermentation-derived succinic acid, bacterial culture stocks for PHA production, and annually renewable corn and sugarcane feedstocks. Single-source vulnerability in Southeast Asian lactide supply creates structural risk. Distribution runs through direct technical service relationships for certified grades and wholesale channels for commodity starch blends.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where EN 13432 certification entrenchment creates switching costs that lock in multinational food brands and defend incumbent positions against unqualified resin suppliers.
For Market Incumbents: Secure captive lactide supply through backward integration or long-term offtake agreements with Thai producers to defend against shipping rate spikes and currency volatility. Reinforce certification depth by expanding EN 13432 validation partnerships with municipal composting operators in the Netherlands and Germany, creating collection infrastructure lock-in that emerging PHA suppliers cannot replicate without 12-18 month contamination protocol cycles. For New Entrants and Emerging Players: Differentiate on marine biodegradability certification per ASTM D6691 to capture coastal regulatory jurisdictions in Italy and Spain where aquaculture gear mandates create procurement preference. Target underpenetrated medical device packaging in Germany where sterilizable PLA trays remain undeveloped despite existing ISO 10993 frameworks. Pursue shared testing consortia in Northern Italy to distribute REACH dossier preparation costs across multiple small compounders. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated petrochemical majors with captive fermentation-derived monomer supply and established converter qualification relationships. Long-term viability over the analysis window favors targets with backward integration into lactide or succinic acid production rather than pure-play compounders exposed to feedstock volatility. Watch for inflection when France's AGEC law bonus credit thresholds trigger accelerated compostable packaging procurement across multinational food brands.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lactide Monomers | Captive Thai supply reduces currency hedging costs and shipping rate exposure for European compounders. |
| EN 13432 Certification Partnership Expansion | Municipal operator validation in Bavaria creates guaranteed offtake pathways that lock out unqualified competitors. |
| Marine Biodegradability Certification Investment | ASTM D6691 compliance unlocks aquaculture gear procurement preference in Italian and Spanish coastal jurisdictions. |
| Shared Testing Consortium Formation | Northern Italian compounders distribute six-figure REACH dossier costs across multiple small and mid-sized converters. |
| Medical Device Packaging Qualification | ISO 10993 biocompatibility frameworks enable sterilizable PLA tray development for German surgical kit applications. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with resin procurement managers at multinational food brands, technical directors at European compounders, municipal composting facility operators in Germany and the Netherlands, and regulatory affairs specialists navigating ECHA REACH requirements. Secondary validation drew from customs and trade data tracking lactide flows from Thailand, SEC filings of listed petrochemical majors, EFSA migration limit opinion documents, and municipal organic waste stream reports. Bottom-up volume estimates from converter qualification pipelines were triangulated against top-down demand projections from packaging reduction mandate trajectories.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across polymer type, certification grade, end-use application, and regional composting infrastructure availability. CAGRs were derived from installed capacity expansion announcements, regulatory phase-out deadline proximity, and converter requalification timeline assumptions. Industry-specific forecast inputs included EFSA positive opinion issuance rates for novel food-contact applications and municipal contamination protocol validation cycle durations.
The analysis sits within stated boundaries; outcomes outside sustained EU Single-Use Plastics Directive enforcement or accelerated industrial composting infrastructure buildout would require recalibration. Forecasts reflect documented assumptions regarding lactide supply concentration persistence and marine biodegradability standard adoption velocity. Revision becomes warranted when Thai petrochemical corridor disruption frequency or Brazilian ethanol policy volatility crosses thresholds that invalidate feedstock cost assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Brazil Bioplastics Market
Bioplastics
Middle East Biodegradable Plastics Market
Bioplastics
Compostable Phone Cases Market
Bioplastics
Global Bioplastic Composites Market
Bioplastics
Southeast Asia Bio-PET Market
Bioplastics
Biodegradable Microbeads Market
Bioplastics
Biopolymers Market
Bioplastics
Global Bioresorbable (Resorbable) Polymers Market
Bioplastics
Synthetic and Bio-Based PMMA Polymethyl Methacrylate Size Market
Bioplastics
Bio-Based Polyolefins Market
Bioplastics
Bio-Polyamide, Specialty Polyamide and Precursors Market
Bioplastics
Global Synthetic and Bio Based Biodegradable Plastics Market
Bioplastics
Global Green and Bio-Based Plastic Additives Market
Bioplastics
Biopolymer Films Market
Bioplastics
US Bioplastics Market
Bioplastics
Bioplastic Textile Market