
 Global Barrier Resins Market | 2026-2036
Global Barrier Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Global Barrier Resins Market Foresight
The EU Green Deal is recalibrating demand specifications across European packaging supply chains, compelling converters to source lower-carbon barrier alternatives. BASF SE leverages its integrated polyamide and EVOH portfolios to anchor supply relationships with major European food processors. Kuraray Co., Ltd. dominates high-barrier EVOH resin production through captive vinyl alcohol technology and Asian manufacturing scale.
Barrier resins are high-performance polymers engineered to restrict gas, moisture, and aroma permeation, typically achieving oxygen transmission rates below 1 cc·mil/100in²/day through controlled crystallinity and polar functional groups. EVOH grades lead the product type landscape due to their exceptional oxygen barrier performance in dry conditions, while PVDC maintains defensive positions in moisture-sensitive pharmaceutical wrapping where its broad sealing window and chemical resistance justify premium positioning despite regulatory scrutiny over chlorine content. Film and sheet forms command the highest value per kilogram as coextruded multilayer structures replace monolayer solutions in retort and modified-atmosphere packaging.
The EPA regulates volatile organic compound emissions from barrier resin manufacturing facilities under Clean Air Act provisions, while REACH restricts certain phthalate and chlorinated chemistries in European food-contact applications. Japan's METI enforces positive-list standards for food-contact materials that exceed Codex Alimentarius baselines, creating technical barriers for non-Japanese suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks in California, Germany, and Japan to anticipate compliance cost allocations across the value chain.
Market Dynamics
Coextrusion technology maturation is compressing multilayer film costs while EU packaging waste directives force material substitutions across food-contact supply chains, creating simultaneous pull and push pressures on resin specifications.
Growth Catalysts
- EU Green Deal packaging targets:Mandatory recycled content thresholds in food-contact films are accelerating demand for compatible barrier layers that maintain performance at lower virgin resin ratios.
- Modified-atmosphere packaging expansion:Fresh protein and ready-meal processors in Germany and Japan are specifying oxygen transmission rates below 0.5 cc·mil/100in²/day for extended shelf-life claims.
- Asian coextrusion capacity buildout:New blown film lines in China and South Korea are absorbing EVOH and polyamide volumes previously supplied from Japanese and European sources.
Market Restraints
- Ethylene feedstock volatility:EVOH production margins fluctuate with ethylene oxide and vinyl acetate monomer pricing, compressing converter pass-through capabilities during upstream spikes.
- Japanese EVOH supply concentration:Kuraray and Mitsubishi Chemical collectively control over 70% of global high-barrier EVOH capacity, creating single-source risk for European and North American compounders.
- PVDC regulatory friction:REACH restrictions on chlorinated polymers in food-contact applications are forcing pharmaceutical and meat packaging converters to qualify alternative moisture barriers with longer validation timelines.
Strategic Opportunities
- India packaged food penetration:Organized retail expansion and cold-chain investment in Maharashtra and Gujarat are creating first-mover positions for barrier film converters establishing local compounding relationships.
- Bio-based barrier polymer development:Polyamide 11 and fermented EVOH analogs are approaching commercial scale, offering brand owners defensible sustainability claims against conventional petroleum-derived alternatives.
- Direct-to-brand technical sales:Bypassing traditional distributor networks, resin suppliers are embedding application engineers with major food processors to co-develop specification-locked formulations.
Industry Challenges
- Multilayer film recycling complexity:Current mechanical recycling infrastructure cannot separate EVOH or polyamide from PE/PP tie layers, forcing converters to fund chemical recycling pilot programs or face extended producer responsibility penalties.
- Food-contact migration testing bottlenecks:Japan's METI positive-list compliance requires 12-18 month validation cycles for new resin grades, delaying product launches and freezing formulation innovation pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Barrier Resins Market |
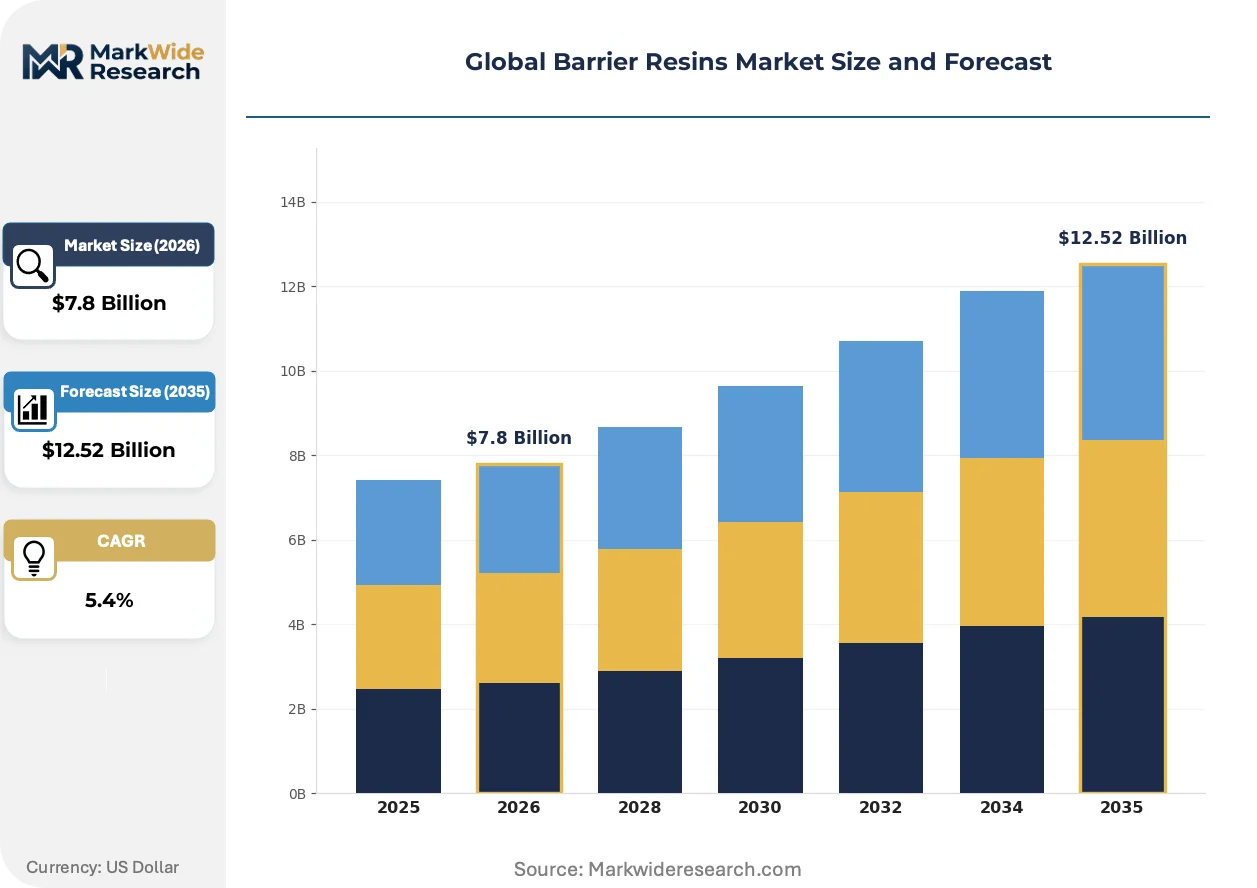
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EVOH, PVDC, Polyethylene Vinyl Acetate, Acrylic, Ethylene Vinyl Alcohol Copolymer, Nylon Application: Food Packaging, Pharmaceutical Wrapping, Personal Care, Industrial Containers, Electronics Protection, Agricultural Films End User Industry: Consumer Goods Manufacturers, Medical Equipment Makers, Chemical Producers, Electronics Assemblers, Agriculture Suppliers, Packaging Firms Form: Pellets, Powders, Granules, Liquid Dispersions, Films, Sheets |
| Companies Covered | BASF SE, Asahi Kasei Corporation, Kuraray Co., Ltd., Mitsubishi Chemical Holdings Corporation, LyondellBasell Industries N.V., The Dow Chemical Company, Solvay S.A., Eastman Chemical Company, E.I. du Pont de Nemours and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Barrier Resins Market Shifts & Advancements
Barrier resin innovation is pivoting from incremental permeability reduction toward circular-economy compatibility, with chemical recyclability and mono-material constructability now co-equal design targets alongside oxygen and moisture resistance.
Nano-clay reinforced polyamide composites are rewriting cost-performance tradeoffs in high-humidity barrier applications. Southeast Asian seafood exporters are adopting these grades at accelerating rates for frozen shrimp and fish fillet packaging. The technology is compressing the premium traditionally commanded by EVOH in moisture-sensitive segments where oxygen barrier requirements are moderate.
REACH restrictions on intentionally added microplastics are forcing reformulation of slip and antiblock additives in barrier films. Compounders serving European food processors are qualifying bio-based erucamide alternatives with comparable coefficient-of-friction performance. Pharmaceutical blister packaging converters face the steepest compliance costs due to stringent migration limits on new additive chemistries.
Brand-led sustainability scorecards are reshaping resin procurement criteria at major food processors. Unilever and Nestlé technical specifications now weight recyclability and carbon footprint equally with barrier performance, displacing pure cost-per-kilogram sourcing models. German and French retail chains are propagating these standards through private-label packaging tenders, compressing margins for converters unable to document supply chain emissions.
Global Barrier Resins Market Segmentation
Barrier resin specifications diverge sharply across integration depths, from standalone film layers to embedded multilayer structures. Understanding where each segment sits on this spectrum reveals which grades command formulation premiums versus commodity positioning.
Product Type:
Integration depth varies dramatically — EVOH and PVDC anchor high-performance coextruded systems, while polyethylene vinyl acetate and acrylic grades serve more modular, standalone applications.
- EVOH:Ethylene-vinyl alcohol copolymers achieve oxygen transmission rates below 0.5 cc·mil/100in²/day in dry conditions through controlled crystallinity. German and Japanese food processors specify these grades for modified-atmosphere meat packaging where shelf-life extension justifies coextrusion complexity. Kuraray's captive vinyl alcohol technology locks in supply relationships with major Asian converters.
- PVDC:Polyvinylidene chloride delivers the broadest sealing window and chemical resistance among commercial barrier resins. Pharmaceutical blister packaging in Switzerland and Germany relies on PVDC despite REACH scrutiny over chlorine content, as moisture barrier requirements exceed what EVOH can deliver in humid conditions.
- Polyethylene Vinyl Acetate:Lower-barrier grades serve cost-sensitive agricultural film applications where moderate moisture resistance suffices.
- Acrylic:Oxygen-scavenging variants integrate into active packaging systems for fresh produce applications.
- Ethylene Vinyl Alcohol Copolymer:Specialty grades with enhanced thermal stability target retort pouch applications in South Korea and Japan.
- Nylon:Polyamide 6 and 66 grades provide puncture resistance and moderate gas barrier for industrial vacuum packaging.
EVOH leads volumes today; bio-based polyamide alternatives are gaining share fastest.
Application:
Cost tier stratification separates premium specification-locked applications from price-sensitive commodity segments.
- Food Packaging:Multilayer coextruded films for fresh protein and ready-meal applications command the highest resin value per kilogram. EU Green Deal recycled content mandates are forcing reformulation of EVOH tie-layer compatibility across German and French supply chains.
- Pharmaceutical Wrapping:Blister packs and cold-form foils require migration-tested grades meeting FDA and EMA standards. Swissmedic and Health Canada oversight creates multi-jurisdiction validation costs that freeze out smaller compounders.
- Personal Care:Fragrance barrier tubes and sachets prioritize aroma containment over oxygen exclusion.
- Industrial Containers:Drum and pail liners emphasize chemical resistance and processability in high-speed blow molding.
- Electronics Protection:Static-dissipative barrier films protect semiconductors during Asia-Pacific shipping.
- Agricultural Films:Fumigation and greenhouse films tolerate higher permeability for cost minimization.
Food packaging dominates revenue; pharmaceutical wrapping offers the steepest margin expansion trajectory.
End User Industry:
Customer type determines technical service intensity and specification lock-in duration.
- Consumer Goods Manufacturers:Nestlé and Unilever sustainability scorecards now weight recyclability equally with barrier performance. These brand-led procurement shifts are displacing pure cost-per-kilogram sourcing models across European private-label networks.
- Medical Equipment Makers:Sterile barrier systems for implantable devices require ISO 11607 compliance with 18-month validation cycles. FDA 510(k) parallel submissions extend qualification timelines for new resin grades.
- Chemical Producers:Drum and intermediate bulk container specifications prioritize chemical compatibility databases.
- Electronics Assemblers:Cleanroom-compatible packaging demands low-outgassing certification.
- Agriculture Suppliers:Seasonal demand patterns favor spot purchasing over long-term supply agreements.
- Packaging Firms:Converter consolidation in Germany and Japan is concentrating procurement leverage.
Packaging firms move the highest tonnage; medical equipment makers generate the most defensible margins.
Form:
Supply concentration clusters in pellet and film forms where compounding and coextrusion capabilities overlap.
- Pellets:Standardized melt-flow grades serve injection molding and blow molding converters. BASF SE's integrated polyamide pellet supply anchors relationships with major European food processors seeking lot-to-lot consistency.
- Films:Coextruded multilayer structures command 3-4x the value per kilogram of monolayer alternatives. New blown film capacity in China and South Korea is absorbing EVOH volumes previously sourced from Japanese suppliers.
- Powders:Rotational molding and coating applications favor fine particle size distributions.
- Granules:Extrusion-grade variants with enhanced thermal stability target sheet applications.
- Liquid Dispersions:Water-based coatings for paper and board barrier treatments.
- Sheets:Thermoformable grades for medical tray and pharmaceutical blister applications.
Pellets dominate volume throughput; films capture the highest value-added realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer chemists and coextrusion engineers cluster in Germany, Japan, and the United States, anchoring the technical workforce that designs multilayer barrier structures for food and pharmaceutical applications.
Germany
Modified-atmosphere packaging for fresh protein drives EVOH and polyamide consumption across Bavarian and North Rhine-Westphalian converter networks. EU Green Deal recycled content mandates force reformulation of tie-layer compatibility in food-contact films. BASF SE's Ludwigshafen complex anchors integrated polyamide supply relationships with major European food processors.
Japan
Retort pouch applications in ready-meal packaging sustain premium EVOH specifications with oxygen transmission rates below 0.5 cc·mil/100in²/day. METI enforces positive-list food-contact standards that exceed Codex Alimentarius baselines, creating technical barriers for non-Japanese suppliers. Kuraray and Mitsubishi Chemical concentrate high-barrier EVOH capacity in the Kansai and Chubu industrial corridors.
United States
Pharmaceutical blister packaging demand in New Jersey and North Carolina sustains PVDC volumes despite regulatory scrutiny. EPA Clean Air Act provisions govern volatile organic compound emissions from barrier resin manufacturing facilities. Dow Chemical and Eastman Chemical maintain compounding and technical service operations across the Gulf Coast petrochemical corridor.
China
New blown film capacity in Jiangsu and Zhejiang provinces absorbs EVOH volumes previously sourced from Japanese suppliers. GB standards for food-contact materials create compliance complexity for imported resin grades. Yangtze River Delta coextrusion lines are expanding modified-atmosphere packaging output for domestic fresh protein processors.
South Korea
Seafood export packaging drives nano-clay reinforced polyamide adoption for frozen shrimp and fish fillet applications. MFDS food-contact regulations align with Codex baselines but require migration testing documentation. Busan-Ulsan industrial complexes host expanding film extrusion capacity serving Japanese and Southeast Asian markets.
Global Barrier Resins Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the barrier resin value chain, with integrated petrochemical giants controlling upstream vinyl alcohol and polyamide monomer supply while specialized compounders focus on formulation customization. The market structure concentrates high-barrier EVOH production among two Japanese conglomerates holding captive vinyl alcohol technology, while European and North American players dominate polyamide integration and technical service intensity. Three archetypes define competitive positioning: integrated petrochemical majors with backward monomer control, regional compounders with application engineering depth, and Asian specialists leveraging manufacturing scale. Dominant competitive moves include geographic expansion through local compounding joint ventures and portfolio diversification into bio-based barrier alternatives.
Within the integrated petrochemical tier, BASF SE and LyondellBasell Industries N.V. represent European and North American archetypes respectively, each anchoring supply relationships through captive polyamide production and technical service networks. Kuraray Co., Ltd. occupies a distinctive position as a Japanese specialist exemplifying concentrated high-barrier EVOH capability through captive vinyl alcohol technology. These three companies collectively illustrate the geographic and technological segmentation that shapes procurement decisions across food packaging and pharmaceutical applications.
| Leading Market Players |
|---|
| BASF SE |
| Asahi Kasei Corporation |
| Kuraray Co., Ltd. |
| Mitsubishi Chemical Holdings Corporation |
| LyondellBasell Industries N.V. |
| The Dow Chemical Company |
| Solvay S.A. |
| Eastman Chemical Company |
| E.I. du Pont de Nemours and Company |
| Others |
Supply & Pricing Matrix
EU Green Deal recycled content mandates are forcing converters to reformulate multilayer structures with compatible barrier layers, compelling resin suppliers to absorb qualification costs while defending specification-locked relationships with major food processors.
Pricing Analysis
Technical service bundling separates premium resin supply from commodity pellet transactions. Three-tier pricing structure across specification-locked, performance-standard, and economy grades reflects certification intensity and coextrusion support depth. Pricing pressure stems from Asian capacity buildout absorbing volumes previously sourced from Japanese suppliers. Small-to-mid converters exhibit highest price sensitivity, while multinational food processors prioritize lot-to-lot consistency over per-kilogram differentials.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States anchor hub-and-spoke patterns for just-in-time coextrusion feedstock delivery. Manufacturing concentration in Germany, Japan, and China draws from ethylene oxide, vinyl acetate monomer, and adipic acid feedstocks. Single-source vulnerability runs through Kuraray and Mitsubishi Chemical captive vinyl alcohol technology. Distribution runs through converter-direct technical service relationships rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: Japanese EVOH supply concentration creates cost premiums that European and North American compounders exploit through localized polyamide compounding and technical service intensity.
For Market Incumbents: Anticipate REACH restrictions on chlorinated polymers by accelerating PVDC alternative qualification timelines. Deepen backward integration into adipic acid and caprolactam to offset ethylene feedstock volatility. Lock in specification-locked relationships with Nestlé and Unilever procurement teams before sustainability scorecards fully displace cost-per-kilogram sourcing. For New Entrants and Emerging Players: Bio-based polyamide development offers a technology-first wedge into brand-led sustainability procurement. Target Maharashtra and Gujarat organized retail expansion for first-mover barrier film compounding positions. Pursue direct-to-brand technical sales embedding application engineers with major food processors rather than distributor channel builds. For Investors and Strategic Acquirers: Asymmetric upside sits with regional compounders possessing application engineering depth and food-contact certification libraries. Five-to-ten year viability hinges on chemical recycling infrastructure maturation and extended producer responsibility framework clarity. Monitor Japan METI positive-list validation cycle compression as inflection indicator for formulation innovation pipeline velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive adipic acid production insulates BASF from feedstock volatility in Ludwigshafen operations. |
| Bio-Based Barrier Polymer Scale-Up | Polyamide 11 fermentation offers defensible sustainability claims against petroleum-derived EVOH alternatives. |
| Local Compounding Joint Ventures | India partnerships bypass Japanese EVOH supply concentration for Maharashtra cold-chain packaging demand. |
| Chemical Recycling Pilot Funding | Mechanical recycling incompatibility forces converter investment to avoid extended producer responsibility penalties. |
| Direct-to-Brand Technical Sales | Embedded application engineers with Unilever procurement teams lock in specification-locked formulation relationships. |
Research Methodology
Multiple input streams — primary interviews with plant managers, procurement leads at downstream converters, distribution channel partners, and technical R&D directors; secondary validation through customs/trade data, ACC/Cefic reports, and SEC 10-K filings; and patent landscape analysis — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across the projection horizon modeled grade tier, end-use industry, packaging format, and regional production hub segmentation dimensions. CAGRs were derived from elasticity-adjusted demand projections and capacity utilization trajectories. Forecast inputs incorporated EU Green Deal implementation pacing and Japan METI validation cycle duration assumptions.
The model holds under sustained coextrusion technology maturation and stable ethylene feedstock availability; deviation in REACH regulatory acceleration or Kuraray supply disruption would shift volume and value trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Ethylene Vinyl Acetate Resins Market
Polymers & Resins
C9 Resin Market
Polymers & Resins
Nylon-6 Market
Polymers & Resins
Polymer Alloys Market
Polymers & Resins
Europe Medical Polyethylene Market
Polymers & Resins
Vinyl Acetate Ethylene Copolymer Powder Market
Polymers & Resins
Bio-Based Construction Polymers Market
Polymers & Resins
Global Polyphenylene Market
Polymers & Resins
Virgin Resin Market
Polymers & Resins
Fluorinated Polyimide Market
Polymers & Resins
Synthetic Polymer Waxes Market
Polymers & Resins
Modified Epoxy Resins Market
Polymers & Resins
Fire Resins Market
Polymers & Resins
Africa Polyethylene Terephthalate (PET) Market
Polymers & Resins
Polycide Market
Polymers & Resins
1-Hexene Based Polyethylene Market