
 Asia-Pacific Hydroxyl-Terminated Polybutadiene (HTPB) Market | 2026-2036
Asia-Pacific Hydroxyl-Terminated Polybutadiene (HTPB) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Hydroxyl-Terminated Polybutadiene (HTPB) Market Outlook
Polymer synthesis pathways for hydroxyl-terminated polybutadiene is fragmenting across catalytic and anionic routes, forcing producers to choose between cost efficiency and molecular-weight precision. Zibo Qilong Chemical Industry Co., Ltd. leverages its Shandong-based butadiene feedstock access to sustain cost-competitive liquid-grade output. Idemitsu Kosan Co., Ltd. anchors its position through refined viscosity control for Japanese aerospace contractors. Evonik Industries AG differentiates via specialized high-functionality grades for European-Asian supply corridors.
Hydroxyl-terminated polybutadiene is a liquid telechelic polymer with terminal hydroxyl groups enabling polyurethane crosslinking, typically manufactured through free-radical polymerization of 1,3-butadiene followed by oxidative cleavage, and serves primarily as a binder and fuel in solid rocket propellants plus a toughening agent in epoxy composites. Low-viscosity grades dominate volume flows due to easier processing in automated propellant casting, while high-viscosity variants command premium positioning in structural adhesive formulations where cohesive strength requirements are stringent. Among end-user verticals, aerospace procurement channels exhibit the most rigid qualification timelines, whereas coatings applications offer faster trial-to-contract conversion for qualified suppliers.
Japan's METI chemical substance regulations and China's MEE environmental compliance frameworks jointly shape feedstock sourcing protocols and emissions thresholds for HTPB producers operating across the region. India's BIS polymer standards and CDSCO chemical safety requirements further segment market access for imported versus domestically manufactured grades. Stakeholders must monitor evolving propellant classification protocols under multiple national defense procurement regimes to anticipate specification shifts before contract renewal cycles.
Market Dynamics
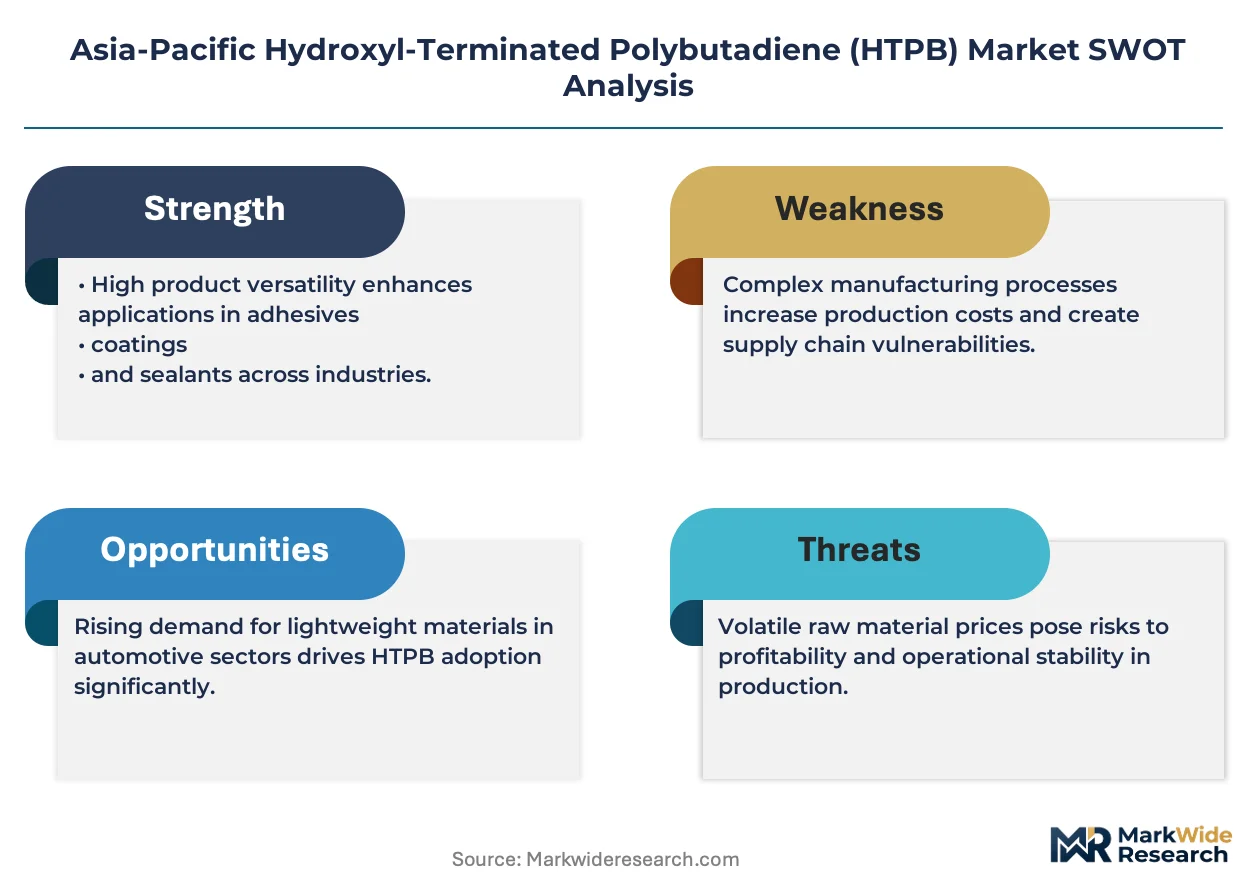
Defense procurement acceleration across Asia-Pacific is compressing HTPB qualification timelines while China's GB chemical safety standards simultaneously tighten feedstock purity thresholds, creating a dual-speed market where aerospace contractors face extended certification cycles.
Growth Catalysts
- Defense Modernization Programs:Solid rocket propellant manufacturers in India and Japan are expanding HTPB procurement volumes under national security frameworks, with India's BIS polymer standards enabling faster domestic supplier qualification.
- REACH-Aligned Environmental Compliance:China's MEE emissions thresholds are pushing Shandong chemical cluster producers toward cleaner anionic polymerization routes, reducing hazardous byproduct generation and opening export corridors to European aerospace contractors.
- Epoxy Composite Toughening Demand:Wind turbine blade manufacturers across South Korea and Australia are adopting HTPB-modified epoxy systems for enhanced fatigue resistance, creating non-defense volume anchors.
Market Restraints
- Butadiene Feedstock Volatility:Crude oil price swings directly transmit to 1,3-butadiene contract pricing, compressing margin visibility for non-integrated HTPB producers lacking captive steam cracker access.
- Shandong Supply Concentration:Over 60% of Asia-Pacific HTPB nameplate capacity sits within 200 kilometers of Zibo, exposing buyers to single-point disruption risks from regional environmental enforcement actions or logistics bottlenecks.
- Polyether Polyurethane Substitution:Polytetramethylene ether glycol (PTMEG) binders are capturing lower-performance solid propellant niches where hydroxyl functionality requirements are less stringent.
Strategic Opportunities
- India Defense Indigenization:CDSCO chemical safety requirements and BIS certification pathways are creating first-mover advantages for domestic HTPB producers supplying ISRO and DRDO propellant programs.
- Dual-Carbon Policy Tailwinds:China's dual carbon goals are accelerating funding for bio-based butadiene pilot plants, potentially decarbonizing HTPB feedstock supply chains for export-oriented producers.
- Digital Propellant Formulation Platforms:Machine learning-driven rheology prediction tools are converging with automated casting simulation, enabling remote qualification of HTPB lots without physical sample shipment.
Industry Challenges
- Anionic Polymerization Expertise Scarcity:Precision molecular-weight control for aerospace-grade HTPB requires specialized organolithium handling capabilities that few regional technicians possess, lengthening plant commissioning timelines.
- Cross-Border Certification Fragmentation:Japan's METI substance notification requirements, China's GB standards, and India's BIS polymer specifications lack mutual recognition, forcing redundant testing for multi-country suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Hydroxyl-Terminated Polybutadiene (HTPB) Market |
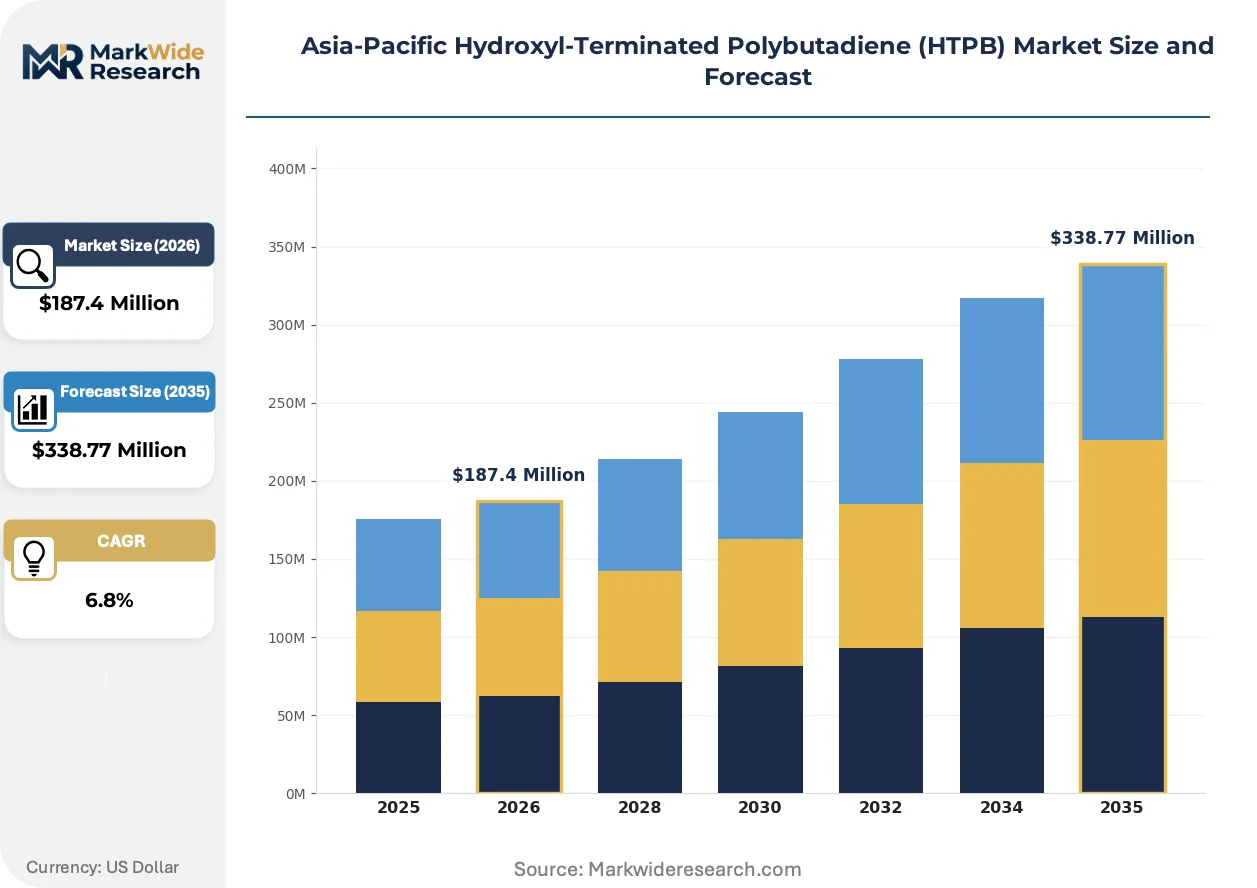
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Viscosity, High Viscosity, Gelled, Liquid End User: Aerospace, Automotive, Coatings, Adhesives Application: Composite Materials, Sealants, Propellants, Elastomers Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Zibo Qilong Chemical Industry Co., Ltd., Shanghai Ruizheng Technology Co., Ltd., Idemitsu Kosan Co., Ltd., Tanyun Chemicals, Orion Chem Pvt. Ltd., Evonik Industries AG, Nippon Soda Co., Ltd., Island Pyrochemical Industries, Cray Valley, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Hydroxyl-Terminated Polybutadiene (HTPB) Market Strategic Shifts
Computational chemistry and regulatory digitization are compressing HTPB development cycles while procurement behaviors shift toward qualified-supplier consolidation. These forces are reconfiguring competitive advantage around data assets and certification velocity rather than scale alone.
Continuous flow reactor technology for free-radical polymerization is virtualizing traditional batch manufacturing economics. Japanese aerospace contractors are piloting these systems for on-demand HTPB synthesis at reduced lot sizes. This technology is virtualizing inventory holding requirements and enabling just-in-time propellant casting operations previously impossible with conventional batch logistics.
China's GB 30000 chemical classification standards are mandating revised safety data sheet formats and hazard communication protocols for hydroxyl-terminated polymers. Industrial consequence includes mandatory reformulation documentation for all HTPB grades sold into domestic defense channels. Aerospace propellant formulators are responding by establishing dedicated regulatory affairs functions in Beijing to preempt compliance gaps before contract renewal cycles.
Buyer concentration among state-owned defense contractors is collapsing supplier rosters from multi-source to dual-source or sole-source arrangements. Tier-2 propellant manufacturers are losing access to premium HTPB grades as prime contractors vertically integrate binder supply or lock in exclusive offtake agreements. This pattern is most visible in China's solid rocket motor sector, where CASC subsidiaries are consolidating procurement under centralized chemical supply platforms.
Asia-Pacific Hydroxyl-Terminated Polybutadiene (HTPB) Market Segmentation
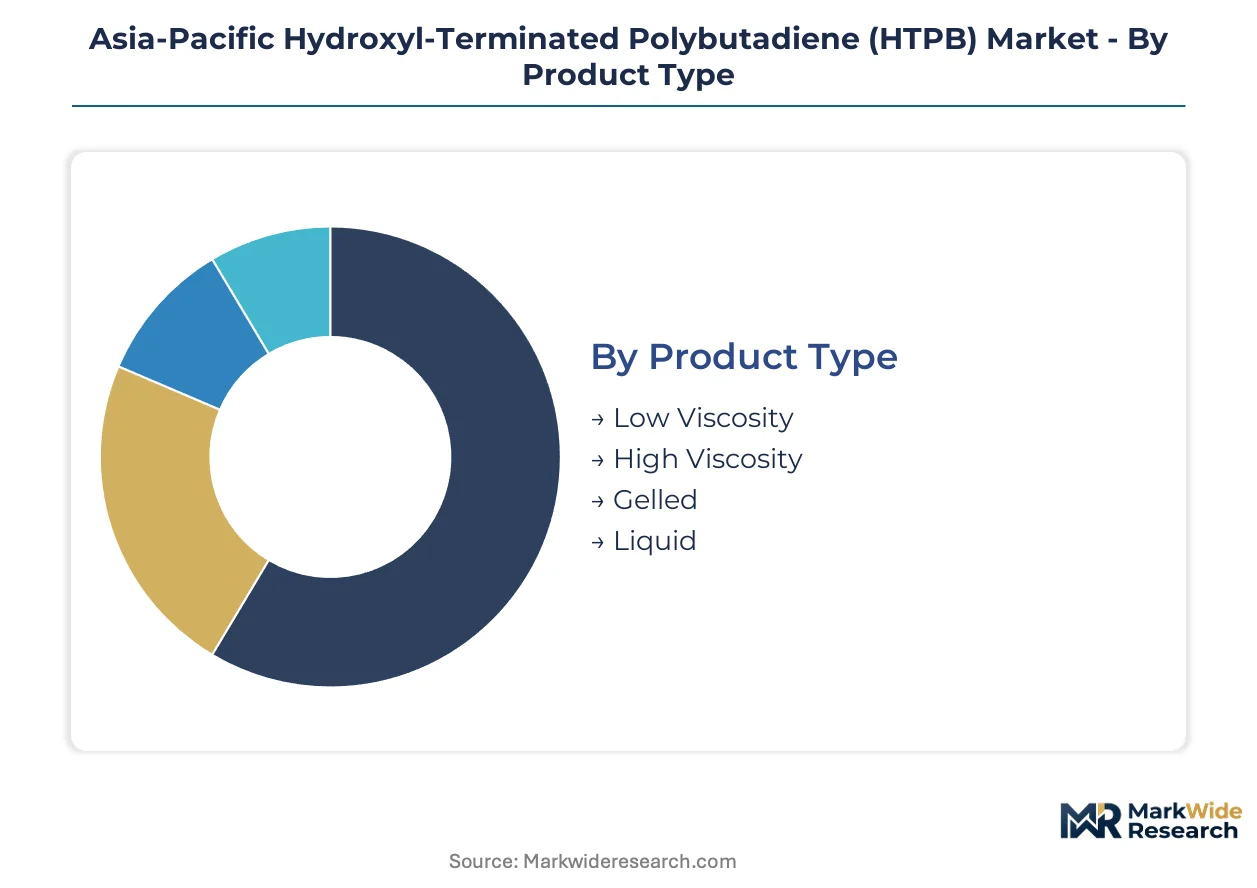
HTPB procurement patterns diverge sharply across viscosity grades, end-use specifications, and channel structures. Defense contractors impose qualification barriers that filter supplier access, while industrial buyers prioritize formulation flexibility and delivery velocity.
Product Type:
Viscosity classification separates automated casting applications from structural bonding requirements, with molecular-weight distribution determining processing economics.
- Low Viscosity:Fluid grades with narrow polydispersity enable high-throughput propellant mixing and automated casting lines. India's ISRO solid motor programs specify these grades for reduced mixing energy and shorter cure cycles.
- High Viscosity:Elevated molecular-weight variants deliver cohesive strength for structural adhesive laminates. Japanese aerospace contractors specify these for carbon-fiber composite toughening where peel resistance is critical.
- Gelled:Thixotropic formulations incorporate fumed silica or clay additives for vertical-surface application. South Korean wind blade manufacturers utilize these for root-end bonding where sag resistance matters.
- Liquid:Standard pourable grades serve general-purpose polyurethane crosslinking across industrial coatings.
Low viscosity commands the established base. The steepest expansion runs through high viscosity.
End User:
Customer archetypes span mission-critical defense procurement to price-sensitive industrial formulation, with certification depth varying accordingly.
- Aerospace:Solid rocket motor manufacturers enforce rigid lot-to-lot consistency protocols. China's CASC subsidiaries consolidate procurement under centralized chemical supply platforms, collapsing supplier rosters.
- Automotive:HTPB-modified epoxy systems penetrate underbody sealant applications for vibration damping. Australian mining vehicle rebuilders specify these for chassis coating durability in abrasive environments.
- Coatings:Industrial formulators prioritize cost-per-liter and color stability over molecular-weight precision. Southeast Asian marine coating producers blend HTPB with conventional polyols for flexibility enhancement.
- Adhesives:Construction-grade bonding applications demand mid-range viscosity with extended pot life.
Aerospace anchors premium positioning. Coatings volume is climbing the fastest as industrial formulators broaden adoption.
Application:
Functional use cases align with material property requirements, from energetic binder service to passive matrix modification.
- Composite Materials:Epoxy toughening leverages HTPB's rubber-phase morphology for crack deflection. South Korean wind turbine blade producers specify these systems for enhanced fatigue resistance in cyclic loading.
- Propellants:Energetic binder service demands precise hydroxyl equivalent weight for isocyanate curing stoichiometry. India's DRDO propellant programs drive domestic qualification of aerospace-grade material.
- Sealants:Low-modulus formulations accommodate thermal expansion mismatches in building joints.
- Elastomers:Cast polyurethane applications exploit HTPB's hydrocarbon backbone for hydrolytic stability.
Propellants dominate value capture. Composite materials are gaining share fastest as renewable energy infrastructure expands.
Distribution Channel:
Channel selection reflects buyer scale, technical support requirements, and regulatory documentation needs.
- Direct Sales:Prime defense contractors negotiate frame contracts with producers for qualified-grade material. China's Shandong cluster producers maintain dedicated account teams for CASC and CASIC subsidiaries.
- Distributors:Regional chemical distributors stock standard viscosity grades for industrial formulators requiring rapid fulfillment. Japanese trading houses coordinate import logistics for European-Asian supply corridors.
- Online Sales:Digital procurement platforms serve small-volume researchers and prototype formulators.
- Retail:Limited presence in specialized polymer outlets for hobbyist rocketry and educational markets.
Direct sales commands the established base. Distributor networks are expanding most quickly as qualified supplier rosters consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense contractors and propellant manufacturers concentrate procurement decisions in four national markets, each shaped by distinct regulatory frameworks and industrial clustering patterns that determine supplier access and qualification velocity.
China
China's GB chemical safety standards and MEE emissions thresholds are tightening feedstock specifications for Shandong-based producers. The dual carbon policy is accelerating funding for bio-based butadiene pilot plants in Zibo. Multiple integrated butadiene-to-polymer operations in this chemical cluster sustain cost-competitive liquid-grade output for domestic aerospace procurement.
Japan
Japanese aerospace contractors demand refined viscosity control for solid motor applications, with METI chemical substance regulations governing feedstock sourcing protocols. Idemitsu Kosan anchors supply relationships through specialized high-functionality grades. The Kanto region hosts concentrated formulation expertise serving JAXA and defense prime contractors.
India
India's BIS polymer standards and CDSCO chemical safety requirements are creating first-mover advantages for domestic producers supplying ISRO and DRDO propellant programs. Defense indigenization policies compress qualification timelines for qualified-grade material. Maharashtra and Gujarat chemical corridors are emerging as domestic manufacturing locations.
South Korea
South Korean wind turbine blade manufacturers are adopting HTPB-modified epoxy systems for enhanced fatigue resistance, creating non-defense volume anchors. The Busan-Ulsan industrial belt concentrates composite fabrication capacity. MFDS chemical safety frameworks govern import documentation for European-Asian supply corridors.
Australia
Australian mining vehicle rebuilders specify HTPB-modified underbody sealants for chassis coating durability in abrasive environments. TGA chemical notification requirements shape import compliance for industrial formulators. Queensland and Western Australia host concentrated mining equipment maintenance operations driving specialty coatings demand.
Asia-Pacific Hydroxyl-Terminated Polybutadiene (HTPB) Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure consolidating around qualified-supplier rosters. Prime defense contractors and state-owned aerospace enterprises are collapsing procurement from multi-source to dual-source or sole-source arrangements. Three archetypes dominate: integrated petrochemical producers with captive butadiene access, specialized polymer manufacturers with viscosity-control expertise, and regional distributors serving industrial formulators. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers seek to secure offtake agreements before contract renewal cycles.
Within the integrated producer tier, Zibo Qilong Chemical Industry Co., Ltd. and Shanghai Ruizheng Technology Co., Ltd. represent Shandong-based operations leveraging feedstock proximity. Idemitsu Kosan Co., Ltd. occupies a position among specialized Japanese manufacturers serving aerospace qualification requirements. Evonik Industries AG exemplifies the European-Asian supply corridor specialist archetype. These named entities serve as anchors for understanding how geographic origin and company structure map to market positioning without asserting specific strategic actions or financial performance.
| Leading Market Players |
|---|
| Zibo Qilong Chemical Industry Co., Ltd. |
| Shanghai Ruizheng Technology Co., Ltd. |
| Idemitsu Kosan Co., Ltd. |
| Tanyun Chemicals |
| Orion Chem Pvt. Ltd. |
| Evonik Industries AG |
| Nippon Soda Co., Ltd. |
| Island Pyrochemical Industries |
| Cray Valley |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Shandong chemical cluster butadiene supply determines both aerospace-grade pricing spreads and regional logistics architecture for Asia-Pacific HTPB procurement. China's MEE emissions enforcement and GB chemical safety standards compress margin visibility for non-integrated producers while amplifying cost advantages for Zibo-based integrated operations.
Pricing Analysis
Cost-plus contracts indexed to 1,3-butadiene spot benchmarks dominate procurement between Shandong producers and Chinese state-owned defense contractors. Aerospace-grade material commands substantial premiums over industrial coating grades due to CDSCO and BIS certification requirements for ISRO and DRDO programs. Pricing pressure intensifies as polyether polyurethane binders capture lower-performance propellant niches. Industrial coating formulators exhibit highest price sensitivity, whereas solid rocket motor manufacturers prioritize lot-to-lot consistency over unit cost.
Supply Chain Analysis
Export-control regimes governing solid propellant precursor chemicals restrict technology transfer and cross-border material flows between Asia-Pacific defense programs. Supply concentrates in China's Shandong province, Japan's Kanto region, and emerging Maharashtra-Gujarat corridors in India. Raw material dependencies center on 1,3-butadiene monomer, organolithium catalysts, and hydroxyl-functionalizing reagents. Single-source vulnerability from Shandong environmental enforcement actions threatens regional availability. Distribution runs through direct sales channels for defense contractors and Japanese trading houses for industrial formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as China's CASC subsidiaries and India's ISRO collapse supplier rosters from multi-source to dual-source arrangements, compressing pricing leverage for non-qualified producers.
For Market Incumbents: Insulate qualified-supplier positions through backward integration into captive butadiene supply and accelerated BIS certification investment for India's defense indigenization programs. Polyether polyurethane substitution in lower-tier propellant applications threatens volume retention. Securing exclusive offtake agreements with prime contractors before contract renewal cycles represents the critical defensive lever. For New Entrants and Emerging Players: Build out bio-based butadiene pilot capabilities aligned with China's dual carbon policy funding streams to differentiate feedstock positioning. South Korean wind turbine blade manufacturers present the most penetrable non-defense segment for HTPB-modified epoxy toughening systems. Targeting composite materials applications through Busan-Ulsan industrial belt distributors offers faster trial-to-contract conversion than aerospace qualification pathways. For Investors and Strategic Acquirers: Specialized viscosity-control manufacturers with existing METI compliance infrastructure and JAXA qualification history represent priority acquisition archetypes for European-Asian supply corridor consolidation. Long-term viability hinges on regulatory digitization capabilities and machine learning-driven rheology prediction tool deployment. The signal to watch is accelerated procurement centralization under China's CASC chemical supply platforms, which would force portfolio repositioning toward domestic Indian producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butadiene | Captive feedstock supply shields margin compression from crude oil volatility for Shandong producers. |
| BIS Certification Investment | Domestic qualification pathways unlock ISRO and DRDO procurement under India's defense indigenization policies. |
| Green Manufacturing Transition | Bio-based butadiene pilot plants align with China's dual carbon goals and European aerospace export requirements. |
| Long-term Supply Agreement | Exclusive offtake contracts with CASC subsidiaries lock in volume before supplier roster consolidation completes. |
| Joint Venture | Technology partnerships with Japanese aerospace contractors accelerate METI-compliant viscosity-grade development. |
Study Parameters
Initial hypotheses were tested against primary input from solid propellant formulators, polymer plant managers, defense procurement officers, and chemical distribution channel partners and refined through secondary validation. Sources included customs and trade flow databases, GB standards documentation, BIS polymer specification filings, and SEC disclosures from multinational chemical producers. Bottom-up capacity modeling and top-down demand segmentation were triangulated to reconcile volume estimates.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions encompassed viscosity grade tiers, end-use industries spanning aerospace and wind energy, and regional production hub clusters. CAGRs were derived from regression analysis against defense budget trajectories and renewable energy installation forecasts. Industry-specific inputs included ISRO launch manifest projections and China's dual carbon policy implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Maharashtra-Gujarat chemical corridor entrants would shift outcomes toward price-based competition. Material shifts in Japan's METI chemical substance notification requirements or China's MEE emissions enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Bio Polyamide Market
Polymers & Resins
Fluorine Polymer Films Market
Polymers & Resins
Europe Polyolefin Foam Market
Polymers & Resins
Cyclic Olefin Polymers (COP) Polymer Syringes Market
Polymers & Resins
PEKK Market
Polymers & Resins
Middle East Engineering Plastics Market
Polymers & Resins
Polyether Block Amide Market
Polymers & Resins
Global Polypropylene Homopolymer (PPH) Market
Polymers & Resins
Synthetic and Bio Thermosets Market
Polymers & Resins
Global Thermoset Resin Market
Polymers & Resins
Cross-Linked Polyethylene (XLPE) Market
Polymers & Resins
Neoprene Market
Polymers & Resins
Polyethersulfone (PES) Market
Polymers & Resins
Middle East LLDPE Market
Polymers & Resins
North America Polyisoprene Market
Polymers & Resins
Polyurethanes (PU) Market