
 Paste PVC Resin Market | 2026-2036
Paste PVC Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Paste PVC Resin Market Outlook
Specialty chemical distribution is fragmenting as regional distributors lose leverage to direct procurement channels serving large-volume compounders. Formosa Plastics Corporation leverages captive chlorine integration to dominate Asian paste PVC supply chains. INEOS Group Limited anchors European demand through specialized K-value grades for medical and automotive applications. Westlake Corporation competes via tight control over VCM-to-paste verticality in North American markets.
Paste PVC resin is a suspension- or emulsion-polymerized polyvinyl chloride supplied as fine dispersible powder with K-values typically ranging from 55 to 80, designed for plastisol formulation where liquid plasticizers create paste systems for coating, dipping, or casting processes. Soft PVC formulations lead paste resin consumption in automotive underbody coatings and synthetic leather, while specialty PVC grades command premium positioning in medical device dipping applications due to stringent purity thresholds. Rigid PVC paste applications remain mature in construction coatings, though flexible PVC segments are gaining traction in protective films for consumer electronics.
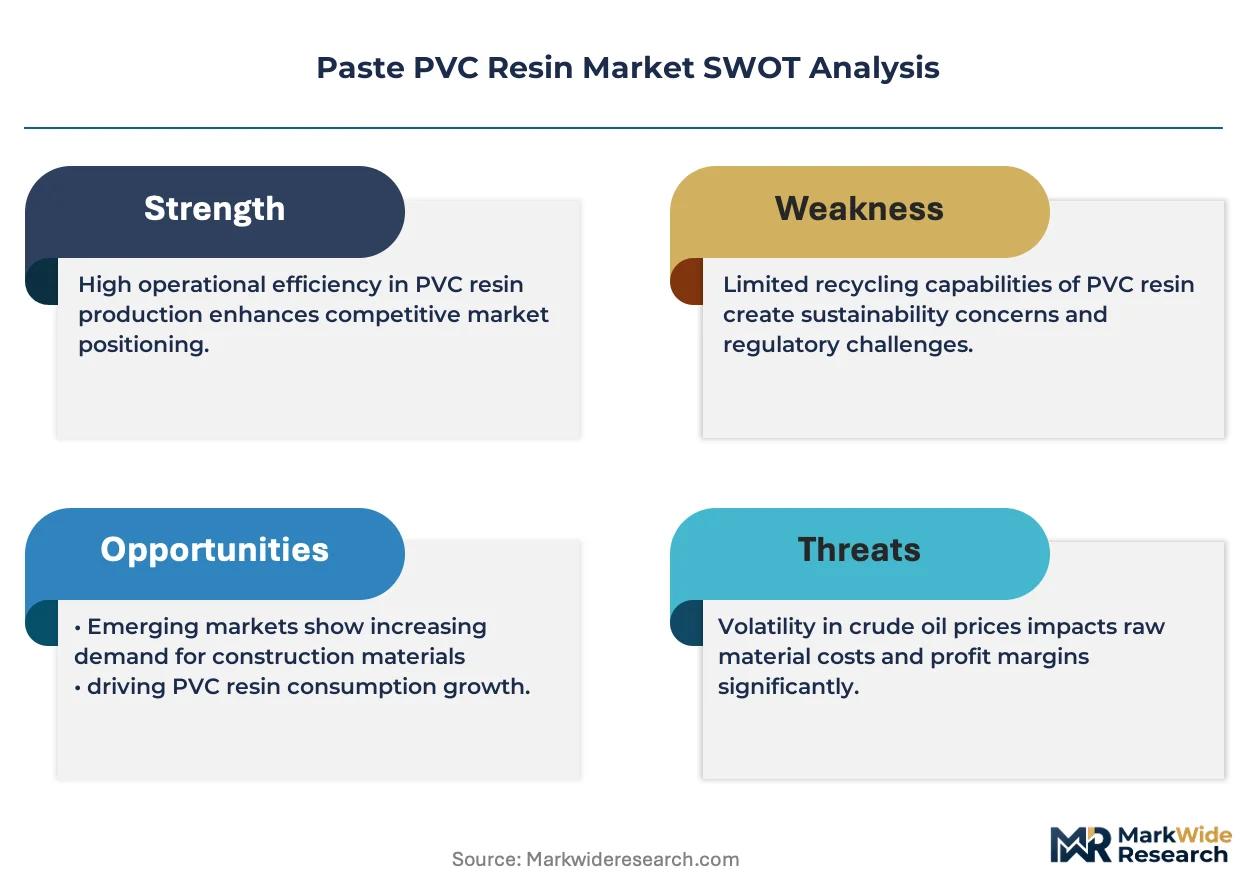
EPA regulates VCM emissions and residual monomer limits in US paste resin production facilities, while REACH governs phthalate plasticizer restrictions across European formulation supply chains. China's MEE enforces dual carbon goals that tighten energy intensity benchmarks for carbide-based PVC plants, reshaping regional cost structures. India's BIS certification requirements for flexible PVC in food-contact packaging create compliance barriers for unqualified imports. Stakeholders must monitor evolving plasticizer substitution pathways and carbon border adjustment mechanisms to align product portfolios with tightening chemical safety frameworks.
Market Dynamics
Plasticizer substitution pathways and tightening residual monomer thresholds are forcing reformulation investments across automotive and medical paste PVC supply chains. Carbide-based production economics face structural pressure from China's dual carbon enforcement.
Growth Catalysts
- Automotive interior expansion:Synthetic leather and underbody coating specifications are pulling paste resin volumes as OEMs specify soft-touch surfaces. Tier-1 compounders in Germany and China are scaling dedicated plastisol lines.
- REACH phthalate restrictions:European ECHA enforcement against legacy plasticizers is accelerating non-phthalate formulation adoption. Medical device manufacturers are qualifying new paste grades ahead of sunset dates.
- Carbide-PVC cluster consolidation:China's Inner Mongolia and Xinjiang regions are concentrating carbide-based paste resin capacity around integrated chlor-alkali complexes. Energy cost advantages are concentrating supply-side leverage.
Market Restraints
- Acetylene feedstock volatility:Calcium carbide production depends on metallurgical coke and electricity inputs. Price swings in Chinese thermal coal markets transmit directly to paste resin cost structures.
- VCM residual monomer limits:EPA maximum achievable control technology standards and REACH registration thresholds impose capital-intensive stripping equipment. Small-batch compounders face compliance cost barriers.
- Thermoplastic polyurethane substitution:TPU films and coatings are capturing premium synthetic leather applications. Paste PVC retains cost advantage only in high-volume dipping and rotational molding.
Strategic Opportunities
- India BIS certification gap:Food-contact flexible PVC regulations are creating qualified-supplier scarcity. Compounders with BIS-certified paste grades can capture import substitution demand.
- Biobased plasticizer convergence:Epoxidized soybean oil and citrate ester technologies are reaching cost parity with petrochemical alternatives. Formulators combining these with paste resins can access green procurement mandates.
- Direct procurement channels:Large-volume automotive and medical device manufacturers are bypassing distributors. Resin producers establishing compounder-direct technical service capabilities can defend margin position.
Industry Challenges
- Plastisol rheology expertise scarcity:Formulating stable paste systems requires specialized knowledge of particle size distribution and plasticizer absorption kinetics. Compounders report difficulty recruiting experienced technicians.
- Multi-jurisdiction certification timelines:Medical-grade paste resins require simultaneous USP Class VI, ISO 10993, and EP 3.1 compliance. Parallel testing protocols extend qualification cycles.
- Legacy compounding equipment retrofit costs:High-shear dispersion systems designed for suspension PVC require modification for paste resin handling. Capital allocation decisions are complicated by uncertain volume forecasts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paste PVC Resin Market |
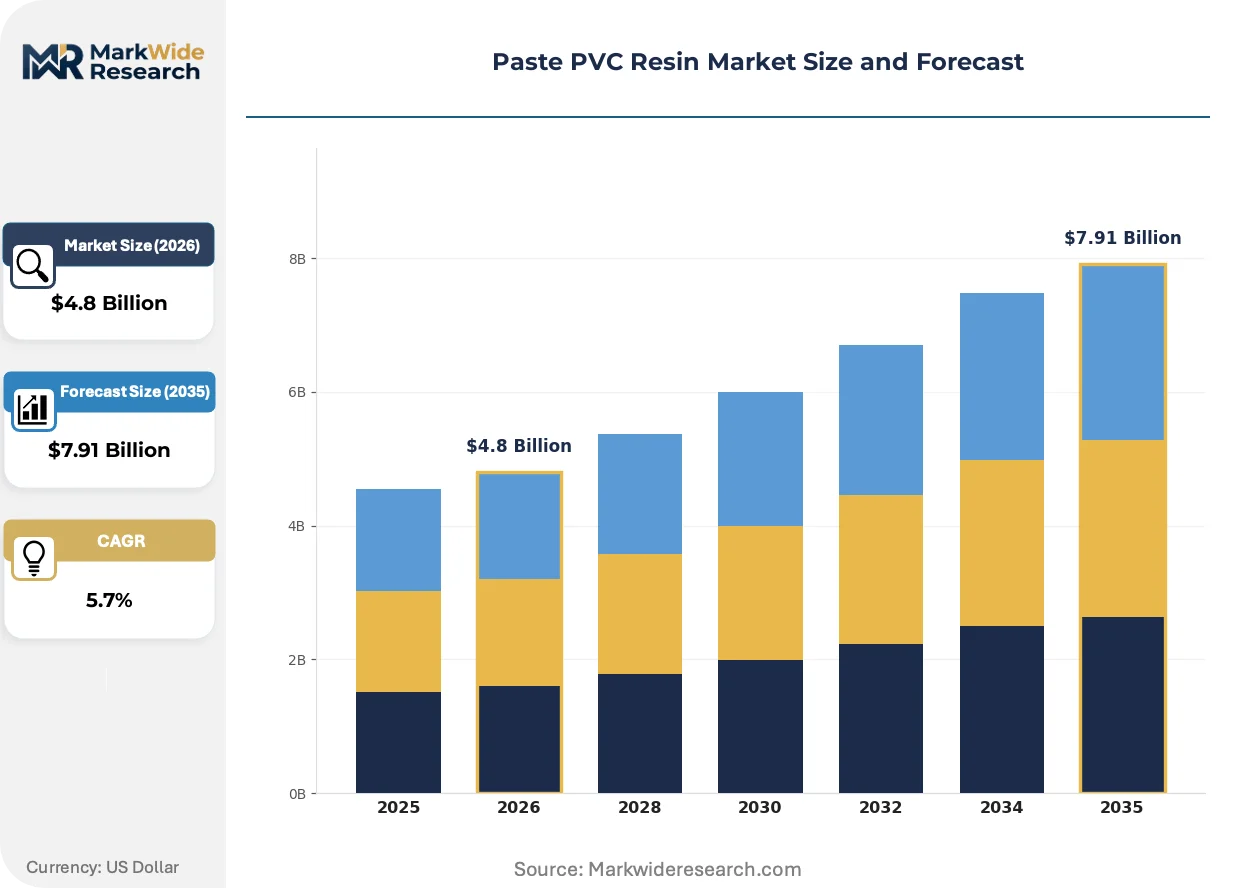
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft PVC, Rigid PVC, Specialty PVC, Flexible PVC Application: Coatings, Adhesives, Sealants, Films End User: Construction, Automotive, Consumer Goods, Packaging Distribution Channel: Direct Sales, Online Retail, Distributors, Others |
| Companies Covered | Formosa Plastics Corporation, Tosoh Corporation, INEOS Group Limited, SCG Chemicals Public Company Limited, Hanwha Solutions Corporation, Westlake Corporation, Chemplast Sanmar, Orbia, LG Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paste PVC Resin Market Strategic Shifts
Reformulation chemistry and digital process control are compressing development cycles for specialty paste grades. Regulatory disclosure requirements are reshaping supply chain transparency expectations.
Micro-suspension polymerization with controlled particle morphology is collapsing the performance gap between emulsion and suspension paste resins. Automotive sealant compounders are adopting these hybrid grades for improved flow control. The technology is collapsing premium pricing for traditional emulsion resins in medium-viscosity applications.
ECHA's SCIP database requirements under the Waste Framework Directive are forcing plasticizer traceability through formulation tiers. Compounders must now disclose full substance composition to downstream automotive and construction customers. Medical device manufacturers in Germany and France are accelerating supplier audits to preempt compliance gaps.
Buyer concentration among large automotive OEMs is compressing compounder margins and consolidating formulation decisions. Tier-1 suppliers are absorbing paste resin procurement directly from resin producers, displacing regional distributors. This pattern is most visible in Germany's automotive corridor and China's Yangtze River Delta manufacturing clusters.
Paste PVC Resin Market Segmentation
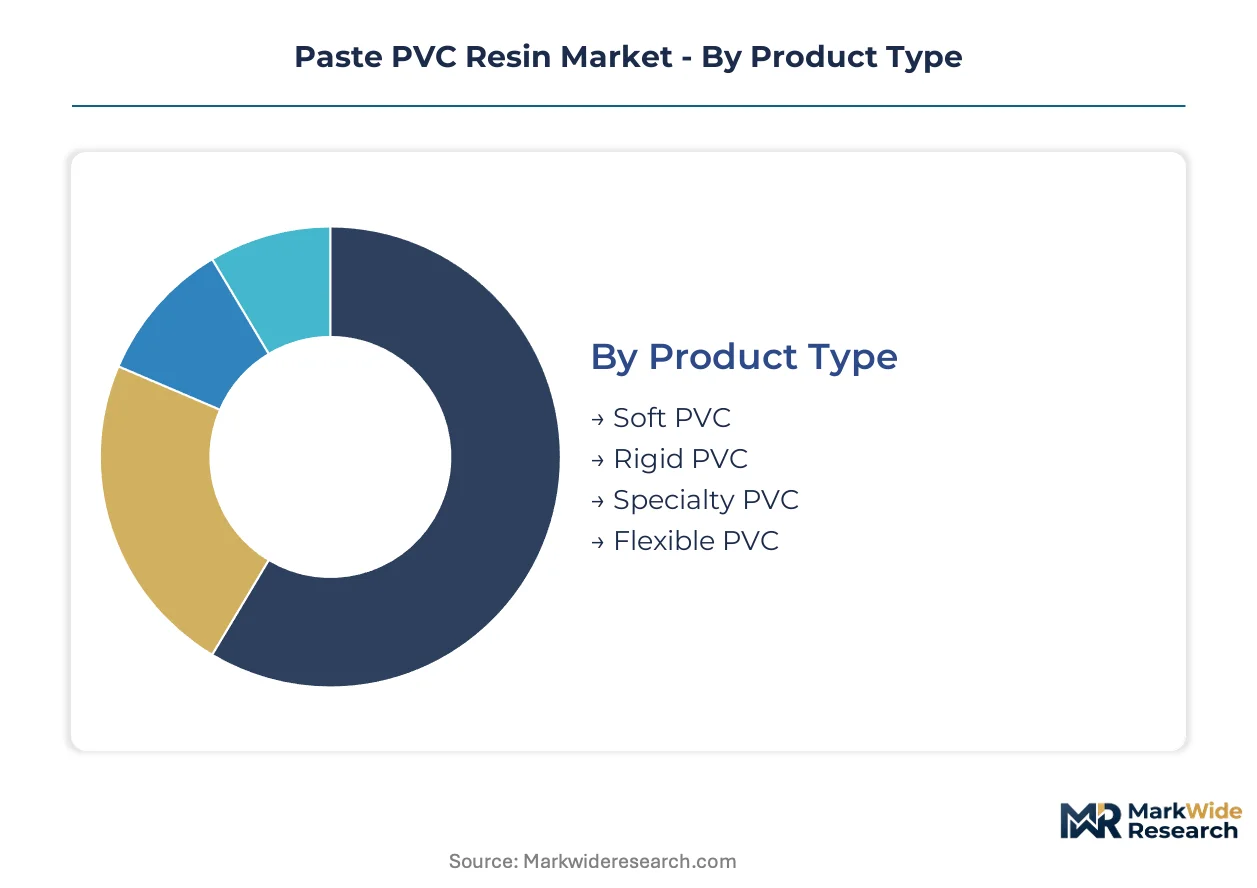
Paste PVC resin segmentation reveals how formulation chemistry and procurement patterns split across distinct value chains. Product type and application dimensions expose where technical service intensity concentrates, while end-user and channel splits show where margin capture diverges.
Product Type:
After-sales technical support intensity varies sharply across product categories, with specialty grades demanding sustained formulation partnership while commodity flexible grades require minimal ongoing service.
- Soft PVC:Plastisol systems formulated with high plasticizer loading for synthetic leather and underbody coatings. Automotive OEMs in Germany and China specify soft-touch interior surfaces, pulling volumes through Tier-1 compounders with dedicated plastisol lines. REACH phthalate restrictions are forcing non-phthalate reformulation investments.
- Specialty PVC:Ultra-low residual VCM grades with controlled particle morphology for medical device dipping. ISO 10993 and USP Class VI compliance requirements concentrate demand among qualified compounders serving catheter and glove manufacturers. Parallel certification timelines across jurisdictions extend supplier qualification cycles.
- Rigid PVC:Lower plasticizer absorption resins for construction coatings and protective films. Mature demand in building applications with limited technical service requirements.
- Flexible PVC:Mid-range K-value grades balancing processability and mechanical properties. Packaging and consumer goods applications dominate with price-sensitive procurement patterns.
Soft PVC holds the largest share; momentum sits with specialty PVC as medical purity thresholds tighten.
Application:
Volume concentration and margin structure diverge across application categories, with coatings commanding scale economies while sealants reward formulation expertise.
- Coatings:Dip and spray plastisol systems for metal finishing and fabric backing. Automotive underbody protection and synthetic leather backing drive demand in China's Yangtze River Delta manufacturing clusters. Micro-suspension polymerization advances are collapsing the performance gap between emulsion and suspension resin pricing.
- Films:Calendered and cast flexible films for consumer electronics protection and decorative laminates. Electronics manufacturers in South Korea and Japan specify low-VOC formulations for cleanroom compatibility.
- Adhesives:Paste resin binders for flooring and wall covering applications. Construction sector demand fluctuates with residential building cycles.
- Sealants:High-fill plastisol compounds for automotive seam sealing and construction joints. Rheology control requirements favor established compounders with particle dispersion expertise.
Coatings dominate volume; films are climbing the fastest as electronics protection specifications proliferate.
End User:
Procurement sophistication and regulatory exposure separate end-user categories, with automotive and medical device manufacturers driving transparency requirements down through supply tiers.
- Automotive:Interior synthetic leather, underbody coatings, and sealant specifications. ECHA's SCIP database requirements under the Waste Framework Directive force full plasticizer disclosure through formulation tiers. German and French OEMs are accelerating supplier audits to preempt compliance gaps.
- Construction:Flooring, wall coverings, and protective coatings. Mature demand with cyclical volume patterns tied to residential and commercial building activity.
- Consumer Goods:Synthetic leather for apparel, footwear, and accessories. TPU substitution pressure is most acute in premium positioning segments.
- Packaging:Flexible films and containers with food-contact compliance requirements. India's BIS certification creates qualified-supplier scarcity for import substitution opportunities.
Automotive commands premium pricing; packaging shows steepest expansion trajectory as food-contact regulations tighten in emerging markets.
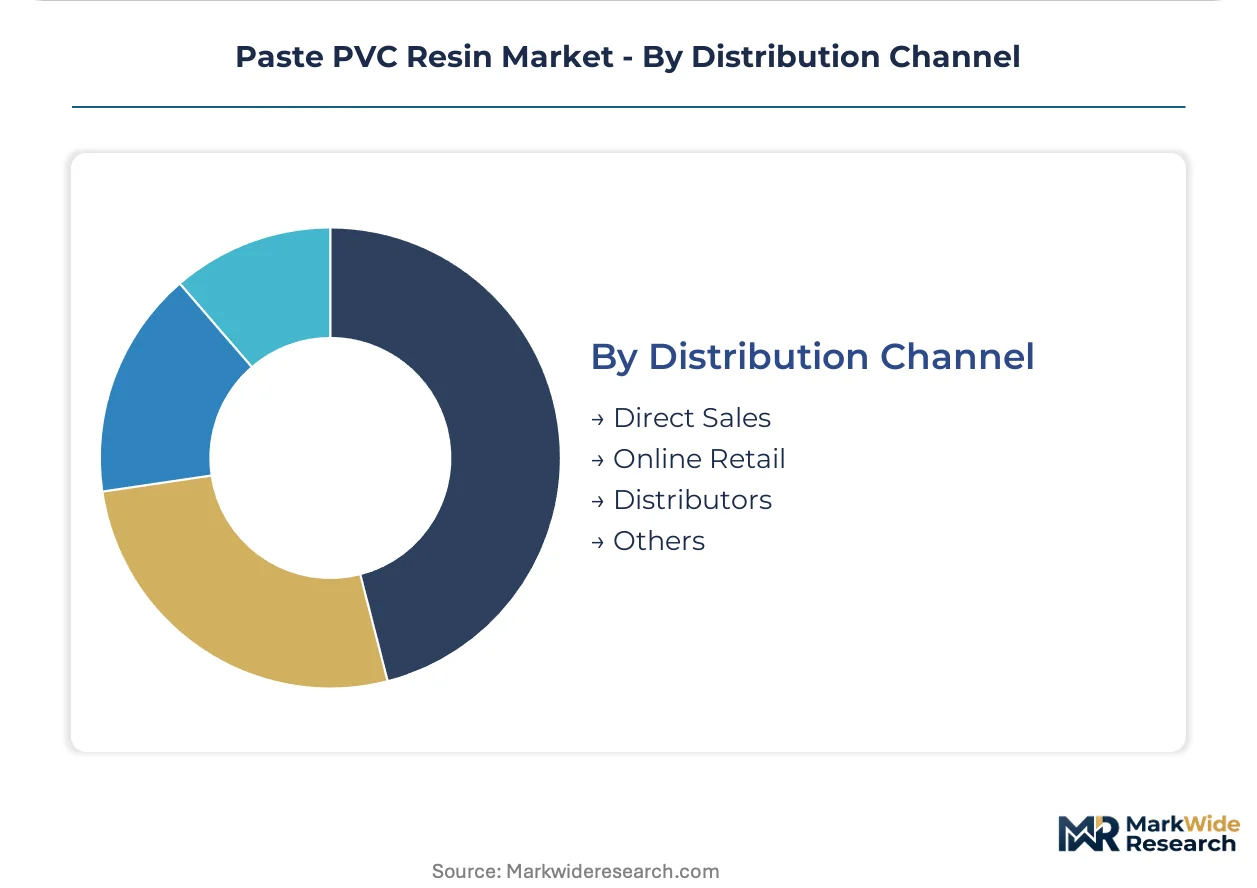
Distribution Channel:
Channel economics reflect buyer scale concentration, with large compounders extracting price concessions through direct procurement while smaller formulators remain distributor-dependent.
- Direct Sales:Producer-to-compounder relationships for high-volume automotive and medical device manufacturers. Technical service capabilities and qualification documentation support defend margin position against distributor bypass.
- Distributors:Regional chemical distributors serving mid-tier compounders and small-batch formulators. Leverage erosion as large buyers consolidate procurement decisions.
- Online Retail:E-procurement platforms for standardized grades and spot purchases. Limited penetration due to formulation technical support requirements.
- Others:Agent-based arrangements and cooperative purchasing structures. Fragmented presence in specialized regional markets.
Direct sales capture the highest value concentration; distributor channel faces ongoing displacement as buyer consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Chinese carbide-based paste resin clusters has decoupled from European ethylene-based production economics. Germany commands premium positioning through medical-grade purity thresholds. India's import substitution dynamics are reshaping qualified-supplier scarcity in food-contact applications.
China
Inner Mongolia and Xinjiang concentrate carbide-based paste resin capacity around integrated chlor-alkali complexes. MEE dual carbon enforcement tightens energy intensity benchmarks for legacy plants. Yangtze River Delta manufacturing clusters absorb volumes for automotive underbody coatings and synthetic leather backing.
Germany
Automotive OEMs in Stuttgart and Munich specify soft-touch interior surfaces, pulling volumes through Tier-1 compounders with dedicated plastisol lines. ECHA SCIP database requirements under the Waste Framework Directive force full plasticizer disclosure through formulation tiers. The Rhine-Ruhr industrial corridor anchors European medical-grade paste resin qualification.
India
Packaging manufacturers in Maharashtra and Gujarat face qualified-supplier scarcity for BIS-certified food-contact flexible PVC. CDSCO and FSSAI parallel enforcement creates compliance barriers for unqualified imports. The Delhi-Mumbai Industrial Corridor is consolidating compounding capabilities to capture substitution demand.
United States
EPA VCM emission standards and residual monomer limits impose capital-intensive stripping equipment on production facilities. Gulf Coast petrochemical corridors leverage ethylene feedstock integration for suspension-grade paste resin economics. Automotive assembly concentrations in Michigan and the Southeast sustain underbody coating specifications.
Japan
Electronics manufacturers in Kanto and Kansai specify low-VOC paste formulations for cleanroom-compatible protective films. METI chemical safety frameworks align with REACH-equivalent disclosure requirements. Nagoya automotive suppliers qualify specialty grades for sealant applications with stringent rheology control.
Paste PVC Resin Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with formulation chemistry leverage. The vendor base stratifies around captive chlorine integration, specialized K-value grades, and regional distribution density. Three archetypes dominate: integrated petrochemical conglomerates with backward control over VCM supply, mid-scale compounders with medical certification depth, and regional distributors facing displacement from direct procurement channels. Competitive moves concentrate on M&A for qualification portfolios and capacity consolidation around energy-advantaged carbide clusters.
Within the integrated conglomerate tier, Formosa Plastics Corporation and INEOS Group Limited exemplify divergent geographic anchoring strategies. Formosa Plastics leverages Taiwanese chlor-alkali integration to dominate Asian paste PVC supply chains. INEOS occupies a position as the European anchor through specialized K-value grades for medical and automotive applications. Westlake Corporation represents North American verticality in VCM-to-paste production.
| Leading Market Players |
|---|
| Formosa Plastics Corporation |
| Tosoh Corporation |
| INEOS Group Limited |
| SCG Chemicals Public Company Limited |
| Hanwha Solutions Corporation |
| Westlake Corporation |
| Chemplast Sanmar |
| Orbia |
| LG Chem |
| Others |
Value Chain & Pricing Dynamics
Inner Mongolia's carbide-based paste resin clusters concentrate capacity around integrated chlor-alkali complexes, translating electricity cost advantages into downstream pricing leverage for high-volume flexible grades. This geographic anchoring reshapes how compounders negotiate contract structures across automotive and medical supply tiers.
Pricing Analysis
Configured-to-order pricing for specialty medical grades commands substantial premiums over standard flexible formulations. Three-tier pricing structure across premium, standard, and economy levels segments by certification intensity and residual VCM thresholds. Pricing pressure stems from TPU substitution in synthetic leather applications, compressing margins in mid-range soft PVC tiers. Automotive OEMs exhibit lowest price sensitivity due to specification lock-in, while packaging compounders face acute cost compression from import competition.
Supply Chain Analysis
Calcium carbide and metallurgical coke feedstock dynamics in China, ethylene chain economics in the United States, and chlorine integration in Germany anchor regional cost structures. VCM monomer, plasticizer compounds, and energy inputs constitute critical input dependencies. Single-source vulnerability concentrates in carbide-based production corridors exposed to thermal coal price volatility. Distribution runs through direct producer-to-compounder channels for automotive and medical volumes, with regional distributors serving fragmented construction and consumer goods formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paste PVC resin operates as a regulatory-entrenchment defensive moat where multi-jurisdiction certification timelines and qualified-supplier scarcity protect incumbent positions. Switching costs compound as automotive OEMs and medical device manufacturers absorb years-long qualification investments.
For Market Incumbents: Build certification-depth moats by accelerating parallel USP Class VI and ISO 10993 qualification pipelines ahead of REACH sunset dates. Expand captive chlorine integration into Xinjiang carbide corridors to capture energy cost advantages. Consolidate formulation technical service teams around Yangtze River Delta automotive clusters to defend against distributor displacement. For New Entrants and Emerging Players: India's BIS-certified food-contact flexible PVC segment represents the most penetrable entry point given qualified-supplier scarcity and import substitution tailwinds. Maharashtra and Gujarat packaging manufacturers offer anchor customer relationships for compounders investing in CDSCO compliance infrastructure. Partner with established chlor-alkali producers for toll manufacturing arrangements rather than greenfield capacity builds. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because carbide-PVC cluster economics favor scale concentration around energy-advantaged production hubs. Target acquisition archetypes include mid-scale compounders with medical certification depth and established automotive Tier-1 relationships. Monitor ECHA enforcement patterns against legacy phthalate plasticizers as inflection signal for non-phthalate formulation adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VCM Supply | Captive chlorine economics in Inner Mongolia and Xinjiang reshape regional cost competitiveness. |
| Medical Certification Portfolio Expansion | Parallel USP Class VI and ISO 10993 qualifications extend supplier lock-in with device manufacturers. |
| Non-Phthalate Formulation R&D | Epoxidized soybean oil and citrate ester convergence opens green procurement mandate access. |
| Direct Technical Service Investment | Producer-to-compounder relationships bypass distributor erosion in automotive procurement consolidation. |
| Carbide Cluster Capacity Consolidation | MEE dual carbon enforcement accelerates closure of subscale legacy plants in energy-intensive corridors. |
Study Parameters
Cross-validation between primary fieldwork with resin producers and secondary trade data anchors the qualitative findings. Plant managers at carbide-based facilities, procurement leads at automotive Tier-1 compounders, distribution channel partners serving construction formulators, and technical R&D directors at medical-grade specialists provided operational perspective. Customs and trade databases, ACC and Cefic industry reports, SEC 10-K filings from integrated petrochemical conglomerates, and MEE environmental enforcement records furnished quantitative validation. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Calibration against historical price elasticities and substitution dynamics across plasticizer chemistries refines projection parameters. Segmentation dimensions span grade tier (specialty, soft, flexible, rigid), end-use industry (automotive, medical, construction, packaging, consumer goods), and regional production hub configuration. CAGRs derive from slope analysis of segment-specific adoption curves and input cost trajectory assumptions. VCM residual monomer regulatory thresholds and biobased plasticizer cost parity timelines constitute key forecast inputs.
Practitioners should monitor thermal coal price volatility in Chinese energy markets and ECHA enforcement intensity against legacy phthalates for early signals of margin compression or formulation disruption. Cross-checking against IHS Markit chemical price benchmarks and Cefic production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polymer Microspheres Market
Polymers & Resins
United States Polyols Market
Polymers & Resins
North America Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Hair Styling Biopolymers Market
Polymers & Resins
Homopolymer Resins Market
Polymers & Resins
MDI, TDI, and Polyurethane Market
Polymers & Resins
Global Protein a Resin Market
Polymers & Resins
Global Alkyd Resin Market
Polymers & Resins
Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market
Polymers & Resins
Lactic Acid and Polylactic Acid Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
PCR Polyolefins Market
Polymers & Resins
India Polyacrylamide Copolymer Market
Polymers & Resins
Global Bio-Based Polyethylene Market
Polymers & Resins
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Brazil Engineering Plastics Market