
 Packaged Cactus Water Market | 2026-2036
Packaged Cactus Water Market Size, Share, and Industry Trends Forecast 2026-2036
Packaged Cactus Water Market Intelligence
Demand from health-conscious consumers is consolidating around brands that offer functional benefits beyond simple hydration. Caliwater leverages celebrity endorsements and social media marketing to build its brand presence in key urban markets. True Nopal Ventures LLC specializes in pure, unsweetened cactus water, targeting beverage purists. Steaz competes by incorporating cactus water into its established line of organic green tea beverages, reaching a different consumer segment.
Packaged cactus water is a beverage derived from the fruit of the Opuntia ficus-indica, or prickly pear cactus. Its production often involves cold-pressing the fruit puree to preserve natural electrolytes, betalains, and antioxidants for use as a functional hydration drink. The organic product type commands a premium, while flavored options are expanding the consumer base. Supermarkets and specialized health stores remain the core distribution channels, though online retail is gaining share.
Labeling and health claims are shaped by national food safety authorities. The US FDA's regulations on nutrient content claims and the term "natural" directly impact marketing strategies. In Europe, EFSA guidelines on health claims and the EU's novel food regulations govern market access for new formulations. Future brand success will hinge on securing certified organic supply chains and navigating distinct labeling laws across international markets.
Market Dynamics
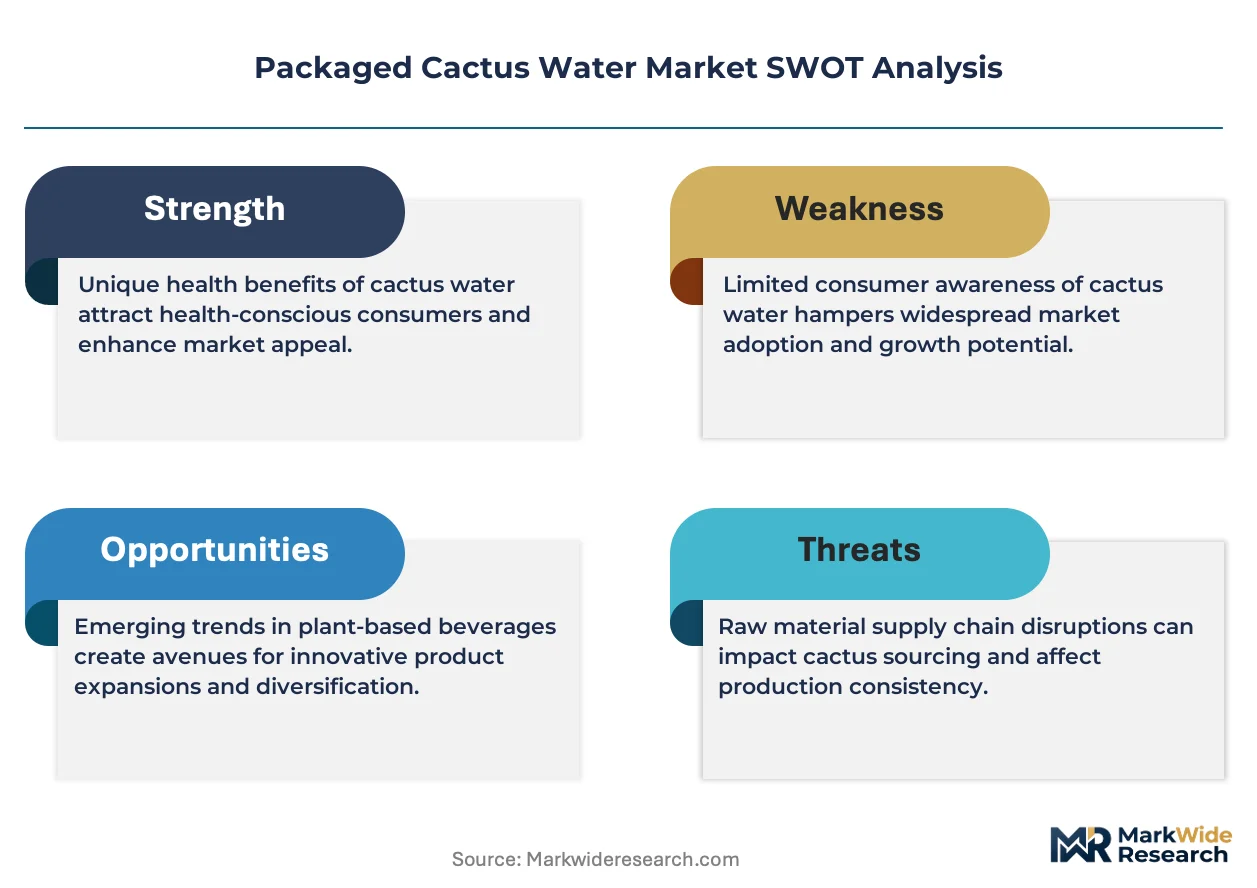
The central force shaping the packaged cactus water market is the conflict between consumer demand for functional health benefits and the intensifying regulatory scrutiny over nutrient content and "natural" marketing claims by authorities like the FDA and EFSA.
Growth Catalysts
- Functional Beverage Demand:Strong consumer interest in low-sugar, plant-based hydration alternatives in markets like the United States and Canada provides a foundational demand driver, especially among wellness-focused demographics seeking functional ingredients like betalain antioxidants.
- Processing Advancements:The adoption of cold-pressing and High-Pressure Processing (HPP) technologies allows for the creation of clean-label products with longer shelf stability and better preservation of natural electrolytes, justifying premium price points.
- Organic Certification:The availability of USDA and EU organic certifications for Opuntia ficus-indica puree serves as a key market catalyst, enabling brands to access premium retail channels and meet demand from discerning consumers.
Market Restraints
- Supply Chain Concentration:The cultivation of prickly pear cactus is concentrated in specific arid climates, primarily in Mexico and the Southwestern US, creating vulnerability to localized climate events and logistical disruptions that can impact raw material costs.
- Dominant Substitutes:The market faces intense competition from established plant-based waters, particularly coconut water, which benefits from a more mature global supply chain, lower price points, and widespread consumer familiarity.
- High Input Costs:The expense and lengthy process associated with obtaining organic certification for cactus fruit farms present a significant structural barrier, limiting the pool of qualified suppliers and inflating production costs for certified products.
Strategic Opportunities
- Ingredient Diversification:There is an opportunity to position cactus water puree as a functional ingredient for other food and beverage categories, such as ready-to-drink cocktails, frozen desserts, and yogurts, expanding its application beyond a standalone beverage.
- Channel Expansion:Developing direct-to-consumer (DTC) subscription models can build brand loyalty and capture recurring revenue, bypassing the competitive shelf space constraints of traditional supermarkets and health food stores.
- Geographic Expansion:Underpenetrated markets in the Middle East and affluent parts of Asia-Pacific represent a significant growth opportunity, where rising disposable incomes and wellness trends create a receptive audience for novel functional beverages.
Industry Challenges
- Labeling Harmonization:Brands face the operational challenge of developing packaging and marketing claims that comply with disparate regulations, such as the FDA's rules on "healthy" claims in the US and EFSA's stricter health claim guidelines in Europe.
- Organic Supply Scalability:A primary challenge is securing a consistent, scalable, and certified organic supply of prickly pear fruit puree that meets quality specifications, which currently constrains rapid production growth for many brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaged Cactus Water Market |
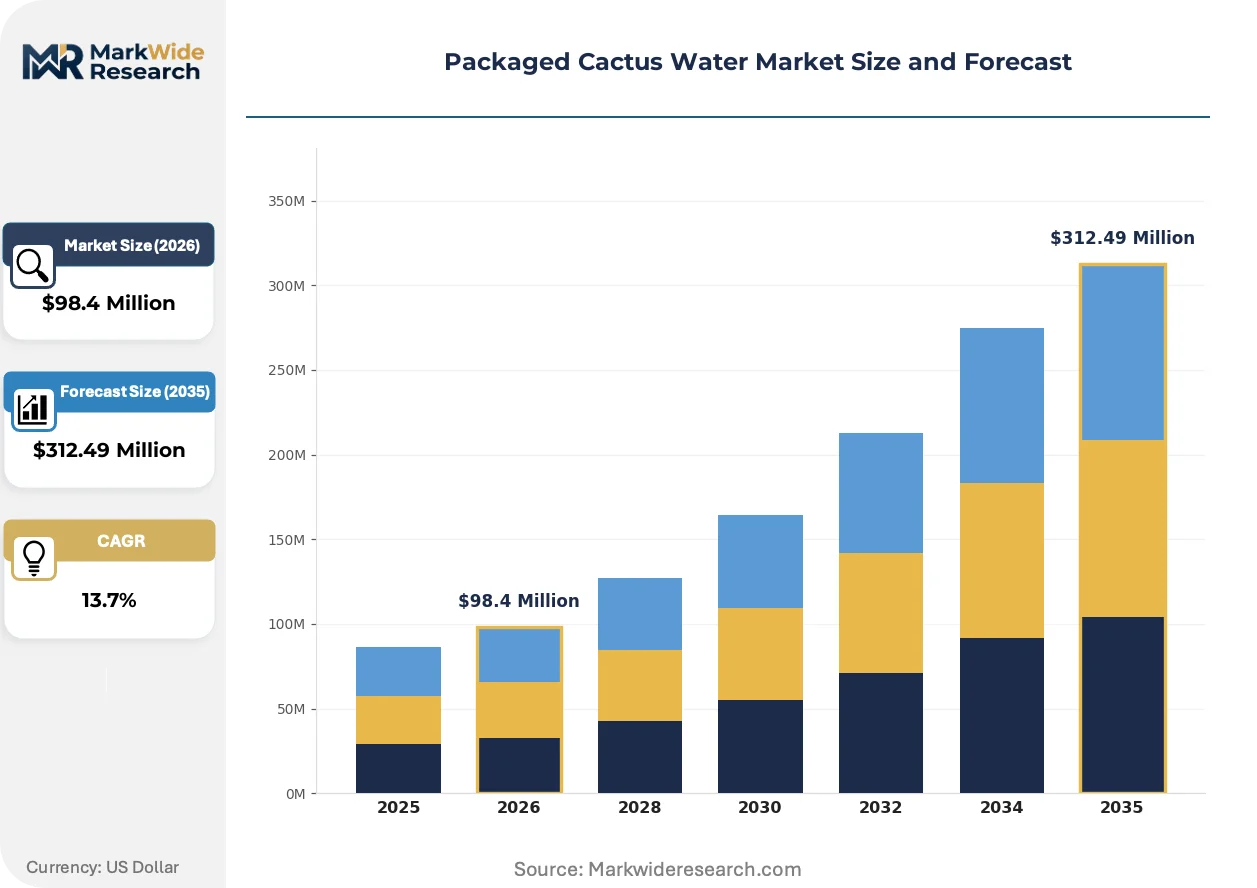
| Market Size in 2026 | $98.4 Million |
| Market Size in 2035 | $312.49 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Flavored, Pure, Carbonated Distribution Channel: Online Retail, Supermarkets, Health Stores, Convenience Stores Packaging Type: Bottled, Tetra Pak, Canned, Pouch End User: Fitness Enthusiasts, Health Conscious Consumers, Restaurants, Hotels |
| Companies Covered | Evissi USA LLC, Steaz, Caliwater, BetterDays, Lauro Company LLC, True Nopal Ventures LLC, The Cactus Water Co. LLC, Green-Go, Pricklee LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaged Cactus Water Market Strategic Shifts & Innovations
The market is advancing from a niche novelty into a more defined functional beverage category. This maturation is driven by the interplay of food science innovations that validate health benefits and stricter regulatory frameworks that standardize product claims.
High-Pressure Processing (HPP) is a non-thermal pasteurization technique that preserves the flavor and nutritional profile of cactus water. Premium and organic-focused brands are rapidly adopting HPP to substantiate clean-label marketing and justify higher price points. The premium segment is absorbing the technology's higher operational costs, compressing the viability of products using traditional heat pasteurization.
Regulatory bodies are enacting stricter controls on beverage marketing. The US FDA's modernization of nutrient content claims for terms like "healthy" is forcing reformulation to reduce or eliminate added sugars in flavored varieties. Brands are responding by shifting to natural, non-caloric sweeteners like monk fruit or stevia to maintain compliance while meeting consumer taste preferences.
Consumer purchasing behavior is pivoting from incidental retail discovery to intentional, recurring online acquisition. This shift is disintermediating traditional health food stores in favor of brand-owned direct-to-consumer (DTC) e-commerce sites and third-party platforms like Amazon. The trend is most advanced in urban centers across the United States and Western Europe, supported by sophisticated logistics networks.
Packaged Cactus Water Market Segmentation
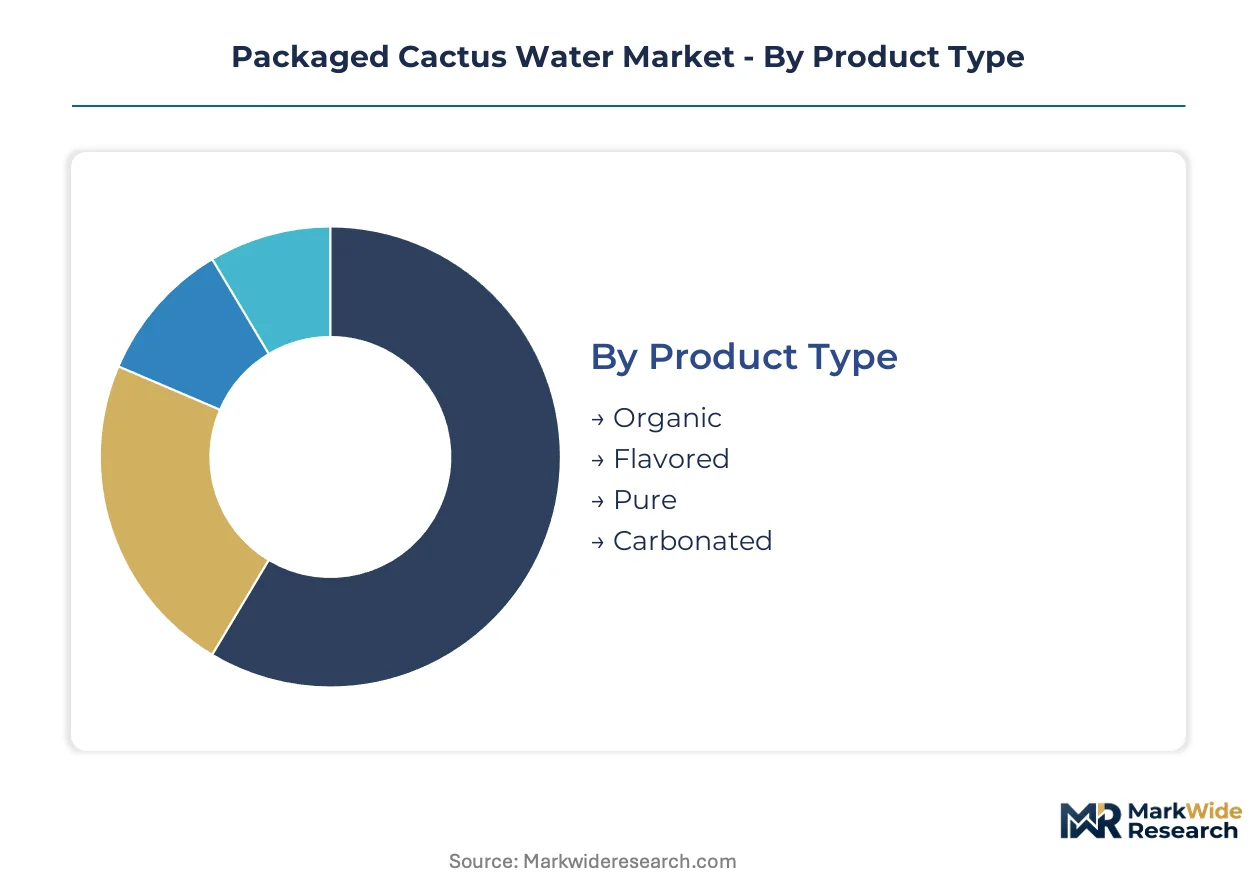
Understanding the segmentation of the packaged cactus water market reveals how diverse consumer needs and operational considerations influence product development and market penetration. This analysis dissects the market into distinct categories, each reflecting specific attributes that drive purchasing decisions and channel effectiveness. Each segment plays a vital role in the overall market structure.
Product Type:
The product type segmentation highlights the market's balance between highly customized formulations and standardized offerings.
- Organic:This product type adheres to strict agricultural and processing standards, ensuring no synthetic pesticides or fertilizers are used. Demand concentrates in the United States and Germany, where consumers prioritize clean-label ingredients and perceive enhanced health benefits from certified organic products.
- Flavored:These products incorporate natural fruit extracts or other botanicals to enhance taste, often using non-caloric sweeteners like monk fruit or stevia. Demand is strong in urban centers across Canada and the United Kingdom, driven by consumers seeking palatable alternatives to plain water without added sugars.
- Pure:This segment comprises unadulterated cactus water, offering the natural taste and functional benefits of the prickly pear fruit.
- Carbonated:Carbonated cactus water provides a sparkling beverage option, appealing to consumers desiring effervescence in their functional drinks.
Leading the category by volume: Pure. Growing fastest: Flavored.
Distribution Channel:
Distribution channels reflect varying levels of market maturity and consumer purchasing habits.
- Supermarkets:These large-format retail stores offer broad product assortments and competitive pricing, making them a primary channel for mass-market reach. Consumer purchasing behavior in France and Spain frequently includes functional beverages as part of regular grocery shopping.
- Online Retail:E-commerce platforms, including brand-owned direct-to-consumer sites and third-party marketplaces, provide convenience and extensive product information. This channel thrives in the United States and Japan, where sophisticated logistics networks support rapid delivery and subscription models.
- Health Stores:Specialized health food stores cater to niche consumer segments seeking premium, organic, and functional food and beverage options.
- Convenience Stores:These smaller retail outlets offer quick access for on-the-go consumption, focusing on single-serve packaged beverages.
Online retail channels are expanding most quickly, while supermarkets maintain the largest market footprint.
Packaging Type:
Packaging type directly influences consumer convenience and product shelf-life across different consumption scenarios.
- Bottled:Typically made from PET plastic or glass, bottles offer resealability and visibility of the product, dominating single-serve and multi-serve formats. This packaging is prevalent in Mexico and Australia, balancing cost-effectiveness with consumer familiarity.
- Tetra Pak:These aseptic cartons provide extended shelf life without refrigeration and are often perceived as more environmentally friendly due to their recyclable nature. Adoption is rising in Germany and Sweden, driven by sustainability initiatives and demand for shelf-stable products.
- Canned:Aluminum cans offer durability, portability, and complete light protection, suitable for carbonated varieties and outdoor activities.
- Pouch:Flexible pouches provide lightweight and compact packaging, often used for smaller, single-serving portions or concentrated purees.
Bottled formats capture the majority of sales, with Tetra Pak solutions climbing the fastest due to sustainability efforts.
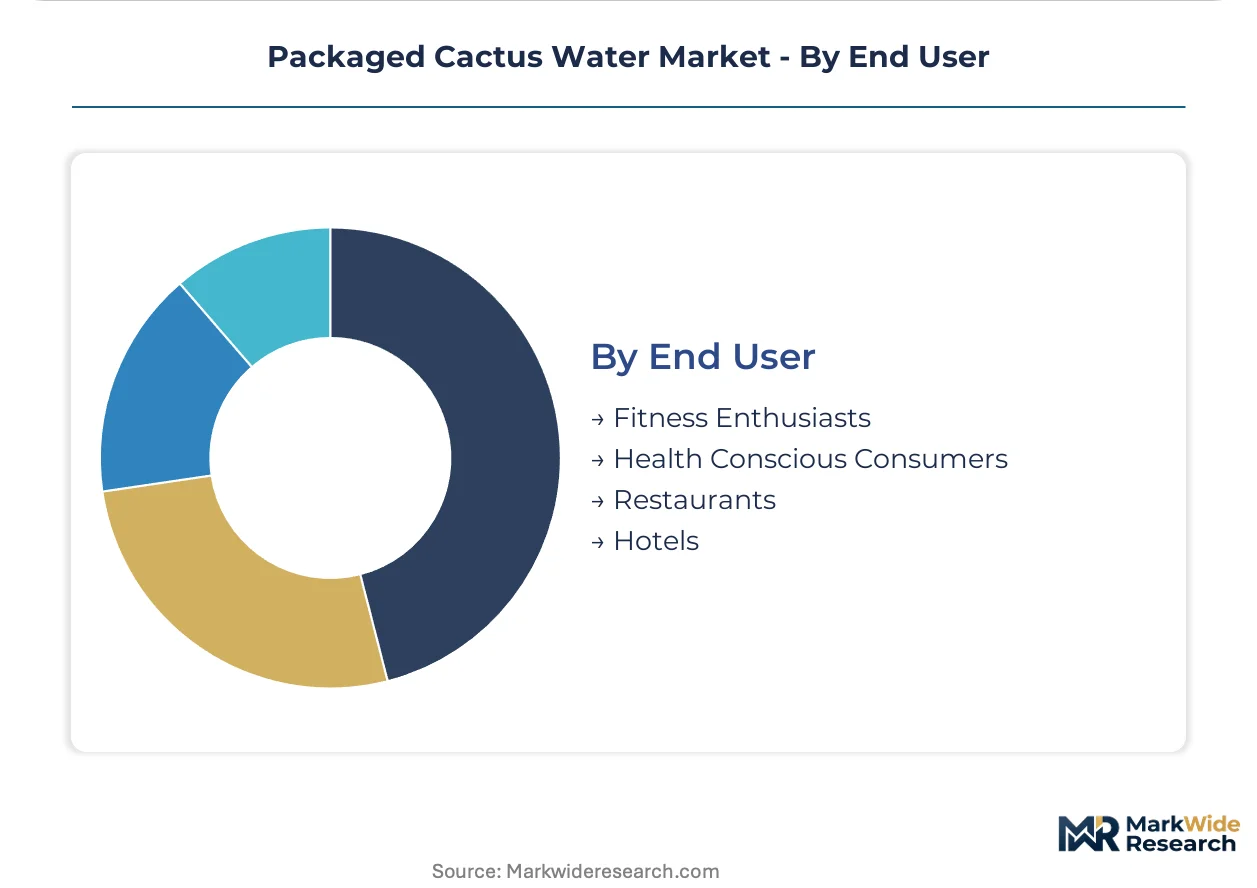
End User:
End-user categories are defined by distinct motivations driving the consumption of functional beverages.
- Health Conscious Consumers:This demographic actively seeks products with perceived health benefits, such as antioxidants, electrolytes, and low sugar content, aligning with broader wellness trends. This segment is robust in the United States and the United Kingdom, driven by proactive health management.
- Fitness Enthusiasts:Individuals engaged in regular physical activity consume cactus water for hydration and electrolyte replenishment, often preferring natural and plant-based options over synthetic sports drinks. This user group is prominent in Canada and the Netherlands, integrating functional beverages into their active lifestyles.
- Restaurants:Food service establishments incorporate cactus water into beverage menus, offering it as a standalone drink or as an ingredient in cocktails and mocktails.
- Hotels:Hospitality venues provide cactus water as a premium beverage option for guests, often in mini-bars or wellness-focused amenities.
Health-conscious consumers represent the largest segment, while fitness enthusiasts demonstrate steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North American agricultural zones, particularly those in Mexico and the Southwestern United States, concentrate the raw material supply for packaged cactus water. These regions benefit from arid climates essential for prickly pear cultivation, supporting a burgeoning industry. Strong demand for functional beverages in key urban centers further drives market development and product innovation.
United States
Demand for low-sugar, plant-based hydration alternatives underpins market expansion in the United States. The US FDA's regulations on nutrient content claims shape marketing strategies for functional benefits. Urban centers like Los Angeles and New York City are primary consumption hubs for novel wellness beverages.
Mexico
Mexico serves as a primary cultivation hub for Opuntia ficus-indica, providing a critical raw material supply for the global market. Government programs supporting agricultural exports and sustainable farming practices encourage local production. Arid regions in Sonora and Baja California are key cultivation areas for prickly pear cactus.
Germany
German consumers prioritize certified organic products, driving demand for premium packaged cactus water. EFSA guidelines on health claims and novel food regulations influence market access for new formulations. Cities like Munich and Berlin show strong adoption of sustainable Tetra Pak packaging solutions.
Canada
Canadian wellness-focused demographics seek functional ingredients like betalain antioxidants in their beverage choices. Health Canada's food labeling requirements ensure transparency for nutrient content. Toronto and Vancouver are significant hubs for plant-based beverage trends and distribution.
United Kingdom
Consumers in the United Kingdom increasingly seek palatable alternatives to plain water with added functional benefits. The UK Food Standards Agency (FSA) provides guidance on food information to consumers. London's health food stores and online retail platforms stock diverse functional beverage options.
Packaged Cactus Water Market Key Industry Players
Top-tier vendors anchor the premium segment with strong brand narratives and certified organic offerings, while smaller, agile brands target niche consumer preferences. The market structure exhibits a tiered approach, with companies differentiating through product purity and functional claims. Strategic archetypes include lifestyle brands, pure-play specialists, and diversified beverage companies leveraging existing distribution. Competitive moves focus on securing certified organic supply chains and expanding distribution channels.
Specialists in brand building and niche positioning include Caliwater, which leverages celebrity endorsements to build brand presence. True Nopal Ventures LLC occupies a position as a pure-play specialist, focusing on unsweetened cactus water for beverage purists. Steaz exemplifies diversification by incorporating cactus water into its established line of organic green tea beverages, reaching distinct consumer segments.
| Leading Market Players |
|---|
| Evissi USA LLC |
| Steaz |
| Caliwater |
| BetterDays |
| Lauro Company LLC |
| True Nopal Ventures LLC |
| The Cactus Water Co. LLC |
| Green-Go |
| Pricklee LLC |
| Others |
Cost & Logistics Intelligence
Vertical integration into raw material sourcing anchors both the supply position and pricing power for packaged cactus water brands. This strategic control minimizes reliance on volatile spot markets and secures consistent quality for premium products.
Pricing Analysis
Premium pricing for short lead times reflects the high demand for certified organic cactus water. Contract-based long-term offtake agreements secure raw material, influencing final product costs. Organic certification and strong brand presence drive price differentiation. Pricing softness emerges from intense competition with established plant-based waters like coconut water. Health-conscious consumers show lower price sensitivity for certified organic options, while mass-market supermarket buyers remain highly price-sensitive.
Supply Chain Analysis
Regional distribution centers facilitate efficient delivery of packaged cactus water from production hubs to consumer markets. Geographic supply concentration for Opuntia ficus-indica fruit puree centers in Mexico and the Southwestern United States. The industry relies heavily on consistent yields of prickly pear fruit puree and specialized packaging materials. Localized climate events in cultivation regions present a significant structural risk, impacting raw material availability. Distribution runs through a dual model, balancing mass-market supermarkets with expanding online retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play, driven by intensifying regulatory scrutiny over nutrient content claims forcing out less compliant brands.
For Market Incumbents:
Anticipate continued regulatory pressure from authorities like the US FDA and EFSA on "healthy" claims. Secure long-term, certified organic supply contracts to mitigate raw material volatility and ensure product integrity. Invest in High-Pressure Processing (HPP) technology to preserve nutritional benefits and justify premium pricing. Diversify product lines with novel flavor profiles using natural sweeteners to counter competition from established beverage giants.
For New Entrants and Emerging Players:
Launch via direct-to-consumer (DTC) subscription models to build brand loyalty in urban centers. Target underpenetrated markets in the Middle East and affluent Asia-Pacific regions, where wellness trends are emerging. Position cactus water puree as a functional ingredient for other food and beverage categories, such as ready-to-drink cocktails or yogurts. Focus on sustainability messaging and transparent sourcing to appeal to discerning consumer segments.
For Investors and Strategic Acquirers:
Exit pathways concentrate in acquiring clean-label specialists with established organic supply chains and strong DTC presences. The long-term viability of the functional beverage market remains robust, supported by sustained consumer shifts towards plant-based hydration. Target acquisition archetypes include brands with proprietary processing technologies like HPP or unique flavor formulations. Watch for regulatory harmonization across international markets as a key inflection indicator for broader market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure Certified Organic Supply | Ensures consistent raw material quality and meets premium consumer demand. |
| Invest in HPP Technology | Preserves nutrients and flavor, justifying higher price points for clean-label products. |
| Expand Direct-to-Consumer Channels | Builds brand loyalty and reduces reliance on competitive retail shelf space. |
| Develop Functional Ingredient Applications | Diversifies revenue streams beyond standalone beverages into new categories. |
| Target Underpenetrated Geographic Markets | Captures new consumer bases in regions with rising disposable incomes and wellness trends. |
Research Approach
Multi-period observation of consumer wellness trends, regulatory shifts, and raw material pricing anchored the trend analysis, supplemented by interviews. Primary research involved discussions with beverage brand executives, organic prickly pear farm operators, food scientists specializing in functional ingredients, and retail category buyers. This primary data was triangulated against secondary sources including USDA organic standards, EFSA health claim guidelines, beverage industry trade reports, and national customs data on fruit puree imports.
Input-output matrices informed the forecast framework, modeling market dynamics over the projection horizon. Segmentation dimensions modeled included product type, distribution channel, packaging type, end user, and organic certification level. Compound annual growth rates were derived from historical data analysis and projected market drivers. Key industry-specific forecast inputs included prickly pear cultivation yields and consumer spending patterns on functional beverages.
Unforeseen climate events affecting harvests, sudden shifts in regulatory frameworks, and significant entry of new substitute products are the dominant revision risks. Forecasts reflect assumptions documented throughout the analysis. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Bottled Deep Ocean Water Market
Beverages
Bubble Food and Beverages Market
Beverages
Milk Tea Powder Market
Beverages
Asia Pacific Soy Beverages Market
Beverages
North America Sugar Free Energy Drinks Market
Beverages
Soft Serve Premix Market
Beverages
Ready to Drink Premixes Market
Beverages
GCC Juice Market
Beverages
United States Recovery Drinks Market
Beverages
Coconut Milk Beverages Market
Beverages
North America Energy Drink Market
Beverages
Bottled Beverages Market
Beverages
Sparkling Bottled Water Market
Beverages
Kombucha Market
Beverages
Dairy Based Beverages Market
Beverages
Spring Water Market