
 Sparkling Bottled Water Market | 2026-2036
Sparkling Bottled Water Market Size, Share, and Industry Trends Forecast 2026-2036
Sparkling Bottled Water Market Outlook
Market Context
The EU Green Deal is decoupling carbon footprint accountability from traditional packaging economics across European sparkling water markets. Danone leverages its integrated spring-to-bottle network to sustain margin resilience under tightening emissions rules. PepsiCo anchors North American volume through direct-store-delivery infrastructure that controls shelf presence. Nestlé Waters differentiates via premium sourcing narratives that command price premiums in specialty retail channels.
Technical Definition and Structural Dynamics
Sparkling bottled water denotes water artificially or naturally infused with carbon dioxide to achieve effervescence, typically bottled at pressures between 1.5 and 3.5 volumes of CO₂ saturation for sensory consistency. The product serves as a sugar-free hydration alternative in commercial foodservice and direct-to-consumer channels. Flavored sparkling commands the fastest expansion as brands layer botanical extracts and zero-calorie sweeteners to capture soda-switching households. Glass bottles retain outsized margin pools in on-premise restaurants and hotels where packaging aesthetics influence menu pricing authority. Supermarkets dominate volume throughput but online retailers are capturing subscription-driven household replenishment with customizable flavor assortments.
Regulatory Framework and Outlook
The FDA enforces bottled water standards under 21 CFR 165.110, while the EPA regulates source water quality through the Safe Drinking Water Act; in Europe, EFSA and national regulators enforce mineral water purity under Directive 2009/54/EC. These frameworks elevate compliance costs for new entrants but validate premium positioning for established brands with certified source protection. Stakeholders must monitor evolving extended producer responsibility mandates that will reshape packaging economics and recyclate sourcing requirements.
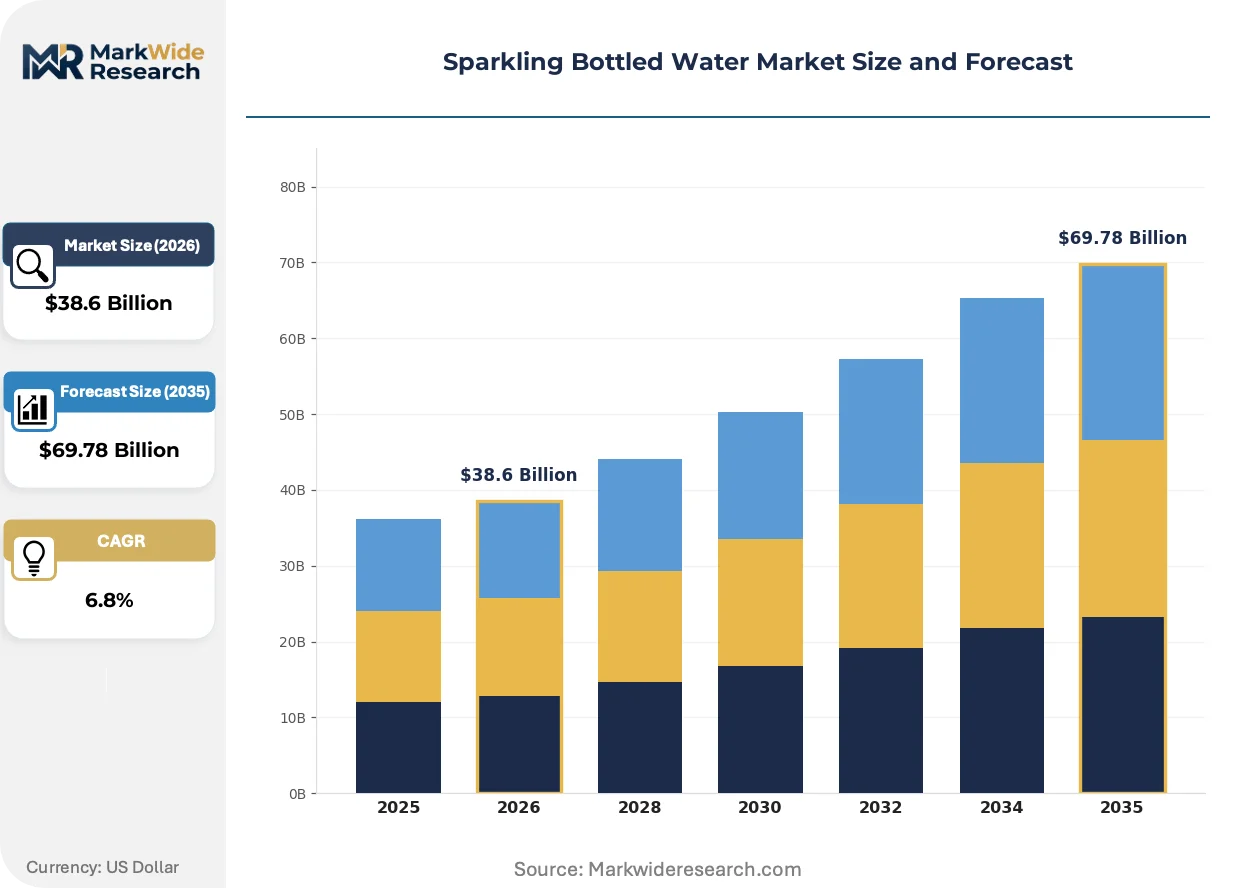
Market Dynamics
Carbonation technology maturation and the EU Green Deal's packaging accountability mandates are compressing legacy supply economics while opening margin pools for brands with certified circular infrastructure.
Growth Catalysts
- Carbon capture utilization:Industrial CO₂ recovery systems now supply beverage-grade gas at lower embodied emissions, qualifying producers for EU Green Deal subsidies and carbon border adjustments.
- Foodservice channel expansion:Hotels and restaurants across the United States are building dedicated sparkling water programs as consumers abandon sugary fountain beverages.
- Directive 2009/54/EC harmonization:Simplified cross-border mineral water recognition is accelerating private-label proliferation in German-speaking markets.
Market Restraints
- Glass supply concentration:European container glass production clusters in Italy and Germany, exposing brands to energy cost volatility and furnace capacity constraints.
- Source water access limitations:Protected spring designations require multi-year geological surveys and municipal negotiations, blocking rapid geographic expansion.
- Aluminum can substitution threat:Still water and seltzer brands are capturing convenience-store velocity with lighter, unbreakable packaging formats.
Strategic Opportunities
- Subscription channel penetration:Direct-to-consumer platforms with customizable flavor assortments are capturing household replenishment cycles previously served by supermarkets.
- Botanical flavor convergence:Zero-calorie sweetener advances paired with natural extract stabilization are enabling soda-switching households to migrate without taste compromise.
- Extended producer responsibility tailwinds:Deposit-return mandates in Germany and Scandinavia are rewarding brands with pre-established refillable bottle networks.
Industry Challenges
- Carbonation engineering talent scarcity:Pressure system design and CO₂ saturation consistency expertise concentrates among legacy equipment manufacturers, constraining new facility commissioning.
- Recyclate certification complexity:FDA validation of post-consumer resin for food-contact applications requires 18-24 month testing protocols, delaying sustainable packaging transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sparkling Bottled Water Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Sparkling, Flavored Sparkling, Functional Sparkling, Organic Sparkling Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores Packaging Type: Plastic Bottles, Glass Bottles, Cans, Tetra Paks End User: Households, Restaurants, Hotels, Gyms |
| Companies Covered | Danone, Spindrift, Nestlé Waters, Primo Water Corporation, Keurig Dr Pepper, PepsiCo, National Beverage Corp., Talking Rain, The Coca-Cola Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sparkling Bottled Water Market Strategic Shifts
Reformulation science and packaging circularity are compressing traditional competitive moats while elevating technical sophistication requirements across production and distribution.
Precision carbonation control systems are expanding into mainstream production lines. These units modulate CO₂ injection by temperature and mineral content, enabling consistent effervescence across variable source water chemistries. Mid-tier bottlers in France and Italy are retrofitting legacy lines to capture on-premise restaurant contracts previously reserved for premium imports.
REACH chemical registration requirements are tightening scrutiny of flavoring compounds and mineral additives used in enhanced sparkling waters. The European Chemicals Agency's expanded substance evaluation list is forcing reformulation of botanical extracts and natural essences. Brands with dedicated regulatory affairs teams are accelerating dossier submissions to secure grandfathered market access.
Home carbonation appliance penetration is compressing bulk purchase cycles for bottled alternatives. SodaStream and competing countertop systems are capturing urban apartment dwellers and small households in German and US metropolitan cores. Retailers are responding with smaller-format multipacks and chilled single-serve placements to defend impulse purchase occasions.
Sparkling Bottled Water Market Segmentation
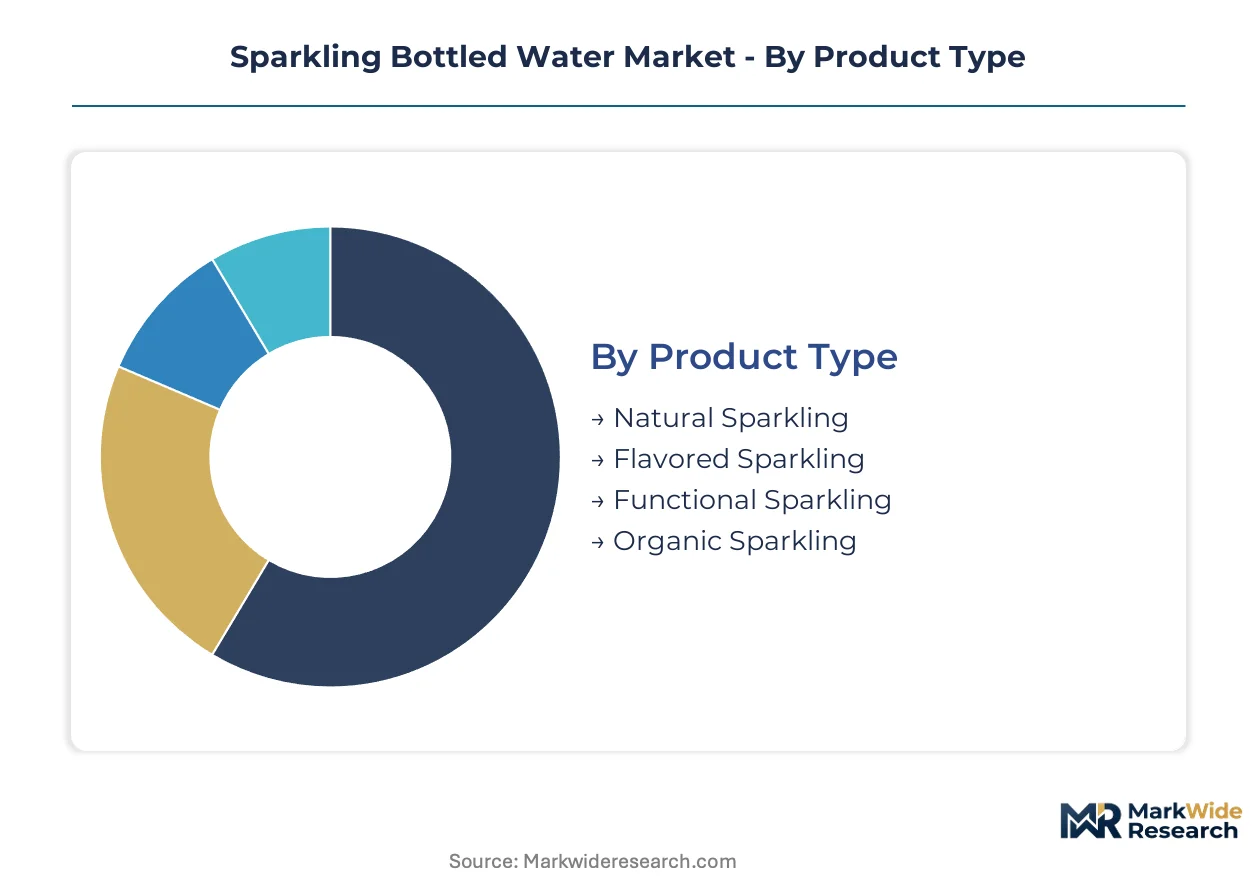
Sparkling bottled water segmentation reveals how carbonation technology, packaging economics, and channel access create distinct margin architectures. Each dimension carries upgrade-cycle implications as consumers trade between convenience, sustainability signaling, and sensory experience.
Product Type:
Reformulation cycles are shortening as zero-calorie sweetener advances and botanical extract stabilization mature, compressing the window between premium innovation and mass-market availability.
- Natural Sparkling:Water carbonated from naturally occurring mineral springs retains effervescence without artificial injection, commanding price premiums in German-speaking markets where protected source designations carry cultural weight. Demand concentrates in traditional foodservice accounts seeking authentic terroir narratives for menu differentiation.
- Flavored Sparkling:Carbonated water infused with natural extracts and zero-calorie sweeteners captures soda-switching households through taste parity without caloric compromise. US supermarkets and convenience stores are expanding chilled single-serve placements to intercept impulse migration from sugary alternatives.
- Functional Sparkling:Enhanced formulations with added electrolytes, vitamins, or adaptogens target post-exercise and workplace consumption occasions.
- Organic Sparkling:Certified organic sourcing appeals to ingredient-conscious households willing to absorb 15-30% price premiums for supply chain transparency.
Natural Sparkling sits at the top of the volume ranking, with Flavored Sparkling climbing the fastest.
Distribution Channel:
Channel economics diverge sharply between high-velocity replenishment and experience-driven discovery, with infrastructure investments determining capture rates of shifting purchase occasions.
- Supermarkets:Dominant volume throughput with chilled vault placements and promotional slotting fees that favor established brands with direct-store-delivery infrastructure. German retailers are expanding refillable bottle return systems under extended producer responsibility mandates.
- Convenience Stores:Impulse-driven velocity for single-serve formats, though aluminum can substitution from still water and seltzer brands is compressing bottled sparkling water facings in US urban locations.
- Online Retailers:Subscription platforms with customizable flavor assortments are capturing household replenishment cycles, reducing price sensitivity through auto-replenishment lock-in.
- Specialty Stores:Curated premium and import selections serve gift occasions and connoisseur discovery, with glass bottle aesthetics influencing purchase authority.
Supermarkets anchor absolute volume contribution, while Online Retailers are expanding most quickly through subscription penetration.
Packaging Type:
Material selection increasingly reflects regulatory pressure rather than pure cost optimization, with circular infrastructure investments becoming competitive differentiators.
- Plastic Bottles:Lightweight PET dominates mass-market volume but faces escalating scrutiny under EU Green Deal packaging accountability mandates and state-level extended producer responsibility laws.
- Glass Bottles:Retains outsized margin pools in on-premise restaurants and hotels where packaging aesthetics influence menu pricing authority, though European production concentration in Italy and Germany exposes brands to energy cost volatility.
- Cans:Aluminum formats are displacing bottles in convenience channels through lighter logistics and unbreakable handling profiles.
- Tetra Paks:Aseptic cartons occupy niche positions in institutional and travel retail segments where breakage resistance and rectangular stacking efficiency matter.
Plastic Bottles maintain volume leadership by a wide margin, with Cans gaining share fastest in convenience-oriented subsegments.
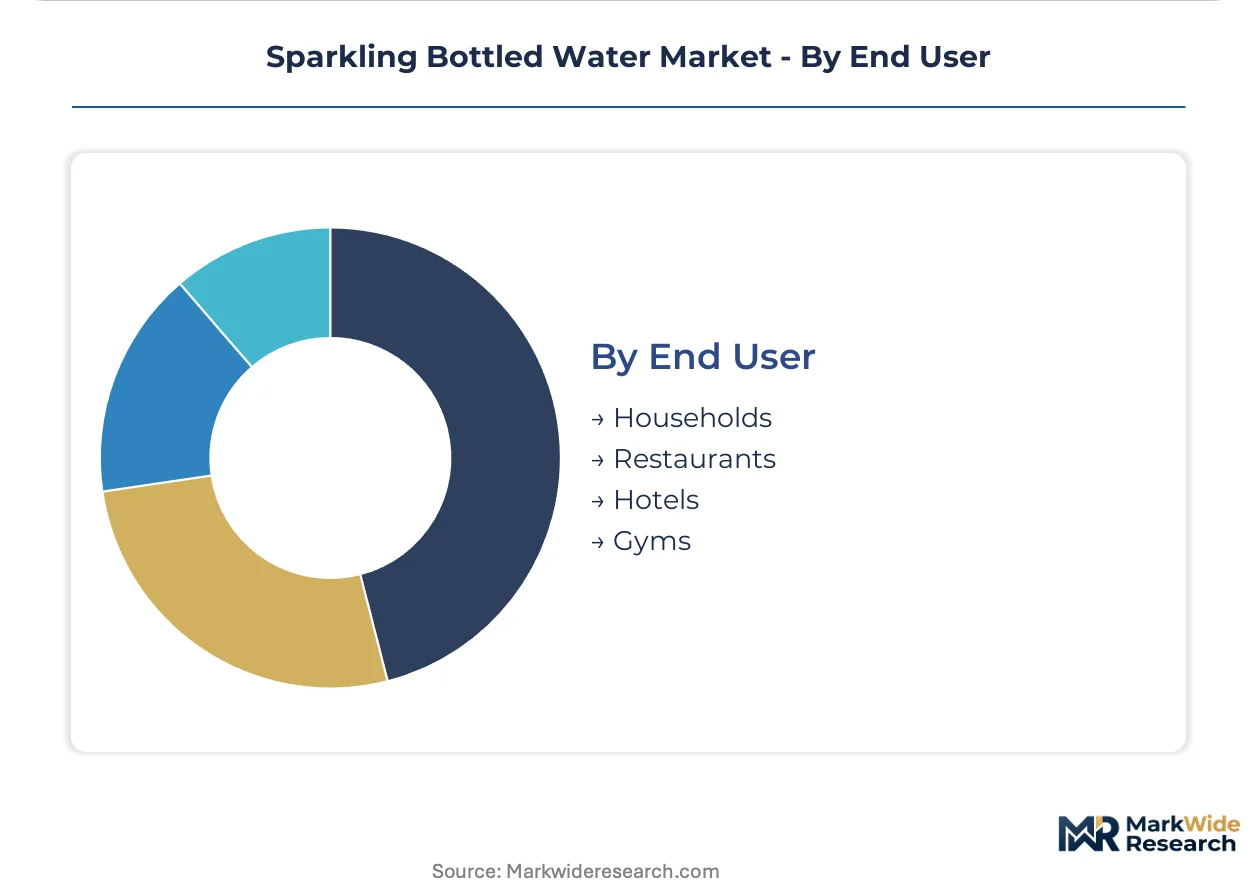
End User:
Consumption occasion fragmentation is forcing brands to maintain parallel channel strategies rather than unified mass-market positioning.
- Households:Core replenishment demand served through supermarket case packs and online subscription, with flavor customization and delivery convenience driving platform switching.
- Restaurants:Dedicated sparkling water programs are expanding across US independent and chain accounts as operators abandon sugary fountain beverages and seek margin-rich beverage alternatives.
- Hotels:In-room and minibar placements prioritize premium glass formats with distinctive sourcing narratives that reinforce property positioning.
- Gyms:Post-workout hydration occasions favor functional sparkling variants with electrolyte enhancement, often distributed through exclusive vending partnerships.
Households represent the largest addressable base, with Restaurants showing the steepest program expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbonation engineering talent clusters in Germany, Italy, and France anchor European production dominance, while US foodservice expansion and Asian convenience retail build parallel demand poles.
United States
Hotels and restaurants in New York, Los Angeles, and Chicago are building dedicated sparkling water programs as consumers abandon sugary fountain beverages. The FDA enforces bottled water standards under 21 CFR 165.110, tightening contaminant thresholds and labeling requirements that elevate compliance costs for new entrants. PepsiCo anchors North American volume through direct-store-delivery infrastructure that controls shelf presence in Texas and California distribution corridors.
Germany
Carbonated mineral water consumption remains culturally embedded in Bavaria and North Rhine-Westphalia, with premium private-label offerings proliferating across Aldi and Lidl networks. The EU Green Deal is decoupling carbon footprint accountability from traditional packaging economics, rewarding brands with certified circular infrastructure. Glass bottle production concentrates in Bavaria and Baden-Württemberg, exposing brands to energy cost volatility and furnace capacity constraints.
France
Protected spring designations in the Massif Central and Vosges Mountains carry terroir narratives that command price premiums in specialty retail channels. EFSA and national regulators enforce mineral water purity under Directive 2009/54/EC, validating premium positioning for established brands with certified source protection. Danone leverages its integrated spring-to-bottle network to sustain margin resilience under tightening emissions rules.
Italy
Mid-tier bottlers in Lombardy and Veneto are retrofitting legacy lines with precision carbonation control systems to capture on-premise restaurant contracts previously reserved for premium imports. REACH chemical registration requirements are tightening scrutiny of flavoring compounds used in enhanced sparkling waters. Container glass production clusters in Tuscany and Emilia-Romagna, creating supply concentration risks.
United Kingdom
Subscription-driven household replenishment through online retailers is capturing flavor-customizable assortments in London and Southeast England. Extended producer responsibility mandates are reshaping packaging economics and recyclate sourcing requirements. Nestlé Waters differentiates via premium sourcing narratives that command price premiums in specialty retail channels across the Midlands and Scotland.
Sparkling Bottled Water Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base fragments across beverage multinationals with integrated spring networks, regional bottlers with protected source access, and private-label specialists serving German discount retail. Three archetypes dominate: scale-driven conglomerates controlling direct-store-delivery infrastructure, terroir-focused premium brands leveraging protected designations, and agile flavor innovators capturing soda-switching households. M&A activity targets regional spring access, while capacity expansion concentrates in certified circular packaging facilities.
Among diversified beverage conglomerates, Danone, PepsiCo, and Nestlé Waters exemplify the scale-driven archetype. Danone occupies a position as the integrated spring-to-bottle operator with European regulatory compliance depth. PepsiCo anchors North American volume infrastructure. Nestlé Waters sits within the premium-tier vector leveraging sourcing narrative differentiation. Regional specialists including Spindrift and Talking Rain represent the flavor-innovation archetype, while National Beverage Corp. and Keurig Dr Pepper exemplify diversified portfolio approaches spanning multiple beverage categories.
| Leading Market Players |
|---|
| Danone |
| Spindrift |
| Nestlé Waters |
| Primo Water Corporation |
| Keurig Dr Pepper |
| PepsiCo |
| National Beverage Corp. |
| Talking Rain |
| The Coca-Cola Company |
| Others |
Value Chain & Pricing Dynamics
US foodservice operators and German discount retail chains anchor demand concentration, locking in divergent pricing models. Subscription platforms extract premium yields from households through auto-replenishment lock-in, while mass-market PET formats compete on per-liter efficiency in supermarket promotional cycles.
Pricing Analysis
Bundled subscription services versus unbundled transactional purchases split the market's pricing architecture. Three-tier pricing structure across premium glass, standard PET, and economy private-label tiers stratifies consumer access, with certification grade under Directive 2009/54/EC and source protection status driving tier placement. Cost compression in mass-market PET is intensifying because EU Green Deal packaging accountability mandates elevate circular infrastructure investments. Household subscribers show lowest price sensitivity through flavor-customization lock-in, while convenience-store impulse buyers exhibit highest elasticity to single-serve promotions.
Supply Chain Analysis
Dual-sourcing requirements for beverage-grade CO₂ and container glass qualify major bottlers for EU Green Deal subsidies and carbon border adjustments. Production gravity centers on Germany, Italy, and France for precision carbonation engineering and protected spring access, with raw material dependencies spanning industrial CO₂ recovery systems, PET resin, and soda-lime glass. Single-source vulnerability concentrates in European container glass furnace capacity clustered in Bavaria and Tuscany. Distribution runs through direct-store-delivery networks for retail volume and specialized cold-chain logistics for foodservice accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sparkling bottled water market compounds steadily as soda-switching households migrate permanently from sugary alternatives, embedding recurring replenishment demand across subscription and retail channels.
For Market Incumbents: Deepen backward integration into certified spring networks and captive CO₂ recovery infrastructure to defend margin position against private-label erosion in German discount retail. Prioritize retrofitting legacy lines with precision carbonation systems to capture on-premise restaurant contracts previously reserved for premium imports. Extend producer responsibility compliance in Germany and Scandinavia creates competitive moats through refillable bottle network density.
For New Entrants and Emerging Players: Begin with subscription channel penetration in US metropolitan cores where home carbonation appliance adoption compresses bulk purchase cycles but flavor customization retains switching costs. Target functional sparkling variants with electrolyte enhancement for gym vending partnerships, the most penetrable white-space segment. Deploy botanical flavor convergence as the primary go-to-market angle, leveraging zero-calorie sweetener advances to intercept soda-switching households without taste compromise.
For Investors and Strategic Acquirers: Beverage conglomerates with integrated spring-to-bottle networks are the most active acquirers in this space, consolidating regional protected source access to sustain margin resilience. The market presents long-term viability as a stable compounder through the projection horizon, with acquisition value concentrating in mid-tier bottlers holding certified circular infrastructure. Watch deposit-return mandate expansion across EU member states as the signal indicating acceleration in refillable format economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Captures household replenishment cycles previously served by supermarket case packs through auto-replenishment lock-in. |
| Precision Carbonation Retrofit | Enables mid-tier bottlers to secure on-premise restaurant contracts previously reserved for premium import brands. |
| Refillable Bottle Network Expansion | Qualifies producers for extended producer responsibility subsidies under German and Scandinavian deposit-return mandates. |
| Botanical Flavor Pipeline Investment | Accelerates soda-switching household migration through zero-calorie sweetener advances paired with natural extract stabilization. |
| Protected Spring Acquisition | Validates premium positioning under Directive 2009/54/EC while blocking rapid geographic expansion by competitors. |
Study Parameters
Bottom-up household and foodservice operator modeling reconciled against top-down spring-to-bottle production tracking forms the analytical core of this study. Primary interviews with brand managers, category buyers at retailers, channel sales heads, and supply planners informed demand-side assumptions, validated against secondary sources including Nielsen retail audit data, customs records, FDA 21 CFR 165.110 filings, and EU Directive 2009/54/EC implementation reports.
Historical trendline analysis across carbonation technology adoption curves and packaging format shifts anchored the projection framework. Segmentation dimensions modeled include product type, distribution channel, packaging material, and end-user occasion, with CAGRs derived from regression analysis against soda consumption decline rates and sparkling water penetration trajectories. Forecast inputs incorporated EU Green Deal compliance cost trajectories and REACH chemical registration timelines for flavor compound reformulation.
Several conditions sit outside the modeled scope, including abrupt regulatory reversals on extended producer responsibility, breakthrough home carbonation technology displacing bottled formats, and source water contamination events invalidating protected designations. Deviation in deposit-return mandate adoption velocity across EU member states would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
United States Beverage Contract Bottling and Filling Market
Beverages
Relaxation Beverages Market
Beverages
North America Energy Drink Market
Beverages
BBQ Charcoal Market
Beverages
Pineapple Juice Market
Beverages
Fruit Water Market
Beverages
Dairy Based Beverages Market
Beverages
Ginger Beer Market
Beverages
Chocolate Powdered Drinks Market
Beverages
Packaged Cactus Water Market
Beverages
Wine Cooler and Chest Freezer Market
Beverages
United States and Australia Coconut Water Market
Beverages
Drinking Bottled Mineral Water Market
Beverages
North America Fruit Juice Market
Beverages
Sparkling Juice Drinks Market
Beverages
GCC Coconut Water Market