
 Spring Water Market | 2026-2036
Spring Water Market Size, Share, and Industry Trends Forecast 2026-2036
Spring Water Market Analytics
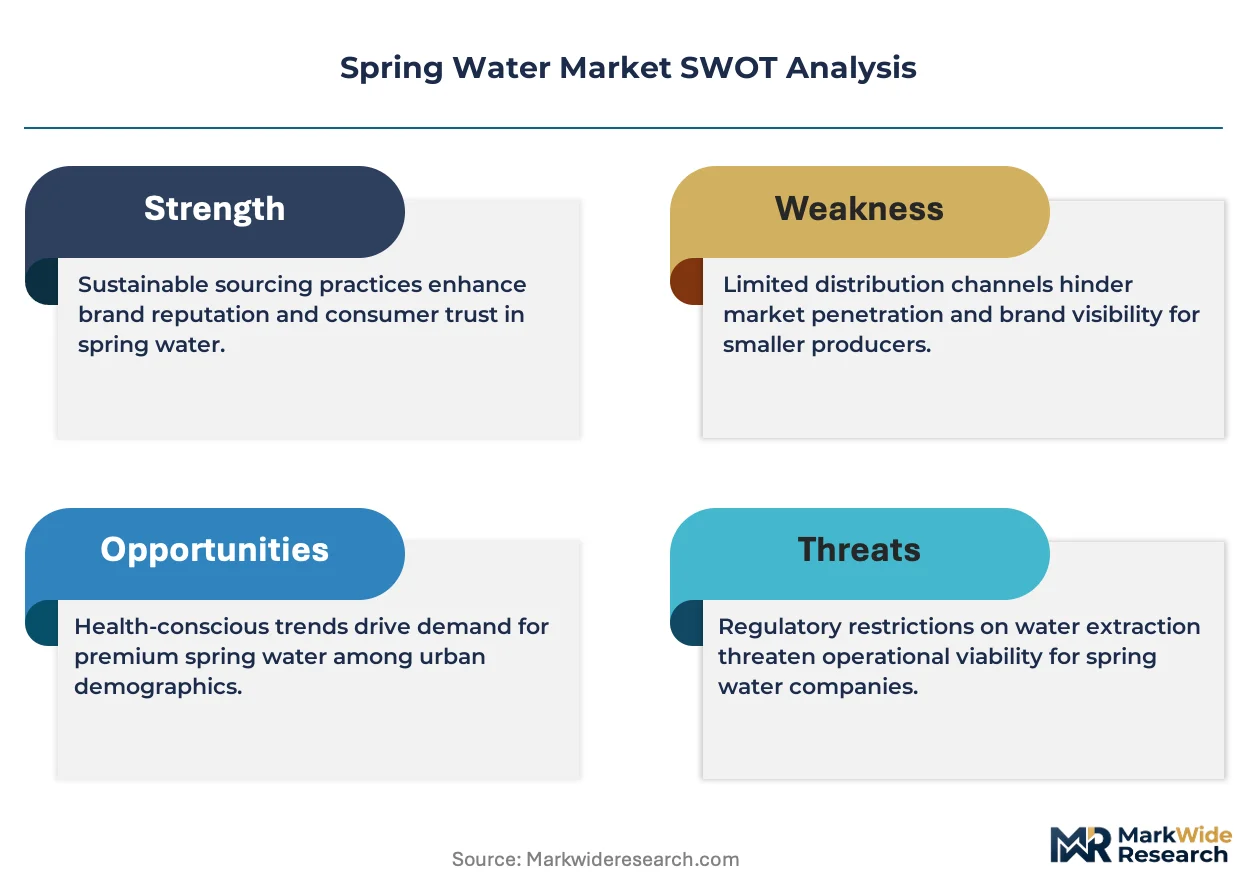
The EU Green Deal is restructuring procurement priorities across European spring water bottlers, forcing material transitions and carbon accounting disclosures. Danone leverages its Alpine source network to sustain premium positioning in still water segments. Nestlé anchors its portfolio through geographic dominance in North American retail channels, while Nongfu Spring controls pricing power across China's tier-one cities through direct-to-consumer platform integration.
Spring water comprises naturally sourced groundwater collected from protected underground formations, with total dissolved solids typically below 500 mg per liter and no added minerals beyond those present at the source. The liquid undergoes minimal processing to preserve original composition, serving commercial and residential hydration needs where taste consistency and perceived purity command price premiums. Still water occupies the largest volume share across retail and food service channels, though flavored water variants attract the fastest-growing consumer cohort among health-conscious younger demographics. Glass bottles capture margin concentration in premium hospitality settings, while plastic bottles dominate household bulk purchasing through supermarket chains.
FDA standards govern source protection and labeling claims in the United States, while the EU F-Gas Regulation and REACH frameworks constrain refrigerant use in cold-chain distribution and packaging material selection across member states. China's SAMR enforces national food safety standards for bottled water production and source monitoring. Stakeholders must monitor evolving extended producer responsibility mandates and carbon border adjustments that will reshape sourcing economics and packaging material decisions.
Market Dynamics
The EU Green Deal's packaging sustainability mandates are forcing bottlers to abandon virgin plastic and accelerate material transitions toward recycled PET and glass alternatives. This regulatory pressure intersects with consumer willingness to pay source-verified premiums, compressing margin structures for mid-tier producers.
Growth Catalysts
- EU F-Gas Regulation:Cold-chain refrigerant phase-downs are compelling bottlers to invest in energy-efficient logistics networks, reducing operational carbon intensity and qualifying products for green procurement tenders.
- Health club channel expansion:Fitness center hydration stations are converting from tap-fed fountains to branded spring water dispensers, creating recurring volume commitments with long-term supply contracts.
- China's tier-one urbanization:Shanghai and Beijing household penetration of premium still water is accelerating as apartment dwellers reject municipal supply taste profiles for source-protected alternatives.
Market Restraints
- Aluminum can input volatility:Metal packaging feedstock price swings are compressing margins for producers pivoting from plastic, with smelter capacity concentrated in energy-cost-sensitive geographies.
- Source protection concentration:Premium Alpine and Appalachian aquifer access is controlled by incumbent leaseholders, blocking new entrants from securing long-term extraction rights.
- Extended producer responsibility mandates:France's Citeo and Germany's DSD packaging fee structures are adding per-unit compliance costs that scale disadvantageously for regional bottlers.
Strategic Opportunities
- Direct-to-consumer platform integration:Subscription-based home delivery apps are bypassing supermarket slotting fees, capturing lifetime value through recurring revenue models in dense urban clusters.
- EU Carbon Border Adjustment Mechanism:Import parity pricing for non-EU bottled water creates protected market space for domestic producers sourcing within member-state boundaries.
- Flavored functional water convergence:Electrolyte-enhanced and adaptogen-infused variants are attracting wellness-focused millennials, commanding price multiples over unenhanced still water.
Industry Challenges
- Microplastics detection protocols:Emerging analytical methods for sub-micron particle identification are outpacing standardized testing frameworks, creating liability exposure for PET-dependent producers.
- Legacy bottling line retrofit costs:Glass-compatible filling equipment requires capital deployment that strains mid-cap balance sheets, delaying material transition timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spring Water Market |
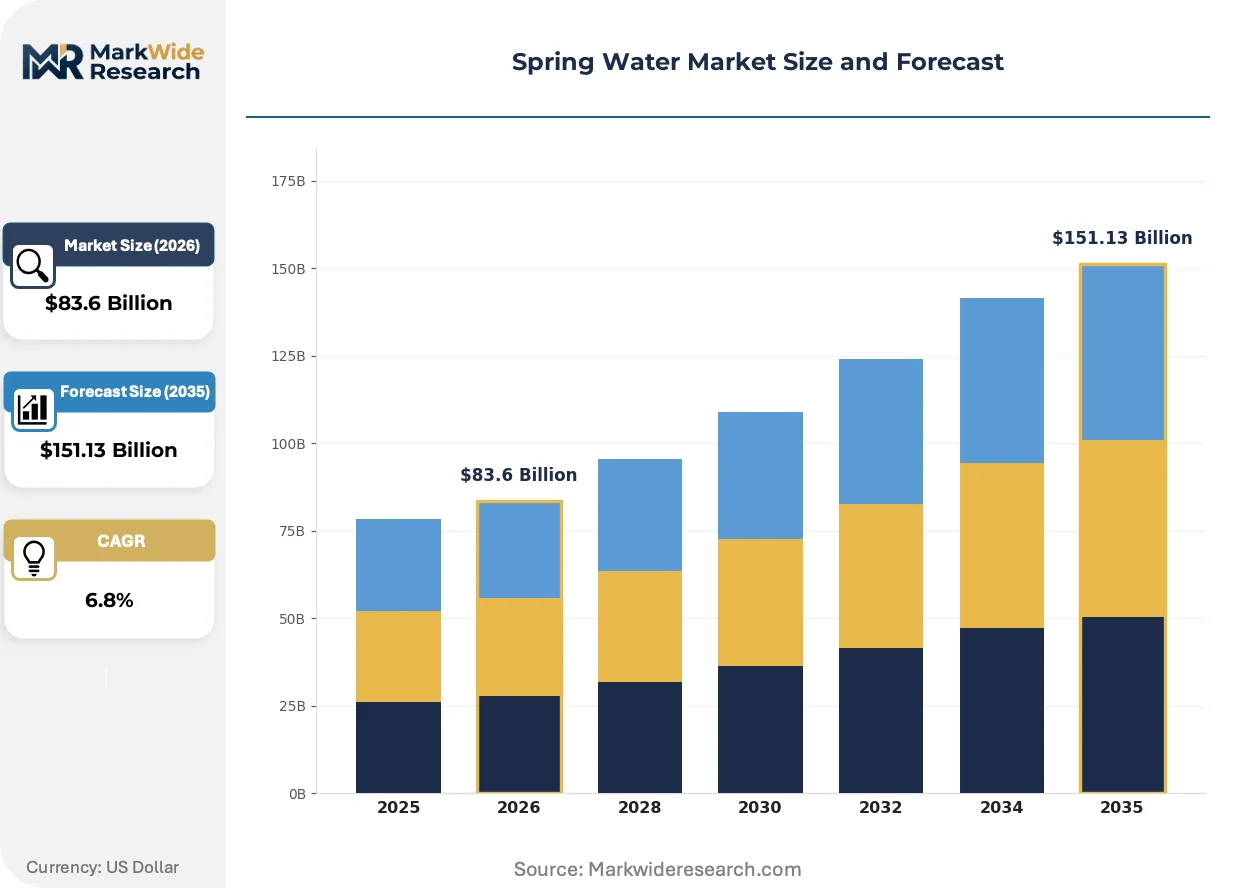
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $151.13 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sparkling Water, Still Water, Flavored Water, Mineral Water Package Type: Glass Bottles, Plastic Bottles, Tetra Paks, Bulk Containers Distribution Channel: Retail Stores, Online Sales, Food Service, Vending Machines End User: Households, Restaurants, Cafés, Health Clubs |
| Companies Covered | The Coca-Cola Company, Danone, Nestlé, Bisleri International, Nongfu Spring, Primo Brands Corporation, Gerolsteiner Brunnen, FIJI Water Company, Suntory Beverage & Food, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spring Water Market Evolving Landscape
Material science breakthroughs and regulatory compliance automation are converging to reshape production economics. Bottlers are racing to deploy traceability infrastructure ahead of mandatory disclosure deadlines.
Recycled PET flake purification technology is modularizing supply chains by enabling regional reprocessing hubs to feed local bottling plants. Mid-size producers in Poland and the Czech Republic are adopting these systems to reduce virgin resin dependence. The technology is modularizing what had been centralized petrochemical supply relationships into distributed circular networks.
REACH SVHC candidate list expansion is restricting colorant and additive chemistries in cap and label manufacturing. European converters are reformulating to eliminate phthalate plasticizers and bisphenol derivatives. Still water SKUs with minimalist packaging specifications are capturing shelf space as retailers preempt compliance risk.
Subscription-based replenishment apps are displacing impulse supermarket purchases among dual-income households. Younger buyers in Seoul and Singapore are prioritizing delivery convenience over in-store selection. Fitness-oriented consumers are consolidating beverage procurement through integrated wellness platform bundles.
Spring Water Market Segmentation
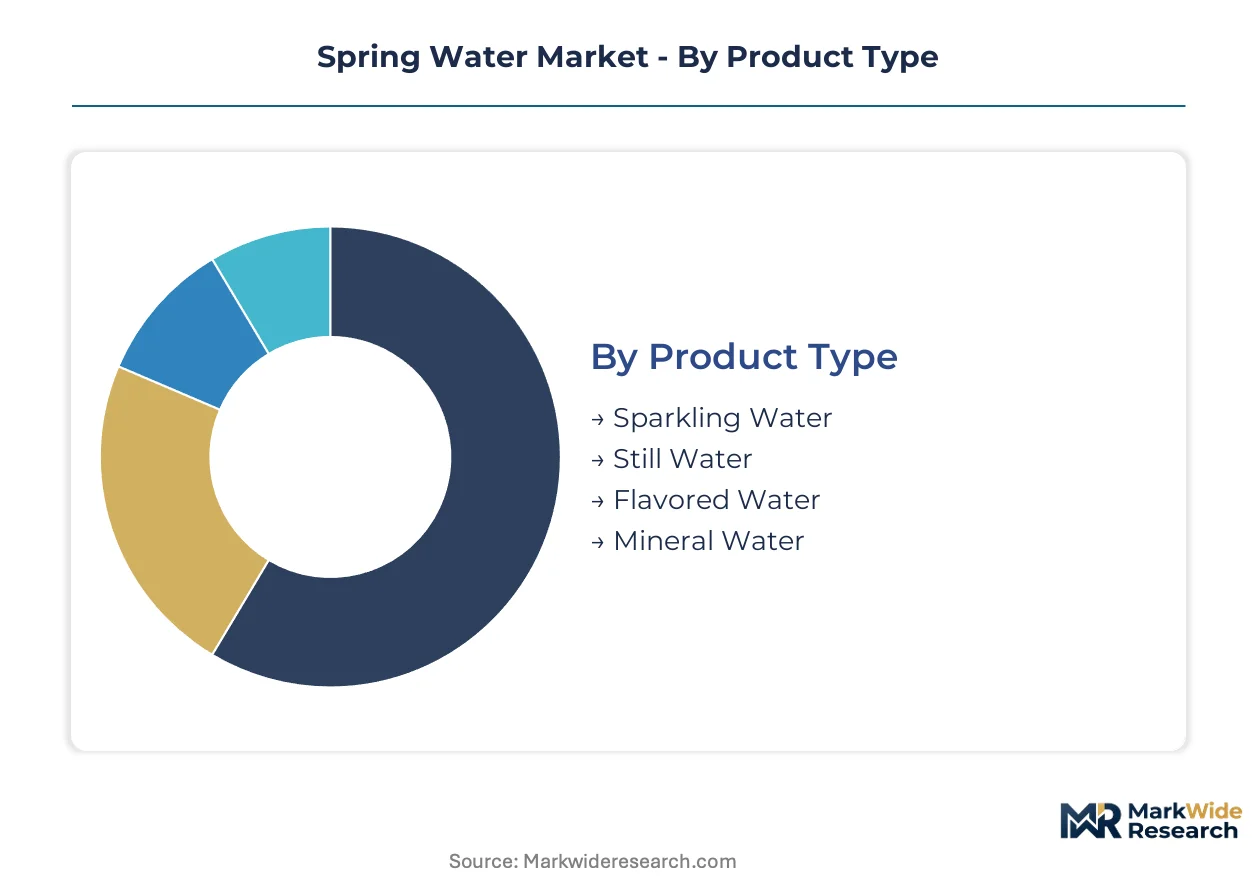
Segmentation in the spring water market reveals how consumption contexts dictate packaging formats, pricing power, and channel economics. Producers must align product specifications with distinct hydration occasions rather than treating water as a commoditized liquid.
Product Type:
Still water functions as the foundational hydration staple across all consumption settings, while flavored and carbonated variants command premium positioning through sensory differentiation.
- Still Water:Unaltered groundwater with total dissolved solids below 500 mg/L serves as the default hydration choice for households and food service operations. Demand concentrates in China's tier-one cities where apartment dwellers reject municipal supply taste profiles for source-protected alternatives.
- Sparkling Water:Naturally carbonated or CO2-injected variants deliver effervescence without caloric content, capturing share among consumers transitioning from sugary sodas. European cafés and restaurants in France and Italy drive volume through table-service integration.
- Flavored Water:Fruit extracts and natural essences create taste differentiation without added sugars, appealing to younger demographics seeking variety.
- Mineral Water:Source-specific mineral compositions above 500 mg/L TDS occupy premium shelf positions in hospitality settings.
Still water leads volumes today; flavored water is gaining share fastest.
Package Type:
Material selection determines carbon intensity compliance, logistics cost structures, and margin capture across retail versus on-premise channels.
- Plastic Bottles:PET and recycled PET formats dominate household bulk purchasing through supermarket chains, though EU Green Deal mandates are accelerating rPET transitions. Germany's DSD packaging fee structures add per-unit compliance costs that scale disadvantageously for regional bottlers.
- Glass Bottles:Premium hospitality settings in Alpine resorts and Parisian restaurants absorb higher unit costs for perceived purity and source authenticity. Legacy bottling line retrofit costs strain mid-cap balance sheets, delaying material transition timelines.
- Tetra Paks:Aseptic carton formats reduce shipping weight and enable ambient distribution, penetrating convenience retail in Japan and South Korea.
- Bulk Containers:Refillable dispensers and five-gallon bottles serve office and health club hydration stations with recurring delivery contracts.
Plastic bottles retain volume leadership; glass alternatives are expanding most quickly in premium channels.
Distribution Channel:
Channel selection determines working capital intensity, brand control, and consumer data capture capabilities for producers.
- Retail Stores:Supermarket and hypermarket shelf placement requires slotting fee investments but delivers mass-market penetration. French retailers are preempting REACH compliance risk by prioritizing minimalist packaging SKUs.
- Online Sales:Subscription-based replenishment apps bypass traditional retail margins, capturing lifetime value through recurring revenue models in dense urban clusters across Seoul and Singapore.
- Food Service:Restaurant and café supply contracts provide volume stability but compress margins through negotiated pricing.
- Vending Machines:Cold-chain refrigeration points in transit hubs and fitness centers convert impulse hydration needs into immediate transactions.
Retail stores anchor current volume; online sales are climbing the fastest among dual-income households.
End User:
End-use concentration shapes product positioning, with institutional buyers prioritizing logistics reliability over brand differentiation.
- Households:Residential consumption drives recurring purchase patterns through subscription models and pantry-loading behaviors at retail. Shanghai and Beijing household penetration of premium still water accelerates as urbanization concentrates.
- Health Clubs:Fitness center hydration stations are converting from tap-fed fountains to branded spring water dispensers, creating recurring volume commitments with long-term supply contracts.
- Restaurants:Table-service integration demands consistent supply and source-verified provenance for menu storytelling.
- Cafés:Coffee shop chains require water with neutral mineral profiles to preserve beverage taste integrity.
Households dominate absolute consumption; health clubs are expanding most quickly through institutional conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial bottling of natural spring water originated in European Alpine regions during the mid-19th century, with French and Italian entrepreneurs first packaging source-protected groundwater for railway travelers and spa visitors. This heritage established quality verification protocols that now govern premium positioning across international markets.
United States
FDA source protection standards and labeling requirements shape competitive entry, while health club channel expansion drives institutional volume growth. The Appalachian aquifer system in Pennsylvania and West Virginia supplies major bottlers with low-mineral groundwater. California's municipal supply taste complaints in Los Angeles and San Francisco accelerate household conversion to source-verified alternatives.
Germany
Carbonated mineral water traditions sustain sparkling variant demand through restaurant and café channels. REACH SVHC restrictions on cap and label additives compel packaging reformulation across the supply base. The Bavarian Alps host concentrated extraction operations serving both domestic premium retail and export hospitality markets.
China
Shanghai and Beijing apartment dwellers reject municipal supply taste profiles, accelerating premium still water penetration in tier-one cities. SAMR enforces national food safety standards for source monitoring and production facility licensing. Nongfu Spring leverages direct-to-consumer platform integration to control pricing power across urban retail and e-commerce channels.
France
Citeo extended producer responsibility fee structures add per-unit compliance costs that disadvantage regional bottlers against integrated multinationals. EU Green Deal packaging mandates accelerate transitions toward recycled PET and glass alternatives. Alpine source networks in the Auvergne-Rhône-Alpes region sustain premium positioning through protected designation claims.
Japan
Tetra Pak aseptic carton formats penetrate convenience retail channels in Tokyo and Osaka, reducing shipping weight and enabling ambient distribution. METI guidelines on plastic reduction target single-use packaging across beverage categories. Fitness-oriented consumers in the Kanto region consolidate procurement through subscription-based wellness platform bundles.
Spring Water Market Competitive Landscape
Capital-heavy producers compete with asset-light designers in a market structure where source lease control and distribution infrastructure determine sustainable positioning. The vendor base clusters around three strategic archetypes: integrated multinationals commanding Alpine and Appalachian aquifer access, regional specialists leveraging local source proximity, and platform-native brands built on direct-to-consumer logistics. Competitive moves concentrate on source lease consolidation and cold-chain capacity expansion to secure institutional contracts.
Within the integrated multinational tier, Danone and Nestlé exemplify scale-driven archetypes anchored by geographic source networks. Nongfu Spring occupies a position as the platform-native specialist, representing direct-to-consumer integration in concentrated urban markets. These three companies illustrate how control over extraction rights, retail channel presence, and digital logistics infrastructure respectively define viable competitive positions.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| Danone |
| Nestlé |
| Bisleri International |
| Nongfu Spring |
| Primo Brands Corporation |
| Gerolsteiner Brunnen |
| FIJI Water Company |
| Suntory Beverage & Food |
| Others |
Value Network & Pricing Analysis
Health club procurement managers consolidating hydration contracts into long-term supply agreements are compressing margin structures for mid-tier regional bottlers while elevating source-verified premiums for integrated multinationals. This buyer concentration forces pricing discipline across plastic, glass, and bulk container formats as institutional volume commitments reshape competitive positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Alpine source-protected brands from municipal-reject alternatives and private-label supermarket tiers. Price differentiation hinges on extraction lease prestige and EU Green Deal compliance certification, with glass formats absorbing hospitality premiums. Cost compression in mid-tier recycled PET is intensifying because aluminum can feedstock volatility squeezes producers pivoting from virgin plastic. Health clubs demonstrate lowest price sensitivity due to bundled wellness platform economics, while household bulk purchasers through supermarket chains exhibit highest elasticity.
Supply Chain Analysis
EU F-Gas Regulation certification requirements for cold-chain refrigerant phase-downs are gating supplier qualification across European distribution networks. Extraction concentrates in France, Italy, and Germany where Alpine aquifer lease control rests with incumbent bottlers. Raw material dependencies span rPET flake, virgin resin, and aluminum sheet feedstock. Single-source vulnerability permeates Appalachian aquifer access in the United States where leasehold concentration blocks new entrant sourcing. Distribution runs through direct-to-consumer platform integration in Chinese tier-one cities alongside traditional retail anchoring in European supermarket chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's packaging sustainability mandates function as a regulatory compounder, accelerating material transitions that reshape procurement economics and source lease valuations across the forecast horizon.
For Market Incumbents: Anticipate margin compression from extended producer responsibility fee scaling by consolidating Alpine and Appalachian aquifer leaseholds ahead of carbon border adjustment implementation. Prioritize backward integration into regional rPET reprocessing hubs in Poland and the Czech Republic to reduce virgin resin exposure. Cold-chain capacity expansion in health club channels offers defensive positioning against supermarket slotting fee inflation. For New Entrants and Emerging Players: SAMR enforcement of national food safety standards in China opens a window for platform-native brands to bypass incumbent retail channel control through subscription-based home delivery apps. Target health club institutional conversion in Seoul and Singapore where fitness-oriented procurement consolidation remains underpenetrated. Lead with flavored functional water convergence featuring electrolyte enhancement to capture wellness-focused millennial cohorts. For Investors and Strategic Acquirers: Beverage multinational strategics are the most active acquirer in this space, seeking source lease control and direct-to-consumer logistics infrastructure. Long-term viability rests on extraction rights duration and carbon intensity compliance positioning. Watch for EU Carbon Border Adjustment Mechanism implementation as the inflection signal protecting domestic European producer margins against non-EU import parity.| Strategic Initiative | Industry Significance |
|---|---|
| Source Lease Consolidation | Danone's Alpine network demonstrates how extraction control sustains premium positioning against private-label erosion. |
| rPET Reprocessing Hub Deployment | Polish and Czech regional hubs modularize supply chains away from centralized petrochemical dependence. |
| Direct-to-Consumer Platform Integration | Nongfu Spring's urban retail and e-commerce control in Shanghai and Beijing captures recurring revenue lifetime value. |
| Health Club Channel Expansion | Fitness center hydration station conversion from tap-fed fountains creates institutional volume commitments with contract stability. |
| Flavored Functional Water Launch | Electrolyte-enhanced variants attract wellness-focused millennials commanding price multiples over unenhanced still water. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with bottling plant managers, retail category buyers, health club procurement officers, and regulatory affairs leads at European producers with secondary validation from FDA source protection filings, EU ECHA REACH SVHC candidate list updates, SAMR food safety standards documentation, and customs trade data on rPET flake imports. Bottom-up volume modeling across extraction regions and top-down value reconciliation anchored triangulation.
Segment-weighting approaches distributed analytical emphasis across still, sparkling, flavored, and mineral water product types; plastic, glass, Tetra Pak, and bulk container formats; retail, online, food service, and vending distribution channels; and household, health club, restaurant, and café end users. CAGRs derived from regression analysis against urbanization rates, health club membership penetration, and regulatory compliance cost trajectories. Forecast inputs incorporated EU F-Gas Regulation phase-down schedules and China's tier-one city household premium water adoption curves.
Revisions become necessary when EU Carbon Border Adjustment Mechanism implementation timelines accelerate, Alpine aquifer lease renewal disputes materialize, or microplastics detection protocol standardization disrupts PET-dependent producer liability exposure. Forecasts reflect documented assumptions on regulatory enforcement intensity and material science transition costs. A model refresh is warranted upon material change in extended producer responsibility fee structures across France, Germany, or equivalent frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Dairy Based Beverages Market
Beverages
Birch Water Market
Beverages
Ginger Beer Market
Beverages
India Soy Beverages Market
Beverages
Coconut Milk Beverages Market
Beverages
Carbonated Soft Drinks Market
Beverages
Citrus Water Market
Beverages
Extra Virgin Olive Oil Market
Beverages
Herb Infused Water Market
Beverages
North America Ready-To-Drink (RTD) Beverages Market
Beverages
Packaged Turmeric-Based Beverage Market
Beverages
Caffeine Mint Market
Beverages
Asia-Pacific Probiotic Drinks Market
Beverages
Asia Pacific Dairy Based Beverages Market
Beverages
North America Yerba Mate Market
Beverages
Still Drinks Market