
 Vegan Frozen Food Market | 2026-2036
Vegan Frozen Food Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Frozen Food Market Insights
V-Label certification is redrawing competitive boundaries in European retail channels, forcing reformulation investments from brands seeking shelf placement in mainstream grocers. Beyond Meat leverages its pea-protein extrusion infrastructure to sustain consistent texture benchmarks across frozen burger and sausage lines. Amy's Kitchen anchors its positioning through certified organic supply chains that command premium placement in health food stores and specialty grocers. Daiya Foods competes on tapioca-based cheese analogues that differentiate its frozen pizza and macaroni offerings from soy-dominant rivals.
Vegan frozen food comprises plant-derived ingredients preserved through blast-freezing at minus 18 degrees Celsius or below, maintaining cellular structure for reheated sensory fidelity in retail and foodservice applications. Plant-based meals and meat alternatives currently command the deepest margin pools as formulation complexity and protein texturization technology justify price premiums over commodity frozen vegetables. Distribution through supermarkets dominates volume throughput, though online retail channels are capturing subscription-based repeat purchases from health-conscious consumers seeking direct-to-home replenishment of specialized SKUs.
FDA nutrition labeling requirements and USDA organic certification standards govern product claims and ingredient disclosure in the United States, while EFSA and EU Green Deal frameworks shape permissible sustainability marketing across European markets. These regulatory architectures elevate compliance costs for new entrants but simultaneously validate premium positioning for established operators with certified supply chains. Stakeholders must monitor evolving protein-source disclosure mandates and carbon-footprint labeling requirements as these rules will determine which formulations retain retail authorization and consumer trust.
Market Dynamics
Supermarket chains are consolidating freezer-section real estate around V-Label certified SKUs, forcing reformulation investments that favor mid-sized processors with dedicated extrusion infrastructure over commodity vegetable packers.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Mandatory sustainability disclosure for processed foods creates first-mover advantage for certified operators with carbon-accounted supply chains.
- Flexitarian household penetration:German discounters Aldi and Lidl have expanded private-label vegan frozen ranges, normalizing plant-based meal replacement across mass-market demographics.
- Blast-freezing at minus 18 degrees Celsius:Cellular preservation technology maintains reheated sensory fidelity, enabling premium positioning for textured protein applications previously limited to fresh channels.
Market Restraints
- Pea-protein input concentration:North American and Canadian pulse processors control upstream supply, exposing margin compression during harvest volatility.
- EFSA novel food authorization timelines:Fermentation-derived proteins and precision-cultured ingredients face 18-24 month safety evaluation windows that delay product launches.
- Legacy cold-chain infrastructure:Third-party logistics providers in Southern Europe lack dedicated minus 18 Celsius capacity, fragmenting distribution economics.
Strategic Opportunities
- Subscription-based online retail:Direct-to-home replenishment of specialized SKUs captures repeat purchase data that supermarket scan data obscures.
- Foodservice channel penetration:Institutional buyers in Nordic countries are mandating plant-based meal quotas, creating volume anchors for scaled production.
- USDA organic certification premium:Certified organic supply chains command placement in health food stores and specialty grocers with margin structures 40% above conventional frozen.
Industry Challenges
- Protein texturization engineering talent:Formulation chemists with extrusion and shear-cell expertise command compensation premiums that strain R&D budgets at sub-scale operators.
- V-Label certification compliance:Third-party audit timelines and ingredient traceability documentation create 6-9 month delays for reformulated products seeking retail authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Frozen Food Market |
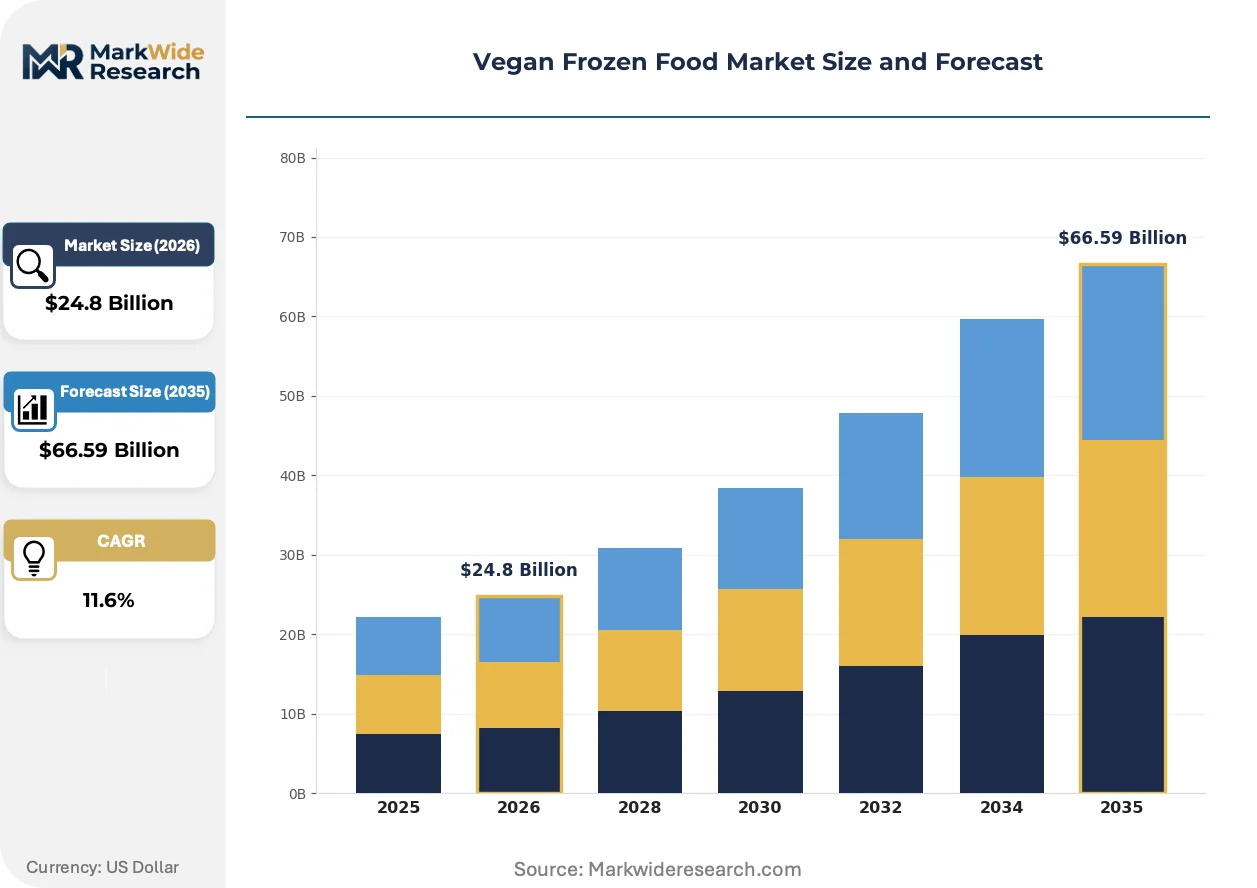
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $66.59 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Vegetables, Vegan Ice Cream, Plant-Based Meals, Meat Alternatives Ingredient Type: Legumes, Grains, Nuts, Soy Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Grocery End User: Families, Health-Conscious Consumers, Vegans, Flexitarians |
| Companies Covered | Beyond Meat, Impossible Foods, Oatly, Tofurky, Gardein, MorningStar Farms, Amy's Kitchen, Daiya Foods, Alpro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Frozen Food Market Trends and Innovations
Pea-protein extrusion infrastructure is bifurcating competitive positioning between capital-intensive operators achieving consistent texture benchmarks and commodity processors trapped in undifferentiated vegetable freezing.
High-moisture extrusion technology is bifurcating the frozen meat analogue segment. Foodservice distributors in Germany and the Netherlands are adopting these formulations for institutional catering contracts. The technology is bifurcating shelf placement economics, separating processors with in-house extrusion capacity from contract manufacturers dependent on tolling arrangements.
EU Green Deal carbon-footprint labeling requirements are tightening permissible sustainability marketing across member states. EFSA guidance on environmental claims is forcing reformulation investments and supply chain re-documentation. Frozen pizza and ready-meal categories face the steepest compliance costs due to multi-ingredient sourcing complexity.
Direct-to-consumer subscription models are capturing health-conscious household replenishment cycles previously routed through supermarket frozen aisles. Nordic markets show the highest subscription penetration, driven by urban density and delivery infrastructure maturity. Specialty retailers in Denmark and Sweden are responding with hybrid click-and-collect fulfillment to defend foot traffic.
Vegan Frozen Food Market Segmentation
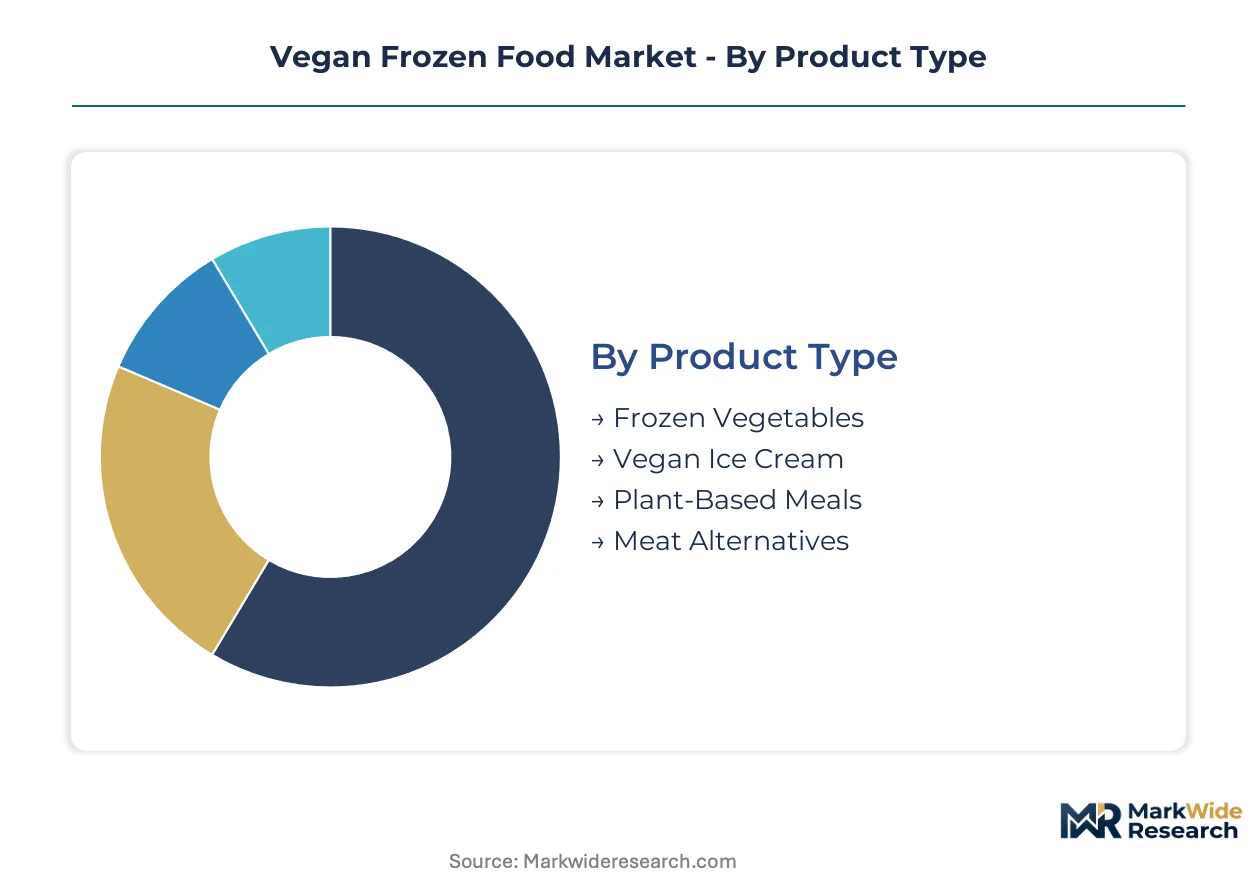
Vegan frozen food segmentation reveals where formulation complexity commands premium pricing versus commodity freezing economics. Protein texturization technology and certification requirements concentrate margin pools in distinct product and channel combinations.
Product Type:
Plant-based meals and meat alternatives capture the deepest margin pools as extrusion infrastructure and sensory engineering justify price premiums over undifferentiated vegetable freezing.
- Frozen Vegetables:Blast-frozen commodity produce at minus 18 degrees Celsius retains cellular structure for reheated applications. German discounters Aldi and Lidl drive volume through private-label positioning that normalizes plant-based meal replacement across mass-market demographics.
- Plant-Based Meals:Multi-component formulations combining textured proteins with sauce matrices and vegetable bases. Demand concentrates in Nordic foodservice channels where institutional buyers mandate plant-based meal quotas, creating volume anchors for scaled production.
- Vegan Ice Cream:Coconut, oat, and almond milk bases displace dairy analogues in freezer-section placement.
- Meat Alternatives:High-moisture extrusion achieves fibrous texture benchmarks previously limited to fresh channels.
Plant-based meals hold installed capacity. Meat alternatives are rotating up the share rankings.
Ingredient Type:
Cost tier stratification separates protein-concentrated inputs commanding formulation premiums from bulk carbohydrate fillers.
- Soy:Isolated protein concentrates and texturized vegetable protein remain the dominant base for frozen meat analogues. North American and Canadian processors control upstream supply, exposing margin compression during harvest volatility.
- Legumes:Pea-protein isolates and fava bean concentrates enable allergen-free positioning distinct from soy-dominant formulations. EU Green Deal carbon-footprint labeling favors pulse crops with lower agricultural emissions intensity.
- Grains:Wheat gluten and ancient grain blends provide binding and texture in frozen ready-meal applications.
- Nuts:Cashew and almond bases differentiate premium frozen desserts and cheese analogues.
Soy holds installed capacity. Legumes are rotating up the share rankings.
Distribution Channel:
Volume throughput concentrates in supermarket chains consolidating freezer-section real estate around V-Label certified SKUs.
- Supermarkets:Dedicated plant-based freezer sections capture flexitarian household spending through mass-market accessibility. Chains across Germany, the Netherlands, and Denmark are expanding linear footage for certified organic and V-Label ranges.
- Online Retail:Direct-to-home replenishment of specialized SKUs captures repeat purchase data that supermarket scan data obscures. Subscription models show highest penetration in Nordic urban markets with mature delivery infrastructure.
- Health Food Stores:Certified organic supply chains command placement with margin structures above conventional frozen.
- Specialty Grocery:Curated assortments targeting health-conscious consumers seeking novel protein formats.
Supermarkets hold installed capacity. Online retail is rotating up the share rankings.
End User:
Customer type determines frequency of purchase and willingness to absorb premium pricing for certification and sensory fidelity.
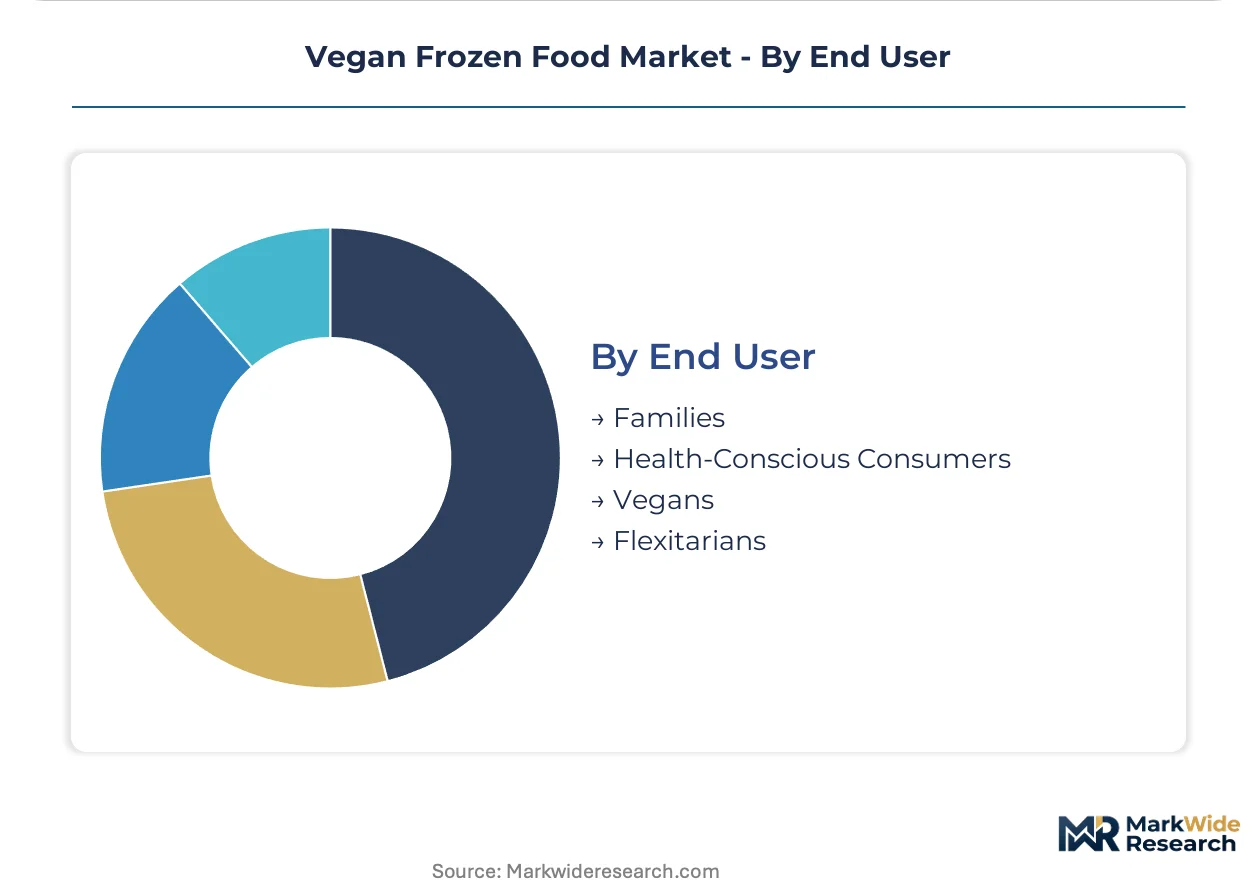
- Flexitarians:Households reducing meat consumption without full dietary conversion drive the largest addressable volume. German retail data shows this segment purchasing private-label vegan frozen ranges alongside conventional proteins.
- Health-Conscious Consumers:Buyers prioritizing organic certification and clean-label ingredient decks. USDA organic and V-Label certifications validate premium positioning for this segment in specialty channels.
- Families:Convenience-oriented purchasers seeking meal solutions with simplified preparation.
- Vegans:Core demographic with highest loyalty but smallest absolute population.
Flexitarians hold installed capacity. Health-conscious consumers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's Farm to Fork Strategy is tightening sustainability criteria for processed food labeling across member states. Supermarket chains in Germany, the Netherlands, and Denmark are expanding dedicated plant-based freezer sections to capture flexitarian household spending. The analysis traces demand concentration through specific national regulatory and retail configurations.
Germany
Discounters Aldi and Lidl have aggressively broadened private-label vegan frozen ranges, normalizing plant-based meal replacement across mass-market demographics. EFSA guidance on environmental claims forces reformulation investments for multi-ingredient products seeking retail authorization. Berlin and Hamburg anchor foodservice procurement clusters where institutional buyers mandate plant-based meal quotas.
United States
FDA nutrition labeling requirements and USDA organic certification standards govern product claims and ingredient disclosure for frozen meat analogues. Health-conscious consumers in coastal metros drive subscription-based repeat purchases through direct-to-home channels. Chicago and Los Angeles concentrate cold-chain distribution hubs serving retail and foodservice segments.
Netherlands
High-moisture extrusion technology adoption concentrates among foodservice distributors serving institutional catering contracts. REACH compliance documentation elevates traceability costs for imported protein concentrates. The Randstad corridor hosts formulation R&D clusters developing next-generation texture benchmarks for frozen applications.
United Kingdom
Supermarket chains are consolidating freezer-section real estate around V-Label certified SKUs, forcing reformulation investments from mid-sized processors. FSA allergen labeling requirements intersect with novel protein disclosure mandates. London and Manchester anchor health food store networks commanding premium placement margins above conventional frozen.
Sweden
Urban density and delivery infrastructure maturity produce the highest subscription penetration for direct-to-consumer vegan frozen replenishment. CSRD-aligned sustainability reporting pressures corporate foodservice procurement toward certified supply chains. Stockholm and Gothenburg specialty retailers deploy hybrid click-and-collect fulfillment to defend foot traffic against pure-play e-commerce.
Vegan Frozen Food Market Competitive Landscape
Player mix skews toward mid-sized processors with dedicated extrusion infrastructure rather than commodity vegetable packers. Market structure fragments across certification tiers, with V-Label authorization creating shelf-placement gatekeeping. Three archetypes dominate: capital-intensive extrusion operators, certified organic supply chain specialists, and private-label contract manufacturers. Competitive moves concentrate on backward integration into pea-protein supply and geographic licensing of high-moisture extrusion technology.
Within the extrusion-technology tier, Beyond Meat and Amy's Kitchen exemplify divergent positioning strategies. Beyond Meat anchors capital-intensive infrastructure plays sustaining consistent texture benchmarks across frozen applications. Amy's Kitchen occupies a position anchored through certified organic supply chains that command premium placement in health food channels. Daiya Foods represents the ingredient-differentiation archetype, competing on tapioca-based formulations distinct from soy-dominant rivals.
| Leading Market Players |
|---|
| Beyond Meat |
| Impossible Foods |
| Oatly |
| Tofurky |
| Gardein |
| MorningStar Farms |
| Amy's Kitchen |
| Daiya Foods |
| Alpro |
| Others |
Pricing and Supply Chain Analysis
Sixty-day frozen inventory cycles in European retail channels concentrate working capital requirements among processors lacking direct-to-consumer subscription infrastructure, compressing margin structures for commodity vegetable packers while amplifying pricing power for extrusion-capable operators with V-Label certification.
Pricing Analysis
Certification level creates the primary spread between premium and economy tiers, with V-Label and USDA organic authorizations commanding placement margins substantially above conventional frozen positioning. Three-tier pricing structure across certified organic, V-Label standard, and private-label economy levels segments buyer archetypes, with flexitarian households in German discounters exhibiting highest price sensitivity while health-conscious subscribers in Nordic urban markets absorb premium positioning. Cost compression in economy tiers intensifies because North American pea-protein processors control upstream supply, exposing contract manufacturers to harvest volatility without captive sourcing.
Supply Chain Analysis
Strategic stockpiling of pea-protein isolates and fava bean concentrates dominates inventory strategy among scaled operators, contrasting with just-in-time vegetable sourcing that leaves smaller processors exposed to seasonal price swings. Upstream concentration centers on Canada and the United States for pulse processing, with secondary sourcing from France and Germany for regional formulation. Supply chain risk manifests through single-source vulnerability for high-moisture extrusion equipment and specialized shear-cell components. Distribution runs through supermarket chains consolidating freezer-section real estate, with cold-chain fragmentation in Southern Europe forcing hub-and-spoke logistics configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's carbon-footprint labeling mandates constitute a regulatory inflection that will disqualify uncertified formulations from mainstream retail authorization, accelerating consolidation around operators with traceable supply chains.
For Market Incumbents: Compound defensible positioning through backward integration into Canadian and North American pulse processing, securing volume commitments that insulate against harvest volatility. Prioritize extrusion capacity expansion in Germany and the Netherlands to capture institutional foodservice quotas. Certification investment in V-Label and EU organic tiers creates shelf-placement gatekeeping against contract manufacturers dependent on tolling arrangements. For New Entrants and Emerging Players: Direct-to-consumer subscription fulfillment gaps in Southern European markets present white-space targets where incumbent supermarket chains lack dedicated minus 18 Celsius last-mile infrastructure. Foodservice channel penetration in Nordic institutional catering offers penetrable volume anchors absent entrenched competitor relationships. Go-to-market execution should leverage hybrid click-and-collect partnerships with specialty retailers defending foot traffic against pure-play e-commerce. For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-premium play because regulatory tightening on carbon-accounted supply chains will progressively deauthorize conventional formulations. Acquisition targets should concentrate on mid-sized processors with in-house extrusion infrastructure and existing V-Label authorization, avoiding commodity vegetable packers without protein texturization capabilities. The signal to watch is EFSA novel food authorization timelines for fermentation-derived proteins, which would reset competitive economics if accelerated.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulse Processing | Captive supply of Canadian pea-protein isolates insulates margin structures from harvest volatility exposure. |
| V-Label Certification Investment | Third-party audit authorization unlocks shelf placement in German supermarket chains consolidating freezer real estate. |
| High-Moisture Extrusion Capacity Expansion | In-house shear-cell infrastructure separates texture-capable operators from tolling-dependent contract manufacturers. |
| Direct-to-Consumer Subscription Launch | Nordic urban density and delivery maturity support repeat purchase data capture obscured by supermarket scan data. |
| Foodservice Channel Penetration | Institutional procurement quotas in Sweden and Denmark create volume anchors for scaled production economics. |
Research Methodology
The analysis maps plant-based meals, meat alternatives, frozen vegetables, and vegan ice cream segments, each validated through formulation chemists, supermarket category buyers, foodservice procurement directors, and cold-chain logistics operators. Primary interviews with R&D heads at extrusion-capable processors and private-label sourcing managers at German discounters combined with secondary validation from EFSA guidance documents, EU Green Deal Farm to Fork Strategy filings, USDA organic certification databases, and Nielsen retail audit data. Bottom-up SKU-level volume builds triangulated against top-down category spend estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, protein source, distribution channel, and certification tier. CAGRs derived from category growth rates applied to penetration assumptions for flexitarian household conversion. Industry-specific inputs incorporated EFSA novel food authorization timelines and cold-chain infrastructure maturity indices by country.
Forecasts assume regulatory continuity in EU Green Deal implementation and FDA nutrition labeling requirements; material policy shifts would require re-modeling. Revision becomes warranted when carbon-footprint labeling mandates accelerate or pea-protein harvest volatility exceeds historical bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
South America RTE Food Market
Processed and Frozen Foods
Dumplings Market
Processed and Frozen Foods
Low-Fat Cool Whip Market
Processed and Frozen Foods
Kimchi Market
Processed and Frozen Foods
Processed and Frozen Fruits Market
Processed and Frozen Foods
Frozen Noodles and Rice Products Market
Processed and Frozen Foods
Frozen Shrimp Market
Processed and Frozen Foods
Frozen-Cooked Ready Meals Market
Processed and Frozen Foods
United Arab Emirates Frozen Food Market
Processed and Frozen Foods
Frozen Baby Food Market
Processed and Frozen Foods
Indonesia Frozen Food Market
Processed and Frozen Foods
Frozen Mushroom Market
Processed and Frozen Foods
Frozen Processed Food Market
Processed and Frozen Foods
Asia Pacific Frozen Desserts Market
Processed and Frozen Foods
Dehydrated Potato Market
Processed and Frozen Foods
Cold Cuts Market