
 Kombucha Market | 2026-2036
Kombucha Market Size, Share, and Industry Trends Forecast 2026-2036
Kombucha Market Analysis
Natural cane sugar is repositioning product economics as brands reduce refined sugar content without sacrificing fermentation integrity. GT's Living Foods leverages vertical integration from tea sourcing to bottling. Health-Ade sustains R&D intensity in small-batch fermentation protocols. Brew Dr. Kombucha anchors geographic dominance through Pacific Northwest production scale.
Kombucha is a fermented tea beverage produced through symbiotic culture of bacteria and yeast (SCOBY) at pH levels typically between 2.5 and 3.5, yielding organic acids, B vitamins, and trace ethanol. Its primary commercial purpose centers on functional refreshment with perceived digestive and immune benefits. Flavored variants lead volume share while organic certification captures premium margin pools. Supermarkets dominate distribution throughput, though online retail channels exhibit the fastest expansion trajectory.
The FDA governs alcohol content thresholds and labeling requirements for kombucha sold in the United States, while the USDA Organic standard shapes ingredient sourcing and certification premiums. The EU's novel food regulations affect SCOBY-derived products entering European markets. Stakeholders must monitor evolving alcohol-by-volume enforcement thresholds and adapt formulation strategies accordingly.
Market Dynamics
The kombucha market is being fundamentally restructured by alcohol-by-volume enforcement thresholds, which are compressing formulation tolerances and forcing producers to recalibrate fermentation protocols or face reclassification as alcoholic beverages.
Growth Catalysts
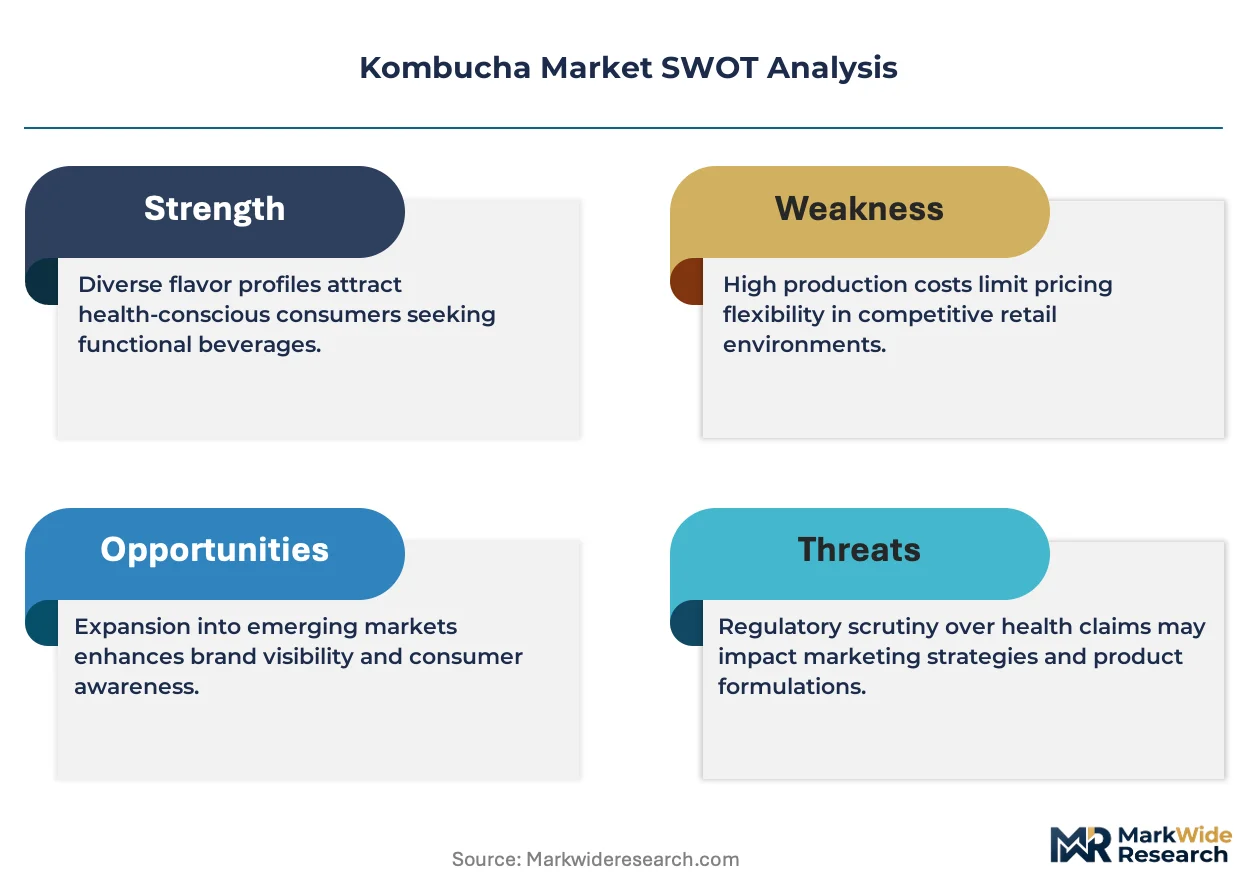
- FDA Labeling Modernization:Updated guidance on fermented beverage alcohol content creates compliance clarity that reduces regulatory uncertainty for scaling producers.
- Supermarket Channel Expansion:Mass retail placement in refrigerated beverage sections exposes kombucha to routine grocery shoppers rather than specialty health food consumers.
- Small-Batch Fermentation Protocols:Controlled SCOBY cultivation methods enable consistent pH stability between 2.5 and 3.5, preserving shelf integrity without pasteurization.
Market Restraints
- Tea Input Cost Volatility:Organic camellia sinensis leaf prices fluctuate with climate-driven harvest variability in India and Sri Lanka.
- Glass Bottle Supply Concentration:Premium kombucha packaging depends on limited North American glass manufacturing capacity, creating lead time vulnerability.
- EU Novel Food Classification:SCOBY-derived products face extended safety assessment timelines before European market entry authorization.
Strategic Opportunities
- Online Retail Channel Penetration:Direct-to-consumer subscription models bypass traditional distributor markups while capturing repeat purchase data.
- Functional Flavor Convergence:Adaptogenic ingredient integration with traditional fermentation creates premium positioning in wellness-oriented beverage portfolios.
- USDA Organic Certification Tailwind:Federal organic standards create price premium capture for certified supply chains in conventional retail placement.
Industry Challenges
- Microbiology Talent Scarcity:SCOBY cultivation expertise resides with a limited pool of fermentation specialists, constraining quality-controlled scale-up.
- Cold Chain Capex Intensity:Refrigerated distribution infrastructure requirements demand substantial capital deployment for geographic expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kombucha Market |
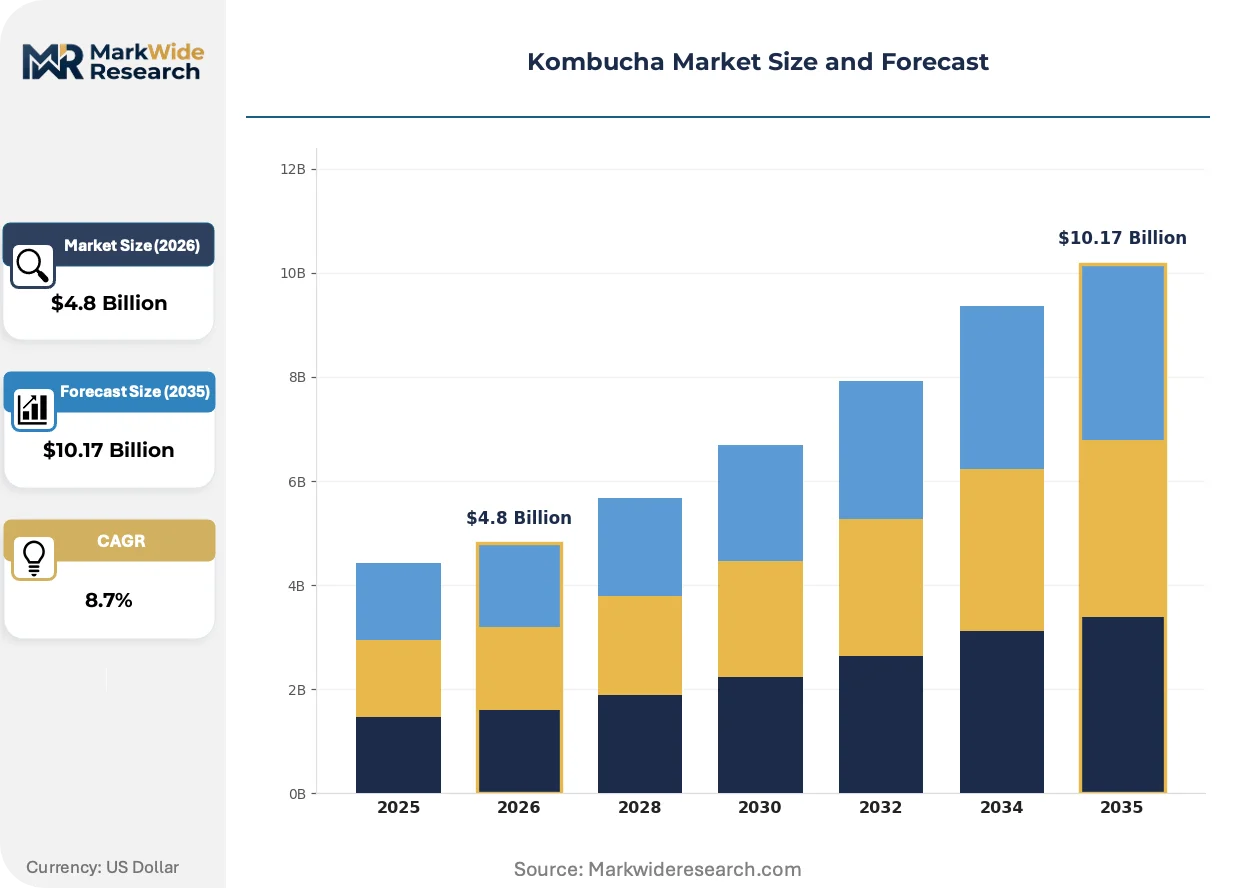
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Sparkling, Flavored, Organic Distribution Channel: Supermarkets, Online Retail, Health Stores, Restaurants Packaging Type: Bottles, Cans, Kegs, Pouches End User: Health Conscious Consumers, Millennials, Fitness Enthusiasts, Organic Product Users |
| Companies Covered | GT's Living Foods, Health-Ade, Brew Dr. Kombucha, Remedy Drinks, Humm Kombucha, KeVita, SYSTM Foods, GO Kombucha, MOMO Kombucha, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kombucha Market Emerging Trajectories
Refrigerated beverage infrastructure is absorbing kombucha into mainstream retail layouts, displacing shelf-stable alternatives and reconfiguring how functional drinks reach consumers.
Continuous fermentation monitoring technology is absorbing quality control functions previously handled by manual pH testing and sensory evaluation. Mid-scale producers are adopting dissolved oxygen and acidity sensors at accelerating rates. This automation is absorbing labor cost pressures while compressing batch-to-batch variability that previously constrained private label contract manufacturing.
The EU's F-Gas Regulation is tightening cold chain refrigerant standards for beverage transport and retail display cases. This policy is forcing logistics providers to retrofit refrigerated vehicles and supermarket cases with lower-global-warming-potential alternatives. German and French kombucha distributors are absorbing compliance costs through consolidated regional warehousing to reduce transport refrigeration exposure.
Subscription-based replenishment models are capturing repeat consumers who previously purchased kombucha through intermittent supermarket visits. This channel shift is disintermediating traditional distributor relationships and concentrating buyer data with direct-to-consumer platforms. The United States exhibits the most visible adoption, where urban consumers prioritize convenience over in-store discovery.
Kombucha Market Segmentation
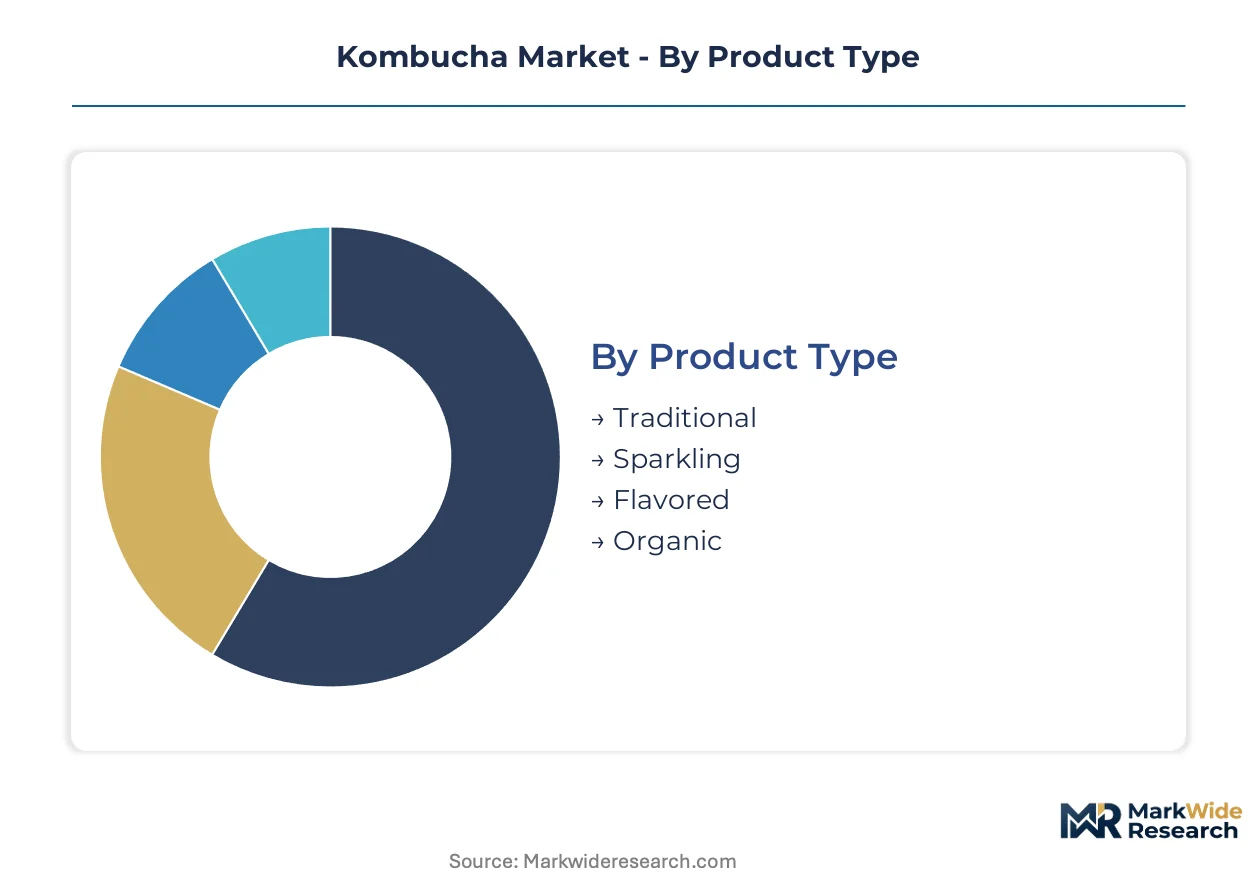
Segmentation in kombucha reveals how fermentation specifications, distribution infrastructure, and consumer identity intersect to determine pricing power and channel access. Product chemistry and packaging format dictate cold chain requirements, while end-user psychographics shape whether brands pursue mass retail or premium specialty positioning.
Product Type:
Fermentation protocols and ingredient composition define the technical axis, separating shelf-stable formulations from live-culture products requiring continuous refrigeration.
- Traditional:Unpasteurized SCOBY-fermented tea maintaining live bacterial cultures at pH 2.5-3.5, demanding refrigerated distribution throughout the supply chain. Health-conscious consumers in Germany and Australia drive demand for authentic fermentation integrity over convenience.
- Flavored:Fruit, botanical, and spice infusions added during secondary fermentation, commanding 30-50% price premiums over base formulations. Millennials in US coastal metros concentrate demand for novel flavor rotations that support subscription replenishment models.
- Sparkling:Carbonation-enhanced variants with controlled CO2 injection or extended fermentation, bridging kombucha with mainstream sparkling beverage occasions. Fitness enthusiasts favor post-workout consumption due to perceived electrolyte content.
- Organic:USDA or equivalent certified ingredients with audited supply chains from tea sourcing through bottling. Organic Product Users absorb price premiums that conventional formulations cannot sustain in supermarket placement.
Flavored variants lead on scale; organic certification leads on margin expansion.
Distribution Channel:
Cold chain capital intensity and buyer data capture separate channels, with refrigerated infrastructure requirements filtering which producers can operate at each tier.
- Supermarkets:Mass retail refrigerated beverage sections with slotting fees and velocity requirements that eliminate small-batch producers. United States conventional grocery chains anchor volume throughput for scaled brands with regional distribution networks.
- Online Retail:Direct-to-consumer and third-party marketplace sales enabling subscription models and flavor customization. This channel is expanding most quickly in urban US markets where convenience outweighs in-store discovery.
- Health Stores:Specialty retailers with educated staff and premium positioning, prioritizing live-culture integrity and local sourcing credentials. Australia’s independent health food sector sustains higher kombucha prices than mass channels.
- Restaurants:On-premise draft and bottled service, particularly in wellness-oriented fast-casual concepts. German café culture integrates kombucha into beverage programs as alcohol alternatives gain acceptance.
Supermarkets dominate absolute volume; online retail leads on data capture and repeat purchase economics.
Packaging Type:
Material specifications and single-serve versus bulk format determine transport economics, retail placement flexibility, and consumption occasion targeting.
- Bottles:Glass and PET containers dominating premium positioning, with amber glass protecting light-sensitive cultures. Glass bottle supply concentration in North America creates lead time vulnerability for scaled producers.
- Cans:Aluminum formats enabling ambient distribution trials and outdoor consumption occasions, though internal lining requirements complicate live-culture claims. Fitness enthusiasts favor cans for gym and trail portability.
- Kegs:Stainless steel draft systems for foodservice and office dispensing, reducing per-ounce packaging cost dramatically. German restaurant chains deploy kegs for consistent quality and waste reduction.
- Pouches:Flexible film formats for children’s portions and sampling programs, limited by consumer perception of quality compromise. Australian brands test pouches for school lunchbox positioning.
Bottles command premium shelf positioning; cans are gaining share fastest in active-lifestyle distribution.
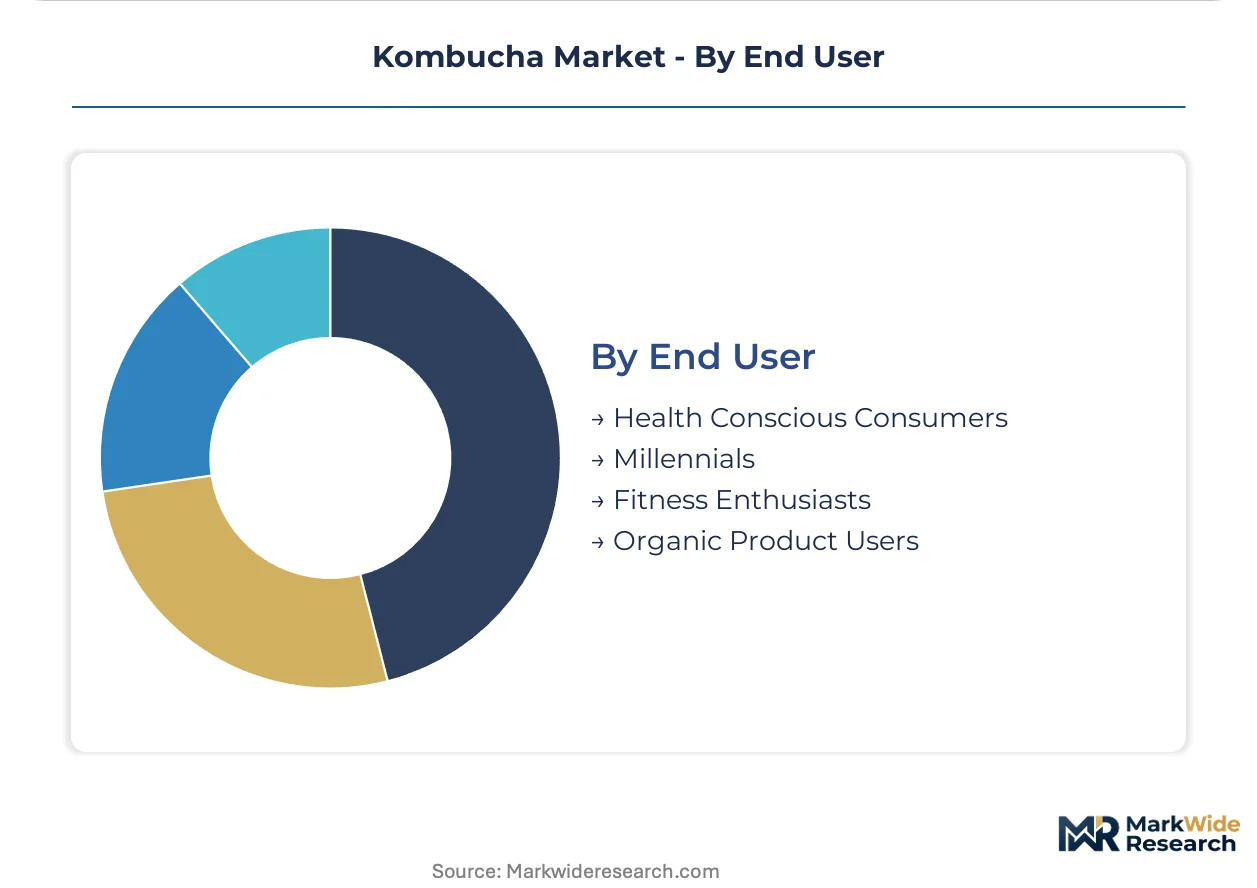
End User:
Consumer identity and purchase motivation determine whether brands emphasize functional claims, lifestyle alignment, or value accessibility in messaging and formulation.
- Health Conscious Consumers:Primary target segment prioritizing digestive and immune function claims, with willingness to pay certification premiums. This group concentrates in US and Australian metro areas with above-average wellness expenditure.
- Millennials:Digital-native cohort driving flavor innovation and social media discovery, with subscription adoption rates exceeding older demographics. Urban US millennials favor direct-to-consumer brands with transparent sourcing stories.
- Fitness Enthusiasts:Exercise-oriented consumers treating kombucha as recovery or hydration alternatives to sports drinks. Post-workout consumption occasions in German fitness studios support functional positioning.
- Organic Product Users:Certification-driven purchasers with cross-category loyalty to USDA Organic and equivalent standards, accepting 20-40% price premiums for audited supply chains. This segment sustains margin pools that conventional formulations cannot access.
Health Conscious Consumers anchor category volume; Millennials drive innovation velocity and channel experimentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pacific Northwest production clusters anchor kombucha manufacturing density in the United States, with Portland and Seattle metropolitan areas hosting scaled fermentation facilities and SCOBY cultivation expertise. German Bavaria and Australian New South Wales sustain comparable ecosystem development through craft beverage infrastructure and health food retail networks.
United States
Millennial subscription adoption and supermarket refrigerated section expansion drive volume growth in coastal metros. FDA alcohol-by-volume enforcement thresholds shape formulation compliance requirements for interstate commerce. Pacific Northwest cities concentrate production scale, with Portland-area facilities supplying West Coast distribution networks.
Germany
Café culture integration and alcohol-alternative beverage demand support on-premise draft placement in Berlin and Munich. EU F-Gas Regulation cold chain refrigerant standards force logistics retrofitting for refrigerated transport fleets. Bavaria anchors manufacturing concentration, with Munich-area producers leveraging regional brewing heritage for fermentation expertise.
Australia
Health food retail premium positioning and independent store density sustain higher price points than mass channels. TGA therapeutic claims oversight shapes labeling restrictions for digestive and immune benefit assertions. New South Wales clusters production in Sydney metropolitan fermentation facilities serving domestic and Asia-Pacific export markets.
United Kingdom
London wellness expenditure concentration and direct-to-consumer brand discovery drive urban trial rates. Food Standards Agency novel food consultations affect SCOBY-derived product authorization timelines. Southeast England logistics hubs consolidate cold chain distribution for European market access.
Canada
Health Canada natural health product classification creates regulatory pathway clarity for functional positioning claims. British Columbia and Ontario metropolitan markets concentrate demand through specialty grocery and fitness studio placement. Toronto-area production facilities serve Quebec and Prairie province distribution networks.
Kombucha Market Vendor Landscape
Global majors compete with regional champions across fermentation scale and cold chain reach, producing a tiered structure where scaled producers occupy supermarket refrigerated sections while craft specialists defend health store positioning. Market concentration splits between vertically integrated tea-to-bottle operators and contract-manufacturing-dependent brands. Three archetypes dominate: Pacific Northwest production-scale leaders, Southern California R&D-intensive formulators, and Australian export-oriented specialists. Competitive moves center on supermarket slotting fee negotiations and direct-to-consumer platform development.
Within the production-scale tier, GT's Living Foods and Health-Ade exemplify vertically integrated fermentation operations, while Brew Dr. Kombucha anchors Pacific Northwest geographic concentration. These entities represent alternative strategic postures around tea sourcing control, small-batch protocol fidelity, and regional production density.
| Leading Market Players |
|---|
| GT's Living Foods |
| Health-Ade |
| Brew Dr. Kombucha |
| Remedy Drinks |
| Humm Kombucha |
| KeVita |
| SYSTM Foods |
| GO Kombucha |
| MOMO Kombucha |
| Others |
Supply Flow & Price Mechanics
Family-owned fermentation specialists with multi-generational SCOBY cultivation expertise anchor supply-side discipline, translating limited microbiology talent pools into pricing power that resists commoditization pressure from contract-manufacturing-dependent brands.
Pricing Analysis
Organic camellia sinensis leaf cost pass-through from India and Sri Lanka harvest volatility compresses margin buffers for non-integrated producers. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic certified supply chains from conventional formulations and private-label alternatives. Price differentiation hinges on certification grade and regional distribution density. Pricing pressure stems from supermarket slotting fee escalation in United States conventional grocery chains. Health Conscious Consumers exhibit lowest price sensitivity while value-oriented supermarket shoppers drive economy tier volume.
Supply Chain Analysis
Glass bottle supply rests on concentrated North American manufacturing capacity, creating lead time vulnerability for scaled producers dependent on amber glass for light-sensitive culture protection. Tea sourcing draws from India, Sri Lanka, and China; SCOBY cultivation expertise concentrates in United States Pacific Northwest, Germany, and Australia. Single-source vulnerability in specialty fermentation equipment constrains quality-controlled scale-up. Distribution runs through refrigerated beverage infrastructure with cold chain capex intensity filtering producer participation by geography.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kombucha market operates as a regulatory compounder where FDA alcohol-by-volume enforcement thresholds continuously reshape formulation compliance requirements and create competitive moats for producers with microbiology talent depth.
For Market Incumbents: Acquire SCOBY cultivation expertise pools to consolidate limited fermentation specialist talent before emerging craft competitors scale quality-controlled operations. Invest in continuous fermentation monitoring technology to automate pH stability protocols and reduce batch-to-batch variability that constrains private label contract manufacturing. Defend against direct-to-consumer platform disintermediation by locking supermarket refrigerated section placement through long-term velocity commitments. For New Entrants and Emerging Players: Continuous fermentation monitoring technology enables quality consistency without legacy microbiology headcount, creating entry pathway for capital-efficient challengers. Target online retail channel penetration in urban United States markets where subscription replenishment models bypass traditional distributor markups and capture repeat purchase data. Pursue functional flavor convergence with adaptogenic ingredient integration to secure premium positioning in wellness-oriented beverage portfolios. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale producers with Pacific Northwest production density and captive tea sourcing but underdeveloped direct-to-consumer platforms. Five-to-ten year viability favors vertically integrated operators with USDA Organic certification and supermarket slotting fee tolerance over contract-manufacturing-dependent brands exposed to input cost volatility. Watch EU novel food classification resolution timelines as inflection indicator for SCOBY-derived product European market entry authorization.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Subscription models bypass distributor markups while capturing repeat purchase data in urban United States markets. |
| USDA Organic Certification Investment | Federal organic standards unlock price premium capture in conventional retail placement against conventional formulations. |
| Continuous Fermentation Technology Deployment | Dissolved oxygen and acidity sensors compress batch-to-batch variability and absorb labor cost pressures. |
| Backward Integration into Tea Sourcing | Captive supply of organic camellia sinensis leaves insulates margin from climate-driven harvest volatility in India and Sri Lanka. |
| EU Market Entry Authorization Pursuit | Novel food safety assessment completion opens SCOBY-derived product access to German café culture and alcohol-alternative demand. |
Methodological Framework
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with fermentation specialists, supermarket category buyers, cold chain logistics operators, and health food retail procurement managers with secondary validation from FDA guidance documents, USDA Organic certification databases, EU F-Gas Regulation compliance filings, and refrigerated beverage retail audit data.
Input-output matrix framing connects organic tea harvest volumes, glass bottle manufacturing capacity, and SCOBY cultivation facility counts to end-user consumption patterns across health-conscious consumers, millennials, fitness enthusiasts, and organic product users. Segmentation dimensions span product type, distribution channel, packaging format, and end-user psychographics. CAGRs derive from regression analysis against regulatory milestone timelines and channel expansion trajectories. Forecast inputs incorporate alcohol-by-volume enforcement threshold evolution and EU novel food classification resolution scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to climate-driven tea harvest variability, glass supply concentration disruption, and microbiology talent scarcity constraining quality-controlled scale-up. A small set of named triggers warrants ongoing watch: FDA alcohol content threshold adjustments, EU F-Gas Regulation cold chain retrofit compliance costs, and Pacific Northwest production cluster expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Hydration Infusers Market
Beverages
Reconstituted Juice Market
Beverages
Italy Probiotic Drinks Market
Beverages
Europe Bottled Water Processing Market
Beverages
Craft Soda Market
Beverages
China Soy Beverages Market
Beverages
Plant Based Beverages Market
Beverages
South America Mate Market
Beverages
Direct Piping Water Dispenser Market
Beverages
Asia Pacific Dairy Based Beverages Market
Beverages
Fruit Vinegar Market
Beverages
North America Juices Market
Beverages
Drinking Water Market
Beverages
Commercial Sparkling Water Dispenser Market
Beverages
Global Electrolyte Drinks Market
Beverages
North America Sugar Free Energy Drinks Market