
 North America Energy Drink Market | 2026-2036
North America Energy Drink Market Size, Share, and Industry Trends Forecast 2026-2036
North America Energy Drink Market Analytics
Functional ingredient platforms is reshaping formulation architectures across the North America energy drink sector. Monster Beverage Corporation leverages its diversified flavor science pipeline to sustain shelf presence in convenience channels. Celsius Holdings differentiates through thermogenic positioning and health-club distribution density. Red Bull GmbH anchors premium pricing through event-sponsorship ecosystems and cultural cachet.
North America energy drinks are caffeinated functional beverages, typically formulated with taurine, B-vitamins, and botanical extracts, manufactured through hot-fill or aseptic processing to preserve active compound stability. Their primary commercial purpose is delivering acute mental alertness and physical performance enhancement to fatigued or time-constrained consumers. Carbonated variants still occupy the largest revenue pool, though sugar-free formulations are capturing disproportionate growth as consumers reject high-fructose corn syrup. Ready-to-drink formats dominate volume, while powdered and shot formats are expanding fastest among gym-centric and travel-use occasions.
The FDA governs caffeine content disclosures and novel ingredient safety assessments, while the USDA's National Organic Program shapes certification pathways for organic-positioned entrants. State-level sugar taxes in select jurisdictions are forcing reformulation investments and pricing recalibrations. Stakeholders must monitor how the FTC's evolving guidance on energy marketing claims to minors intersects with state legislative proposals to restrict sales to adolescent buyers.
Market Dynamics
The North America energy drink sector is undergoing a formulation pivot driven by the FDA's intensifying scrutiny of caffeine disclosure thresholds and state-level sugar taxation schemes. This regulatory pressure is compressing legacy high-sugar portfolios while accelerating clean-label investments.
Growth Catalysts
- Gym-centric consumption occasions:Fitness communities in Texas and California are normalizing pre-workout energy drink rituals, expanding volume per capita beyond traditional convenience-store purchase patterns.
- USDA National Organic Program certification:Organic-positioned entrants are capturing shelf space in natural-channel retailers, creating premium pricing corridors previously occupied by conventional formulations.
- FTC guidance evolution on youth marketing:Self-regulatory frameworks are pushing brands toward adult-targeted messaging, inadvertently sharpening demographic focus and improving media efficiency.
Market Restraints
- High-fructose corn syrup input volatility:Corn futures fluctuations and biofuel policy competition are compressing margin structures for sugar-dependent legacy portfolios.
- Supply concentration in aluminum can manufacturing:Domestic can sheet production capacity bottlenecks are extending lead times for new product launches and seasonal promotions.
- Caffeine content technical ceilings:FDA-advised daily intake thresholds limit formulation differentiation, constraining functional claim expansion for stimulant-heavy variants.
Strategic Opportunities
- Underpenetrated Canadian provinces:Quebec and British Columbia exhibit per-capita consumption gaps relative to US benchmarks, offering white-space expansion for thermogenic-positioned entrants.
- Powdered format channel innovation:Direct-to-consumer subscription models are bypassing traditional convenience-store slotting fees, improving unit economics for niche flavor platforms.
- California state sugar tax regulatory tailwind:Reformulation mandates are accelerating clean-label R&D investments that yield exportable product architectures for other jurisdictions.
Industry Challenges
- Flavor chemist talent scarcity:Specialized formulation expertise for masking alternative sweetener aftertastes is concentrating among a small pool of beverage scientists, inflating compensation costs.
- Co-packer certification timeline compression:USDA Organic and SQF facility dual-certification requirements are extending new product commercialization cycles by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Energy Drink Market |
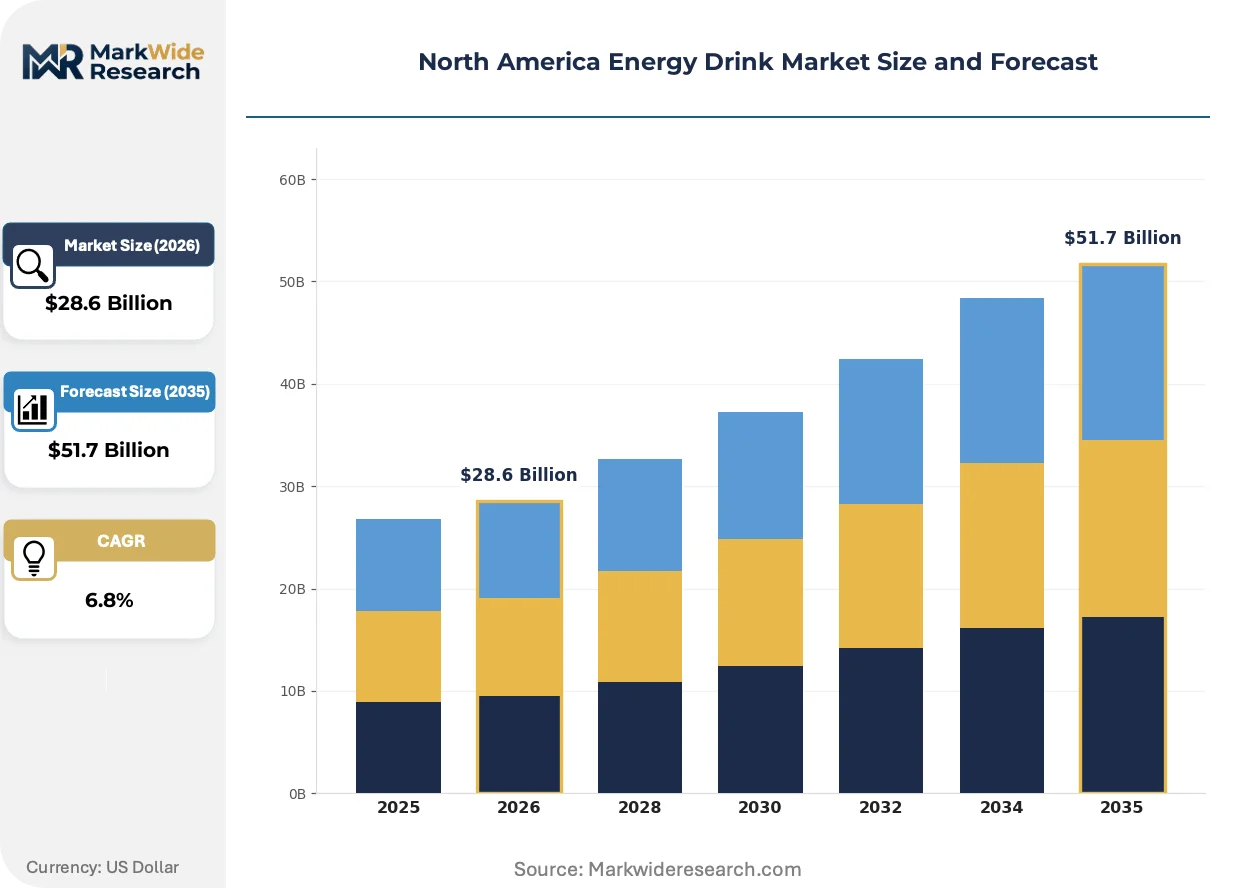
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated, Non-Carbonated, Organic, Sugar-Free Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Stores End User: Teens, Young Adults, Professionals, Athletes Formulation: Ready-to-Drink, Powdered, Shots, Concentrates |
| Companies Covered | Red Bull GmbH, Monster Beverage Corporation, PepsiCo, The Coca-Cola Company, Keurig Dr Pepper, Living Essentials, Celsius Holdings, Congo Brands, National Beverage Corp, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Energy Drink Market Evolving Landscape
Formulation architectures across the North America energy drink market are pivoting toward functional ingredient platforms that extend beyond caffeine-centric stimulation. This evolution is reshaping competitive differentiation and procurement priorities simultaneously.
Botanical adaptogen complexes are migrating from niche wellness positioning into mainstream energy drink formulations. Gym-centric consumers and esports participants are adopting ashwagandha and rhodiola-enhanced variants at accelerating rates. This ingredient migration is compressing the market share of taurine-dependent legacy formulations while opening premium pricing tiers.
The FDA's evolving caffeine labeling requirements are forcing granular disclosure of synthetic versus natural caffeine sources. This policy shift is compelling reformulation investments and supply chain documentation upgrades. Sugar-free and naturally-caffeinated sub-segments are capturing disproportionate shelf space as brands preempt enforcement actions.
Consumer purchasing is fragmenting across channel types as subscription direct-to-consumer models displace convenience-store dominance. Health-club micro-markets and gaming lounge vending are capturing volume that previously flowed through gas station coolers. This behavioral rotation is most visible in California and Texas metropolitan corridors where fitness density and esports venue concentration overlap.
North America Energy Drink Market Segmentation
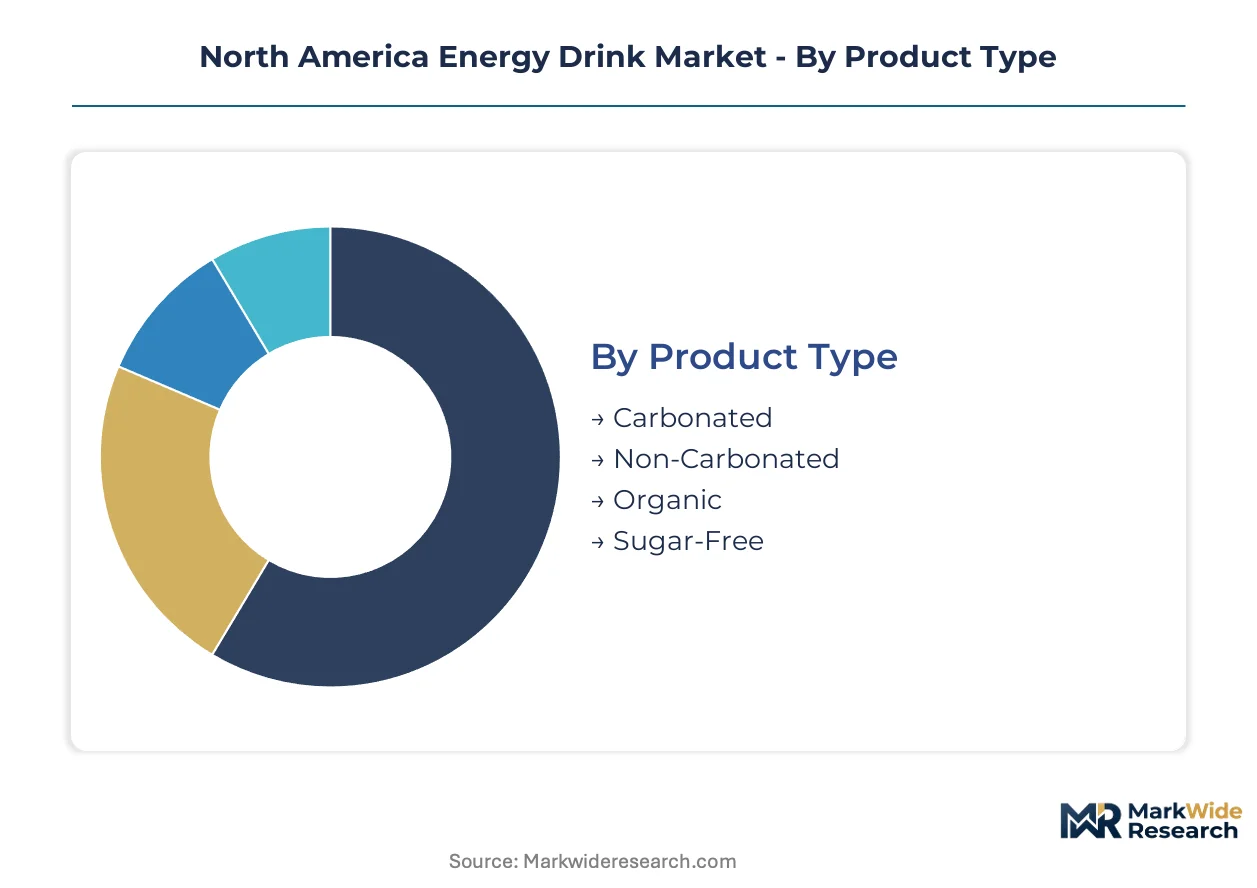
Energy drink segmentation in North America reflects divergent consumption rituals across fitness, gaming, and workplace contexts. Manufacturers calibrate formulation intensity, channel presence, and messaging architecture to match distinct user psychographics and purchase occasions.
Product Type:
Maturity varies sharply across this dimension, with carbonated legacy formats facing margin pressure while emerging clean-label variants capture premium shelf positioning.
- Carbonated:Traditional effervescent formulations rely on high-fructose corn syrup or sucrose bases with synthetic caffeine and taurine complexes. Demand concentrates in Texas and California convenience-store corridors where impulse purchase patterns dominate and cooler placement drives velocity.
- Sugar-Free:Aspartame, sucralose, and stevia-sweetened variants address FDA-advised intake thresholds and state-level sugar tax exposure. Young adult professionals in metropolitan health-club ecosystems are normalizing these as daily consumption staples, expanding per-capita frequency beyond occasional use.
- Non-Carbonated:Still formulations reduce gastrointestinal discomfort for endurance athletes and extended gaming sessions.
- Organic:USDA National Organic Program certification enables natural-channel placement and clean-label pricing premiums.
Carbonated retains volume leadership; sugar-free holds the steepest expansion curve.
Distribution Channel:
Channel economics separate high-velocity mass retail from relationship-driven specialty placement where margin structures differ materially.
- Convenience Stores:Gas station and corner-store coolers generate the highest transaction frequency through impulse-driven single-can purchases. Texas and California volume anchors concentrate here, with slotting fee structures favoring established portfolios with proven turns.
- Online Retail:Direct-to-consumer subscriptions and marketplace fulfillment bypass traditional slotting economics while capturing gym-centric bulk purchasing and flavor exploration behavior. Powdered format compatibility with shipping logistics accelerates this channel's share gain.
- Supermarkets:Grocery multi-pack placements target household pantry stocking and family consumption occasions.
- Health Stores:Natural-channel retailers elevate organic and adaptogen-positioned variants through curated assortment and educated staff recommendation.
Convenience stores dominate transaction volume; online retail climbs the fastest.
End User:
Demographic targeting precision determines regulatory exposure and media efficiency simultaneously.
- Young Adults:College-aged and early-career consumers drive category volume through social consumption rituals, gaming lounge presence, and fitness community integration. FTC guidance on youth marketing is compressing adolescent-directed messaging, sharpening focus on this legally unambiguous cohort.
- Athletes:Competitive and recreational performers demand thermogenic and adaptogen-enhanced formulations with transparent ingredient sourcing. Pre-workout consumption rituals in Texas and California health-club micro-markets expand per-capita consumption beyond traditional patterns.
- Professionals:Workplace alertness applications favor discrete packaging and moderate caffeine dosing for sustained cognitive performance.
- Teens:Legislative proposals in multiple states threaten access restrictions, forcing brand architecture separation from core adult-targeted portfolios.
Young adults anchor category volume; athletes gain share fastest.
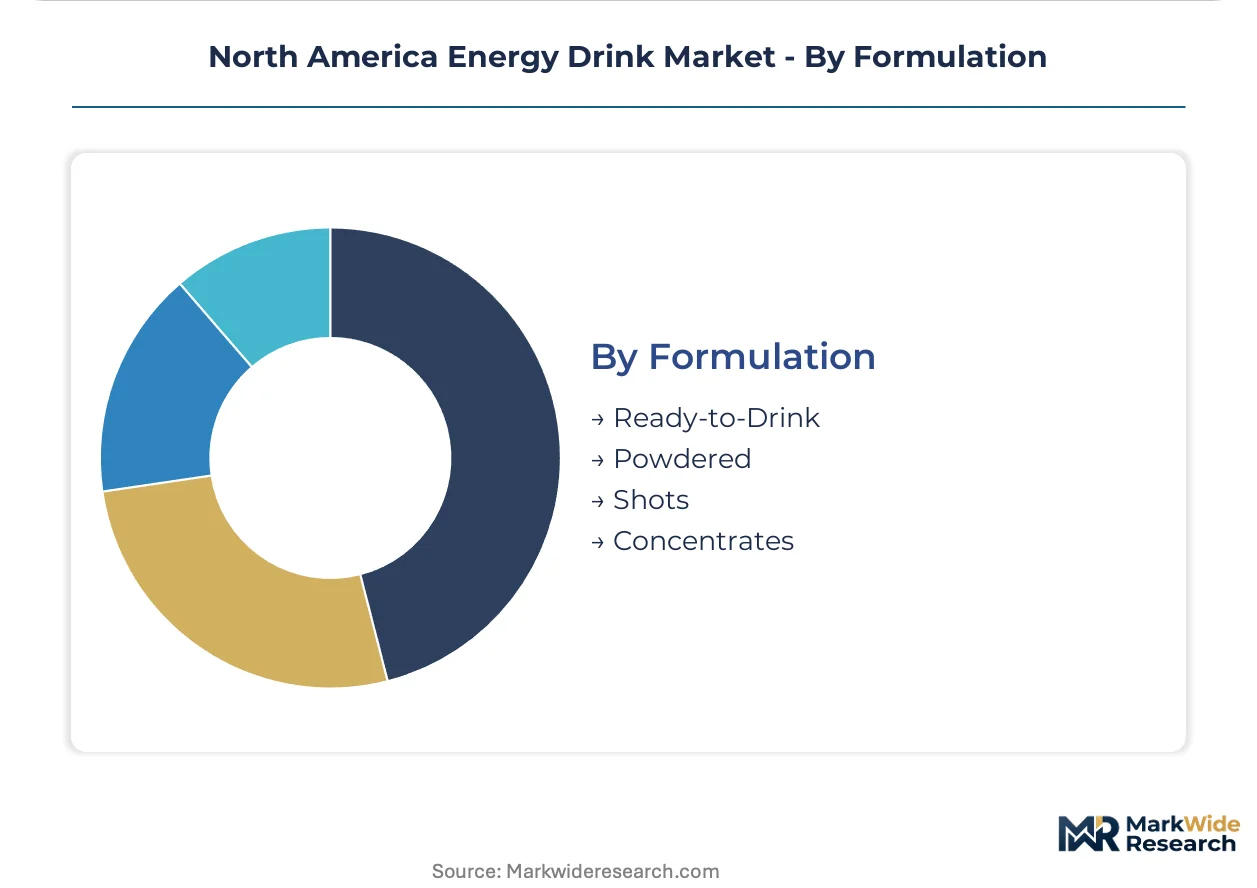
Formulation:
Physical format dictates consumption occasion flexibility and supply chain configuration simultaneously.
- Ready-to-Drink:Canned and bottled single-serve formats occupy cooler space across convenience, grocery, and health-club channels. Aluminum can supply concentration is extending lead times for seasonal promotions and new product launches.
- Powdered:Scoop-and-mix formats enable direct-to-consumer subscription economics and travel-use occasions. Gym-centric consumers in California metropolitan corridors are adopting these for cost efficiency and dose customization.
- Shots:Concentrated small-format delivery suits rapid consumption and portability constraints.
- Concentrates:Dilution-required formats reduce shipping weight and enable fountain or home-mixing applications.
Ready-to-Drink retains volume leadership; powdered expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian energy drink exports flow primarily into the United States through integrated North American distribution networks. Cross-border supply chains leverage shared regulatory frameworks and consolidated retail partnerships. Mexico serves as an emerging production hub for US-bound volume.
United States
Fitness culture penetration in Texas and California metro corridors drives per-capita consumption above national averages. FDA caffeine disclosure requirements are compressing legacy formulation portfolios and accelerating clean-label investments. Chicago and Miami serve as distribution gravity centers where health-club micro-markets and convenience-store channels overlap.
Canada
Quebec and British Columbia exhibit consumption gaps relative to US benchmarks, creating white-space expansion potential for thermogenic-positioned entrants. Health Canada's evolving guidance on caffeine marketing intersects with provincial retail licensing frameworks. Toronto anchors national distribution infrastructure while Vancouver natural-channel retailers elevate organic-certified variants.
Mexico
Manufacturing cost advantages are attracting US brand co-packing investments for re-export volume. SAMR-aligned facility standards facilitate seamless cross-border supply integration. Monterrey and Tijuana industrial corridors concentrate aluminum can filling capacity serving North American demand.
North America Energy Drink Market Competitive Landscape
On the supply side, the industry is consolidating around beverage conglomerates with diversified flavor science pipelines and established convenience-channel slotting relationships. Tiered competitive structures separate premium-positioned specialists from scale-driven mass-market portfolios. Strategic archetypes include thermogenic health-club specialists, event-sponsorship premium brands, and diversified beverage conglomerates. Dominant competitive moves encompass clean-label reformulation investments and direct-to-consumer subscription channel development.
Within the premium-positioned tier, Red Bull GmbH and Celsius Holdings exemplify divergent archetypes—one anchoring cultural cachet through sponsorship ecosystems, the other penetrating health-club density with thermogenic formulations. Monster Beverage Corporation occupies a scale-driven position representing diversified flavor-platform strategies.
| Leading Market Players |
|---|
| Red Bull GmbH |
| Monster Beverage Corporation |
| PepsiCo |
| The Coca-Cola Company |
| Keurig Dr Pepper |
| Living Essentials |
| Celsius Holdings |
| Congo Brands |
| National Beverage Corp |
| Others |
Value Network & Pricing Analysis
Aluminum can sheet supply concentration in domestic manufacturing corridors determines both premium-to-economy pricing spreads and supply chain configuration across the North America energy drink sector. Input volatility in high-fructose corn syrup futures simultaneously compresses legacy portfolio margins and accelerates clean-label sourcing investments.
Pricing Analysis
Legacy carbonated formulations versus sugar-free next-generation variants versus organic-certified premium tiers stratify across three distinct pricing levels. Premium-mid-economy pricing differentiation rests on USDA Organic certification status, health-club channel placement density, and adaptogen ingredient transparency. Cost compression in economy-tier carbonated portfolios is intensifying because corn futures volatility intersects with state sugar tax exposure. Young adult professionals in metropolitan fitness ecosystems exhibit lowest price sensitivity; convenience-store impulse buyers in Texas and California corridors show highest elasticity.
Supply Chain Analysis
Extended payment terms from aluminum can manufacturers are compressing working capital cycles for mid-tier brands while supply-chain finance facilities concentrate among beverage conglomerates with diversified procurement leverage. Domestic can sheet production in the United States, cross-border filling capacity in Mexico, and Canadian natural-channel distribution infrastructure anchor North American supply geography. Formulation inputs draw from high-fructose corn syrup, stevia and sucralose alternatives, and botanical adaptogen extracts. Single-source vulnerability in domestic aluminum smelting creates tariff exposure chokepoints. Distribution runs through integrated convenience-store cooler networks, health-club micro-market vending, and direct-to-consumer subscription fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from functional beverage hybrids and nootropic-positioned wellness shots that capture gym-centric consumption occasions. Defense requires sharpening differentiation through formulation architecture and channel control investments.
For Market Incumbents: Entrench shelf presence through exclusive cooler placement contracts with top convenience-store chains in Texas and California volume corridors. Deepen backward integration into aluminum can manufacturing to neutralize supply concentration risk. Celsius Holdings and Monster Beverage Corporation demonstrate how thermogenic positioning and flavor-platform diversification respectively defend against nootropic shot substitution threats.
For New Entrants and Emerging Players: Build out direct-to-consumer subscription infrastructure for powdered format distribution, bypassing slotting fee barriers that protect incumbent cooler dominance. Quebec and British Columbia consumption gaps relative to US benchmarks offer the most penetrable white-space geography. Health-club micro-market partnerships in California metropolitan corridors provide the clearest go-to-market angle for thermogenic-positioned entrants.
For Investors and Strategic Acquirers: FDA caffeine labeling enforcement reshapes the acquisition landscape by elevating compliance infrastructure value and compressing valuations for legacy synthetic-caffeine portfolios. Five-to-ten year viability favors brands with USDA Organic dual-certification capability and established health-club channel density. Acquisition target archetype: mid-cap specialists with proprietary adaptogen formulation pipelines and SQF-certified co-packer relationships. Signal to watch: state legislative momentum on adolescent sales restrictions that would bifurcate brand architecture requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | USDA Organic certification opens natural-channel placement and premium pricing corridors in California and Texas. |
| Direct-to-Consumer Channel Launch | Powdered format subscription models bypass convenience-store slotting economics and capture gym-centric bulk purchasing. |
| Health-Club Micro-Market Expansion | Fitness ecosystem penetration in metropolitan corridors normalizes pre-workout consumption rituals beyond traditional patterns. |
| Adaptogen Ingredient Pipeline Development | Ashwagandha and rhodiola complexes differentiate from taurine-dependent legacy formulations and command premium shelf positioning. |
| Co-Packer Certification Acceleration | USDA Organic and SQF dual-certification compresses new product commercialization timelines against six-to-nine month industry averages. |
Research Methodology
A standing panel of brand managers at energy drink portfolios, category buyers at convenience-store chains, health-club procurement directors, and flavor chemists at beverage formulation labs provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against FDA caffeine disclosure filings, USDA National Organic Program certification databases, Nielsen retail audit data, and corn futures market records. Bottom-up volume modeling across distribution channels and top-down macroeconomic triangulation anchored the analytical framework.
Scenario-bracketing across regulatory enforcement intensity, corn price volatility bands, and aluminum supply disruption probabilities bounded the projection range. Segmentation dimensions modeled include product type, distribution channel, end-user demographic, and formulation format across the analysis window. CAGRs were derived from trend extrapolation calibrated against historical consumption elasticity patterns. Forecast inputs incorporated state-level sugar tax legislative momentum and FTC guidance evolution on youth marketing restrictions.
Stress conditions across FDA enforcement timelines, corn futures volatility corridors, and aluminum tariff exposure thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory trajectory and commodity market behavior. Macroeconomic contraction, accelerated state adolescent sales restrictions, or breakthrough nootropic formulation adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
South America Mate Market
Beverages
Aloe Vera Juice Market
Beverages
Chocolate Powdered Drinks Market
Beverages
Hot Chocolate Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market
Beverages
Beverage Dispenser Market
Beverages
Still Drinks Market
Beverages
Asia-Pacific Bottled Water Market
Beverages
Chocolate Malt Drink Market
Beverages
Soy Drinks Market
Beverages
Crystal Boba Market
Beverages
Morocco Bottled Water Market
Beverages
Breakfast Drink Market
Beverages
NFC JUICE Market
Beverages
Global Beverage Emulsion Market
Beverages
North America Cold Pressed Juices Market