
 Bubble Food and Beverages Market | 2026-2036
Bubble Food and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Bubble Food and Beverages Market Intelligence
The proliferation of asset-light franchise models is fragmenting the competitive landscape, lowering barriers to entry for new operators. Gong Cha leverages a master franchise system for rapid international expansion. In contrast, HeyTea differentiates through premium branding and direct store ownership in key Chinese cities. Chatime sustains its presence with a flexible kiosk and storefront format.
Bubble food and beverages encompass drinks and desserts featuring chewy tapioca pearls, known as boba, or other toppings. These pearls are typically made from cassava starch and require precise cooking to achieve their characteristic chewy texture. While traditional boba leads the product type segment, jellies and foam toppings are gaining share. Fruity and creamy flavor profiles dominate sales, with herbal infusions representing a niche but growing category.
Food safety regulations from bodies like the US FDA and the European EFSA govern ingredient sourcing and allergen labeling. In India, FSSAI standards for additives and sugar content directly influence product formulation. Navigating divergent international standards on sweeteners and food colorants is a critical strategic consideration for brands seeking to expand their geographic footprint.
Market Dynamics
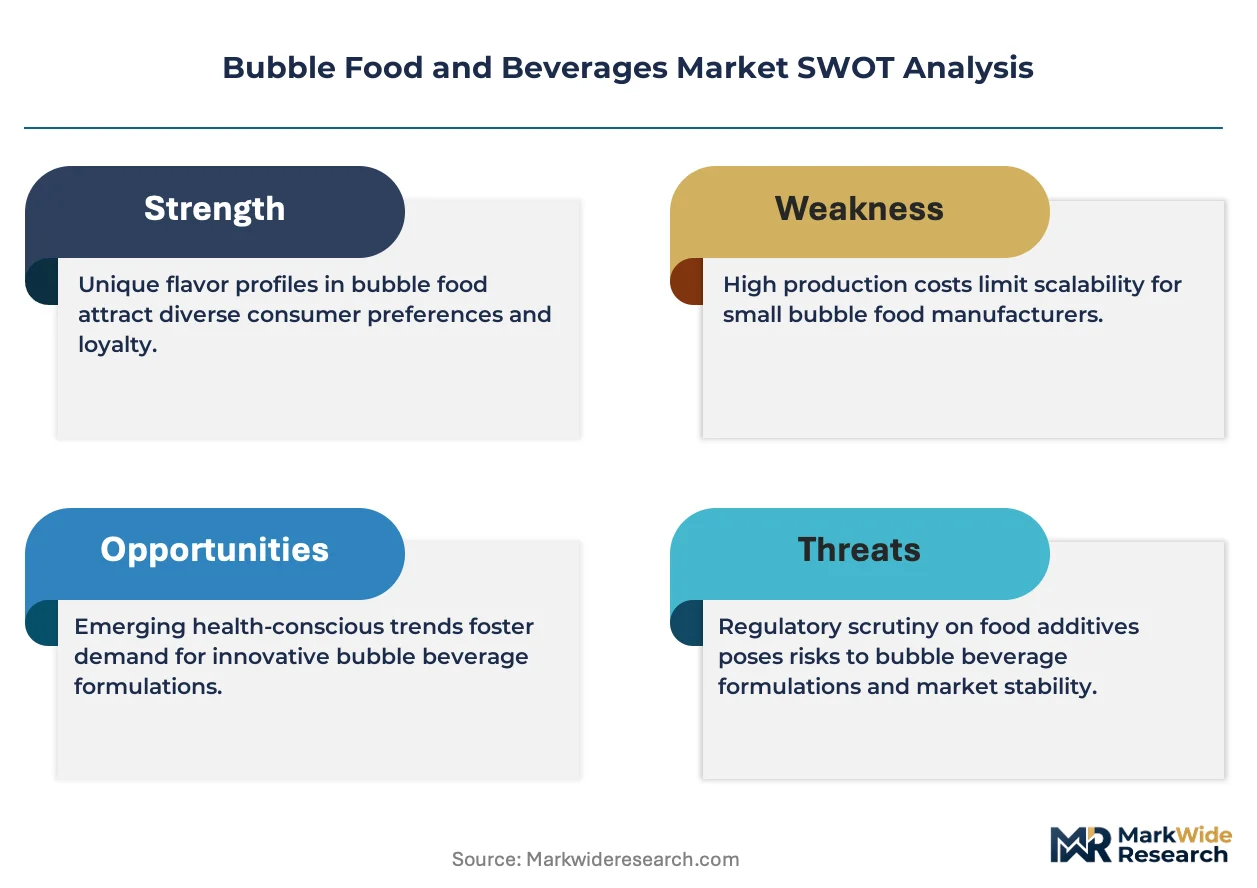
The central tension shaping the market is the drive for product premiumization against the need for operational scalability. This dynamic forces brands to balance artisanal quality and unique ingredients with the standardized, efficient processes required for rapid franchise expansion in competitive urban markets.
Growth Catalysts
- Plant-Based Formulations:Innovations in oat, almond, and soy milk alternatives are expanding the consumer base to include lactose-intolerant and vegan demographics, aligning products with broader dietary trends.
- QSR Channel Penetration:Integration into the menus of quick-service restaurants provides a significant new distribution channel, introducing bubble tea to a mainstream audience beyond dedicated specialty shops.
- Western Market Adoption:Surging popularity in urban centers across the United States and Europe signifies a crucial expansion beyond traditionally strong Asian consumer markets, creating new geographic growth frontiers.
Market Restraints
- Input Cost Volatility:The price of essential raw materials, particularly cassava starch for tapioca pearls and specialty teas, is subject to supply chain disruptions and agricultural commodity market fluctuations.
- Divergent Food Regulations:Navigating conflicting international standards for sweeteners and food colorants from bodies like the US FDA and the European EFSA complicates global product formulation and labeling strategies.
- Threat of Substitution:The market faces intense competition from other beverage categories, including specialty coffee, artisanal sodas, and functional health drinks, which vie for the same consumer spending.
Strategic Opportunities
- Untapped Geographic Markets:Expansion into nascent markets in Latin America and the Middle East, where consumer awareness is low but disposable income is rising, offers first-mover advantages.
- Product Line Extensions:Incorporating boba pearls and jellies into adjacent product categories, such as ready-to-eat desserts, frozen yogurt, and packaged ice cream, can create new revenue streams.
- Health and Wellness Niche:Developing product lines featuring functional ingredients like herbal infusions, probiotics, or protein fortification can appeal to health-conscious consumers and command premium pricing.
Industry Challenges
- Quality Consistency:Maintaining uniform taste and texture, especially the chewiness of tapioca pearls, across a geographically dispersed network of franchise locations presents a significant operational and logistical hurdle.
- Complex Compliance:Adhering to country-specific food safety and allergen labeling mandates, such as FSSAI rules in India, requires significant investment in compliance and supply chain traceability.
- Skilled Labor Scarcity:Finding and retaining staff trained in the precise cooking methods for tapioca and consistent preparation of complex drink orders is a persistent challenge for store operators.
Report Scope
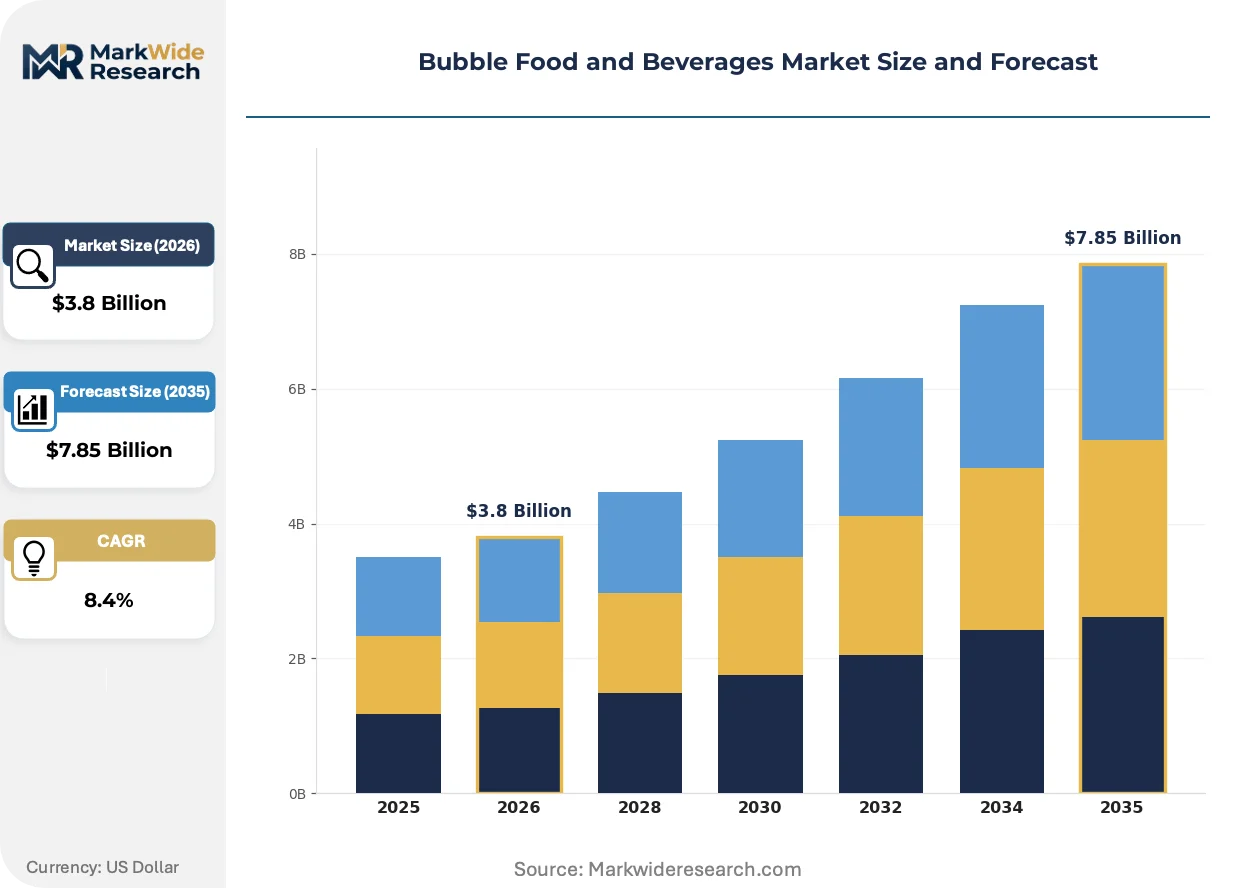
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bubble Food and Beverages Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boba, Foam Topping, Pudding, Jellies Preparation Method: Shaken, Blended, Mixed, Steamed Flavor Profile: Fruity, Creamy, Herbal, Sweet End User: Cafes, Restaurants, Supermarkets, Online Retailers |
| Companies Covered | Gong Cha, CoCo Fresh Tea & Juice, Chatime, HeyTea, Sharetea, Kung Fu Tea, Mixue Ice Cream & Tea, Lollicup Coffee & Tea, Bubbleology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bubble Food and Beverages Market Strategic Shifts & Innovations
Product personalization and operational automation are the defining forces in the market. Food science advancements are enabling wider customization options, while technology is streamlining production to meet demand in high-traffic environments, altering the competitive calculus for both new entrants and established chains.
Automated tea-brewing and boba-making machines ensure precise temperature control and cooking times for ingredients. High-volume franchise locations and quick-service restaurants are the primary adopters, seeking to reduce labor costs and eliminate inconsistencies. This wave of automation is collapsing the skill-based quality gap that previously separated small artisanal shops from large-scale chain operations.
European Union initiatives promoting front-of-pack nutritional labeling are influencing product development globally. This regulatory pressure compels brands to reformulate beverages to lower sugar and fat content to achieve more favorable health scores. Manufacturers targeting the EU market are leading this shift, accelerating the development of drinks using natural sweeteners and functional ingredients.
Consumer purchasing behavior is shifting decisively toward digital and mobile-first ordering. This trend, powered by brand-specific apps and third-party delivery aggregators, is disrupting the traditional counter-service model. The shift is most pronounced in dense urban centers in North America and Southeast Asia, where delivery speed and user interface design are becoming key competitive differentiators.
Bubble Food and Beverages Market Segmentation
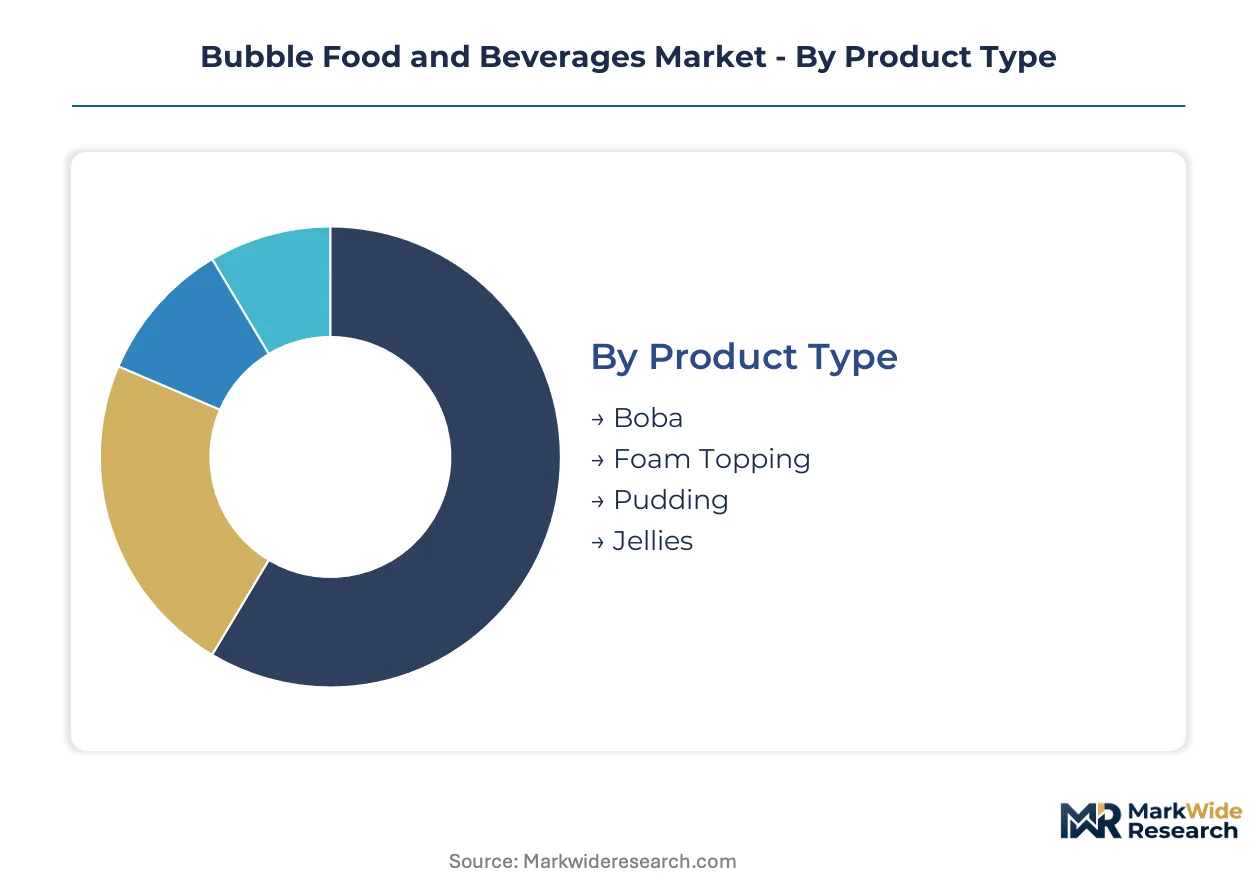
The bubble food and beverages market segmentation provides a granular view of consumer preferences and operational dynamics across diverse product offerings and distribution channels. Understanding these distinct segments is crucial for brands to tailor product development, marketing strategies, and expansion efforts effectively.
Product Type:
The product type segment spans a maturity spectrum, from established core offerings to rapidly evolving innovative inclusions. This categorization highlights the foundational components that define bubble food and beverages.
- Boba:Boba pearls, typically made from cassava starch, are the foundational component, providing the characteristic chewy texture. Demand concentrates in quick-service restaurants in the United States, driven by mainstream consumer adoption.
- Foam Topping:Foam toppings, often made from cheese, cream, or milk, add a rich, savory, or sweet layer to beverages. This segment caters to consumers seeking enhanced textural complexity and visual appeal in their drinks.
- Pudding:Pudding, frequently egg or milk-based, introduces a smooth, custardy texture to bubble drinks and desserts. Its inclusion offers a distinct mouthfeel, appealing to consumers desiring a dessert-like experience.
- Jellies:Jellies, often fruit-flavored or made from agar, offer a lighter, refreshing textural contrast to traditional pearls. Their appeal is expanding across European urban centers, fueled by a desire for diverse and visually appealing beverage components.
Boba retains volume leadership; Jellies hold the steepest expansion curve.
Preparation Method:
Volume considerations significantly influence the choice of preparation method, impacting both operational efficiency and product consistency. Each method caters to different product characteristics and service requirements.
- Shaken:Shaken preparation involves combining ingredients vigorously with ice, creating a well-mixed and chilled beverage. This method is prevalent in high-throughput cafes in Singapore, where speed and consistency are paramount for customer satisfaction.
- Blended:Blended methods incorporate ice and other ingredients into a thick, smoothie-like consistency, often for dessert-style beverages. Demand for blended options is high in casual dining establishments across Australia, catering to indulgent consumer preferences.
- Mixed:Mixed preparation involves stirring ingredients together without shaking or blending, often for simpler, less viscous drinks. This method is suitable for beverages where ingredient layering or delicate textures are desired.
- Steamed:Steamed preparation, less common for core bubble tea, applies heat to ingredients, sometimes used for specific milk teas or warming components. This technique is occasionally employed for specialty hot beverages in Japan.
Shaken methods optimize for rapid service, while blended preparations cater to specific dessert-drink market segments.
Flavor Profile:
Customer preferences for taste and sensory experience delineate the flavor profile segment, influencing product development and market positioning. Offerings range from widely accessible to niche and specialized tastes.
- Fruity:Fruity profiles, often derived from natural fruit purees or syrups, offer a refreshing and broadly appealing taste experience. These flavors drive sales in family-oriented establishments in the United Kingdom, appealing to a wide demographic.
- Creamy:Creamy profiles, typically incorporating milk, cream, or plant-based alternatives, provide a rich and indulgent mouthfeel. Their popularity is pronounced in specialty cafes across South Korea, where consumers seek luxurious beverage options.
- Herbal:Herbal flavor profiles, utilizing ingredients like grass jelly or specific tea infusions, cater to consumers seeking traditional or health-conscious options. This niche segment holds appeal in traditional Asian markets like Taiwan.
- Sweet:Sweet profiles, often achieved through various sweeteners, form the base for many traditional bubble tea formulations. This foundational taste underpins broad consumer acceptance across diverse geographies.
Fruity and creamy profiles dominate consumer choice, with herbal infusions capturing a distinct, health-conscious niche.
End User:
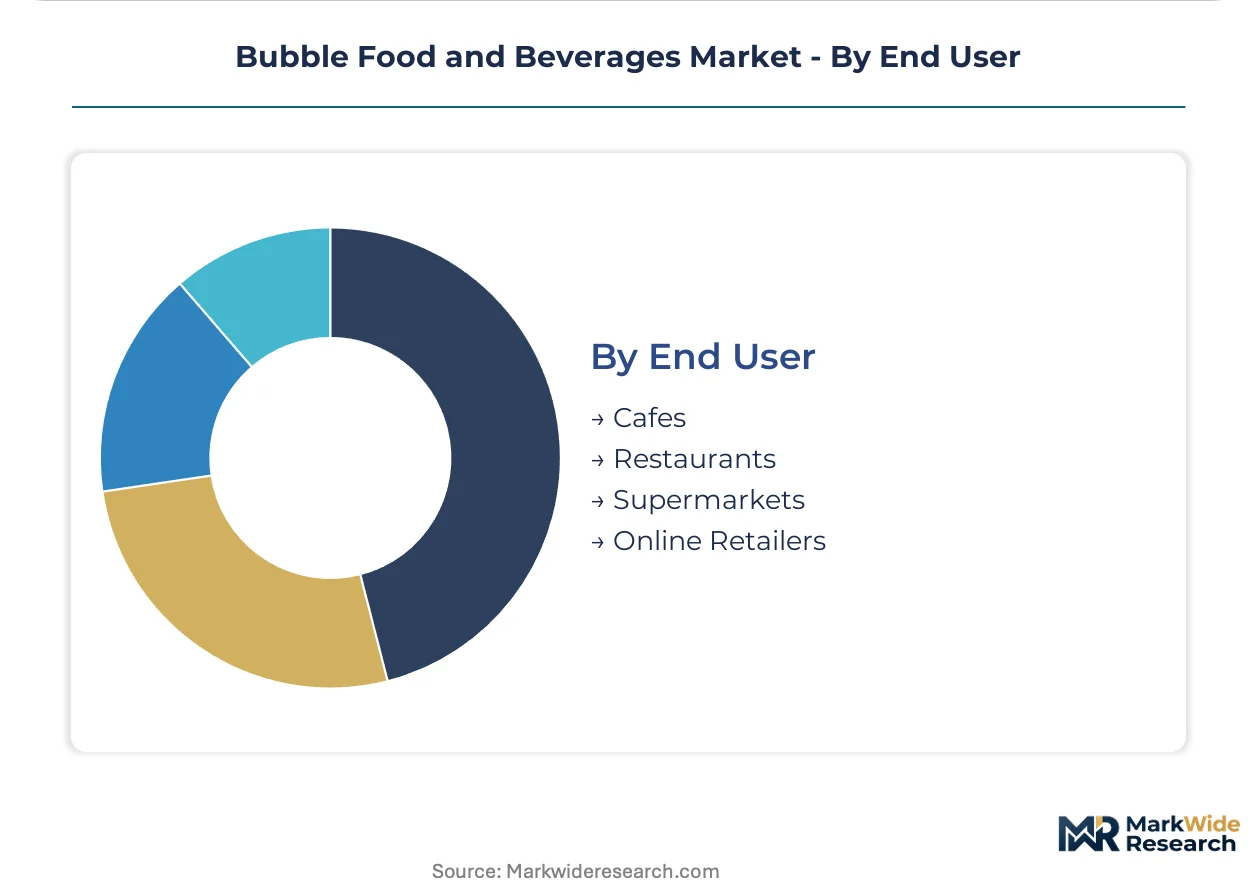
Supply concentration within the end-user segment highlights dominant distribution channels and emerging retail opportunities for bubble food and beverages. Each channel serves a distinct consumer base and operational model.
- Cafes:Cafes, including specialized bubble tea shops, serve as primary points of consumption, offering a tailored beverage experience. These dedicated outlets are central to market growth in metropolitan areas like New York City, fostering brand loyalty.
- Restaurants:Restaurants, particularly quick-service chains, integrate bubble beverages into their expanded menu offerings, reaching a mainstream audience. This channel penetration is significant in fast-casual dining across Canada, driving new consumer trials.
- Supermarkets:Supermarkets offer ready-to-drink or DIY bubble tea kits, providing convenience and accessibility for at-home consumption. This retail channel broadens market reach beyond specialized food service.
- Online Retailers:Online retailers facilitate the sale of ingredients, kits, and sometimes prepared drinks for delivery, catering to digital-first consumer purchasing habits. This segment is growing rapidly in urban centers across Germany.
Specialty cafes remain a core distribution channel, while supermarkets and online retailers expand accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global bubble food and beverages market exhibits a dynamic trade balance, driven by ingredient sourcing and finished product distribution. Key raw materials like cassava starch often originate from specific agricultural regions, influencing import patterns. Finished product demand centers in urban areas, necessitating efficient supply chains to meet consumer preferences.
United States
Mainstream consumer adoption and QSR channel penetration drive significant demand for bubble beverages. US FDA food safety regulations govern ingredient sourcing and allergen labeling for all products. Urban centers like New York City show high demand, fostering brand loyalty in dedicated cafes and quick-service restaurants.
United Kingdom
Fruity flavor profiles and family-oriented establishments contribute to consumer preference for bubble food and beverages. European EFSA standards impact additive and sweetener formulations for market entry. London's metropolitan area sees strong sales, with cafes adapting to diverse consumer tastes and product innovations.
India
Rising disposable income and FSSAI standards directly influence product formulation and market growth. FSSAI mandates specific standards for additives and sugar content in all beverage categories. Major cities like Mumbai and Delhi are crucial for product development, balancing traditional tastes with modern preferences.
South Korea
Creamy flavor profiles and popularity in specialty cafes define consumer choices within this market. MFDS regulations guide food safety and labeling requirements for both local and imported ingredients. Seoul's vibrant cafe culture drives innovation, with consumers seeking luxurious beverage options and unique flavor combinations.
Singapore
High-throughput cafes and demand for rapid service and consistency characterize the local market dynamics. The Singapore Food Agency (SFA) ensures stringent food safety and quality control standards. Central Business District cafes prioritize speed and efficiency, optimizing shaken preparation methods for customer satisfaction.
Bubble Food and Beverages Market Key Industry Players
On the supply side, the industry is fragmenting due to the proliferation of asset-light franchise models. This lowers barriers to entry for new operators, fostering a diverse competitive environment across various market tiers. Strategic archetypes include brands focused on rapid international expansion, those emphasizing premium branding and direct ownership in key urban centers, and others utilizing flexible kiosk and storefront formats. Companies are primarily engaged in geographic expansion and product portfolio diversification to capture new consumer segments and maintain relevance.
Within the competitive landscape, companies exemplify distinct strategic approaches to market penetration and brand building. Gong Cha, for instance, represents a model built on rapid international expansion through a master franchise system, anchoring its presence across diverse global markets. HeyTea occupies a position emphasizing premium branding and direct store ownership, particularly within key Chinese urban markets, cultivating a high-end consumer experience. Chatime further exemplifies a strategy centered on flexible kiosk and storefront formats, allowing for broad market penetration and accessibility across various retail environments. These players collectively illustrate the varied operational and branding strategies employed to capture market share in a fragmenting industry.
| Leading Market Players |
|---|
| Gong Cha |
| CoCo Fresh Tea & Juice |
| Chatime |
| HeyTea |
| Sharetea |
| Kung Fu Tea |
| Mixue Ice Cream & Tea |
| Lollicup Coffee & Tea |
| Bubbleology |
| Others |
Cost & Logistics Intelligence
Cassava starch processing undercapacity in Southeast Asia drives input cost volatility, directly impacting supplier margins and the pricing posture for finished bubble tea products sold globally. This dynamic forces brands to balance raw material costs with consumer price expectations.
Pricing Analysis
Quick-service restaurant buyers anchor contract-based long-term offtake agreements for bulk ingredients like tapioca pearls and tea concentrates. Price differentiation stems from quality grade of ingredients, such as specific tea varieties, and volume scale for large franchise networks. Pricing pressure stems from input cost volatility, particularly for cassava starch and specialty teas, which suppliers attempt to pass through. Consumers purchasing ready-to-drink options in supermarkets exhibit higher price sensitivity compared to those seeking premium experiences in specialty cafes.
Supply Chain Analysis
Extended payment terms often characterize relationships between ingredient suppliers and large bubble tea franchises to manage working capital across dispersed networks. Geographic supply concentration for cassava starch primarily lies in Southeast Asia, while specialty teas originate largely from East Asian agricultural regions. Raw material dependencies include cassava starch, various tea leaves, and diverse fruit purees for flavorings. Commodity price volatility for these agricultural inputs represents a significant supply chain risk. Distribution runs through both dedicated cafes and quick-service restaurant channels globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bubble food and beverages market is experiencing a cyclical recovery driven by a resurgence in out-of-home consumer spending post-pandemic. This trend fuels demand for experiential and customizable beverage options across urban centers, particularly among younger demographics.
For Market Incumbents: Entrench market share by investing in automation technologies for consistent product quality across franchise locations. Innovate with plant-based milk alternatives and low-sugar formulations to appeal to broader dietary trends and counter the threat of substitution from other beverage categories. Deepen channel control through strategic partnerships with quick-service restaurants, leveraging their existing customer bases for wider reach. Focus R&D on functional ingredients and herbal infusions to capture the health-conscious consumer segment.
For New Entrants and Emerging Players: Underpenetration in Latin America and the Middle East offers significant white-space opportunities for new entrants. Target these nascent markets by introducing localized flavor profiles and leveraging digital-first ordering platforms for rapid consumer adoption. Expand product lines into adjacent categories like ready-to-eat desserts or frozen yogurt incorporating boba pearls. A go-to-market angle focused on convenience and cultural adaptation can accelerate market entry.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among master franchise systems that provide consistent ingredient supply and operational support to their network. The market offers long-term viability through continuous product innovation and geographic expansion into new consumer segments. Target acquisition profiles include brands with proven premium positioning or those with strong intellectual property in automation or functional ingredient formulations. The signal to watch is the sustained growth of digital and mobile-first ordering platforms in dense urban centers.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Line Extension | Incorporating boba into ready-to-eat desserts diversifies revenue streams. |
| Automated Equipment Deployment | Reduces labor costs and ensures consistent quality across locations. |
| Plant-Based Formulation R&D | Expands consumer base to vegan and lactose-intolerant demographics. |
| QSR Channel Partnership | Introduces bubble beverages to a mainstream audience, increasing distribution. |
| Digital Ordering Platform Investment | Captures mobile-first consumer purchasing habits in urban markets. |
Research Approach
Initial hypotheses were tested against primary input from franchise owners, QSR procurement managers, and food scientists, then refined through iterative processes. This involved extensive interviews with key industry stakeholders and validation against secondary data sources such including US FDA guidelines, European EFSA reports, and company financial disclosures. Bottom-up market sizing from specific segment data was triangulated with top-down validation of overall market estimates.
Demand-supply balance models projected market trajectory across the analysis window, considering consumer adoption rates and raw material availability. Segmentation dimensions included product type, preparation method, flavor profile, end user, and regional regulatory frameworks. Compound annual growth rates derived from historical trends and projected QSR channel penetration. Key forecast inputs included cassava starch commodity price forecasts and plant-based milk alternative market penetration.
The forecast holds incumbent behavior within observed patterns; aggressive moves by rapid international expanders or premium direct-ownership brands would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and consumer preference evolution. Unforeseen supply chain disruptions or significant shifts in food safety regulations could prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Mixers Market
Beverages
Europe Bottled Water Market
Beverages
Detox Drinks Market
Beverages
Saudi Arabia Retail Bubble Tea Kits Market
Beverages
Electrolyte Mixes Market
Beverages
CBD-Infused Beverages Market
Beverages
Root Beer Market
Beverages
Soft Serve Premix Market
Beverages
Freezer & Beverage and Wine Cooler Market
Beverages
Kombucha Market
Beverages
Low Calorie RTD Beverages Market
Beverages
Milk Tea Powder Market
Beverages
Soft Serves Market
Beverages
North America Kombucha Market
Beverages
North America Fruits and Vegetables Juice Market
Beverages
Fruit Juices and Nectars Market