
 Pig Protein Concentrate Market | 2026-2036
Pig Protein Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Pig Protein Concentrate Market Analytics
Pet food manufacturers are rotating toward pig plasma and peptide concentrates as premiumization reshapes ingredient procurement. Cargill leverages its integrated rendering-to-feed pipeline to secure consistent supply of pork meal across North American livestock operations. Nutreco anchors European demand through specialized premix formulations that incorporate porcine-derived functional proteins. Darling Ingredients dominates rendering collection density, converting slaughterhouse byproducts into standardized protein meals for industrial buyers.
Pig protein concentrate denotes a dried, processed derivative of porcine tissue—typically containing 60-85% crude protein by weight—manufactured through rendering, enzymatic hydrolysis, or spray-drying of blood, plasma, or meat tissues. The material serves primarily as a high-bioavailability amino acid source in formulated animal diets and functional pet nutrition. Pork meal occupies the largest volume position among product types due to its cost efficiency in bulk livestock feed, while pig plasma commands premium positioning in early-weaning piglet diets and superpremium pet food where palatability drives formulation decisions. Peptides represent the fastest-expanding category as hydrolyzed protein fractions gain traction in nutraceutical applications targeting gut health modulation.
The EPA regulates air emissions from rendering facilities under Clean Air Act provisions, while FDA oversight through the Food Safety Modernization Act governs ingredient traceability and pathogen control in animal feed streams. In Europe, EFSA safety assessments and REACH chemical registration requirements shape import eligibility and processing standards for porcine-derived materials crossing member-state borders. Feed manufacturers and nutraceutical formulators must monitor evolving divergence between US and EU regulatory thresholds for specified risk materials to avoid supply chain disqualification.
Market Dynamics
Pet food manufacturers are consolidating procurement around functional porcine proteins as premiumization restructures ingredient sourcing hierarchies, while rendering capacity concentrates near industrial slaughter clusters.
Growth Catalysts
- EU Green Deal Implementation:Emissions reduction mandates are accelerating capital deployment into closed-loop rendering systems across member-state processing facilities.
- Early-Weaning Nutrition:Piglet diet formulations are absorbing higher plasma inclusion rates as producers prioritize gut development and feed conversion metrics.
- German Feed Milling Density:Centralized compound feed production in Lower Saxony and North Rhine-Westphalia creates procurement pull for standardized protein meals.
Market Restraints
- Input Cost Volatility:Slaughter byproduct availability fluctuates with pork production cycles, compressing renderer margins during herd contraction phases.
- Regulatory Friction:EFSA specified risk material classifications create border-crossing complexity for porcine-derived materials entering EU member states.
- Plant Protein Substitution:Fermented soybean and pea protein isolates are capturing share in mid-tier livestock feed formulations.
Strategic Opportunities
- Peptide Nutraceuticals:Hydrolyzed porcine fractions are penetrating gut health modulation applications in companion animal supplements.
- Direct-to-Formulator Channels:Bypassing traditional distributors, renderers are establishing captive supply relationships with large-scale pet food manufacturers.
- F-Gas Regulation Compliance:Refrigeration retrofit incentives are enabling energy-efficient cold chain infrastructure for plasma collection networks.
Industry Challenges
- Enzymatic Hydrolysis Expertise:Peptide production requires specialized biochemist talent pools that remain concentrated in pharmaceutical and flavor industries.
- FSMA Traceability Systems:FDA Food Safety Modernization Act record-keeping mandates demand capital-intensive digital infrastructure for batch-level ingredient tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pig Protein Concentrate Market |
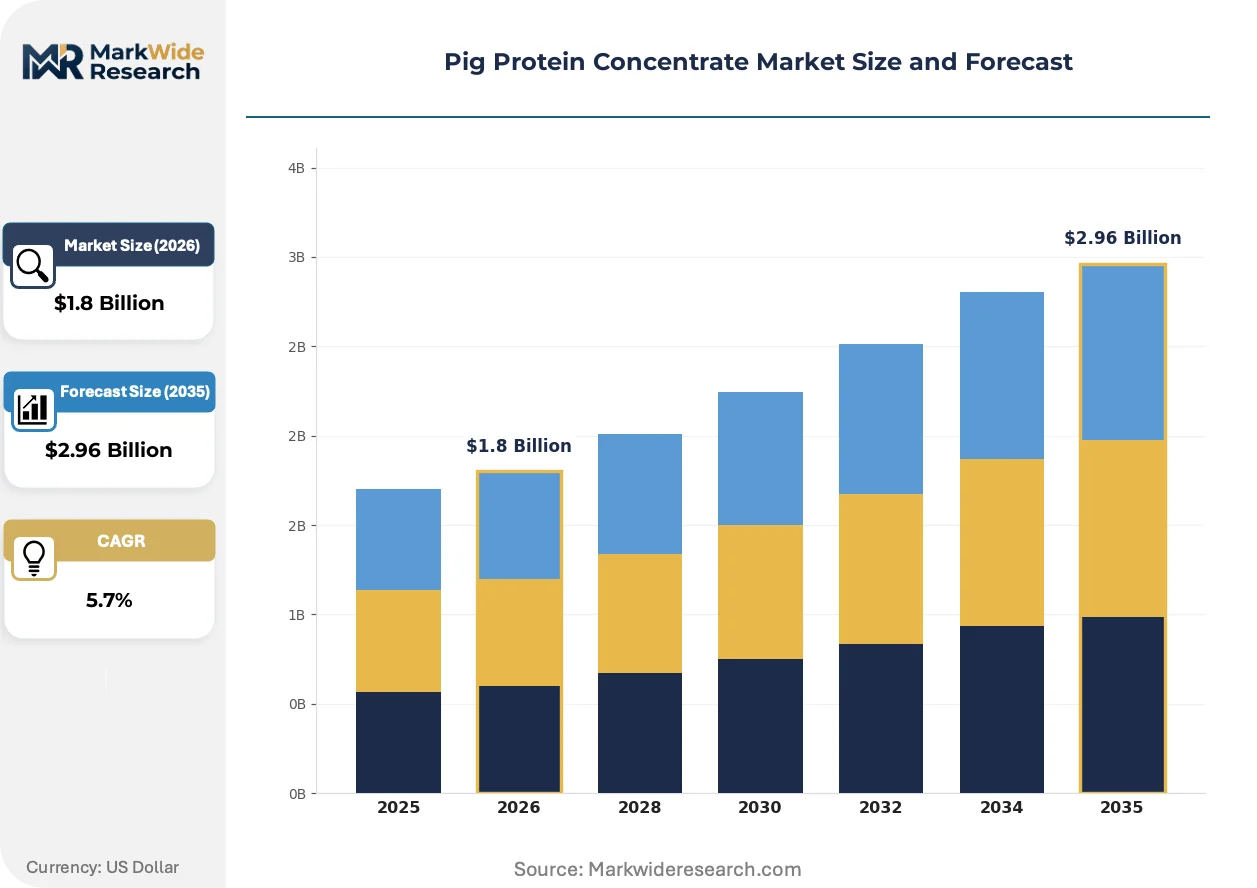
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pork Meal, Pig Plasma, Peptides, Isolates Application: Animal Feed, Pet Food, Human Nutrition, Nutraceuticals End User: Livestock Farms, Feed Manufacturers, Food Processors, Nutraceutical Companies Distribution Channel: Online Retail, Wholesale, Direct Sales, Distributors |
| Companies Covered | Cargill, Archer Daniels Midland, Nutreco, Alltech, DSM Animal Nutrition & Health, Chr. Hansen, Evonik Industries, Darling Ingredients, Laucke Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pig Protein Concentrate Market Evolving Landscape
Processing technology is fragmenting into divergent efficiency-versus-functionality pathways, while regulatory pressure and buyer consolidation reshape competitive requirements across the value chain.
Enzymatic hydrolysis technology is bifurcating the protein concentrate landscape into commodity meal and high-value peptide fractions. Pet food formulators in North America are adopting hydrolyzed plasma at accelerated rates for palatability enhancement. This technology is compressing the addressable market for standard spray-dried blood meal while expanding premium pricing headroom for bioactive fractions.
REACH chemical registration requirements are tightening substance documentation obligations for porcine-derived imports crossing into EU member states. Industrial buyers now face extended qualification timelines for new supplier onboarding. Feed compounders in the Netherlands and Denmark are responding by pre-qualifying renderer partnerships through multi-year supply agreements.
Consolidated procurement desks at major pet food manufacturers are displacing spot-market purchasing for porcine protein inputs. Long-term offtake contracts with fixed volume commitments are replacing quarterly tender processes. This behavioral shift is most visible in Germany, where superpremium pet food producers have locked in three-year plasma supply arrangements with integrated rendering operations.
Pig Protein Concentrate Market Segmentation
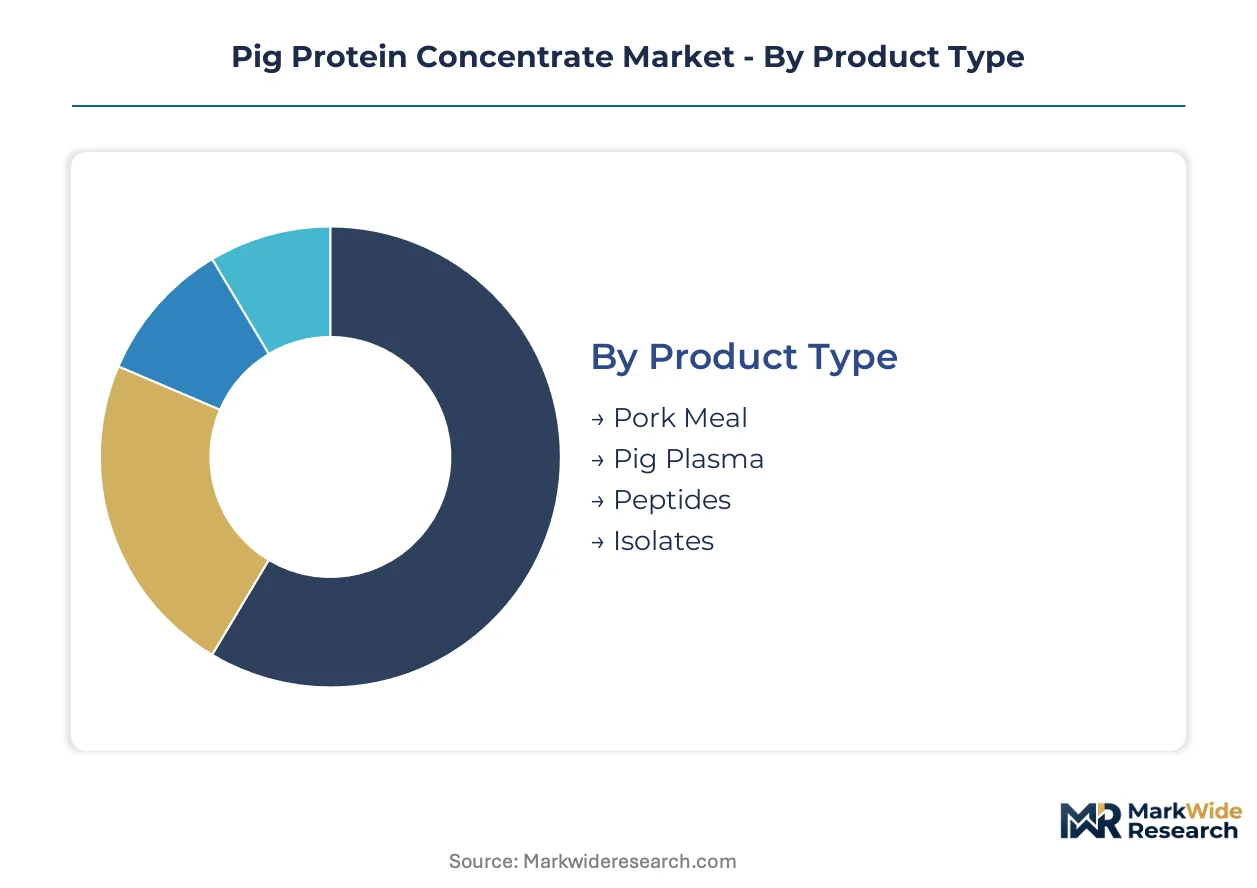
Segmentation in pig protein concentrates reveals how regulatory thresholds, formulation requirements, and procurement scale fragment demand across distinct technical specifications and customer workflows. Each category exposes different margin structures and compliance burdens that shape supplier positioning.
Product Type:
EFSA specified risk material classifications and FDA pathogen control mandates create divergent qualification burdens across protein formats, with spray-dried and hydrolyzed variants facing distinct documentation requirements for cross-border movement.
- Pork Meal:Rendered and dried porcine tissue meal containing 60-75% crude protein serves as the baseline amino acid source for bulk livestock formulations. Demand concentrates in German compound feed operations in Lower Saxony where centralized milling clusters prioritize cost-efficient protein standardization for swine and poultry diets.
- Pig Plasma:Spray-dried blood plasma with 75-85% protein content delivers superior palatability and immunoglobulin content for early-weaning piglet diets and superpremium pet food. Procurement is consolidating around direct renderer-to-formulator contracts in North American pet food manufacturing corridors where gut development metrics drive inclusion rates.
- Peptides:Enzymatically hydrolyzed protein fractions with enhanced bioavailability penetrate nutraceutical applications targeting gut health modulation in companion animals.
- Isolates:Highly refined protein concentrates with minimized fat and ash content serve specialized pharmaceutical and medical nutrition formulations requiring maximum purity.
Established volume favors pork meal; emerging adoption favors peptides.
Application:
Formulation sophistication and price tolerance diverge sharply across end-use categories, with companion animal nutrition commanding premium positioning while livestock feed prioritizes cost-per-unit-protein optimization.
- Animal Feed:Swine, poultry, and aquaculture diets absorb the majority of commodity pork meal volumes where feed conversion ratios dominate procurement decisions. Demand clusters in integrated livestock operations across Iowa and North Carolina where captive feed mills source directly from regional rendering networks to minimize transport costs.
- Pet Food:Premium and superpremium dog and cat formulations incorporate pig plasma and hydrolyzed fractions for palatability enhancement and functional gut health claims. North American superpremium manufacturers are locking in multi-year plasma offtake agreements to secure supply against rendering capacity constraints.
- Human Nutrition:Medical foods and specialized dietary supplements utilize highly processed isolates with extensive safety documentation for immunocompromised consumer populations.
- Nutraceuticals:Bioactive peptide fractions targeting digestive health and immune modulation in companion animal supplements represent the steepest expansion trajectory as enzymatic hydrolysis capabilities mature.
Livestock feed absorbs absolute tonnage; pet food commands absolute margins.
End User:
Procurement scale and technical capability separate large-scale integrated operations from specialized formulators, with regulatory compliance infrastructure acting as a gatekeeper for market participation.
- Livestock Farms:Integrated swine and poultry operations with captive feed milling capacity purchase commodity pork meal in bulk truckload quantities. These buyers dominate volume offtake in the US Corn Belt where rendering plants cluster near slaughter facilities.
- Feed Manufacturers:Commercial compound feed producers in the Netherlands and Denmark blend standardized protein meals into species-specific formulations, requiring consistent nutritional specifications and batch-level traceability documentation.
- Food Processors:Human-grade ingredient suppliers face stringent FSMA and HACCP compliance requirements for protein isolates entering medical and functional food channels.
- Nutraceutical Companies:Specialized formulators of companion animal supplements source hydrolyzed peptides for gut health products, prioritizing bioactivity documentation over cost minimization.
Integrated farms drive volume consolidation; nutraceutical specialists drive innovation premiums.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and the need for cold chain integrity in plasma and peptide handling.
- Direct Sales:Large pet food manufacturers and integrated livestock operations establish captive supply relationships with rendering operations, bypassing distributor markups for plasma and high-volume pork meal contracts.
- Wholesale:Regional feed ingredient traders aggregate commodity pork meal for smaller compound feed producers lacking direct renderer access.
- Distributors:Specialized animal nutrition distributors provide technical formulation support and inventory management for mid-tier feed manufacturers across European member states.
- Online Retail:E-commerce platforms serve niche nutraceutical and specialty pet supplement brands with small-batch peptide and isolate requirements.
Direct channels capture plasma premiumization; wholesale retains commodity pork meal liquidity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated livestock operations and pet food manufacturers concentrate procurement in four countries where rendering infrastructure clusters near slaughter capacity and formulation expertise.
United States
Iowa and North Carolina host dense rendering-to-feed mill corridors where captive supply relationships dominate pork meal procurement. EPA Clean Air Act enforcement shapes emissions compliance investments across rendering facilities. Darling Ingredients anchors collection density in the Corn Belt, converting slaughterhouse byproducts into standardized protein meals for industrial buyers.
Germany
Lower Saxony and North Rhine-Westphalia concentrate European compound feed production, creating procurement pull for standardized protein meals. EU Green Deal emissions mandates accelerate capital deployment into closed-loop rendering systems. Superpremium pet food producers in Bavaria have locked in multi-year plasma supply arrangements with integrated rendering operations.
Netherlands
Commercial compound feed producers blend standardized protein meals into species-specific formulations requiring batch-level traceability. EFSA specified risk material classifications create extended qualification timelines for new supplier onboarding. Feed compounders in Gelderland and Overijssel pre-qualify renderer partnerships through multi-year supply agreements.
China
Swine production consolidation in Sichuan and Henan provinces drives demand for early-weaning plasma in industrial piglet operations. National food safety regulators enforce pathogen control standards for animal feed ingredient streams. Yangtze River Delta feed manufacturers source porcine protein meals from regional rendering networks serving integrated livestock enterprises.
Denmark
Specialized premix formulators incorporate porcine-derived functional proteins into high-value aquaculture and swine diets. REACH chemical registration requirements tighten substance documentation for imported protein concentrates. Rendering operations in Jutland supply compound feed producers with batch-traceable meals meeting EFSA safety assessments.
Pig Protein Concentrate Market Competitive Landscape
Player mix skews toward integrated agribusiness conglomerates with captive rendering-to-feed pipelines, creating tiered competition between commodity meal suppliers and premium plasma specialists. Three archetypes dominate: diversified nutrition conglomerates with global premix networks, dedicated rendering operators with collection density advantages, and enzymatic hydrolysis specialists targeting peptide nutraceuticals. Competitive moves concentrate on direct-to-formulator channel establishment and multi-year offtake contracting.
Among diversified nutrition conglomerates, Cargill exemplifies the integrated rendering-to-feed archetype through its North American supply pipeline, while Nutreco anchors European demand through specialized premix formulations. Darling Ingredients occupies the dedicated rendering tier, converting slaughterhouse byproducts into standardized protein meals. These three companies represent distinct competitive positions: upstream supply control, formulation technical service, and byproduct collection density.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland |
| Nutreco |
| Alltech |
| DSM Animal Nutrition & Health |
| Chr. Hansen |
| Evonik Industries |
| Darling Ingredients |
| Laucke Mills |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with fixed volume commitments lock in plasma supply access for North American pet food manufacturers while anchoring price visibility against slaughter byproduct availability swings. German compound feed producers leverage similar structures to standardize pork meal procurement costs amid EU Green Deal compliance investments.
Pricing Analysis
Cost-plus contracts indexed to hog slaughter volumes and energy input costs dominate plasma and peptide transactions, insulating renderers from margin compression during herd contraction phases. Three-tier pricing structure across premium, standard, and economy levels separates spray-dried plasma for superpremium pet food from commodity pork meal for bulk livestock feed. Pricing pressure stems from fermented soybean and pea protein isolates capturing share in mid-tier formulations. Livestock feed manufacturers exhibit highest price sensitivity due to feed conversion ratio optimization mandates, while nutraceutical formulators tolerate premium positioning for bioactive peptide fractions.
Supply Chain Analysis
Strategic stockpiling of slaughter byproducts near rendering clusters contrasts with just-in-time plasma collection requiring refrigerated transport infrastructure. Supply concentrates in the United States, Germany, and China where industrial slaughter capacity anchors rendering operations. Raw material flows draw from hog processing facilities, blood collection networks, and enzymatic hydrolysis chemical inputs. Single-source vulnerability runs through concentrated rendering-to-feed mill corridors in Iowa and Lower Saxony. Distribution runs through direct renderer-to-formulator channels for plasma and wholesale aggregation for commodity pork meal.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive moat built on regulatory entrenchment—EFSA specified risk material classifications and FDA FSMA traceability mandates create disqualification barriers that protect qualified incumbents from commodity substitution threats.
For Market Incumbents: Consolidate rendering collection density through captive supply relationships with industrial slaughter clusters in the Corn Belt and Lower Saxony. Deepen backward integration into enzymatic hydrolysis capabilities to capture peptide nutraceutical premiums before pharmaceutical biochemist talent pools fully migrate. Neutralize plant protein substitution threats by locking multi-year plasma offtake agreements with superpremium pet food manufacturers. For New Entrants and Emerging Players: Lead with peptide fraction specialization targeting gut health modulation in companion animal supplements, the steepest expansion trajectory with lowest incumbent saturation. Penetrate through direct-to-formulator channel establishment bypassing traditional distributor markups, anchored by bioactivity documentation partnerships with veterinary research institutions. White-space concentrates in online retail distribution for small-batch nutraceutical brands lacking renderer access. For Investors and Strategic Acquirers: Dedicated rendering operators with cold chain plasma infrastructure represent the highest-conviction acquisition archetype given premiumization tailwinds and supply inelasticity. Long-term viability rests on F-Gas Regulation compliance retrofit completion enabling energy-efficient refrigeration networks. Watch for EFSA specified risk material reclassification announcements as inflection indicators requiring supply chain re-qualification capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzymatic Hydrolysis | Captures peptide nutraceutical premiums beyond commodity meal margins. |
| Long-term Plasma Offtake Agreements | Locks supply access for North American superpremium pet food manufacturers. |
| F-Gas Regulation Compliance Retrofit | Enables energy-efficient cold chain infrastructure for plasma collection networks. |
| Direct-to-Formulator Channel Establishment | Bypasses distributor markups while securing formulation technical partnerships. |
| Multi-year Supply Agreement Pre-qualification | Addresses REACH documentation burdens for EU cross-border protein concentrate movement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA FSMA guidance documents, EFSA safety assessments, EPA Clean Air Act enforcement records, and rendering industry trade data. Primary interviews incorporated feed procurement directors at compound feed manufacturers, rendering operations managers, pet food formulation scientists, and veterinary nutraceutical product developers. Secondary validation drew from EU Green Deal implementation reports, REACH chemical registration databases, and hog production cycle statistics. Bottom-up volume estimates triangulated against top-down market sizing across product type and application segments.
Segmentation dimensions modeled include protein format tier, end-use application sophistication, buyer procurement scale, and geographic regulatory cluster across the analysis window. CAGRs derive from slope analysis of historical volume trajectories adjusted for policy implementation timelines and technology adoption curves. Industry-specific forecast inputs incorporate slaughter byproduct availability elasticity and enzymatic hydrolysis capacity expansion pipelines.
Forecasts assume regulatory continuity in FDA FSMA traceability mandates and EFSA specified risk material classifications; material policy shifts would require re-modeling supply chain qualification timelines. Revision becomes warranted when plant protein substitution rates in mid-tier livestock feed cross threshold penetration levels or when F-Gas Regulation enforcement intensity accelerates rendering facility consolidation beyond modeled capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Bay Leaf Oil Market
Ingredients
Pea Starch Market
Ingredients
Oak Chips White Extract Market
Ingredients
Asia-Pacific Brewing Enzymes Market
Ingredients
Stock Cubes Market
Ingredients
Cocoa Derivatives Market
Ingredients
Corn Steep Liquor Market
Ingredients
Italy Soy Protein Market
Ingredients
Food Grade Hydrolyzed Casein Market
Ingredients
Asia-Pacific Protein Market
Ingredients
Soybean Meal Market
Ingredients
Dried Beet Pulp Market
Ingredients
Edible Peanut Oil and Soybean Oil Market
Ingredients
Volatile Fatty Acids Market
Ingredients
Global Egg White Peptide Market
Ingredients
Vegetable Powder Market