
 GCC Juice Market | 2026-2036
GCC Juice Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Juice Market Foresight
Gulf Standardization Organization (GSO) certification for halal-compliant beverage processing is bifurcating the competitive landscape between qualified and non-qualified producers. Almarai Company leverages its integrated dairy-to-juice infrastructure across Saudi Arabia to sustain shelf-space dominance in modern trade channels. NADEC anchors supply security through captive agricultural operations in the Al-Qassim region. Al Rabie Saudi Foods Co differentiates via specialized aseptic packaging capabilities that extend ambient distribution reach into smaller Gulf markets.
Juice in the GCC context comprises fruit-derived beverages processed through extraction, pasteurization, and aseptic filling to achieve shelf stability in ambient and chilled formats, with brix levels and pulp content varying by product classification. The primary commercial purpose is delivering convenient, packaged hydration and nutrition aligned with regional preferences for tropical and citrus flavor profiles. Juice drinks occupy the largest volume position due to accessible price points, while 100% juice commands disproportionate margin contribution from health-conscious consumers. Carton packaging leads institutional channels, though pouches gain traction in single-serve convenience formats across food service.
MOHAP in the UAE enforces strict nutritional labeling and sugar-content thresholds that reshape product formulation priorities for manufacturers targeting premium positioning. Saudi Food and Drug Authority (SFDA) halal certification requirements and GSO technical regulations collectively determine market access eligibility across the six-member economic bloc. Stakeholders must monitor evolving front-of-pack labeling mandates and sugar taxation discussions that could recalibrate portfolio mix decisions.
Market Dynamics
MOHAP's tightening additive disclosure rules and SFDA's evolving halal certification standards are compressing formulation flexibility while rewarding producers with integrated cold-chain infrastructure across Saudi Arabia and the UAE.
Growth Catalysts
- SFDA Halal Certification:Mandatory Gulf Standardization Organization compliance is filtering out non-qualified producers and consolidating shelf access for certified facilities in Saudi Arabia's modern trade channels.
- Riyadh-Jeddah Corridor Concentration:Dense modern retail infrastructure with dedicated cold-chain distribution is enabling premium juice category expansion at accessible price points.
- Aseptic Filling Technology:Advanced ambient-stable processing is extending distribution reach into smaller Gulf markets without refrigerated logistics investment.
Market Restraints
- Concentrate Import Dependency:GCC juice producers rely on tropical fruit concentrate shipments from Southeast Asian and South American suppliers, exposing margins to shipping rate volatility and currency fluctuation.
- Water Scarcity Input Costs:Reverse osmosis and desalination requirements for beverage-grade water in Saudi Arabia and UAE elevate production costs versus regions with natural freshwater access.
- Sugar Taxation Discussions:Pending fiscal policy debates across Gulf states threaten to compress volume demand for juice drinks while accelerating portfolio reformulation costs.
Strategic Opportunities
- Kuwait and Bahrain Underpenetration:Smaller Gulf markets with nascent modern trade development offer first-mover shelf establishment before competitor cold-chain infrastructure hardens.
- Front-of-Pack Labeling Mandates:Anticipated MOHAP and SFDA nutritional scoring requirements create advantage for producers with existing clean-label formulations and transparent supply chains.
- Pouch Format Convenience:Single-serve flexible packaging is capturing food service and on-premise consumption occasions previously dominated by carton institutional channels.
Industry Challenges
- GSO Certification Timeline Compression:Halal compliance documentation and facility audit queues are extending product launch windows by 4-8 months for new market entrants.
- Cold-Chain Talent Scarcity:Refrigerated logistics engineering and temperature-controlled warehouse management expertise remains concentrated among a limited pool of regional operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Juice Market |
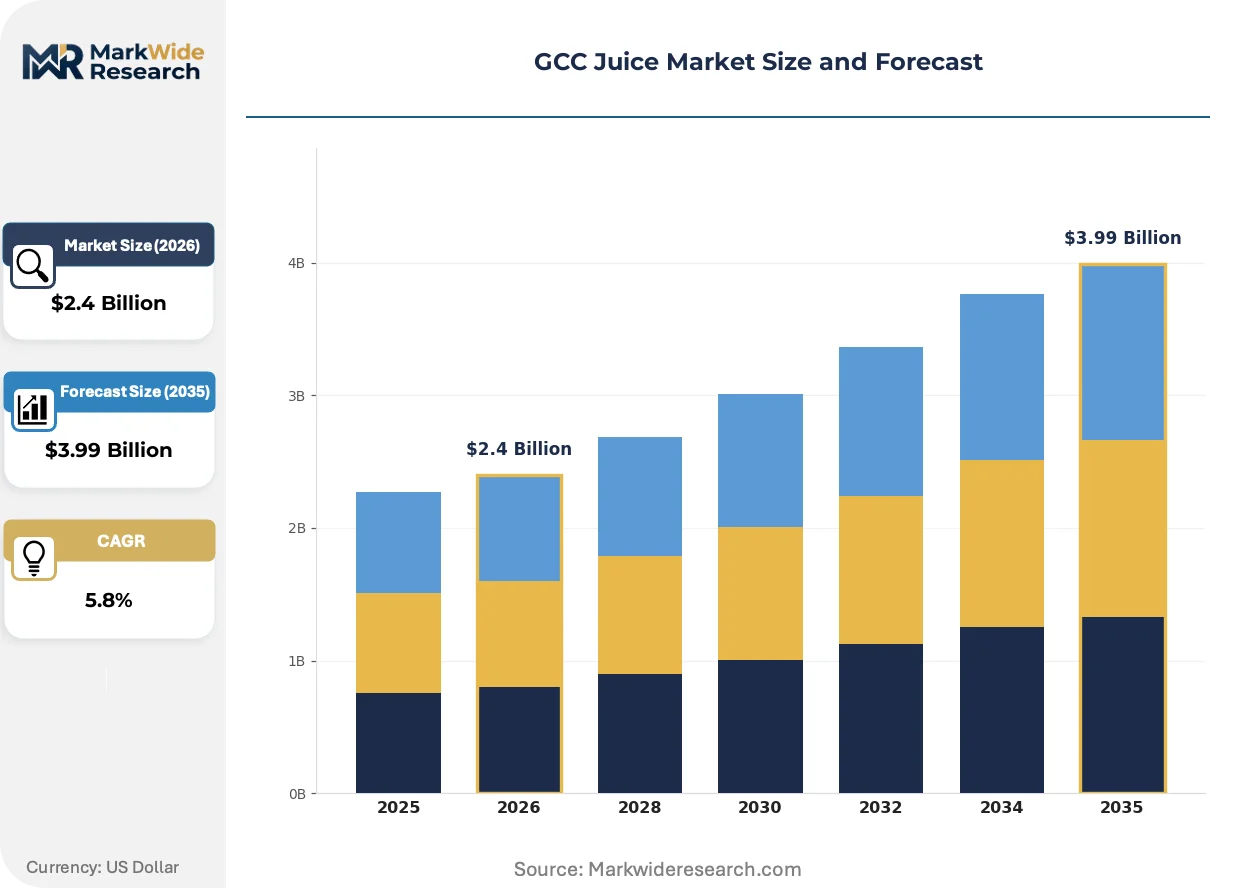
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 100% Juice, Juice Drinks, Smoothies, Nectar Packaging Type: Bottles, Cartons, Pouches, Cans Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service Customer Type: Health-Conscious Consumers, Families, Young Adults, Athletes |
| Companies Covered | NADEC, National Food Products Company, Almarai Company, Arrow Juice Factory, Kuwaiti Danish Dairy Co, Al Rabie Saudi Foods Co, Al Rawabi Dairy Company, Al Ain Dairy Co, The Coca-Cola Company, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Juice Market Shifts & Advancements
Reformulation pressure, packaging format experimentation, and procurement sophistication are restructuring competitive advantage sources across the GCC juice value chain.
HPP (High Pressure Processing) technology is fragmenting the premium juice segment by enabling clean-label shelf extension without thermal degradation of vitamin content. Health-conscious consumers in Saudi Arabia's Riyadh-Jeddah corridor are adopting HPP-treated 100% juice at accelerating velocity. This cold pasteurization method is fragmenting traditional aseptic filling dominance by rewarding regional producers with capital-intensive installed capacity.
MOHAP's enforced nutritional labeling and sugar-content thresholds are mandating reformulation investment across UAE-targeted portfolios. Manufacturers must disclose additive compositions and meet strict brix specifications to maintain premium positioning in Dubai and Abu Dhabi retail channels. Juice drink categories face disproportionate pressure to reduce added sugar content while preserving palatability for mass-market acceptance.
Modern trade buyers in Saudi Arabia are consolidating procurement authority into centralized category management functions with data-driven performance metrics. Traditional broker-mediated purchasing is contracting as Almarai Company and NADEC establish direct supplier relationships with hypermarket chains. This concentration is most visible in Riyadh's retail cluster where shelf-space negotiations now hinge on integrated supply security and promotional fund commitments.
GCC Juice Market Segmentation
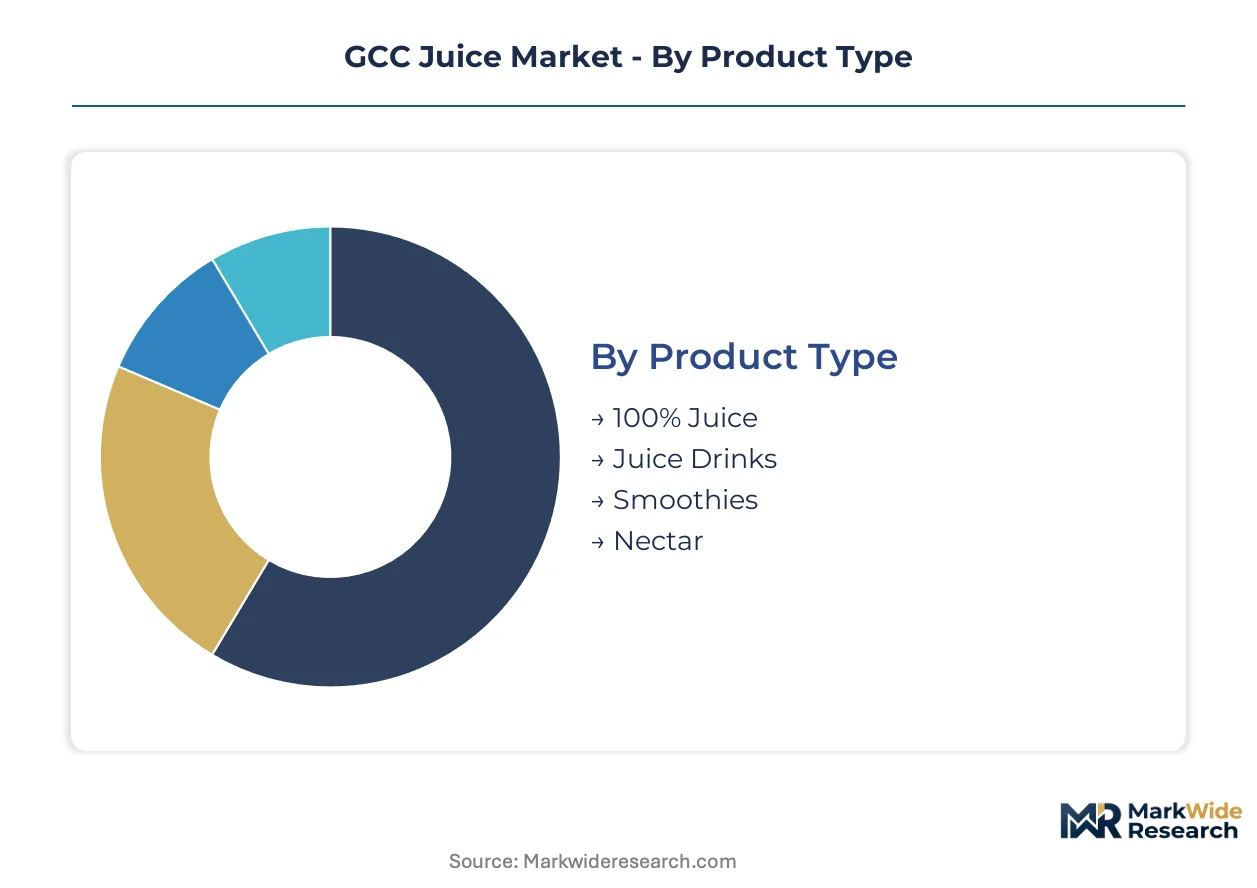
Segmentation in the GCC juice market reveals how health positioning, packaging convenience, and channel access stratify purchasing behavior across Saudi Arabia and the UAE. Each dimension carries distinct regulatory and infrastructure implications that reshape manufacturer priorities.
Product Type:
Domestic production concentrates in ambient-stable categories serving Saudi Arabia's Riyadh-Jeddah corridor, while export-oriented premium formats target smaller Gulf markets with limited cold-chain reach.
- 100% Juice:Pure fruit extraction with no added sugars or preservatives, processed through pasteurization or HPP cold pasteurization. Demand concentrates among health-conscious consumers in Saudi Arabia's urban centers where SFDA labeling requirements reward clean formulations. Premium positioning commands disproportionate margin contribution despite smaller volume share.
- Juice Drinks:Beverages containing 25-99% fruit content with added water, sweeteners, and permitted additives. Volume leadership stems from accessible price points across UAE hypermarkets facing MOHAP sugar-content thresholds. Reformulation pressure intensifies as front-of-pack labeling mandates approach.
- Smoothies:Blended fruit preparations with pulp retention and often dairy or plant-base additions. Chilled distribution requirements limit penetration to modern trade channels with dedicated cold-chain infrastructure in Dubai and Abu Dhabi.
- Nectar:Thickened beverages with 25-50% fruit content and higher pulp density. Popular in food service channels across Kuwait and Bahrain where ambient stability simplifies logistics.
Juice Drinks commands the established base. The steepest expansion runs through 100% Juice.
Packaging Type:
Cost tier differentiation separates institutional volume plays from convenience-driven premium positioning, with material choice directly determining distribution economics and shelf-life extension.
- Bottles:PET and glass containers dominating chilled juice segments with transparent visibility of product quality. Premium 100% juice adoption in Saudi Arabia's modern trade favors PET bottles with oxygen barrier technology. Higher per-unit costs restrict penetration in price-sensitive mass markets.
- Cartons:Aseptic multilayer packaging enabling ambient distribution without refrigeration investment. Institutional channel leadership in UAE supermarkets reflects decades of established supplier relationships and filling line amortization across Almarai and NADEC facilities.
- Pouches:Flexible single-serve formats gaining traction in food service and on-premise consumption. Lower material costs and shipping cube efficiency attract new entrants targeting Bahrain and Oman convenience channels.
- Cans:Aluminum packaging with superior light and oxygen protection for extended shelf stability. Niche positioning in sports and athletic consumption occasions across UAE gyms and recreation facilities.
Cartons anchor volume throughput. Pouch formats are climbing the fastest as food service procurement shifts toward single-serve convenience.
Distribution Channel:
Channel selection determines margin capture versus volume scale, with modern trade consolidation in Saudi Arabia reshaping supplier negotiation dynamics.
- Supermarkets:Hypermarket and supermarket chains with centralized category management and data-driven performance metrics. Riyadh and Jeddah retail clusters concentrate procurement authority among integrated producers with captive supply security. Shelf-space negotiations now hinge on promotional fund commitments and direct supplier relationships.
- Convenience Stores:Small-format retail with extended hours serving immediate consumption occasions. Pouch and single-serve bottle formats dominate in UAE petrol station retail and neighborhood grocery channels.
- Online Retail:E-commerce platforms with subscription models and bulk purchasing options. Emerging channel with logistics complexity around chilled product handling in Saudi Arabia's extreme summer temperatures.
- Food Service:Hotels, restaurants, and catering operations with institutional procurement and specification requirements. Carton concentrate and ambient-ready formats preferred for operational simplicity across Gulf hospitality chains.
Supermarkets control the revenue base. Online Retail is gaining share fastest as delivery infrastructure matures for temperature-sensitive categories.
Customer Type:
Maturity differentiation separates established family purchasing patterns from emerging health-driven segments with distinct formulation and messaging requirements.
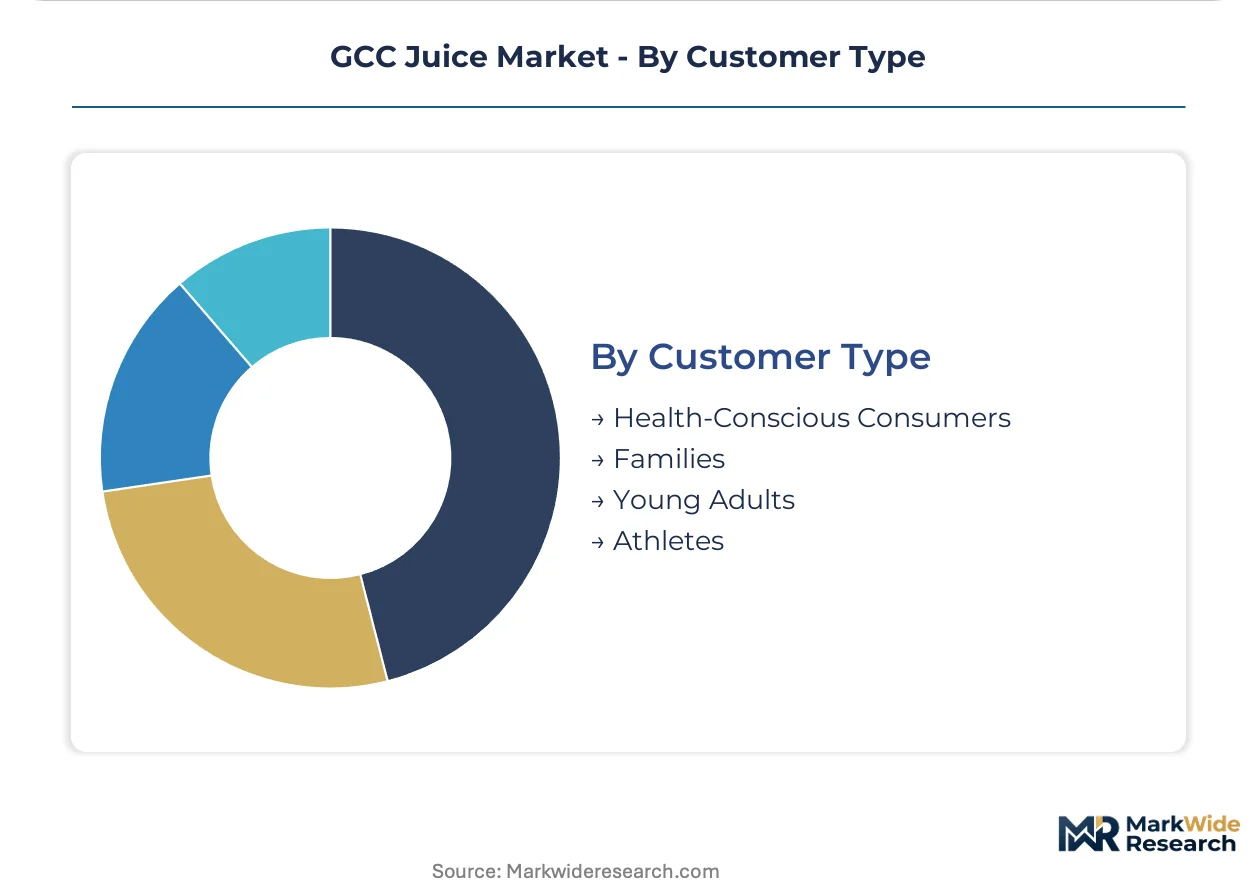
- Health-Conscious Consumers:Buyers prioritizing clean labels, reduced sugar content, and functional nutrition claims. HPP-treated 100% juice adoption accelerates in Saudi Arabia's Riyadh-Jeddah corridor where disposable income supports premium positioning. MOHAP and SFDA labeling transparency mandates reinforce this segment's expansion.
- Families:Multi-person households purchasing larger-format cartons for home consumption. Volume stability in UAE and Saudi Arabia mass markets despite sugar taxation discussions threatening juice drink categories.
- Young Adults:Single-person households and workplace consumers favoring convenience formats and on-the-go consumption. Pouch and small-bottle preference drives packaging innovation in Dubai and Abu Dhabi urban centers.
- Athletes:Performance-oriented consumers seeking electrolyte fortification and protein-enhanced formulations. Niche but high-margin segment concentrated in UAE fitness and sports nutrition channels.
Families represent the volume foundation. Health-Conscious Consumers show the steepest expansion trajectory as clean-label certification becomes a purchase prerequisite.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious buyers concentrate in Saudi Arabia's urban corridors and the UAE's premium retail clusters, with purchasing patterns diverging sharply between mass-market juice drinks and clean-label 100% juice segments.
Saudi Arabia
The Riyadh-Jeddah corridor anchors regional demand through dense hypermarket infrastructure and expanding cold-chain logistics. SFDA halal certification requirements filter market access, privileging producers with integrated dairy-to-juice processing facilities. Al-Qassim agricultural operations supply captive fruit inputs to major processors consolidating shelf space in modern trade channels.
United Arab Emirates
Dubai and Abu Dhabi retail clusters drive premium positioning through health-conscious expatriate and local consumer segments with elevated disposable income. MOHAP nutritional labeling mandates enforce strict sugar-content thresholds and additive disclosure rules that reshape formulation priorities. Chilled distribution networks concentrate in coastal urban zones where temperature-controlled logistics investment exceeds regional norms.
Kuwait
Nascent modern trade development creates first-mover shelf establishment opportunities before competitor infrastructure hardens. The country's national food safety regulator enforces Gulf Standardization Organization technical regulations that align with Saudi and UAE standards. Hawalli and Ahmadi retail clusters show accelerating pouch format adoption in convenience channels previously underserved by ambient-stable carton distribution.
Bahrain
Smaller market scale enables agile format experimentation without major capital commitment to refrigerated logistics. Food service procurement concentrates in Manama's hospitality corridor where ambient nectar and juice drink categories simplify operational requirements. The national standards body implements GSO certification protocols with shorter facility audit queues than larger neighboring markets.
Oman
Geographic dispersion across coastal and interior governorates fragments distribution economics, favoring aseptic-filled ambient products with extended shelf stability. Muscat retail modernization lags Saudi and UAE benchmarks, creating runway for pouch and single-serve bottle formats in emerging convenience channels. Import dependency for tropical fruit concentrates exposes local bottlers to shipping rate volatility from Southeast Asian suppliers.
GCC Juice Market Competitive Landscape
Player mix skews toward integrated dairy conglomerates with backward supply control over agricultural inputs and captive cold-chain infrastructure. Market structure concentrates around three to four vertically positioned groups commanding modern trade shelf access through direct procurement relationships. Strategic archetypes separate integrated agricultural processors, specialized aseptic packaging operators, and multinational beverage licensees with regional bottling agreements. Competitive dynamics center on GSO certification acquisition speed and promotional fund commitments to centralized retail category managers.
Within the integrated agricultural tier, Almarai Company and NADEC exemplify producers leveraging captive supply security to anchor shelf-space negotiations in Saudi hypermarket channels. Al Rabie Saudi Foods Co occupies a specialized position representing aseptic packaging capabilities that extend ambient distribution reach into smaller Gulf markets without refrigerated logistics investment. Among multinational licensees, The Coca-Cola Company anchors beverage diversification beyond carbonated categories through regional bottling partnerships. These three archetypes capture divergent competitive vectors: agricultural integration, packaging technology specialization, and brand portfolio breadth.
| Leading Market Players |
|---|
| NADEC |
| National Food Products Company |
| Almarai Company |
| Arrow Juice Factory |
| Kuwaiti Danish Dairy Co |
| Al Rabie Saudi Foods Co |
| Al Rawabi Dairy Company |
| Al Ain Dairy Co |
| The Coca-Cola Company |
| Others |
Supply & Pricing Matrix
Scale economies in aseptic filling lines across Saudi Arabia's Riyadh-Jeddah corridor compress unit costs for ambient-stable juice categories while elevating price floors for chilled premium formats requiring dedicated cold-chain infrastructure.
Pricing Analysis
Cost-plus contracts with Southeast Asian concentrate suppliers indexed to shipping rate fluctuations dominate procurement economics for GCC juice producers. Three-tier pricing structure across premium HPP-treated 100% juice, standard aseptic-filled cartons, and economy juice drink tiers separates health-conscious Saudi consumers from mass-market UAE families. Pricing pressure stems from MOHAP sugar-content thresholds forcing reformulation investment without commensurate price recovery. Families purchasing multi-serve cartons exhibit highest price sensitivity; health-conscious buyers in Dubai's premium retail clusters accept substantial premiums for clean-label certification.
Supply Chain Analysis
Thailand and Brazil anchor tropical fruit concentrate supply for GCC processors, while domestic Saudi agricultural operations in Al-Qassim provide captive date and citrus inputs. Production rests on imported pulp concentrates, PET resin shipments, and aseptic packaging materials from European suppliers. Single-source vulnerability concentrates in Southeast Asian shipping lanes exposed to Red Sea route disruptions. Distribution runs through integrated dairy-to-juice conglomerates with direct hypermarket relationships, bypassing traditional broker networks in Riyadh's consolidated retail clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-growth disruption characterizes the GCC juice market as HPP cold pasteurization fragments traditional aseptic dominance and MOHAP labeling mandates force portfolio-wide reformulation.
For Market Incumbents: Consolidate shelf access through accelerated GSO certification acquisition and captive agricultural expansion in Saudi Arabia's Al-Qassim region. Almarai and NADEC should deepen direct procurement relationships with Riyadh hypermarket chains before competitor cold-chain infrastructure hardens. Defensive priority centers on locking promotional fund commitments with centralized category managers. For New Entrants and Emerging Players: Lead with pouch format convenience targeting Bahrain and Kuwait food service channels where ambient-stable distribution avoids refrigerated logistics investment. White-space opportunity concentrates in Manama's hospitality corridor and Hawalli's emerging convenience retail. Go-to-market angle should emphasize single-serve cube efficiency and lower material costs versus institutional carton formats. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized aseptic packaging operators with Gulf Standardization Organization compliance already secured. Long-term viability over the next decade hinges on clean-label formulation capabilities and transparent supply chain documentation. Signal to monitor: MOHAP front-of-pack labeling mandate implementation timeline as inflection indicator for reformulation cost exposure.| Strategic Initiative | Industry Significance |
|---|---|
| HPP Technology Deployment | Cold pasteurization capacity captures premium 100% juice demand in Saudi Arabia's Riyadh-Jeddah corridor. |
| GSO Certification Acceleration | Halal compliance documentation compresses product launch windows and filters non-qualified competitors from shelf access. |
| Pouch Format Expansion | Flexible single-serve packaging reduces shipping cube costs for Bahrain and Kuwait convenience channel penetration. |
| Captive Agricultural Investment | Backward integration into Al-Qassim date and citrus operations secures supply against concentrate import volatility. |
| Direct Retail Procurement | Bypassing broker networks with hypermarket category managers locks shelf space through promotional fund commitments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with Saudi hypermarket category managers, UAE food service procurement directors, GCC cold-chain logistics engineers, and aseptic packaging technology specialists. Secondary validation drew from SFDA regulatory filings, MOHAP nutritional labeling directives, GSO technical regulations, customs import records for tropical fruit concentrates, and Nielsen retail audit data for Saudi Arabia and UAE modern trade channels. Bottom-up volume modeling triangulated against top-down macroeconomic consumption indicators.
Across the analysis window, forecasts employed segmented modeling across product type, packaging format, distribution channel, and customer archetype dimensions. CAGRs were derived from trend extrapolation of health-conscious consumer adoption rates, HPP capacity installation schedules, and modern trade consolidation patterns. Industry-specific inputs included MOHAP sugar-content threshold compliance costs and GSO certification timeline assumptions for new market entrants.
The analysis sits within stated boundaries; outcomes outside sustained cold-chain infrastructure investment, stable shipping lane access, or delayed sugar taxation implementation would require recalibration. Forecasts reflect documented assumptions around regulatory enforcement intensity and consumer willingness-to-pay for clean-label certification. Recalibration cycles align with material shifts in MOHAP labeling mandates, SFDA halal audit queue lengths, and Red Sea shipping route stability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Bangladesh Energy Drinks Market
Beverages
Semillon Market
Beverages
Aloe Vera-Based Drink Market
Beverages
Wine Cooler and Chest Freezer Market
Beverages
Global Fruit Juice Concentrate Market
Beverages
Blackstrap Molasses Market
Beverages
Peanut Oil Market
Beverages
Global Soft Drinks Concentrate Market
Beverages
Saudi Arabia Drinking Water Market
Beverages
Nitro-Infused Beverages Market
Beverages
Coconut Milk Beverages Market
Beverages
Adaptogenic Beverages Market
Beverages
Carbonate Drink Maker Market
Beverages
Botanical Infused Beverages Market
Beverages
Packaged Coconut Water Market
Beverages
Asia Pacific Soy Beverages Market