
 Soft Serve Premix Market | 2026-2036
Soft Serve Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Serve Premix Market Analytics
Software-defined flavor calibration is shifting how soft serve premix vendors structure recurring revenue, moving beyond bulk powder sales toward subscription-based dispensing systems. Nestlé leverages its dairy supply chain to anchor European food service accounts. Cargill competes through in-house stabilizer and emulsifier production. Dole Food Company specializes in fruit-based flavor concentrates for tropical market variants.
Soft serve premix comprises a dry or liquid base mixture containing milk solids, sugars, stabilizers, and emulsifiers, reconstituted with water or milk and frozen under shear in a soft serve machine to achieve overrun. The formulation typically targets 30-60% overrun with a serving temperature of -6°C to -8°C for optimal texture and mouthfeel. Vanilla and chocolate product types dominate volume due to operational simplicity in single-flavor machines, while mint captures seasonal peaks in Q2-Q3. Pouch packaging leads in cost-sensitive channels, though tub formats command stronger placement in full-service restaurants where batch consistency matters.
FDA dairy labeling requirements and EFSA food additive specifications shape permissible stabilizer combinations and front-of-pack claims across export-bound production. BIS standards in India and FSSAI dairy safety norms govern import premix formulations entering South Asian food service. Stakeholders must monitor evolving clean-label thresholds as enzyme-modified starch and carrageenan face reformulation pressure in premium positioning tiers.
Market Dynamics
Clean-label ingredient mandates from EFSA and FDA are forcing reformulation across soft serve premix portfolios, compressing stabilizer options while elevating enzyme-modified starch and carrageenan scrutiny in premium tiers.
Growth Catalysts
- Quick-service expansion:Southeast Asian QSR chains are scaling soft serve programs as dairy-processing infrastructure modernizes in Thailand and Vietnam, creating concentrated demand pull.
- EFSA additive specifications:Evolving food additive frameworks are accelerating permissible stabilizer innovation, opening formulation flexibility for export-bound European production.
- Software-defined dispensing:IoT-enabled flavor calibration systems are embedding subscription revenue models, shifting vendor economics beyond bulk powder transactions.
Market Restraints
- Skim milk powder volatility:Dairy commodity input costs fluctuate with New Zealand and EU production cycles, squeezing margin predictability for premix manufacturers.
- Stabilizer supply concentration:Carrageenan and locust bean gum sourcing clusters in Southeast Asian coastal regions, exposing formulators to climate and logistics disruptions.
- Clean-label technical ceiling:Removal of modified starches degrades freeze-thaw stability and mouthfeel, creating formulation trade-offs that premium positioning cannot always absorb.
Strategic Opportunities
- India food service penetration:BIS standards and FSSAI dairy safety norms are harmonizing, reducing import friction for premix vendors targeting underpenetrated South Asian QSR chains.
- Fruit-concentrate convergence:Blending tropical flavor concentrates with dairy bases is capturing seasonal menu rotations in Southeast Asian hospitality channels.
- Direct-to-operator digital channels:E-procurement platforms are disintermediating traditional distributor networks, enabling margin capture and customer data ownership for premix suppliers.
Industry Challenges
- Refrigerated logistics reconfiguration:Cold-chain infrastructure gaps in emerging markets force premix vendors to absorb last-mile spoilage risk or partner with capital-intensive 3PL operators.
- Clean-label certification timelines:EFSA and FDA parallel review processes for novel stabilizer approvals extend time-to-market by 18-36 months, compressing innovation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Serve Premix Market |
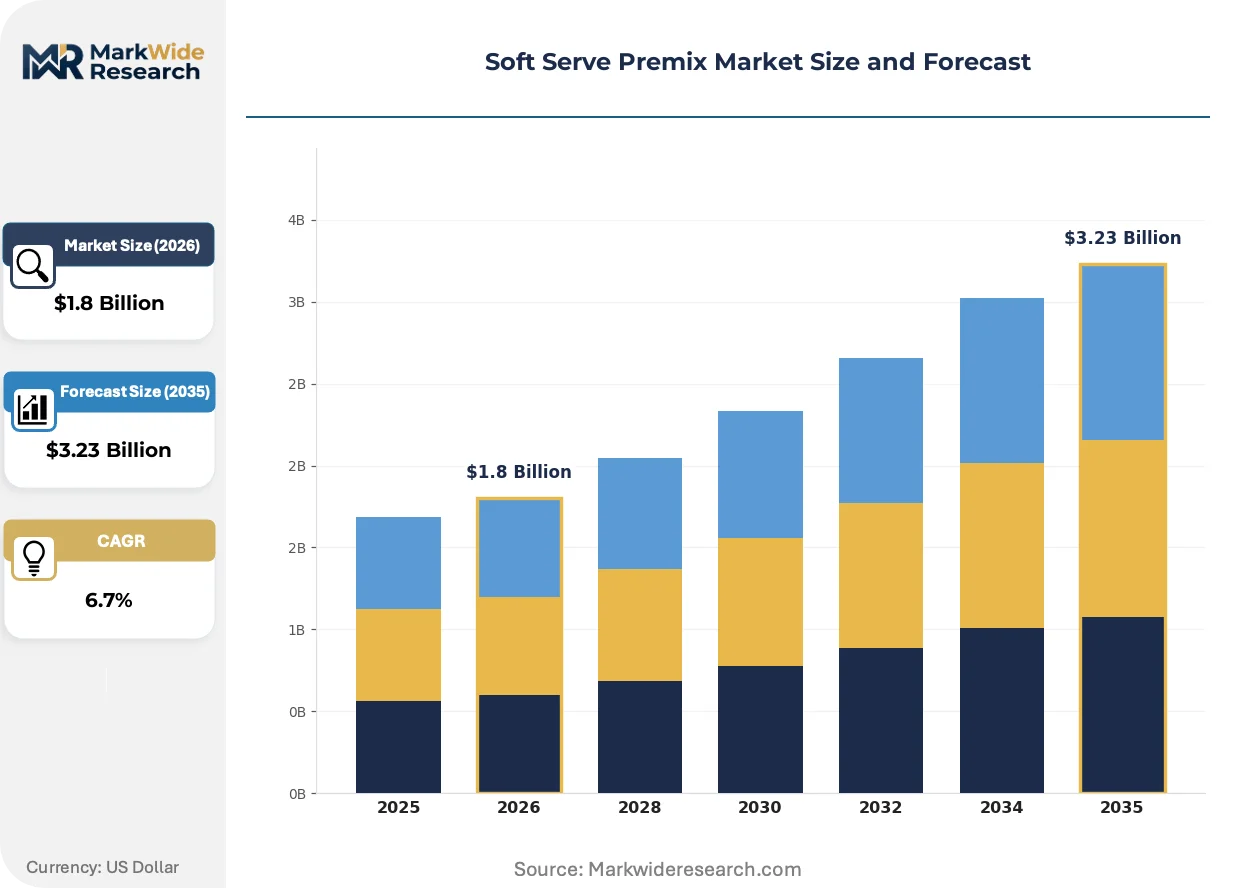
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vanilla, Chocolate, Strawberry, Mint Distribution Channel: Online, Supermarkets, Convenience Stores, Food Service Packaging Type: Pouches, Tubs, Cartons, Sachets End User: Ice Cream Shops, Restaurants, Cafés, Mobile Vendors |
| Companies Covered | Chomthana, Dole Food Company, Michael Foods, Cargill, Nestlé, General Mills, Conagra Brands, Kraft Foods, McCain Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Serve Premix Market Evolving Landscape
Digital integration of dispensing hardware with formulation supply is collapsing the traditional separation between equipment and ingredient vendors, creating unified service architectures.
Precision fermentation-derived dairy proteins are unifying functional performance with label-friendly positioning. Mid-scale food service operators in the Netherlands and Denmark are piloting these alternatives at test-scale volumes. This convergence is unifying what were previously separate premium and clean-label product tiers into single-positioning SKUs.
EFSA's evolving stance on enzyme-modified starch is tightening permissible processing aids in front-of-pack claims. Manufacturers serving EU-bound exports are pre-emptively reformulating with native starches and hydrocolloid blends. Premium-positioned tub formats for full-service restaurants face the steepest compliance cost escalation.
Subscription-based dispensing systems are displacing capital equipment purchases across Southeast Asian QSR chains. Operators in Bangkok and Ho Chi Minh City are leasing machines with locked-in premix supply, transferring capex burden to vendors. This procurement pivot is most visible in chains operating 50-200 outlet networks seeking operational flexibility.
Soft Serve Premix Market Segmentation
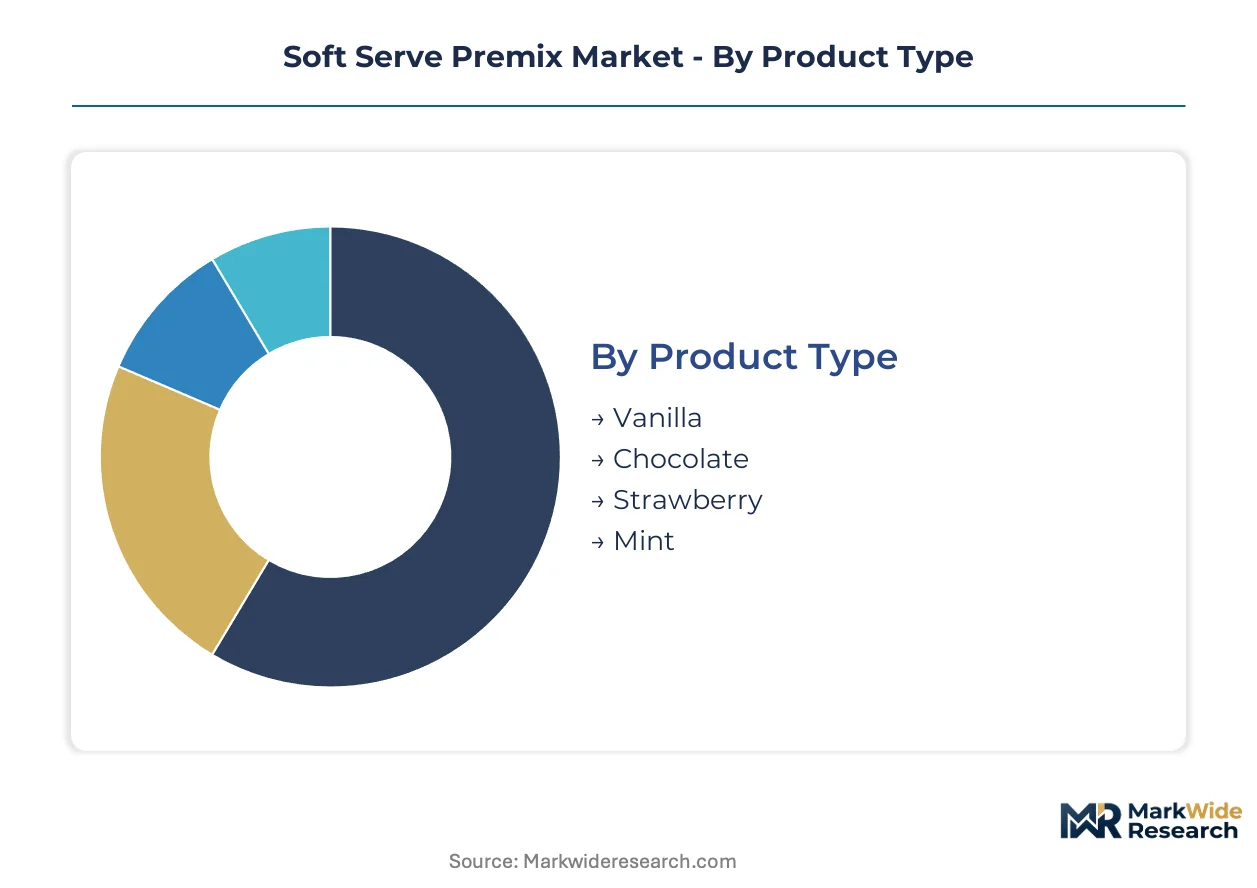
Soft serve premix segmentation reveals divergent margin architectures across product types and channel configurations. Volume concentration in vanilla and chocolate masks faster value expansion in seasonal and specialty variants, while packaging format choices directly determine cold-chain economics and spoilage exposure.
Product Type:
Vanilla and chocolate anchor operational simplicity in single-flavor dispensing systems, while mint and strawberry command premium positioning through seasonal rotation strategies.
- Vanilla:Standard base formulation with 30-60% overrun targets and -6°C serving parameters. Quick-service chains in Thailand and Vietnam standardize on vanilla for operational consistency across high-volume outlet networks, though margin compression intensifies as dairy commodity volatility transmits through skim milk powder costs.
- Chocolate:Cocoa-based variant requiring modified stabilizer blends to manage fat-protein emulsion stability. Full-service restaurants in European markets favor chocolate for menu differentiation, with EFSA additive specifications forcing native starch reformulation that elevates unit economics in premium tub formats.
- Strawberry:Fruit-acidified dairy base demanding precise pH buffering to prevent protein precipitation. Southeast Asian hospitality channels rotate strawberry seasonally, with Dole Food Company supplying concentrated flavor inputs.
- Mint:Seasonal peak variant capturing Q2-Q3 demand surges in temperate markets. Limited annual production windows constrain inventory planning for premix vendors serving North American and European ice cream shop segments.
Today's leader: Vanilla. Tomorrow's challenger: Mint.
Distribution Channel:
Channel selection determines customer data ownership and margin capture potential, with direct digital routes displacing traditional distributor networks.
- Online:E-procurement platforms enable subscription-based dispensing system bundling. Bangkok and Ho Chi Minh City QSR chains lease IoT-enabled machines through locked-in premix supply contracts, transferring capex burden to vendors while securing recurring revenue streams.
- Supermarkets:Retail shelf placement for home-use pouch formats competes on unit economics against food service bulk pricing. Cold-chain requirements limit geographic reach to markets with established refrigerated logistics infrastructure.
- Convenience Stores:Impulse-oriented sachet and small-pouch formats targeting mobile consumption. Urban clusters in India show emerging penetration as BIS standards harmonize with FSSAI dairy safety norms.
- Food Service:Direct supply relationships with ice cream shops, restaurants, and cafés dominate value concentration. Batch consistency requirements in full-service restaurants favor tub packaging over cost-sensitive pouch alternatives.
Food service channels currently capture the steepest value expansion trajectory, with online routes climbing fastest in Southeast Asian metropolitan networks.
Packaging Type:
Format selection encodes cold-chain investment requirements and batch size flexibility trade-offs that segment customer types.
- Pouches:Flexible film packaging dominates cost-sensitive channels with lower per-unit material costs. Mobile vendors and convenience store routes favor pouches for logistics efficiency, though puncture risk elevates spoilage exposure in last-mile distribution.
- Tubs:Rigid plastic containers command placement in full-service restaurants where batch-to-batch consistency determines operator loyalty. Premium positioning tiers absorb steeper compliance costs from EFSA enzyme-modified starch restrictions.
- Cartons:Paperboard-based formats with polyethylene liners serving intermediate volume operators. Sustainability positioning pressures are accelerating carton adoption in European food service accounts.
- Sachets:Single-serve portions for trial-size marketing and mobile vendor impulse sales. Unit economics constrain sachet viability to high-margin specialty flavors in developed market urban cores.
Tubs currently anchor premium value pools. Pouches are gaining share fastest in emerging market volume expansion.
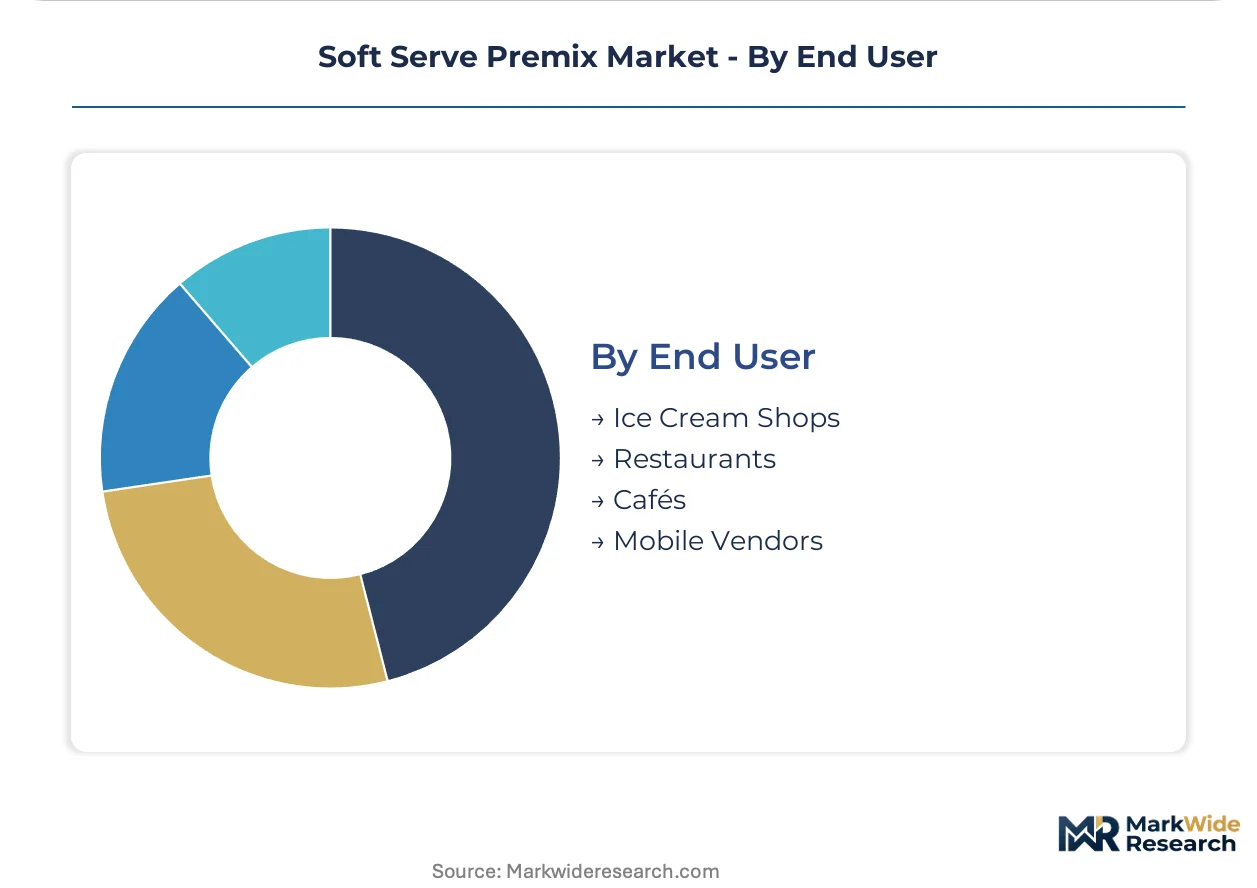
End User:
Operator scale and equipment sophistication segment formulation requirements and service intensity demands.
- Ice Cream Shops:Dedicated soft serve operators requiring high-overrun consistency and multi-flavor machine compatibility. Seasonal demand volatility in temperate markets creates inventory financing challenges for premix suppliers.
- Restaurants:Full-service dining establishments integrating soft serve as dessert menu components. Batch size flexibility and native starch clean-label compliance drive tub format preference in EU-bound export markets.
- Cafés:Coffee-forward operators adding soft serve as complementary beverage pairing. Limited equipment space constrains machine footprint, favoring compact dispensing systems with locked-in supply contracts.
- Mobile Vendors:Festival, event, and street-food operators with intermittent power access and minimal cold storage. Pouch formats and dry-mix reconstitution dominate this segment's technical requirements.
Restaurants currently concentrate premium value. Mobile vendors represent the most rapid volume expansion opportunity in Southeast Asian urban clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand and Vietnam concentrate Southeast Asian demand pull, while the Netherlands and Denmark pilot precision fermentation alternatives that unify premium and clean-label tiers.
United States
Quick-service restaurant chains scale soft serve programs across metropolitan networks, with seasonal mint variants capturing Q2-Q3 demand surges. FDA dairy labeling requirements shape permissible stabilizer combinations and front-of-pack claims for domestic and export-bound production. Dallas and Atlanta clusters anchor high-volume dispensing system deployments through subscription-based procurement models.
Thailand
Dairy-processing infrastructure modernization creates concentrated demand for vanilla premix standardization across 50-200 outlet QSR networks. BIS standards harmonization with regional norms facilitates cross-border supply chain integration. Bangkok metropolitan operators lease IoT-enabled machines with locked-in premix contracts, transferring capex burden to vendors.
Vietnam
Ho Chi Minh City chains adopt software-defined flavor calibration systems that embed recurring revenue beyond bulk powder transactions. FSSAI dairy safety norms influence import formulation standards for South Asian market access. Urban hospitality channels rotate strawberry seasonally, blending tropical concentrates with dairy bases.
Germany
EFSA food additive specifications accelerate permissible stabilizer innovation for enzyme-modified starch and carrageenan alternatives. Native starch reformulation elevates unit economics in premium tub formats serving full-service restaurants. Bavaria and North Rhine-Westphalia industrial zones concentrate clean-label premix manufacturing for EU-bound export markets.
Netherlands
Mid-scale food service operators pilot precision fermentation-derived dairy proteins at test-scale volumes. EFSA evolving thresholds on modified starches tighten front-of-pack claim eligibility. Randstad logistics hubs enable refrigerated distribution infrastructure for emerging market cold-chain reconfiguration.
Soft Serve Premix Market Competitive Landscape
Top-tier vendors anchor integrated dairy supply chains, while mid-scale specialists compete through stabilizer innovation and tropical flavor concentration. The market structure concentrates around multinational food conglomerates with captive ingredient production, regional dairy processors with distribution depth, and fruit specialists with hospitality channel relationships. Strategic archetypes include backward-integrated dairy majors, in-house stabilizer producers, and tropical concentrate blenders. Competitive moves center on subscription-based dispensing system bundling and clean-label reformulation pre-empting regulatory tightening.
Within the multinational conglomerate tier, Nestlé S.A. and Cargill, Incorporated occupy positions defined by supply chain control and ingredient manufacturing integration. Dole Food Company exemplifies the tropical specialization archetype. These three entities represent divergent strategic vectors: dairy supply chain anchoring, in-house stabilizer and emulsifier production, and fruit-based flavor concentrate development for regional variants.
| Leading Market Players |
|---|
| Chomthana |
| Dole Food Company |
| Michael Foods |
| Cargill |
| Nestlé |
| General Mills |
| Conagra Brands |
| Kraft Foods |
| McCain Foods |
| Others |
Value Network & Pricing Analysis
Software-defined dispensing system rollouts are compressing equipment procurement costs while simultaneously concentrating premix supply relationships around locked-in subscription contracts. This technology shift transfers capital expenditure burdens from Southeast Asian QSR operators to vendors, reshaping margin economics across vanilla standardization and seasonal flavor rotation tiers.
Pricing Analysis
Capacity additions in Thailand and Vietnam are reshaping price floors for vanilla premix standardization across 50-200 outlet QSR networks. Three-tier pricing structure across premium, standard, and economy levels segments by clean-label certification grade and volume commitment scale. Cost compression in economy tiers is intensifying because skim milk powder volatility transmits through dairy commodity cycles. Mobile vendors in Southeast Asian urban clusters exhibit highest price sensitivity, while full-service restaurants in Germany absorb premium tub format premiums.
Supply Chain Analysis
EFSA clean-label certification timelines gate supply eligibility for EU-bound export production, forcing native starch reformulation investments. Manufacturing concentrates in Germany, the Netherlands, and Thailand, with precision fermentation pilots in Denmark drawing from novel dairy protein inputs. Carrageenan and locust bean gum sourcing clusters in Southeast Asian coastal regions, exposing formulators to climate disruption. Distribution runs through food service direct channels and emerging e-procurement platforms disintermediating traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Soft Serve Premix Market functions as a geographic-arbitrage play: EFSA regulatory tightening elevates compliance costs in Europe while Southeast Asian infrastructure modernization creates demand pull at lower operational cost bases.
For Market Incumbents: Anticipate precision fermentation-derived dairy proteins unifying premium and clean-label tiers by accelerating native starch reformulation R&D. Defend margin position through backward integration into stabilizer production, countering carrageenan supply concentration risks. Lock in 50-200 outlet QSR networks via subscription-based dispensing system bundling before emerging specialists capture this procurement pivot.
For New Entrants and Emerging Players: Enter via direct-to-operator digital channels in underpenetrated Indian metropolitan clusters where BIS-FSSAI harmonization reduces import friction. Target mobile vendor segments in Bangkok and Ho Chi Minh City with pouch-format dry-mix solutions optimized for intermittent power access. Lead with seasonal fruit-concentrate blending capabilities that incumbent dairy majors lack.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional dairy processors with distribution depth but lacking IoT-enabled dispensing system integration. Five-to-ten year viability hinges on clean-label certification asset ownership rather than commodity premix volume. Watch EFSA novel stabilizer approval timelines as inflection indicator for formulation-locked vendor repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription-Based Dispensing System Bundling | Locks in recurring revenue streams across Southeast Asian QSR chains transferring capex burden. |
| Native Starch Reformulation Investment | Pre-empts EFSA enzyme-modified starch restrictions elevating compliance costs in premium tiers. |
| Precision Fermentation Protein Integration | Unifies functional performance with label-friendly positioning in Netherlands and Denmark pilots. |
| Direct-to-Operator Digital Channel Buildout | Disintermediates distributor networks enabling margin capture and customer data ownership. |
| Tropical Fruit-Concentrate Blending Capability | Captures seasonal menu rotations in Southeast Asian hospitality channels Dole Food Company anchors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with QSR procurement directors, food service equipment distributors, dairy processing plant managers, and EFSA regulatory affairs specialists with secondary validation. Trade data from customs records, dairy commodity price indices, and food additive specification databases anchored supply-side assessment. Bottom-up outlet network expansion modeling and top-down category spend analysis provided triangulation.
Segment-weighting across product type, packaging format, distribution channel, and end-user scale dimensions structured volume and value outputs across the projection horizon. CAGRs derived from fitted growth curves applied to dairy infrastructure investment pipelines and QSR expansion announcements. Clean-label regulatory threshold evolution and precision fermentation commercialization timelines served as scenario variables.
Inputs from EFSA additive specification drafts and FSSAI dairy safety norm consultations were available through the study window; gaps in real-time QSR lease contract disclosure introduce uncertainty bands around subscription revenue capture rates. Forecasts reflect documented assumptions on infrastructure modernization pace and regulatory approval timelines. A model refresh is warranted upon material change in EFSA novel stabilizer approval velocity or precision fermentation protein cost parity achievement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Botanical Infused Beverages Market
Beverages
Morocco Bottled Water Market
Beverages
Germany Probiotic Drinks Market
Beverages
Chocolate Malt Drink Market
Beverages
Ginger Ale Market
Beverages
Global Bottled Water Market
Beverages
GCC Fruit Juice Market
Beverages
Recovery Drinks Market
Beverages
Middle East and Africa Ready to Drink Beverages Market
Beverages
Africa Dairy Based Beverages Market
Beverages
Apple Juice Concentrate Market
Beverages
Hydrogen Water Bottle Market
Beverages
Asia-Pacific Bottled Water Market
Beverages
Craft Soda Market
Beverages
Still Drinks Market
Beverages
Packaged Turmeric-Based Beverage Market