
 Coconut Milk Beverages Market | 2026-2036
Coconut Milk Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Coconut Milk Beverages Market Insights
The EU Green Deal is shifting procurement criteria across European foodservice channels, prompting buyers to scrutinize supply chain provenance and carbon intensity. Thai Coconut Public Company Limited leverages integrated plantation operations to secure raw material consistency. Vita Coco anchors its position through dominant shelf presence in North American health stores and supermarkets. Goya Foods differentiates via entrenched distribution within Hispanic retail corridors across the United States.
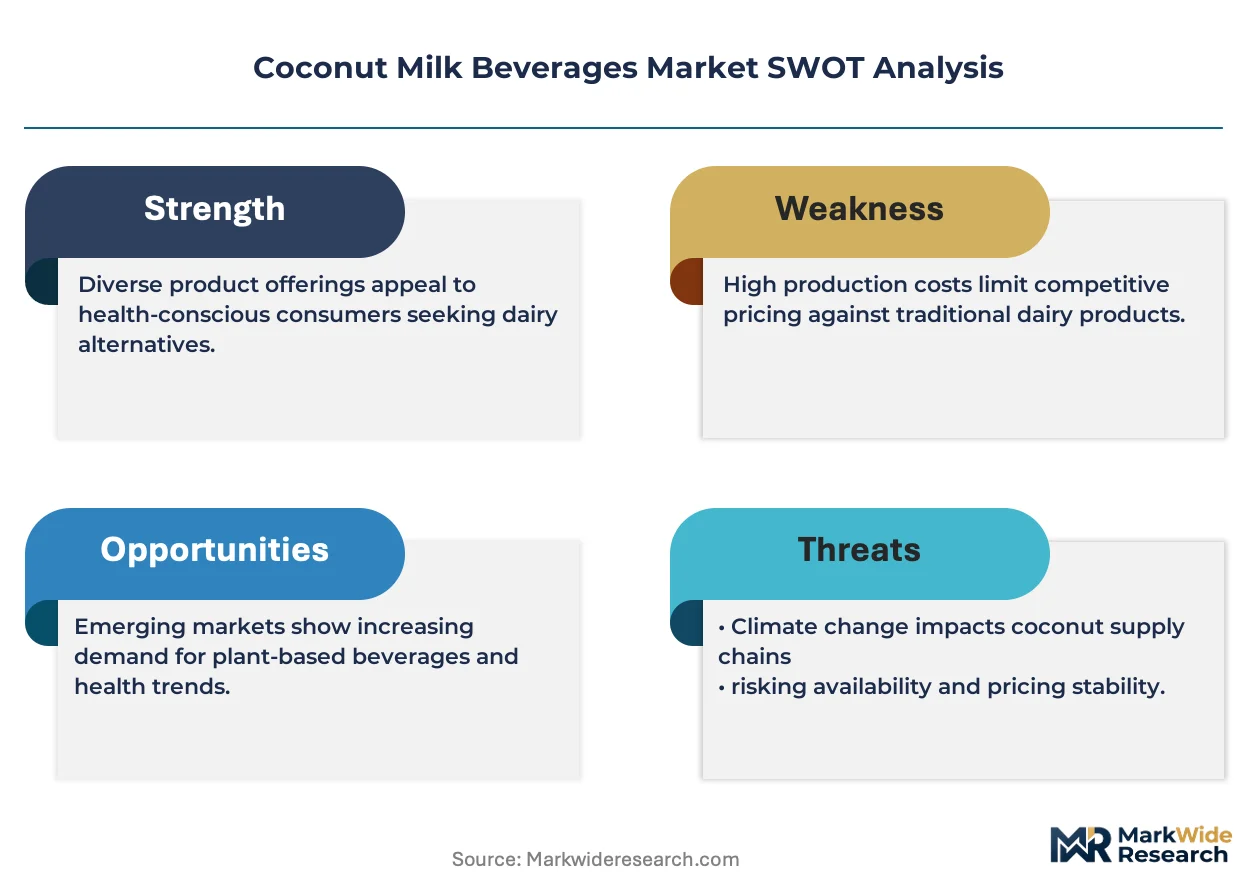
Coconut milk beverages comprise emulsified aqueous extracts from grated coconut kernel, typically containing 15-25% fat and stabilized through homogenization or canning processes to prevent phase separation. The primary commercial purpose centers on delivering dairy-alternative functionality for direct consumption, coffee preparation, and culinary applications. Traditional formulations currently dominate volume, though organic certification commands disproportionate margin pools as health stores and specialty shops enforce stricter sourcing standards. Tetra Pak packaging is expanding fastest among formats, driven by ambient distribution economics and retailer preference for extended shelf life without refrigeration.
FDA labeling requirements for plant-based milk alternatives in the United States shape permissible nutrient claims and comparison disclosures. EFSA guidance on novel food status affects how fortified coconut milk products enter European markets. Health Canada and PMRA oversight of pesticide residues on imported coconut raw materials influences which suppliers achieve import approval. Stakeholders must monitor evolving allergen disclosure mandates and carbon border adjustment mechanisms as these frameworks increasingly determine competitive access rather than mere compliance burden.
Market Dynamics
The EU Green Deal's sustainable packaging mandates are forcing rapid reformulation across European foodservice channels, compressing margins while reshaping supplier qualification criteria toward carbon intensity metrics and provenance transparency.
Growth Catalysts
- Specialty Coffee Expansion:Plant-based milk programs at United States and Western European coffee chains are normalizing coconut milk as a default dairy alternative in espresso-based beverages.
- EU Green Deal Procurement Pressure:Sustainable packaging requirements are rewriting buyer specifications across German, United Kingdom, and Canadian retail channels.
- Tetra Pak Ambient Distribution:Extended shelf-life economics without refrigeration are unlocking rural and convenience-store penetration in Southeast Asian sourcing hubs.
Market Restraints
- Raw Material Concentration Risk:Coconut kernel supply concentrates in Thailand, Indonesia, and the Philippines, exposing processors to climate volatility and shipping bottlenecks.
- FDA Labeling Friction:Nutrient claim restrictions and comparison disclosure requirements for plant-based milk alternatives limit marketing flexibility in United States retail.
- Oat Milk Substitution:Barista-formulated oat beverages are capturing coffee-chain shelf space through superior foam stability and neutral flavor profiles.
Strategic Opportunities
- Canadian Market Underpenetration:Health Canada and PMRA import pathways for pesticide-residue-compliant coconut materials remain underexploited relative to United States volume.
- Organic Certification Premium:Health stores and specialty shops are enforcing stricter sourcing standards that command disproportionate margin pools.
- Fortification Convergence:Protein and micronutrient fortification technologies are opening clinical nutrition and senior-care channel access.
Industry Challenges
- Homogenization Engineering Talent:Stabilizing 15-25% fat emulsions without phase separation requires scarce food-process engineering expertise.
- EFSA Novel Food Timelines:Fortified coconut milk products face extended European market entry delays pending novel food status determinations.
- Carbon Border Adjustment Readiness:Supply chain documentation systems must retrofit to capture embedded emissions data for impending tariff mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coconut Milk Beverages Market |
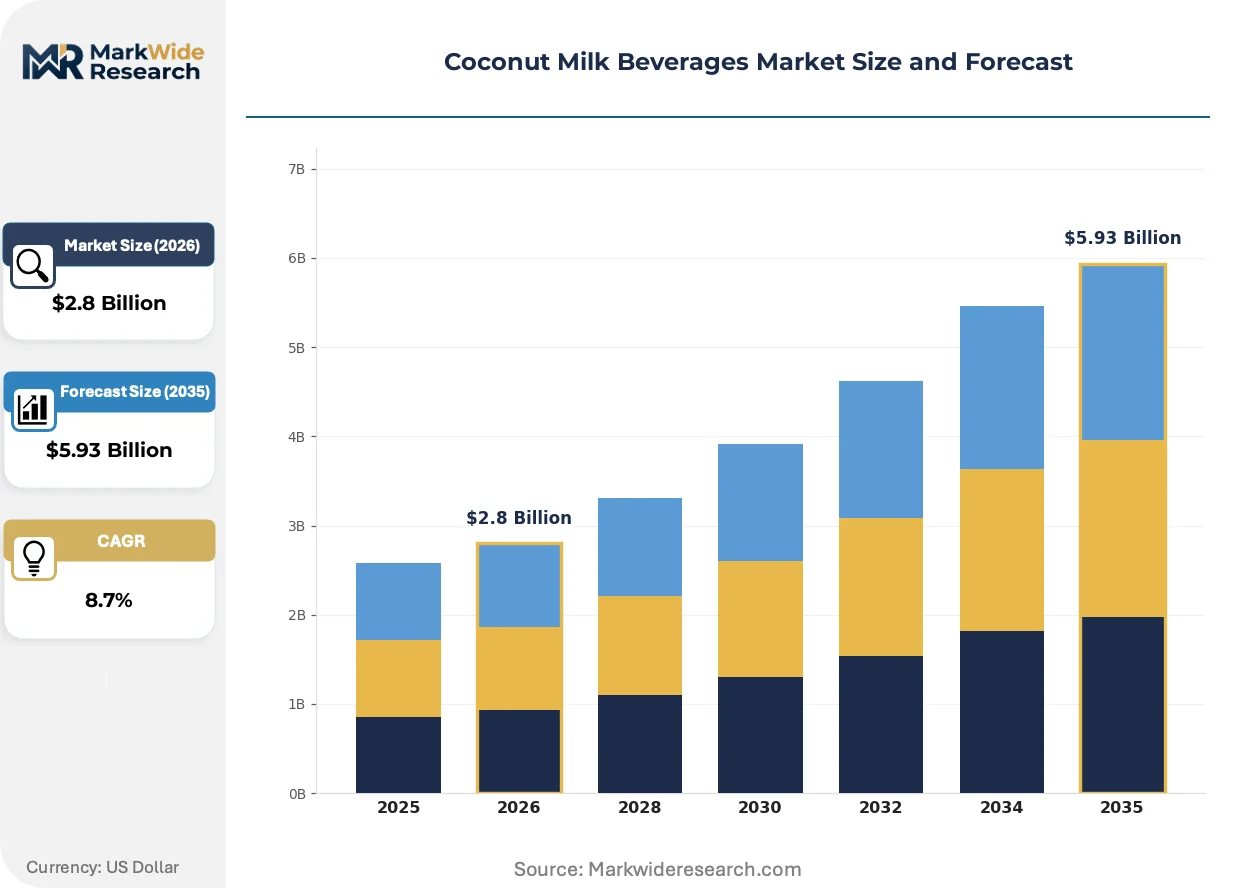
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Flavored, Organic, Shelf-Stable End User: Households, Cafés, Restaurants, Food Manufacturers Packaging Type: Bottles, Cans, Tetra Paks, Pouches Distribution Channel: Supermarkets, Health Stores, Online Retailers, Specialty Shops |
| Companies Covered | Theppadungporn Coconut Co., Ltd., Thai Coconut Public Company Limited, Goya Foods, Vita Coco, McCormick & Company, Danone, Sambu Group, Axelum Resources Corp., Betrimex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coconut Milk Beverages Market Trends and Innovations
Reformulation priorities are diverging between clean-label minimalism and functional fortification, while packaging formats and procurement specifications undergo simultaneous pressure from sustainability mandates and distribution economics.
High-pressure processing and aseptic filling technology is modularizing production footprints for coconut milk beverages. Mid-sized processors in Germany and the United Kingdom are adopting containerized processing lines to serve regional foodservice accounts without centralized canning infrastructure. This distributed manufacturing model is compressing lead times and enabling just-in-time delivery contracts.
EFSA guidance on novel food status is reshaping European product development roadmaps. Fortified coconut milk formulations with added proteins or vitamins now require pre-market authorization, extending launch timelines by months. German and United Kingdom importers are responding by prioritizing traditional formulations for near-term volume while isolating innovation pipelines in separate regulatory tracks.
Buyer concentration among specialty coffee chains is shortening supplier switching cycles. United States and Canadian coffee operators are unbundling milk procurement from equipment contracts, enabling quarterly supplier rotations based on price and sustainability credentials. This disintermediation is most visible in Pacific Northwest and Ontario markets where barista preference data drives rapid vendor turnover.
Coconut Milk Beverages Market Segmentation
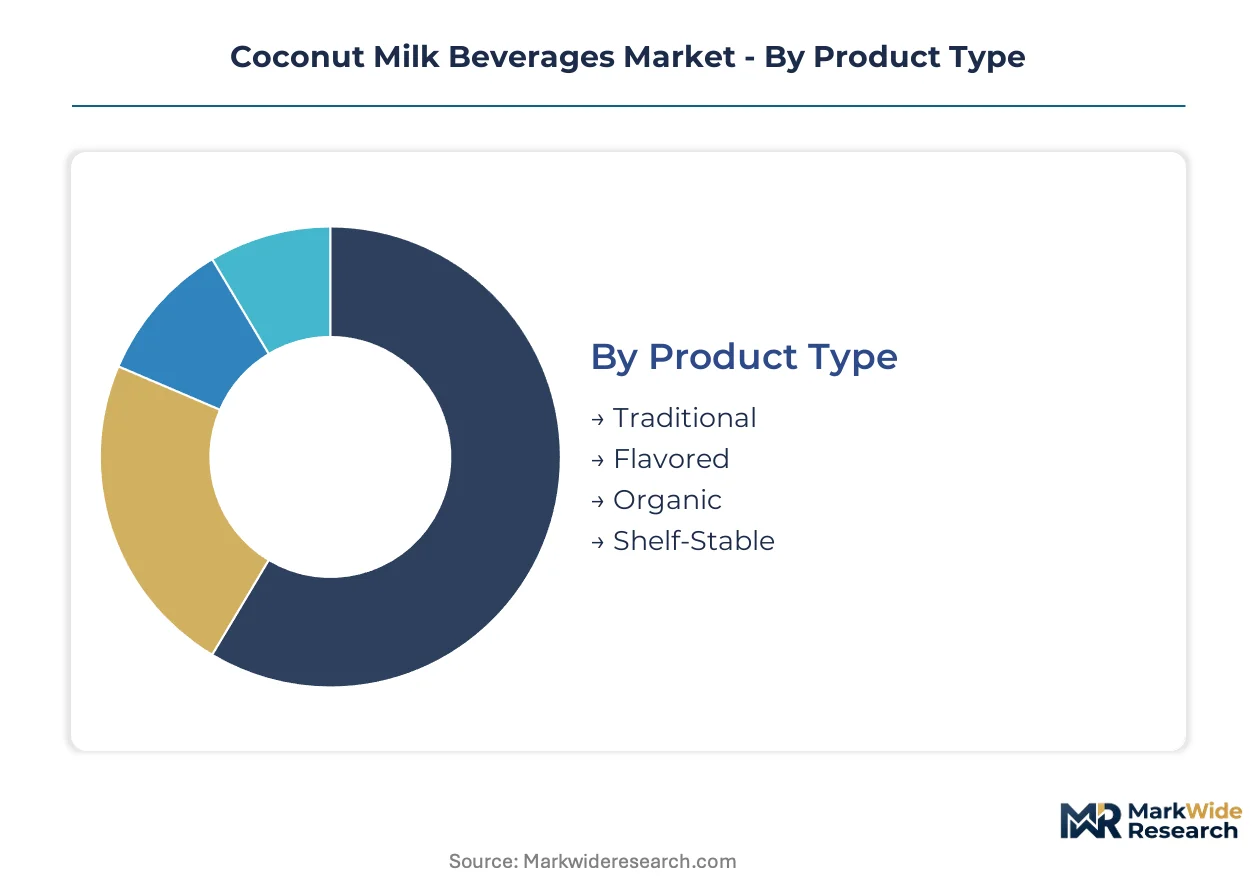
Coconut milk beverage suppliers configure production lines around distinct upgrade cycles. Traditional formulations anchor household pantry replenishment, while organic and barista-grade variants command shorter innovation cycles tied to coffee-chain menu refreshes and health-store certification standards.
Product Type:
Upgrade cycles vary dramatically across formulation tiers, with organic certification driving the most compressed replacement timelines.
- Traditional:Standard 15-25% fat emulsions stabilized through homogenization or thermal processing dominate volume in Thai and Indonesian sourcing corridors. Household demand in Germany and the United Kingdom treats this as a commodity pantry staple with minimal brand switching.
- Organic:Certification-compliant sourcing from integrated plantation operations secures disproportionate margin pools in North American health stores. The EU Green Deal's carbon intensity metrics are accelerating procurement shifts toward traceable organic supply chains in Canadian retail channels.
- Flavored:Vanilla and chocolate extensions target direct-consumption occasions in United States supermarkets.
- Shelf-Stable:Aseptic processing enables ambient distribution economics across Southeast Asian convenience networks.
Volume placements concentrate in Traditional formulations; the faster expansion belongs to Organic certification tiers.
End User:
Application requirements split sharply between at-home consumption and professional foodservice specifications.
- Cafés:Barista-formulated variants with enhanced foam stability and neutral flavor profiles dominate specialty coffee programs in the United States and Western Europe. Quarterly supplier rotations based on sustainability credentials are shortening switching cycles in Pacific Northwest and Ontario markets.
- Households:Direct-consumption and culinary applications drive replenishment velocity in German and United Kingdom supermarkets. Tetra Pak formats with extended shelf life are displacing refrigerated alternatives in pantry-stockpiling behavior.
- Restaurants:Foodservice bulk formats require consistent emulsion stability under holding conditions.
- Food Manufacturers:Ingredient-grade supply contracts for dairy-alternative product lines specify precise fat content and microbial thresholds.
Café procurement is climbing the fastest as coffee-chain plant-based programs normalize coconut milk defaults.
Packaging Type:
Format selection trades off distribution economics against sustainability credentials and consumption occasion.
- Tetra Paks:Aseptic carton systems deliver ambient shelf life without refrigeration, unlocking rural penetration in Thailand, Indonesia, and the Philippines while satisfying EU Green Deal packaging mandates. German and United Kingdom retailers prefer this format for extended inventory turns.
- Cans:Metal packaging retains entrenched position in Hispanic retail corridors across the United States through Goya Foods' distribution legacy. Thermal processing ensures phase stability in high-temperature supply chains.
- Bottles:Refrigerated PET and glass formats dominate premium positioning in health stores.
- Pouches:Flexible packaging gains traction in single-serve convenience applications.
Can volumes retain legacy placement; Tetra Pak configurations are gaining share fastest on sustainability and distribution economics.
Distribution Channel:
Channel strategy must reconcile certification requirements with format economics and geographic concentration.
- Supermarkets:Mass-market shelf presence demands competitive unit economics and dominant facing allocations. Vita Coco's North American position rests on securing refrigerated and ambient space in top-tier United States chains.
- Health Stores:Stricter sourcing standards and organic certification requirements command premium pricing in specialty retail. EFSA novel food timelines for fortified formulations create regulatory friction distinct from mainstream channels.
- Online Retailers:Direct-to-consumer subscription models concentrate in United States urban markets.
- Specialty Shops:Curated assortment and staff recommendation drive discovery in United Kingdom independent retail.
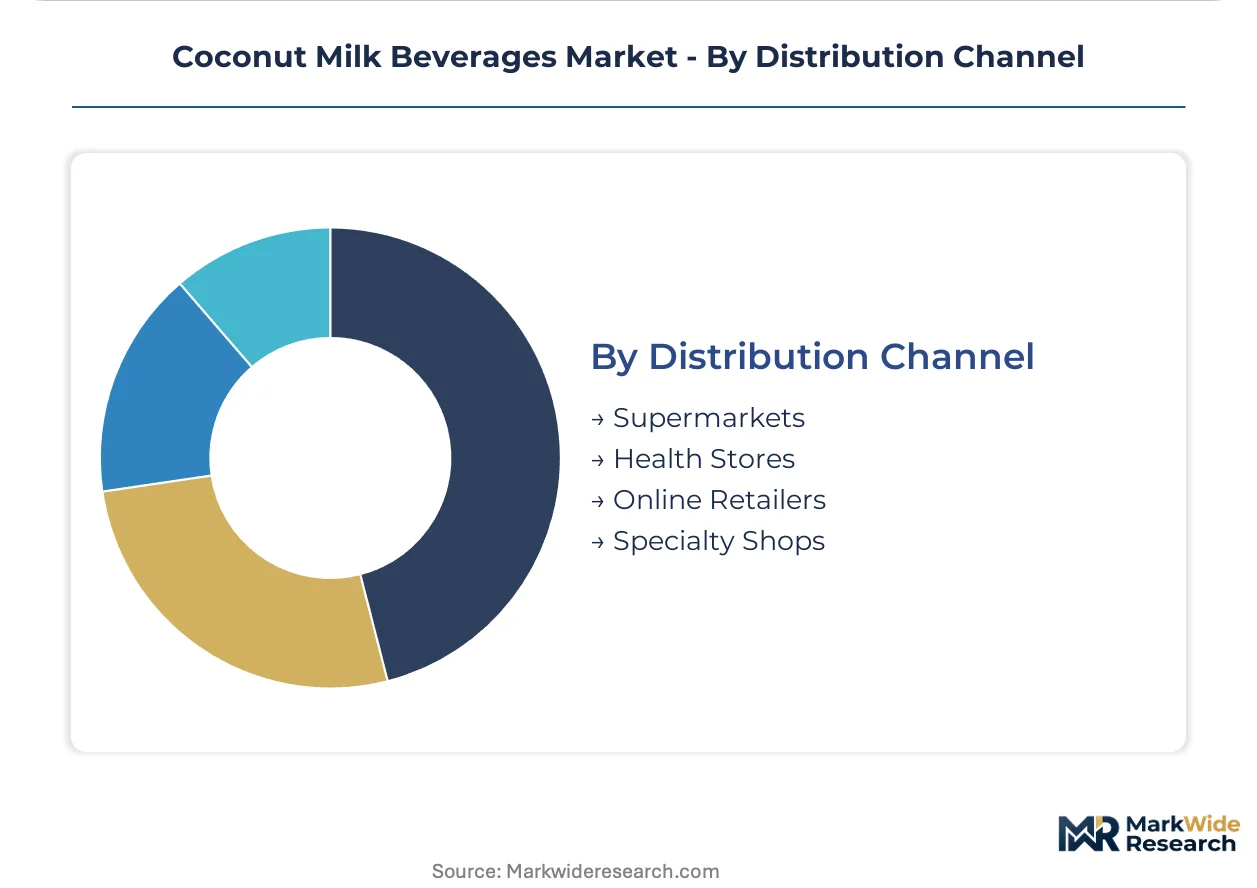
Supermarket placements hold volume concentration; Health Stores show the steepest expansion trajectory on certification premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangkok anchors procurement gravity for coconut kernel supply, with integrated plantation operations in Thailand's central plains feeding processing corridors that stretch from Samut Sakhon to Chonburi.
United States
Specialty coffee chains in Seattle and Portland normalize coconut milk defaults for espresso-based beverages. FDA labeling requirements for plant-based milk alternatives restrict nutrient claims and mandate comparison disclosures against dairy. Pacific Northwest barista preference data drives quarterly supplier rotations in Oregon and Washington state markets.
Germany
Retail channels in Berlin and Hamburg enforce EU Green Deal sustainable packaging mandates that rewrite procurement specifications. EFSA novel food status determinations delay fortified product launches by months. The Rhine-Ruhr industrial corridor hosts containerized processing lines serving regional foodservice accounts with compressed lead times.
United Kingdom
London-based specialty shops and supermarket chains accelerate organic certification requirements that command premium pricing. Health Canada and PMRA import pathways influence which suppliers achieve North American approval, creating spillover qualification standards. The Midlands distribution hub concentrates Tetra Pak ambient format penetration for extended shelf-life economics.
Canada
Toronto and Vancouver cafés disaggregate milk procurement from equipment contracts, enabling rapid vendor turnover based on sustainability credentials. Health Canada and PMRA oversight of pesticide residues on imported coconut materials filters supplier eligibility. Ontario's foodservice bulk channels remain underpenetrated relative to United States volume benchmarks.
Thailand
Samut Sakhon processing clusters leverage integrated plantation operations to secure raw material consistency against climate volatility. The country's central plains concentrate kernel supply for emulsion stabilization at 15-25% fat content. Chonburi's port infrastructure handles export volumes destined for German and United Kingdom retail channels under EU Green Deal carbon intensity scrutiny.
Coconut Milk Beverages Market Competitive Landscape
The competitive structure tilts toward plantation-integrated processors with captive raw material supply. Tiered differentiation separates organic-certified specialists from commodity-scale canners. Three archetypes dominate: integrated Thai plantation operators, North American brand marketers with refrigerated distribution dominance, and Hispanic-channel legacy distributors. Capacity consolidation and sustainability certification racing constitute the primary competitive moves.
Among Southeast Asian plantation-integrated processors, Thai Coconut Public Company Limited exemplifies captive supply chain control, while Axelum Resources Corp. occupies a position within Filipino sourcing corridors. On the brand-marketing tier, Vita Coco anchors North American health store and supermarket shelf presence. These three represent divergent strategic positions: upstream integration versus downstream brand equity versus entrenched ethnic retail distribution.
| Leading Market Players |
|---|
| Theppadungporn Coconut Co., Ltd. |
| Thai Coconut Public Company Limited |
| Goya Foods |
| Vita Coco |
| McCormick & Company |
| Danone |
| Sambu Group |
| Axelum Resources Corp. |
| Betrimex |
| Others |
Pricing and Supply Chain Analysis
Organic certification ladder divergence separates premium health-store positioning from commodity pantry staples, compressing procurement specifications toward traceable supply chains while forcing traditional processors to absorb carbon intensity documentation costs without price recovery mechanisms. EU Green Deal mandates rewrite buyer qualification criteria across German and United Kingdom retail channels, embedding compliance overhead into landed costs that Thai plantation-integrated operators pass through more efficiently than dependent importers.
Pricing Analysis
Value-based pricing anchors on foam stability performance and barista preference scores in United States specialty coffee channels. Three-tier pricing structure across premium organic, standard barista-grade, and economy traditional levels stratifies by certification grade and volume scale. Cost compression in commodity tiers is intensifying because oat milk substitution captures coffee-chain shelf space through superior technical performance. Household replenishment buyers in Germany demonstrate highest price sensitivity; health-store operators in North America accept premium capture for organic provenance.
Supply Chain Analysis
Direct-to-foodservice channels handle hyperscale café demand through containerized processing lines in Germany and the United Kingdom, compressing lead times for regional accounts. Raw material supply concentrates in Thailand, Indonesia, and the Philippines, with kernel processing feeding emulsion stabilization at 15-25% fat content. Coconut kernel availability, aseptic packaging materials, and ocean freight capacity constitute critical input dependencies. Single-source vulnerability from climate volatility in Southeast Asian sourcing corridors threatens consistent supply. Distribution runs through Tetra Pak ambient networks for extended shelf-life economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU Green Deal carbon intensity metrics and EFSA novel food timelines erect barrier-to-entry moats favoring plantation-integrated incumbents with captive documentation systems.
For Market Incumbents: Anticipate oat milk substitution pressure by securing exclusive barista-formulation partnerships with Pacific Northwest coffee chains. Deepen backward integration into Thai central plains plantation operations to insulate raw material consistency against climate volatility. Prioritize organic certification racing to capture health-store margin pools before EFSA timelines delay fortified product competition. For New Entrants and Emerging Players: Mid-tier price-point gaps between premium organic and economy traditional formulations offer white-space entry in Canadian retail channels where Health Canada import pathways remain underexploited. Target Ontario foodservice bulk segments with Tetra Pak ambient formats. Pursue private-label supply contracts with German supermarket chains seeking EU Green Deal compliant sourcing without brand premium overhead. For Investors and Strategic Acquirers: Re-rating potential sits with plantation-integrated processors given EU Green Deal procurement pressure concentrating buyer preference toward traceable supply chains. Long-term viability favors upstream-controlled operators with captive kernel supply and carbon documentation infrastructure. Monitor EFSA novel food approval velocity as inflection indicator for fortified product pipeline value realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Operations | Thai Coconut Public Company Limited's captive supply model secures raw material consistency against climate volatility. |
| Organic Certification Expansion | Health stores in North America enforce stricter sourcing standards that command disproportionate margin pools. |
| Containerized Processing Deployment | German and United Kingdom regional foodservice accounts gain compressed lead times without centralized infrastructure. |
| Barista-Formulation Partnerships | Pacific Northwest coffee chains normalize quarterly supplier rotations based on foam stability performance data. |
| Tetra Pak Format Conversion | EU Green Deal packaging mandates accelerate ambient distribution economics across German retail channels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with coconut plantation operations managers, foodservice procurement directors at specialty coffee chains, Tetra Pak technical sales engineers, and health-store category buyers. Secondary sources included FDA labeling guidance documents, EFSA novel food status determinations, Health Canada PMRA residue monitoring reports, EU Green Deal technical specifications, and Thai Board of Trade export statistics. Bottom-up volume modeling triangulated against top-down value projections.
Granularity-level framing applied country-specific demand curves for Thailand, Indonesia, Germany, United Kingdom, United States, and Canada alongside product-type segmentation across traditional, organic, and barista-grade formulations. End-user splits modeled café, household, restaurant, and food manufacturer channels separately. CAGRs derived from regression analysis of historical trade flows and forward projection of coffee-chain plant-based program expansion rates. Packaging format economics and carbon intensity documentation compliance costs fed scenario-weighted outputs across the analysis window.
Inputs from Thai customs authorities and EU regulatory databases were available through the study window; gaps in real-time barista preference survey data introduce uncertainty bands around coffee-chain adoption velocity assumptions. Forecasts embed assumptions regarding EFSA novel food timeline resolution and Health Canada import pathway standardization. Practitioners should monitor oat milk foam stability patent filings and EU carbon border adjustment mechanism implementation dates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Drinking Bottled Mineral Water Market
Beverages
Asia Pacific Dairy Based Beverages Market
Beverages
Detox Drinks Market
Beverages
Sports and Energy Drinks Market
Beverages
CBD-Infused Beverages Market
Beverages
Asia-Pacific Energy Drink Market
Beverages
Carbonated Soft Drinks Market
Beverages
Kvass Market
Beverages
Fruit Juice Market
Beverages
Europe Probiotic Drinks Market
Beverages
Coconut Water Market
Beverages
United Kingdom Energy Drink Market
Beverages
US and Canada Tonic Water Market
Beverages
United States Beverage Contract Bottling and Filling Market
Beverages
Canned Beverages Market
Beverages
North America Energy Drink Market