
 Cactus Water Market | 2026-2036
Cactus Water Market Size, Share, and Industry Trends Forecast 2026-2036
Cactus Water Market Analysis
Mexican nopal cactus farming cooperatives is restructuring supply chains to meet North American beverage-grade demand. True Nopal Ventures LLC leverages direct agricultural partnerships in Sonora to secure raw material consistency. Caliwater LLC sustains its position through flavored product innovation targeting wellness retailers. Pricklee LLC anchors distribution through health store channels in urban California markets.
Cactus water is an aqueous extract derived from Opuntia ficus-indica cladodes, containing electrolytes, betalains, and taurine at approximately 5–10 Brix soluble solids, primarily commercialized as a low-calorie functional hydration alternative to coconut water. Pure Cactus Water dominates volume as the base ingredient for beverage company formulations, while Flavored Cactus Water captures premium shelf positioning in health stores and online retail. Organic Cactus Water carries certification-dependent margin premiums that Tetra Pak packaging preserves through extended ambient shelf stability.
FDA beverage identity standards and USDA National Organic Program rules govern label claims and agricultural input traceability for cactus water sold in the United States. The country's national food safety regulator enforces Good Manufacturing Practices that constrain small-batch producers seeking retail expansion. Stakeholders must monitor evolving plant-based beverage classification precedents that could reshape competitive access to mass-market distribution.
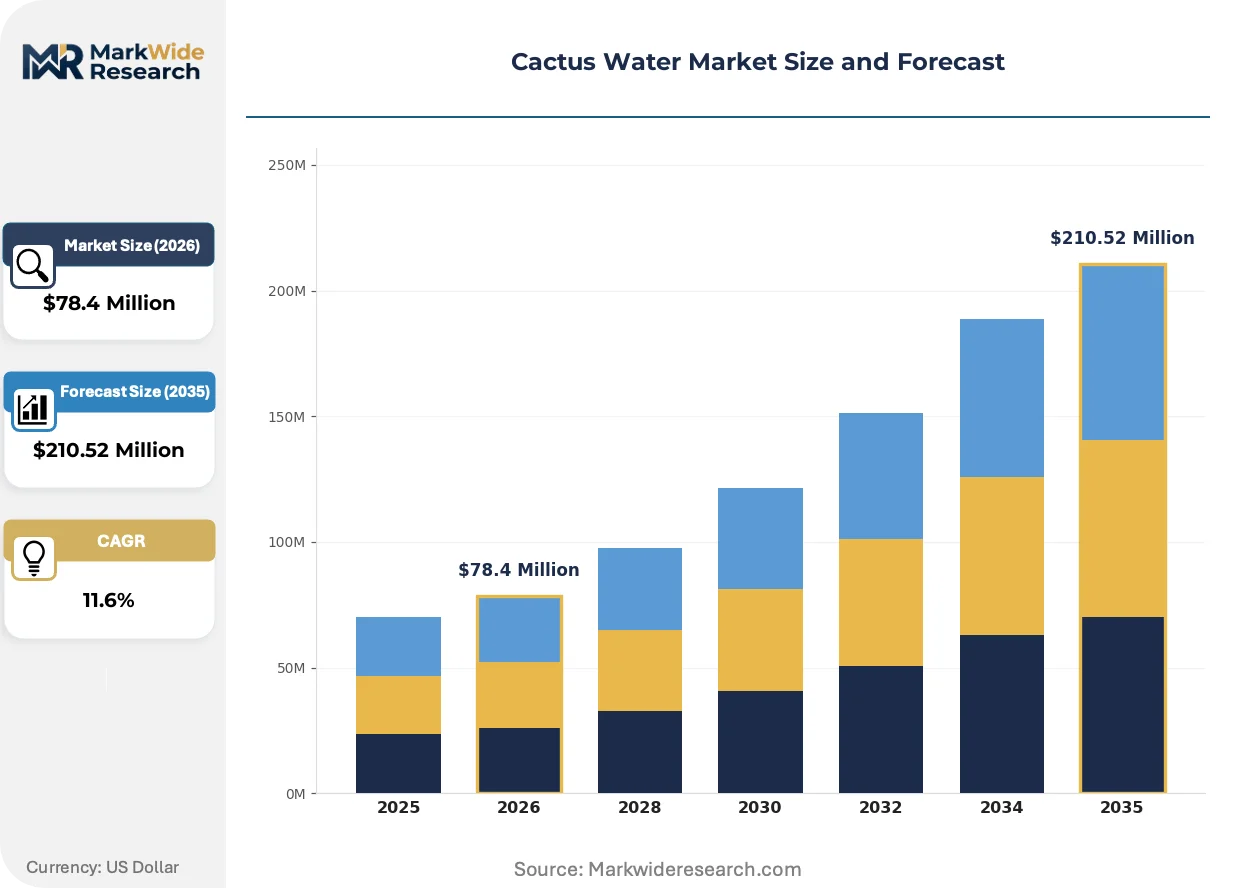
Market Dynamics
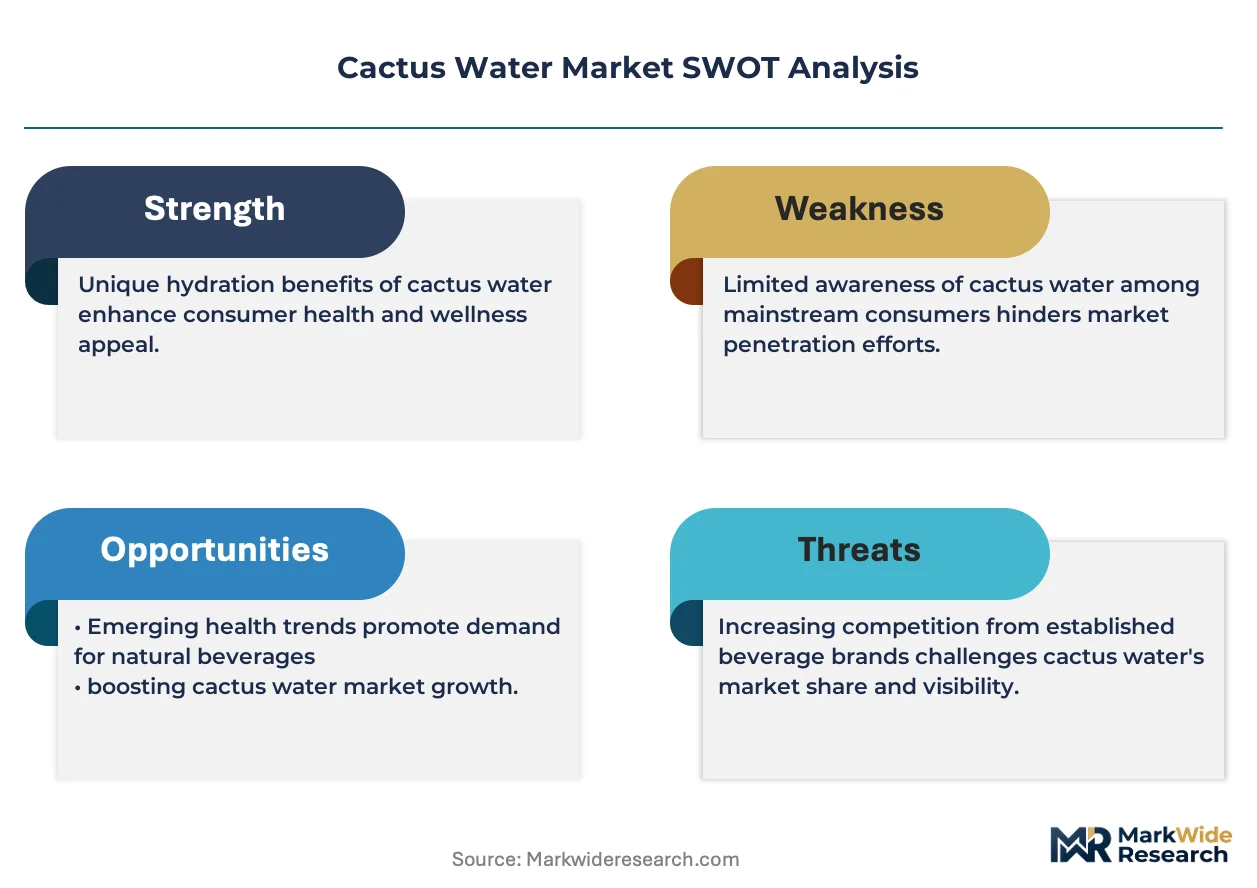
Beverage-grade nopal supply chains are consolidating around Sonora-Mexico agricultural clusters as FDA beverage identity standards tighten traceability requirements for plant-based hydration inputs. This structural pressure is forcing procurement restructuring across North American formulation partners.
Growth Catalysts
- USDA National Organic Program certification:Premium shelf positioning in California health retailers now requires documented agricultural input traceability, accelerating cooperative investment in certified farming operations.
- Sports nutrition end-use demand:Electrolyte and taurine content in Opuntia ficus-indica extracts is driving beverage company R&D budgets toward cactus-derived functional hydration formulations.
- Sonora supply cluster maturation:Direct agricultural partnerships are reducing raw material variability for North American processors seeking consistent cladode quality.
Market Restraints
- Cladode harvest seasonality:Opuntia ficus-indica soluble solids concentration fluctuates 5–10 Brix across growing cycles, creating formulation standardization costs for batch processors.
- Single-origin supply risk:Mexican nopal cooperative concentration exposes procurement to regional drought and climate volatility without diversified sourcing alternatives.
- Coconut water substitution threat:Established electrolyte beverage infrastructure and consumer familiarity constrain cactus water shelf space expansion in conventional retail.
Strategic Opportunities
- Tetra Pak ambient packaging convergence:Aseptic carton technology is extending organic-certified product shelf stability without refrigeration infrastructure, opening convenience store distribution.
- Wellness retailer channel expansion:Urban California health store networks are creating dedicated functional beverage sections that favor novel plant-based hydration storytelling.
- Flavored variant white space:Botanical and citrus infusion development is capturing premium positioning beyond pure extract commoditization.
Industry Challenges
- Beverage-grade processing capex requirements:FDA Good Manufacturing Practice compliance for retail expansion demands filtration and pasteurization equipment investments that strain small-batch producers.
- Organic certification timeline compression:USDA three-year transition requirements for conventional nopal farms are constraining rapid supply scale-up to meet beverage company procurement timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cactus Water Market |
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $210.52 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Cactus Water, Flavored Cactus Water, Organic Cactus Water, Sparkling Cactus Water Distribution Channel: Supermarkets, Health Stores, Online Retail, Convenience Stores End User: Fitness Enthusiasts, Health Conscious Consumers, Beverage Companies, Restaurants Packaging Type: Bottles, Cans, Tetra Pak, Pouches |
| Companies Covered | True Nopal Ventures LLC, Caliwater LLC, Pricklee LLC, The Cactus Water Co. LLC, Evissi USA LLC, The Lauro Company LLC, Steaz, Green-Go, BetterDays, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cactus Water Market Emerging Trajectories
Functional beverage formulation is pivoting toward modular ingredient systems that let brands customize electrolyte and antioxidant profiles without reformulating base stocks. This shift is compressing product development cycles across plant-based hydration.
Microfiltration and reverse osmosis concentration technology is modularizing cactus water processing into portable, skid-mounted units that Sonora cooperatives can deploy at harvest sites. Beverage companies are adopting these distributed systems to reduce raw material transport costs and preserve betalain stability. The technology is modularizing supply chain architecture by enabling just-in-time extraction rather than centralized processing.
USDA organic certification requirements are tightening documentation standards for agricultural input provenance, forcing nopal suppliers to implement digital traceability systems. Small-scale Sonora farming cooperatives are responding by consolidating into certified producer groups that share compliance infrastructure. California wellness retailers are now requiring batch-level organic verification before granting premium shelf placement.
Health-conscious consumers are rotating toward low-calorie functional hydration with transparent ingredient labeling, displacing sugar-forward sports drinks in fitness-oriented purchase occasions. Urban California gym and studio channels are capturing this shift through refrigerated grab-and-go placement. Direct-to-subscription models are consolidating repeat purchases among premium-seeking households in Los Angeles and San Francisco metro clusters.
Cactus Water Market Segmentation
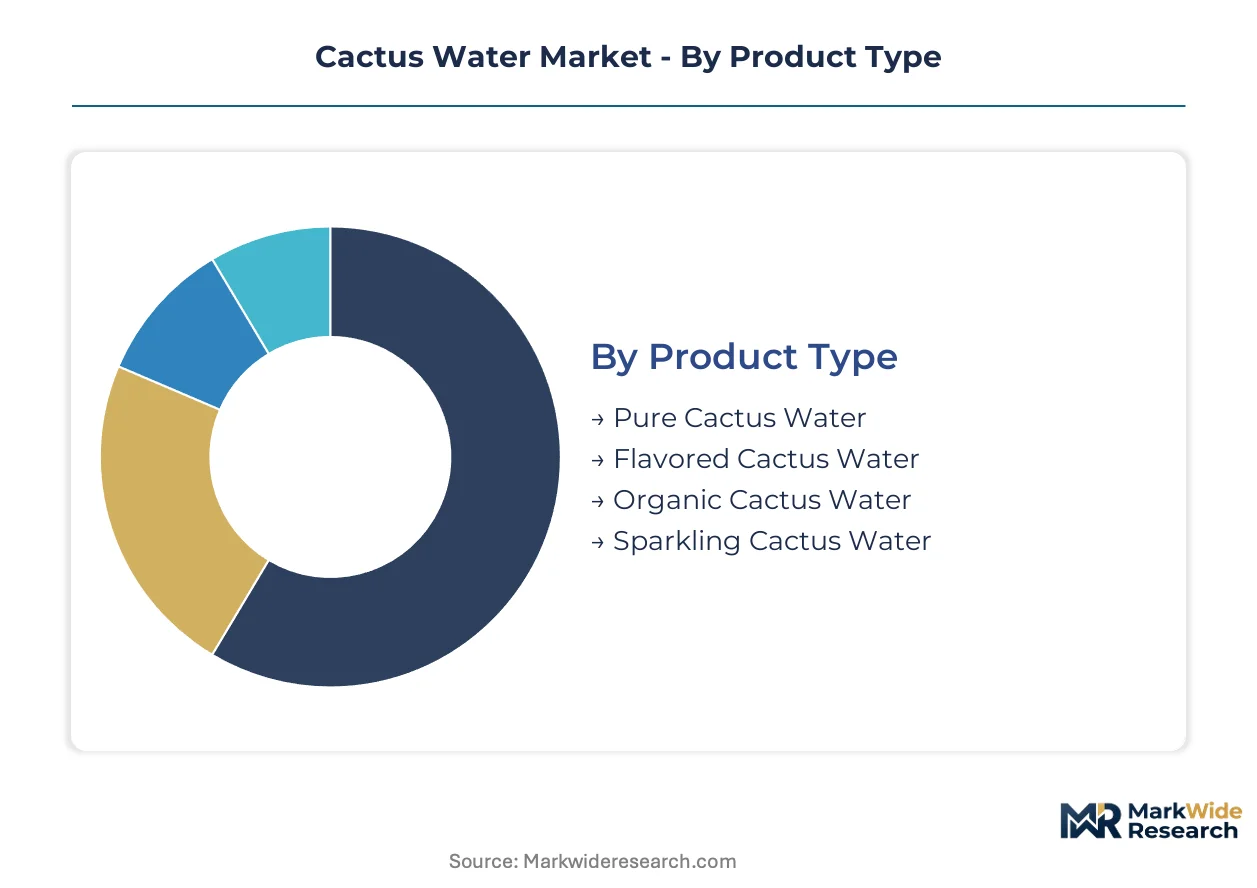
Cactus water segmentation reveals a bifurcation between commodity-grade inputs for beverage manufacturers and premium-positioned SKUs targeting California wellness retailers. Understanding these tiered demand pools clarifies where formulation investments and certification spending generate returns.
Product Type:
Pure extract dominates volume throughput while flavored and organic variants capture margin premiums.
- Pure Cactus Water:Aqueous extract from Opuntia ficus-indica cladodes at 5–10 Brix soluble solids serves as the base stock for beverage company formulations. Demand concentrates among North American sports drink manufacturers seeking electrolyte and taurine content for functional hydration lines.
- Organic Cactus Water:USDA National Organic Program certification commands shelf placement premiums in California health retailers. Three-year farm transition timelines constrain supply scale-up as documented agricultural input traceability becomes mandatory for premium positioning.
- Flavored Cactus Water:Botanical and citrus infusions target wellness retailers with novel plant-based hydration storytelling beyond pure extract commoditization.
- Sparkling Cactus Water:Carbonated variants compete in the low-calorie refreshment occasion against established sparkling water brands.
Today's leader: Pure Cactus Water. Tomorrow's challenger: Organic Cactus Water.
Distribution Channel:
Channel selection determines refrigeration requirements and certification documentation intensity.
- Health Stores:Urban California networks create dedicated functional beverage sections favoring novel plant-based hydration with transparent ingredient labeling and batch-level organic verification.
- Supermarkets:Conventional retail placement remains constrained by coconut water substitution threat and established electrolyte beverage infrastructure.
- Online Retail:Direct-to-subscription models consolidate repeat purchases among premium-seeking households in Los Angeles and San Francisco metro clusters.
- Convenience Stores:Tetra Pak ambient packaging opens this channel by extending shelf stability without refrigeration infrastructure.
Health Stores anchor premium positioning. Convenience Stores represent the steepest expansion trajectory for mass-market penetration.
End User:
User type dictates formulation complexity and procurement scale.
- Beverage Companies:Bulk procurement of pure extract for sports and wellness drink R&D budgets drives the largest volume transactions.
- Health Conscious Consumers:Individual purchasers rotating toward low-calorie functional hydration displace sugar-forward sports drinks in fitness-oriented purchase occasions.
- Fitness Enthusiasts:Gym and studio channel grab-and-go placement captures this segment through refrigerated positioning.
- Restaurants:Foodservice adoption remains nascent as mixology and premium non-alcoholic beverage programs experiment with cactus-derived ingredients.
Beverage Companies dominate procurement volume. Health Conscious Consumers are gaining share fastest as direct-to-consumer channels mature.
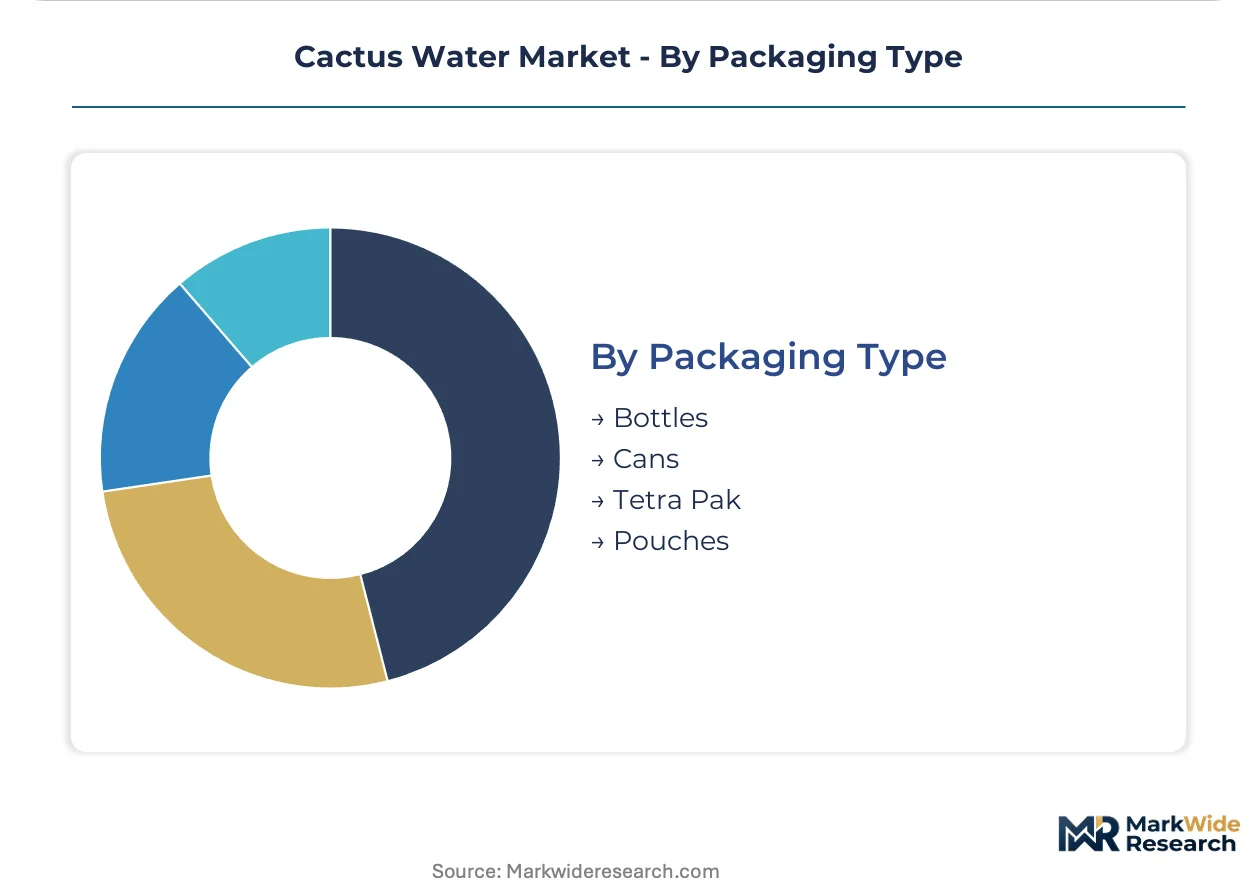
Packaging Type:
Packaging technology determines shelf stability economics and retail channel access.
- Tetra Pak:Aseptic carton technology preserves organic-certified product stability without refrigeration, enabling convenience store and mass retail distribution expansion.
- Bottles:PET and glass formats dominate health store refrigerated sections with transparent ingredient labeling visibility.
- Cans:Aluminum formats target fitness and outdoor consumption occasions with portability advantages.
- Pouches:Flexible packaging offers lightweight shipping economics for online retail fulfillment.
Tetra Pak unlocks ambient channel access. Bottles defend refrigerated premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is concentrating beverage-grade nopal processing in Mexican agricultural clusters where USDA organic transition costs undercut US domestic cultivation. FDA traceability requirements for plant-based hydration inputs are pushing North American brands toward Sonora-based supply partnerships rather than domestic farm development.
United States
California health retailers and Los Angeles fitness studios drive premium positioning for organic-certified cactus water. FDA beverage identity standards and USDA National Organic Program rules govern label claims and agricultural input traceability. Urban California wellness networks in San Francisco and Los Angeles metro areas now require batch-level organic verification before granting shelf placement.
Mexico
Sonora agricultural cooperatives supply the majority of North American beverage-grade nopal as direct partnerships reduce raw material variability. The country's national food safety regulator enforces Good Manufacturing Practices that constrain small-batch producers. Sonora-Mexico clusters are consolidating around microfiltration-equipped processing sites to meet FDA traceability timelines.
Canada
Health Canada and PMRA regulations govern natural health product classifications for cactus-derived beverages entering the functional hydration category. Toronto and Vancouver health store channels are replicating California's premium positioning for organic plant-based hydration. British Columbia wellness retailers are piloting direct-to-subscription models for certified organic imports.
Germany
EMA and EFSA standards for novel food ingredients shape import requirements for Opuntia ficus-indica extracts in functional beverages. Berlin and Munich organic retailers are testing cactus water SKUs within established plant-based hydration sections. Bavarian distribution networks are evaluating Tetra Pak ambient formats for convenience channel expansion.
Australia
TGA regulations for complementary medicines influence how cactus water positions within sports nutrition and wellness categories. Sydney and Melbourne fitness culture is creating refrigerated grab-and-go placement opportunities for electrolyte-forward formulations. New South Wales health store networks are requiring transparent ingredient labeling matching California benchmarks.
Cactus Water Market Vendor Landscape
Mexican agricultural producers anchor the raw material tier; California-based beverage specialists hold formulation and brand equity positions. The vendor structure bifurcates between Sonora farming cooperatives supplying certified organic cladodes and US entities managing finished-product distribution. Three archetypes dominate: vertically integrated agricultural partnerships, flavor innovation houses, and health channel distributors. Competitive moves center on direct farm partnerships for supply security and Tetra Pak packaging adoption for ambient channel access.
Within the agricultural partnership archetype, True Nopal Ventures LLC represents direct Sonora sourcing integration. Caliwater LLC and Pricklee LLC exemplify the flavor innovation and health channel distribution vectors respectively. These three entities collectively illustrate how geographic specialization—Mexican raw material security, California brand development, and urban retail anchoring—shapes competitive positioning without requiring operational overlap.
| Leading Market Players |
|---|
| True Nopal Ventures LLC |
| Caliwater LLC |
| Pricklee LLC |
| The Cactus Water Co. LLC |
| Evissi USA LLC |
| The Lauro Company LLC |
| Steaz |
| Green-Go |
| BetterDays |
| Others |
Supply Flow & Price Mechanics
Beverage company procurement teams concentrate buying power around Sonora-Mexico agricultural clusters, anchoring contract-based long-term offtake as the dominant pricing model for pure extract base stocks. This buyer concentration compresses margins for small-batch processors while rewarding certified organic suppliers with shelf placement premiums in California health retailers.
Pricing Analysis
Distributor margin layers in California wellness retail absorb 35-45 points before organic-certified products reach health store shelves. Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified organic SKUs from conventional extracts and commodity-grade inputs for beverage formulations. Cost compression in pure extract tiers is intensifying because Sonora cooperative consolidation reduces bargaining leverage for small-batch processors. Beverage companies exhibit highest price sensitivity due to volume procurement scale, while direct-to-consumer subscription households show lowest sensitivity to per-unit premiums.
Supply Chain Analysis
USDA National Organic Program certification gates access to premium California retail channels, forcing Sonora farming cooperatives into three-year transition timelines and digital traceability investments. Geographic supply concentration centers on Mexico, with secondary processing nodes in California and emerging distribution hubs in Canada and Australia. Raw material dependencies rest on Opuntia ficus-indica cladode harvest cycles, microfiltration equipment, and Tetra Pak aseptic packaging inputs. Single-origin vulnerability to Sonora drought conditions threatens supply continuity without diversified sourcing alternatives. Distribution runs through direct agricultural partnerships for beverage company bulk procurement, health store networks for premium SKUs, and convenience store channels for ambient-stable formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in cactus water hinges on Tetra Pak packaging cost curves flattening and organic certification premiums widening as California retailers tighten batch-level verification requirements.
For Market Incumbents: Cement supply security through captive partnerships with Sonora cooperatives completing USDA organic transition, locking in multi-year offtake before three-year certification timelines constrain competitor access. Defend shelf position by accelerating flavored variant R&D to capture botanical infusion white space ahead of coconut water brand extensions. Threat: Established electrolyte beverage infrastructure constrains conventional retail expansion. Lever: Certification investment in digital traceability systems meets California retailer verification mandates. For New Entrants and Emerging Players: Direct-to-subscription channels offer the lowest customer acquisition cost entry vector for Los Angeles and San Francisco metro households seeking repeat purchase convenience. Target sparkling cactus water as the most penetrable white space, competing against seltzer incumbents with electrolyte-forward positioning. White space: Convenience store distribution remains underdeveloped for ambient-stable organic formats. Go-to-market: Partner with existing Sonora processors for white-label supply rather than building captive agricultural infrastructure. For Investors and Strategic Acquirers: Beverage conglomerates seeking functional hydration portfolio expansion represent the most active acquirer category in this space. Long-term viability frames around 5-10 year organic-certified supply scarcity as three-year farm transition timelines lag demand growth. Target acquisition archetype: Sonora-based cooperatives with completed USDA certification and installed microfiltration capacity. Signal to watch: California health retailer consolidation into fewer buying desks that demand batch-level traceability.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Agricultural Partnership | Secures Sonora nopal supply consistency for FDA traceability compliance. |
| USDA Organic Certification Investment | Unlocks California health retailer shelf placement premiums. |
| Tetra Pak Packaging Adoption | Enables convenience store distribution without refrigeration infrastructure. |
| Flavored Variant Development | Captures botanical infusion white space beyond pure extract commoditization. |
| Digital Traceability Implementation | Meets batch-level organic verification requirements from urban wellness retailers. |
Methodological Framework
Coverage spans the United States, Mexico, Canada, Germany, and Australia, with primary inputs from each regional cluster combining executive interviews with beverage company procurement directors, Sonora cooperative agricultural managers, California health store category buyers, and Tetra Pak packaging specialists. Secondary validation draws from FDA beverage identity standards filings, USDA National Organic Program certification databases, customs trade records for nopal extract shipments, and retail audit data from urban California wellness channels. Bottom-up volume triangulation across product type, distribution channel, and end user segments reconciles with top-down market sizing.
Granularity-level modeling captures pure extract, organic-certified, flavored, and sparkling product types at the SKU level, with distribution channel dynamics modeled separately for health stores, supermarkets, online retail, and convenience stores. End user segmentation distinguishes beverage company bulk procurement from health-conscious consumer and fitness enthusiast purchase occasions. CAGRs derive from segment-level volume build-ups applied against pricing trajectories across the analysis window. Forecast inputs incorporate Sonora harvest yield variability, USDA certification pipeline timelines, and Tetra Pak packaging cost curves.
The model assumes sustained Tetra Pak ambient packaging adoption; alternative pathways for cold-chain-dependent distribution would alter channel expansion outlooks. Forecasts reflect assumptions about California retailer organic verification requirements remaining stable, Sonora cooperative consolidation continuing, and coconut water substitution pressure persisting in conventional retail. A model refresh is warranted upon material change in FDA plant-based beverage classification precedents or USDA organic transition timeline adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Breakfast Drink Market
Beverages
United States Soy Beverages Market
Beverages
Africa Dairy Based Beverages Market
Beverages
Solid Beverages Market
Beverages
South America Energy Drink Market
Beverages
Germany Probiotic Drinks Market
Beverages
Caffeinated Beverage Market
Beverages
Water Bottle Market
Beverages
Asia-Pacific Juices Market
Beverages
South America Dairy Based Beverages Market
Beverages
Beverage Cooler Market
Beverages
Rose Floral Water Market
Beverages
Hot Chocolate Market
Beverages
Fruit Juice Market
Beverages
Cold Pressed Juice Market
Beverages
Reconstituted Juice Market