
 Bottled Deep Ocean Water Market | 2026-2036
Bottled Deep Ocean Water Market Size, Share, and Industry Trends Forecast 2026-2036
Bottled Deep Ocean Water Market Analysis
ISO 22000 certification is bifurcating the competitive landscape into qualified operators and speculative entrants. Hawaii Deep Blue leverages its Pacific extraction rights to sustain premium positioning across North American wellness retail. Taiwan Yes Deep Ocean Water Co., Ltd. anchors regional supply through vertical control of pipeline infrastructure from the East China Sea. Kona Deep competes on mineral-profile differentiation rather than volume scale.
Bottled deep ocean water refers to water sourced from ocean depths exceeding 200 meters, characterized by distinct mineral compositions including elevated magnesium, potassium, and trace elements absent in surface water, and processed through cold sterilization or membrane filtration to preserve bioactive properties for functional hydration and therapeutic applications. The mineral water category dominates current revenue pools due to clinical credibility, while flavored water segments attract younger demographics through functional positioning. E-commerce channels capture the fastest expansion as direct-to-consumer subscriptions bypass traditional retail markups.
The US FDA governs bottled water standards under 21 CFR 165.110, while Japan's Ministry of Health, Labour and Welfare enforces mineral-content verification for therapeutic claims. Hawaii's state environmental regulators impose extraction permits that limit offtake volumes and protect marine ecosystems. Stakeholders must monitor evolving mineral-claim substantiation requirements across jurisdictions to preserve market access and premium pricing power.
Market Dynamics
ISO 22000 certification is bifurcating the competitive landscape into qualified operators and speculative entrants, while Japan's Ministry of Health, Labour and Welfare mineral-content rules filter out subscale producers. This structural tension between compliance capability and extraction access defines current market positioning.
Growth Catalysts
- Functional hydration positioning:Wellness retail channels in South Korea absorb rising volumes as magnesium and trace element claims gain clinical credibility among metropolitan consumers.
- Direct-to-consumer channel expansion:E-commerce subscriptions bypass traditional retail markups, capturing younger demographics through personalized mineral-profile matching.
- Cold sterilization technology maturation:Membrane filtration advances preserve bioactive properties without thermal degradation, enabling therapeutic-grade positioning in premium hospitality.
Market Restraints
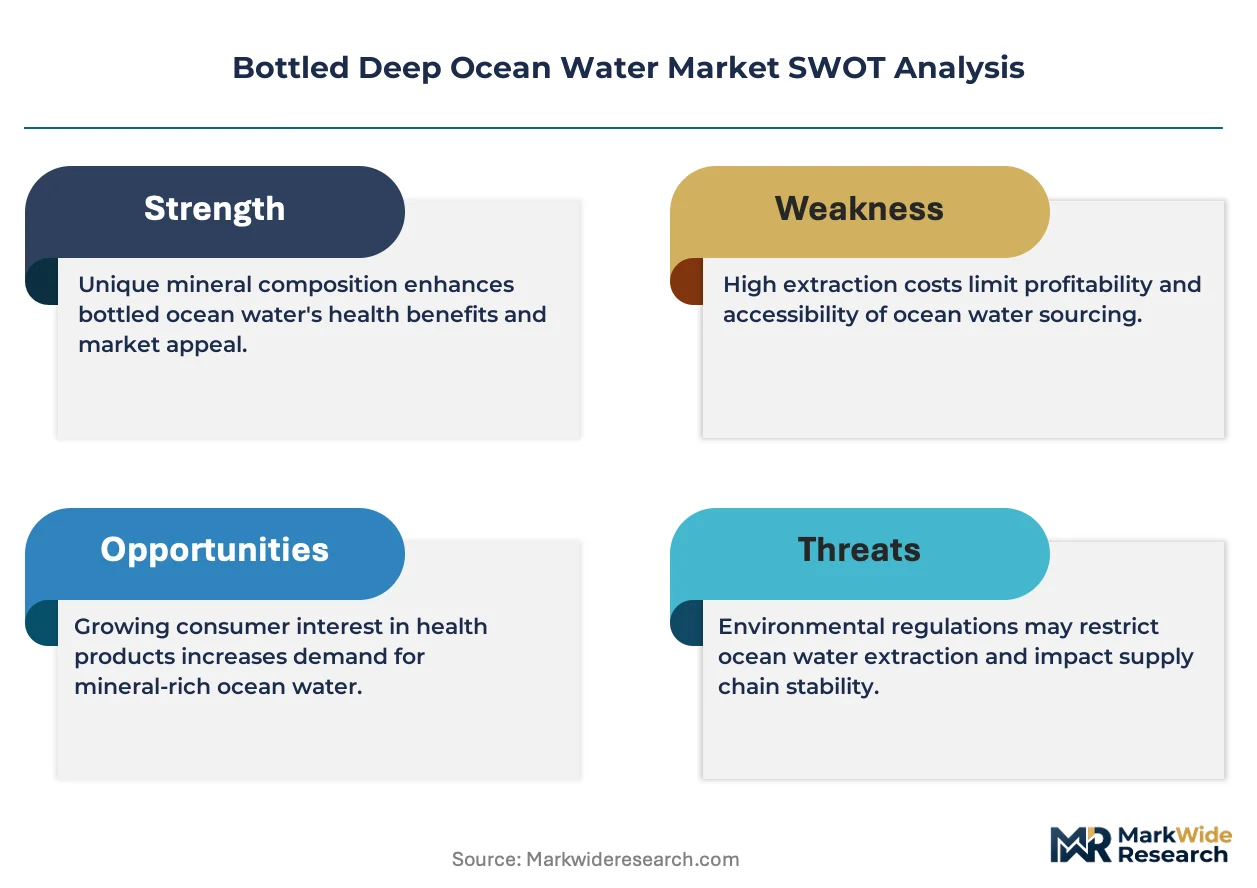
- Deep-water extraction infrastructure concentration:Viable offtake points cluster along East Asian metropolitan corridors with established pipeline networks, limiting new entrant geography.
- Hawaii state environmental permit scarcity:Regulatory caps on Pacific extraction volumes protect marine ecosystems while constraining North American supply expansion.
- Surface-sourced mineral water substitution:Lower-cost alternatives with comparable electrolyte profiles compete on price in standard hydration segments.
Strategic Opportunities
- Flavored functional water white space:Younger demographics in Taiwan and Japan respond to taste-forward formulations with retained mineral density.
- Therapeutic claim substantiation pathways:Japan's Ministry of Health, Labour and Welfare verification framework creates first-mover advantage for compliant operators in clinical channels.
- Subscription model penetration:North American wellness retail presents underdeveloped recurring-revenue potential versus East Asian market maturity.
Industry Challenges
- ISO 22000 certification timeline compression:The 12-18 month qualification window delays market entry for capitalized but unverified operators.
- Marine ecosystem impact assessment complexity:Hawaii state regulators demand extensive environmental review, extending permit acquisition cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottled Deep Ocean Water Market |
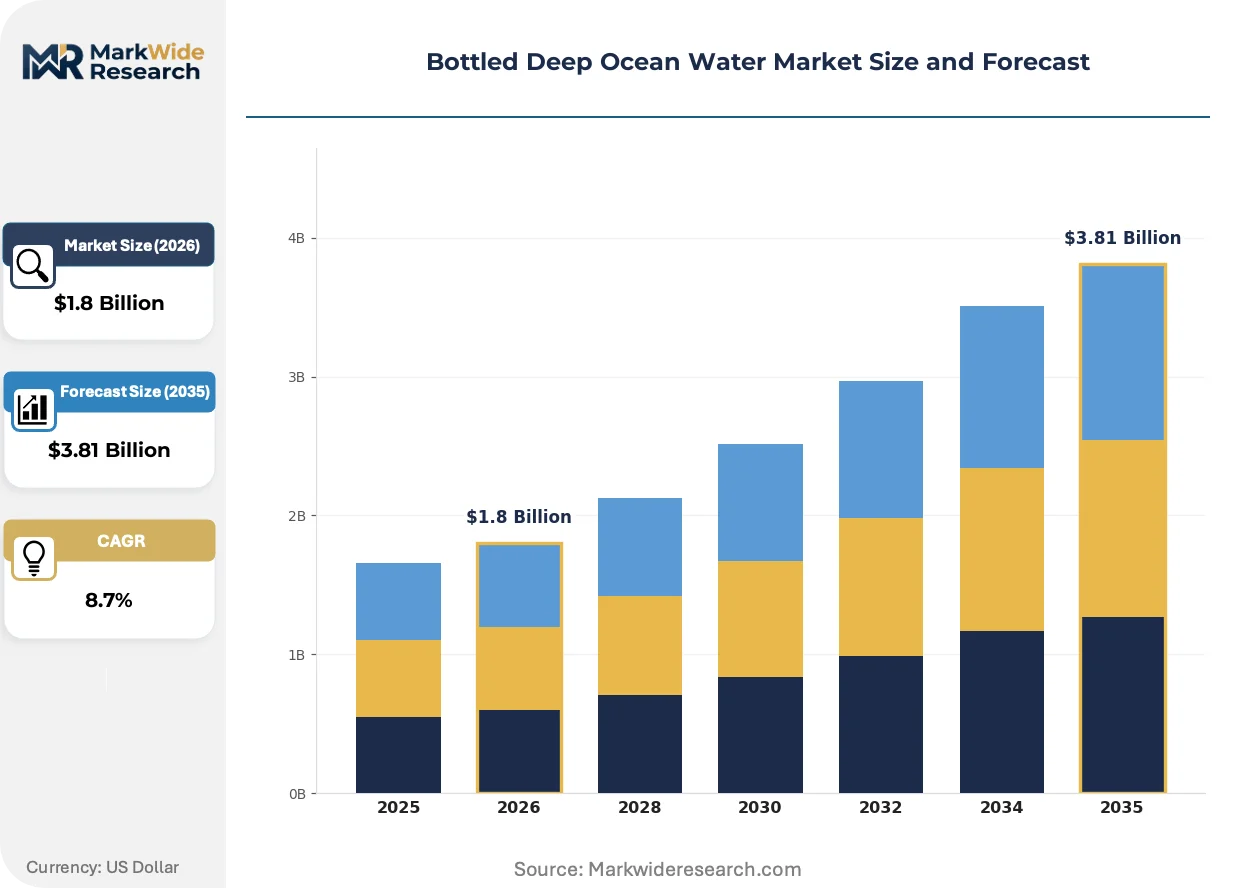
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spring Water, Mineral Water, Flavored Water, Distilled Water Distribution Channel: Retail Stores, E-commerce, Wholesalers, Food Service End User: Households, Restaurants, Hotels, Gyms Packaging Type: Plastic Bottles, Glass Bottles, Tetra Paks, Cans |
| Companies Covered | Hawaii Deep Blue, Taiwan Yes Deep Ocean Water Co., Ltd., Kona Deep, Blu Octopus, Jeju Deep Water, Deep Ocean Enterprises, Okinawa Deep Ocean Water Co., Ltd., Mariana DSW, PK-DSW, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottled Deep Ocean Water Market Emerging Trajectories
Cold sterilization membrane systems are reshaping production economics while regulatory mineral-verification frameworks tighten across East Asian markets. These forces are compressing the competitive set toward certified operators with proven extraction rights.
Membrane filtration with pore-size precision below 0.1 microns is bifurcating the producer base. Premium hospitality buyers in Seoul and Tokyo specify certified cold-sterilized output, while uncertified operators retreat to commodity positioning. This technology is compressing margins for thermal-treatment legacy systems.
Japan's Ministry of Health, Labour and Welfare enforces mineral-content verification for therapeutic claims, requiring third-party laboratory certification. The rule redirects marketing investment toward clinical substantiation rather than lifestyle branding. Functional hydration segments absorb compliance costs most readily.
Subscription direct-to-consumer models displace traditional retail distribution in North American wellness channels. Buyers bypass supermarket markups through automated replenishment tied to mineral-profile preferences. Hawaii-sourced brands leverage this channel most aggressively among extraction-rights holders.
Bottled Deep Ocean Water Market Segmentation
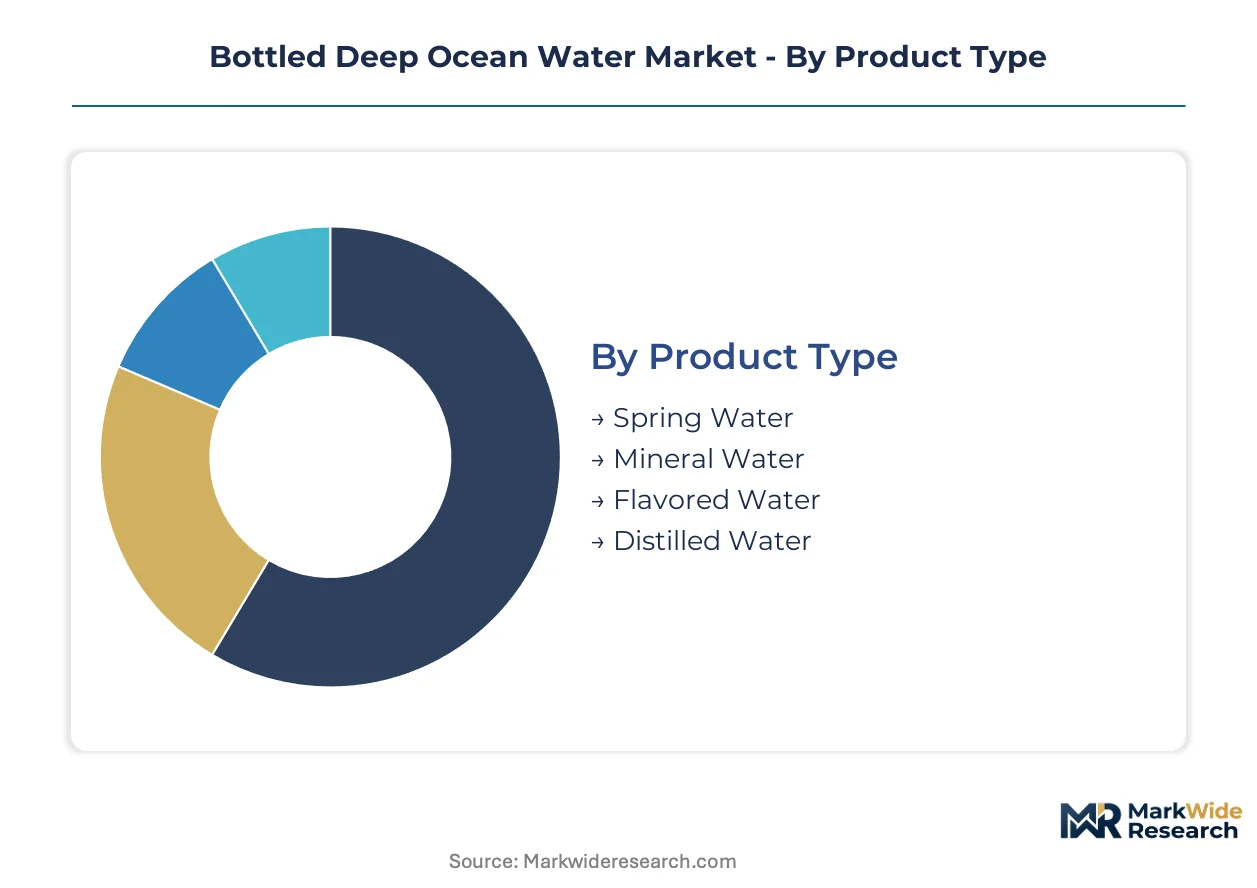
Segmentation in bottled deep ocean water reveals how mineral-profile certification and channel access determine margin capture. Each dimension reflects distinct regulatory thresholds and buyer willingness-to-pay for therapeutic-grade positioning.
Product Type:
Japan's Ministry of Health, Labour and Welfare enforces mineral-content verification that segments clinical credibility from lifestyle positioning.
- Mineral Water:Elevated magnesium and trace element profiles sourced below 200 meters depth command premium placement in Seoul and Tokyo wellness retail. Clinical substantiation requirements in Japan filter out uncertified competitors from therapeutic channels.
- Flavored Water:Taste-forward formulations with retained mineral density attract younger demographics in Taiwan through functional positioning without sacrificing bioactive claims. Direct-to-consumer subscriptions capture this segment fastest.
- Spring Water:Surface-sourced alternatives compete on price in standard hydration with comparable electrolyte profiles.
- Distilled Water:Thermal treatment strips bioactive properties, relegating this grade to commodity industrial applications.
Mineral Water handles the majority of throughput; Flavored Water is expanding most quickly on share.
Distribution Channel:
Channel economics bifurcate between markup-heavy traditional retail and subscription-driven recurring revenue models.
- E-commerce:Automated replenishment tied to mineral-profile preferences bypasses supermarket markups in North American wellness retail. Hawaii-sourced brands leverage this channel aggressively among extraction-rights holders.
- Retail Stores:Premium hospitality placement in Seoul and Tokyo requires ISO 22000 certification for shelf access, compressing margins for uncertified operators.
- Food Service:Restaurants absorb volume through white-label supply agreements with established pipeline operators.
- Wholesalers:Bulk distribution to institutional buyers concentrates in East Asian metropolitan corridors with established extraction infrastructure.
E-commerce climbs the fastest on volume contribution; Retail Stores still anchor absolute revenue.
End User:
Buyer sophistication varies sharply between clinical-grade institutional procurement and household functional hydration.
- Hotels:Premium hospitality channels in South Korea specify cold-sterilized membrane filtration output for guest wellness programs. Certification requirements redirect procurement toward qualified operators.
- Households:Metropolitan consumers in East Asian corridors respond to magnesium and trace element claims with subscription-based replenishment.
- Restaurants:Menu integration of deep ocean water as a premium beverage option concentrates in certified supply zones.
- Gyms:Functional hydration positioning targets post-workout electrolyte recovery with mineral-profile matching.
Hotels command the highest unit economics; Households show the steepest expansion trajectory.
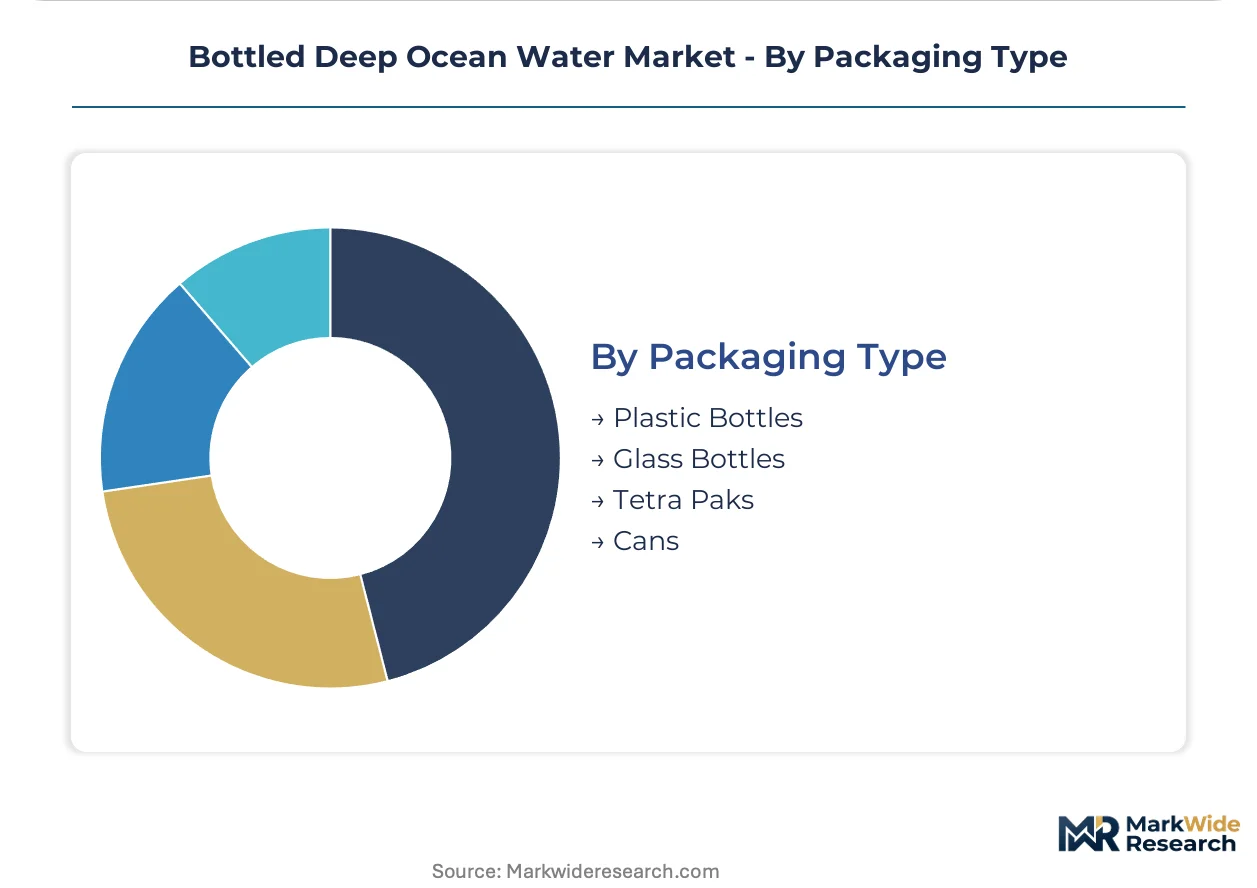
Packaging Type:
Material selection reflects trade-offs between mineral stability preservation and sustainability positioning.
- Glass Bottles:Inert material prevents chemical leaching of bioactive compounds during extended shelf storage. Premium hospitality buyers in Tokyo and Seoul specify glass for therapeutic-grade products.
- Plastic Bottles:Lightweight logistics enable cost-competitive distribution to mass retail channels with shorter turnover cycles.
- Tetra Paks:Aseptic filling technology extends shelf life for e-commerce subscription models with irregular delivery frequencies.
- Cans:Aluminum barriers suit flavored water variants where taste preservation outweighs mineral stability concerns.
Glass Bottles dominate certified therapeutic positioning; Plastic Bottles capture volume scale in standard hydration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Ministry of Health, Labour and Welfare enforces mineral-content verification that shapes competitive positioning across East Asian markets. South Korea's MFDS maintains parallel standards for therapeutic-grade hydration products. Hawaii's state environmental regulators cap Pacific extraction volumes, constraining North American supply expansion.
South Korea
Premium hospitality channels in Seoul absorb rising volumes as wellness positioning intensifies among metropolitan consumers. MFDS certification requirements filter subscale producers from therapeutic-grade segments. The Seoul Capital Area concentrates demand through established deep-water extraction infrastructure serving hotel and restaurant networks.
Japan
Metropolitan consumers in Tokyo and Osaka respond to magnesium and trace element claims with subscription-based replenishment patterns. The Ministry of Health, Labour and Welfare maintains strict mineral-content labeling rules that redirect marketing investment toward clinical substantiation. Kanto and Kansai regions anchor national supply through verified cold-sterilization pipeline networks.
Taiwan
Younger demographics in Taipei drive flavored water segment expansion through taste-forward formulations with retained mineral density. National regulators enforce extraction permit standards that protect marine ecosystems while constraining offtake volumes. The East China Sea pipeline infrastructure concentrates supply control among vertically integrated operators.
United States
North American wellness retail channels show underdeveloped recurring-revenue potential relative to East Asian market maturity. The FDA governs bottled water standards under 21 CFR 165.110 without specific deep ocean water provisions. Hawaii anchors Pacific supply through state-regulated extraction permits that limit volume expansion.
China
Coastal metropolitan corridors in Shanghai and Shenzhen absorb imported therapeutic-grade positioning where domestic extraction infrastructure remains limited. SAMR oversees bottled water safety standards with increasing scrutiny of mineral claim substantiation. Yangtze River Delta distribution networks channel volume toward premium hospitality procurement.
Bottled Deep Ocean Water Market Vendor Landscape
Listed leaders compete with private specialists across certification capability and extraction access. The competitive set compresses toward ISO 22000-qualified operators with proven pipeline rights, while speculative entrants face 12-18 month qualification delays. Three archetypes dominate: vertically integrated pipeline operators, wellness-brand marketers, and hospitality-focused niche suppliers. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure marine ecosystem permits.
Within the vertically integrated tier, Taiwan Yes Deep Ocean Water Co., Ltd. and Okinawa Deep Ocean Water Co., Ltd. exemplify regional supply control through pipeline infrastructure ownership. Hawaii Deep Blue occupies a position among Pacific extraction-rights holders serving North American wellness retail. Kona Deep sits within the mineral-profile differentiation archetype rather than competing on volume scale. These named entities anchor industry-level commentary on how certification and geography stratify competitive positioning.
| Leading Market Players |
|---|
| Hawaii Deep Blue |
| Taiwan Yes Deep Ocean Water Co., Ltd. |
| Kona Deep |
| Blu Octopus |
| Jeju Deep Water |
| Deep Ocean Enterprises |
| Okinawa Deep Ocean Water Co., Ltd. |
| Mariana DSW |
| PK-DSW |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between East Asian pipeline operators and Seoul-Tokyo hospitality chains lock in extraction access while providing price visibility against spot-market volatility. These arrangements tether premium mineral-water grades to certified cold-sterilization capacity, insulating qualified operators from commodity substitution pressure.
Pricing Analysis
Certification level creates the primary spread between ISO 22000-verified therapeutic grades and uncertified commodity positioning. Pricing stratifies across premium certified, standard membrane-filtered, and economy thermal-treated tiers, with subscription models capturing recurring-revenue premiums in North American wellness retail. Cost compression in the standard tier intensifies as surface-sourced mineral water substitutes compete on electrolyte parity. Household subscribers show least price sensitivity; institutional food-service buyers absorb volume at thin margins.
Supply Chain Analysis
Strategic stockpiling of membrane filtration capacity dominates over just-in-time raw-water sourcing given Hawaii state permit scarcity and East Asian pipeline concentration. Supply draws from Taiwan, Japan, and South Korea as the three viable extraction geographies, with raw-water dependencies on deep-water intake infrastructure, cold-sterilization membrane systems, and glass packaging for therapeutic grades. Single-source vulnerability concentrates around the East China Sea pipeline network. Distribution runs through vertically integrated operators controlling extraction-to-bottling corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surface-sourced mineral water with comparable electrolyte profiles poses immediate substitution threat to uncertified deep ocean water grades, forcing incumbents to defend therapeutic claim credibility.
For Market Incumbents: Consolidate extraction rights through permit acquisition in Hawaii and Taiwan before regulatory caps tighten further. Deepen backward integration into membrane filtration manufacturing to capture technology margin and insulate against equipment supply bottlenecks. Defend against surface-water substitutes by accelerating Japan Ministry of Health, Labour and Welfare certification timelines for clinical-channel access. For New Entrants and Emerging Players: Lead with flavored functional water white space in Taipei and Seoul where taste-forward formulations with retained mineral density attract younger demographics underserved by incumbent pure-water positioning. Target direct-to-consumer subscription channels in North American wellness retail where recurring-revenue models remain underdeveloped relative to East Asian maturity. Deploy mineral-profile matching algorithms as the primary go-to-market wedge. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated pipeline operators with proven ISO 22000 certification and locked extraction permits rather than brand-marketing pure-plays. Long-term viability over the projection horizon hinges on marine ecosystem permit renewals and cold-sterilization technology maturation. Monitor Hawaii state environmental review timelines as the critical inflection signal for North American supply expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Marine Ecosystem Permit Acquisition | Hawaii state regulators cap Pacific extraction volumes, constraining supply expansion for qualified operators. |
| Cold-Sterilization Capacity Buildout | Membrane filtration below 0.1 microns preserves bioactive properties for therapeutic-grade positioning in Seoul-Tokyo hospitality. |
| Direct-to-Consumer Channel Launch | Subscription models bypass supermarket markups and capture younger demographics through personalized mineral-profile matching. |
| Clinical Substantiation Investment | Japan Ministry of Health, Labour and Welfare verification redirects marketing spend toward therapeutic claim credibility. |
| Flavor Formulation R&D Partnership | Taiwan and Seoul buyers respond to taste-forward variants with retained mineral density, expanding addressable demand. |
Methodological Framework
The analysis maps mineral water, flavored water, and therapeutic-grade segments, each validated through extraction facility operators, hospitality procurement managers, wellness retail buyers, and membrane filtration equipment specialists. Primary fieldwork combined structured interviews with secondary validation against FDA 21 CFR 165.110 filings, Japan Ministry of Health, Labour and Welfare mineral-content databases, Hawaii state environmental permit records, and East Asian customs trade data. Bottom-up volume modeling triangulated against top-down category spend estimates.
Consistency checks validated volume and value outputs against pipeline capacity disclosures and hospitality sector procurement patterns across the analysis window. Segmentation dimensions modeled include product type, distribution channel, end-user archetype, and packaging format, with geographic regulatory clusters as an additional industry-specific layer. CAGRs derived from fitted growth curves applied to verified base-year extraction volumes, incorporating cold-sterilization technology adoption rates and subscription channel penetration curves as key inputs.
Underlying assumptions cover marine ecosystem permit renewal continuity and membrane filtration cost trajectories, with deviation risk concentrated in Hawaii state regulatory review delays and surface-water substitution acceleration. Revision becomes warranted when Japan Ministry of Health, Labour and Welfare substantiation requirements tighten beyond current compliance timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Foaming Creamer Market
Beverages
CBD-Infused Beverages Market
Beverages
Semillon Market
Beverages
Nitro-Infused Beverages Market
Beverages
Global Electrolyte Drinks Market
Beverages
Sparkling Water Market
Beverages
Water Bottle Market
Beverages
China Soy Beverages Market
Beverages
Asia-Pacific Vinegar Market
Beverages
Bubble Food and Beverages Market
Beverages
United Kingdom Energy Drink Market
Beverages
Grab and Go Bottles Market
Beverages
Ginger Ale Market
Beverages
Root Beer Market
Beverages
Fruit Juice Market
Beverages
BBQ Charcoal Market