
 Ready to Drink Premixes Market | 2026-2036
Ready to Drink Premixes Market Size, Share, and Industry Trends Forecast 2026-2036
Ready to Drink Premixes Market Analysis
ISO 22000 certification for food safety management systems is unwinding competitive access across the ready to drink premixes landscape, forcing smaller blenders into costly facility upgrades. Diageo leverages its captive distillery network to secure base spirit supply for canned cocktail lines. Bacardi Limited anchors Caribbean rum authenticity claims across hard seltzer and flavored spirit extensions. Pernod Ricard competes through absinthe and anise-forward premix portfolios that exploit European flavor preferences.
Ready to drink premixes comprise alcohol-based or non-alcohol beverages formulated with pre-blended spirits, mixers, flavoring agents, and carbonation, typically packaged in single-serve aluminum cans or bottles with shelf stability achieved through pasteurization or cold-fill aseptic processing; their primary purpose is to deliver consistent bar-quality consumption experiences without on-premise preparation equipment. Cocktails dominate value capture given higher alcohol content and premium positioning, while hard seltzers sustain volume leadership through lower-calorie formulations that attract health-conscious young adults. Supermarkets and online retail together concentrate margin pools as direct-to-consumer platforms reduce intermediary markups.
The FDA governs alcohol beverage labeling and ingredient disclosure under the Federal Alcohol Administration Act, while TTB permitting requirements shape interstate distribution feasibility for new entrants. EFSA and national regulators across the European Union enforce additive limits and health claim restrictions that constrain flavor innovation in berry and herbal formulations. Stakeholders must monitor evolving excise tax structures and single-use packaging directives as these policy levers increasingly determine which formulation architectures and material choices sustain profitability.
Market Dynamics
The ready to drink premixes market is being fundamentally restructured by the FDA's updated alcohol labeling requirements, which are forcing reformulation cycles and compliance investments that favor scaled producers with dedicated regulatory teams over smaller blenders.
Growth Catalysts
- Flavor Innovation Pipelines:Young adult consumers in the United States are pulling novel botanical and tropical flavor profiles into mainstream distribution, expanding addressable occasions beyond traditional cocktail hours.
- TTB Permitting Efficiency:Streamlined interstate distribution approvals under federal alcohol administration frameworks are reducing market entry timelines for compliant new entrants.
- Cold-Fill Aseptic Processing:This packaging technology is extending shelf stability without thermal degradation, enabling cleaner ingredient decks that resonate with health-positioned buyers.
Market Restraints
- Aluminum Input Volatility:Single-serve can dependency exposes margins to commodity price swings in rolled aluminum sheet, the dominant primary packaging substrate.
- Caribbean Rum Supply Concentration:Authenticity claims for hard seltzer extensions tie formulation stability to specific island distillery capacity, creating geographic bottleneck risk.
- EFSA Additive Limits:European berry and herbal formulation ceilings constrain flavor architecture options for brands seeking cross-Atlantic portfolio standardization.
Strategic Opportunities
- Direct-to-Consumer Channel Maturation:United States-based platforms are capturing margin pools previously absorbed by wholesale intermediaries, enabling price experimentation.
- Absinthe-Forward Portfolios:European anise flavor preferences present white space for premium positioning in markets underserved by botanical spirit blends.
- ISO 22000 Certification Arbitrage:Food safety management gaps among smaller blenders create acquisition targets for scaled players seeking facility footprint expansion.
Industry Challenges
- Reformulation Cycle Compression:FDA compliance timelines are compressing product development windows, straining R&D throughput for multi-SKU portfolios.
- Cross-Border Formulation Complexity:Divergent TTB and EFSA additive thresholds force parallel recipe maintenance, inflating quality assurance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready to Drink Premixes Market |
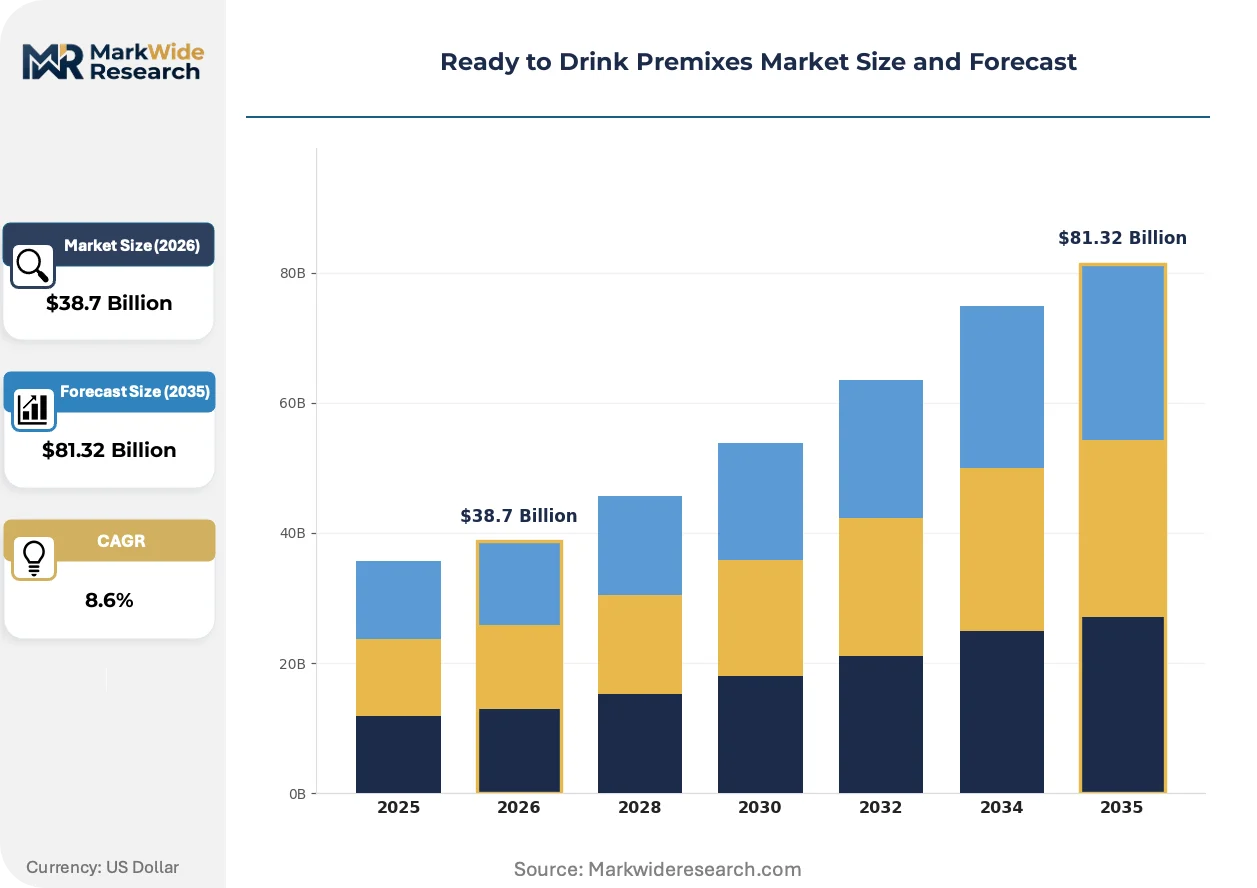
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cocktails, Mocktails, Hard Seltzers, Flavored Spirits Distribution Channel: Supermarkets, Online Retail, Bars, Convenience Stores End User: Young Adults, Professionals, Event Planners, Retail Consumers Flavor Profile: Citrus, Spicy, Herbal, Berry |
| Companies Covered | Diageo, Bacardi Limited, Pernod Ricard, Brown-Forman, Suntory Holdings Limited, Anheuser-Busch InBev, Mark Anthony Brands, Constellation Brands, Campari Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready to Drink Premixes Market Emerging Trajectories
Active packaging technologies and regulatory transparency mandates are converging to reshape how ready to drink premixes are formulated, labeled, and delivered to convenience-seeking consumers.
Nitrogen dosing systems for widget-free cascading are miniaturizing from draft-line installations into self-contained can architectures. Young adult buyers seeking bar-quality texture without on-premise equipment are accelerating adoption of these modified atmosphere packages. The technology is miniaturizing the experiential gap between packaged and freshly mixed serves, compressing premium pricing justification cycles.
The FDA's updated alcohol labeling requirements under the Federal Alcohol Administration Act are mandating expanded ingredient disclosure and nutritional transparency. This regulatory shift is forcing reformulation investments and label redesign costs across the competitive set. Cocktails with complex botanical decks face the steepest compliance burden, driving simplification toward shorter ingredient lists.
Young adult procurement patterns are fragmenting across channel types, with supermarket and online retail splitting volume in ways that undermine traditional wholesale concentration. Direct-to-consumer platforms are capturing trial occasions previously owned by on-premise discovery, particularly for novel flavor introductions. This channel rotation is most pronounced in United States metropolitan markets where delivery infrastructure density supports impulse replenishment cycles.
Ready to Drink Premixes Market Segmentation
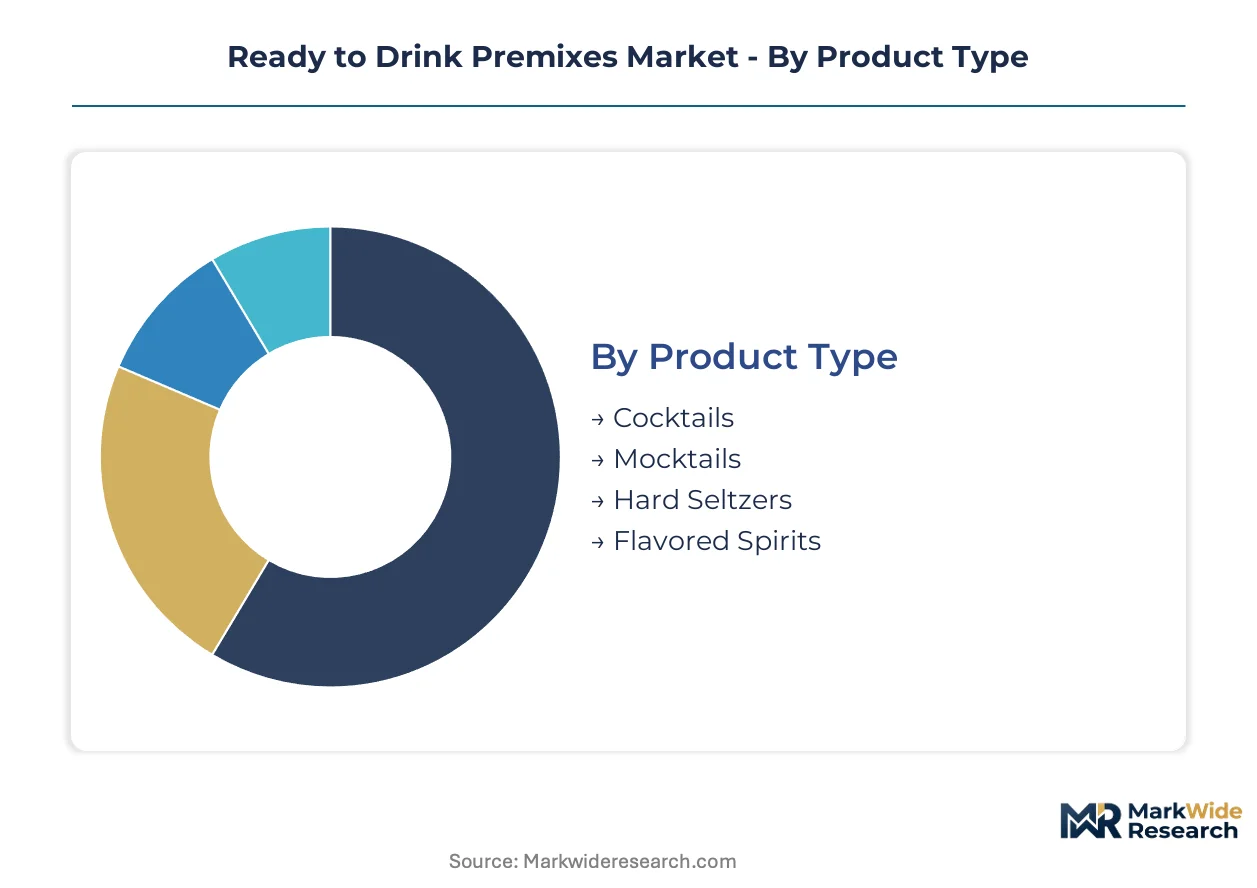
Segmentation in ready to drink premixes reveals how formulation architecture, channel access, and demographic targeting determine margin capture. Each dimension carries distinct regulatory and supply chain implications that reshape competitive positioning across the forecast window.
Product Type:
Premium alcohol content and mixology complexity concentrate value in spirit-forward formulations, while volume scales through lighter, sessionable alternatives.
- Cocktails:Pre-blended spirits with multiple ingredients and higher ABV deliver bar-quality experiences in aluminum formats. United States metropolitan demand pulls botanical and tropical variants into mainstream distribution as young adults seek occasion expansion beyond traditional cocktail hours.
- Hard Seltzers:Carbonated water base with distilled spirits and natural flavors achieves lower-calorie positioning that attracts health-conscious buyers. Cold-fill aseptic processing enables cleaner ingredient decks without thermal degradation, supporting shelf stability claims.
- Mocktails:Non-alcohol alternatives replicate cocktail complexity through botanical extracts and carbonation for designated-driver and wellness occasions.
- Flavored Spirits:Base spirit infusions with fruit or spice essences bridge ready-to-drink convenience with traditional liquor category familiarity.
Cocktails hold installed capacity. Hard Seltzers is rotating up the share rankings.
Distribution Channel:
Channel selection determines margin retention and trial accessibility, with direct routes capturing pools previously absorbed by wholesale intermediaries.
- Supermarkets:High-velocity retail environments with refrigerated shelf space generate volume through impulse and planned replenishment cycles. United States chains are expanding dedicated RTD sets as flavor innovation pipelines mature and young adult foot traffic concentrates in suburban formats.
- Online Retail:Direct-to-consumer platforms reduce intermediary markups and enable price experimentation for novel introductions. Delivery infrastructure density in metropolitan markets supports subscription models and same-day impulse purchasing.
- Bars:On-premise discovery channels validate premium positioning through draft-line quality comparisons before packaged conversion.
- Convenience Stores:Grab-and-go occasions favor single-serve formats with immediate consumption timelines and location-based impulse triggers.
Supermarkets hold installed capacity. Online Retail is rotating up the share rankings.
End User:
Demographic targeting aligns formulation intensity and packaging format with consumption occasion patterns and procurement channel preferences.
- Young Adults:Convenience-seeking consumption patterns reshape beverage purchasing across United States markets as this cohort pulls novel botanical profiles into mainstream distribution. TTB permitting efficiency and streamlined interstate approvals reduce discovery friction for compliant new entrants targeting this segment.
- Professionals:Time-constrained buyers prioritize consistent quality without preparation equipment, favoring premium cocktail formats for home entertaining.
- Event Planners:Bulk procurement needs favor shelf-stable formats with predictable serving costs and minimal on-site labor requirements.
- Retail Consumers:Occasional purchasers respond to promotional pricing and seasonal flavor rotations in supermarket environments.
Young Adults represent the steepest expansion trajectory. Professionals maintain steady share.
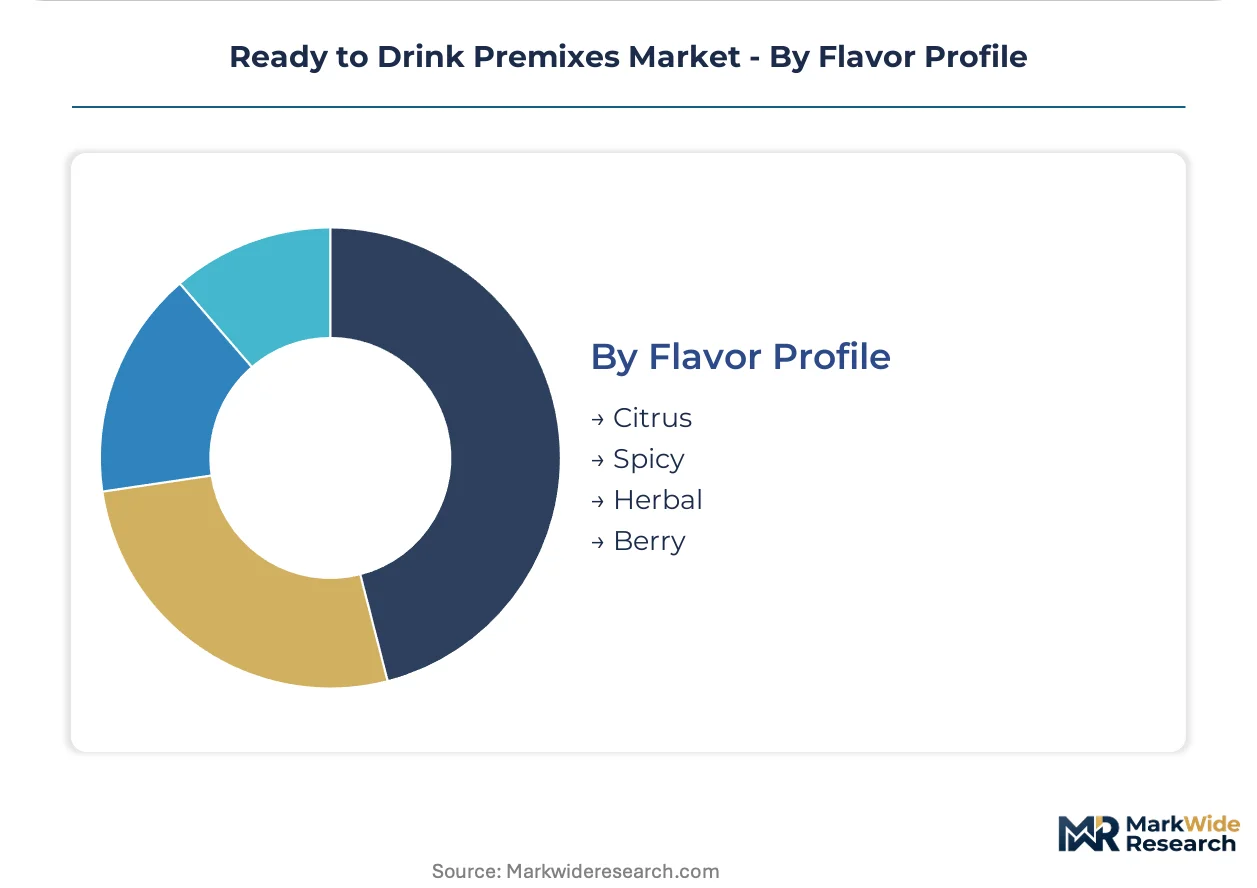
Flavor Profile:
Regional preference divergence and regulatory ceilings on additive loading constrain formulation standardization across Atlantic markets.
- Citrus:Lemon, lime, and grapefruit bases dominate volume given broad palatability and supply chain maturity. EFSA additive limits on certain citrus-derived compounds force parallel recipe maintenance for European market access, inflating quality assurance overhead.
- Herbal:Botanical and anise-forward variants exploit European flavor preferences where absinthe heritage supports premium positioning. FDA expanded ingredient disclosure requirements impose reformulation investments on complex botanical decks.
- Berry:Strawberry, raspberry, and mixed berry profiles attract health-positioned buyers though EFSA ceilings constrain formulation architecture options for cross-Atlantic portfolio standardization.
- Spicy:Chili, ginger, and pepper infusions target adventurous palates with sensory differentiation in crowded shelf sets.
Citrus holds installed capacity. Herbal is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA labeling mandates and TTB permitting efficiency are concentrating ready to drink premixes investment in the United States, while EFSA additive ceilings force parallel formulation architectures for European market access.
United States
Young adult procurement patterns and direct-to-consumer channel maturation drive flavor innovation pipelines in metropolitan markets. TTB streamlined interstate distribution approvals reduce discovery friction for compliant entrants. California and New York clusters anchor premium cocktail format development as delivery infrastructure density supports impulse replenishment cycles.
Germany
Health-conscious buyer segments and lower-calorie formulation demand expand hard seltzer addressable occasions. EFSA health claim restrictions constrain berry and herbal additive loading, forcing recipe simplification. Bavaria-based blenders invest in ISO 22000 certification to secure supermarket shelf space against private label incursion.
United Kingdom
Convenience-seeking consumption patterns reshape supermarket procurement as dedicated RTD sets expand in suburban formats. The country's national alcohol regulator enforces labeling transparency mandates that parallel FDA disclosure trajectories. London metropolitan demand pulls botanical and tropical variants into mainstream distribution channels.
Japan
Time-constrained professional segments favor consistent quality without preparation equipment, supporting premium cocktail format adoption. METI standards for food safety management systems create certification barriers for smaller blenders. Tokyo and Osaka clusters concentrate flavor innovation investment as cold-fill aseptic processing extends shelf stability claims.
Brazil
Event planner bulk procurement needs favor shelf-stable formats with predictable serving costs for hospitality occasions. ANVISA additive thresholds shape formulation architecture options for cross-border portfolio standardization. São Paulo industrial corridors concentrate canning capacity investment as aluminum input volatility exposes margin compression risk.
Ready to Drink Premixes Market Vendor Landscape
Listed leaders compete with private specialists across formulation architecture and channel access dimensions, producing a tiered structure where scale-driven regulatory teams face agile flavor innovators. The vendor base fragments across captive distillery networks, third-party bottling arrangements, and contract manufacturing partnerships. Three archetypes dominate: integrated spirit majors with in-house production, specialist blenders with niche flavor positioning, and beverage conglomerates leveraging existing distribution infrastructure. Competitive moves concentrate on M&A for facility footprint expansion and strategic partnerships for cross-border formulation compliance.
Within the integrated spirit major tier, Diageo and Bacardi Limited exemplify archetypes built on captive supply networks and authenticity claims. Pernod Ricard occupies a position representing European flavor preference exploitation through anise-forward portfolios. These three entities anchor the competitive set as regulatory compliance investments favor scaled producers with dedicated technical teams over smaller blenders seeking ISO 22000 certification arbitrage.
| Leading Market Players |
|---|
| Diageo |
| Bacardi Limited |
| Pernod Ricard |
| Brown-Forman |
| Suntory Holdings Limited |
| Anheuser-Busch InBev |
| Mark Anthony Brands |
| Constellation Brands |
| Campari Group |
| Others |
Supply Flow & Price Mechanics
Cold-fill aseptic processing substitution for thermal pasteurization redraws supply geography toward regions with capital-intensive packaging infrastructure while compressing pricing premiums for shelf-stable formulations. This equipment migration concentrates production economics in markets where aluminum can fabrication clusters support just-in-time inventory models.
Pricing Analysis
Certification level creates the primary spread between ISO 22000-verified facilities and uncertified blenders, with three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on TTB compliance overhead and captive distillery access, with premium tiers commanding spreads for botanical complexity. Pricing pressure stems from aluminum input volatility exposing margin compression in single-serve formats. Young adult buyers in direct-to-consumer channels exhibit lowest price sensitivity, while event planners in bulk procurement show highest elasticity.
Supply Chain Analysis
Inventory lead times stretch longest for Caribbean rum base spirits tied to island distillery capacity and seasonal harvest cycles. Geographic supply concentrates in the United States, Germany, and Japan where TTB efficiency, EFSA compliance infrastructure, and METI certification frameworks anchor production. Raw material dependencies center on rolled aluminum sheet, natural flavor extracts, and distilled spirits feedstock. Single-source vulnerability runs through Caribbean rum authenticity claims. Distribution feeds from captive distillery networks through third-party bottling arrangements into supermarket and online retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-consumer platform maturation transforms this market into a platform-economics inflection where delivery infrastructure density and subscription interoperability reshape discovery and replenishment patterns.
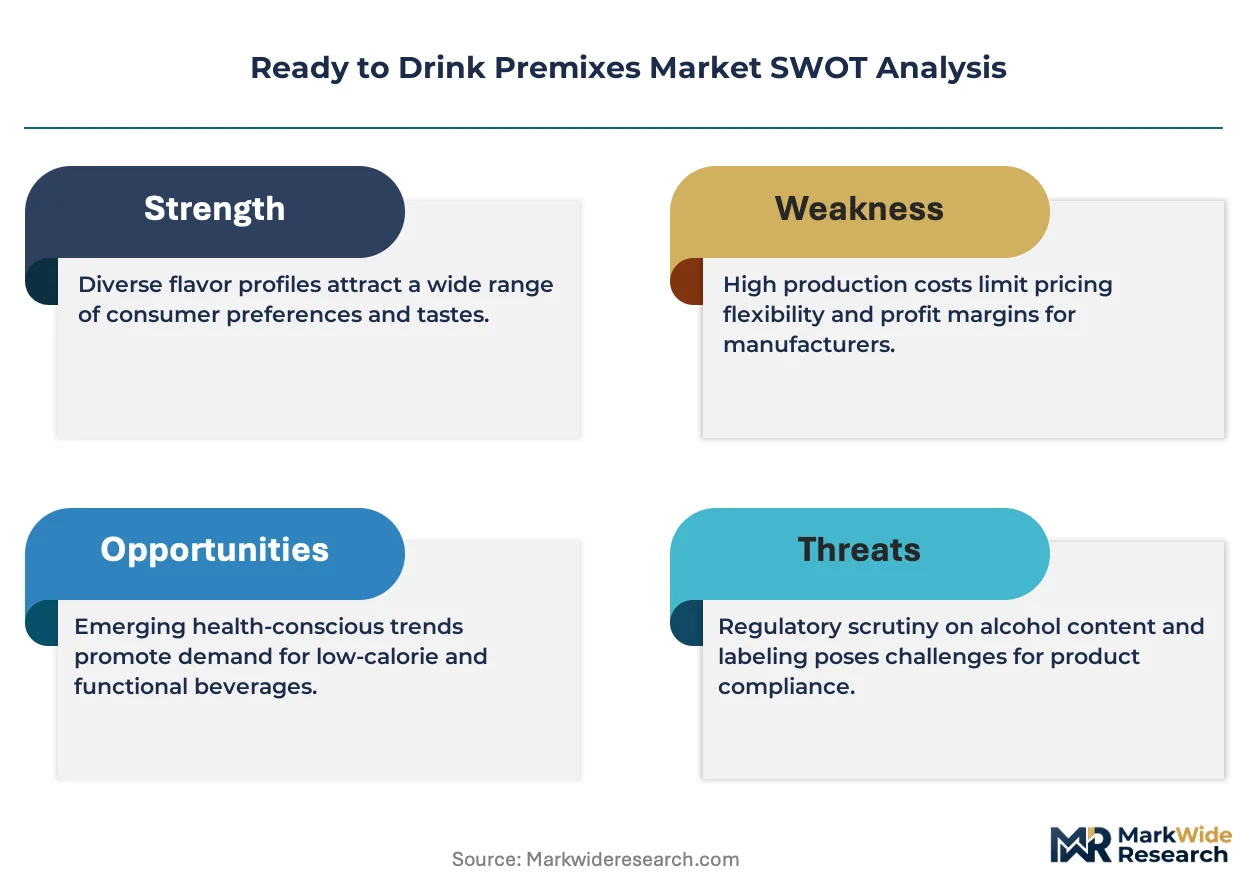
For Market Incumbents: Consolidate ISO 22000-certified facility footprints through targeted acquisition of smaller blenders facing compliance cost barriers. Deepen backward integration into captive distillery networks to secure base spirit supply against Caribbean rum concentration risk. Channel control through exclusive supermarket RTD set placement defends margin position against private label incursion. For New Entrants and Emerging Players: FDA streamlined approval pathways offer certification fast-track entry into United States metropolitan markets with lowest regulatory friction. White space concentrates in absinthe-forward portfolios exploiting European anise preferences underserved by botanical spirit blends. Go-to-market angles should leverage cold-fill aseptic processing claims for health-positioned hard seltzer introductions. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors scaled players with dedicated regulatory teams over fragmented specialists. Long-term viability over the next decade hinges on cross-border formulation compliance capabilities. Acquisition targets should profile ISO 22000-certified blenders in Germany and Japan with underutilized capacity. The signal to watch is EFSA additive threshold revisions that would force parallel recipe maintenance overhead.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 22000 Certification Investment | Unlocks supermarket shelf access against private label competitors in Germany and Japan. |
| Cold-Fill Aseptic Processing Scale-Up | Enables cleaner ingredient decks that resonate with health-conscious young adult buyers. |
| Direct-to-Consumer Platform Launch | Captures margin pools previously absorbed by wholesale intermediaries in United States metros. |
| Captive Distillery Network Expansion | Secures base spirit supply against Caribbean rum geographic bottleneck risk. |
| Cross-Border Formulation Compliance | Reduces quality assurance overhead from divergent TTB and EFSA additive thresholds. |
Methodological Framework
Operator-level perspectives from brand managers, category buyers at retailers, channel sales heads, and supply planners anchored the qualitative base for this study. Primary interviews combined with secondary validation from Nielsen retail audit data, customs records, SEC 10-K filings, and TTB permitting databases. Bottom-up SKU-level volume builds triangulated against top-down category spend estimates.
Sensitivity analysis tested forecast outputs against aluminum price volatility scenarios and regulatory timeline compression assumptions. Segmentation dimensions modeled include product type, distribution channel, end user demographic, and flavor profile across the projection horizon. CAGRs derived from category growth rate reconciliation with per-capita consumption elasticity and channel shift coefficients. Forecast inputs incorporated TTB permitting efficiency indices and EFSA additive limit revision probabilities.
Decision-makers should treat outputs as directional under stable regulatory frameworks and intact supply chain configurations; material deviation in FDA labeling timelines or Caribbean rum harvest conditions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Spring Water Market
Beverages
Popping Bobas Market
Beverages
Africa Dairy Based Beverages Market
Beverages
Relaxation Beverages Market
Beverages
Blenders Market
Beverages
Maple Water Market
Beverages
Global Soft Drinks Concentrate Market
Beverages
South East Asia Bottled Water Market
Beverages
Asia-Pacific Energy Drink Market
Beverages
Global Squash Drinks Market
Beverages
United States Soy Beverages Market
Beverages
Fruit Juice Market
Beverages
Italy Probiotic Drinks Market
Beverages
Freezer & Beverage and Wine Cooler Market
Beverages
Ginger Ale Market
Beverages
Asia Pacific Fruits and Vegetables Juice Market