
 Bottled Beverages Market | 2026-2036
Bottled Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Bottled Beverages Market Insights
rPET resin is pivoting away from virgin PET in bottled beverages as carbon-accounting pressure intensifies. The Coca-Cola Company leverages its captive recycling infrastructure to secure rPET supply chains across multiple continents. PepsiCo anchors its North American bottling network with renewable electricity commitments at production facilities. Nestlé differentiates through mineral water sourcing rights that control access to protected aquifers in strategic geographies.
Bottled beverages comprise commercially packaged liquid refreshments sealed in consumer-portable containers, typically ranging from 200 milliliters to 2 liters, using aseptic cold-filling or hot-fill processes to ensure microbiological stability and shelf life extension. Carbonated drinks and water together occupy the dominant volume positions, though sports drinks represent the fastest-expanding margin pool as functional hydration claims command price premiums. Plastic bottles retain cost leadership in Packaging Type, yet glass bottles capture premium positioning in restaurant and bar channels where perceived quality directly influences consumer selection.
FDA food-contact substance regulations and EPA recycling mandates in the United States, alongside EU Green Deal packaging requirements and REACH chemical safety standards in Europe, collectively elevate compliance costs while rewarding early movers in sustainable material transitions. India's BIS certification for packaged drinking water and FSSAI labeling mandates further fragment market access protocols across major demand centers. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate-specific tax regimes to anticipate which packaging formats will sustain profitability under tightening environmental compliance.
Market Dynamics
rPET resin shortages and EU Green Deal packaging mandates are compressing profit margins while forcing rapid capital redeployment toward circular material infrastructure.
Growth Catalysts
- EU Green Deal packaging requirements:Mandatory recycled content thresholds in beverage containers are pulling forward rPET capacity investments across European bottling networks.
- Urban middle-class consumption:Brazil, Indonesia, and Nigeria are registering sustained demand pull for branded single-serve hydration as convenience retail expands.
- Hotels and corporate catering:Procurement of portion-controlled bottled options is accelerating as hospitality operators standardize minibar and meeting room offerings.
Market Restraints
- rPET feedstock scarcity:Collection infrastructure gaps in key markets limit post-consumer bottle availability, inflating resin costs relative to virgin PET.
- Aluminum can supply concentration:Rolling mill capacity is geographically concentrated, creating input bottlenecks for brands pivoting from plastic.
- FDA food-contact substance timelines:Novel barrier coating approvals for sustainable substrates extend product development cycles by 18-36 months.
Strategic Opportunities
- Extended producer responsibility frameworks:Early compliance with deposit-return schemes in Germany and Nordic markets secures preferential shelf placement.
- Aseptic cold-filling convergence with barrier films:Technology pairing enables shelf-stable plant-based beverages in lightweight rPET bottles.
- Direct-to-hotel distribution:Bypassing traditional wholesale channels captures margin from institutional buyers seeking customized labeling and volume flexibility.
Industry Challenges
- Certification complexity:India's BIS packaged drinking water certification and FSSAI labeling mandates require dedicated regulatory affairs capacity for market entry.
- Legacy filling line retrofit costs:Hot-fill equipment conversion for heat-sensitive alternative materials demands capital outlays that strain mid-tier bottlers.
- REACH chemical safety compliance:Substance of very high concern screenings for imported packaging additives create supply chain verification burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottled Beverages Market |
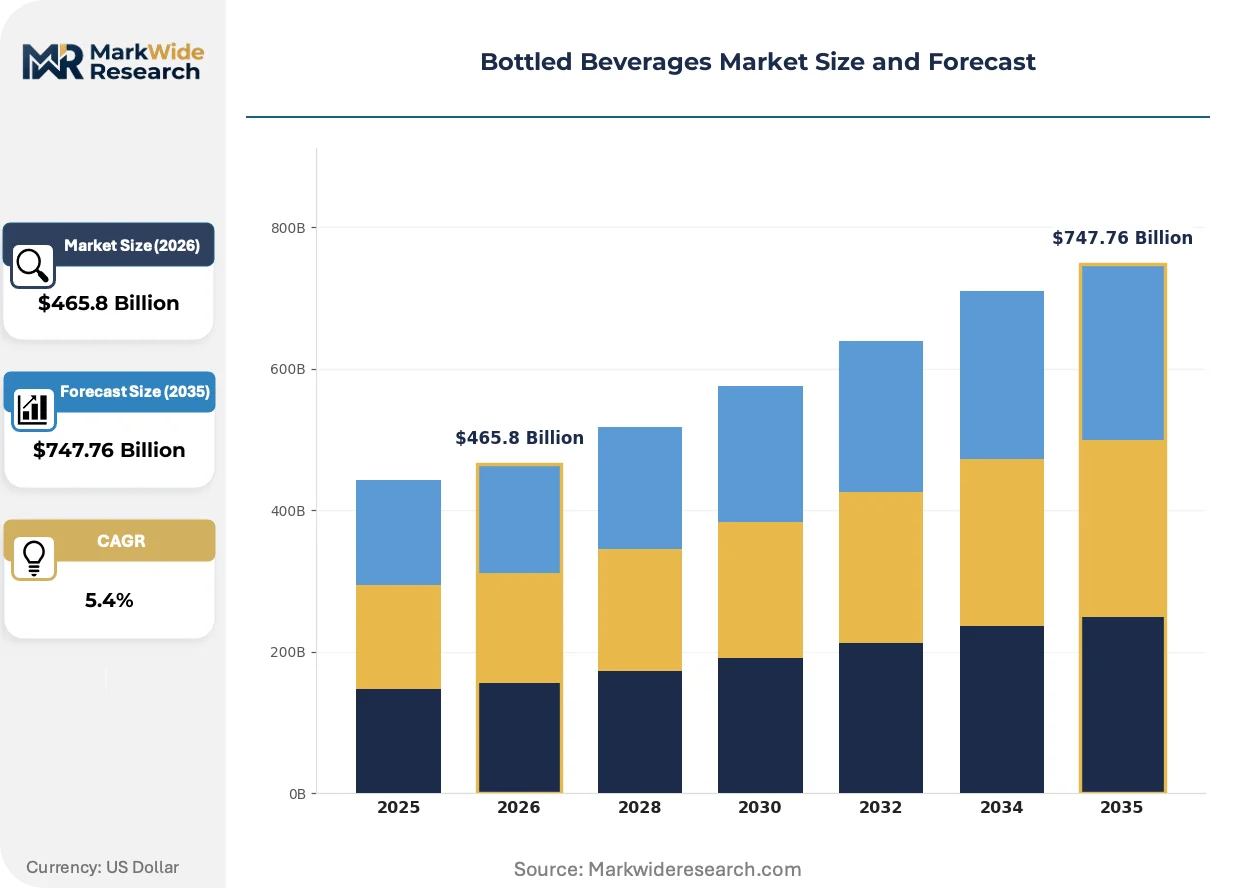
| Market Size in 2026 | $465.8 Billion |
| Market Size in 2035 | $747.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated Drinks, Juices, Water, Sports Drinks Packaging Type: Plastic Bottles, Glass Bottles, Tetra Packs, Cans End User: Retail Consumers, Restaurants, Bars, Vending Machines Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesalers |
| Companies Covered | The Coca-Cola Company, PepsiCo, Nestlé, Anheuser-Busch InBev, Danone, Keurig Dr Pepper, Monster Beverage Corporation, Red Bull GmbH, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottled Beverages Market Trends and Innovations
Material science breakthroughs and regulatory compliance automation are compressing product development timelines while fragmenting competitive advantage sources.
rPET resin with intrinsic viscosity stabilization is rewriting beverage packaging economics by enabling bottle-to-bottle closed-loop recycling without performance degradation. Major bottling networks in Germany and California are adopting this material at scale, displacing virgin PET in premium water segments. The technology is rewriting cost structures by reducing dependency on fossil-based feedstocks while satisfying EU Green Deal recycled content mandates.
REACH chemical safety standards in Europe are forcing reformulation of barrier coatings and adhesives used in multilayer bottles. The regulation is accelerating substitution of conventional epoxy-based liners with polyester alternatives in sensitive beverage categories. Functional water and infant nutrition segments are most affected, with manufacturers front-loading toxicology testing budgets to maintain market access.
Single-serve portion preference is consolidating purchasing authority within hotel procurement departments and corporate catering contracts. Traditional wholesale distributors are losing share to specialized beverage service operators offering inventory management software and private-label customization. This shift is most visible in Brazil's coastal tourism corridor and Nigeria's Lagos-Abuja corporate corridor.
Bottled Beverages Market Segmentation
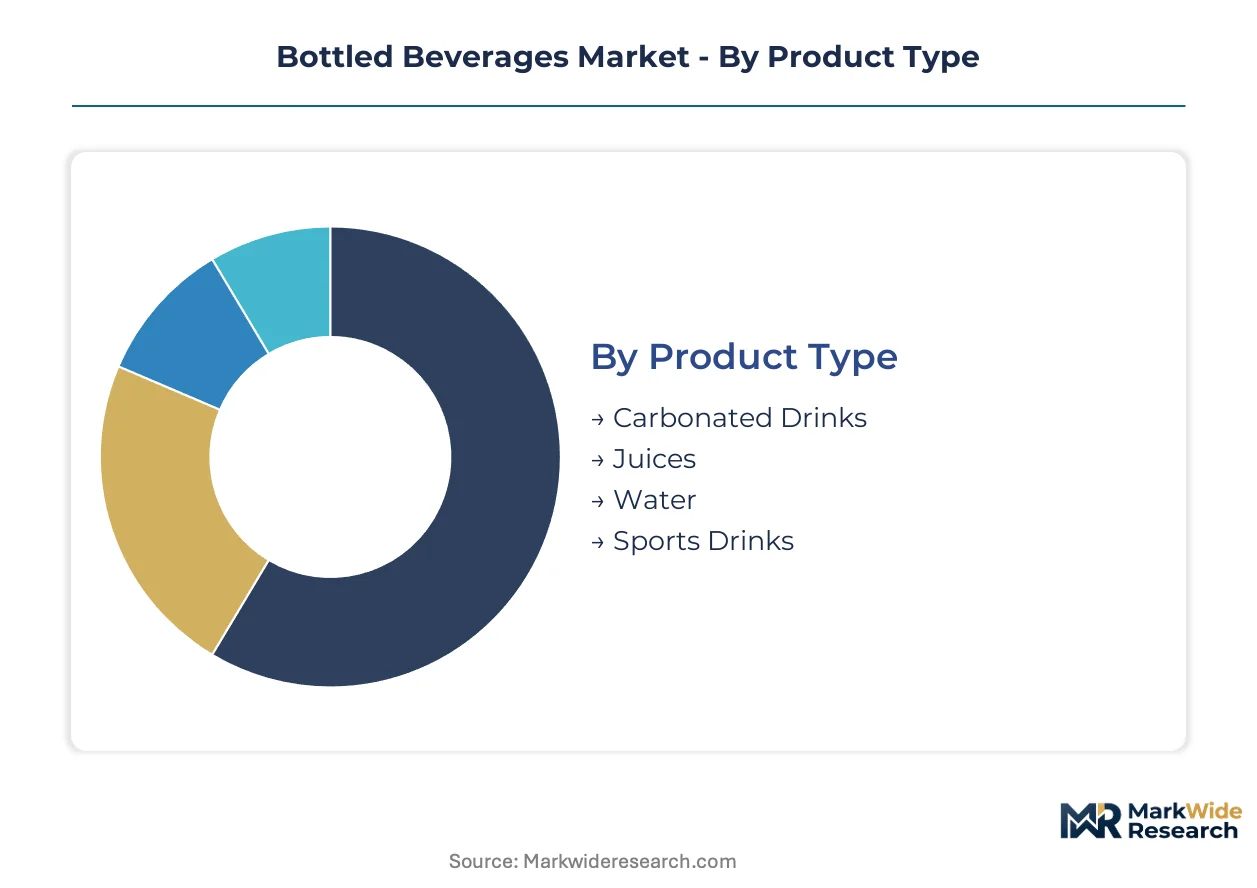
Segmentation in bottled beverages reveals how packaging economics and consumption context fragment profit pools. Buyers select formats based on portability requirements, shelf-life needs, and channel-specific quality signaling rather than liquid content alone.
Product Type:
Consumer hydration priorities and functional benefit claims determine portfolio allocation across liquid categories.
- Carbonated Drinks:Sugar-sweetened and zero-calorie formulations using phosphoric or citric acid preservation systems. Demand concentrates in Brazil's convenience retail expansion as urban middle-class consumers seek affordable refreshment with established brand recognition.
- Water:Still and sparkling variants sourced from protected aquifers or municipal treatment with mineral enhancement. Hotels and corporate catering services in Nigeria's Lagos-Abuja corridor are expanding procurement of premium single-serve options for minibar standardization.
- Juices:Pasteurized or high-pressure processed fruit and vegetable blends with vitamin fortification. Indonesia's tropical fruit supply base supports regional production cost advantages for not-from-concentrate offerings.
- Sports Drinks:Electrolyte-replenishment formulations with isotonic or hypotonic osmolality profiles. Functional hydration claims command price premiums in gym and athletic club channels.
Volume sits with Water; growth tilts toward Sports Drinks.
Packaging Type:
Material selection trade-offs between cost, recyclability, and barrier performance shape capital deployment across bottling networks.
- Plastic Bottles:rPET and virgin PET containers using stretch blow-molding with hot-fill or aseptic cold-filling compatibility. EU Green Deal recycled content mandates are pulling forward rPET capacity investments across German and Nordic bottling facilities.
- Glass Bottles:Returnable and single-use formats with superior oxygen and light barrier properties. Restaurant and bar channels in premium urban districts capture margin through perceived quality differentiation.
- Tetra Packs:Multilayer carton structures with aluminum foil cores for ambient shelf stability. Aseptic filling technology enables juice and plant-based beverage distribution without cold-chain dependency.
- Cans:Aluminum two-piece drawn-and-ironed containers with internal epoxy or polyester barrier coatings. Rolling mill capacity concentration creates input bottlenecks for brands pivoting from plastic formats.
Cost leadership belongs to Plastic Bottles; sustainability compliance is accelerating Cans.
End User:
Purchasing authority and consumption occasion define service requirements and customization depth.
- Retail Consumers:Individual and household purchasers selecting single units or multi-packs from shelf displays. Brazil's urban convenience retail expansion is reshaping pack size preferences toward immediate-consumption formats.
- Restaurants:Table-service establishments sourcing portion-controlled bottles with inventory management requirements. Direct-to-hotel distribution models are bypassing traditional wholesale channels for customized labeling.
- Bars:On-premise beverage service operators prioritizing premium presentation and rapid chill performance. Glass bottle formats dominate where perceived quality directly influences consumer selection.
- Vending Machines:Automated retail operators requiring drop-resistant packaging with extended ambient shelf life. Plastic bottles retain mechanical durability advantages for high-frequency dispensing environments.
Transaction volume concentrates with Retail Consumers; margin expansion favors Restaurants.
Distribution Channel:
Channel economics and inventory velocity determine working capital intensity and promotional investment levels.
- Supermarkets:Large-format retailers with category management systems and private-label negotiation leverage. Extended producer responsibility compliance in Germany secures preferential shelf placement for deposit-return scheme participants.
- Convenience Stores:Small-footprint urban retailers with high-rent locations demanding rapid inventory turns. Indonesia's urban middle-class consumption shift is expanding branded single-serve hydration availability.
- Online Retail:E-commerce platforms with direct-to-consumer fulfillment and subscription model potential. Packaging durability requirements intensify for last-mile delivery handling.
- Wholesalers:Traditional distributors serving fragmented retail and foodservice accounts. Specialized beverage service operators are capturing share through inventory management software and private-label customization.
Volume flows through Supermarkets; growth concentrates in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the UAE and special economic corridors in Vietnam are concentrating bottling capacity investments through tax-holiday incentives and duty exemptions on imported filling equipment.
United States
Convenience retail chains and hotel procurement departments are driving single-serve format expansion across Florida and Texas corridors. FDA food-contact substance regulations and EPA recycling mandates elevate compliance costs for alternative substrate introductions. California's rPET processing clusters in Los Angeles County and the Central Valley are scaling bottle-to-bottle recycling infrastructure to serve West Coast bottling networks.
Germany
Deposit-return scheme participation and EU Green Deal packaging mandates are reshaping material procurement decisions across Bavaria and North Rhine-Westphalia. REACH chemical safety standards force reformulation of barrier coatings in multilayer structures. The Rhine-Main bottling corridor around Frankfurt anchors continental rPET supply chain integration for premium water segments.
Brazil
Urban middle-class consumption patterns and coastal tourism expansion are pulling branded hydration demand through São Paulo and Rio de Janeiro retail channels. ANVISA labeling mandates and municipal waste management regulations fragment market access protocols. The São Paulo state industrial belt concentrates aseptic filling capacity for juice and functional beverage exports.
Indonesia
Tropical fruit supply availability and convenience store network expansion are positioning the archipelago for regional production cost advantages. The country's national food safety regulator enforces packaged drinking water certification requirements that strain new entrants. Java's Greater Jakarta and Surabaya manufacturing zones are capturing Japanese and Korean bottler joint venture investments.
Nigeria
Lagos-Abuja corporate corridor procurement and minibar standardization programs are accelerating premium single-serve water demand. Extended producer responsibility frameworks remain under development, creating regulatory uncertainty for packaging format transitions. Lagos State's Apapa port zone concentrates import-dependent filling line equipment and virgin PET resin distribution.
Bottled Beverages Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational beverage conglomerates commanding retail shelf space while regional co-packers capture foodservice and private-label volumes. The market structure tilts toward consolidated leadership in carbonated and water categories, with functional beverages exhibiting greater fragmentation. Three archetypes dominate: vertically integrated giants with captive recycling infrastructure, mineral water specialists controlling aquifer access rights, and agile co-manufacturers serving private-label programs. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players secure rPET supply commitments and aseptic filling technology licensing.
Within the integrated multinational tier, The Coca-Cola Company, PepsiCo, and Nestlé exemplify divergent strategic positioning. The Coca-Cola Company anchors global volume through captive recycling infrastructure investments across multiple continents. PepsiCo occupies a position defined by renewable electricity commitments at North American production facilities. Nestlé represents the mineral water specialist archetype, with portfolio differentiation built on protected aquifer sourcing rights in strategic geographies. These three entities collectively illustrate how material security, energy transition, and resource control constitute distinct vectors of competitive advantage in constrained supply environments.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo |
| Nestlé |
| Anheuser-Busch InBev |
| Danone |
| Keurig Dr Pepper |
| Monster Beverage Corporation |
| Red Bull GmbH |
| Unilever |
| Others |
Pricing and Supply Chain Analysis
rPET resin price indices cascade through European bottling networks into three-tier pricing structures across premium, standard, and economy levels, with EU Green Deal recycled content mandates compressing margins for converters locked into virgin PET contracts. Hotel procurement departments and corporate catering buyers absorb premium tier pricing for customized labeling, while convenience retail channels in Brazil and Indonesia negotiate volume discounts that reflect scale efficiencies in aseptic filling lines.
Pricing Analysis
Short lead-time premiums command price advantages for spot rPET deliveries from California and German processing clusters, while extended offtake contracts secure discounted resin access for integrated bottlers with captive collection infrastructure. Pricing stratifies across premium, standard, and economy tiers based on certification grade (FDA food-contact clearance vs. non-food applications) and customization depth (private-label artwork, bottle geometry modifications). Cost compression in standard-tier carbonated beverages is intensifying because aluminum can rolling mill capacity constraints inflate input costs for brands pivoting from plastic. Retail consumers in emerging markets exhibit highest price sensitivity, whereas hospitality operators in Nigeria's Lagos-Abuja corridor demonstrate lowest sensitivity due to minibar standardization requirements.
Supply Chain Analysis
FDA food-contact substance approvals and EU REACH chemical safety screenings gate supplier qualification, extending vendor onboarding timelines for barrier coating and adhesive manufacturers serving multilayer bottle segments. Raw material supply concentrates in Germany, the United States, and Indonesia, with rPET flake processing anchored in Los Angeles County and the Rhine-Main corridor while tropical fruit concentrate for juice applications sources from Java-based processors. Virgin PET resin, aluminum sheet stock, and aseptic barrier films constitute critical input dependencies. Single-source vulnerability pervades aluminum rolling mill supply, with capacity geographically concentrated in North America and Western Europe. Distribution runs through specialized beverage service operators offering inventory management software, displacing traditional wholesale channels in hotel and corporate catering segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards vertical-integration race winners who secure captive rPET supply chains or protected aquifer sourcing rights, with upstream material security constituting the decisive competitive lever over the projection horizon.
For Market Incumbents: Hedge against rPET feedstock scarcity by backward integration into post-consumer bottle collection infrastructure across German and Nordic deposit-return scheme territories, while defending premium water positioning through mineral sourcing rights in protected European aquifers. Capacity expansion in California's Central Valley rPET processing clusters offsets regulatory pressure from EPA recycling mandates. For New Entrants and Emerging Players: Launch via direct-to-hotel distribution models bypassing wholesale intermediaries in Brazil's coastal tourism corridor, capturing margin from inventory management software and private-label customization demand. White-space concentration sits with functional sports drinks in Nigeria's gym and athletic club channels, where isotonic formulation expertise commands price premiums absent entrenched multinational presence. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier mineral water specialists with aquifer access rights in European protected zones, positioned for premium repositioning as EU Green Deal packaging mandates accelerate format transitions. Long-term viability hinges on circular material infrastructure ownership rather than brand equity alone. Watch rPET resin spot price volatility as inflection indicator for integrated vs. non-integrated bottler margin divergence.| Strategic Initiative | Industry Significance |
|---|---|
| Captive rPET Infrastructure Investment | Secures bottle-to-bottle recycling supply chains independent of volatile virgin PET markets. |
| Protected Aquifer Sourcing Rights | Controls access to premium mineral water segments where provenance commands consumer price premiums. |
| Direct-to-Hotel Distribution Launch | Bypasses wholesale margin extraction while capturing customized labeling demand from hospitality procurement. |
| Aseptic Cold-Filling Technology Licensing | Enables shelf-stable plant-based beverages in lightweight rPET formats compliant with EU mandates. |
| Deposit-Return Scheme Early Compliance | Secures preferential supermarket shelf placement in German and Nordic extended producer responsibility frameworks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with bottling plant managers, hotel procurement directors, retail category buyers, and rPET processing facility operators. FDA food-contact substance databases, EU ECHA REACH registrations, and national packaging waste reports supplied regulatory trajectory signals. Bottom-up volume builds from country-level consumption data triangulated against top-down macroeconomic elasticity models.
Data-stream reconciliation across production volume disclosures, import-export trade flows, and channel inventory surveys generated consistent baseline estimates. Segmentation modeling incorporated product type (carbonated, water, juice, sports drinks), packaging material (rPET, glass, aluminum, carton), end-user archetype (retail, hospitality, foodservice), and distribution channel (supermarket, convenience, online, wholesale). CAGRs derived from elasticity-adjusted trend extrapolation, with rPET capacity expansion timelines and EU Green Deal implementation schedules as industry-specific forecast inputs.
rPET feedstock availability shocks, aluminum rolling mill capacity bottlenecks, and REACH chemical safety reformulation delays are the dominant revision risks to modeled outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Ready-To-Drink (RTD) Beverages Market
Beverages
Powdered Beverages Market
Beverages
Bottled Deep Ocean Water Market
Beverages
Asia-Pacific Vinegar Market
Beverages
Milk Tea Powder Market
Beverages
China Soy Beverages Market
Beverages
Apple Juice Concentrate Market
Beverages
Bottled Water Processing Market
Beverages
Root Beer Market
Beverages
Caffeine Mint Market
Beverages
Packaged Milkshake Market
Beverages
Herb Infused Water Market
Beverages
GCC Sports and Energy Drinks Market
Beverages
Asia-Pacific Spring Water Market
Beverages
Water Bottle Market
Beverages
Germany Probiotic Drinks Market