
 Dairy Based Beverages Market | 2026-2036
Dairy Based Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Based Beverages Market Outlook
Oat protein concentrate is pivoting into creamy smoothie formulations as brands reformulate to reduce reliance on fluid milk solids. Danone SA leverages its plant-dairy hybrid R&D pipeline to sustain innovation velocity across European markets. Fonterra Cooperative Group anchors its competitive stance through backward integration into pasture-to-bottle supply chains. Chobani Global Holdings differentiates via Greek yogurt drink platforms that command premium shelf positioning in US retail.
Dairy based beverages comprise fluid or semi-fluid products derived from cow, goat, or buffalo milk through homogenization, pasteurization, and flavor infusion, typically containing 2.5–8% milk fat and standardized protein levels for nutritional consistency. These products serve refreshment, meal replacement, and targeted nutrition delivery across retail and food service channels. Flavored milk occupies the largest volume share due to its penetration in school nutrition programs and family purchasing, while yogurt drinks generate superior margins through probiotic positioning and health claims. Online retail represents the fastest-growing access channel as direct-to-consumer subscription models bypass traditional supermarket slotting fees.
FDA nutrition labeling rules and USDA school meal standards shape product formulation and permissible health claims in the United States, while EFSA novel food assessments and EU Green Deal sustainability disclosures constrain ingredient sourcing and packaging choices across European markets. India's FSSAI fortification mandates and BIS quality certifications determine market access for domestic and imported brands. Stakeholders must monitor evolving carbon-accounting requirements and shifting procurement criteria from quick-service restaurant chains to anticipate which formulation and packaging investments will align with downstream buyer specifications.
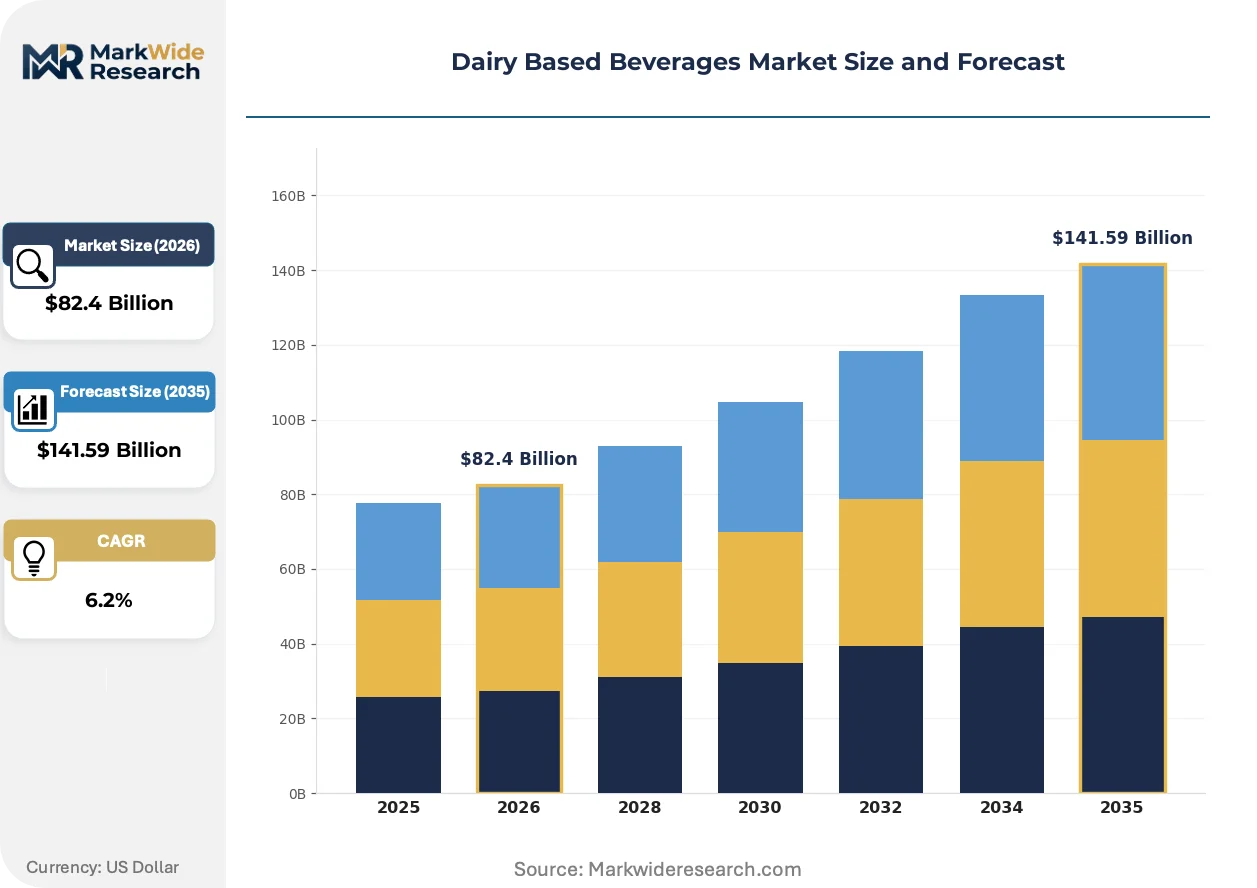
Market Dynamics
The EU Green Deal carbon-accounting mandates are compressing formulation timelines as processors retrofit facilities to meet Scope 3 disclosure requirements before enforcement phases begin.
Growth Catalysts
- EU Green Deal sustainability disclosures:Mandatory carbon-footprint reporting for dairy processing creates competitive differentiation for early-compliant brands across European retail channels.
- Fitness-oriented young adults:Functional beverage adoption among this demographic pulls protein-fortified and probiotic-positioned products into convenience store and gym channel expansion.
- India urban household shift:Movement from unpackaged milk to branded ready-to-drink formats concentrates demand growth in Mumbai, Delhi, and Bangalore metropolitan corridors.
Market Restraints
- Fluid milk solids cost volatility:Input price swings for butterfat and protein concentrates compress margin stability for mid-scale processors lacking forward-contract coverage.
- Pasture-to-bottle supply concentration:Backward integration dominance by New Zealand and Australian cooperative structures limits third-party processor access to premium raw milk streams.
- Plant-based substitution acceleration:Oat protein concentrate and pea isolate formulations displace dairy solids in smoothie and beverage applications among flexitarian consumer segments.
Strategic Opportunities
- India tier-2 city penetration:Branded ready-to-drink formats remain underdistributed in Pune, Hyderabad, and Ahmedabad relative to saturation levels in tier-1 metros.
- Direct-to-consumer subscription models:Online retail channel innovation bypasses supermarket slotting fees and captures recurring revenue through personalized nutrition profiling.
- FSSAI fortification mandates:India's mandatory vitamin A and D enrichment creates formulation standardization tailwinds for compliant domestic and imported brands.
Industry Challenges
- Carbon-accounting skill gaps:Shortage of lifecycle assessment specialists delays Scope 3 data collection and verification for EU Green Deal compliance submissions.
- Legacy pasteurization infrastructure retrofit costs:Capex intensity for energy-efficient heat recovery systems strains balance sheets of regional processors with limited access to green financing instruments.
- Novel ingredient EFSA assessment timelines:Extended novel food approval durations for probiotic strains and bioactive peptides stall product launch schedules in European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Based Beverages Market |
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $141.59 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milkshake, Yogurt Drink, Creamy Smoothie, Flavored Milk Application: Convenience Store, Supermarket, Online Retail, Food Service Customer Type: Diet-Conscious Consumers, Families, Children, Young Adults Packaging Type: Bottle, Carton, Tetra Pak, Can |
| Companies Covered | Lactalis, Dairy Farmers of America, Danone SA, Nestle SA, Arla Foods amba, Fonterra Cooperative Group, Chobani Global Holdings, General Mills, Agropur Dairy Cooperative, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Based Beverages Market Strategic Shifts
Reformulation pipelines are pivoting toward hybrid plant-dairy architectures as brands seek to retain functional benefits while meeting tightening sustainability procurement criteria from food service buyers.
Precision fermentation-derived whey proteins are integrating into premium beverage formulations as brands seek to decouple protein supply from herd-size constraints. Specialty nutrition manufacturers in Denmark and the Netherlands are adopting these inputs at pilot scale for sports recovery drinks. This technology is integrating upstream bioprocessing capabilities into traditional dairy R&D structures, compressing the historical separation between biotechnology and fluid milk operations.
EFSA novel food assessments and EU Green Deal sustainability disclosures are constraining ingredient sourcing flexibility for European processors. Industrial consequence includes mandatory packaging recyclability quotas and farm-level methane reporting that reshape supplier qualification criteria. Yogurt drink and probiotic beverage segments face the steepest compliance burden, with reformulation cycles accelerating to meet 2025 disclosure deadlines.
Quick-service restaurant chains are unbundling beverage procurement from dairy supplier agreements, creating direct contracting opportunities for specialized ready-to-drink manufacturers. This channel disruption shifts volume concentration away from broadline distributors toward vertically integrated processors with captive flavor development labs. The United States exhibits the most visible procurement restructuring, with regional burger and coffee chains establishing dedicated beverage innovation partnerships outside traditional dairy cooperative networks.
Dairy Based Beverages Market Segmentation
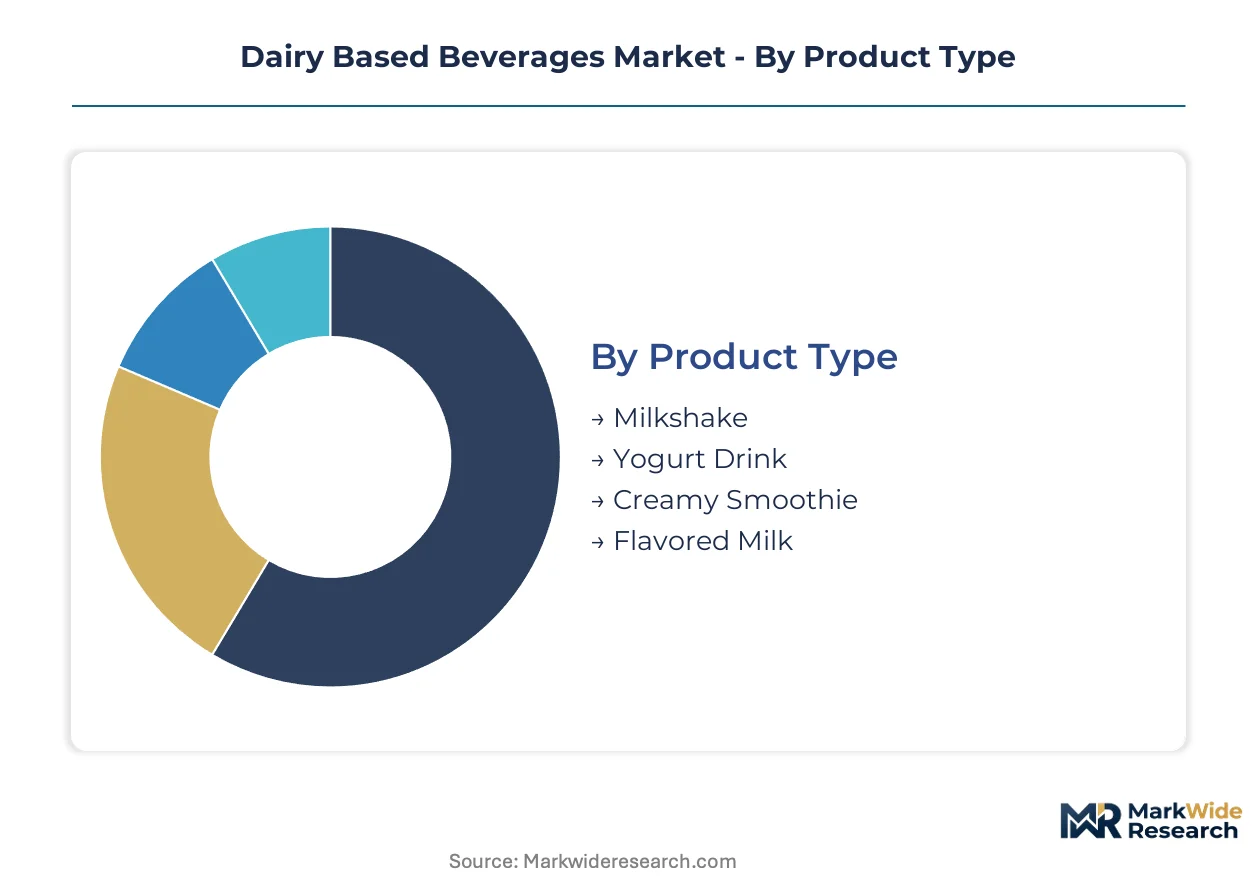
Segmentation in dairy based beverages reveals distinct margin architectures and channel strategies. Product type determines formulation complexity and shelf-life requirements. Application and customer type segments dictate packaging investments and promotional spend allocation.
Product Type:
Volume concentration sits with school-program and family formats, while premium positioning clusters around functional nutrition claims.
- Flavored Milk:Standardized formulations contain 2.5–3.5% milk fat with chocolate, strawberry, or vanilla flavor systems. Demand concentrates in US school nutrition programs and Indian urban households shifting from unpackaged milk, pulled by FSSAI fortification mandates for vitamins A and D.
- Yogurt Drink:Fermented dairy beverages carry 10^8–10^9 CFU probiotic counts per serving with 1.5–4% milk fat. Premium shelf positioning in European retail channels accelerates as EFSA novel food assessments validate strain-specific health claims.
- Milkshake:Higher-fat formulations at 4–8% milk fat target indulgence occasions through thicker viscosity and extended stability systems.
- Creamy Smoothie:Hybrid plant-dairy architectures reduce fluid milk solids content while retaining mouthfeel through oat protein concentrate integration.
Mature deployment sits with Flavored Milk. Newer deployment is concentrated in Creamy Smoothie.
Application:
Channel economics separate high-frequency convenience purchases from subscription-driven recurring revenue models.
- Online Retail:Direct-to-consumer platforms bypass supermarket slotting fees through personalized nutrition profiling and subscription lock-in. Indian tier-2 cities including Pune and Hyderabad show underdistributed penetration relative to Mumbai saturation.
- Supermarket:Branded ready-to-drink formats command prime cold-chain placement with standardized planogram compliance across European retail networks.
- Convenience Store:Single-serve protein-fortified and probiotic-positioned products target fitness-oriented young adults in gym-adjacent locations.
- Food Service:Quick-service restaurant chains unbundle beverage procurement from dairy supplier agreements, creating direct contracting opportunities for specialized ready-to-drink manufacturers.
Volume leadership rests with Supermarket. Steepest expansion trajectory belongs to Online Retail.
Customer Type:
Demographic targeting determines fortification levels, portion sizing, and claim substantiation requirements.
- Families:Multi-serve packaging formats with value-tier pricing dominate household refrigerator stock-up occasions.
- Young Adults:Functional beverage adoption pulls protein-fortified and probiotic-positioned products into convenience store and gym channel expansion.
- Children:School nutrition program eligibility drives formulation standardization around reduced-sugar targets and vitamin fortification.
- Diet-Conscious Consumers:Calorie-controlled and reduced-lactose variants command premium positioning through specialized retail placement.
Established demand centers on Families. Emerging demand concentrates with Young Adults.
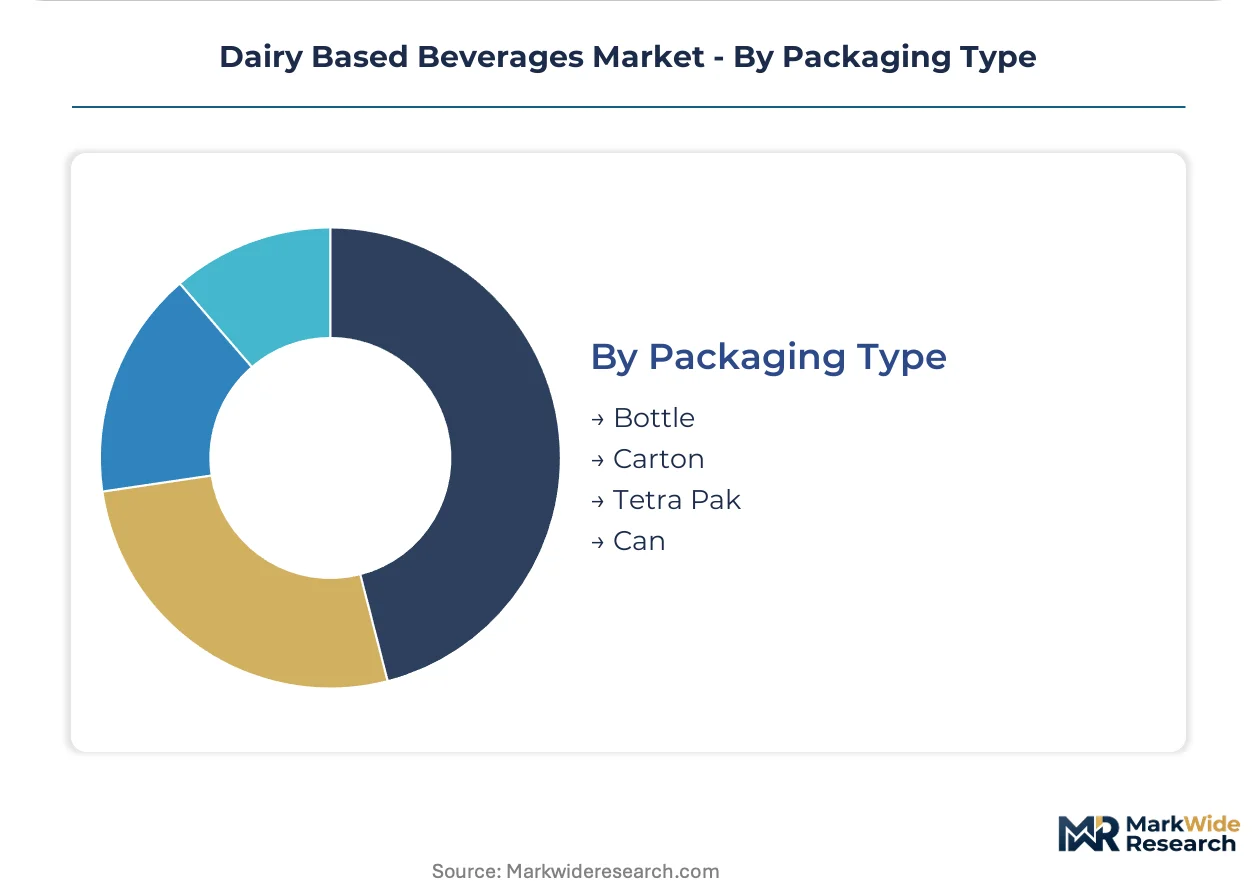
Packaging Type:
Material selection balances carbon-accounting compliance against shelf-life extension and logistics efficiency.
- Tetra Pak:Aseptic carton systems enable ambient distribution with 6–12 month shelf stability, critical for Indian market expansion beyond cold-chain constraints.
- Bottle:PET and HDPE formats support high-visibility branding in refrigerated retail sections with established recycling infrastructure.
- Carton:Gable-top refrigerated cartons serve fresh dairy positioning with shorter shelf-life requirements.
- Can:Aluminum formats target food service and convenience channel single-serve consumption with premium tactile differentiation.
Scale concentration sits with Tetra Pak. Sustainability-driven substitution targets Bottle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates demand growth as urban households abandon unpackaged milk for branded ready-to-drink formats. The United States anchors functional beverage innovation through protein-fortified and probiotic-positioned products. European markets face the steepest sustainability compliance burden under EU Green Deal carbon-accounting mandates.
United States
Fitness-oriented young adults pull protein-fortified beverages into convenience stores and gym-adjacent retail channels. FDA nutrition labeling rules and USDA school meal standards constrain permissible health claims and formulation targets. California and Texas metropolitan corridors host the densest concentrations of direct-to-consumer subscription platforms bypassing traditional supermarket slotting fees.
India
Urban households in Mumbai, Delhi, and Bangalore accelerate their shift from unpackaged milk to branded ready-to-drink formats. FSSAI fortification mandates for vitamins A and D create standardization tailwinds for compliant domestic and imported brands. Tier-2 cities including Pune, Hyderabad, and Ahmedabad remain underdistributed relative to tier-1 metro saturation levels.
Germany
EFSA novel food assessments validate strain-specific probiotic health claims for yogurt drink premium positioning. EU Green Deal sustainability disclosures and mandatory carbon-footprint reporting reshape supplier qualification criteria. Bavaria and North Rhine-Westphalia industrial clusters retrofit processing facilities to meet Scope 3 disclosure requirements before enforcement phases begin.
France
Plant-dairy hybrid R&D pipelines accelerate reformulation toward reduced fluid milk solids content. EFSA novel food assessments constrain ingredient sourcing flexibility and packaging choices across European markets. Paris and Lyon metropolitan retail networks exhibit the most advanced cold-chain placement for premium functional beverage formats.
China
Middle-class consumers in Yangtze River Delta and Pearl River Delta metropolitan clusters expand adoption of meal-replacement and targeted nutrition delivery formats. SAMR food safety standards and GB quality certifications determine market access for domestic and international brands. Shanghai and Shenzhen anchor the fastest-growing online retail channel penetration for direct-to-consumer dairy beverage subscriptions.
Dairy Based Beverages Market Competitive Environment
Backward integration into pasture-to-bottle supply chains dominates the current landscape as processors secure captive raw milk streams. The vendor base separates into three strategic archetypes: multinational conglomerates with hybrid plant-dairy R&D pipelines, cooperative structures with upstream supply control, and specialized ready-to-drink manufacturers with captive flavor development labs. M&A activity and geographic expansion into underdistributed tier-2 markets represent the two dominant competitive moves reshaping market share distribution.
Within the cooperative archetype, Fonterra Cooperative Group and Arla Foods amba exemplify upstream supply control models that limit third-party processor access to premium raw milk streams. Among multinational diversified players, Danone SA and Nestle SA occupy positions defined by hybrid plant-dairy innovation velocity and European market sustainability compliance leadership. At the specialized ready-to-drink end, Chobani Global Holdings represents Greek yogurt drink platform differentiation commanding premium shelf positioning in US retail channels.
| Leading Market Players |
|---|
| Lactalis |
| Dairy Farmers of America |
| Danone SA |
| Nestle SA |
| Arla Foods amba |
| Fonterra Cooperative Group |
| Chobani Global Holdings |
| General Mills |
| Agropur Dairy Cooperative |
| Others |
Value Chain & Pricing Dynamics
Fluid milk solids cost volatility traces a direct path from New Zealand and Australian pasture-based production through cooperative pricing structures to margin compression for mid-scale processors lacking forward-contract coverage. Butterfat and protein concentrate spot markets transmit upstream feed-cost fluctuations into finished beverage pricing tiers, with branded ready-to-drink formats commanding premium shelf positioning against private-label economy alternatives.
Pricing Analysis
Volume leadership sits with flavored milk in school nutrition and family purchasing, while yogurt drinks and creamy smoothie hybrids capture superior margins through probiotic positioning and plant-dairy reformulation premiums. Three-tier pricing structure across premium, standard, and economy levels separates functional fortification claims from basic refreshment positioning, with certification tier and brand premium as primary differentiation drivers. Pricing pressure stems from oat protein concentrate substitution in flexitarian segments, compressing fluid milk solids demand. Families exhibit highest price sensitivity through value-tier multi-serve formats, while young adults in fitness channels accept premium positioning for protein-fortified convenience.
Supply Chain Analysis
Regional distribution centers in Mumbai, Delhi, and Bangalore anchor hub-and-spoke patterns for Indian branded ready-to-drink expansion, with cold-chain infrastructure gaps constraining tier-2 city penetration. Raw milk sourcing concentrates in New Zealand, Australia, and India, with precision fermentation-derived whey proteins emerging as alternative protein inputs. Distribution runs through supermarket slotting-fee structures in mature markets while direct-to-consumer subscription models bypass traditional retail gatekeepers. Single-source vulnerability from cooperative-dominated pasture-to-bottle supply chains limits third-party processor access to premium raw milk streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation technology is displacing herd-dependent protein supply, compressing the historical separation between biotechnology and fluid milk operations as brands reformulate for sustainability procurement criteria.
For Market Incumbents: Hedge against plant-based substitution acceleration by deepening captive supply relationships in India and accelerating hybrid plant-dairy R&D pipeline velocity. Secure backward integration into tier-2 Indian distribution infrastructure before saturation. EU Green Deal carbon-accounting mandates threaten margin stability for non-compliant European processing assets. For New Entrants and Emerging Players: Precision fermentation-derived ingredient platforms offer technology-first wedge into premium sports recovery and specialty nutrition segments underserved by legacy dairy cooperatives. Target Pune, Hyderabad, and Ahmedabad for branded ready-to-drink distribution gaps relative to Mumbai saturation. Direct-to-consumer subscription models with personalized nutrition profiling bypass supermarket slotting barriers. For Investors and Strategic Acquirers: FSSAI fortification mandate compliance certification is the leading indicator that Indian market access will consolidate around standardized domestic and imported brands. Five-to-ten-year viability favors processors with hybrid formulation capabilities and carbon-accounting infrastructure. Acquisition target archetype: specialized ready-to-drink manufacturers with captive flavor development labs and quick-service restaurant chain partnerships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pasture-to-Bottle Supply | Fonterra and Arla cooperative structures limit third-party processor access to premium raw milk streams. |
| Hybrid Plant-Dairy R&D Pipeline Acceleration | Danone SA sustains innovation velocity across European markets as EU Green Deal tightens carbon-footprint standards. |
| Direct-to-Consumer Subscription Launch | Online retail bypasses supermarket slotting fees and captures recurring revenue through personalized nutrition profiling. |
| Precision Fermentation Protein Integration | Danish and Dutch specialty nutrition manufacturers adopt bioprocessing inputs at pilot scale for sports recovery drinks. |
| Tier-2 City Distribution Expansion | Pune, Hyderabad, and Ahmedabad remain underdistributed relative to Mumbai, Delhi, and Bangalore saturation levels. |
Study Parameters
Document review covered FSSAI fortification compliance filings, EU Green Deal sustainability disclosure frameworks, and customs trade data for fluid milk solids and protein concentrate movements, complemented by interviews with dairy processing plant managers, retail category buyers, food service procurement directors, and flavor development R&D leads. Secondary validation drew from SEC filings of multinational beverage conglomerates, Nielsen retail audit data for cold-chain placement metrics, and EFSA novel food assessment registers. Bottom-up volume modeling triangulated against top-down category spend analysis.
Cross-referencing historical volume trajectories against industry panel input established baseline growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, application channel, customer demographic, and packaging format, with regional regulatory cluster as an additional dairy-specific dimension. CAGRs derived from elasticity-adjusted demand curves incorporating protein-fortification adoption rates and urban household format-shift propensities in India.
Several conditions sit outside the modeled scope, including geopolitical disruption to New Zealand-Australian raw milk trade flows, breakthrough cost reductions in precision fermentation at commercial scale, and accelerated EU enforcement timelines for Scope 3 disclosure. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Nitro-Infused Beverages Market
Beverages
Premium Bottled Water Market
Beverages
Drinking Bottled Mineral Water Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market
Beverages
Commercial Drink Mixers Market
Beverages
Middle East and Africa Fruits and Vegetable Juice Market
Beverages
Fermented Foods and Beverages Market
Beverages
Apple Cider Vinegar Market
Beverages
Fruit Water Market
Beverages
India Sports Drinks Market
Beverages
Semillon Market
Beverages
Craft Soda Market
Beverages
North America Fruit Juice Market
Beverages
Root Beer Market
Beverages
BBQ Charcoal Market
Beverages
Europe Animal-Based Food and Beverage Market