
 Canada Dairy Alternatives Market | 2026-2036
Canada Dairy Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Dairy Alternatives Market Insights
Ontario's expanding oat processing infrastructure is reshaping domestic supply availability for Canada dairy alternatives. Earth's Own Food Co. leverages its Prairie oat sourcing to sustain cost-competitive production. SunOpta Inc. anchors its North American ingredient platform with Canadian extraction capacity. Danone SA competes through established refrigerated distribution networks.
Canada dairy alternatives comprise plant-derived beverages and ingredients formulated from oats, soy, almonds, or coconuts through enzymatic hydrolysis, milling, and homogenization to achieve protein content, viscosity, and fat profiles mimicking bovine milk for direct consumption and food manufacturing. Oat milk dominates product type expansion due to neutral flavor compatibility and lower allergenicity versus nut or soy bases. Supermarkets anchor distribution channel volume, though online retailers capture accelerated growth from subscription replenishment models.
Health Canada governs nutritional labeling and fortification standards for dairy alternatives, while CFIA enforces allergen declaration and plant-based protein safety protocols. The Canadian Food Guide revision shapes institutional procurement toward plant-forward options. Stakeholders must monitor pending CFIA guidance on fermentation-derived dairy proteins and their classification relative to traditional plant milks.
Market Dynamics
Health Canada's Food Guide revision is reallocating institutional procurement toward plant-forward nutrition categories, while Prairie oat processing investments compress domestic ingredient costs and reshape competitive positioning among beverage formulators.
Growth Catalysts
- Health Canada Food Guide:The 2019 revision de-emphasized dairy as a distinct food group, accelerating K-12 school board and hospital cafeteria procurement shifts toward oat and soy beverages.
- Prairie oat milling expansion:Processing capacity additions in Manitoba and Saskatchewan are reducing import dependency for base ingredients, lowering formulation costs for domestic brands.
- Foodservice menu engineering:Quick-service restaurant chains and specialty coffee operators are standardizing oat milk as the default plant-based option, creating pull-through demand at retail.
Market Restraints
- Input cost volatility:Organic oat and almond prices fluctuate with Prairie drought cycles and California water allocation decisions, compressing margin stability for mid-tier producers.
- Supply concentration risk:Domestic oat protein extraction capacity clusters in southern Ontario, creating single-point vulnerability for ingredient security.
- Regulatory friction:CFIA's pending classification of fermentation-derived dairy proteins threatens to bifurcate labeling standards and complicate shelf positioning for traditional plant milks.
Strategic Opportunities
- Atlantic Canada underpenetration:Alternative milk household penetration in Nova Scotia and New Brunswick trails Ontario by double digits, offering whitespace for regional distribution partnerships.
- Precision fermentation convergence:Hybrid products combining plant bases with microbial dairy proteins could capture consumers seeking taste parity without bovine sourcing.
- Subscription channel innovation:Direct-to-consumer replenishment models are capturing urban households seeking convenience and packaging sustainability.
Industry Challenges
- Formulation talent scarcity:Food scientists with enzymatic hydrolysis and lipid stabilization expertise command premium compensation, constraining R&D velocity for emerging brands.
- Fortification compliance timelines:Health Canada's evolving standards for calcium, vitamin D, and protein equivalence claims extend product launch cycles by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Dairy Alternatives Market |
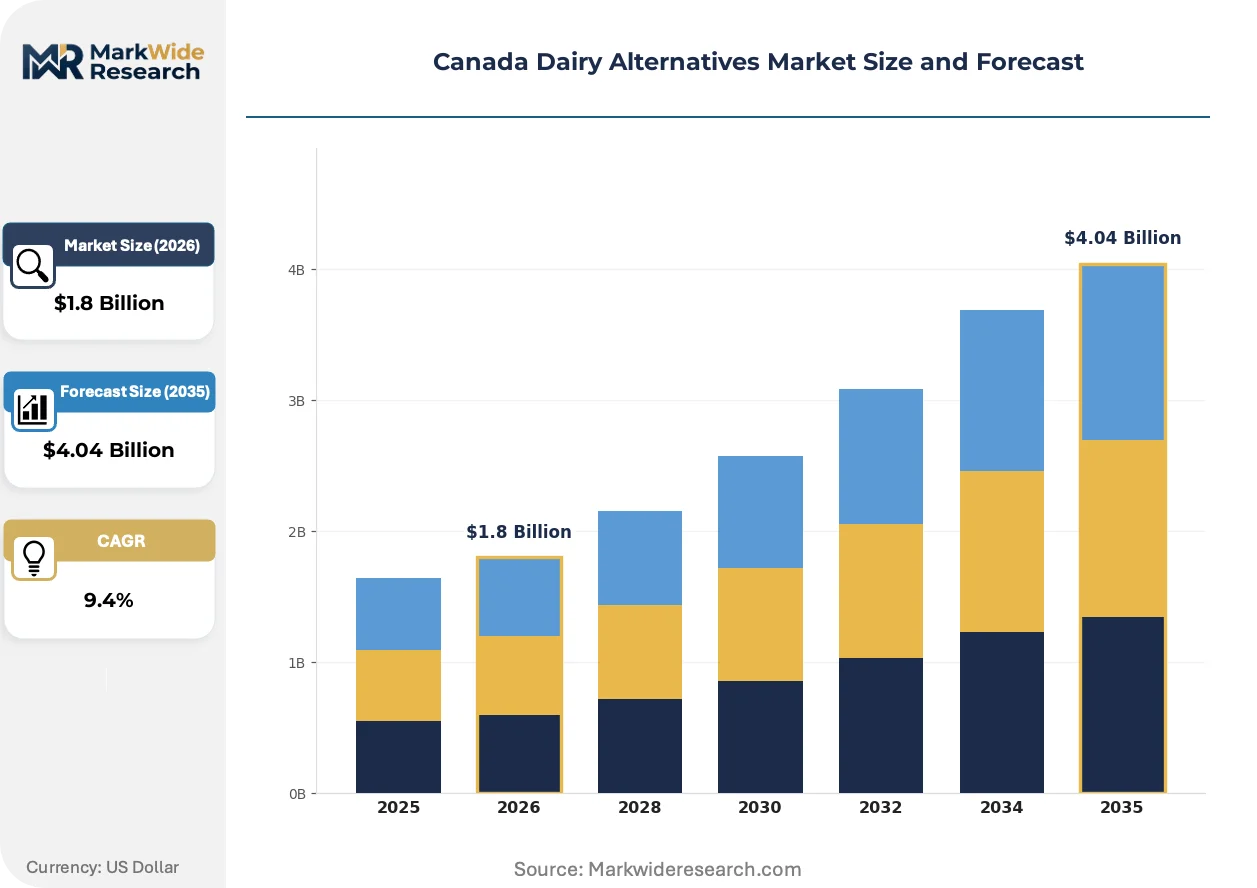
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Oat Milk, Coconut Milk Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Stores Consumer Type: Vegans, Lactose Intolerant, Health-Conscious Consumers, Flexitarians End Use Application: Cooking, Baking, Beverages, Smoothies |
| Companies Covered | Danone SA, Earth’s Own Food Co., SunOpta Inc., Blue Diamond Growers, Groupe Lactalis, Agrifoods International Cooperative Ltd, Nutrisoya Foods Inc., Sunrise Soya Foods, Oat Canada Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Dairy Alternatives Market Trends and Innovations
Enzymatic processing advances and regulatory clarity around novel proteins are compressing formulation cycles, while procurement patterns shift toward consolidated supplier relationships and sustainability-verified sourcing.
Enzymatic hydrolysis of oat starches is virtualizing texture engineering in plant milk production. Barista-grade oat formulations now achieve microfoam stability without added gums or oils. Specialty coffee chains in Toronto and Vancouver are adopting these next-generation bases, collapsing the performance gap with conventional dairy in high-heat applications.
Health Canada's pending guidance on fermentation-derived dairy proteins is forcing label architecture decisions. The classification ambiguity threatens to segment retail shelving between traditional plant milks and bio-identical alternatives. Domestic formulators are hedging with dual-track product development pending regulatory resolution.
Consolidated procurement contracts are displacing spot-market ingredient purchasing among mid-size beverage brands. British Columbia and Ontario manufacturers are locking multi-year oat supply agreements with Prairie processors. This shift is most visible in organic and non-GMO certified product lines where traceability requirements exceed commodity market capabilities.
Canada Dairy Alternatives Market Segmentation
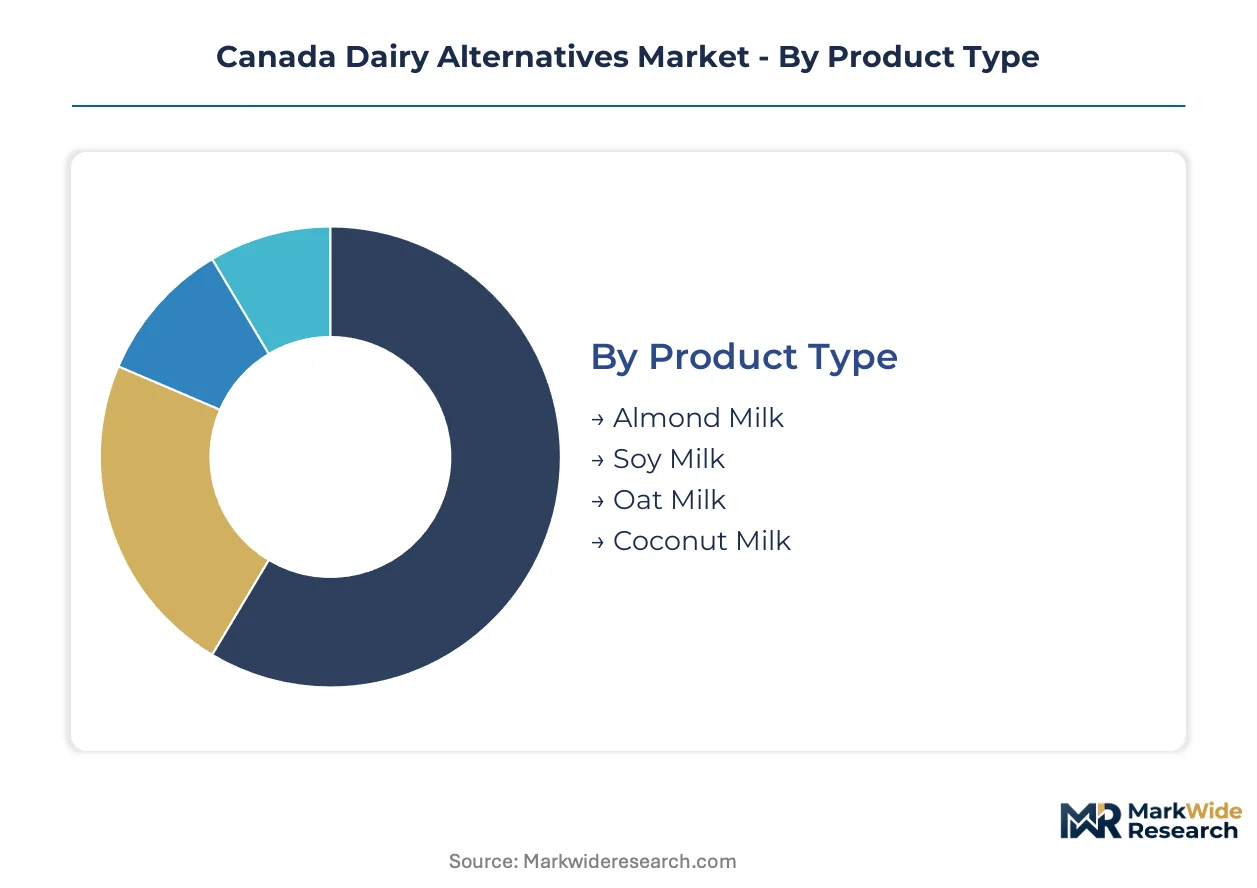
Canada dairy alternatives fragment across formulation chemistry, purchase context, and dietary motivation. Each segmentation axis reveals distinct margin structures and channel control points that shape competitive strategy.
Product Type:
Formulation chemistry determines protein equivalence, viscosity performance, and allergen profile for Health Canada labeling compliance.
- Oat Milk:Enzymatic hydrolysis of Prairie-sourced starches yields neutral flavor and microfoam stability. Toronto and Vancouver barista channels are standardizing this base for high-heat applications, compressing the performance gap with conventional dairy.
- Soy Milk:Higher protein content meets institutional procurement standards for K-12 and hospital nutrition programs. Health Canada fortification requirements for calcium and vitamin D equivalence extend launch timelines for reformulated variants.
- Almond Milk:Lower calorie positioning captures health-conscious households in British Columbia. California water allocation volatility transmits directly to base ingredient cost structures.
- Coconut Milk:Tropical flavor profile concentrates in ethnic cuisine applications and premium dessert formulations. Limited domestic processing capacity constrains cost-competitive positioning.
Oat milk commands the established base. The steepest expansion runs through soy milk as institutional procurement accelerates.
Distribution Channel:
Channel selection governs margin capture, shelf positioning autonomy, and consumer data access for subscription conversion.
- Supermarkets:Refrigerated case placement in Loblaws, Sobeys, and Metro chains anchors volume throughput. Planogram negotiations with category managers determine facings allocation between plant-based and conventional dairy.
- Online Retailers:Direct-to-consumer replenishment models capture urban households seeking packaging sustainability and convenience. Subscription algorithms optimize reorder timing based on consumption velocity data.
- Health Food Stores:Organic and non-GMO certified SKUs concentrate in specialty retail with higher shelf fees but lower competitive density. Prairie traceability requirements exceed commodity market capabilities here.
- Specialty Stores:Ethnic grocers and independent retailers serve diaspora communities with imported coconut and soy variants. Limited distribution infrastructure constrains national brand penetration.
Supermarkets anchor volume throughput. The steepest expansion trajectory runs through online retailers capturing subscription household lock-in.
Consumer Type:
Dietary motivation segments reveal price elasticity differentials and cross-category purchase patterns.
- Health-Conscious Consumers:Fortification claims and clean-label positioning drive premium willingness-to-pay. These households cross-shop organic produce and functional beverage categories.
- Lactose Intolerant:Medical necessity creates inelastic demand with lower brand switching frequency. Physician and dietitian recommendations influence initial trial and subsequent loyalty.
- Vegans:Ethical sourcing verification and animal welfare certifications command disproportionate attention. These consumers demonstrate highest engagement with brand sustainability reporting.
- Flexitarians:Occasional plant-based substitution creates volume volatility but expands category trial. Restaurant menu exposure drives retail conversion for this segment.
Health-conscious consumers anchor premium tier revenue. The steepest expansion runs through flexitarians as foodservice menu engineering drives trial.
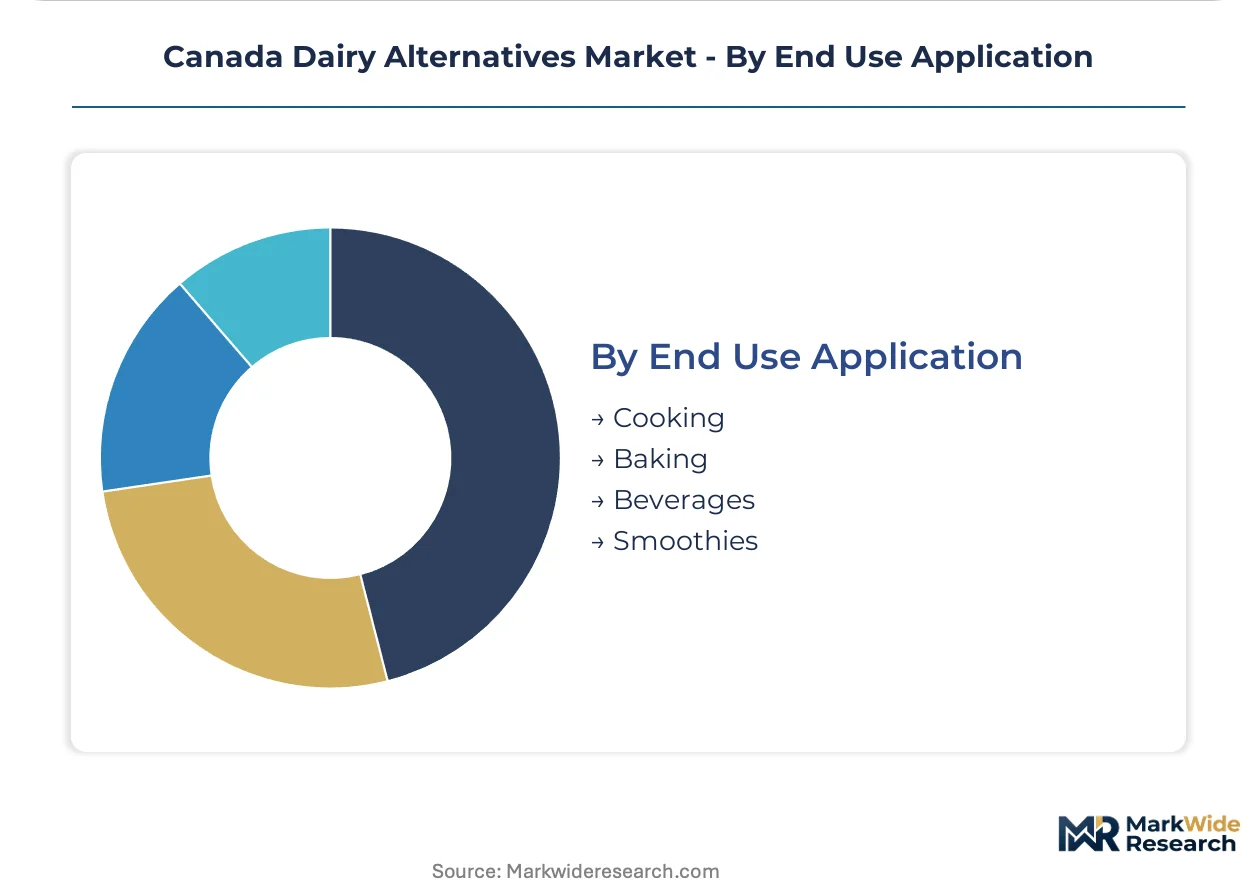
End Use Application:
Functional performance requirements vary sharply across preparation temperature, acidity tolerance, and fat emulsion stability.
- Beverages:Direct consumption demands flavor neutrality and chilled shelf stability. Barista-grade formulations require microfoam performance without added gums.
- Cooking:Heat stability and sauce reduction behavior determine suitability for soups and curries. Oat bases demonstrate superior performance in high-temperature applications.
- Baking:Protein content and leavening interaction affect texture outcomes in cakes and pastries. Soy milk's higher protein concentration supports structural integrity.
- Smoothies:Viscosity and blend compatibility with frozen fruit concentrates demand specific hydrocolloid stabilization. Health food store distribution skews toward this application.
Beverage applications command volume concentration. The steepest expansion runs through cooking as Prairie oat processing investments improve heat-stable formulation economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prairie oat processing capacity clusters in Manitoba and Saskatchewan, compressing ingredient costs for domestic formulators while Ontario and British Columbia concentrate demand through foodservice and retail channel density.
Ontario
Toronto's specialty coffee chains are standardizing barista-grade oat milk as the default plant-based option, pulling through retail demand. Health Canada fortification standards govern calcium and vitamin D equivalence claims for K-12 school procurement. Southern Ontario hosts the country's densest oat protein extraction infrastructure, with multiple enzymatic hydrolysis facilities serving national beverage brands.
British Columbia
Vancouver's health-conscious households drive premium positioning for organic and non-GMO certified alternative milks. The provincial government's CleanBC initiative shapes institutional procurement toward lower-carbon food options. Metro Vancouver's independent roasters and third-wave cafés anchor West Coast barista formulation standards that diffuse eastward.
Quebec
Montreal's foodservice distributors are expanding plant-based portfolios to serve the province's restaurant recovery. The Ministère de l'Agriculture, des Pêcheries et de l'Alimentation du Québec monitors dairy alternative labeling under provincial consumer protection frameworks. Laval and Quebec City retail corridors concentrate shelf-space negotiations with national grocery banners.
Prairie Provinces
Manitoba and Saskatchewan oat milling investments are reducing import dependency for base starches and proteins. Agriculture and Agri-Food Canada programs support value-added processing infrastructure expansion. Brandon, Regina, and Saskatoon processing hubs are locking multi-year supply agreements with Ontario and British Columbia beverage manufacturers.
Atlantic Canada
Halifax and St. John's alternative milk penetration trails national averages by double digits, creating whitespace for regional distribution partnerships. Health Canada's Food Guide revision is slowly penetrating institutional procurement in provincial health authorities. Limited cold-chain infrastructure constrains refrigerated case expansion outside major urban centers.
Canada Dairy Alternatives Market Competitive Landscape
Multinational beverage conglomerates and domestic oat specialists split the market between scale-driven distribution and ingredient-origin positioning. The structure tilts toward consolidation at the retail tier while fragmentation persists in specialty and organic sub-segments. Two archetypes dominate: global dairy-alternative platforms leveraging refrigerated logistics networks, and Prairie-rooted formulators emphasizing domestic oat provenance. Competitive moves center on multi-year supply contract lock-ins with Prairie processors and barista-grade formulation partnerships with specialty coffee chains.
Within the domestic specialist tier, Earth's Own Food Co. and SunOpta Inc. exemplify Prairie-sourcing strategies that compress input costs and sustain price competitiveness against larger rivals. Danone SA anchors the multinational platform archetype, occupying a position defined by established cold-chain distribution density. These three companies represent the competitive spectrum from captive ingredient control to logistics-scale dominance.
| Leading Market Players |
|---|
| Danone SA |
| Earth's Own Food Co. |
| SunOpta Inc. |
| Blue Diamond Growers |
| Groupe Lactalis |
| Agrifoods International Cooperative Ltd |
| Nutrisoya Foods Inc. |
| Sunrise Soya Foods |
| Oat Canada Inc. |
| Others |
Pricing and Supply Chain Analysis
The CN Rail corridor linking Prairie oat processing hubs to Ontario distribution centers governs freight cost pass-through to retail shelf price tiers, concentrating margin pressure on mid-tier brands lacking multi-year supply contracts while enabling premium positioning for traceability-certified lines.
Pricing Analysis
Health Canada fortification standards dictate the pricing tier structure across the Canada dairy alternatives landscape. Three-tier pricing separates organic non-GMO certified premiums from conventional barista-grade standards and private-label economy offerings. Price differentiation rests on Prairie provenance verification and CleanBC-aligned carbon labeling. Cost compression in the standard tier is intensifying because Prairie drought cycles transmit volatility into organic oat base inputs. Lactose-intolerant households demonstrate lowest price sensitivity, while flexitarian trialists exhibit highest elasticity.
Supply Chain Analysis
Domestic toll processing capacity clusters with SunOpta Inc. and Earth's Own Food Co. facilities anchoring enzymatic hydrolysis throughput. Ingredient sourcing draws from Manitoba and Saskatchewan oat milling investments, with secondary dependence on California almond processors for nut-based lines. Single-source vulnerability concentrates in southern Ontario protein extraction infrastructure. Distribution runs through Loblaws, Sobeys, and Metro refrigerated networks, with direct-to-consumer subscription channels capturing accelerated growth in Toronto and Vancouver urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
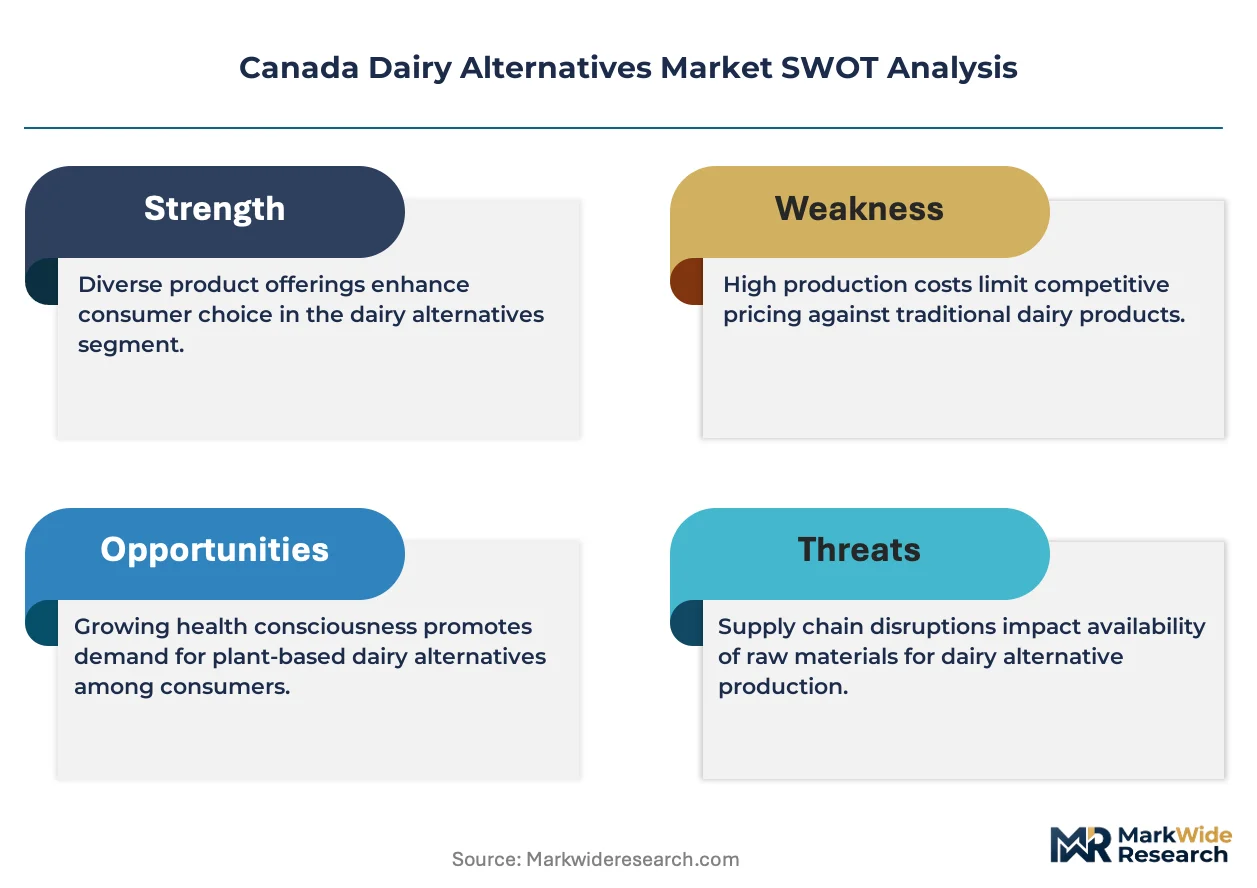
The Canada dairy alternatives market rewards regulatory entrenchment as its primary defensive moat. Health Canada fortification compliance timelines and CFIA allergen protocols create switching costs that favor established players with dedicated regulatory affairs infrastructure.
For Market Incumbents: Insulate margin position through captive oat supply agreements with Brandon and Regina processing hubs. Lock multi-year Prairie sourcing contracts before drought-driven spot price volatility escalates. Prioritize barista-grade formulation R&D to defend against precision fermentation substitutes threatening taste parity claims.
For New Entrants and Emerging Players: Atlantic Canada grocery corridors represent the most penetrable entry point, with Halifax and St. John's penetration trailing Ontario by double digits. Specialty coffee chain partnerships in Montreal and Quebec City offer lower competitive density than Toronto barista channels. Lead with subscription replenishment models to bypass refrigerated case slotting fees at national banners.
For Investors and Strategic Acquirers: Prairie-rooted formulators with integrated oat milling assets command scarcity premiums as ingredient security concerns intensify. Long-term viability hinges on fermentation-derived protein classification resolution by CFIA. Watch Health Canada guidance on novel protein labeling as the decisive inflection signal for portfolio rebalancing between traditional plant milks and bio-identical alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Prairie Supply Contract Lock-In | Multi-year oat agreements with Manitoba processors compress input cost volatility for Ontario formulators. |
| Barista-Grade Formulation Partnership | Toronto specialty coffee chain adoption validates microfoam performance and pulls retail trial. |
| Direct-to-Consumer Channel Launch | Subscription algorithms optimize reorder timing based on consumption velocity data from urban households. |
| Precision Fermentation Dual-Track Development | Hedging against CFIA classification ambiguity protects shelf positioning regardless of regulatory outcome. |
| Atlantic Distribution Partnership | Regional alliances with Maritime foodservice distributors exploit whitespace in Nova Scotia retail penetration. |
Research Methodology
A spread of perspectives from beverage formulators, Prairie oat processors, Loblaws category managers, and Health Canada regulatory consultants converged on the working assumptions. Primary interviews with plant-based R&D directors and CFIA compliance officers combined with secondary validation from Agriculture and Agri-Food Canada processing infrastructure reports, Nielsen retail audit data, and SEC filings of listed ingredient suppliers. Bottom-up volume modeling triangulated against top-down category spend estimates.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry, distribution channel, dietary motivation, and end-use application. CAGRs derived from iterative reconciliation of historical Prairie oat price series, foodservice procurement volume trends, and institutional adoption curves. Forecast inputs incorporated Health Canada Food Guide penetration rates and CleanBC institutional procurement mandates.
Practitioners should monitor CFIA fermentation-derived protein guidance and Prairie precipitation indices for early signals of forecast revision. Quarterly review of Loblaws planogram reallocation rates and Toronto barista channel formulation switches is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Dairy-Free Chocolate Market
Dairy Alternatives
Vegan Cheese Market
Dairy Alternatives
South Korea Dairy Alternatives Market
Dairy Alternatives
United States Oat Milk Market
Dairy Alternatives
Pea Milk Market
Dairy Alternatives
Dry Yogurt Market
Dairy Alternatives
Australia Dairy Alternatives Market
Dairy Alternatives
Germany Non-Dairy Milk Market
Dairy Alternatives
Non-Dairy Creamer Market
Dairy Alternatives
Plant Milk Market
Dairy Alternatives
Savory Yogurt Foods Market
Dairy Alternatives
Coconut Milk Powder Market
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
Clarified Butter Market
Dairy Alternatives
Coconut Milk Derivatives Market
Dairy Alternatives
Global Milk Replacers Market