
 North America Sugar Free Energy Drinks Market | 2026-2036
North America Sugar Free Energy Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sugar Free Energy Drinks Market Insights
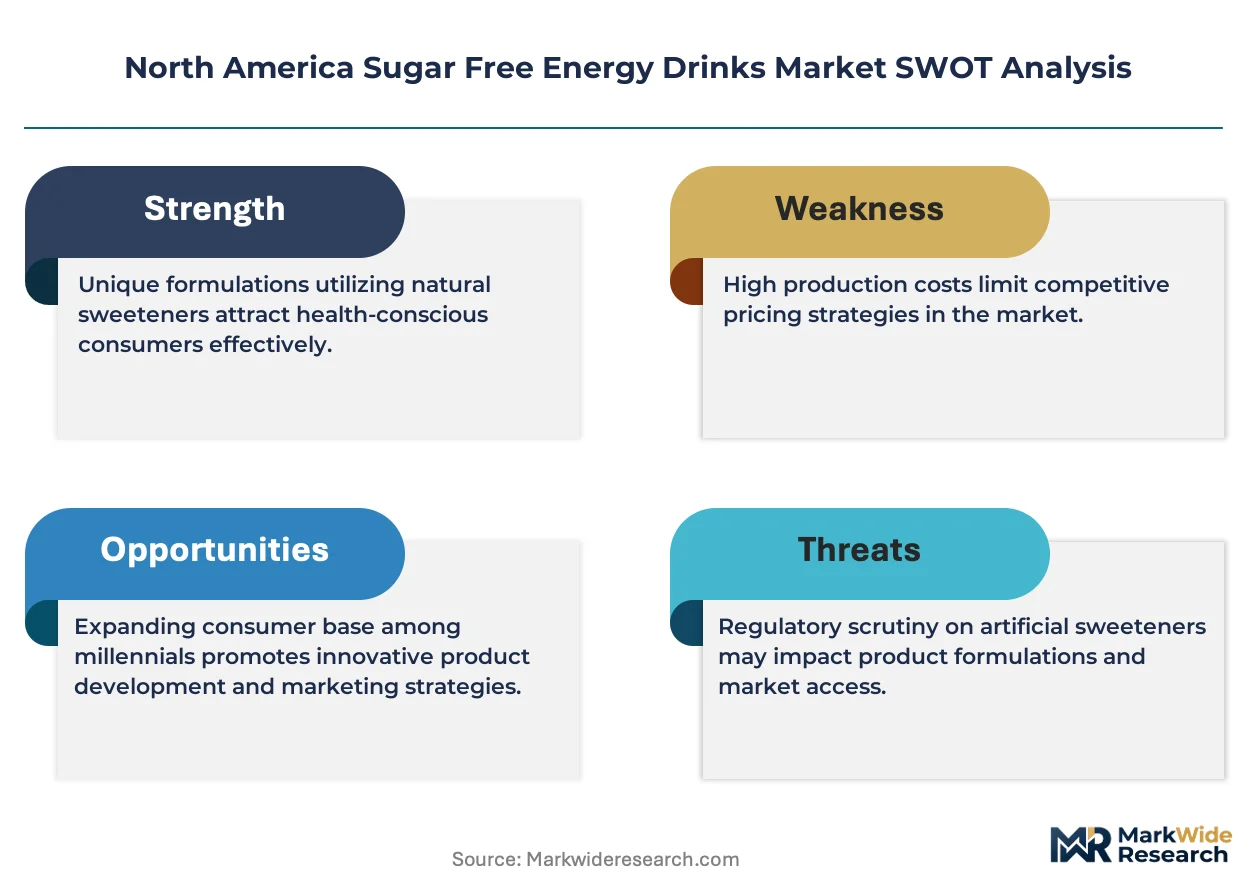
FDA caffeine disclosure mandates is consolidating the cost-of-entry calculus for sugar-free energy drink startups, forcing smaller brands to absorb expensive reformulation and labeling audits before reaching shelves. PepsiCo, Inc. leverages its vertically integrated beverage distribution network to sustain shelf dominance across mass retail channels. Monster Beverage Corporation anchors its position through deep convenience store relationships and motorsports sponsorship equity. Celsius Holdings Inc. differentiates via fitness-centric positioning and clean-label ingredient narratives that resonate with performance-oriented consumers.
North America sugar free energy drinks are non-alcoholic, carbonated or still beverages formulated with caffeine, amino acids, vitamins, and non-caloric sweeteners designed to enhance mental alertness and physical performance without glucose loading. Manufacturing relies on acidified water systems, precise caffeine standardization, and aseptic cold-fill or hot-fill processing to preserve functional ingredient stability across shelf life. Carbonated variants occupy the largest volume share given established consumer habituation and fountain infrastructure, while non-carbonated formats are expanding fastest as they align with hydration-positioned product strategies. Natural extracts as an ingredient focus command premium shelf pricing and margin pools, whereas artificial sweetener-dependent formulations face reformulation pressure from clean-label consumer sentiment.
The FDA governs caffeine content limits and GRAS status for sweetener additives, while Health Canada and PMRA enforce parallel standards that shape cross-border product standardization and labeling uniformity. USDA organic certification and state-level sugar taxes in select jurisdictions further bifurcate permissible formulation pathways and channel access. Stakeholders must monitor pending FDA guidance on synthetic caffeine sourcing disclosure and preemptively audit supply chains for natural extract provenance to defend market access.
Market Dynamics
FDA caffeine disclosure mandates and Health Canada sweetener standards are compressing formulation flexibility, forcing brands to absorb expensive reformulation audits and dual-label compliance before shelf placement across US and Canadian retail channels.
Growth Catalysts
- Fitness-Centric Demand Rotation:Gym-goers and performance athletes are abandoning caloric pre-workout formulas in favor of clean-label, non-carbonated functional beverages that align with hydration-focused training regimens.
- Clean-Label Ingredient Premiumization:Natural extract sourcing commands measurable shelf price premiums as artificial sweetener-dependent formulations face consumer sentiment pressure and reformulation requirements.
- Convenience Store Channel Density:Motorsports and action sports sponsorship equity drives impulse purchase velocity through high-traffic fuel and convenience retail networks concentrated in coastal metropolitan corridors.
Market Restraints
- Input Cost Volatility in Natural Extracts:Stevia and monk fruit supply concentrates in select Southeast Asian growing regions, exposing margins to climate-driven harvest variability and freight cost spikes.
- Regulatory Friction from FDA GRAS Scrutiny:Evolving guidance on synthetic caffeine sourcing disclosure and artificial sweetener safety reviews extends new product approval timelines and raises legal exposure for emerging brands.
- Technical Limitation in Aseptic Cold-Fill Scaling:Preserving functional ingredient stability across extended shelf life requires capital-intensive processing infrastructure that smaller entrants cannot readily replicate.
Strategic Opportunities
- Underpenetrated Canadian Convenience Retail:Health Canada parallel standards create cross-border product standardization advantages for US brands with existing dual-label compliance infrastructure.
- Emerging Hydration-Positioned Formats:Non-carbonated still beverages align with wellness-oriented consumption patterns in Pacific Coast metropolitan clusters where functional hydration commands premium positioning.
- State-Level Sugar Tax Arbitrage:Select US jurisdictions with beverage excise taxes on caloric drinks create channel access advantages for zero-sugar formulations in taxed metro areas.
Industry Challenges
- Specialized Formulation Chemistry Talent Scarcity:Acidified water system engineering and caffeine standardization expertise concentrates among legacy beverage technologists, constraining R&D velocity for new entrants.
- USDA Organic Certification Timeline Compression:Supply chain audits for natural extract provenance and organic sweetener verification extend go-to-market schedules by 12-18 months for clean-label product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sugar Free Energy Drinks Market |
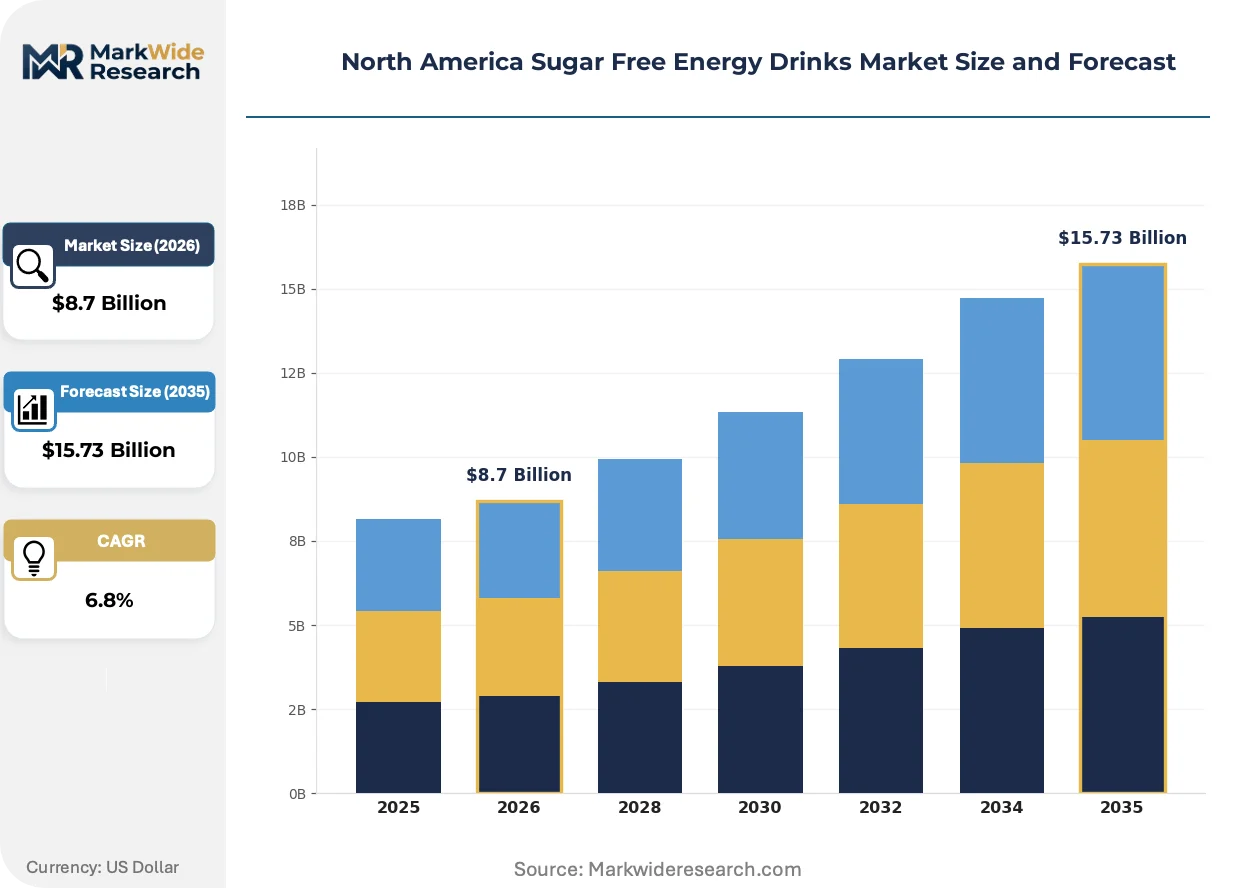
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated, Non-Carbonated, Ready-to-Drink, Powdered Ingredient Focus: Natural Extracts, Artificial Sweeteners, Caffeine Sources, Vitamins Consumer Age Group: Teens, Young Adults, Middle-Aged, Seniors Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Fitness Centers |
| Companies Covered | PepsiCo, Inc., Congo Brands, Monster Beverage Corporation, Living Essentials LLC, Ghost Beverages LLC, Red Bull GmbH, Celsius Holdings Inc., Performix LLC, The Coca-Cola Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sugar Free Energy Drinks Market Trends and Innovations
Reformulation chemistry and processing technology are converging to enable functional stability without artificial preservatives, while regulatory disclosure requirements and channel-specific consumption patterns reshape competitive positioning across North American retail.
Natural caffeine extraction from green coffee beans and yerba mate is electrifying clean-label formulation strategies as brands seek to displace synthetic caffeine in premium positioning. Fitness-oriented consumers and boutique gym operators are accelerating adoption of these botanical sources. This ingredient shift is electrifying margin compression for artificial-sweetener-dependent legacy portfolios while enabling premium shelf price capture for extract-based alternatives.
The FDA's pending guidance on synthetic caffeine sourcing disclosure is tightening GRAS documentation requirements for non-natural stimulant additives. Manufacturers must now maintain batch-level provenance records and third-party testing protocols to defend market access. Carbonated variants with artificial caffeine sources face the most acute compliance exposure, driving accelerated reformulation timelines ahead of anticipated enforcement windows.
Direct-to-subscription models through fitness apps and wearable-integrated wellness platforms are fragmenting traditional convenience store dominance among performance-oriented consumers. Boutique cycling studios and CrossFit affiliates are replacing gas station coolers as initial trial points for emerging brands. This channel rotation is most visible in California, Texas, and Florida metropolitan corridors where digital-native purchasing patterns concentrate among millennial and Gen Z demographics.
North America Sugar Free Energy Drinks Market Segmentation
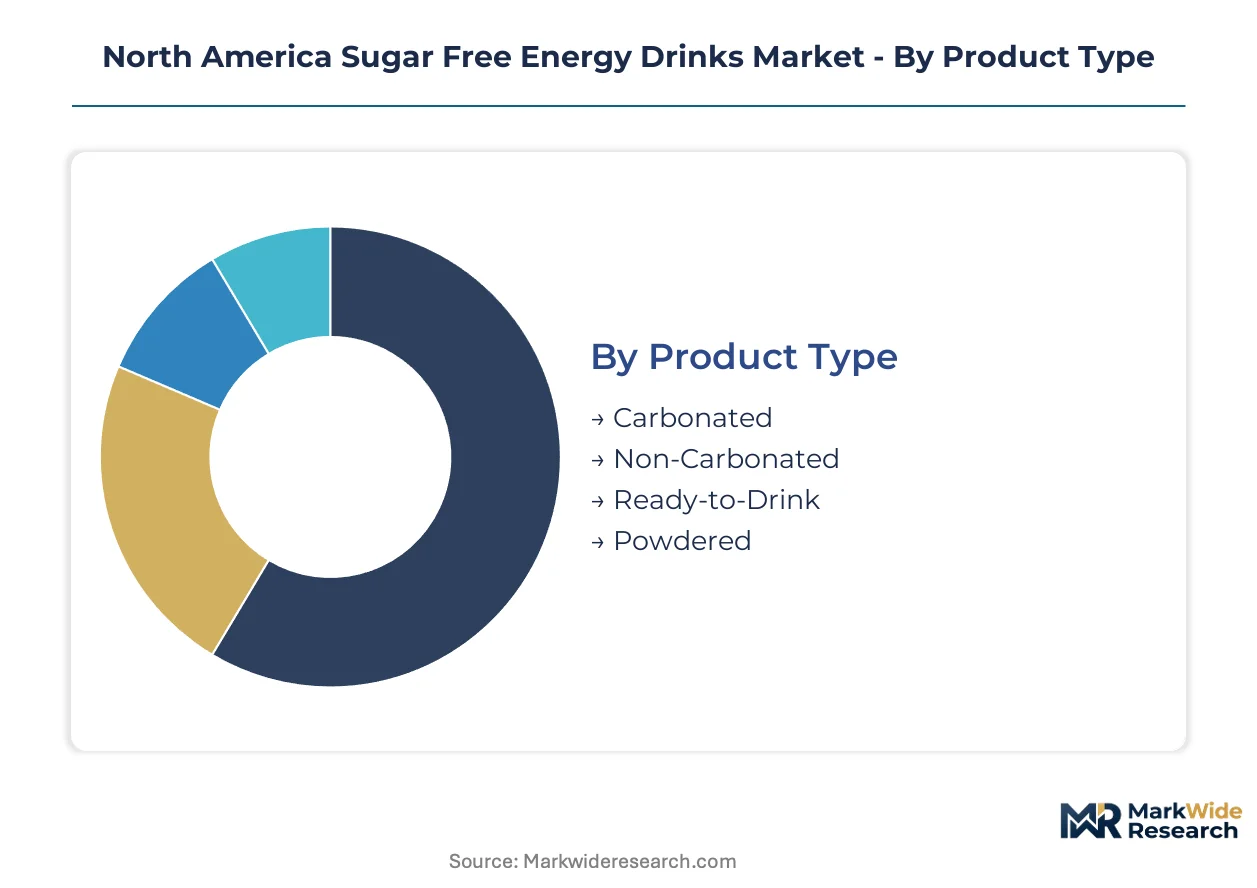
Segmentation in sugar-free energy drinks reveals how formulation chemistry, channel infrastructure, and demographic clustering create distinct margin pools. Manufacturers must align processing capabilities and compliance postures with the specific technical and regulatory demands of each segment tier.
Product Type:
Carbonation status and format portability separate buyers by consumption occasion and shelf-life requirements.
- Carbonated:Acidified water systems with precise CO2 saturation deliver the sensory bite consumers associate with energy delivery. Coastal metropolitan corridors in the United States concentrate demand here, driven by established fountain infrastructure and impulse purchase habits at convenience retail.
- Non-Carbonated:Still formulations rely on aseptic cold-fill processing to preserve functional ingredient stability without carbonation's antimicrobial effects. Pacific Coast wellness clusters and hydration-focused training regimens in boutique fitness studios are accelerating adoption of these formats.
- Ready-to-Drink:Pre-mixed liquid formats dominate mass retail velocity through standardized unit economics and minimal preparation friction.
- Powdered:Dry concentrate formats appeal to bulk purchasers seeking dose customization and reduced shipping weight for subscription delivery models.
Volume sits with carbonated variants; growth tilts toward non-carbonated still beverages.
Ingredient Focus:
Clean-label positioning and FDA disclosure mandates are fragmenting procurement strategies across natural and synthetic input streams.
- Natural Extracts:Stevia, monk fruit, and botanical caffeine sources command premium shelf pricing but expose margins to Southeast Asian supply concentration and climate-driven harvest variability. USDA organic certification requirements extend go-to-market timelines for brands pursuing this positioning.
- Artificial Sweeteners:Aspartame, sucralose, and acesulfame potassium formulations face escalating reformulation pressure from consumer sentiment shifts and pending FDA GRAS scrutiny. Legacy portfolios dependent on these inputs confront margin compression as clean-label alternatives capture performance-oriented consumers.
- Caffeine Sources:Green coffee bean and yerba mate extracts electrify premium positioning while synthetic caffeine batches require intensified provenance documentation under evolving FDA guidance.
- Vitamins:B-complex and amino acid fortification differentiates functional claims but demands precise stability engineering across shelf life.
Revenue concentrates in natural extract formulations; artificial sweetener-dependent lines are shedding share fastest.
Consumer Age Group:
Life stage determines caffeine tolerance, brand loyalty patterns, and channel access preferences.
- Teens:Regulatory scrutiny around caffeine exposure limits and school district beverage policies constrain market access for this cohort.
- Young Adults:Millennials and Gen Z consumers in coastal metropolitan corridors drive clean-label adoption and digital-native subscription purchasing through fitness app integrations.
- Middle-Aged:Career professionals seeking sustained alertness without caloric loading represent stable repeat purchase velocity in convenience and mass retail channels.
- Seniors:Cardiovascular caution and medication interaction concerns limit penetration, though low-caffeine functional hydration formats show emerging traction.
Young adults anchor volume contribution; middle-aged consumers sustain baseline replenishment rates.
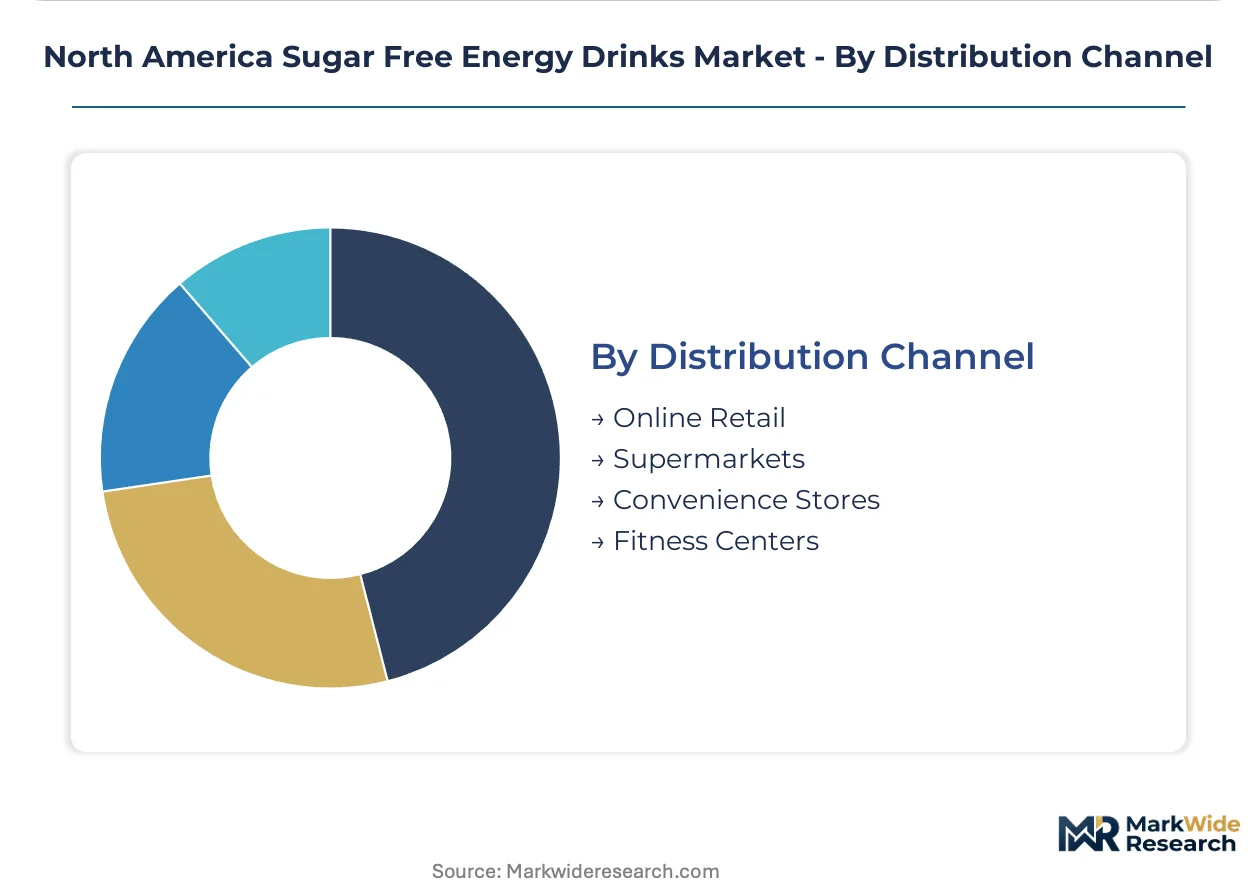
Distribution Channel:
Channel selection determines compliance burden, margin structure, and brand positioning latitude.
- Online Retail:Direct-to-consumer and third-party marketplace sales enable subscription mechanics and personalized bundling. Fitness app integrations and wearable wellness platform partnerships are fragmenting traditional channel dominance among performance-oriented buyers in California, Texas, and Florida metropolitan clusters.
- Supermarkets:Mass retail placement demands slotting fee absorption and standardized dual-label compliance for US-Canada cross-border distribution.
- Convenience Stores:High-traffic fuel retail networks concentrate impulse velocity through motorsports sponsorship equity and cooler placement density.
- Fitness Centers:Boutique cycling studios and CrossFit affiliates are replacing gas station coolers as initial trial points for emerging brands targeting gym-goers abandoning caloric pre-workout formulas.
Convenience stores capture the highest transaction frequency; fitness centers are climbing the fastest as acquisition channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in coastal metropolitan corridors where health-conscious millennials and Gen Z consumers cluster, with fitness-oriented purchasing patterns reshaping regional distribution strategies. The FDA's evolving caffeine labeling mandates and Health Canada parallel standards create cross-border compliance complexity that favors established players with dual-label infrastructure. State-level sugar tax arbitrage and organic certification requirements further fragment formulation pathways across sub-regional markets.
United States
Fitness enthusiasts in California, Texas, and Florida drive clean-label adoption through digital-native subscription models integrated with wearable wellness platforms. The FDA governs caffeine content limits and GRAS status for sweetener additives, tightening documentation requirements for synthetic caffeine sourcing. Pacific Coast metropolitan clusters anchor non-carbonated format growth as hydration-positioned products capture boutique gym and CrossFit affiliate channels.
Canada
Health Canada and PMRA enforce sweetener standards that parallel FDA requirements, enabling product standardization advantages for US brands with existing compliance infrastructure. The country's national food regulator maintains strict caffeine disclosure protocols that extend new product approval timelines. Ontario and Quebec convenience retail networks remain underpenetrated relative to US density, creating expansion opportunities for brands with established cross-border distribution.
Mexico
Mexico City Metro and Nuevo León industrial corridors concentrate manufacturing capacity for North American supply chain integration. The country's federal commission for protection against sanitary risk enforces beverage labeling standards that diverge from US-Canada harmonization. Jalisco and Bajío Region distribution networks are expanding cooler placement density as impulse purchase habits shift toward functional hydration formats.
Northeast United States
Career professionals in New York Metro and Greater Boston sustain baseline replenishment rates for convenience and mass retail channels. State-level beverage excise taxes in select jurisdictions create channel access advantages for zero-sugar formulations. The Northeast Corridor's organic certification demand extends go-to-market schedules by 12-18 months for clean-label product lines seeking USDA verification.
Southeast United States
Florida metropolitan clusters concentrate motorsports sponsorship equity and high-traffic fuel retail networks driving impulse purchase velocity. The region's humidity and outdoor training culture accelerates adoption of hydration-positioned non-carbonated formats. Georgia and Carolinas distribution infrastructure supports convenience store channel density that captures transaction frequency leadership across the regional market.
North America Sugar Free Energy Drinks Market Competitive Landscape
United States producers anchor the mass retail tier; Canadian and Mexican specialists hold regional distribution advantages. The market exhibits tiered consolidation with legacy beverage conglomerates commanding shelf dominance through vertically integrated networks, mid-cap fitness-positioned brands capturing premium margins, and emerging entrants fragmenting across direct-to-consumer channels. Strategic archetypes include convenience store velocity players, clean-label premium specialists, and subscription-model disruptors. Dominant competitive moves encompass motorsports sponsorship equity accumulation and fitness app partnership development.
Within the legacy conglomerate tier, PepsiCo, Inc. and Monster Beverage Corporation occupy positions defined by established distribution infrastructure and channel access density. Celsius Holdings Inc. exemplifies the fitness-centric clean-label archetype that has displaced artificial sweetener-dependent alternatives among performance-oriented consumers. These three entities collectively represent the competitive spectrum from mass retail velocity to premium subscription capture.
| Leading Market Players |
|---|
| PepsiCo, Inc. |
| Congo Brands |
| Monster Beverage Corporation |
| Living Essentials LLC |
| Ghost Beverages LLC |
| Red Bull GmbH |
| Celsius Holdings Inc. |
| Performix LLC |
| The Coca-Cola Company |
| Others |
Pricing and Supply Chain Analysis
Fitness app-integrated subscription buyers concentrate purchasing power in direct-to-consumer channels, anchoring a hybrid pricing model that blends recurring revenue with premium per-unit capture for clean-label formulations. This buyer archetype's channel preference feeds back into supply chain decisions, favoring domestic co-packing partnerships over mass-retail slotting fee structures.
Pricing Analysis
Short lead-time premiums for aseptic cold-fill capacity dominate contract negotiations, with brands paying measurable markups for expedited production slots during peak fitness seasonality. Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified organic lines from conventional natural extract formulations and artificial sweetener-dependent legacy portfolios. Price differentiation hinges on certification tier and volume scale, with boutique gym subscription channels showing lowest price sensitivity. Cost compression in artificial-sweetener tiers is intensifying because clean-label consumer sentiment accelerates reformulation timelines.
Supply Chain Analysis
Dual-sourcing mandates for stevia and monk fruit extracts now appear in procurement contracts from major beverage brands, driven by climate-driven harvest variability in Southeast Asian growing regions. Supply concentrates in Thailand, China, and Vietnam for natural sweetener inputs, while green coffee bean caffeine extraction centers on Brazil and Colombia. Raw material dependencies span botanical extracts, acidified water treatment chemicals, and aseptic packaging films. Single-source vulnerability in Southeast Asian extract supply exposes margins to freight cost spikes. Distribution runs through vertically integrated beverage networks for mass retail, with emerging direct-to-subscription models fragmenting downstream structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America sugar-free energy drinks sector sits in a formulation-transition phase, with natural caffeine extraction from green coffee beans and yerba mate displacing synthetic stimulant dependence across premium positioning tiers.
For Market Incumbents: Acquire boutique fitness studio distribution networks to defend shelf access against subscription-model disruptors. Consolidate aseptic cold-fill processing capacity in California and Texas manufacturing corridors to capture hydration-format growth. FDA GRAS scrutiny on synthetic caffeine sourcing poses immediate reformulation threat; backward integration into natural extract supply secures compliance runway. For New Entrants and Emerging Players: Direct-to-subscription routes through wearable-integrated wellness platforms offer lowest customer acquisition friction for emerging clean-label brands. White-space targets include Canadian convenience retail underpenetration and Pacific Coast metropolitan hydration-positioned formats. CrossFit affiliate and boutique cycling studio channels represent most penetrable initial trial points. For Investors and Strategic Acquirers: The window for entry favors mid-cap fitness-positioned specialists with established dual-label compliance infrastructure. Long-term viability hinges on clean-label ingredient narratives and subscription retention mechanics rather than convenience store velocity. Watch FDA enforcement timing on synthetic caffeine disclosure as inflection indicator for portfolio rebalancing toward natural extract-dependent assets.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Extract Supply Integration | Backward integration into Thai and Vietnamese stevia sourcing defends margin against climate-driven harvest variability. |
| Fitness App Partnership Development | Wearable wellness platform integrations fragment traditional convenience store dominance among performance-oriented consumers. |
| Dual-Label Compliance Investment | Parallel FDA and Health Canada documentation infrastructure enables cross-border expansion into underpenetrated Canadian retail. |
| Aseptic Cold-Fill Capacity Expansion | Preservation engineering for non-carbonated formats captures Pacific Coast hydration-positioned demand growth. |
| USDA Organic Certification Pipeline | Supply chain audits for natural extract provenance command premium shelf pricing in coastal metropolitan corridors. |
Research Methodology
Multi-period observation of formulation patent filings, regulatory submission timelines, and channel placement velocity anchored the trend analysis, supplemented by interviews with beverage R&D directors, category buyers at mass retailers, boutique gym operators, and co-packing facility managers. Secondary validation drew from FDA GRAS notices, Health Canada product licensing databases, USDA organic certification records, and Nielsen retail audit data. Bottom-up segment sizing triangulated against top-down category spending estimates.
Input-output matrix modeling connected caffeine standardization chemistry, aseptic processing capacity utilization, and channel-specific price realization across the projection horizon. Segmentation dimensions spanned carbonation status, ingredient focus, consumer age cohort, and distribution channel archetype. CAGRs derived from fitted growth curves applied to baseline volume and value estimates, with cross-validation against historical category evolution patterns. Forecast inputs included regulatory approval timeline assumptions and natural extract supply concentration indices.
The model holds under stable FDA enforcement posture and contained climate volatility in Southeast Asian growing regions; deviation in synthetic caffeine disclosure mandate timing or stevia harvest disruption would shift volume trajectories materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Carbonated Beverages Market
Beverages
Baby Drinks Market
Beverages
CBD-Infused Beverages Market
Beverages
Yerba Mate Market
Beverages
Saudi Arabia Drinking Water Market
Beverages
Asia Pacific Dairy Based Beverages Market
Beverages
Detox Drinks Market
Beverages
Citrus Water Market
Beverages
Fruit Beverages Market
Beverages
Aloe Vera Juice Market
Beverages
Victorian Jars Market
Beverages
Asia-Pacific Probiotic Drinks Market
Beverages
Juice Concentrates Market
Beverages
GCC Bottled Water Market
Beverages
Peanut Oil Market
Beverages
US Bubble Tea Market