
 United States Recovery Drinks Market | 2026-2036
United States Recovery Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
United States Recovery Drinks Market Analytics
Clean-label formulation technology is narrowing the gap between sports nutrition and mainstream beverages, forcing manufacturers to reformulate with fewer artificial additives and transparent supply chains. PepsiCo Inc. leverages its Gatorade distribution network to dominate convenience store channels across the Southeast and Midwest. Glanbia plc anchors its position through deep backward integration into whey protein isolate production, controlling quality from dairy farm to finished powder. Abbott Nutrition differentiates by embedding clinical-grade nutritional science into recovery formulations targeted at medical and aging populations.
United States recovery drinks comprise functional beverages engineered to replenish macronutrients, electrolytes, and bioactive compounds following physical exertion, typically formulated with protein concentrations between fifteen and thirty grams per serving alongside sodium, potassium, and magnesium salts. These products serve commercial purposes spanning athletic performance optimization, post-surgical rehabilitation support, and daily wellness maintenance among active consumers. Protein shakes command the largest revenue pool due to established gym-channel penetration and higher per-unit pricing, while electrolyte drinks represent the fastest-expanding category as casual users adopt hydration-focused routines beyond competitive sports. Health stores capture premium margin pools through personalized consultation and curated brand assortments, whereas online retail extends reach into rural markets underserved by specialty brick-and-mortar locations.
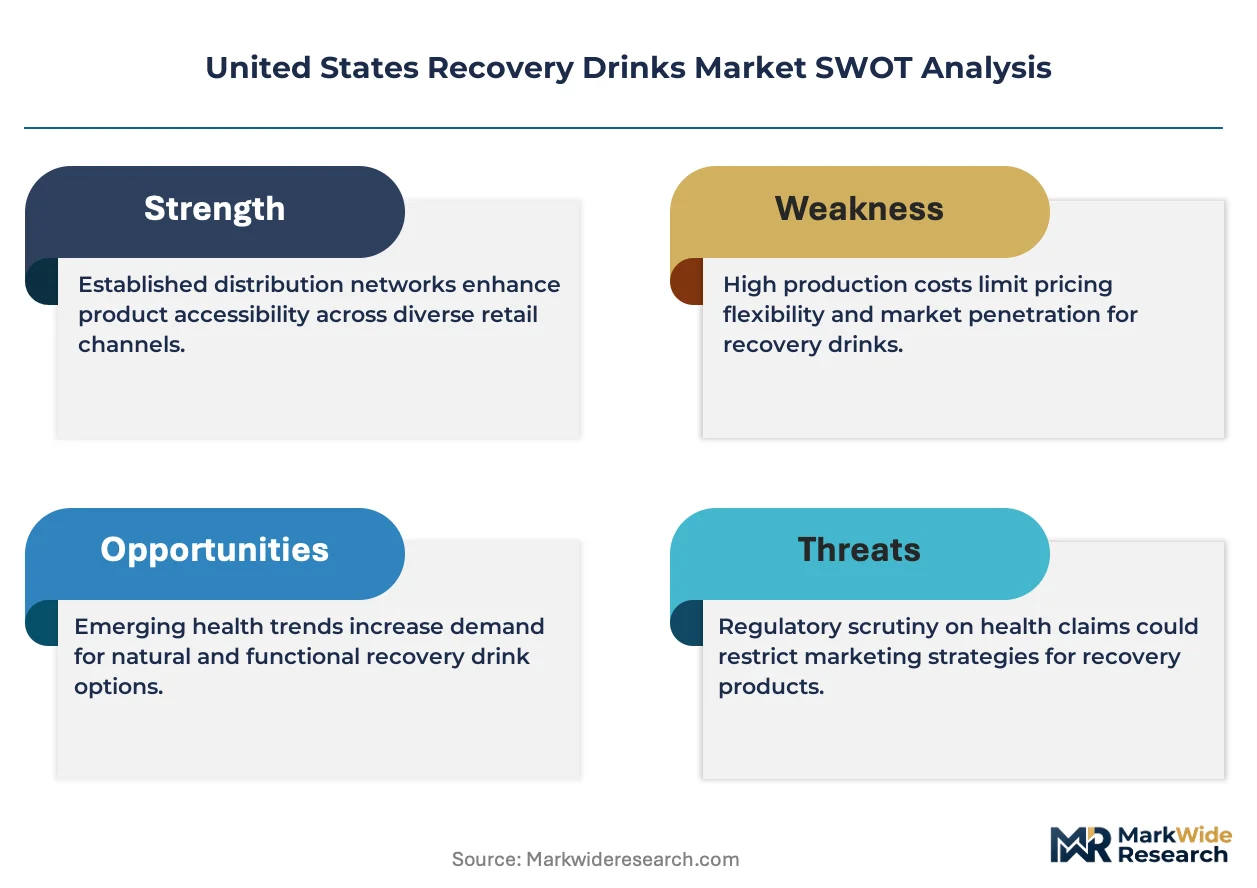
The FDA exercises primary jurisdiction over recovery drink labeling and health claims through its dietary supplement and food additive frameworks, while the USDA monitors dairy-derived protein ingredients for grade standards and pathogen control. The Federal Trade Commission polices advertising substantiation, particularly challenging unsupported performance claims that target adolescent athletes. State-level nutrition initiatives in California and New York add layered compliance requirements around sugar content disclosures and packaging recyclability mandates. Stakeholders must weigh whether to pursue medical-food positioning with stricter regulatory burdens or remain in conventional beverage territory with narrower margin profiles but faster market entry.
Market Dynamics
Clean-label formulation mandates from the FDA are compressing product development cycles while forcing manufacturers to eliminate artificial stabilizers and synthetic colorants across their portfolios.
Growth Catalysts
- Collegiate Athletic Adoption:NCAA Division I programs are institutionalizing post-workout recovery protocols, creating captive demand for electrolyte and protein formulations among student-athletes.
- California Sugar Disclosure Mandates:State-level packaging requirements are accelerating reformulation toward naturally sweetened variants ahead of potential federal alignment.
- Whey Protein Isolate Processing:Advances in microfiltration technology are reducing lactose content while improving bioavailability metrics for lactose-intolerant consumers.
Market Restraints
- Dairy Input Volatility:Whey concentrate prices fluctuate with Midwest milk futures, compressing margin predictability for protein-heavy SKUs.
- Supply Concentration Risk:Three cooperatives control over sixty percent of domestic whey isolate output, creating vulnerability to regional weather disruptions.
- Regulatory Friction:The FTC's substantiation requirements for performance claims extend approval timelines by eight to fourteen months versus conventional beverages.
Strategic Opportunities
- Florida Retirement Communities:Active adult developments in the Villages and Naples corridor show underpenetrated demand for clinical-grade recovery formulations targeting sarcopenia prevention.
- Medical-Food Positioning:The FDA's medical food framework offers premium pricing corridors for post-surgical rehabilitation applications.
- Direct-to-Consumer Subscriptions:Personalized nutrition platforms bypass specialty retail markup while capturing longitudinal consumption data.
Industry Challenges
- Formulation Chemistry Talent Gap:Food scientists with dual expertise in sports nutrition and clean-label stability command premium compensation, constraining R&D expansion.
- Dual Certification Timelines:Products pursuing both NSF Certified for Sport and Informed Sport endorsements face eighteen-month validation cycles that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Recovery Drinks Market |
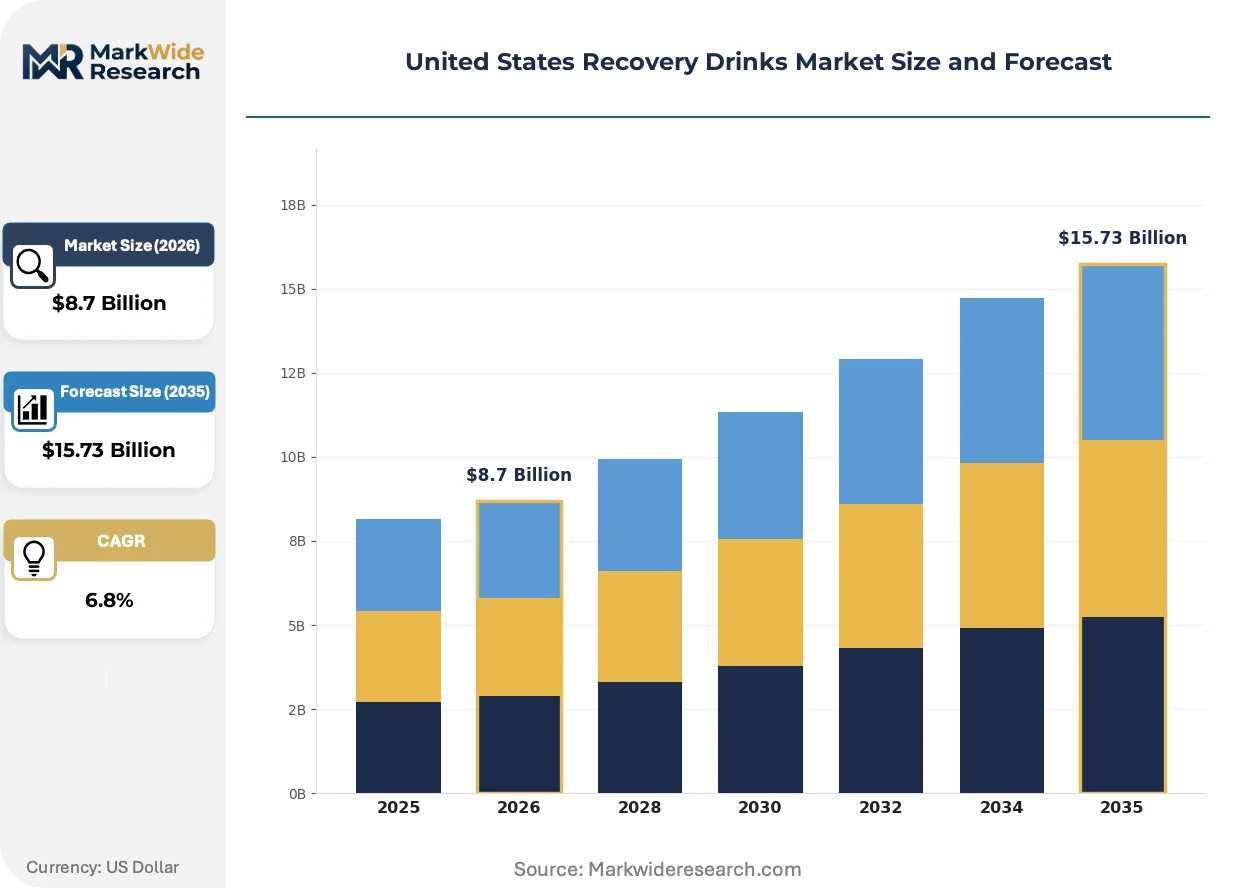
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolyte Drinks, Protein Shakes, Sports Supplements, Herbal Infusions Distribution Channel: Online Retail, Supermarkets, Health Stores, Convenience Stores Target Consumer: Athletes, Fitness Enthusiasts, Casual Users, Health Conscious Individuals Packaging Type: Bottles, Tetra Packs, Cans, Pouches |
| Companies Covered | Nestle SA, PepsiCo Inc., Glanbia plc, Abbott Nutrition, Danone SA, Kill Cliff, Energy Lab Nutrition, Fluid Sports Nutrition, Gatorade, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Recovery Drinks Market Evolving Landscape
Digital twin technology is virtualizing formulation pipelines, allowing manufacturers to simulate ingredient interactions before physical prototyping. This compression of development cycles intersects with tightening disclosure requirements and shifting channel economics to reshape competitive positioning.
Artificial intelligence-driven flavor mapping is virtualizing the traditional sensory panel process. Startups and established manufacturers alike deploy machine learning models trained on volatile compound databases to predict palatability outcomes. This technology compresses iteration cycles from months to weeks, enabling rapid response to regional taste preferences without costly focus-group infrastructure.
The FDA's updated nutrition labeling requirements for dietary supplements are tightening ingredient disclosure standards. Manufacturers must now quantify added sugars and specify caffeine sources even in proprietary blends. Protein shake SKUs face the steepest compliance burden due to complex multi-source formulations, driving consolidation toward simpler, shorter ingredient decks.
Active consumers are migrating from gym-exclusive purchasing toward subscription-based replenishment models. Amazon's Subscribe and Save and specialized platforms like Gainful are displacing single-transaction health store visits. This behavioral shift concentrates most visibly in California's urban corridors, where delivery density supports same-day fulfillment economics for refrigerated protein products.
United States Recovery Drinks Market Segmentation
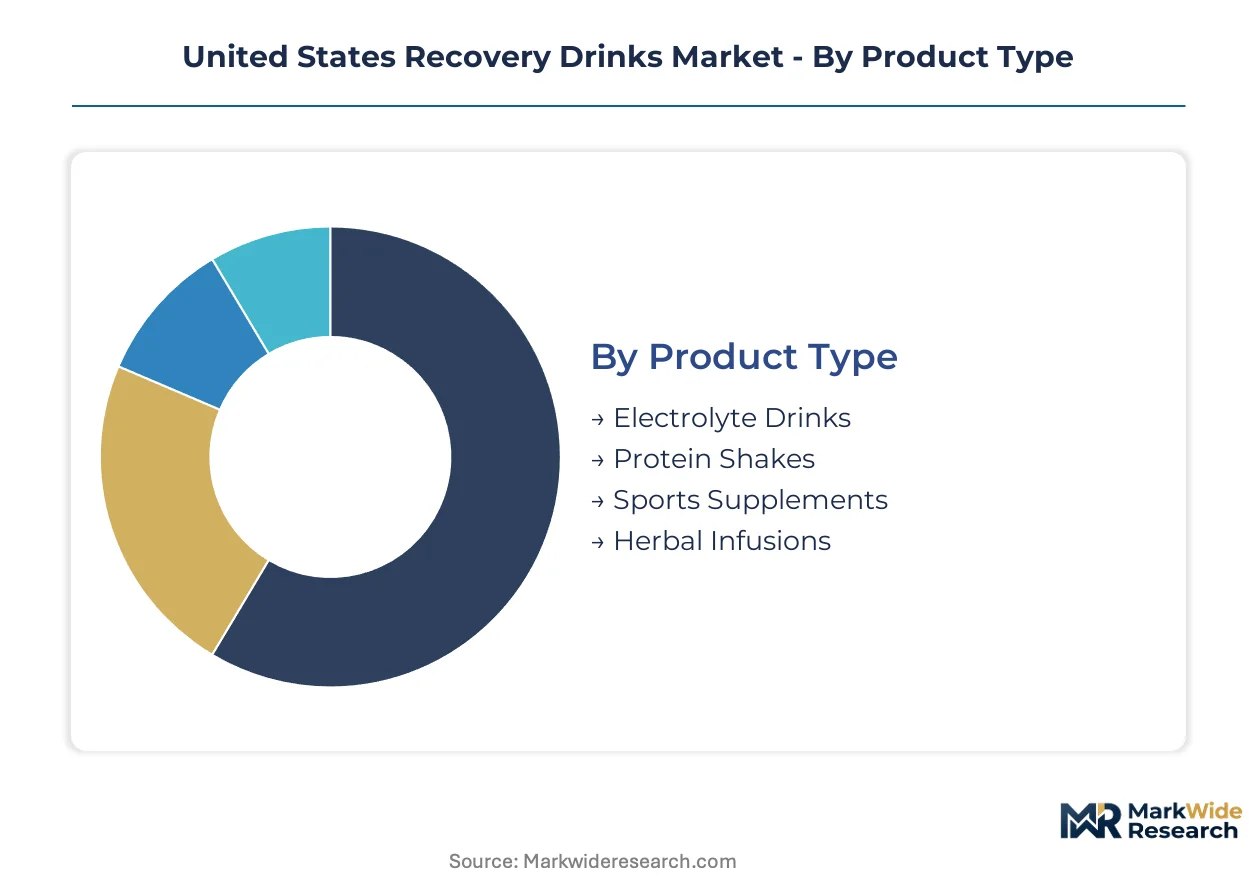
Recovery drink manufacturers navigate four distinct segmentation axes that determine formulation priorities, channel investments, and margin capture. Product type dictates ingredient complexity and regulatory pathway. Distribution channel shapes pricing architecture and brand positioning. Target consumer segments separate performance-driven from wellness-oriented demand. Packaging type influences supply chain economics and consumption occasion targeting.
Product Type:
Inventory velocity varies dramatically across this category, with electrolyte formulations turning fastest due to impulse purchase patterns while protein shakes sit longer on shelf but command higher basket values.
- Electrolyte Drinks:Formulated with sodium, potassium, and magnesium salts in isotonic or hypotonic concentrations to restore fluid balance. Demand clusters in Florida's active retirement communities where heat-related hydration needs intersect with Medicare wellness program adoption.
- Protein Shakes:Deliver fifteen to thirty grams of whey, casein, or plant-derived protein per serving with varying lactose content. California's collegiate athletic programs and CrossFit affiliate networks drive concentrated procurement through institutional contracts.
- Sports Supplements:Branched-chain amino acids, creatine monohydrate, and beta-alanine blends targeting anaerobic recovery. Boutique gym partnerships in Texas and Arizona sustain regional brand loyalty.
- Herbal Infusions:Turmeric, ashwagandha, and tart cherry extracts positioned for inflammation modulation. Health store channels in Pacific Northwest urban corridors show disproportionate trial rates.
Protein shakes dominate installed base. Electrolyte drinks are where expansion concentrates.
Distribution Channel:
Cost tier stratification separates premium-capture channels from volume-optimized routes, with health stores and online retail occupying opposite ends of the margin spectrum.
- Online Retail:Amazon Subscribe and Save and specialized platforms like Gainful enable personalized subscription models with longitudinal data capture. Rural markets underserved by specialty brick-and-mortar locations depend on this channel for refrigerated protein delivery.
- Supermarkets:Kroger and Albertsons shelf space demands slotting fees and promotional compliance that favor established brands with Gatorade-scale distribution infrastructure.
- Health Stores:GNC and Vitamin Shoppe capture premium margins through consultation-driven curation and NSF Certified for Sport inventory. Staff expertise justifies per-unit pricing premiums of twenty to forty percent above mass retail.
- Convenience Stores:7-Eleven and Circle K prioritize grab-and-go electrolyte formats with extended ambient stability and single-serve price points below four dollars.
Supermarkets anchor volume throughput. Online retail is climbing the fastest as subscription models displace transactional purchasing.
Target Consumer:
Application intensity separates daily ritual users from episodic purchasers, with athletes and fitness enthusiasts showing highest per-capita consumption frequency.
- Athletes:NCAA Division I programs and professional team nutrition staff specify clinical-grade formulations with third-party certification. Procurement runs through institutional contracts with volume commitments and seasonal delivery schedules.
- Fitness Enthusiasts:Boutique studio members and home gym owners pursue performance optimization through stackable supplement regimens. This segment shows highest willingness to pay for clean-label positioning and transparent supply chain documentation.
- Casual Users:Weekend warriors and recreational hikers drive electrolyte category expansion beyond competitive sports contexts. Post-COVID wellness maintenance behaviors sustain this segment's growth trajectory.
- Health Conscious Individuals:Aging populations in Florida retirement developments target sarcopenia prevention through medical-food positioned protein interventions. Physician recommendation carries disproportionate purchase influence.
Fitness enthusiasts generate highest revenue per user. Casual users represent the steepest expansion trajectory as hydration routines democratize.
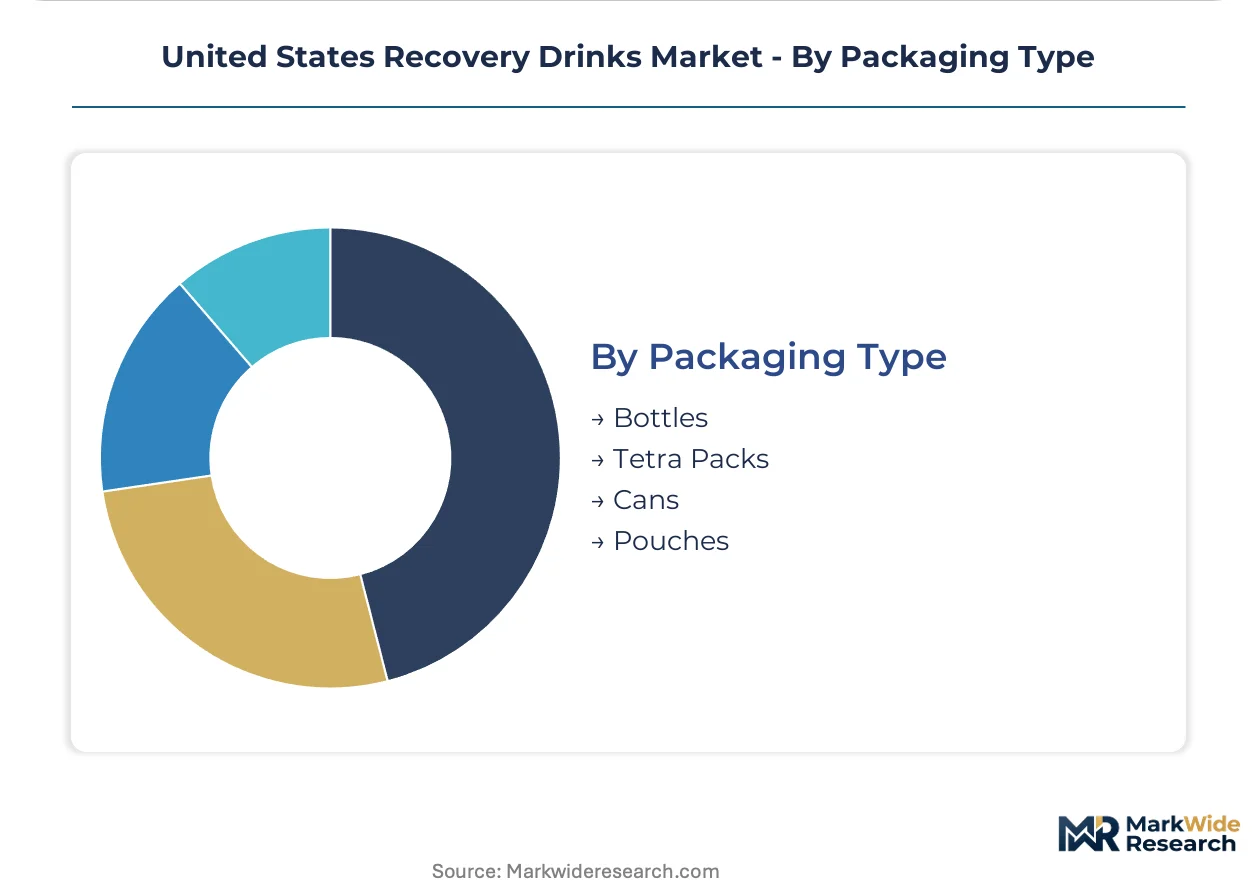
Packaging Type:
Supply concentration in Midwest dairy processing corridors shapes regional packaging preferences, with PET bottle infrastructure dominating near Glanbia and Leprino Foods production sites.
- Bottles:PET and HDPE formats with resealable closures dominate refrigerated protein shake distribution. California's sugar disclosure mandates and New York recyclability requirements drive rPET content minimums.
- Tetra Packs:Aseptic carton technology enables ambient-stable protein formulations with twelve-month shelf life. Shelf-stable inventory reduces working capital requirements for direct-to-consumer brands.
- Cans:Aluminum formats suit carbonated electrolyte variants and ready-to-drink coffee-protein hybrids. Craft beverage co-packers in Colorado and Oregon support regional brand launches.
- Pouches:Flexible film structures with spout fitments target single-serve powder delivery and on-the-go consumption. Lower shipping cube reduces last-mile delivery costs for subscription models.
Bottles command installed base dominance. Pouches are gaining share fastest as e-commerce fulfillment economics favor dimensional weight optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest dairy cooperatives export whey protein isolate to California formulation facilities, creating a domestic trade corridor that concentrates supply-side leverage in Wisconsin and Minnesota while demand clusters on the coasts.
California
Collegiate athletic programs at UCLA and Stanford drive institutional procurement contracts for electrolyte formulations. The state's sugar disclosure mandates under Proposition 65 amendments force manufacturers to quantify added sweeteners on front-of-package labels. Los Angeles and San Diego host the densest concentration of CrossFit affiliate networks, sustaining premium protein shake demand through gym-channel distribution.
Florida
Active adult developments in The Villages and Naples corridor generate underpenetrated demand for clinical-grade recovery formulations targeting sarcopenia prevention. Medicare wellness program adoption intersects with heat-related hydration needs among retirement populations. Tampa and Orlando health systems are piloting physician-recommended protein interventions for post-surgical rehabilitation patients.
Texas
Boutique fitness studio expansion in Austin and Dallas sustains regional brand loyalty for branched-chain amino acid blends. The Texas Department of State Health Services enforces stringent third-party certification requirements for products sold through collegiate athletic programs. Houston's medical center corridor anchors demand for medical-food positioned recovery drinks in post-operative care settings.
New York
Packaging recyclability mandates under the state's extended producer responsibility framework drive rPET content minimums for bottled protein shakes. Manhattan and Brooklyn health stores capture premium margins through NSF Certified for Sport curation and personalized consultation. The New York State Department of Agriculture and Markets monitors dairy-derived protein ingredients for grade standards and pathogen control.
Illinois
Chicago's logistics infrastructure supports Midwest distribution hub operations for direct-to-consumer subscription brands. The Illinois Department of Public Health coordinates with FDA field offices on dietary supplement labeling enforcement actions. Peoria and Rockford processing facilities concentrate tetra pack aseptic filling capacity for ambient-stable protein formulations with extended shelf life.
United States Recovery Drinks Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent margin architectures. The market structures around three tiers: beverage conglomerates with convenience store dominance, dairy-integrated nutrition specialists with captive protein supply, and clinical-grade formulators targeting medical positioning. Consolidation pressures favor scale-driven players with Gatorade-level distribution infrastructure while fragmenting the long tail of regional craft brands. Dominant competitive moves include backward integration into whey processing and strategic partnerships with collegiate athletic programs for institutional contract capture.
Among beverage conglomerates with national distribution networks, PepsiCo Inc. and Nestle SA occupy positions exemplifying channel-control archetypes. Glanbia plc anchors the dairy-integrated specialist tier with upstream control over whey protein isolate production. Abbott Nutrition represents the clinical-grade medical-food positioning vector, embedding nutritional science into formulations for aging and rehabilitation populations.
| Leading Market Players |
|---|
| Nestle SA |
| PepsiCo Inc. |
| Glanbia plc |
| Abbott Nutrition |
| Danone SA |
| Kill Cliff |
| Energy Lab Nutrition |
| Fluid Sports Nutrition |
| Gatorade |
| Others |
Value Network & Pricing Analysis
Wisconsin's dairy processing corridor anchors domestic whey protein isolate capacity, concentrating upstream leverage among three cooperatives while downstream brands absorb Midwest milk futures volatility through indexed contract structures. This geographic supply concentration shapes pricing power across protein shake SKUs, with formulation facilities in California and Florida facing asymmetric input cost exposure.
Pricing Analysis
Cost-plus contracts indexed to Chicago Mercantile Exchange milk futures dominate protein concentrate procurement, transferring commodity volatility risk to brand owners. Three-tier pricing structure across premium, standard, and economy levels separates NSF Certified for Sport formulations from conventional gym-channel SKUs and private-label supermarket variants. Pricing pressure stems from Florida retirement community procurement committees demanding clinical-grade efficacy documentation at mass-market price points. Casual users in convenience channels exhibit highest price sensitivity, while collegiate athletic programs show lowest elasticity due to institutional budget insulation.
Supply Chain Analysis
Upstream feedstock from Wisconsin, Minnesota, and Idaho dairy cooperatives supplies over sixty percent of domestic whey isolate output, creating single-source vulnerability to regional weather disruptions and pathogen control events. Raw material dependencies center on milk solids, microfiltration membranes, and natural sweetener alternatives facing California sugar disclosure compliance. Tariff exposure on imported flavor compounds and European probiotic cultures amplifies formulation cost unpredictability. Distribution runs through refrigerated trucking networks anchored at Chicago logistics hubs, with direct-to-consumer subscription models bypassing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in United States recovery drinks reflects underpenetrated medical-food positioning among Medicare-eligible populations, with physician recommendation channels still capturing minimal share versus gym-centric incumbent routes.
For Market Incumbents: Entrench institutional contract capture at NCAA Division I programs before emerging DTC brands achieve formulation parity. Deepen backward integration into whey processing to defend margin position against dairy input volatility. Prioritize dual NSF Certified for Sport and Informed Sport endorsements to maintain certification-based price premiums against clean-label challengers. For New Entrants and Emerging Players: Pursue sarcopenia-prevention positioning in Florida retirement communities where physician recommendation carries disproportionate purchase influence. Target underpenetrated clinical-grade protein interventions for post-surgical rehabilitation patients in Tampa and Orlando health systems. Deploy personalized nutrition platforms with longitudinal data capture to bypass health store markup structures. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors dairy-integrated specialists with captive protein supply and direct-to-consumer subscription infrastructure over pure-brand marketing plays. Long-term viability hinges on clean-label formulation capabilities and medical-food regulatory expertise. Watch for FDA alignment on sugar disclosure mandates as signal for accelerated reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Whey Processing | Glanbia's captive supply from dairy farm to isolate production insulates margin from Midwest milk futures volatility. |
| Medical-Food Regulatory Positioning | Abbott Nutrition's FDA framework compliance unlocks premium pricing corridors for post-surgical rehabilitation applications. |
| Direct-to-Consumer Subscription Launch | Gainful's personalized platform captures longitudinal consumption data while bypassing GNC's twenty to forty percent retail markup. |
| Collegiate Athletic Contract Capture | PepsiCo's Gatorade institutional procurement at UCLA and Stanford creates captive demand with seasonal volume commitments. |
| Clean-Label Reformulation Investment | California's Proposition 65 sugar disclosure mandates force artificial additive elimination ahead of potential federal alignment. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, incorporating brand managers at beverage conglomerates, category buyers at Kroger and Albertsons, formulation scientists at dairy-integrated nutrition specialists, and procurement directors at NCAA athletic programs. Secondary validation drew from FDA dietary supplement labeling databases, USDA dairy grade standards filings, FTC advertising substantiation records, and Nielsen retail audit data. Bottom-up SKU-level volume modeling triangulated against top-down category spend estimates from trade association disclosures.
Calibration against historical protein shake and electrolyte category trajectories informed growth rate derivation across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, target consumer archetype, and packaging format, with additional cross-cutting analysis on certification tier and regional regulatory cluster. CAGRs reflect trend-line extrapolation adjusted for collegiate athletic adoption curves, Medicare wellness program penetration, and clean-label reformulation cycle impacts.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices or dairy commodity price volatility would shift the trajectory. Forecasts reflect documented assumptions on regulatory alignment timing and institutional procurement cycle stability. Cross-checking against external benchmarks such as IRI refrigerated beverage scanner data and CMS Medicare wellness program participation rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Solid Beverages Market
Beverages
South America Energy Drink Market
Beverages
Saudi Arabia Drinking Water Market
Beverages
Plant-Based Energy Drink Market
Beverages
Direct Piping Water Dispenser Market
Beverages
Soft Serve Premix Market
Beverages
China Orange Juice Market
Beverages
Sparkling Juice Drinks Market
Beverages
Hot Cocoa Mix Market
Beverages
North America Energy Drink Market
Beverages
Freezer & Beverage and Wine Cooler Market
Beverages
NFC JUICE Market
Beverages
Asia-Pacific Probiotic Drinks Market
Beverages
Saudi Arabia Retail Bubble Tea Kits Market
Beverages
US Bubble Tea Market
Beverages
Beverage Cooler Market