
 Asia Pacific Soy Beverages Market | 2026-2036
Asia Pacific Soy Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Soy Beverages Market Outlook
Soybean processing capacity across Southeast Asia is restructuring as regional crush facilities expand output for food-grade protein isolates. Pulmuone Co., Ltd. leverages its integrated tofu-to-beverage pipeline to secure Korean retail shelf space. Danone anchors premium positioning through specialized fermentation expertise in soy-based yogurt. Vitasoy International Holdings Ltd. dominates Greater China distribution with century-old brand recognition in soy milk.
Asia Pacific soy beverages comprise aqueous extracts of whole soybeans or soy protein isolates, typically standardized to 2.5-4.0% protein content and homogenized for suspension stability, serving as lactose-free alternatives in hydration and nutritional applications. Non-dairy milk remains the volume anchor in retail channels across Indonesia and Vietnam, while soy-based yogurt captures expanding margin pools in Japanese and Australian convenience stores. Flavored soy milk competes aggressively against oat and almond variants through localized taste profiles such as black sesame and matcha.
Japan's Consumer Affairs Agency enforces FOSHU standards that restrict health claims to clinically substantiated benefits, compelling reformulation investment. China's National Health Commission and GB standards govern soy protein labeling thresholds and genetically modified ingredient disclosure, directly shaping import eligibility for regional suppliers. Australia's Food Standards Code mandates allergen warnings that influence packaging design across export-bound production lines. Stakeholders must monitor evolving plant protein tariff schedules and biotechnology approval timelines to calibrate sourcing strategies.
Market Dynamics
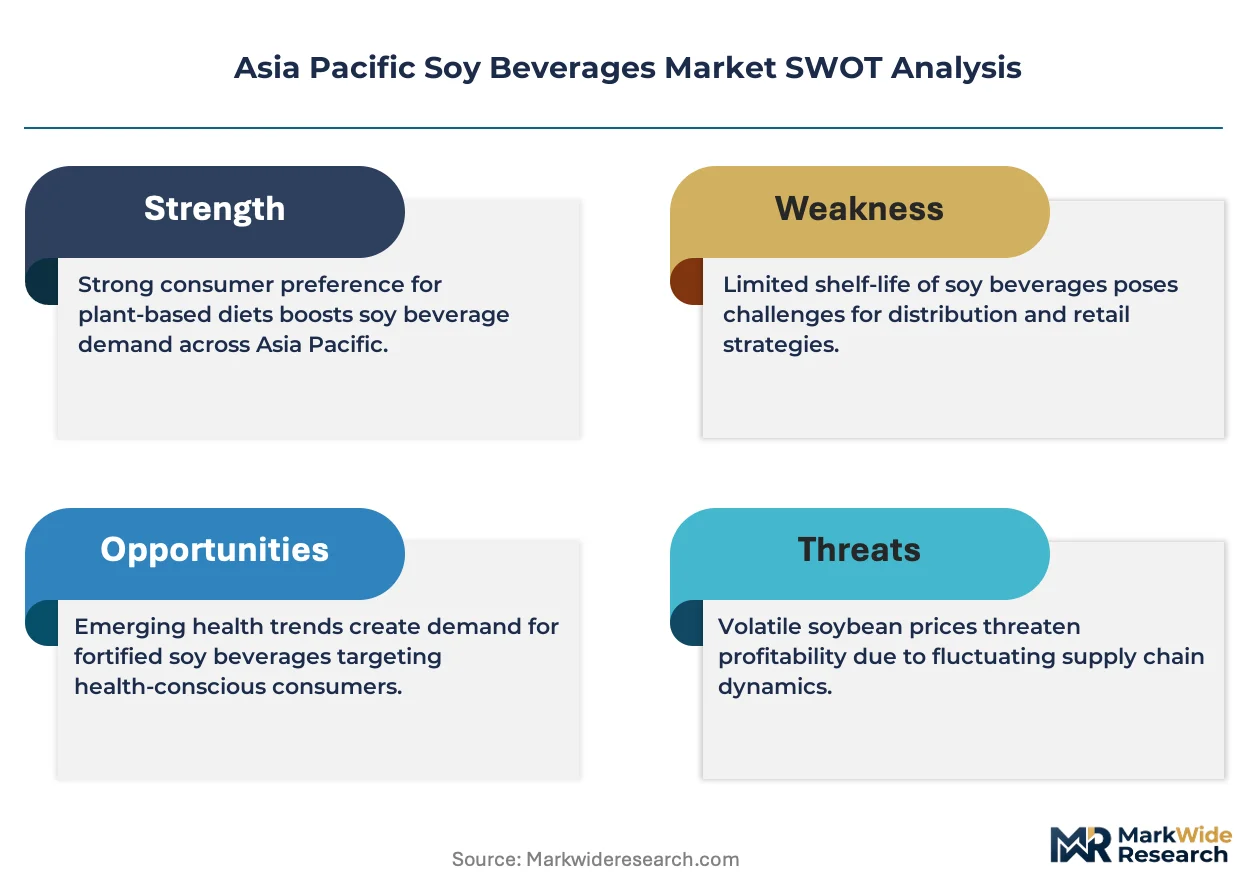
Fortification mandates and protein-labeling thresholds across China, Japan, and Australia are compressing formulation cycles and forcing capital redeployment toward cleaner-label production lines.
Growth Catalysts
- Japan's FOSHU framework:Clinically validated health claims create premium pricing headroom for functional soy beverages targeting metabolic health endpoints.
- Urban convenience-store penetration:Refrigerated soy yogurt and flavored variants now command dedicated shelf space in Shanghai, Tokyo, and Sydney metro outlets.
- Enzymatic debittering:Advanced protease treatments eliminate beany off-notes, expanding acceptability among Southeast Asian consumers historically averse to soy taste profiles.
Market Restraints
- Non-GMO soybean sourcing concentration:Dependence on limited certified acreage in Northeast China and Black Sea origins creates input cost volatility and traceability gaps.
- Cross-allergen labeling stringency:Australia's Food Standards Code mandates prominent soy allergen warnings that reduce impulse purchase conversion in export-bound formats.
- Oat milk substitution:Barista-grade oat formulations from Nordic and Australian suppliers capture café-channel volume previously held by soy alternatives.
Strategic Opportunities
- Vietnamese secondary cities:Ho Chi Minh City and Da Nang exhibit underpenetrated modern trade channels where ambient soy milk remains dominant over refrigerated premium lines.
- Dual-fermentation convergence:Combining traditional koji cultures with precision-controlled lactobacillus strains enables novel texture profiles in drinkable yogurt formats.
- China's dual carbon policy alignment:Carbon-neutral processing certifications unlock preferential listing terms in state-owned retail networks and institutional procurement.
Industry Challenges
- Food-grade isolates talent scarcity:Protein extraction and functionalization expertise concentrates among aging specialists in Japanese and Korean research institutes.
- GB standards compliance timelines:China's genetically modified ingredient disclosure requirements impose 12-18 month reformulation cycles for imported concentrate suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Soy Beverages Market |
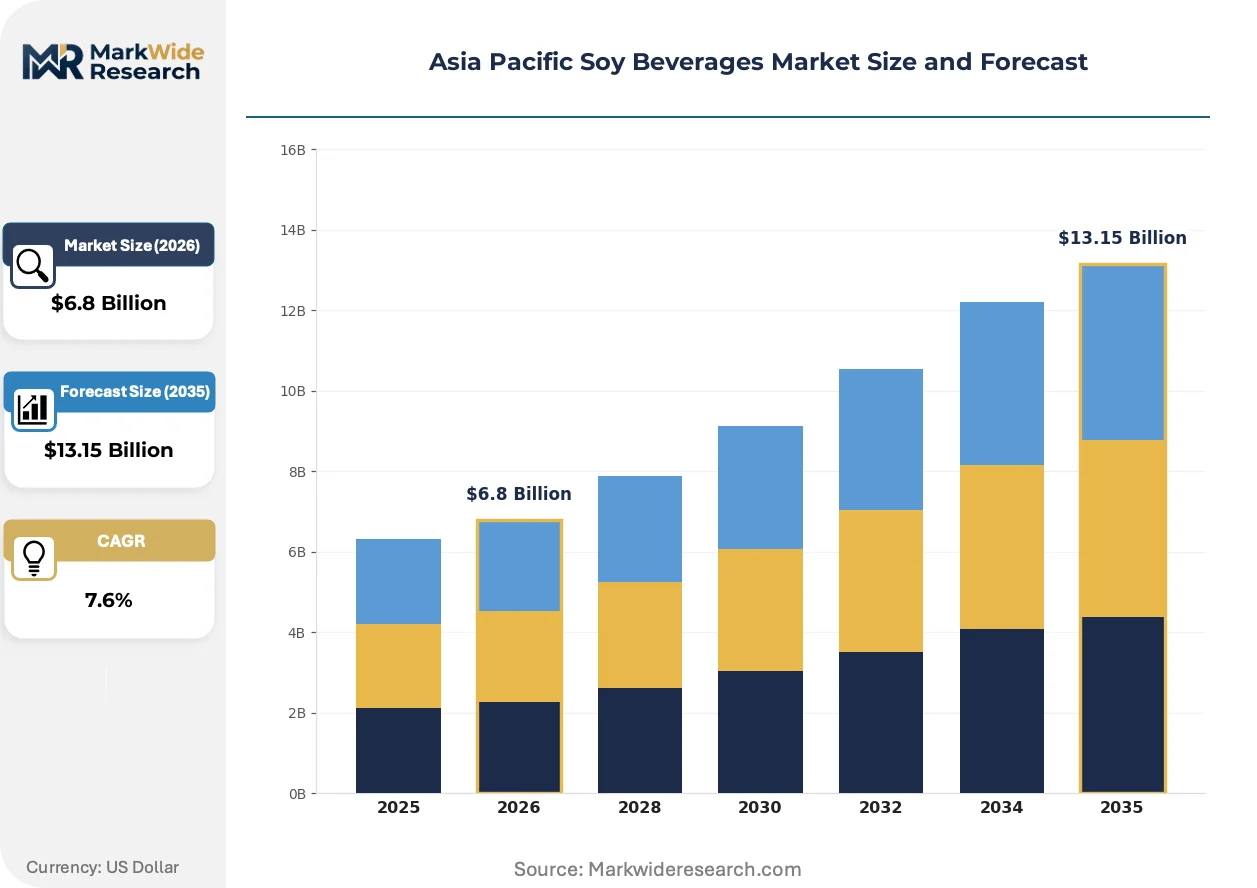
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Dairy Milk, Flavored Soy Milk, Soy Protein, Soy-Based Yogurt Application: Food Service, Retail, Household, Culinary End User: Fitness Enthusiasts, Vegetarians, Health-Conscious Consumers, General Population Distribution Channel: Supermarkets, Online Stores, Convenience Stores, Direct Sales |
| Companies Covered | Pulmuone Co., Ltd., Danone, Vitasoy International Holdings Ltd., Pureharvest, Vitamilk, Kikkoman Corporation, Maeil Dairies Co., Ltd., The Sanitarium Health and Wellbeing Company, Morinaga Milk Industry Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Soy Beverages Market Strategic Shifts
Processing technology and regulatory disclosure requirements are fragmenting competitive advantages, with shelf-stable and refrigerated formats diverging toward distinct technical specifications and channel strategies.
Membrane filtration and enzymatic hydrolysis is decentralizing protein standardization away from centralized crushing facilities. Mid-scale beverage processors in Thailand and Malaysia now achieve 3.5% protein equivalence previously requiring industrial isolates. This capability diffusion enables regional brands to bypass legacy toll-manufacturing relationships and capture margin previously held by integrated tofu-to-beverage conglomerates.
Australia's Food Standards Code allergen warning protocols are compressing packaging design cycles and forcing bilingual label investments. Domestic manufacturers absorb compliance costs through format consolidation, while export-oriented suppliers face batch-segregation requirements that reduce line efficiency. Japanese convenience-store chains now demand Australia-compliant labeling for cross-border private-label programs, extending regulatory reach beyond direct jurisdiction.
Buyer concentration in Chinese tier-one city retail is shifting procurement leverage toward hypermarket and membership-warehouse chains. These operators impose exclusive flavor development and promotional calendar alignment that erodes brand autonomy. The shift is most visible in Shanghai and Beijing, where refrigerated soy yogurt SKUs proliferate under retailer-controlled labels while heritage brands retreat to ambient shelf-stable positioning.
Asia Pacific Soy Beverages Market Segmentation
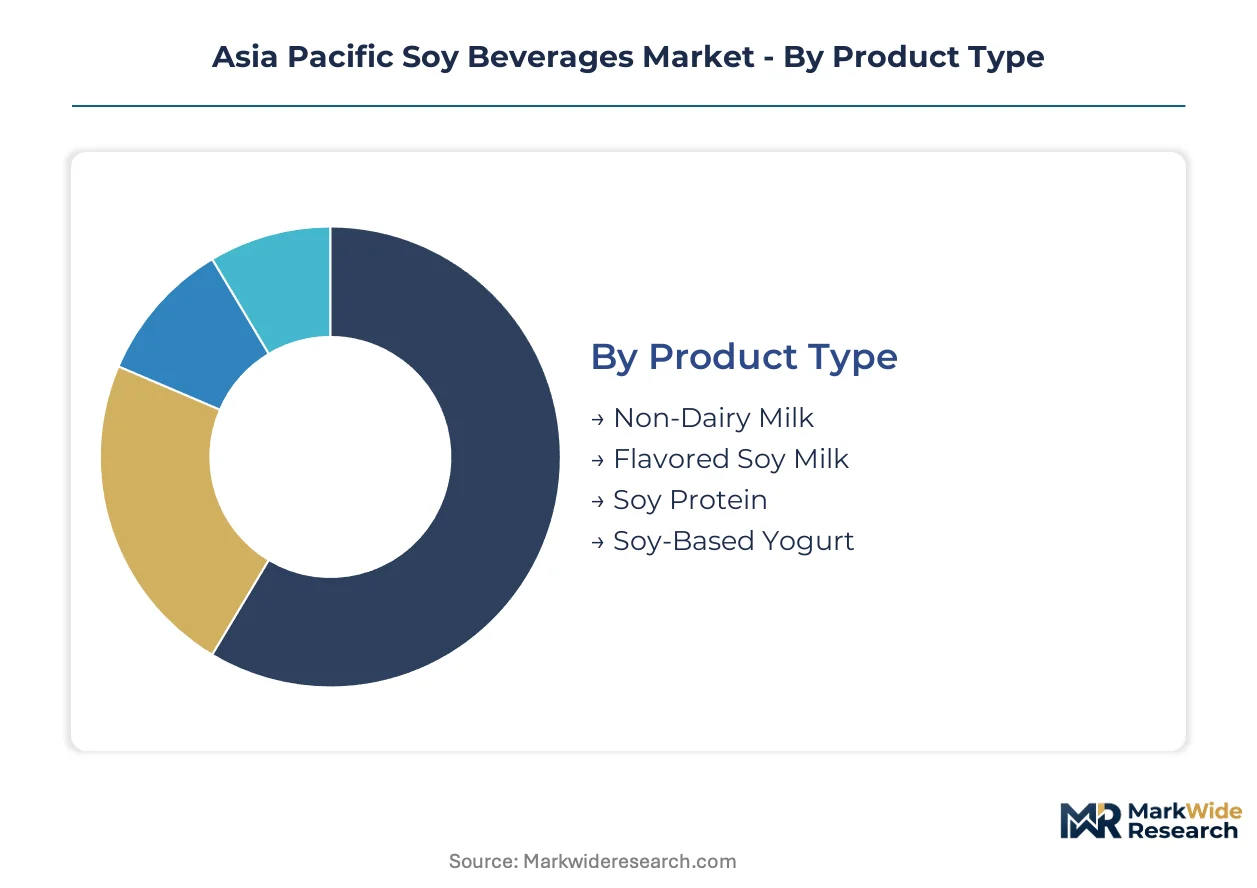
Product architecture in Asia Pacific soy beverages fragments across refrigerated and ambient stability requirements, with protein standardization and fermentation protocols creating distinct margin pools. Channel-specific formulation demands and allergen labeling mandates further subdivide competitive positioning within each segment category.
Product Type:
Supply concentration clusters around integrated crush-to-beverage facilities in Northeast China and Korea, where food-grade isolate capacity determines formulation flexibility across formats.
- Non-Dairy Milk:Aqueous extracts standardized to 2.5-4.0% protein content serve as the volume foundation across Indonesian and Vietnamese retail channels. China's tier-one cities concentrate demand for barista-grade formulations with enhanced foaming stability.
- Soy-Based Yogurt:Dual-fermentation combining koji cultures with lactobacillus strains creates premium texture profiles capturing dedicated shelf space in Tokyo and Shanghai convenience stores. Japanese FOSHU labeling requirements restrict health claims to clinically validated functional endpoints.
- Flavored Soy Milk:Localized taste profiles including black sesame and matcha compete against oat and almond variants in Australian and Southeast Asian markets.
- Soy Protein:Isolates and concentrates supply ingredient inputs for sports nutrition and fortified beverage applications across the region.
Today's leader: Non-Dairy Milk. Tomorrow's challenger: Soy-Based Yogurt.
Application:
Cost tier separation between food service bulk procurement and retail premium positioning drives divergent protein specification and packaging investment.
- Retail:Refrigerated and ambient formats compete for shelf space in hypermarkets and membership warehouses, with China's state-owned retail networks imposing exclusive flavor development requirements.
- Food Service:Café and hospitality channels demand barista-grade foaming performance, where oat milk substitution has captured volume previously held by soy alternatives in Australian and Japanese markets.
- Household:Direct consumption concentrates in urban households across China's tier-one cities and Japanese metropolitan areas.
- Culinary:Ingredient applications in food manufacturing leverage soy protein functional properties for texture and emulsification.
Margin pools favor retail premium positioning, though food service volume sustains bulk isolate demand.
End User:
Volume concentration tracks urban health-conscious demographics with lactose intolerance prevalence and metabolic health awareness.
- Health-Conscious Consumers:Fortification-responsive buyers in Shanghai, Tokyo, and Sydney drive demand for protein-standardized and vitamin-enriched formulations.
- Vegetarians:Plant-based dietary adherence in Indian and Southeast Asian markets sustains baseline consumption of traditional soy milk preparations.
- Fitness Enthusiasts:Sports nutrition applications favor high-protein isolates with specific amino acid profiles.
- General Population:Mass-market penetration depends on enzymatic debittering technologies that eliminate historical taste aversion in Southeast Asia.
Health-Conscious Consumers anchor premium pricing; Vegetarians provide volume stability.
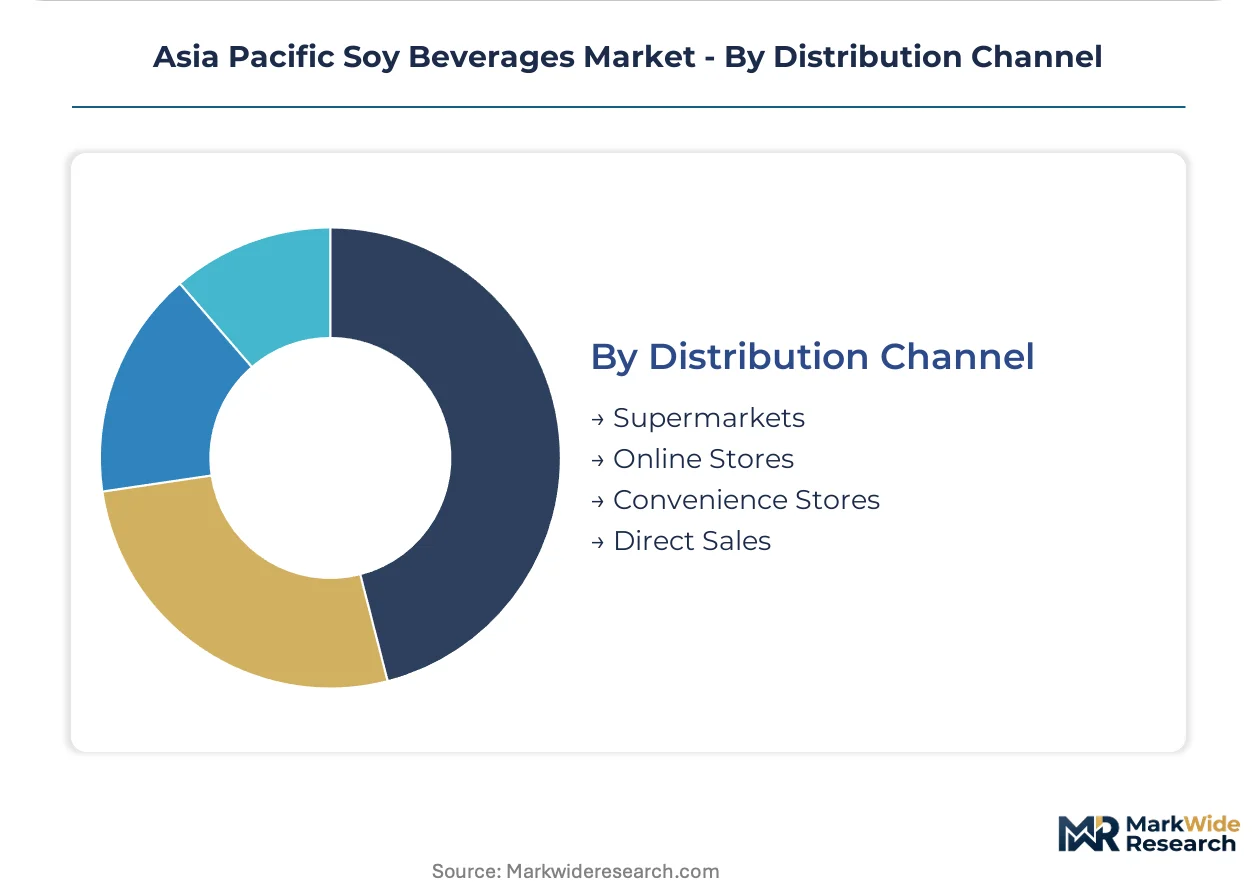
Distribution Channel:
Channel maturity separates modern trade consolidation in Chinese cities from fragmented traditional retail in secondary Vietnamese and Indonesian markets.
- Supermarkets:Hypermarket and membership-warehouse chains in Shanghai and Beijing impose promotional calendar alignment and private-label development that erodes heritage brand autonomy.
- Convenience Stores:Japanese and Australian chains demand Australia-compliant allergen labeling for cross-border programs, extending regulatory reach beyond direct jurisdiction.
- Online Stores:E-commerce penetration accelerates in China's tier-one cities with subscription models for refrigerated yogurt delivery.
- Direct Sales:Institutional procurement and food service supply relationships concentrate in Korea and Japan.
Supermarkets control pricing leverage; Convenience Stores command format innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity migrates toward jurisdictions with streamlined protein-labeling regimes, as compliance cost differentials reshape investment flows across Northeast Asia and Southeast Asia.
China
Shanghai and Beijing concentrate demand for refrigerated soy yogurt and barista-grade formulations. GB standards and the National Health Commission enforce genetically modified ingredient disclosure thresholds that extend reformulation cycles for imported suppliers. Yangtze River Delta processing clusters absorb capital redeployment from toll-manufacturing relationships toward in-house membrane filtration capabilities.
Japan
Tokyo and Osaka metropolitan areas sustain premium pricing for FOSHU-labeled functional beverages targeting metabolic health endpoints. The Consumer Affairs Agency restricts health claims to clinically substantiated benefits, compelling sustained R&D investment. Kanto region convenience-store chains now impose Australia-compliant allergen labeling for cross-border private-label programs.
Australia
Sydney and Melbourne anchor demand for flavored variants competing against oat and almond alternatives. Food Standards Code mandates prominent soy allergen warnings that compress packaging design cycles and force bilingual label investments. Domestic manufacturers absorb compliance costs through format consolidation while export-oriented suppliers face batch-segregation requirements.
South Korea
Seoul Capital Area retail channels reward integrated tofu-to-beverage pipelines with preferential shelf-space allocation. MFDS labeling requirements align with regional fortification standards. Korean research institutes concentrate scarce protein extraction expertise that regional competitors seek to access through technology licensing arrangements.
Vietnam
Ho Chi Minh City and Da Nang exhibit underpenetrated modern trade channels where ambient soy milk dominates over refrigerated premium lines. Local regulators enforce import standards that favor ASEAN-origin suppliers. Mekong Delta crush facilities expand food-grade isolate output to serve regional beverage processors.
Asia Pacific Soy Beverages Market Competitive Environment
Northeast Asian producers anchor the premium functional tier; Southeast Asian specialists hold cost-competitive ambient positions. The vendor base separates into integrated crush-to-beverage conglomerates, fermentation-technology licensors, and regional private-label suppliers. Three archetypes dominate: heritage brands with century-old distribution networks, dairy diversifiers leveraging fermentation expertise, and toll-manufacturing specialists serving retailer-controlled labels. Capacity expansion and exclusive flavor development partnerships constitute the dominant competitive moves.
Within the heritage-brand tier, Vitasoy International Holdings Ltd. and Kikkoman Corporation occupy positions built on decades of retail channel presence. Pulmuone Co., Ltd. exemplifies the integrated-production archetype spanning tofu through beverage formats. Danone represents dairy-sector diversification into plant-based fermentation, anchoring premium positioning through specialized technical capabilities.
| Leading Market Players |
|---|
| Pulmuone Co., Ltd. |
| Danone |
| Vitasoy International Holdings Ltd. |
| Pureharvest |
| Vitamilk |
| Kikkoman Corporation |
| Maeil Dairies Co., Ltd. |
| The Sanitarium Health and Wellbeing Company |
| Morinaga Milk Industry Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Non-GMO soybean premiums cascade through three distinct pricing tiers as certified acreage constraints in Northeast China and Black Sea origins tighten input cost structures for finished beverage formulations.
Pricing Analysis
Distributor margins compress most severely in ambient shelf-stable formats where Vietnamese and Indonesian traditional trade channels compete on unit economics. Three-tier pricing structure across premium, standard, and economy levels separates FOSHU-labeled functional beverages from conventional refrigerated lines and bulk food-service concentrates. Pricing pressure stems from oat milk substitution in Australian and Japanese café channels where barista-grade foaming performance commands loyalty. Food-service procurement teams exhibit highest price sensitivity; health-conscious consumers in Shanghai and Tokyo convenience stores accept meaningful premiums for clinically validated functional claims.
Supply Chain Analysis
Single-source vulnerability sits with food-grade protein isolate capacity concentrated among aging specialists in Japanese and Korean research institutes. Northeast China, South Korea, and Vietnam anchor supply concentration for crush-to-beverage integrated facilities. Raw material dependencies center on certified non-GMO soybeans, enzymatic debittering agents, and specialized koji culture strains. Regulatory restriction risk manifests in China's GB standards compliance timelines that impose extended reformulation cycles for imported concentrate suppliers. Distribution runs through modern trade consolidation in Chinese tier-one cities alongside fragmented traditional retail networks across secondary Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific soy beverages function as a regulatory compounder where Japan's FOSHU framework creates premium pricing headroom through clinically substantiated health claim validation.
For Market Incumbents: Anticipate oat milk substitution threats by securing exclusive flavor development partnerships with Shanghai and Beijing hypermarket chains before retailer-controlled labels capture refrigerated yogurt shelf space. Anchor defensive positioning through backward integration into Yangtze River Delta membrane filtration capabilities that bypass legacy toll-manufacturing relationships. Prioritize Australia-compliant allergen labeling investments to maintain cross-border private-label access as Japanese convenience-store chains extend regulatory reach beyond direct jurisdiction. For New Entrants and Emerging Players: Enzymatic debittering technology offers a technology-first wedge into Vietnamese secondary cities where ambient soy milk dominates and modern trade channels remain underpenetrated. Target Ho Chi Minh City and Da Nang with barista-grade formulations that exploit café-channel displacement of soy by oat alternatives. Pursue direct-to-institutional procurement relationships in Korean food-service supply chains where integrated tofu-to-beverage pipelines currently hold preferential allocation. For Investors and Strategic Acquirers: Consolidation pressure builds where food-grade isolate talent scarcity concentrates among Japanese and Korean research institutes nearing generational transition. Frame long-term viability around carbon-neutral processing certifications that unlock preferential listing terms in China's state-owned retail networks under dual carbon policy alignment. Monitor biotechnology approval timelines and plant protein tariff schedules as primary inflection indicators for sourcing strategy recalibration across regional suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fermentation Convergence | Combining koji cultures with precision lactobacillus strains creates novel texture profiles in drinkable yogurt formats. |
| Carbon-Neutral Processing Certification | China's dual carbon policy alignment unlocks preferential listing terms in state-owned retail procurement channels. |
| Membrane Filtration Capability Buildout | Mid-scale Thai and Malaysian processors now achieve protein equivalence previously requiring industrial isolates. |
| Exclusive Flavor Development Partnership | Hypermarket chains in Shanghai and Beijing impose promotional calendar alignment that erodes heritage brand autonomy. |
| Australia-Compliant Labeling Investment | Batch-segregation requirements for export-bound formats reduce line efficiency but maintain cross-border program access. |
Study Parameters
Bottom-up beverage consumption modeling reconciled against top-down crush facility capacity tracking forms the analytical core of this study. Primary interviews with brand managers, category buyers at Chinese hypermarkets, soy protein extraction specialists, and regulatory affairs leads at FOSHU-certified manufacturers combined with secondary validation from customs records, GB standards filings, and Japan Consumer Affairs Agency substantiation databases. Triangulation across stakeholder inputs and trade data ensures segmentation integrity.
Input-output matrices map protein isolate supply through finished beverage demand across product type, application, end-user demographic, and distribution channel dimensions. CAGRs derive from modeled volume trajectories reconciled against capacity expansion announcements and regulatory milestone timelines. Forecast inputs incorporate enzymatic debittering technology diffusion rates and convenience-store refrigerated shelf-space allocation shifts throughout the projection horizon.
The model holds under stable biotechnology approval timelines and tariff schedule continuity; deviation in China's genetically modified ingredient disclosure requirements or Australia's Food Standards Code allergen protocols would shift trajectory bands. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Blackstrap Molasses Market
Beverages
Hot Chocolate Market
Beverages
Popping Bobas Market
Beverages
Caffeine Mint Market
Beverages
Caffeinated Beverage Market
Beverages
Electrolyte Mixes Market
Beverages
Packaged Coconut Water Market
Beverages
Oat Based Beverages Market
Beverages
Japan Energy Drink Market
Beverages
Vegetable Juice Market
Beverages
Sarsaparilla Market
Beverages
Reconstituted Juice Market
Beverages
South America Mate Market
Beverages
Smoothies Market
Beverages
Coconut Water Market
Beverages
Drinking Water Market