
 Bottled Water Cooler Market | 2026-2036
Bottled Water Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Bottled Water Cooler Market Analytics
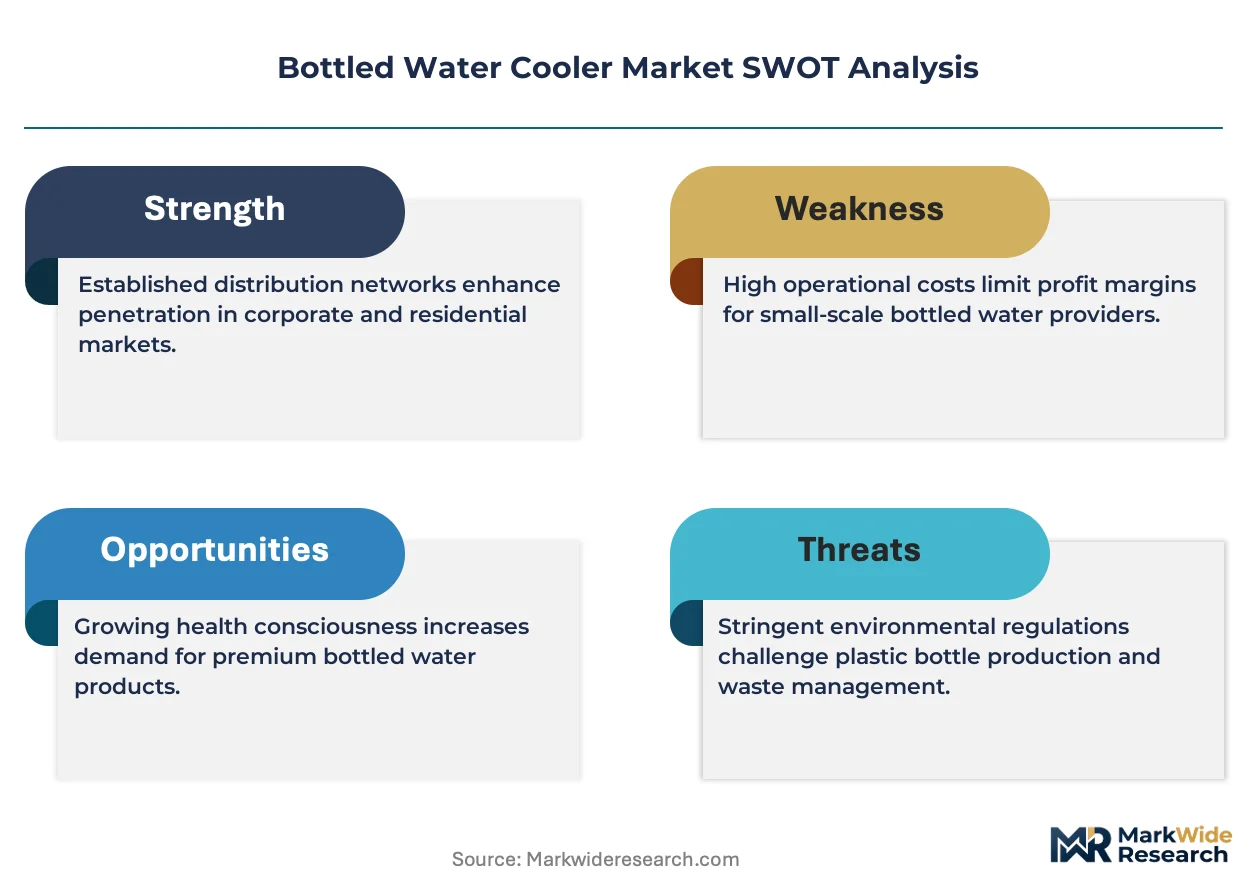
IoT-enabled telemetry and sensor-based monitoring is reconfiguring how bottled water coolers are serviced, shifting the industry from reactive maintenance to predictive replenishment models. Primo Water Corporation leverages its direct-to-consumer platform to control last-mile delivery density across North America. Waterlogic sustains competitive advantage through UV purification specialization in commercial installations. Culligan International Company anchors its position via extensive dealer networks that dominate multi-unit residential contracts.
A bottled water cooler is a freestanding or countertop appliance designed to dispense chilled, ambient, or heated water from replaceable bottles, typically incorporating compressor-based refrigeration systems operating between 2°C and 10°C with storage capacities ranging from 2 to 5 liters for commercial units. Point-of-Use systems now lead value generation as facilities bypass bottle logistics entirely, while Water Filtration attachments represent the fastest-growing attachment category by margin contribution. The Premium tier captures disproportionate profit pools in healthcare and corporate segments where certification requirements and aesthetic specifications command price premiums over Economy units.
The EPA regulates refrigerant emissions under Section 608 of the Clean Air Act, compelling cooler manufacturers to transition away from high-GWP hydrofluorocarbons toward hydrocarbon or natural refrigerant alternatives. OSHA workplace sanitation guidelines and the FDA Food Code jointly shape product standards for units deployed in healthcare facilities and food service environments. Stakeholders must monitor refrigerant compliance deadlines and antimicrobial certification requirements as procurement criteria harden across institutional buyers.
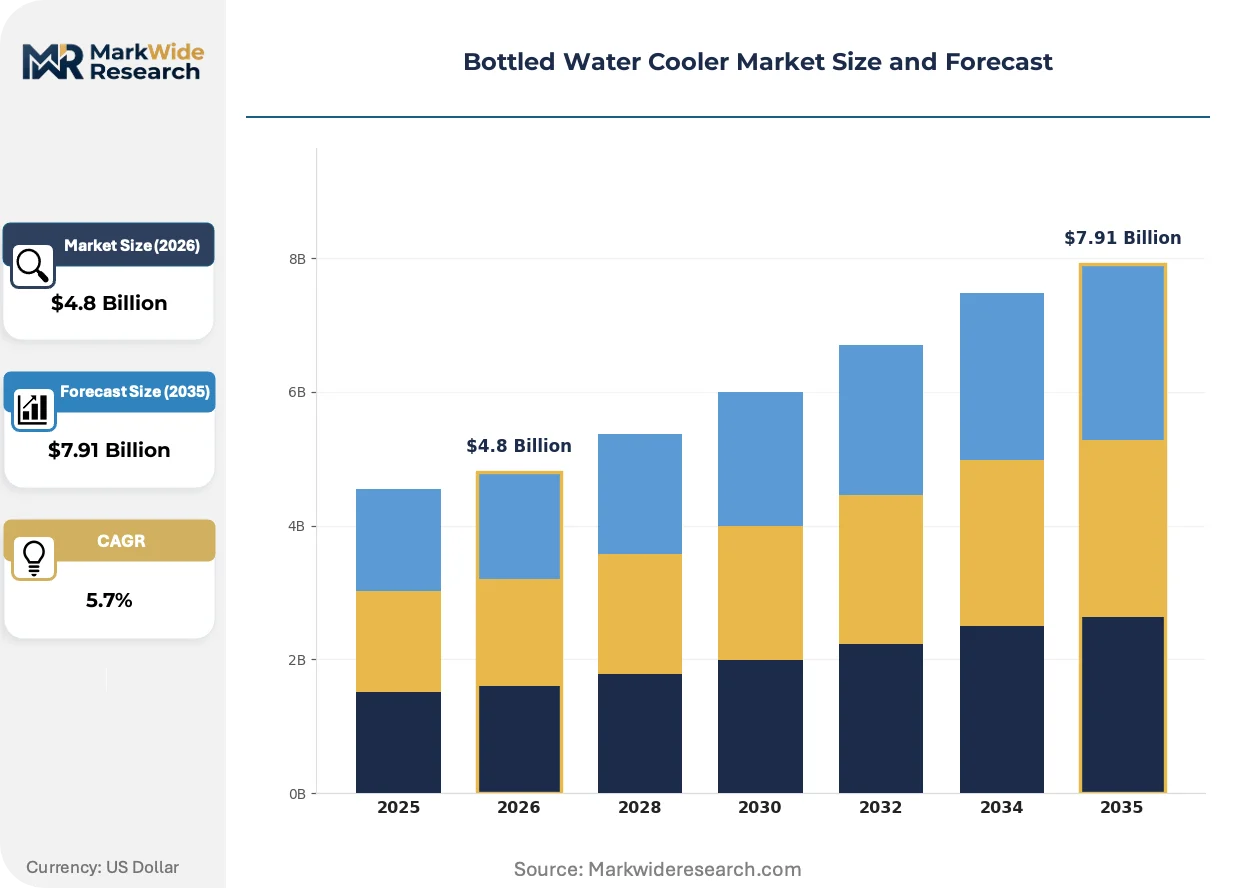
Market Dynamics
The bottled water cooler sector is undergoing a fundamental transition as refrigerant phase-outs under the EU F-Gas Regulation force manufacturers to redesign cooling architectures around hydrocarbon alternatives, compressing product development cycles and reshaping supplier qualifications.
Growth Catalysts
- Workplace Wellness Mandates:Corporate offices across Germany and France face stricter hydration standards under national occupational health frameworks, accelerating filtered cooler procurement in commercial buildings.
- REACH Compliance:Antimaterial restrictions on legacy plastics are driving cooler housing material shifts toward bio-based polymers certified under EU chemical safety protocols.
- Sensor Telemetry:IoT-enabled consumption monitoring is enabling predictive replenishment models that reduce distributor route density and improve asset utilization rates.
Market Restraints
- Refrigerant Supply Concentration:Hydrocarbon refrigerant production clusters in specialized German and Italian chemical facilities, creating input bottlenecks during cooler manufacturing ramp-ups.
- Point-of-Use Substitution:Direct-plumbed filtration systems bypass bottle logistics entirely, capturing institutional contracts in healthcare and education verticals where hygiene certification is paramount.
- OSHA Sanitation Burden:Workplace sanitation guidelines impose quarterly deep-cleaning protocols that elevate total cost of ownership for deployed units in food service environments.
Strategic Opportunities
- Healthcare Certification Gap:Premium coolers with UV purification and antimicrobial touchpoints command price premiums in German and Swiss hospital procurement where infection control standards exceed general commercial specifications.
- CSRD Reporting Alignment:Corporate sustainability disclosure mandates create demand for carbon-accounted hydration systems that document refrigerant emissions and bottle logistics footprints.
- Last-Mile Platform Convergence:Direct-to-consumer delivery networks originally built for beverage distribution are expanding into cooler leasing and maintenance bundling.
Industry Challenges
- Refrigerant Retrofit Complexity:Existing installed bases of HFC-dependent coolers face technical barriers to hydrocarbon conversion, requiring full unit replacement rather than component upgrades.
- Dealer Network Fragmentation:Multi-unit residential contracts depend on dispersed service technician pools with inconsistent training on new purification technologies and connected diagnostics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottled Water Cooler Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Point-of-Use, Bottled, Water Dispensing, Water Filtration End User: Residential, Corporate Offices, Educational Institutions, Healthcare Facilities Distribution Channel: Retail Stores, Online Platforms, Direct Sales, Wholesalers Price Tier: Economy, Mid-range, Premium, Luxury |
| Companies Covered | Primo Water Corporation, Waterlogic, Culligan International Company, Midea Group, Avalon Water Coolers, Alfred Kärcher SE & Co. KG, Oasis International, Blue Star Limited, Elkay Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottled Water Cooler Market Evolving Landscape
Refrigerant architecture, connectivity integration, and procurement model restructuring are converging to redefine competitive positioning in hydration equipment, with sustainability certification and predictive service emerging as primary differentiation vectors.
Compressor-based cooling systems are hybridizing with thermoelectric backup modules to maintain temperature stability during peak demand intervals in high-traffic corporate installations. Facility managers in Frankfurt and Munich are specifying these dual-mode units for conference center deployments where thermal consistency affects contract renewal terms. The technology is compressing warranty risk profiles for manufacturers while enabling premium pricing tiers tied to uptime guarantees.
The EU F-Gas Regulation is mandating stepped reductions in hydrofluorocarbon refrigerant volumes through 2030, compelling cooler OEMs to validate hydrocarbon charge sizes below 150 grams for safety compliance. German manufacturers are accelerating R290 propane adoption ahead of quota allocation deadlines, while Italian producers pursue CO2 transcritical cycles for larger commercial formats. Healthcare and food service segments face the steepest compliance timelines, driving accelerated replacement cycles in facilities governed by FDA Food Code equivalents.
Subscription-based hydration service contracts are displacing capital purchase models in mid-market corporate accounts, bundling cooler hardware, filtration maintenance, and consumption analytics into per-employee fees. Channel intermediaries in France and the Netherlands are consolidating route density through these arrangements, while direct operators bypass traditional dealer networks entirely. The shift is most visible in Benelux markets where facility management outsourcing already dominates commercial real estate operations.
Bottled Water Cooler Market Segmentation
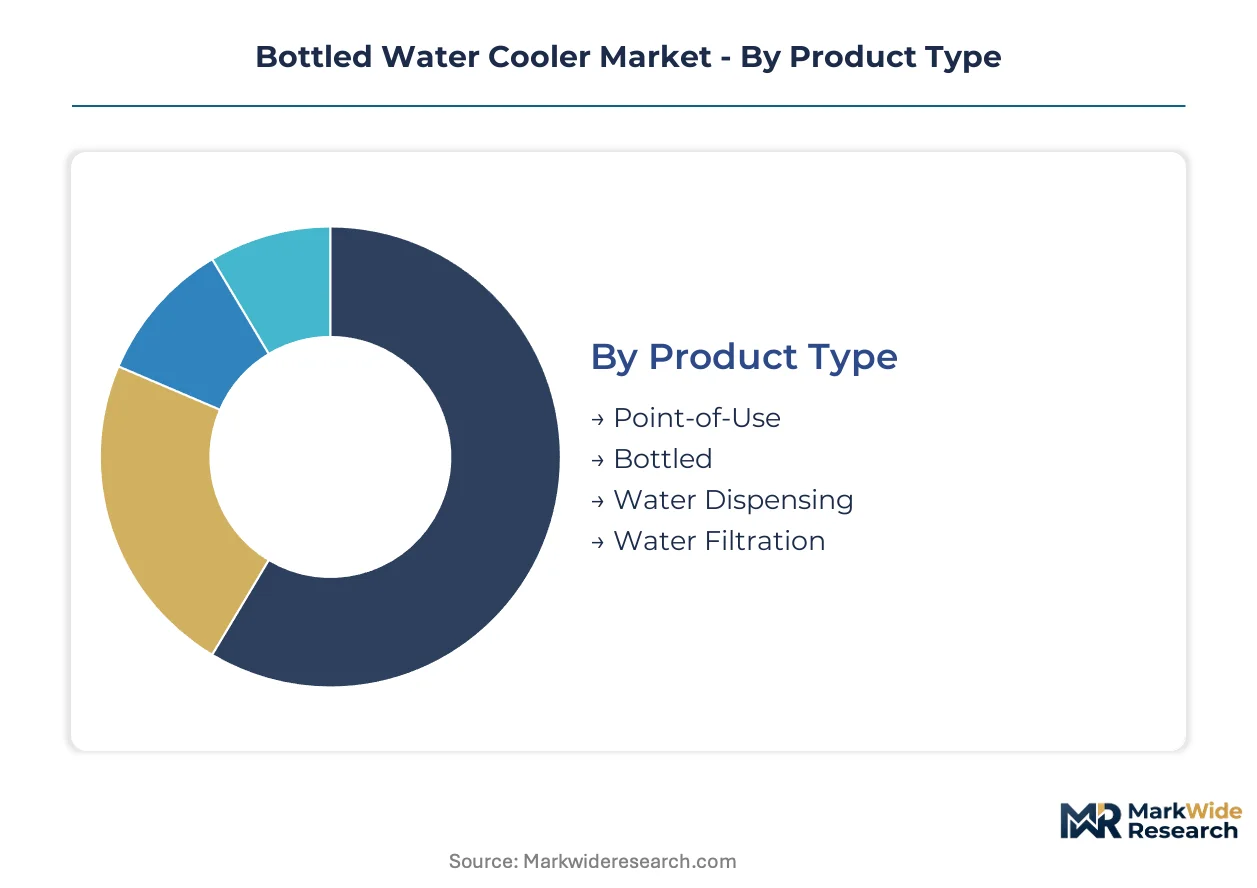
Segmentation in the bottled water cooler market reveals divergent equipment specifications and procurement patterns across installation types and buyer categories. Facility managers, procurement officers, and residential consumers each impose distinct performance thresholds that reshape product development priorities and channel economics.
Product Type:
Installation requirements span from plumbed infrastructure to portable bottle-dependent systems, creating fundamentally different service models and margin profiles.
- Point-of-Use:Direct-plumbed units connect to building water supplies, eliminating bottle logistics entirely. Healthcare facilities in Germany and France specify these systems under infection control protocols that mandate sealed water pathways and UV sterilization stages.
- Bottled:Traditional replaceable-bottle systems remain dominant in leased commercial spaces and residential settings lacking plumbing modifications. Corporate offices in Frankfurt and Munich deploy these units for deployment flexibility during building retrofit cycles.
- Water Dispensing:Basic temperature-controlled dispensing units without integrated filtration target cost-sensitive institutional buyers. Educational institutions in the Netherlands favor these for cafeteria and common area installations.
- Water Filtration:Attachable or integrated filtration modules address escalating water quality concerns. Swiss hospital procurement frameworks now require carbon block or reverse osmosis stages as baseline specifications.
The dominant share belongs to Bottled systems, while Point-of-Use is closing the gap fastest.
End User:
Buyer sophistication and compliance burden vary sharply across residential, commercial, and institutional deployment contexts.
- Residential:Single-family and multi-unit dwellings prioritize countertop footprint and aesthetic integration. French consumers show particular sensitivity to energy efficiency labeling under national building codes.
- Corporate Offices:Workplace wellness mandates and CSRD reporting requirements are accelerating procurement of connected, carbon-accounted hydration systems. German occupational health frameworks now specify minimum hydration access standards.
- Educational Institutions:Schools and universities balance capital constraints against durability requirements for high-traffic environments. Benelux facility management outsourcing trends concentrate purchasing power through consolidated service contracts.
- Healthcare Facilities:Hospitals and clinics impose the most stringent certification requirements, including antimicrobial touchpoint materials and FDA Food Code equivalent compliance. Swiss and German procurement leads this segment's premium tier expansion.
Corporate Offices command the largest volume commitment, with Healthcare Facilities expanding most quickly.
Distribution Channel:
Route density and service bundling capabilities determine channel viability for equipment-plus-consumables business models.
- Retail Stores:Big-box and specialty appliance retailers serve residential replacement demand and small commercial walk-in purchases. German electronics retailers have expanded cooler assortments alongside air purification categories.
- Online Platforms:Direct-to-consumer and B2B marketplaces enable subscription bundling of hardware, filtration, and replenishment. Dutch and Belgian operators leverage these channels to bypass traditional dealer networks.
- Direct Sales:Manufacturer-controlled sales organizations target large corporate accounts with customized service agreements. Primo Water Corporation's North American platform exemplifies this channel's last-mile density advantages.
- Wholesalers:Regional distributors aggregate multi-brand portfolios for dealer networks serving fragmented residential and small commercial markets. Italian wholesalers face refrigerant logistics constraints under F-Gas quota allocations.
Direct Sales captures the highest margin per unit, though Online Platforms are scaling fastest.
Price Tier:
Certification grade and connectivity features stratify pricing architectures across buyer willingness-to-pay thresholds.
- Economy:Basic compressor-cooled units with minimal filtration and no telemetry capabilities serve price-sensitive residential and small commercial accounts. REACH compliance on housing materials constrains cost engineering flexibility.
- Mid-range:Units incorporating single-stage filtration and basic temperature control dominate standard corporate installations. French and German mid-market offices specify this tier for balance of capital outlay and feature coverage.
- Premium:Multi-stage purification, IoT connectivity, and hydrocarbon refrigerant architectures define this tier. Healthcare and corporate segments in Switzerland and Germany absorb premium pricing for infection control and sustainability certification.
- Luxury:Designer aesthetics, bespoke finishes, and concierge service bundling target executive suites and high-end residential. Milan and Zurich commercial real estate developments specify these for tenant amenity differentiation.
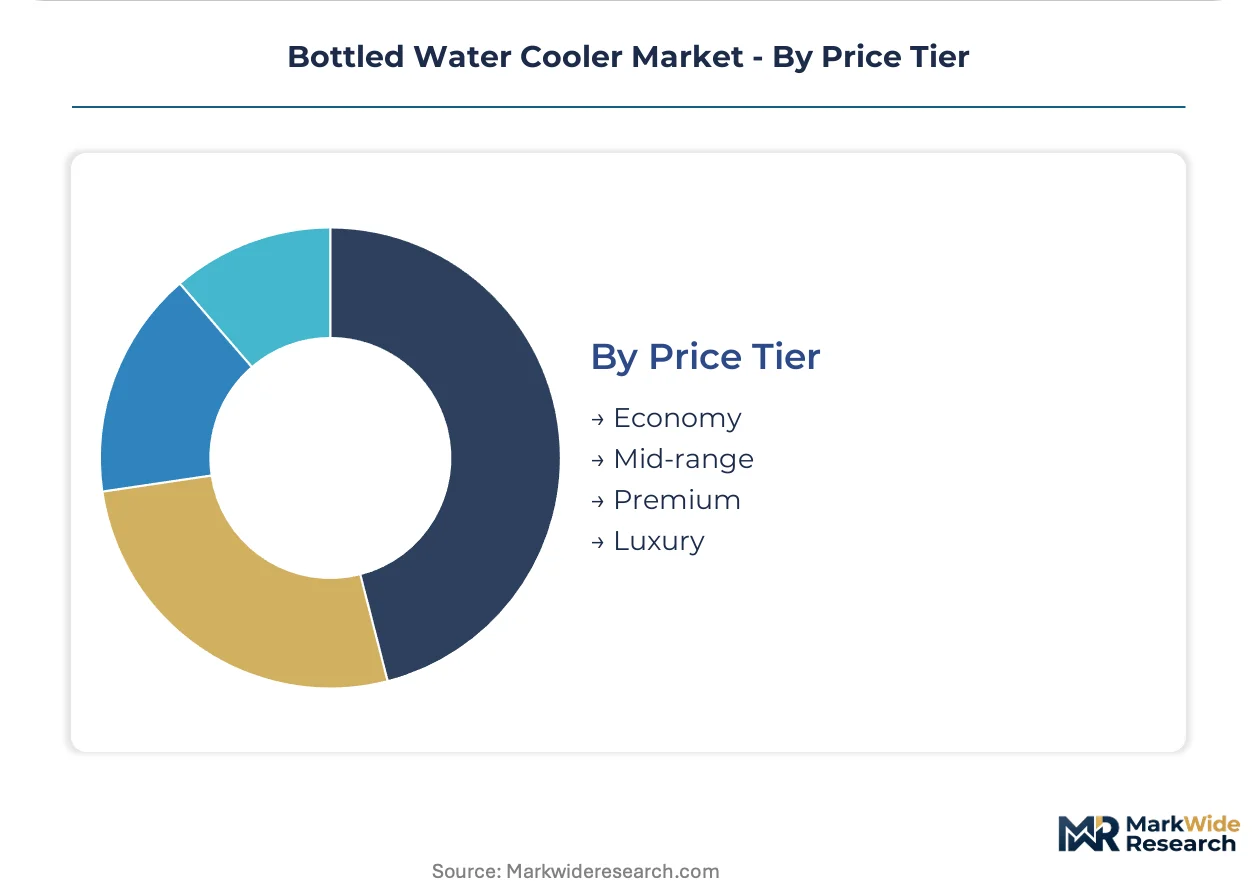
Premium systems hold the dominant revenue position, with Mid-range units showing steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cooler manufacturers export hydrocarbon-based units to Swiss and Austrian healthcare systems, while Italian producers supply CO2 transcritical systems to French corporate campuses. This trade corridor shapes regional equipment specifications and refrigerant compliance timelines.
Germany
Commercial building retrofits in Frankfurt and Munich drive cooler replacements as facility managers pursue sustainability certifications. The EU F-Gas Regulation mandates stepped HFC reductions through 2030, compressing product development cycles for domestic OEMs. Bavarian manufacturing clusters around Munich specialize in R290 propane architectures for hospital procurement.
Switzerland
Swiss hospital procurement frameworks impose infection control standards exceeding general commercial specifications, creating premium-tier demand. Swissmedic certification requirements for antimicrobial touchpoint materials filter supplier qualifications. Zurich commercial real estate developments specify luxury-designer coolers for tenant amenity differentiation in new office towers.
France
National occupational health frameworks now specify minimum hydration access standards for corporate offices, accelerating filtered cooler procurement. REACH compliance on housing materials constrains cost engineering flexibility for economy-tier imports. Paris and Lyon facility management outsourcing trends concentrate purchasing power through consolidated service contracts.
Italy
Italian producers pursue CO2 transcritical cycles for larger commercial formats ahead of quota allocation deadlines. The country's chemical facilities cluster hydrocarbon refrigerant production, creating input bottlenecks during manufacturing ramp-ups. Milan commercial developments drive luxury-tier specification for executive suite installations.
Netherlands
Benelux markets exhibit the most visible shift toward subscription-based hydration service contracts displacing capital purchase models. Dutch operators leverage online platforms to bypass traditional dealer networks entirely. Rotterdam and Amsterdam facility management outsourcing already dominates commercial real estate operations, bundling cooler hardware into per-employee fees.
Bottled Water Cooler Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a structurally tiered vendor base. The market fragments between consolidated direct-to-consumer platforms and dispersed dealer networks serving fragmented residential contracts. Three archetypes dominate: direct-platform operators with last-mile density, UV purification specialists with healthcare certification, and diversified appliance conglomerates with manufacturing scale. Competitive moves center on route density consolidation through subscription bundling and refrigerant architecture transitions ahead of regulatory deadlines.
Among North American platform operators, Primo Water Corporation exemplifies the direct-to-consumer archetype with its controlled last-mile delivery density. Waterlogic occupies a position within the purification-specialist tier, while Culligan International Company anchors the dealer-network archetype through extensive service technician pools. These three represent distinct competitive vectors: platform convergence, certification specialization, and network fragmentation respectively.
| Leading Market Players |
|---|
| Primo Water Corporation |
| Waterlogic |
| Culligan International Company |
| Midea Group |
| Avalon Water Coolers |
| Alfred Kärcher SE & Co. KG |
| Oasis International |
| Blue Star Limited |
| Elkay Manufacturing |
| Others |
Value Network & Pricing Analysis
Bavarian manufacturing clusters around Munich dictate cooler pricing power through R290 propane refrigerant specialization and hydrocarbon charge optimization below EU F-Gas thresholds. OEMs with captive German chemical partnerships command premium positioning against importers facing quota allocation bottlenecks.
Pricing Analysis
Current-generation hydrocarbon-based units carry 15-25% premiums over prior-generation HFC-dependent stock as refrigerant phase-out deadlines compress replacement cycles. Three-tier pricing structure across premium, standard, and economy levels separates certification-grade healthcare systems from cost-sensitive educational procurement. Price differentiation hinges on antimicrobial touchpoint materials and IoT telemetry integration. Cost compression in economy tiers is intensifying because REACH compliance constrains bio-based polymer sourcing flexibility. Educational institutions exhibit highest price sensitivity; Swiss hospital procurement shows lowest.
Supply Chain Analysis
Propane refrigerant feedstock draws from specialized German and Italian chemical facilities clustered around Ludwigshafen and Milan. Cooler manufacturing rests on compressor assemblies from Chinese tier-one suppliers, bio-based polymer housings certified under EU chemical safety protocols, and UV sterilization modules from Swiss component specialists. Single-source vulnerability concentrates in hydrocarbon refrigerant production during quota allocation periods. Distribution runs through direct-to-consumer platforms consolidating route density alongside fragmented dealer networks serving multi-unit residential contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bottled water cooler market sits in cyclical recovery as commercial building retrofit cycles in Germany and Switzerland accelerate replacement demand following pandemic-deferred capital expenditure.
For Market Incumbents: Pre-empt Point-of-Use substitution threats by bundling predictive replenishment analytics into subscription contracts that lock in multi-year corporate accounts. Hydrocarbon refrigerant architecture transitions ahead of EU F-Gas deadlines serve as the priority lever to disqualify import competitors lacking German chemical partnerships.
For New Entrants and Emerging Players: Build out last-mile delivery density in Benelux markets where facility management outsourcing concentrates purchasing power through per-employee hydration service fees. The most penetrable white-space sits in mid-range corporate installations seeking carbon-accounted systems for CSRD reporting alignment without premium-tier certification overhead.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because dealer network fragmentation across European markets creates roll-up opportunities for platform operators with route optimization software. The acquisition target archetype is regional service providers with dense technician pools but underutilized connected diagnostics capabilities. Watch hydrocarbon refrigerant quota allocation announcements as the inflection signal for manufacturing margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Architecture Transition | R290 propane adoption ahead of EU F-Gas deadlines locks in German OEM competitive positioning. |
| Subscription Service Bundling | Per-employee hydration fees displace capital purchase models in Dutch facility management outsourcing. |
| UV Purification Certification | Swissmedic antimicrobial touchpoint standards filter supplier qualifications in hospital procurement. |
| IoT Telemetry Integration | Predictive replenishment algorithms reduce distributor route density across North American direct platforms. |
| Dealer Network Consolidation | Route density optimization captures fragmented residential contracts in Italian multi-unit markets. |
Research Methodology
A standing panel of facility management directors, cooler OEM product managers, refrigerant supply specialists, and healthcare procurement officers provided ongoing calibration across the research cycle. Primary interviews triangulated against customs trade data for hydrocarbon refrigerant flows, EU F-Gas Regulation quota filings, SEC 10-K disclosures from listed hydration equipment manufacturers, and hospital procurement database extracts from German and Swiss GPOs. Bottom-up unit shipment modeling cross-checked with top-down market value reconstructions.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning installation type, end-user vertical, distribution channel, and price tier. CAGRs derived from fitted growth curves applied to refrigerant transition timelines and commercial building retrofit cycle data. Forecast inputs incorporated EU F-Gas stepped reduction mandates and CSRD disclosure adoption rates across corporate accounts.
Stress conditions across refrigerant supply disruptions, hydrocarbon safety compliance delays, and Point-of-Use substitution acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on replacement cycle timing and regulatory enforcement intensity. Cross-checking against cooler shipment data from German mechanical engineering associations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Canada Food Service Market
Food Service
Europe Food Away from Home Market
Food Service
Electric Tiffin Market
Food Service
Restaurants in Belgium Market
Food Service
Countertop Pressure Fryer Market
Food Service
Australia Foodservice Market
Food Service
Cloud Kitchen Market
Food Service
Asia-Pacific Food Away from Home Market
Food Service
Food and Grocery Retail Market
Food Service
United States Quick Service Restaurants Market
Food Service
Vacuum Flask Market
Food Service
Europe Out of Home (OOH) Delivery Market
Food Service
Philippines Quick Service Restaurants Market
Food Service
Commercial Restaurant Rangers Market
Food Service
Asia Pacific Airline Catering Services Market
Food Service
Food Truck Services Market