
 Milk Tea Powder Market | 2026-2036
Milk Tea Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Milk Tea Powder Market Foresight
Specialty beverage chain procurement is expanding across tier-two cities and suburban trade zones, fragmenting what was once concentrated urban demand. ITO EN leverages its integrated tea estate network to secure consistent raw material supply for powder formulations. Nestlé competes through R&D intensity in spray-drying technology that preserves volatile flavor compounds. Xiangpiaopiao Food anchors its position in China's domestic convenience channel with sachet-format instant powder portfolios.
Milk tea powder consists of finely processed blends containing tea extract, dairy or non-dairy creamer, sweeteners, and stabilizers, manufactured through spray-drying or freeze-drying to achieve solubility in ambient water. The product serves commercial food service operators and retail consumers seeking consistent beverage preparation without brewed tea infrastructure. Instant Powder dominates volume throughput due to shelf stability and logistics efficiency across tropical climates, while Concentrated Liquid captures premium margin pools in chained bubble tea operations. Food Service Providers represent the fastest-expanding customer type as franchise networks standardize recipes across multiple locations.
China's SAMR enforces GB standards for food additive disclosure and dairy analog labeling, directly shaping product formulation decisions for export-bound manufacturers. Japan's Ministry of Health, Labour and Welfare applies positive-list requirements for food contact materials in powder packaging. The FDA in the United States monitors imported milk tea powders for undeclared allergens and non-dairy creamer composition. Stakeholders must monitor evolving sweetener regulations across their priority export corridors and align R&D pipelines with clean-label certification trajectories.
Market Dynamics
Specialty beverage chains are consolidating procurement power through centralized sourcing hubs, forcing powder manufacturers to reconfigure production networks around franchise density zones rather than traditional port-centric distribution. This buyer-side concentration is compressing margin structures while elevating technical service requirements.
Growth Catalysts
- Spray-drying infrastructure expansion:Southeast Asian contract manufacturers are installing second-generation atomization lines capable of handling higher solids loads, reducing unit energy consumption for powder output.
- GB standards compliance as competitive filter:China's SAMR labeling mandates for non-dairy creamer disclosure are eliminating informal producers, creating volume redistribution toward certified export facilities.
- Bubble tea franchise standardization:Chained operators in Vietnam and Indonesia are mandating pre-mixed powder specifications to ensure taste consistency across 50-plus outlet networks.
Market Restraints
- Palm oil derivative cost volatility:Non-dairy creamer formulations depend on refined palm oil fractions whose pricing fluctuates with Malaysian export duty adjustments.
- Freeze-drying capacity concentration:Premium powder segments rely on equipment concentrated in Japanese and South Korean toll manufacturing facilities, creating single-source vulnerability.
- Clean-label substitution pressure:Fresh-brewed tea systems in upscale urban cafes are capturing consumers averse to additive-heavy powder ingredients.
Strategic Opportunities
- Philippine provincial market penetration:Davao and Cebu corridors show underdeveloped bubble tea infrastructure relative to Metro Manila, presenting first-mover positioning for powder distributors.
- EU Green Deal alignment:Reformulation toward plant-based creamers without hydrogenated oils qualifies certain powders for preferential tariff treatment under sustainability-linked trade frameworks.
- E-commerce direct-to-café channels:B2B marketplace platforms are collapsing traditional distributor layers, enabling manufacturers to capture margin previously allocated to wholesale intermediaries.
Industry Challenges
- Food technologist scarcity:Formulation expertise spanning emulsion stability and flavor encapsulation concentrates in Shanghai and Tokyo, constraining R&D scaling for second-tier producers.
- Dual certification timelines:Simultaneous pursuit of Halal and organic credentials for identical SKUs extends validation cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milk Tea Powder Market |
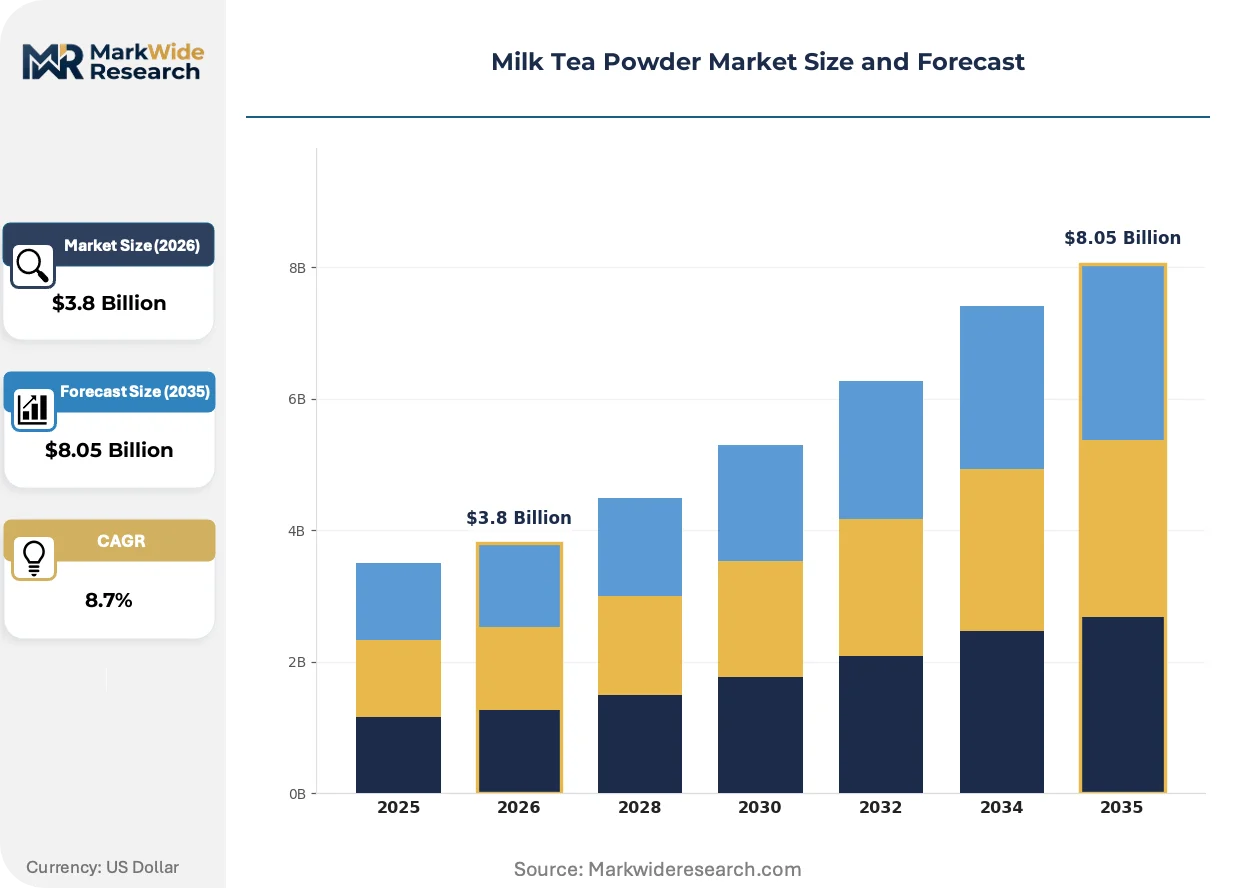
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Powder, Concentrated Liquid, Tea Bags, Ready-to-Drink Customer Type: Retail Consumers, Food Service Providers, E-commerce Platforms, Wholesalers Flavor: Classic Milk, Chocolate, Matcha, Fruit Variants Packaging Type: Bags, Tetra Packs, Bottles, Sachets |
| Companies Covered | ITO EN, Zhejiang Tea Group, Lipton (Unilever), Xiangpiaopiao Food, Fujian Tea Industry Group, Nestlé, Tata Consumer Products, Damin Food, Uni-President, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milk Tea Powder Market Shifts & Advancements
Clean-label reformulation and precision drying technologies are converging to redefine powder quality benchmarks, while regulatory disclosure requirements are accelerating transparency investments across the supply base.
Microencapsulation of volatile tea aromatics using modified starch matrices is expanding into premium instant powder lines, preserving flavor integrity through ambient storage. Chained bubble tea operators in Ho Chi Minh City and Jakarta are adopting these formulations for flagship menu items. The technology is expanding into mid-tier product tiers as equipment costs decline and toll manufacturing availability broadens.
China's SAMR enforcement of GB 7718 prepackaged food labeling standards is mandating explicit declaration of trans fat content and dairy analog origin on powder packaging. Manufacturers serving export markets must maintain parallel label inventories or reformulate to meet the strictest jurisdiction's requirements. Vietnamese import authorities are mirroring these disclosure expectations, affecting cross-border shipment documentation.
Café procurement committees are consolidating supplier rosters from twelve-plus vendors to three preferred partners with integrated technical service capabilities. This concentration is displacing spot-market purchasing in Indonesia's Greater Jakarta cluster. Procurement teams now prioritize manufacturers offering on-site barista training and equipment calibration support alongside powder supply.
Milk Tea Powder Market Segmentation
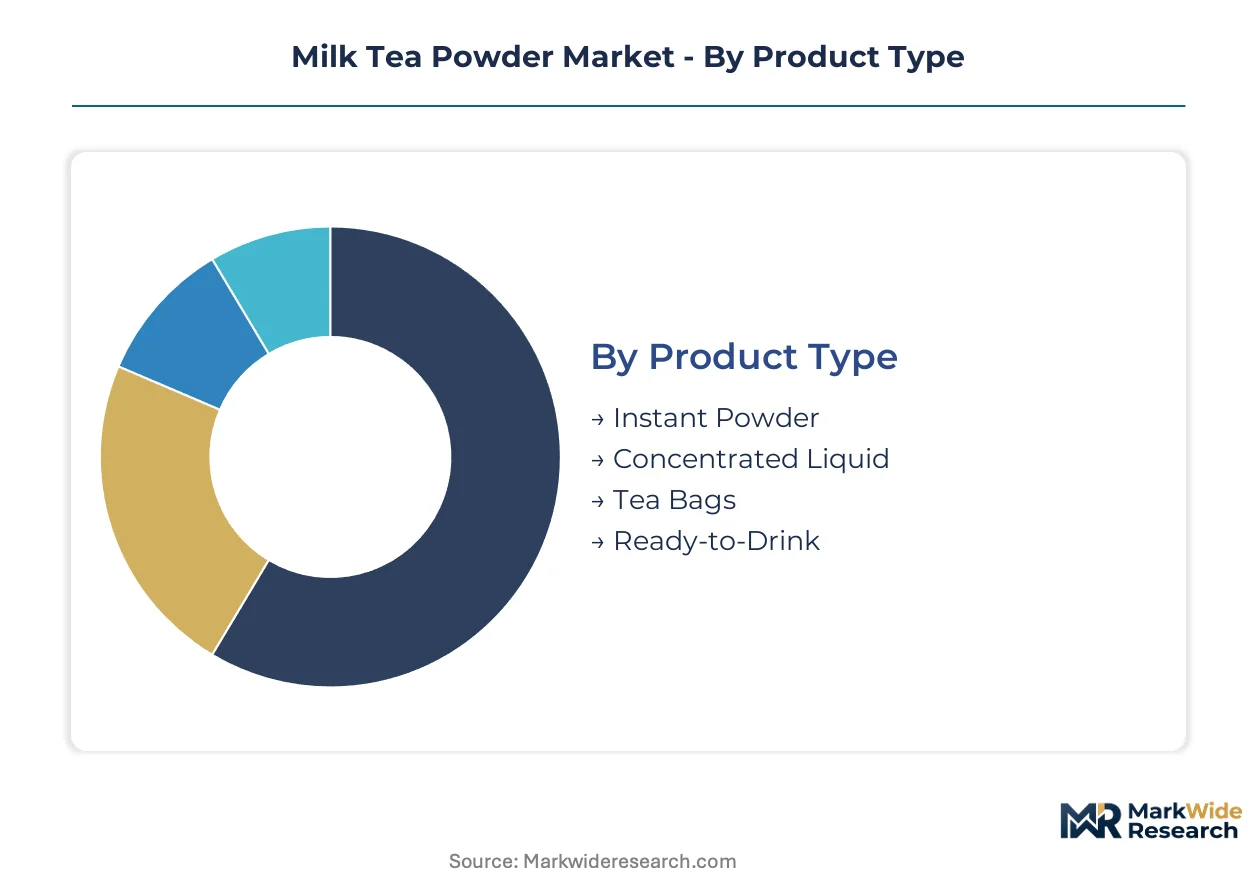
Milk tea powder segmentation reveals divergent capital requirements across production formats, with spray-drying infrastructure demanding heavy fixed investment while liquid concentration lines offer lower entry thresholds. Understanding these structural economics helps stakeholders align capacity decisions with margin profiles and customer concentration patterns.
Product Type:
Capital intensity varies sharply across production technologies, with thermal processing infrastructure representing the dominant upfront commitment.
- Instant Powder:Spray-drying towers and atomization systems require substantial fixed investment, with energy-intensive operations concentrated in Vietnam and Indonesia to serve tropical logistics corridors. Ho Chi Minh City contract manufacturers absorb the bulk of installed capacity as chained bubble tea operators mandate standardized powder specifications across 50-plus outlet networks.
- Concentrated Liquid:Lower thermal processing requirements enable faster capacity scaling, though cold-chain distribution adds recurring operational cost. Greater Jakarta bubble tea clusters drive demand concentration as franchise procurement committees consolidate supplier rosters toward integrated technical service partners.
- Tea Bags:Minimal processing infrastructure beyond blending and packaging equipment, with demand anchored in China's domestic convenience channel.
- Ready-to-Drink:Aseptic filling lines and extended shelf-life formulation require beverage-grade manufacturing certification, limiting viable production sites.
Instant Powder absorbs the bulk of installed capacity; Concentrated Liquid is expanding most quickly.
Customer Type:
Volume concentration patterns diverge between fragmented retail channels and consolidating institutional procurement.
- Food Service Providers:Centralized sourcing hubs in Vietnam and Indonesia are compressing supplier margins while elevating technical service requirements, with chained operators mandating on-site barista training and equipment calibration support. This segment captures the steepest expansion trajectory as franchise networks standardize recipes across multiple locations.
- Retail Consumers:Sachet-format portfolios in China's domestic market anchor volume, with convenience channel penetration driving repeat purchase frequency.
- E-commerce Platforms:B2B marketplace channels are collapsing traditional distributor layers, enabling manufacturers to capture margin previously allocated to wholesale intermediaries.
- Wholesalers:Traditional port-centric distribution faces displacement as procurement gravity shifts toward franchise density zones.
Food Service Providers command the fastest volume growth; Retail Consumers retain the largest absolute transaction base.
Flavor:
Formulation complexity and raw material sourcing economics shape competitive positioning across taste profiles.
- Classic Milk:Non-dairy creamer dependency exposes producers to refined palm oil fraction cost volatility linked to Malaysian export duty adjustments. Demand concentrates in Indonesia's Greater Jakarta cluster where chained operators prioritize taste consistency.
- Matcha:Premium Japanese tea estate sourcing requires integrated supply relationships, with ITO EN leveraging captive production networks for consistent raw material access.
- Chocolate:Cocoa derivative procurement and flavor stability formulation add processing complexity.
- Fruit Variants:Volatile aromatic preservation demands microencapsulation investment, currently expanding from premium tiers into mid-market lines as equipment costs decline.
Classic Milk dominates current production runs; Matcha commands the highest margin expansion potential.
Packaging Type:
Packaging technology selection directly interfaces with shelf-life requirements and distribution climate resilience.
- Sachets:Minimal material cost and ambient stability suit tropical logistics, with Xiangpiaopiao Food anchoring China's convenience channel through single-serve format dominance.
- Bags:Bulk formats serve food service procurement with lower per-unit packaging overhead.
- Tetra Packs:Aseptic carton technology enables liquid format shelf stability without refrigeration.
- Bottles:Ready-to-drink positioning requires beverage-grade filling infrastructure and extended distribution partnerships.
Sachets represent the most widely deployed format; Tetra Packs are gaining share in liquid concentrate segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates most visibly in Vietnam's Ho Chi Minh City corridor and Indonesia's Greater Jakarta bubble tea cluster, with procurement gravity shifting toward franchise density zones rather than traditional port-centric distribution.
China
Centralized sourcing hubs in Shanghai and Shenzhen are compressing supplier margins while elevating technical service requirements. SAMR enforcement of GB 7718 prepackaged food labeling standards mandates explicit declaration of trans fat content and dairy analog origin. Yangtze River Delta contract manufacturers absorb the bulk of installed spray-drying capacity as chained operators standardize recipes.
Vietnam
Chained bubble tea operators in Ho Chi Minh City are mandating pre-mixed powder specifications across 50-plus outlet networks. Vietnamese import authorities mirror China's disclosure expectations for cross-border shipment documentation. The southern corridor dominates volume throughput as franchise procurement committees consolidate supplier rosters.
Indonesia
Greater Jakarta's bubble tea cluster drives demand concentration as centralized sourcing hubs fragment what was once concentrated urban demand. Halal certification requirements from the country's national food and drug regulator shape export-bound formulation decisions. Distributors face displacement as B2B marketplace platforms collapse traditional wholesale layers.
Japan
Premium powder segments rely on freeze-drying equipment concentrated in toll manufacturing facilities, creating single-source vulnerability. The Ministry of Health, Labour and Welfare applies positive-list requirements for food contact materials in powder packaging. Kanto region specialists anchor integrated tea estate networks for consistent raw material supply.
Philippines
Davao and Cebu corridors show underdeveloped bubble tea infrastructure relative to Metro Manila, presenting first-mover positioning for powder distributors. The country's national food and drug regulator enforces labeling alignment with ASEAN harmonized standards. Provincial market penetration lags as procurement committees prioritize technical service capabilities.
Milk Tea Powder Market Competitive Landscape
Chinese producers anchor one tier; Japanese specialists hold premium freeze-drying capabilities. The vendor base fragments across integrated beverage conglomerates and regional tea estate operators. Three strategic archetypes dominate: integrated tea estate networks, spray-drying technology licensors, and convenience-channel sachet specialists. Competitive moves center on backward integration into raw material supply and geographic expansion through franchise procurement consolidation.
Within the integrated estate tier, ITO EN represents captive production network advantages, while Nestlé occupies a position emphasizing R&D intensity in drying technology preservation. Xiangpiaopiao Food exemplifies the convenience-channel archetype through domestic market sachet-format dominance. These three anchors illustrate how competitive positioning diverges across supply chain control, technical service depth, and retail channel penetration.
| Leading Market Players |
|---|
| ITO EN |
| Zhejiang Tea Group |
| Lipton (Unilever) |
| Xiangpiaopiao Food |
| Fujian Tea Industry Group |
| Nestlé |
| Tata Consumer Products |
| Damin Food |
| Uni-President |
| Others |
Supply & Pricing Matrix
Refined palm oil fraction benchmarks cascade through non-dairy creamer formulations into three-tier pricing structures across premium, standard, and economy levels, with Malaysian export duty adjustments compressing margins for spot-market purchasers while contract buyers lock in stability.
Pricing Analysis
Volume throughput concentrates in instant powder formats while freeze-dried variants capture premium margins. Three-tier pricing structure across premium, standard, and economy levels stratifies by microencapsulation sophistication and Halal certification grade. Cost compression in standard tiers intensifies because chained bubble tea operators consolidate procurement rosters, squeezing spot-market suppliers. Retail consumers through China's convenience channel exhibit highest price sensitivity; chained food service providers prioritize technical service bundling over unit cost.
Supply Chain Analysis
Freight cost volatility for tropical climate distribution shapes manufacturer location decisions, with Ho Chi Minh City and Greater Jakarta emerging as procurement gravity centers. Spray-drying capacity concentrates in Vietnam, Indonesia, and China's Yangtze River Delta, drawing from tea extract, refined palm oil fractions, and modified starch matrices. Single-source vulnerability persists for freeze-drying equipment tethered to Japanese and South Korean toll facilities. Distribution runs through B2B marketplace platforms collapsing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The milk tea powder market functions as a vertical-integration race where captive tea estate control and spray-drying technology ownership determine margin capture. Players are pursuing backward integration into raw material supply as the decisive lever.
For Market Incumbents: To counter procurement consolidation by chained bubble tea operators, secure captive tea estate networks in Fujian or Zhejiang provinces and expand spray-drying capacity in Vietnam's southern corridor. Invest in dual Halal-organic certification pipelines to maintain roster eligibility with Indonesian franchise committees. For New Entrants and Emerging Players: E-commerce direct-to-café channels offer lowest barrier entry, targeting Davao and Cebu corridors where bubble tea infrastructure lags Metro Manila. White-space exists in mid-tier microencapsulated fruit variants as equipment costs decline. Prioritize technical service partnerships over price competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor contract manufacturers with installed spray-drying towers in Vietnam or Indonesia. Long-term viability hinges on clean-label reformulation capabilities and integrated estate access. Watch for SAMR enforcement actions as inflection indicators for volume redistribution toward certified export facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tea Estates | Captive supply from Fujian or Zhejiang plantations secures raw material consistency for powder formulations. |
| Spray-Drying Capacity Expansion | Second-generation atomization lines in Vietnam reduce energy consumption per powder output unit. |
| Dual Certification Investment | Parallel Halal and organic validation opens procurement rosters with Indonesian franchise networks. |
| B2B Marketplace Channel Development | Direct-to-café platforms capture margin previously allocated to wholesale intermediaries in Greater Jakarta. |
| Microencapsulation Technology Licensing | Modified starch matrices for volatile tea aromatics differentiate premium powder lines for chained operators. |
Research Methodology
Multi-period observation of spray-drying capacity installations, franchise outlet expansion rates, and SAMR regulatory filings anchored the trend analysis, supplemented by interviews with contract manufacturing executives, bubble tea franchise procurement heads, food technologists specializing in emulsion stability, and convenience channel category managers. Secondary validation drew from China customs export records, Indonesian BPOM regulatory databases, Vietnam industry association capacity surveys, and ASEAN food additive harmonization protocols. Bottom-up facility capacity modeling and top-down demand segmentation were triangulated against each other.
Input-output matrices mapped tea extract supply, creamer formulation costs, and distribution logistics across production format, customer type, flavor profile, and packaging technology dimensions throughout the forecast period. CAGRs were derived from installed capacity trajectories, franchise network expansion plans, and regulatory compliance timelines. Industry-specific forecast inputs included Malaysian palm oil export duty cycles and microencapsulation equipment cost decline curves.
Inputs from regulatory filing databases and contract manufacturer disclosures were available through the study window; gaps in informal producer output estimates introduce uncertainty bands around China market sizing. Forecasts reflect documented assumptions regarding franchise standardization rates and clean-label substitution velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Kombucha Market
Beverages
Carbonate Drink Maker Market
Beverages
Carbonated Soft Drinks Market
Beverages
Growlers Market
Beverages
Sports Drink Market
Beverages
Probiotic Beverage Market
Beverages
US and Canada Tonic Water Market
Beverages
Morocco Bottled Water Market
Beverages
Middle East and Africa Fruits and Vegetable Juice Market
Beverages
Smoothies Market
Beverages
Europe Smoothies Market
Beverages
India Bottled Water Market
Beverages
Fermented Drinks Market
Beverages
Asia Pacific Fermented Drinks Market
Beverages
Grape Juice Concentrate for Wine Making Market
Beverages
Packaged Cactus Water Market