
 Volatile Fatty Acids Market | 2026-2036
Volatile Fatty Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Volatile Fatty Acids Market Analytics
The Volatile Fatty Acids Market is pivoting on a widening split between pharmaceutical-grade purity tiers and commodity feed-grade volumes. Eastman Chemical Company leverages its integrated acetic acid platform to dominate high-specification solvent applications. Kao Corporation anchors its position in personal care and pharmaceutical intermediates through specialized fatty acid derivatives. BASF competes across both tiers, extending its reach from industrial chemical manufacturing into food preservation and animal nutrition segments.
Volatile fatty acids comprise short-chain carboxylic acids—primarily acetic, propionic, butyric, and valeric acids—typically containing two to five carbon atoms, produced through petrochemical synthesis or anaerobic fermentation of biomass. These compounds function as platform chemicals for preservatives, feed additives, and biofuel precursors, with purity specifications ranging from technical grade to food and pharmaceutical grades exceeding 99.5 percent concentration. Acetic acid occupies the largest volume share, serving as a backbone for vinyl acetate monomer and purified terephthalic acid production. Butyric acid represents the fastest-expanding category, driven by gut health applications in monogastric animal feeds and encapsulation technologies that improve palatability. The pharmaceutical application segment captures the deepest margin pools, where propionic acid derivatives command premium pricing for antifungal and anti-inflammatory formulations.
The EPA regulates volatile organic compound emissions from acetic acid manufacturing facilities under the National Emission Standards for Hazardous Air Pollutants, while REACH mandates registration and safety assessment for imports into the European Union. China's MEE enforces wastewater discharge standards that favor biological production routes over petrochemical pathways. Stakeholders must monitor tightening carbon intensity thresholds and feedstock traceability requirements that will determine which production technologies secure long-term offtake agreements.
Market Dynamics
Biological production routes are displacing petrochemical synthesis as the EU F-Gas Regulation and China's dual carbon goals tighten emissions standards for acetic acid and propionic acid manufacturing. Feedstock traceability requirements now determine which producers secure long-term offtake agreements with animal nutrition and pharmaceutical formulators.
Growth Catalysts
- EU Green Deal carbon intensity thresholds:The regulation favors anaerobic fermentation of agricultural waste over fossil-based pathways, redirecting capital toward biorefinery infrastructure in the Netherlands and Denmark.
- Monogastric feed gut health applications:Encapsulated butyric acid addresses antibiotic growth promoter bans, with livestock producers in Spain and Poland adopting microencapsulation technologies for palatability improvement.
- China's biofuel mandates:The MIIT policy accelerates volatile fatty acid recovery from rice straw and corn stover as precursors for advanced biofuel production.
Market Restraints
- Natural gas feedstock volatility:Steam reforming costs for synthetic acetic acid fluctuate with European TTF pricing, compressing margins for petrochemical producers in Germany and Belgium.
- Pharmaceutical-grade purification bottlenecks:Crystallization and distillation capacity for 99.5%+ purity grades concentrates in Switzerland and Japan, creating supply concentration risk.
- Propionic acid substitution in food preservation:Sorbates and benzoates displace synthetic propionates in bakery applications, particularly in France and Italy where clean-label preferences intensify.
Strategic Opportunities
- India's PLI scheme for biomanufacturing:The incentive framework attracts fermentation-based propionic acid investments targeting pharmaceutical intermediates and antifungal formulations.
- Carbon capture integration with anaerobic digestion:Biogas upgraders in Sweden and Finland are coupling volatile fatty acid extraction with CO2 liquefaction for circular chemical production.
- Veterinary prescription feed channels:Direct distribution to swine and poultry integrators bypasses commoditized trader networks, capturing margin in Denmark and the Netherlands.
Industry Challenges
- Pharmaceutical GMP certification timelines:EMA and FDA validation for excipient-grade butyric acid requires 18-24 month qualification periods, delaying market entry for new fermentation entrants.
- Anaerobic microbiome engineering talent scarcity:Metabolic pathway optimization for mixed-culture VFA yields demands specialized synthetic biology expertise concentrated in Danish and German research clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Volatile Fatty Acids Market |
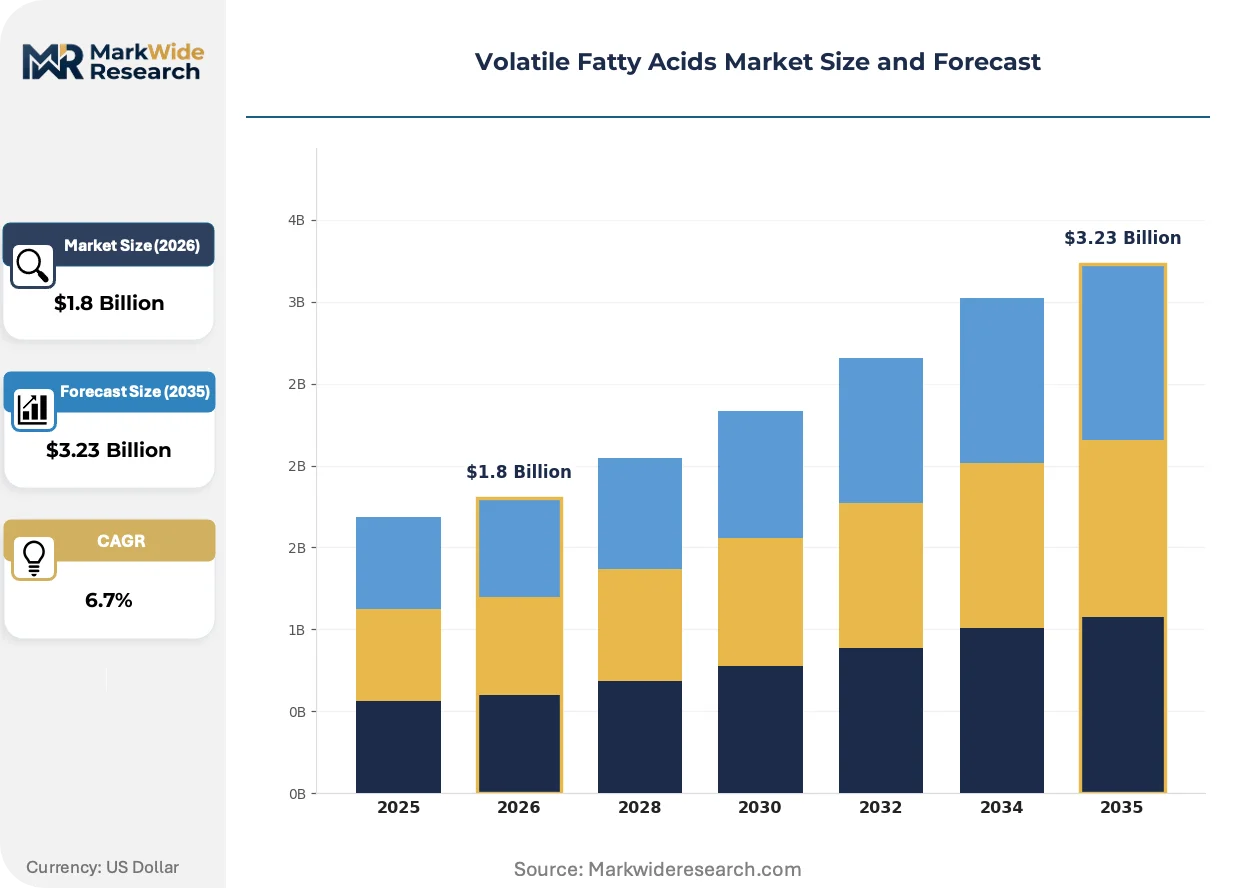
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetic Acid, Propionic Acid, Butyric Acid, Valeric Acid Application: Animal Feed, Food Preservation, Pharmaceutical, Biofuels End User: Agriculture, Food Industry, Healthcare, Chemical Manufacturing Distribution Channel: Online Sales, Direct Sales, Retail Outlets, Wholesalers |
| Companies Covered | AppliTek NV, Kao Corporation, Eastman Chemical Company, KLK OLEO, Wilmar International Ltd., Merck KGaA, BASF, Godrej Industries, Hach Company Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Volatile Fatty Acids Market Evolving Landscape
In-line spectroscopic monitoring is compressing batch cycle times and purity variability in fermentation-based production. Real-time process control now enables dynamic feed adjustment that was previously manual and reactive.
Electrochemical membrane separation is automating the recovery of individual volatile fatty acids from complex fermentation broths. Pharmaceutical manufacturers in Switzerland and Japan are retrofitting existing acetic acid plants with bipolar electrodialysis stacks. The technology is automating what required energy-intensive distillation sequences, reducing thermal input costs by half for high-purity grades.
REACH authorization requirements for synthetic C3-C5 acids are tightening substance volume tracking across the European Economic Area. ECHA's SCIP database mandates disclosure of VFA-containing articles in automotive and construction supply chains. German chemical distributors are restructuring inventory management systems to accommodate serialized substance flow documentation.
Consolidated procurement by integrated livestock multinationals is displacing fragmented feed compounder purchasing. Swine and poultry integrators in Denmark and the Netherlands now contract directly with butyric acid encapsulators for multi-year supply security. The shift concentrates volume commitments among three to four producers per protein category, compressing spot market liquidity.
Volatile Fatty Acids Market Segmentation
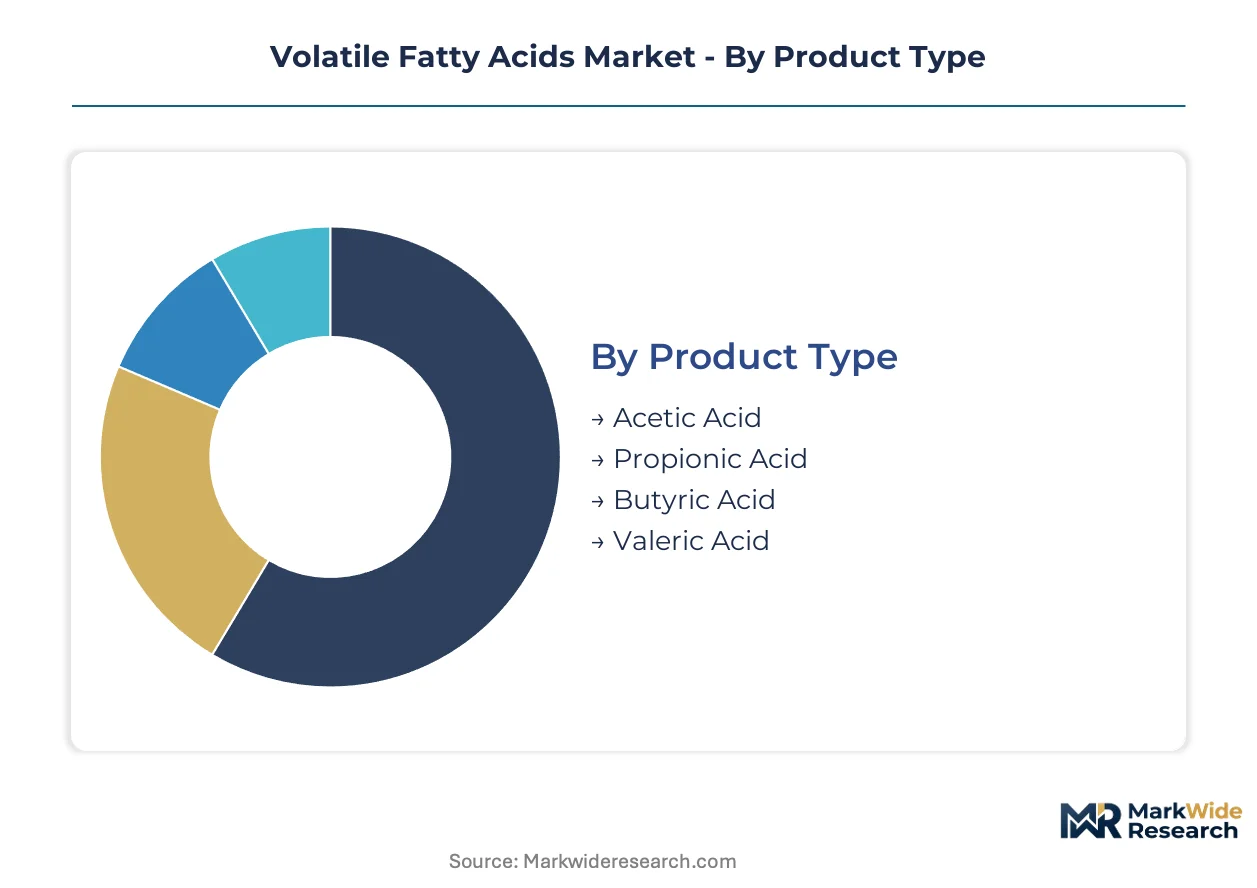
Volatile fatty acid producers navigate divergent certification pathways across product tiers, with pharmaceutical and food-grade specifications demanding GMP validation while technical grades face emissions compliance. Segmentation clarity determines which production assets can pivot between margin pools without costly requalification delays.
Product Type:
Certification burden intensifies with carbon chain length, as butyric and valeric acids for pharmaceutical use require EMA or FDA excipient validation, while acetic acid volumes flow predominantly through industrial chemical registrations.
- Acetic Acid:Two-carbon carboxylic acid serving as backbone chemistry for vinyl acetate monomer and purified terephthalic acid synthesis. Demand concentrates in China and Germany where polyester manufacturing clusters absorb technical-grade volumes, though REACH registration costs disadvantage smaller European producers against integrated petrochemical majors.
- Butyric Acid:Four-carbon short-chain fatty acid increasingly deployed in encapsulated forms for monogastric gut health applications. Spanish and Polish livestock integrators are contracting directly with microencapsulation specialists, bypassing commoditized feed compounder networks as antibiotic growth promoter bans tighten across the EU.
- Propionic Acid:Three-carbon preservative acid facing substitution pressure from sorbates in French and Italian clean-label bakery applications.
- Valeric Acid:Five-carbon specialty acid concentrated in Swiss and Japanese pharmaceutical intermediate manufacturing.
Acetic acid sits at the top of the volume ranking, with butyric acid climbing the fastest.
Application:
Margin structure varies dramatically across use cases, with pharmaceutical formulations commanding five-to-tenfold premiums over commodity feed applications and biofuel precursor volumes trading on carbon credit eligibility rather than chemical value alone.
- Animal Feed:Encapsulated butyric acid products addressing gut health in swine and poultry production. Danish and Dutch integrators are consolidating procurement through direct veterinary prescription channels, concentrating multi-year supply agreements among three to four producers per protein category and eroding spot market liquidity for unencapsulated grades.
- Pharmaceutical:Propionic acid derivatives for antifungal and anti-inflammatory formulations, plus butyric acid excipients requiring 18-24 month GMP qualification timelines. Swiss and Japanese purification specialists control crystallization capacity for 99.5%+ grades, creating supply concentration risk for fermentation-based entrants seeking market access.
- Food Preservation:Synthetic propionates for bakery shelf-life extension facing displacement by benzoates and sorbates in premium clean-label segments.
- Biofuels:Mixed VFA streams from agricultural waste fermentation serving as advanced biofuel precursors under China's MIIT mandates.
Animal feed dominates current volume flows, while pharmaceutical applications capture the steepest margin expansion trajectory.
End User:
Customer sophistication determines specification stringency, with healthcare and food industry buyers imposing batch-level traceability requirements that agricultural and chemical manufacturing offtakers rarely demand.
- Agriculture:Livestock producers and feed compounders purchasing encapsulated butyric acid for monogastric gut health. Consolidated procurement by Danish and Dutch swine and poultry integrators is displacing fragmented purchasing patterns, with direct manufacturer contracts replacing distributor intermediation.
- Healthcare:Pharmaceutical formulators and excipient manufacturers requiring GMP-certified propionic and butyric acid derivatives. EMA validation timelines and FDA facility inspections create 18-24 month entry barriers for new fermentation-based suppliers.
- Food Industry:Bakery and processed food manufacturers deploying propionates for mold inhibition.
- Chemical Manufacturing:Industrial consumers of acetic acid for vinyl acetate monomer and PTA synthesis, concentrated in China and Germany.
Agriculture represents the largest end-use volume, with healthcare gaining share fastest on margin expansion.
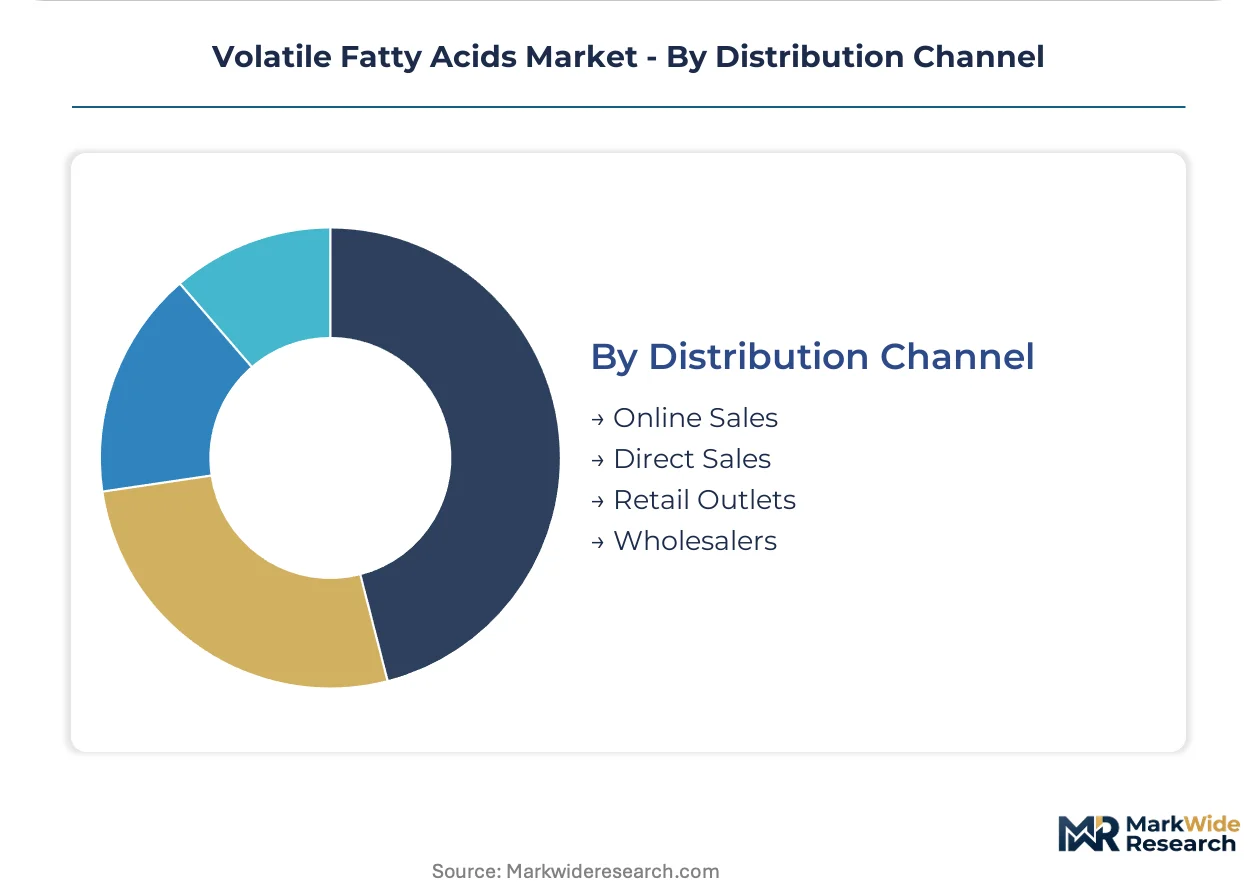
Distribution Channel:
Channel selection reflects customer scale and specification complexity, with pharmaceutical and large agricultural integrators favoring direct relationships while smaller compounders and regional food manufacturers remain dependent on distributor networks.
- Direct Sales:Long-term supply agreements between VFA producers and large livestock integrators, pharmaceutical formulators, and chemical manufacturers. Danish and Dutch swine and poultry producers are contracting directly with encapsulation specialists for multi-year supply security, bypassing traditional feed compounder intermediation.
- Online Sales:Digital procurement platforms for standardized technical-grade acetic acid and commodity feed additives.
- Wholesalers:Regional chemical distributors managing inventory for smaller food preservation and industrial customers.
- Retail Outlets:Limited channel for specialty agricultural and food-grade VFA products.
Direct sales channels command the largest volume share, with online platforms expanding most quickly for commoditized grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized anaerobic microbiome engineering talent concentrates in Danish and German research clusters, anchoring biological production innovation. Swiss and Japanese purification specialists control pharmaceutical-grade crystallization capacity. China's MIIT policy accelerates agricultural waste-to-VFA infrastructure deployment.
China
Rice straw and corn stover feedstock availability drives anaerobic fermentation capacity expansion. MIIT biofuel mandates require VFA recovery from agricultural waste streams as advanced biofuel precursors. Industrial biotechnology investments concentrate in Jiangsu and Shandong provinces where biorefinery clusters process crop residues.
Germany
Steam reforming cost volatility from European TTF natural gas pricing compresses synthetic acetic acid margins. REACH registration requirements and EU F-Gas Regulation emissions standards favor biological production routes. North Rhine-Westphalia hosts petrochemical majors integrating carbon capture with existing acetic acid infrastructure.
Denmark
Swine and poultry integrators consolidate procurement through direct veterinary prescription channels for encapsulated butyric acid. EU Green Deal carbon intensity thresholds redirect capital toward biorefinery infrastructure. Copenhagen-Aarhus corridor anchors metabolic pathway optimization research for mixed-culture VFA yields.
Switzerland
Pharmaceutical-grade purification bottlenecks concentrate crystallization and distillation capacity for 99.5%+ purity grades. EMA GMP validation timelines create 18-24 month entry barriers for new fermentation entrants. Basel-Zurich corridor controls excipient-grade butyric acid qualification for antifungal formulations.
India
PLI scheme incentives attract fermentation-based propionic acid investments targeting pharmaceutical intermediates. CDSCO regulatory alignment with ICH standards enables export-oriented GMP certification. Maharashtra and Gujarat host emerging biomanufacturing clusters serving domestic and Middle Eastern pharmaceutical formulators.
Volatile Fatty Acids Market Competitive Landscape
Capital-heavy petrochemical producers compete with asset-light fermentation technology licensors for market positioning. The vendor base stratifies across three tiers: integrated chemical majors with acetic acid platforms, specialized fatty acid derivative houses, and regional agricultural processors upgrading waste streams. Dominant competitive moves include backward integration into feedstock supply and geographic expansion through distribution partnerships in high-growth Asian markets.
Within the integrated chemical tier, Eastman Chemical Company and BASF anchor positions spanning industrial solvent and food preservation applications. Kao Corporation exemplifies the specialized derivative archetype, concentrating personal care and pharmaceutical intermediate manufacturing. Among emerging biological producers, Godrej Industries and Wilmar International Ltd. occupy positions linking agricultural commodity processing to fermentation-based VFA output.
| Leading Market Players |
|---|
| AppliTek NV |
| Kao Corporation |
| Eastman Chemical Company |
| KLK OLEO |
| Wilmar International Ltd. |
| Merck KGaA |
| BASF |
| Godrej Industries |
| Hach Company Inc. |
| Others |
Value Network & Pricing Analysis
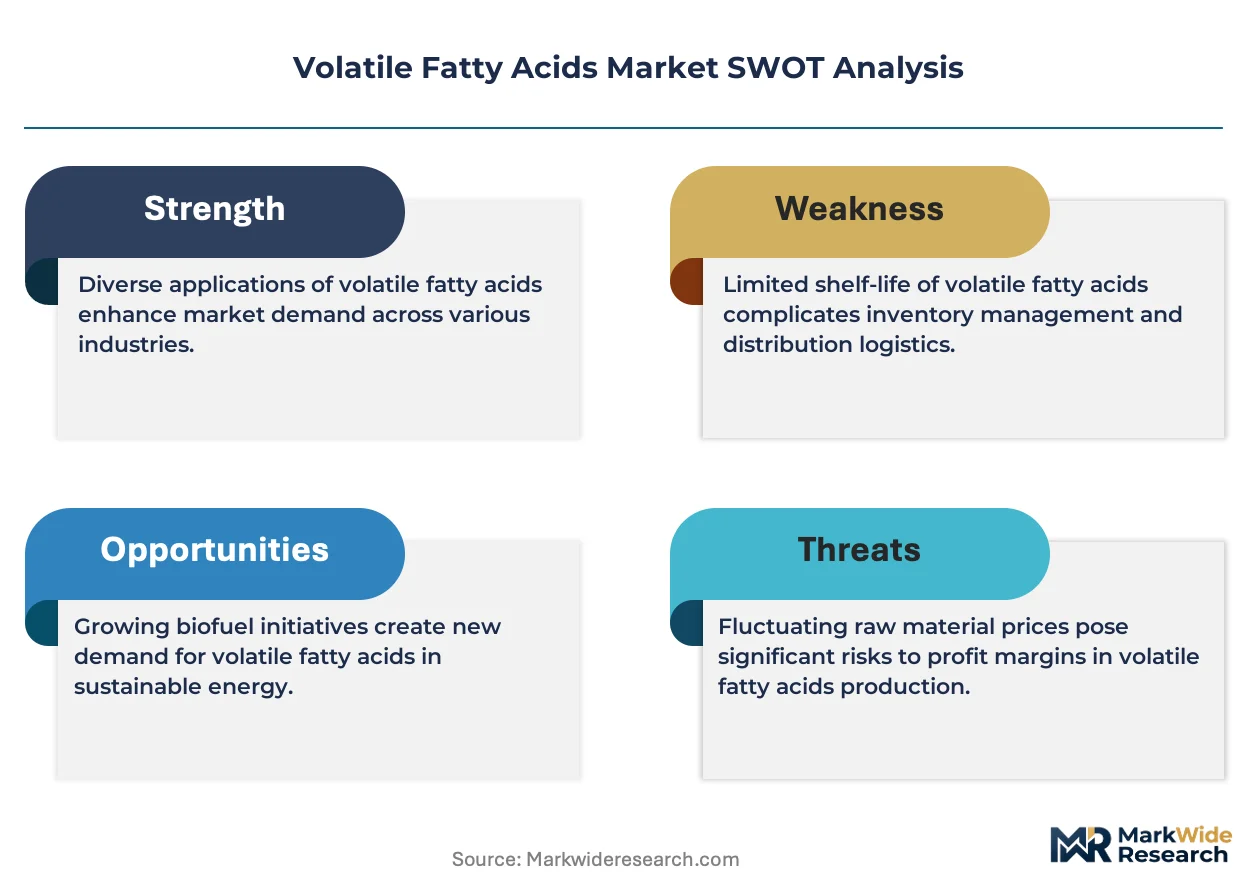
EU F-Gas Regulation carbon intensity thresholds gate qualified supply for premium-tier volatile fatty acid grades, restricting pharmaceutical-grade butyric acid access to producers with validated fermentation pathways and crystallization capacity. This environmental mandate simultaneously elevates pricing power for Swiss and Japanese purification specialists while compressing margins for German petrochemical acetic acid exposed to European TTF volatility.
Pricing Analysis
Bundled encapsulation services command substantial premiums over unencapsulated butyric acid commodity volumes. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade levels reflects certification burden and purity specifications, with EMA-validated excipient grades capturing five-to-tenfold multiples over feed-grade baselines. Cost compression in synthetic acetic acid is intensifying because European natural gas feedstock volatility erodes steam reforming economics. Agricultural integrators in Denmark and the Netherlands demonstrate lowest price sensitivity through multi-year direct contracts, while fragmented feed compounders in Southern Europe face acute margin pressure from spot market exposure.
Supply Chain Analysis
Direct-to-integrator channels handle consolidated livestock demand in Denmark and the Netherlands, while distributor networks serve fragmented food preservation and industrial customers. Geographic supply concentration centers on China for agricultural waste fermentation capacity, Germany for petrochemical acetic acid infrastructure, and Switzerland plus Japan for pharmaceutical-grade purification. Raw material flows draw from rice straw and corn stover in Jiangsu province, North Sea natural gas for steam reforming, and specialized anaerobic microbiome cultures from Copenhagen-Aarhus research clusters. Single-source vulnerability concentrates in Swiss crystallization capacity for 99.5%+ grades, creating supply concentration risk for fermentation entrants seeking pharmaceutical qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as antibiotic growth promoter bans across the EU redirect livestock procurement toward encapsulated butyric acid with proven gut health efficacy.
For Market Incumbents: Lock in multi-year supply agreements with Danish and Dutch swine and poultry integrators before fermentation-based competitors achieve GMP qualification. Prioritize backward integration into agricultural waste feedstock supply in China's Jiangsu and Shandong provinces to secure carbon credit eligibility under MIIT biofuel mandates. Defensive capacity expansion in pharmaceutical-grade crystallization addresses the 18-24 month EMA validation bottleneck threatening new entrant displacement. For New Entrants and Emerging Players: Begin with India's PLI scheme incentives for fermentation-based propionic acid targeting CDSCO-aligned pharmaceutical intermediates. The most penetrable white space sits in veterinary prescription feed channels bypassing commoditized trader networks, with Maharashtra and Gujarat biomanufacturing clusters offering regulatory alignment with ICH export standards. Direct distribution partnerships with Middle Eastern pharmaceutical formulators provide go-to-market acceleration without Swiss-Japanese purification incumbent confrontation. For Investors and Strategic Acquirers: Roll-up economics work for regional agricultural processors upgrading waste streams because fragmented feedstock collection infrastructure lacks scaled fermentation capacity integration. Long-term viability hinges on carbon intensity threshold compliance across the EU-China regulatory corridor. Acquisition targets should demonstrate validated anaerobic microbiome engineering partnerships with Danish or German research clusters. The inflection signal to monitor is EMA GMP certification timeline compression for excipient-grade butyric acid entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Waste Feedstock | Secures carbon credit eligibility under China's MIIT biofuel mandates for Jiangsu biorefineries. |
| Pharmaceutical GMP Certification Investment | Addresses 18-24 month EMA validation barriers blocking fermentation entrant market access. |
| Encapsulation Technology Licensing | Captures gut health application premiums as Spanish and Polish integrators adopt microencapsulation. |
| Carbon Capture Integration with Anaerobic Digestion | Aligns Swedish and Finnish biogas upgraders with EU Green Deal circular chemical production thresholds. |
| Direct Veterinary Prescription Channel Development | Bypasses commoditized feed compounder networks in Denmark and Netherlands livestock procurement consolidation. |
Research Methodology
Bottom-up animal feed and pharmaceutical formulation modeling reconciled against top-down biorefinery capacity and trade flow tracking forms the analytical core. Primary interviews with plant managers at German petrochemical facilities, procurement leads at Danish livestock integrators, technical R&D directors in Swiss purification operations, and distribution channel partners across European chemical networks combined with secondary validation from customs and trade data, Cefic industry reports, SEC 10-K filings, and ECHA registration databases. Triangulation across these sources calibrated production volume estimates against downstream consumption patterns.
Historical trendline analysis of acetic acid and butyric acid production economics established baseline growth trajectories across the projection horizon. The segmentation framework modeled grade tier, end-use industry, and regional production hub dimensions with CAGRs derived from elasticity analysis of carbon intensity threshold compliance costs and feedstock substitution patterns. Industry-specific forecast inputs incorporated MIIT biofuel mandate implementation pace and EU antibiotic growth promoter ban enforcement timelines.
Several conditions sit outside the modeled scope, including abrupt natural gas price dislocations beyond European TTF historical volatility bands and unanticipated REACH authorization withdrawals for synthetic C3-C5 acids. Forecasts reflect assumptions about EMA GMP certification timeline stability and anaerobic microbiome engineering talent availability in Danish and German research clusters. Periodic stress-testing of base assumptions is recommended against regulatory enforcement variance and agricultural waste feedstock supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Dill Seed Oil Market
Ingredients
Glucose (Dextrose) Market
Ingredients
Microencapsulated Oil Market
Ingredients
India Soy Protein Market
Ingredients
Trait Enhanced Oils Market
Ingredients
Algae Omega-3 Ingredients Market
Ingredients
Stock Cubes Market
Ingredients
Chickpea Flour Market
Ingredients
North America Feed Yeast Market
Ingredients
Glucuronolactone Market
Ingredients
Coconut Oil Based Products Market
Ingredients
Low-Odor Fish Protein Hydrolysates from Med Species Market
Ingredients
Carotenes Market
Ingredients
North America Vegetable Oils Market
Ingredients
Animal and Marine Fats and Oils Market
Ingredients
Tryptose Market