
 Europe Silicone Market | 2026-2036
Europe Silicone Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Silicone Market Foresight
German chemical producers is realigning silicone polymer output toward medical-grade and electric vehicle specifications. Wacker Chemie AG leverages its Burghausen integrated site to sustain captive siloxane supply for specialty elastomers. Dow Inc anchors Western European distribution through its Barry, Wales manufacturing complex and controls regional fluid silicone pricing. Elkem ASA competes on ferrosilicon backward integration, extending cost advantages into silicone intermediate production.
Silicone denotes a synthetic polymer chain of alternating silicon and oxygen atoms with organic side groups, typically produced via direct synthesis of silicon metal with methyl chloride followed by hydrolysis and polymerization; its thermal stability spans minus sixty to over two hundred degrees Celsius, enabling sealing, insulation, and biocompatible applications across demanding environments. Liquid silicone rubber leads product type revenue due to injection molding efficiency in medical device and automotive component fabrication, while silicone resins capture concentrated margin pools in electronics conformal coatings where thermal resistance commands premium positioning. Solid silicone rubber retains volume dominance in construction sealants across Southern European building renovation programs.
REACH registration requirements administered by ECHA govern monomer and crosslinker import volumes, while the EU F-Gas Regulation indirectly redirects fluoropolymer demand toward silicone alternatives in sealing and gasket applications. The EU Medical Device Regulation imposes biological evaluation standards that filter subscale compounders from healthcare supply chains. Stakeholders must monitor CSRD disclosure timelines and bio-based feedstock certification schemes to secure long-term OEM qualification status.
Market Dynamics
Automotive electrification mandates across Germany and France are compressing silicone specification cycles from five years to eighteen months, forcing compounders to validate thermal management grades faster than legacy testing protocols permit.
Growth Catalysts
- EU Green Deal chemical sustainability mandates:REACH registration deadlines for cyclic siloxanes are accelerating reformulation investments toward bio-based feedstocks. Medical device OEMs in Germany's industrial corridor now specify high-purity grades for implantable components.
- France's automotive electrification program:Battery pack sealing requirements are displacing fluoropolymer gaskets with silicone alternatives that withstand wider thermal cycling ranges.
- Liquid silicone rubber injection molding:Medical device manufacturers across Switzerland and the Netherlands are adopting two-shot molding processes that reduce assembly steps for respiratory masks and surgical instruments.
Market Restraints
- Methyl chloride and silicon metal cost volatility:Ferrosilicon spot pricing fluctuations in Norway and Iceland concentrate margin pressure on non-integrated compounders lacking captive metallurgical-grade silicon supply.
- Siloxane monomer supply concentration:Western European siloxane capacity clusters along the German-Austrian border, creating single-source risk for specialty elastomer producers in Southern Europe.
- Fluoropolymer substitution in aerospace:Perfluoroelastomer seals retain performance advantages in jet engine applications above 250 degrees Celsius, limiting silicone penetration in French and UK aerospace supply chains.
Strategic Opportunities
- Poland and Czech Republic automotive component manufacturing:Tier-2 suppliers in these markets lack qualified local silicone compounders, creating white space for medical-grade certification holders to establish toll-manufacturing partnerships.
- CSRD disclosure timelines:Large EU corporates must report Scope 3 chemical emissions from 2025, generating procurement preference for silicone suppliers with certified bio-carbon content.
- Silicone-thermoplastic hybrid overmolding:Automotive connector manufacturers are converging liquid silicone rubber with polyamide substrates to eliminate secondary sealing operations.
Industry Challenges
- EU Medical Device Regulation biological evaluation timelines:ISO 10993-5 cytotoxicity testing for new silicone formulations now requires twelve to eighteen months, delaying product launches for cardiovascular device startups.
- Specialized compounding technician scarcity:Platinum-catalyzed liquid silicone rubber processing expertise concentrates among aging workforces in Germany's Bavarian chemical cluster, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Silicone Market |
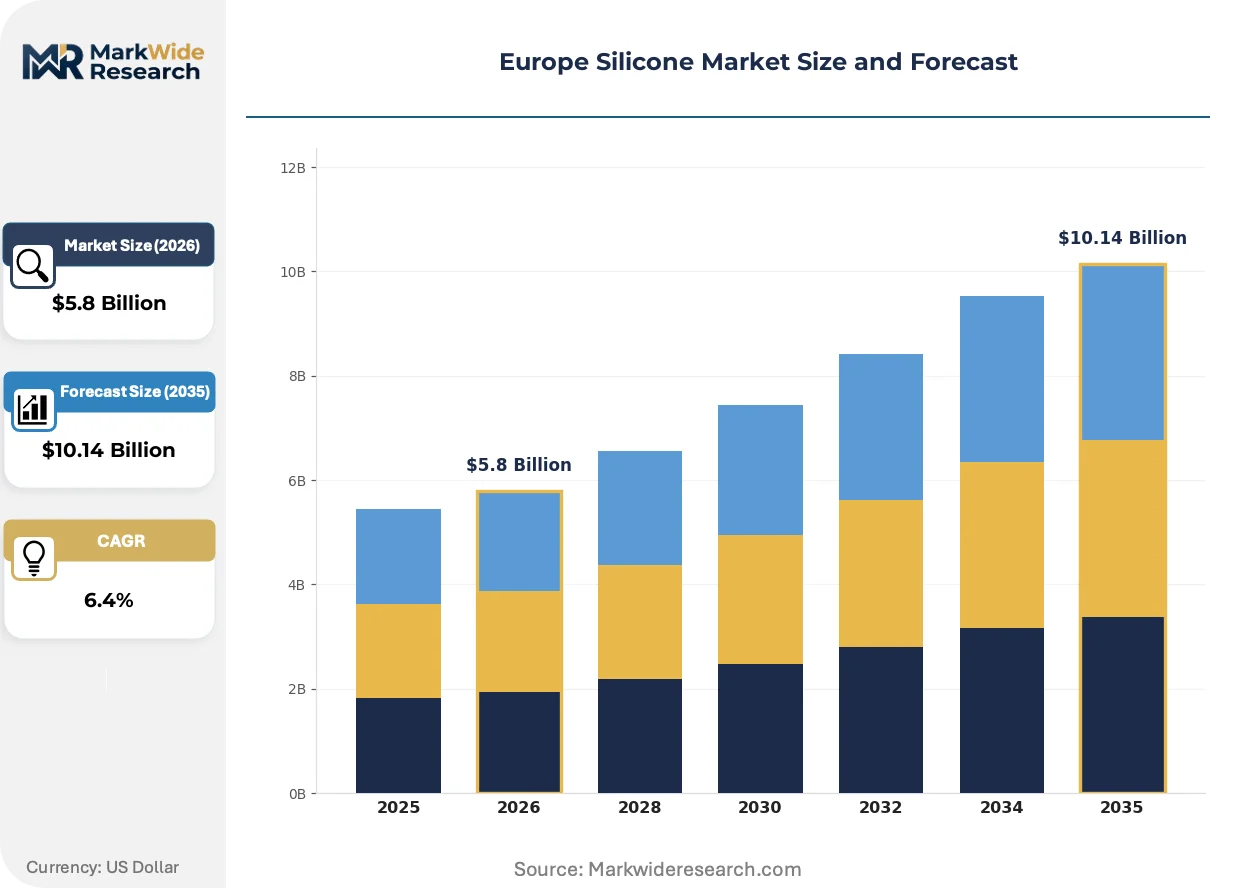
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Silicone Rubber, Solid Silicone Rubber, Silicone Gels, Silicone Resins Application: Automotive Parts, Medical Devices, Electronics, Construction Sealants End Use Industry: Healthcare, Automotive, Construction, Consumer Goods Form: Blocks, Sheets, Tubes, Coatings |
| Companies Covered | Wacker Chemie AG, Shin-Etsu Chemical Co Ltd, Elkem ASA, Dow Inc, Momentive Performance Materials Inc, Evonik Industries AG, AB Specialty Silicones, ACSIC Ingredients, Simtec Silicone Parts, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Silicone Market Shifts & Advancements
Digital formulation platforms and closed-loop recycling systems are compressing development cycles and raw material intensity simultaneously, reshaping how European silicone compounders compete on speed and sustainability credentials.
Additive manufacturing-grade silicone pastes are rewriting prototyping economics for medical device developers. Dutch and Belgian orthopedic implant startups now print patient-specific surgical guides in biocompatible silicone within forty-eight hours, collapsing traditional metal-tooling lead times from six weeks. This speed compression is forcing established molders to maintain digital fabrication capabilities alongside conventional injection presses.
REACH authorization requirements for octamethylcyclotetrasiloxane are tightening monomer import controls into the EU. Compounders without registered downstream user status face supply interruptions, driving consolidation toward ECHA-registered integrated producers. Medical-grade specialists in Switzerland and Germany are absorbing this regulatory friction by qualifying alternative cyclic siloxane feedstocks ahead of sunset date enforcement.
Automotive OEMs are unbundling material certification from component supply contracts. Tier-1 seal manufacturers in France and Germany now procure silicone compounds through qualified material lists rather than single-source agreements, compressing compounder margins while expanding qualified supplier rosters. This procurement fragmentation is most visible in battery thermal interface material categories, where three to five compounders now serve programs previously dominated by one.
Europe Silicone Market Segmentation
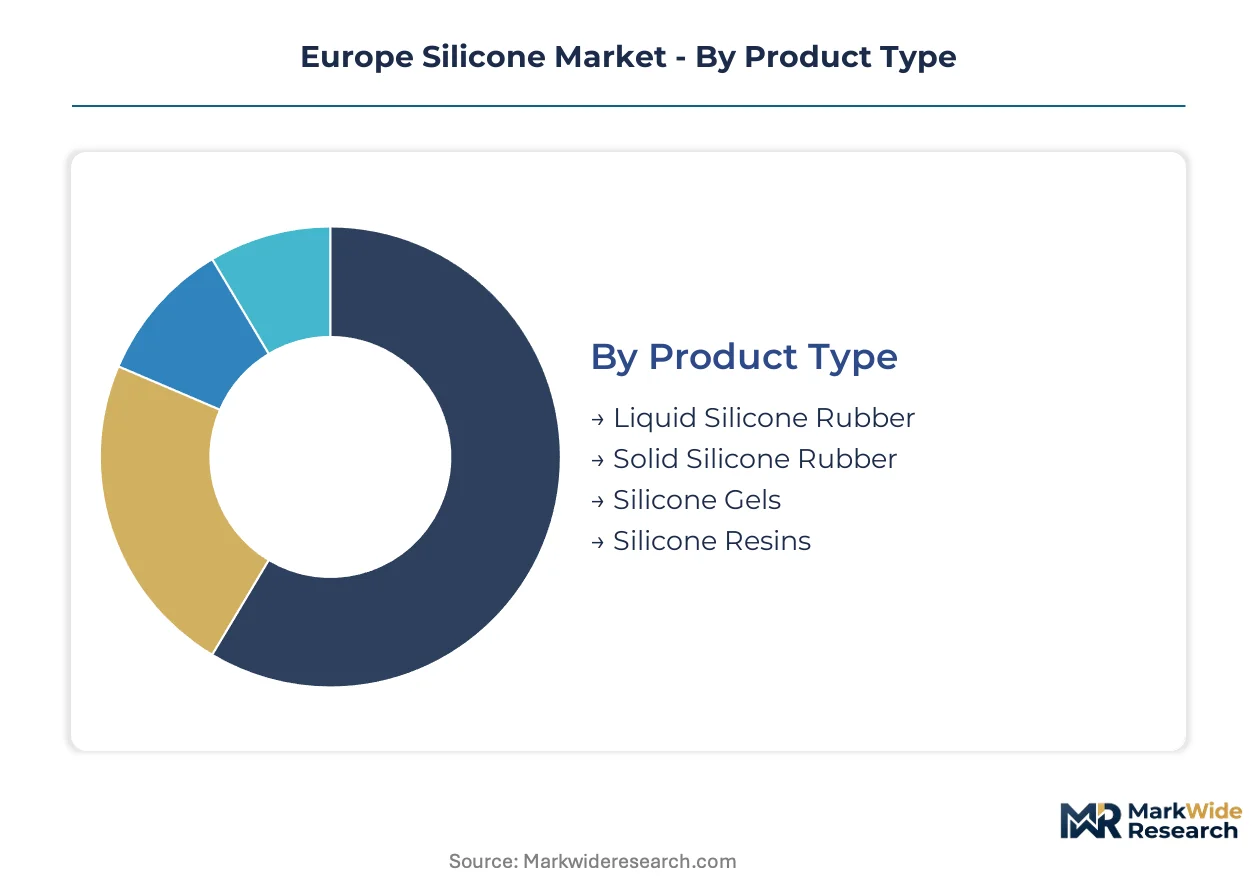
European silicone procurement patterns diverge sharply across formulation chemistry, end-use performance requirements, and regulatory compliance tiers. Buyers in Germany's automotive corridor prioritize thermal cycling resistance and REACH-registered supply chains, while Swiss medical device manufacturers filter on ISO 10993 biocompatibility certification. Understanding these segment-specific qualification thresholds determines supplier positioning and margin capture potential.
Product Type:
Cost tier differentiation separates commodity elastomer buyers from premium-grade specifiers in this category.
- Liquid Silicone Rubber:Two-part platinum-catalyzed systems enable high-cavitation injection molding with cycle times under thirty seconds. German automotive OEMs and Dutch medical device manufacturers concentrate procurement here for respiratory masks, surgical instruments, and battery thermal interface materials where precision and biocompatibility converge.
- Solid Silicone Rubber:High-consistency rubber compounds rely on peroxide or platinum curing for extrusion and compression molding applications. Southern European construction renovation programs in Italy and Spain anchor volume demand for facade sealants and glazing gaskets where weathering resistance spans decades.
- Silicone Gels:Soft, conformable materials cushion electronics and medical implants; French pacemaker manufacturers specify ultra-soft grades for device encapsulation.
- Silicone Resins:Crosslinked polysiloxane networks deliver thermal stability above 200 degrees Celsius; conformal coatings for German automotive electronics command premium positioning.
Solid silicone rubber leads volumes today; liquid silicone rubber is gaining share fastest.
Application:
Application selection tracks directly to the severity of thermal, chemical, or biological stress environments.
- Automotive Parts:Battery pack sealing, thermal interface pads, and connector gaskets dominate electrification-driven demand. French and German OEMs validate silicone grades for 1,500-hour thermal aging protocols, compressing supplier qualification cycles to eighteen months.
- Medical Devices:Implantable cardiovascular components, respiratory masks, and surgical instruments require ISO 10993-5 cytotoxicity clearance. Swiss and German compounders with ECHA-registered downstream user status capture disproportionate share in this high-margin category.
- Electronics:Potting compounds and conformal coatings protect PCBs from moisture and thermal shock; Dutch semiconductor packaging operations drive precision-grade demand.
- Construction Sealants:Movement joints and facade glazing in Mediterranean climate zones specify UV-stable formulations with 25-year durability warranties.
Construction sealants anchor volume consumption; medical devices expand most quickly.
End Use Industry:
Customer type determines whether procurement prioritizes total cost of ownership or performance-critical specifications.
- Healthcare:Implantable and long-term contact applications filter supply chains to ECHA-registered compounders with dedicated cleanroom compounding. German medical device OEMs in the Bavarian corridor specify platinum-cured liquid silicone rubber for cardiovascular and orthopedic applications.
- Automotive:Electrification mandates across Germany and France are displacing fluoropolymer seals with silicone alternatives in battery thermal management. Tier-1 suppliers now procure through qualified material lists rather than single-source agreements.
- Construction:Southern European building energy renovation programs drive sealant volume; Italian and Spanish contractors prioritize weathering resistance and application productivity.
- Consumer Goods:Kitchenware, personal care, and infant products demand food-contact and skin-safe certifications; Nordic markets lead bio-based feedstock preference.
Automotive procurement leads absolute value; healthcare commands the steepest expansion trajectory.
Form:
Supply chain configuration and processing equipment compatibility shape buyer preferences in this category.
- Blocks:Uncured high-consistency rubber for mill mixing and calendering serves construction and industrial gasket manufacturers; German compounders distribute through regional toll processors.
- Sheets:Pre-cured and uncured rolls enable die-cutting and laminating operations; automotive and electronics converters in Poland and Czech Republic concentrate demand.
- Tubes:Extruded profiles for fluid transfer and sealing applications serve medical and food processing equipment; Swiss precision extruders dominate high-purity grades.
- Coatings:Solvent-based and solventless liquid systems for spray, dip, and brush application protect industrial substrates; French aerospace maintenance operations specify thermal-resistant formulations.
Sheets and blocks dominate tonnage; coatings climb the fastest on electronics and aerospace demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands greater silicone procurement volumes than France, yet French electrification mandates are compressing supplier qualification cycles more aggressively. National regulatory frameworks and industrial clustering patterns create distinct competitive terrains across the continent.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg drive thermal management grade demand for battery packs and power electronics. The KBA enforces stringent material approval protocols for electrified vehicle components. Wacker Chemie's Burghausen integrated complex anchors captive siloxane supply for specialty elastomer production serving medical device manufacturers in the Munich corridor.
France
Renault and Stellantis electrification programs displace fluoropolymer seals with silicone alternatives in battery thermal cycling applications. The EU Green Deal's chemical sustainability mandates accelerate bio-based feedstock qualification timelines. Lyon and Grenoble host precision compounders developing high-purity grades for implantable cardiovascular devices under ANSM oversight.
Switzerland
Medical device manufacturers in the Basel-Zurich corridor specify platinum-cured liquid silicone rubber for orthopedic and respiratory applications. Swissmedic enforces biological evaluation standards that filter subscale compounders from healthcare supply chains. Precision extruders in the Swiss Mittelland dominate high-purity tube production for fluid transfer systems.
Italy
Southern European building renovation programs anchor solid silicone rubber consumption for facade sealants and glazing gaskets. REACH registration deadlines for cyclic siloxanes concentrate procurement toward ECHA-registered integrated producers. Lombardy-based compounders distribute through regional toll processors serving construction contractors across the Po Valley.
Netherlands
Semiconductor packaging operations in Eindhoven drive precision-grade silicone demand for potting compounds and conformal coatings. CSRD disclosure timelines from 2025 generate procurement preference for suppliers with certified bio-carbon content. Dutch orthopedic implant startups leverage additive manufacturing-grade silicone pastes for patient-specific surgical guide production.
Europe Silicone Market Competitive Landscape
German-Austrian producers anchor the integrated tier; Swiss and Nordic specialists hold positions in medical-grade certification. The vendor base stratifies across three tiers: siloxane-integrated majors with captive metallurgical silicon supply, regional compounders with ECHA-registered downstream user status, and toll processors serving construction and industrial gasket markets. Strategic archetypes include backward-integrated material producers, biocompatibility-certified healthcare specialists, and automotive-qualified thermal management compounders. Capacity expansion and qualification-driven M&A represent the dominant competitive moves as electrification compresses specification cycles.
Among the integrated majors, Wacker Chemie AG and Dow Inc exemplify siloxane-integrated archetypes with Western European manufacturing footprints. Elkem ASA occupies a position representing ferrosilicon backward integration advantages extending into silicone intermediate production. These three anchors illustrate how supply-side concentration along the German-Austrian border shapes procurement options for specialty elastomer producers across Southern and Eastern Europe.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| Shin-Etsu Chemical Co Ltd |
| Elkem ASA |
| Dow Inc |
| Momentive Performance Materials Inc |
| Evonik Industries AG |
| AB Specialty Silicones |
| ACSIC Ingredients |
| Simtec Silicone Parts |
| Others |
Supply & Pricing Matrix
EU Green Deal chemical sustainability mandates gate both qualified supply and premium-tier pricing access, filtering compounders without bio-based feedstock certification from automotive OEM procurement lists while elevating margin capture for ECHA-registered integrated producers serving medical device manufacturers.
Pricing Analysis
Capacity additions in Germany and Austria are reshaping price floors for siloxane monomers, compressing margins for non-integrated compounders dependent on spot procurement. Three-tier pricing structure across medical-grade, automotive-qualified, and construction-standard levels separates ISO 10993-certified biocompatibility premiums from commodity elastomer benchmarks. Cost compression in construction-grade solid rubber intensifies because Southern European toll processors compete on volume scale without captive silicon metal supply. Medical device manufacturers in Switzerland exhibit lowest price sensitivity due to regulatory qualification switching costs, while Italian construction contractors drive hardest bargain negotiations.
Supply Chain Analysis
Single-source vulnerability sits with siloxane monomer production clustered along the German-Austrian border, exposing Southern European specialty elastomer producers to supply interruption risk. Germany, Austria, and Norway anchor metallurgical-grade silicon and ferrosilicon output feeding downstream polymerization. Raw material dependencies center on methyl chloride, platinum catalysts, and high-purity silicon metal subject to energy cost volatility. Tariff exposure on Chinese silicon metal imports presents structural risk for non-integrated compounders. Distribution runs through regional toll processors in Italy and Spain serving construction markets, while direct supply agreements dominate automotive and medical tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe silicone demand has shifted toward premium specifications as automotive electrification and medical device biocompatibility requirements compress qualification cycles and elevate performance thresholds.
For Market Incumbents: Deepen captive siloxane supply through backward integration into metallurgical-grade silicon or long-term offtake agreements with Norwegian ferrosilicon producers. Accelerate bio-based feedstock certification ahead of CSRD disclosure timelines to defend automotive OEM qualification status against emerging Polish compounders. Prioritize platinum-catalyzed liquid silicone rubber capacity expansion in Germany's Bavarian corridor where technician scarcity constrains rival expansion. For New Entrants and Emerging Players: Enter via toll-manufacturing partnerships with Tier-2 automotive suppliers in Poland and Czech Republic lacking qualified local silicone compounders. Target medical-grade certification white space in cardiovascular implant applications where ISO 10993-5 clearance timelines filter incumbent capacity. Pursue silicone-thermoplastic hybrid overmolding qualifications with automotive connector manufacturers eliminating secondary sealing operations. For Investors and Strategic Acquirers: Roll-up economics work for ECHA-registered regional compounders with downstream user status because REACH authorization requirements for cyclic siloxanes are driving consolidation toward compliant integrated producers. Five-to-ten year viability hinges on bio-based feedstock positioning and automotive thermal management grade portfolios. Monitor CSRD procurement preference shifts toward certified bio-carbon content as inflection indicator for premium-tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallurgical-Grade Silicon | Captive ferrosilicon supply from Norway anchors cost advantages against spot-price volatility. |
| Bio-Based Feedstock Certification | CSRD disclosure timelines from Brussels generate procurement preference for verified sustainable content. |
| Medical-Grade Cleanroom Compounding Capacity | ISO 10993-5 clearance capabilities filter subscale competitors from Swiss implantable device supply chains. |
| Automotive Thermal Management Grade Qualification | Eighteen-month KBA validation protocols compress supplier rosters for battery pack sealing applications. |
| Silicone-Thermoplastic Hybrid Overmolding Partnerships | Polyamide substrate convergence eliminates secondary operations for French automotive connector manufacturers. |
Research Methodology
Multiple input streams — primary interviews with silicone plant managers, automotive Tier-1 procurement leads, and medical device regulatory affairs directors; secondary validation through ECHA registration databases, Cefic chemical trade reports, and SEC filings from integrated producers; plus customs data on silicon metal and methyl chloride trade flows — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against expert panel assessments of electrification-driven specification cycle compression. Segmentation dimensions modeled include product type chemistry, end-use industry performance requirements, form factor processing compatibility, and regional regulatory compliance tiers. CAGRs were derived from elasticity-adjusted demand curves incorporating automotive battery thermal management content per vehicle and medical device implantable component growth vectors.
Inputs from ECHA registration filings and OEM qualification databases were available through the study window; gaps in proprietary formulation cost structures and toll-processing contract terms introduce uncertainty bands around margin estimates. Forecasts reflect assumptions regarding REACH authorization enforcement timelines and bio-based feedstock scale-up trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Global Electronic Materials Market
Semiconductor Material
Electronic Circuit Board Level Underfill Material Market
Semiconductor Material
Europe Semiconductor Materials Market
Semiconductor Material
Asia Pacific Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Global Magnesium Oxide Nanopowder Market
Semiconductor Material
North America Silicone Market
Semiconductor Material
Quartz Market
Semiconductor Material
Titanium Diboride Market
Semiconductor Material
Zinc Oxide Market
Semiconductor Material
Global Silicon Alloys Market
Semiconductor Material
Synthetic Sapphire Market
Semiconductor Material
Semiconductor Fabrication Material Market
Semiconductor Material
Rhenium Market
Semiconductor Material
Silicon Hydride Market
Semiconductor Material
5G Substrate Materials Market
Semiconductor Material
Global Polybutylene Terephthalate (PBT) Market