
 Global Gallium Oxide Market | 2026-2036
Global Gallium Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gallium Oxide Market Foresight
Substrate-grade crystal quality is redrawing competitive boundaries in gallium oxide supply. Novel Crystal Technology leverages proprietary melt-growth expertise to dominate beta-phase bulk crystal production. Furukawa Electric anchors Japan's substrate pipeline through integrated ingot-to-epiwafer operations. Infineon Technologies AG navigates European power module qualification by sourcing gallium oxide substrates for next-generation inverter designs.
Gallium oxide is a ultra-wide-bandgap semiconductor with a bandgap of approximately 4.8 eV and critical electric field strength exceeding silicon carbide, manufactured via melt-based methods for bulk crystals and vapor-phase epitaxy for thin films; its primary purpose is enabling high-efficiency power switching and ultraviolet detection beyond silicon and gallium nitride limits. Substrates command the dominant value share as device manufacturers prioritize low-defect native templates over foreign epitaxy. MOCVD and HVPE deposition technologies are splitting process leadership depending on whether device architectures demand thick drift layers or precise heterointerfaces. Power electronics applications absorb the majority of wafer volume as electric vehicle inverters and grid converters test gallium oxide against incumbent silicon carbide.
Japan's METI coordinates national substrate capacity expansion through its semiconductor revival framework, while the EU Green Deal's efficiency mandates accelerate wide-bandgap material qualification for renewable energy converters. REACH chemical registration requirements in Europe govern precursor sourcing for HVPE and MOCVD processes, shaping supplier entry barriers. Stakeholders must monitor substrate diameter scaling milestones and automotive AEC-Q101 qualification timelines to time capacity commitments against silicon carbide cost curves.
Market Dynamics
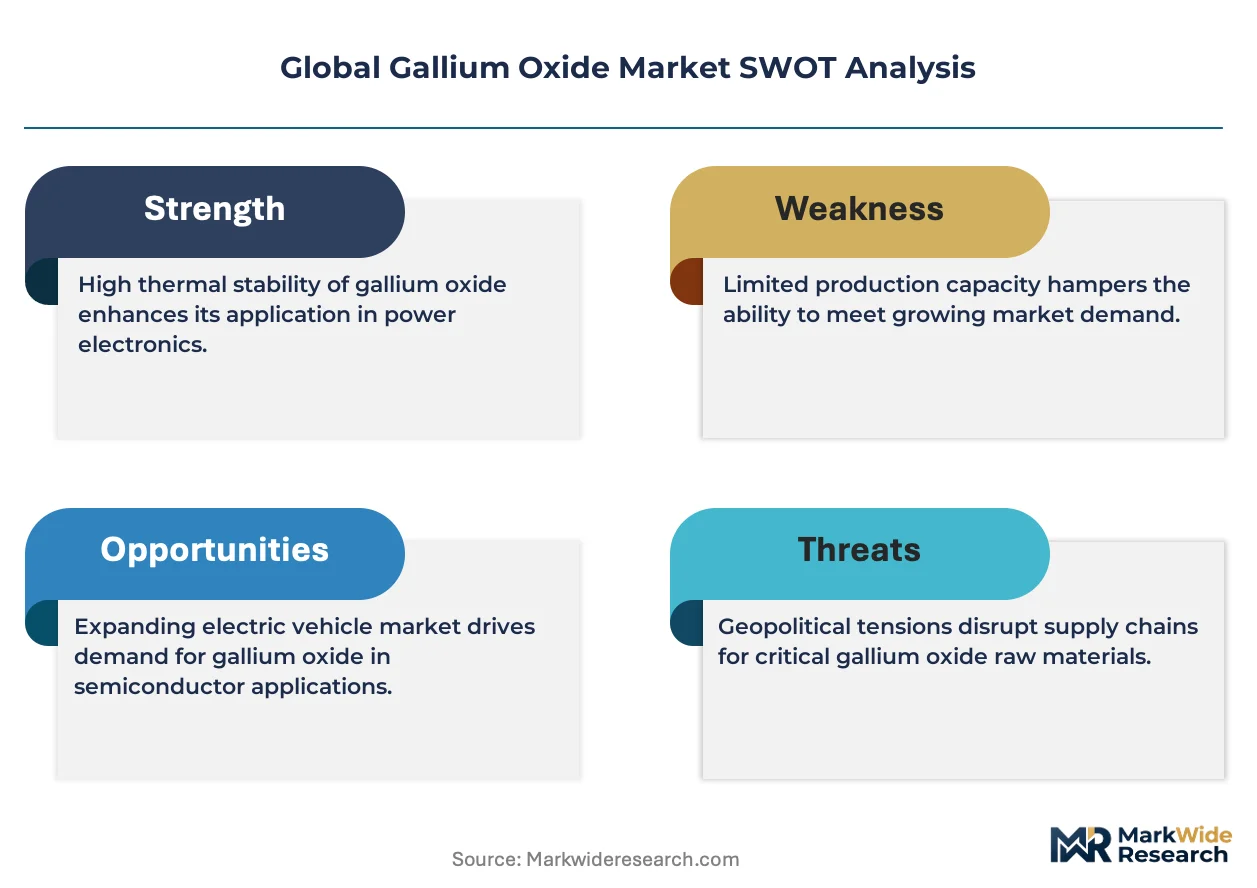
Substrate diameter scaling is compressing commercialization timelines as power electronics manufacturers demand 6-inch native templates for next-generation inverter architectures. Japan's METI subsidy framework and the EU Green Deal's efficiency mandates are accelerating foundry qualification cycles beyond historical silicon carbide adoption curves.
Growth Catalysts
- Automotive power module demand:Electric vehicle manufacturers in Germany are qualifying gallium oxide substrates for 800V inverter platforms, displacing silicon carbide in cost-sensitive volume segments.
- METI's semiconductor revival framework:Japan's coordinated national capacity expansion subsidizes beta-phase bulk crystal growth infrastructure, compressing substrate lead times for domestic foundry clusters.
- HVPE deposition advances:Thick drift layer capabilities above 10 micrometers are enabling vertical power device architectures previously unattainable with foreign epitaxy on sapphire templates.
Market Restraints
- Indium supply concentration:Precursor sourcing for melt-based bulk crystal growth depends on Chinese indium refining capacity, exposing substrate manufacturers to export control volatility.
- Silicon carbide incumbent lock-in:Wolfspeed and STMicroelectronics have secured decade-long automotive supply agreements, creating switching cost barriers for gallium oxide qualification.
- REACH chemical registration:ECHA requirements for trimethylgallium and other MOCVD precursors extend European supplier entry timelines by 18-24 months versus Asian competitors.
Strategic Opportunities
- Grid converter retrofit cycles:US utility-scale solar installations under FERC Order 2023 interconnection reforms are testing wide-bandgap materials for 1500V string inverter upgrades.
- UV-C detection modules:Water purification system manufacturers are sourcing gallium oxide photodiodes for mercury-free disinfection monitoring, opening non-power electronics revenue streams.
- India's PLI scheme for semiconductors:Central government production-linked incentives for compound semiconductor fabs are attracting substrate technology transfer partnerships.
Industry Challenges
- Crystal growth technician scarcity:Melt-based beta-phase bulk production requires expertise in high-temperature oxide melt dynamics that existing silicon carbide talent pools cannot directly transfer.
- AEC-Q101 qualification timelines:Automotive power module certification cycles for wide-bandgap materials extend 36-48 months, delaying revenue recognition against compressed subsidy windows.
- Epitaxial interface defect control:Threading dislocation densities above 10^8 per square centimeter in heteroepitaxial films limit device yield for high-voltage Schottky barrier diodes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gallium Oxide Market |
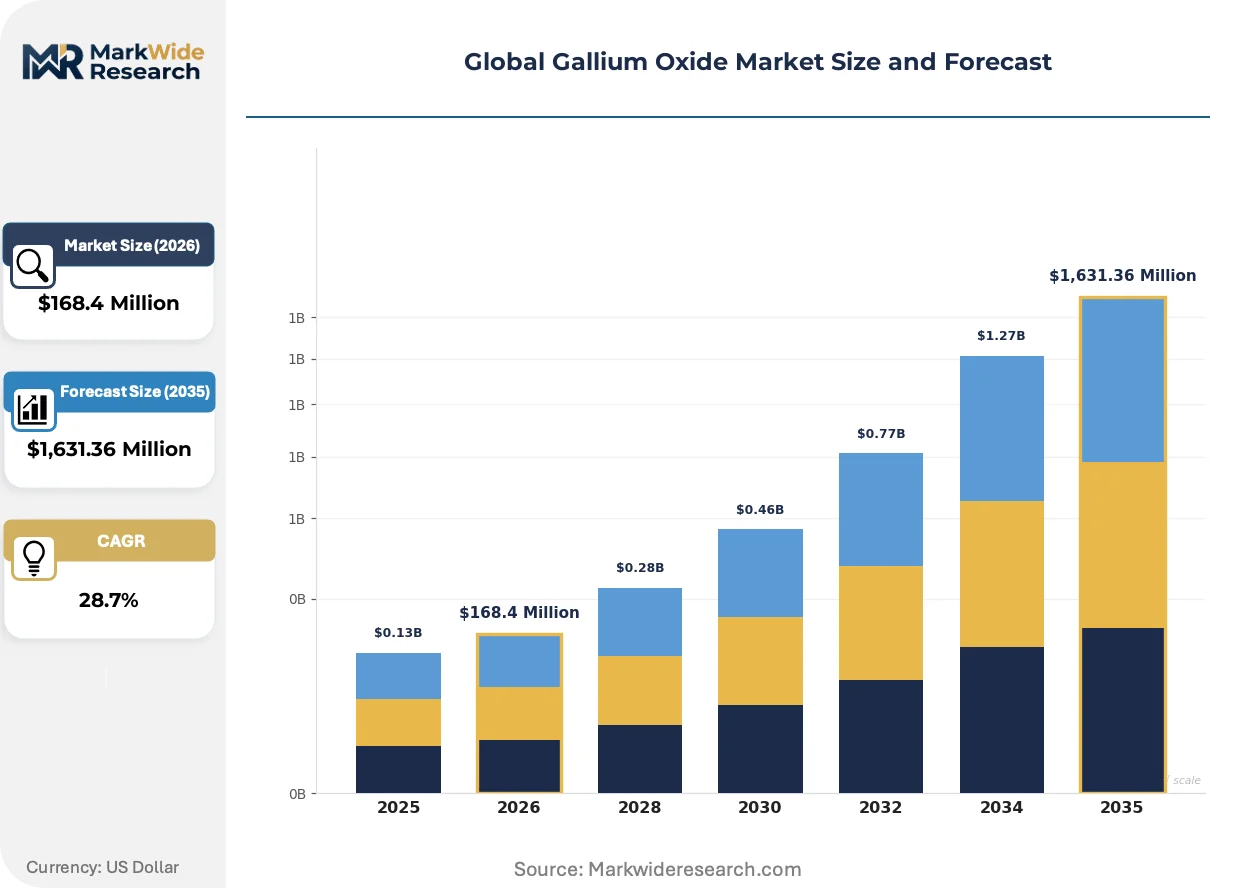
| Market Size in 2026 | $168.4 Million |
| Market Size in 2035 | $1,631.36 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk Crystals, Thin Films, Nanoparticles, Powders, Substrates Technology: MOCVD, HVPE, PLD, Sputtering, CVD Application: Power Electronics, UV Photodetectors, Gas Sensors, High-frequency Devices, Transparent Electronics End User Industry: Semiconductor Fabricators, Electronics Manufacturers, Sensor Developers, Research Institutions |
| Companies Covered | Furukawa Electric, Novel Crystal Technology, Inc., Infineon Technologies AG, PowerCubeSemi, Mitsubishi Chemical Corporation, Texas Instruments Incorporated, ROHM Semiconductor, Sumitomo Electric Industries, Ltd., STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gallium Oxide Market Shifts & Advancements
Wafer processing technology is fragmenting along application-specific performance requirements rather than converging on universal substrate standards. Equipment suppliers and device manufacturers are placing divergent bets on crystal growth methods and epitaxial deposition platforms.
Substrate manufacturing is bifurcating between melt-grown beta-phase bulk crystals for vertical power devices and heteroepitaxial thin films on sapphire for lateral RF applications. Japanese foundry clusters prioritize Novel Crystal Technology's Czochralski-derived templates for 650V automotive inverters. German power module suppliers are demanding 6-inch diameters that only melt-growth methods can currently yield, compressing timelines for vapor-phase alternatives.
EU REACH chemical registration requirements are reshaping precursor supply chains for European MOCVD and HVPE equipment operators. ECHA's extended substance evaluation timelines for organometallic gallium compounds favor incumbent Asian chemical suppliers with grandfathered registrations. German automotive power module manufacturers are qualifying Japanese substrate sources to bypass European chemical import bottlenecks.
Automotive tier-one procurement is consolidating supplier panels around vertically integrated substrate-to-device providers. Bosch and Continental are negotiating multi-year supply agreements that bundle native template sourcing with foundry processing, displacing merchant substrate vendors. Japan's integrated ingot-to-epiwafer operations capture disproportionate qualification slots against specialized crystal growers lacking in-house epitaxy capability.
Global Gallium Oxide Market Segmentation
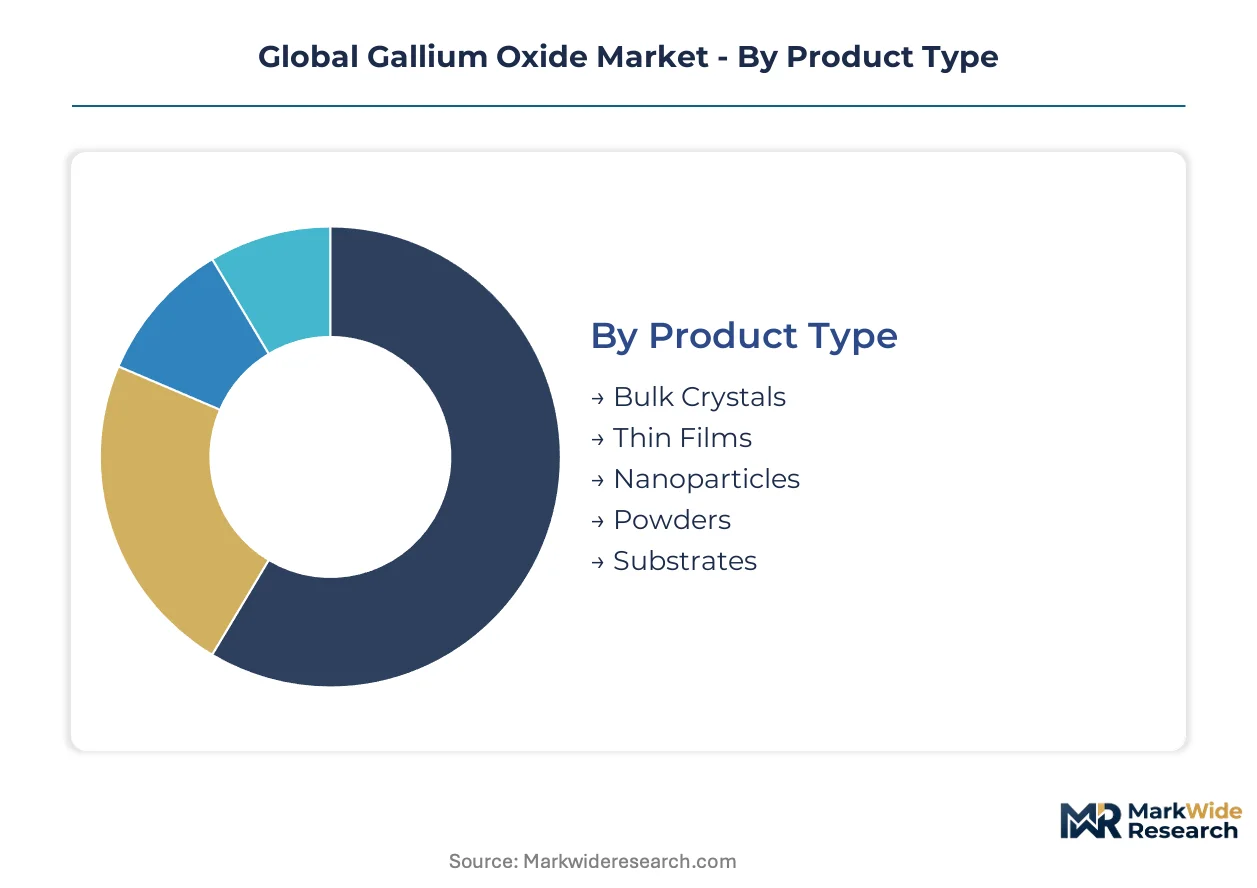
Segmentation in gallium oxide markets tracks the divergence between substrate-grade bulk crystal production and thin-film deposition routes. Each technology pathway locks manufacturers into distinct equipment ecosystems and qualification timelines that resist switching.
Product Type:
Substitution pressure from silicon carbide substrates is most acute in bulk crystal segments where diameter scaling determines foundry compatibility.
- Substrates:Native beta-phase templates grown via melt-based methods deliver the low threading dislocation densities required for vertical power devices. German automotive power module manufacturers are prioritizing 6-inch diameter qualification to match silicon carbide form factors.
- Bulk Crystals:Czochralski-derived ingots constitute the feedstock for all subsequent wafer processing, with Japanese foundry clusters absorbing the majority of high-purity output under METI-coordinated supply agreements.
- Thin Films:Heteroepitaxial layers on sapphire or silicon templates serve cost-sensitive UV detection applications where native substrates are economically prohibitive.
- Nanoparticles:Colloidal synthesis routes target specialized gas sensor formulations requiring high surface-area reactivity.
- Powders:Sinter-grade material feeds ceramic target manufacturing for physical vapor deposition equipment.
Substrates anchors the volume base while thin films gains share at the steepest rate.
Technology:
Cost tier stratification separates capital-intensive melt-growth infrastructure from deposition equipment accessible to mid-scale entrants.
- HVPE:Halide vapor phase epitaxy achieves drift layer thicknesses exceeding 10 micrometers for 1200V-class Schottky diodes. Japanese equipment suppliers dominate installed base expansion as domestic foundries scale 6-inch production.
- MOCVD:Metal-organic chemical vapor deposition offers precise heterointerface control for lateral RF transistors requiring abrupt doping transitions. REACH registration requirements for trimethylgallium precursors disadvantage European equipment operators against Asian competitors.
- PLD:Pulsed laser deposition serves research-scale production of complex oxide heterostructures with limited commercial throughput.
- Sputtering:Magnetron sputtering targets transparent conductive oxide integration in display backplane applications.
- CVD:Conventional chemical vapor deposition remains confined to silicon-compatible thermal budgets incompatible with gallium oxide's growth kinetics.
HVPE commands the capital commitment intensity while MOCVD attracts the broadest equipment supplier base.
Application:
Application maturity spreads from power electronics qualification cycles toward emerging UV detection deployments with shorter certification pathways.
- Power Electronics:Electric vehicle inverters and grid converters absorb the majority of substrate volume as 800V architectures test gallium oxide against entrenched silicon carbide supply chains.
- UV Photodetectors:Mercury-free water purification monitoring systems are sourcing gallium oxide photodiodes for 265nm detection, opening non-power revenue streams with faster commercialization timelines.
- Gas Sensors:Ozone and nitrogen dioxide detection modules leverage the material's surface reactivity for environmental monitoring networks.
- High-frequency Devices:Lateral transistor architectures on sapphire templates target 5G base station power amplifiers with lower thermal budgets than gallium nitride alternatives.
- Transparent Electronics:Deep-ultraviolet transparent conductors remain confined to laboratory demonstrations pending p-type doping breakthroughs.
Power electronics anchors the volume base while UV photodetectors climbs the fastest.
End User Industry:
Customer type concentration favors vertically integrated semiconductor fabricators over merchant substrate vendors.
- Semiconductor Fabricators:Foundry operators in Japan and Germany are consolidating substrate procurement through multi-year supply agreements that bundle native template sourcing with device processing.
- Electronics Manufacturers:Tier-one automotive suppliers are qualifying gallium oxide power modules for inverter platforms, displacing merchant silicon carbide sourcing where cost structures permit.
- Sensor Developers:Water treatment equipment OEMs are integrating UV photodiodes into disinfection monitoring systems with shorter qualification cycles than automotive power electronics.
- Research Institutions:University and national laboratory programs drive early-stage heterostructure development with limited production scale impact.
Semiconductor fabricators anchors the volume base while electronics manufacturers gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports refined indium precursors and beta-phase substrates while importing MOCVD equipment from European suppliers, creating a trade deficit in deposition technology. Germany and the United States run substrate deficits against Japanese wafer foundries. China controls upstream indium refining, exposing downstream fabricators to export control volatility.
Japan
Domestic foundry clusters in Tokyo and Osaka absorb the majority of native template production for 650V automotive inverter qualification. METI's semiconductor revival framework subsidizes beta-phase bulk crystal growth infrastructure through coordinated national capacity expansion. Novel Crystal Technology anchors the Kanto region's substrate pipeline with proprietary melt-growth expertise.
Germany
Bosch and Continental are bundling native template procurement with foundry processing for 800V electric vehicle platforms. The EU Green Deal's efficiency mandates accelerate wide-bandgap material qualification timelines for renewable energy converters. Bavaria's automotive power module supply chains source Japanese substrates to bypass ECHA chemical import bottlenecks.
United States
Utility-scale solar installations under FERC Order 2023 interconnection reforms test gallium oxide for 1500V string inverter upgrades. The Inflation Reduction Act's domestic content bonuses incentivize compound semiconductor fab construction. Texas and Arizona emerge as substrate qualification hubs for grid converter retrofit cycles.
China
Indium refining concentration in Yunnan and Guangxi provinces supplies precursor feedstock for global melt-based bulk crystal growth. The Ministry of Industry and Information Technology's dual carbon goals accelerate wide-bandgap semiconductor R&D funding. Yangtze River Delta fabrication clusters import Japanese templates while developing indigenous HVPE capabilities.
India
Central government production-linked incentives for compound semiconductor fabs attract substrate technology transfer partnerships from Japanese equipment suppliers. The Bureau of Indian Standards develops domestic certification pathways for wide-bandgap power devices. Karnataka and Telangana foundry clusters target automotive power module qualification for export markets.
Global Gallium Oxide Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and technology licensing dimensions. The vendor base stratifies between vertically integrated ingot-to-epiwafer operators and specialized crystal growers lacking in-house epitaxy capability. Three archetypes dominate: Japanese integrated fabricators with METI-backed capacity, European power module designers sourcing foreign substrates, and equipment suppliers licensing deposition technology. Competitive moves center on multi-year supply agreement bundling and substrate diameter scaling commitments against silicon carbide cost curves.
Within the integrated-fabricator tier, Furukawa Electric and Novel Crystal Technology, Inc. exemplify the Japanese model of coordinated national capacity expansion. Infineon Technologies AG represents the European design-house archetype navigating substrate procurement through qualified Japanese sources. These three companies anchor the competitive structure without exhaustive market coverage.
| Leading Market Players |
|---|
| Furukawa Electric |
| Novel Crystal Technology, Inc. |
| Infineon Technologies AG |
| PowerCubeSemi |
| Mitsubishi Chemical Corporation |
| Texas Instruments Incorporated |
| ROHM Semiconductor |
| Sumitomo Electric Industries, Ltd. |
| STMicroelectronics |
| Others |
Supply & Pricing Matrix
Fourteen-month substrate qualification timelines concentrate pricing power among Japanese ingot-to-epiwafer operators with METI-backed capacity expansion, while German automotive power module manufacturers absorb premium native templates to bypass ECHA chemical import bottlenecks.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that bundle native template procurement with foundry processing. Price differentiation rests on AEC-Q101 certification tier and volume scale commitments exceeding 10,000 wafer starts annually. Cost compression in standard-grade heteroepitaxial films is intensifying because sapphire template suppliers are expanding HVPE capacity. Tier-one automotive suppliers exhibit the lowest price sensitivity due to decade-long silicon carbide incumbent lock-in, while sensor developers prioritize economy-tier heteroepitaxial sourcing for UV detection modules.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes extend trimethylgallium precursor lead times by 18-24 months versus Asian competitors. Geographic supply concentrates in Japan, China, and Germany, with indium refining anchored in Yunnan and Guangxi provinces feeding melt-based bulk crystal growth. Raw material dependencies encompass high-purity indium ingots, gallium metal feedstock, and organometallic precursors for MOCVD deposition. Single-source vulnerability in Chinese indium refining exposes substrate manufacturers to export control volatility. Distribution runs through vertically integrated foundry clusters rather than merchant substrate vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gallium oxide's emergence as a silicon carbide alternative creates platform-economics inflection where substrate-to-device interoperability standards will determine ecosystem lock-in, similar to how SiC MOSFET gate-drive compatibility shaped automotive power module procurement.
For Market Incumbents: Fortify substrate diameter scaling commitments ahead of silicon carbide cost curve convergence, prioritizing 6-inch beta-phase bulk crystal capacity in Kanto and Osaka foundry clusters. Deepen backward integration into indium precursor refining to mitigate Chinese export control exposure. Accelerate AEC-Q101 qualification timelines through METI-coordinated automotive consortium testing.
For New Entrants and Emerging Players: Lead with UV photodetector applications for water purification OEMs, where mercury-free disinfection monitoring demands shorter certification cycles than automotive power electronics. Target India's PLI scheme for compound semiconductor fabs as the most penetrable geography for substrate technology transfer partnerships. Position through equipment licensing rather than capital-intensive crystal growth infrastructure.
For Investors and Strategic Acquirers: Long-term, this sits as a materials-scarcity play because melt-based beta-phase bulk production requires expertise in high-temperature oxide melt dynamics that existing silicon carbide talent pools cannot directly transfer. Acquisition target archetype: Japanese integrated ingot-to-epiwafer operators with METI-subsidized capacity expansion. Watch substrate diameter scaling milestones against silicon carbide 8-inch transition timelines as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Substrate Diameter Scaling | 6-inch beta-phase qualification compresses commercialization timelines for German automotive inverter platforms. |
| Backward Integration into Precursor Refining | Indium supply security mitigates Chinese export control volatility for Japanese bulk crystal growers. |
| AEC-Q101 Certification Acceleration | METI-coordinated consortium testing reduces automotive power module qualification cycles. |
| HVPE Equipment Licensing | Technology transfer partnerships enable India's PLI scheme participation without capital-intensive infrastructure. |
| UV Photodetector Commercialization | Mercury-free water purification monitoring opens non-power revenue streams with faster deployment. |
Research Methodology
Operator-level perspectives from substrate manufacturing engineers, automotive power module procurement leads, HVPE equipment specialists, and water treatment OEM technical directors anchored the qualitative base. Primary interviews combined with secondary validation from METI semiconductor framework disclosures, ECHA REACH registration databases, FERC Order 2023 interconnection filings, and SEC 10-K equipment supplier reports. Bottom-up wafer demand modeling and top-down compound semiconductor market sizing provided triangulation across the analysis window.
Sensitivity analysis tested penetration scenarios across product type, technology platform, application maturity, and end-user industry concentration dimensions. The analytical framework modeled volume and value outputs over the projection horizon, with CAGRs derived from substrate diameter scaling milestones and automotive qualification timeline compression. Forecast inputs incorporated silicon carbide incumbent supply agreement expirations and EU Green Deal efficiency mandate implementation pacing.
Forecasts assume regulatory continuity in Japan's METI subsidy framework and EU REACH chemical registration requirements; material policy shifts would require re-modeling. Substrate supply disruptions from indium export controls or AEC-Q101 timeline extensions represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Semiconductor Film Market
Semiconductor Material
United States Sapphire Glass Market
Semiconductor Material
Silicon Metal Market
Semiconductor Material
Glass Substrate in Semiconductor Market
Semiconductor Material
Niobium Hydride Market
Semiconductor Material
Semiconductor PI Film Market
Semiconductor Material
Cadmium Market
Semiconductor Material
Polycrystalline Silicon Market
Semiconductor Material
Monocrystalline Silicone Market
Semiconductor Material
Electronic-Grade Polysilicon Market
Semiconductor Material
Solar-Grade Polysilicon Market
Semiconductor Material
Quartz Market
Semiconductor Material
High Purity Germanium (Ge) Market
Semiconductor Material
Encapsulant Market
Semiconductor Material
Global Strontium Market
Semiconductor Material
Silicon Carbide Ceramics Market