
 Specialty Control Plasma Market | 2026-2036
Specialty Control Plasma Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Control Plasma Market Analytics
Pharmaceutical-grade specification tiers is collapsing the gap between research-use and clinical-diagnostic control plasma, forcing manufacturers to recertify legacy product lines. CSL Behring leverages captive plasma collection networks across multiple continents to sustain supply continuity for high-purity coagulation factors. Grifols anchors its position through vertical integration into plasma fractionation, while Takeda competes on recombinant-alternative portfolios that pressure traditional plasma-derived pricing.
Specialty control plasma comprises calibrated human or animal plasma matrices with defined analyte concentrations, manufactured through controlled fractionation and viral inactivation protocols to serve as reference materials for in-vitro diagnostic assays. These products validate coagulation analyzer accuracy, immunoglobulin quantification methods, and albumin measurement systems across hospital laboratories and blood banking operations. Coagulation factor controls dominate current revenue as hemophilia monitoring protocols expand, while immunoglobulin segments gain traction from rising primary immunodeficiency diagnoses. Albumin controls remain mature with stable hospital demand, though clotting factor concentrates attract margin focus from specialized pharmacy channels managing rare bleeding disorders.
FDA blood product regulations and EMA plasma master file requirements shape manufacturing standards, with ISO 15189 accreditation becoming mandatory for diagnostic laboratories sourcing control materials in major markets. The EU Medical Device Regulation reclassifies certain control plasma products, tightening conformity assessment pathways for European distributors. Stakeholders must monitor evolving pharmacovigilance obligations and plasma traceability mandates as regulators link donor screening intensity to finished product release criteria.

Market Dynamics
Pharmaceutical-grade recertification requirements are compressing product lifecycles as manufacturers must bridge research-use and clinical-diagnostic specifications under tightening FDA and EMA plasma master file protocols.
Growth Catalysts
- Hemophilia treatment center expansion:United States clinical networks are standardizing higher-precision coagulation monitoring protocols that require calibrated control plasma matrices for analyzer validation.
- EU Medical Device Regulation reclassification:The MDR's tightened conformity assessment pathways for European distributors is accelerating demand for ISO 15189-accredited diagnostic reference materials.
- Viral inactivation protocol advances:Improved fractionation technologies are expanding the addressable pool of donor plasma suitable for high-purity coagulation factor production.
Market Restraints
- Captive plasma collection concentration:Supply continuity depends on geographically concentrated donor networks across multiple continents, exposing manufacturers to regional collection disruptions.
- Recombinant alternative substitution:Takeda and other developers of recombinant coagulation factors are pressuring traditional plasma-derived pricing structures in hemophilia segments.
- EMA plasma master file compliance costs:The regulatory burden of documenting viral safety and traceability across fractionation batches is elevating fixed costs for mid-tier manufacturers.
Strategic Opportunities
- Primary immunodeficiency diagnostics growth:Rising diagnoses in Germany and other European markets with specialized blood product laboratories are expanding immunoglobulin control plasma demand.
- Specialized pharmacy channel penetration:Rare bleeding disorder management through clotting factor concentrate distribution is creating margin-focused procurement relationships outside hospital laboratories.
- ISO 15189 accreditation mandates:Diagnostic laboratory certification requirements across major markets are locking in recurring demand for certified reference materials with documented traceability.
Industry Challenges
- Fractionation specialist talent scarcity:The technical workforce capable of managing controlled plasma fractionation and viral inactivation protocols is concentrated among legacy blood product manufacturers.
- Legacy product line recertification timelines:Manufacturers face compressed windows to revalidate research-use plasma products under clinical-diagnostic pharmaceutical-grade specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Control Plasma Market |
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulation Factor, Immunoglobulin, Albumin, Clotting Factor Concentrates Application: Hemophilia Treatment, Immune Deficiencies, Trauma Care, Burn Treatment End User: Hospitals, Blood Banks, Rehabilitation Centers, Research Institutions Distribution Channel: Direct Sales, Online Retail, Wholesalers, Specialty Pharmacies |
| Companies Covered | CSL Behring, Grifols, Takeda, Octapharma, Biotest, LFB, Kedrion Biopharma, ADMA Biologics, BPL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Control Plasma Market Evolving Landscape
Next-generation viral inactivation chemistries and automated fractionation systems are reshaping manufacturing economics while regulatory harmonization efforts across FDA and EMA frameworks are redefining compliance architectures.
Photochemical pathogen reduction technologies employing amotosalen and UVA light treatment are displacing solvent-detergent viral inactivation as the dominant safety protocol for high-purity coagulation factor controls. CSL Behring and Grifols are retrofitting European and Australian fractionation facilities with these systems to reduce processing time and improve batch-to-batch consistency. The shift is compressing capital recovery timelines for legacy solvent-detergent infrastructure while enabling broader donor pool eligibility.
EMA's evolving plasma master file requirements are forcing manufacturers to document donor screening intensity linked directly to finished product release criteria. The regulation is elevating documentation burdens for fractionators sourcing plasma across multiple collection networks. German and Austrian blood product laboratories are prioritizing suppliers with integrated donor management systems that satisfy these traceability mandates.
Consolidated procurement through hemophilia treatment center networks is displacing fragmented hospital laboratory purchasing for coagulation factor controls. United States treatment centers are negotiating multi-year supply agreements that bundle control plasma with therapeutic concentrates, compressing spot-market volumes. This concentration is most visible in the Northeast and Midwest clinical networks where integrated delivery systems manage both diagnostic and therapeutic blood product budgets.
Specialty Control Plasma Market Segmentation
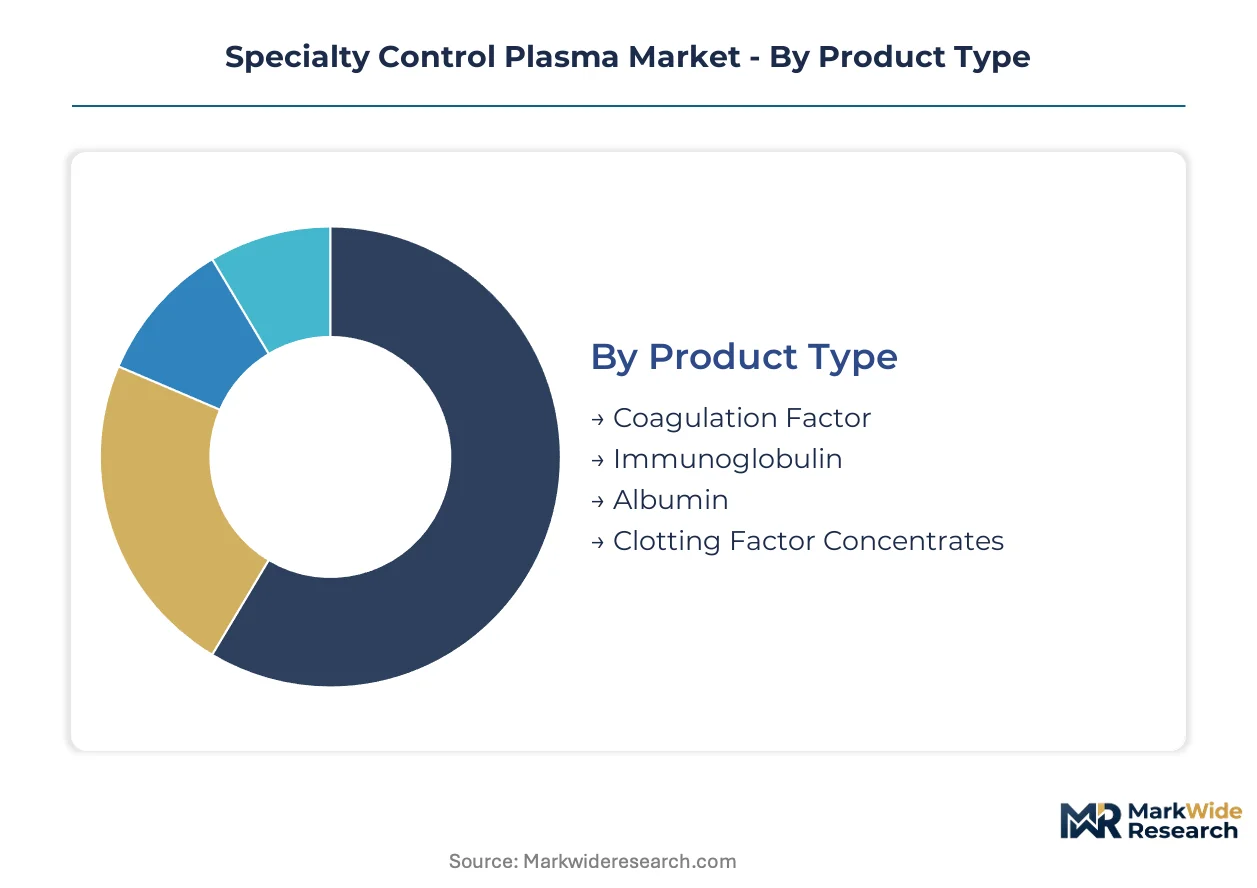
Specialty control plasma manufacturers configure product portfolios around distinct margin architectures. Segment boundaries determine pricing power, regulatory burden, and customer lock-in durability across diagnostic and therapeutic applications.
Product Type:
Coagulation factor controls command premium pricing through FDA lot-release requirements and hemophilia treatment center procurement consolidation.
- Coagulation Factor:Calibrated human plasma matrices with defined factor VIII, IX, and von Willebrand factor concentrations validate analyzer accuracy in clinical laboratories. United States hemophilia treatment centers bundle these controls with therapeutic concentrates, locking in multi-year supply agreements that compress spot-market availability.
- Immunoglobulin:Reference materials for IgG, IgA, and IgM quantification support primary immunodeficiency diagnostics in German and Austrian blood product laboratories. Rising diagnosis rates in specialized European facilities are expanding procurement volumes beyond traditional hospital channels.
- Albumin:Mature segment with stable hospital demand for nutritional monitoring and liver function assessment.
- Clotting Factor Concentrates:High-purity controls for rare bleeding disorder management through specialized pharmacy distribution.
Coagulation factor controls hold installed capacity. Immunoglobulin controls are rotating up the share rankings.
Application:
Diagnostic protocol standardization varies sharply across clinical settings, with hemophilia monitoring driving the most stringent control plasma specifications.
- Hemophilia Treatment:Precision coagulation monitoring protocols require pharmaceutical-grade certified reference materials with documented viral inactivation and traceability. United States clinical networks are standardizing analyzer validation procedures that exclude research-use plasma from procurement eligibility.
- Immune Deficiencies:Primary immunodeficiency diagnosis demands immunoglobulin quantification controls with extended analyte panels. German laboratories anchor European demand through specialized blood product testing facilities with ISO 15189 accreditation mandates.
- Trauma Care:Massive transfusion protocols utilize coagulation controls for rapid thromboelastography validation in emergency settings.
- Burn Treatment:Albumin and protein measurement controls support fluid resuscitation monitoring in specialized burn centers.
Hemophilia treatment concentrates purchasing authority. Immune deficiency applications are climbing the fastest.
End User:
Customer concentration patterns determine contract structure, with integrated delivery systems capturing pricing leverage unavailable to fragmented purchasers.
- Hospitals:Clinical laboratories source control plasma through group purchasing organizations with tiered pricing tied to ISO 15189 certification status. Northeast and Midwest United States health systems bundle diagnostic and therapeutic blood product budgets, consolidating vendor relationships.
- Blood Banks:Fractionation facilities and transfusion services require viral-inactivated reference materials for quality assurance testing. EMA plasma master file documentation requirements are elevating supplier qualification thresholds.
- Rehabilitation Centers:Extended care facilities with coagulation monitoring capabilities represent emerging demand for point-of-care control materials.
- Research Institutions:Academic and pharmaceutical research laboratories utilize research-grade plasma for assay development, though FDA guidance is collapsing distinctions between research-use and clinical-diagnostic specifications.
Hospitals hold purchasing volume. Blood banks are consolidating supplier panels most aggressively.
Distribution Channel:
Channel selection determines margin capture, with direct relationships preserving pricing power that intermediaries erode.
- Direct Sales:Manufacturers negotiate multi-year agreements with hemophilia treatment center networks and integrated health systems. CSL Behring and Grifols leverage captive plasma collection infrastructure to offer supply continuity guarantees that distributors cannot match.
- Specialty Pharmacies:Rare bleeding disorder management channels procure clotting factor concentrates bundled with control materials, creating margin-focused relationships outside hospital procurement.
- Wholesalers:Regional distributors serve mid-tier hospital laboratories with fragmented purchasing authority and limited contract negotiation capacity.
- Online Retail:Emerging channel for research-grade and secondary market control plasma, though regulatory uncertainty constrains clinical-diagnostic eligibility.
Direct sales commands pricing power. Specialty pharmacies are gaining procurement influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances for specialty control plasma tilt toward net imports in most markets, with fractionation capacity concentrated among a handful of multi-continental suppliers. The United States and Germany anchor procurement demand through hemophilia treatment networks and specialized blood product laboratories. Regulatory divergence between FDA and EMA frameworks creates compliance arbitrage opportunities for manufacturers with dual-continent production footprints.
United States
Hemophilia treatment center networks in the Northeast and Midwest drive calibrated control plasma procurement through bundled multi-year agreements. FDA lot-release requirements for coagulation factor controls exclude research-use materials from clinical eligibility. Boston and Philadelphia clinical clusters standardize analyzer validation protocols that demand pharmaceutical-grade certified reference materials.
Germany
Specialized blood product laboratories in Frankfurt and Munich anchor European demand for immunoglobulin quantification controls. EMA plasma master file documentation requirements elevate supplier qualification thresholds for fractionators sourcing across multiple collection networks. Bavarian testing facilities prioritize integrated donor management systems that satisfy traceability mandates.
Australia
CSL Behring's captive collection infrastructure supplies domestic fractionation facilities with viral-inactivated plasma for coagulation factor production. TGA alignment with EMA frameworks simplifies dual-market registration for control plasma manufacturers. Melbourne and Sydney hospital networks consolidate diagnostic and therapeutic blood product procurement through integrated delivery systems.
Japan
PMDA oversight of plasma-derived products maintains stringent viral safety documentation standards that favor established fractionators with multi-decade track records. Tokyo and Osaka clinical laboratories source control materials through specialized import channels given limited domestic fractionation capacity. METI industrial policy supports biotechnology partnerships that strengthen plasma traceability systems.
Switzerland
Swissmedic regulatory frameworks for blood products attract manufacturers seeking centralized European market access with streamlined conformity assessment. Basel and Zurich pharmaceutical clusters host quality control laboratories that demand ISO 15189-accredited reference materials. The country's position outside EU customs territory creates distribution advantages for non-European suppliers.
Specialty Control Plasma Market Competitive Landscape
Listed leaders compete with private specialists across plasma collection and fractionation capabilities. The market structures around three tiers: integrated plasma collectors with captive fractionation, standalone fractionators sourcing from contracted donor networks, and recombinant developers pressuring traditional plasma-derived pricing. Strategic archetypes include geographic consolidators, vertical integrators, and recombinant substitution players. Capacity expansion and backward integration into plasma collection dominate competitive moves.
CSL Behring and Grifols exemplify the integrated archetype through multi-continent plasma collection infrastructure. Takeda occupies a position bridging plasma-derived and recombinant portfolios. Octapharma and Biotest sit within the specialized fractionator tier. Kedrion Biopharma represents European-focused supply continuity strategies. ADMA Biologics and BPL anchor mid-tier positions dependent on contracted plasma sourcing. LFB exemplifies national-champion structures with government-linked procurement relationships.
| Leading Market Players |
|---|
| CSL Behring |
| Grifols |
| Takeda |
| Octapharma |
| Biotest |
| LFB |
| Kedrion Biopharma |
| ADMA Biologics |
| BPL |
| Others |
Value Network & Pricing Analysis
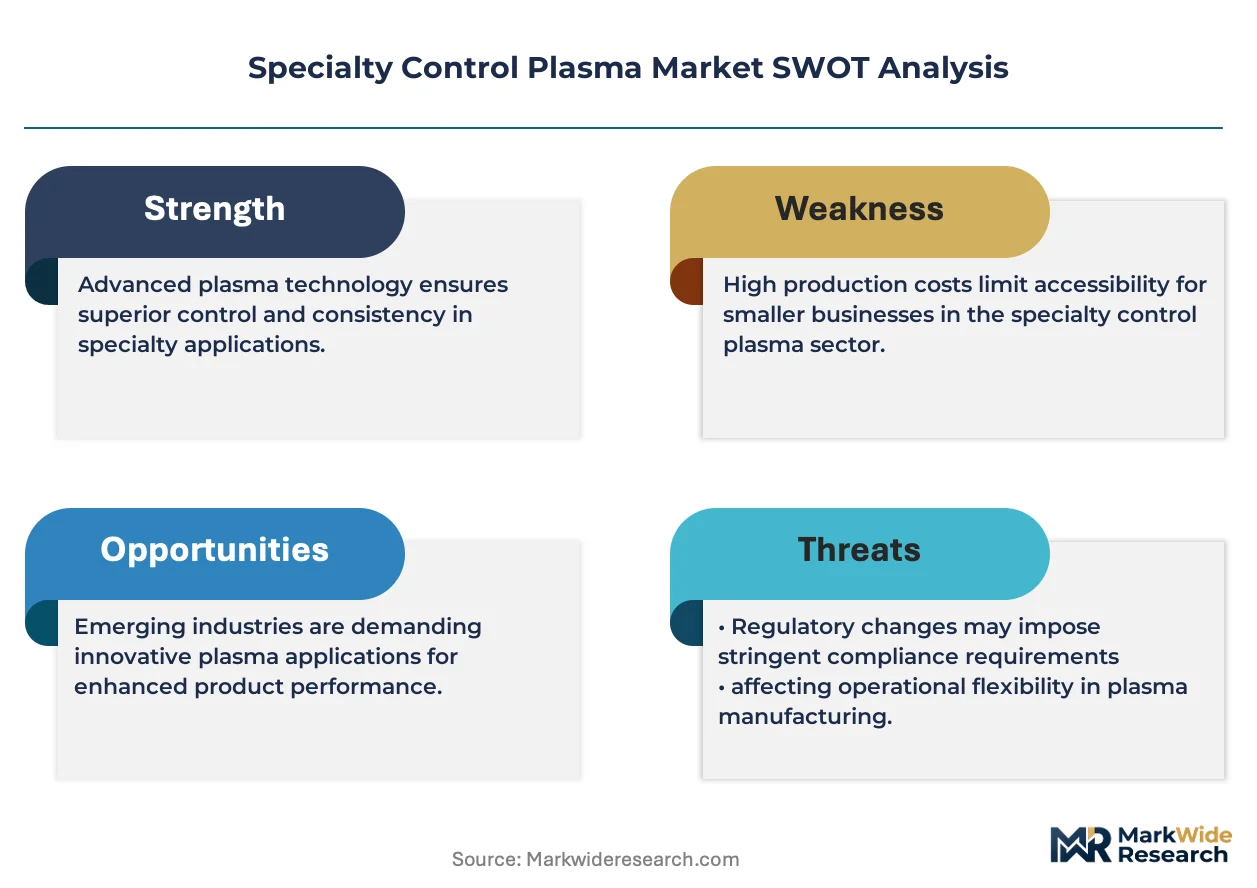
ISO 15189 accreditation gates both supplier qualification and price differentiation simultaneously, as diagnostic laboratories in the United States and Germany exclude uncertified control plasma from procurement eligibility while paying premiums for documented traceability. This certification divide splits the market into pharmaceutical-grade certified reference materials commanding sustained pricing power versus research-use products facing eligibility compression.
Pricing Analysis
Hemophilia treatment center networks anchor contract-based long-term offtake structures, with three-tier pricing structure across premium, standard, and economy levels tied to viral inactivation protocol sophistication and analyte panel breadth. Price differentiation stems from FDA lot-release certification status and captive plasma collection infrastructure ownership. Cost compression in mid-tier immunoglobulin controls is intensifying because recombinant alternative developers are pressuring traditional plasma-derived positioning. Hospital group purchasing organizations exhibit highest price sensitivity, while specialized pharmacy channels managing rare bleeding disorders demonstrate lowest sensitivity due to margin-focused procurement relationships.
Supply Chain Analysis
Plasma collection network concentration across the United States, Germany, and Australia underwrites fractionation capacity allocation for high-purity coagulation factor production. Raw material dependencies center on donor plasma volume, viral inactivation chemistries including amotosalen, and specialized fractionation equipment. Single-source vulnerability runs through geographically concentrated captive collection infrastructure exposed to regional donor availability disruptions. Distribution runs through direct manufacturer relationships with hemophilia treatment center networks, bypassing traditional wholesale channels for premium-tier products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation between FDA and EMA frameworks creates structural white-space for specialized entrants, as divergent plasma master file documentation requirements and MDR conformity pathways generate niche qualification demands that consolidated incumbents address unevenly.
For Market Incumbents: Compound defensive positioning through backward integration into donor management systems that satisfy EMA traceability mandates, while expanding ISO 15189-accredited reference material portfolios to capture laboratory certification-driven demand. Recombinant substitution threats from Takeda and portfolio competitors necessitate locking hemophilia treatment centers into multi-year supply agreements bundling diagnostic controls with therapeutic concentrates.
For New Entrants and Emerging Players: Differentiate on integrated donor management software paired with regional plasma collection partnerships, targeting German and Austrian blood product laboratories where EMA documentation burdens disadvantage fragmented suppliers. Primary immunodeficiency diagnostics in specialized European facilities represents the most penetrable segment, with go-to-market execution through direct clinical laboratory relationships rather than hospital procurement channels.
For Investors and Strategic Acquirers: EU Medical Device Regulation reclassification reshapes the acquisition landscape by elevating fixed compliance costs that strain mid-tier fractionators lacking integrated collection infrastructure. Long-term viability favors suppliers with dual-continent production footprints capable of regulatory arbitrage between FDA and EMA frameworks. The signal to watch is consolidation velocity among standalone fractionators sourcing from contracted donor networks as documentation burdens accelerate.
| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | CSL Behring and Grifols leverage multi-continent infrastructure to guarantee supply continuity for hemophilia treatment centers. |
| Viral Inactivation Technology Retrofit | Photochemical pathogen reduction systems displace solvent-detergent protocols, reducing processing time and expanding donor pool eligibility. |
| Regulatory Dual-Registration Investment | Simultaneous FDA and EMA plasma master file documentation enables market access arbitrage across North American and European jurisdictions. |
| Hemophilia Treatment Center Partnership | Bundled diagnostic-therapeutic agreements lock in multi-year revenue streams and compress spot-market competitor access. |
| Specialized Pharmacy Channel Penetration | Rare bleeding disorder management through clotting factor concentrate distribution captures margin-focused procurement outside hospital laboratories. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA plasma master file submissions, and ISO 15189 accreditation databases, combining structured interviews with fractionation facility directors, diagnostic laboratory quality managers, and hemophilia treatment center procurement leads. Bottom-up demand modeling triangulates against top-down plasma collection volume data from national blood service agencies across the United States, Germany, and Australia.
Segmentation dimensions modeled include coagulation factor versus immunoglobulin versus albumin control categories, hemophilia treatment versus immune deficiency versus trauma care applications, and direct sales versus specialty pharmacy versus wholesale distribution channels. CAGRs were derived from installed base growth of coagulation analyzers, diagnosis rate trends for primary immunodeficiency, and plasma collection network expansion trajectories across the projection horizon.
Forecasts assume regulatory continuity in FDA blood product guidance and EMA medical device frameworks; material policy shifts including accelerated recombinant substitution mandates or tightened viral safety documentation would require re-modeling. Practitioners should keep alternative scenarios live as MDR implementation timelines and plasma traceability requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
North America Pressure Sensors Market
Sensors and Controls
Global Smart Biosensors Market
Sensors and Controls
Sensor Development Kit Market
Sensors and Controls
Smart Level Probe Market
Sensors and Controls
Sensor Bearing Market
Sensors and Controls
Water and Wastewater Sensors Market
Sensors and Controls
Infrared Sensors Market
Sensors and Controls
Parking Sensors Market
Sensors and Controls
Asia-Pacific Touch Sensor Market
Sensors and Controls
PM2.5 Sensors Market
Sensors and Controls
Microseismic Monitoring Technology Market
Sensors and Controls
Distributed Fiber Optic Sensing Market
Sensors and Controls
Glucose Sensor Market
Sensors and Controls
Digital Array Microphone Market
Sensors and Controls
Pressure Transmitter Market
Sensors and Controls
Inductive Encoder Market