
 Semiconductor Film Market | 2026-2036
Semiconductor Film Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Film Market Analytics
Advanced-node polyimide specifications is reorganizing procurement priorities across the Semiconductor Film Market. Nitto Denko Corporation leverages its adhesive-coating dominance in East Asian supply chains. DuPont de Nemours, Inc. sustains R&D intensity around high-temperature dielectric formulations. Panasonic Corporation anchors display-integrated semiconductor packaging through its materials-science division.
Semiconductor film denotes thin-layer substrates or deposited coatings—typically one to fifty micrometers thick—engineered for electrical insulation, thermal management, or patterned conductivity in microelectronic fabrication. These films enable wafer-level packaging, interposer routing, and flexible circuit substrates that downstream device assemblers require for miniaturization. Polyimide films command premium positioning due to their thermal stability in flip-chip bonding, while copper films face margin compression from electroplating efficiency gains. Application demand across RF components outpaces display films as 5G base-station deployment accelerates substrate consumption.
EPA rules on perfluorinated compound emissions constrain wet-processing chemistries in US-based film manufacturing. REACH substance restrictions and RoHS hazardous-material limits in Europe redirect formulation investments toward halogen-free polymer alternatives. Japan's METI subsidizes domestic supply-chain resilience for critical semiconductor materials. Stakeholders must monitor how dual-use export controls and carbon-border adjustment mechanisms reshape regional sourcing economics.
Market Dynamics
Advanced-node polyimide specifications are reorganizing procurement priorities across the Semiconductor Film Market, as thermal stability requirements in flip-chip bonding compress supplier qualification timelines and concentrate volume commitments among coating-capable specialists.
Growth Catalysts
- Advanced Packaging Demand:Consumer electronics manufacturers are accelerating wafer-level packaging adoption for smartphone and wearable miniaturization, pulling high-temperature dielectric formulations into mainstream procurement.
- REACH Compliance:European RoHS hazardous-material limits and ECHA substance restrictions are redirecting formulation investments toward halogen-free polymer alternatives, expanding addressable markets for compliant suppliers.
- 5G Infrastructure Deployment:RF component substrate consumption is outpacing display film demand as base-station buildouts concentrate procurement in South Korea's Seoul-Pyeongtaek memory cluster.
Market Restraints
- Fluorinated Compound Constraints:EPA emissions rules on perfluorinated wet-processing chemistries are constraining US-based film manufacturing flexibility and elevating compliance overhead.
- Copper Film Margin Compression:Electroplating efficiency gains in East Asian supply chains are eroding profitability for legacy copper deposition specialists.
- Supply Concentration Risk:Adhesive-coating dominance in East Asian supply chains creates single-source vulnerability for advanced-node polyimide procurement.
Strategic Opportunities
- Carbon-Border Adjustment Positioning:EU carbon-border mechanisms are creating first-mover advantages for low-emission film producers qualifying under CSRD-aligned supply chain reporting.
- Flexible Circuit Substrates:Display-integrated semiconductor packaging is opening new specification tiers for materials-science divisions with roll-to-roll coating capabilities.
- Domestic Resilience Subsidies:Japan's METI subsidies for critical semiconductor materials are enabling captive supply investments for polyimide precursor production.
Industry Challenges
- Dual-Use Export Control Navigation:Stakeholders face qualification timeline extensions as semiconductor film technologies trigger cross-border licensing requirements in multiple jurisdictions.
- High-Temperature Dielectric R&D Intensity:Sustained capital allocation for formulation science is compressing cash conversion cycles for mid-tier material suppliers.
- Halogen-Free Certification Timelines:REACH-aligned substance verification is extending product launch cycles by 12-18 months for reformulated polymer platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Film Market |
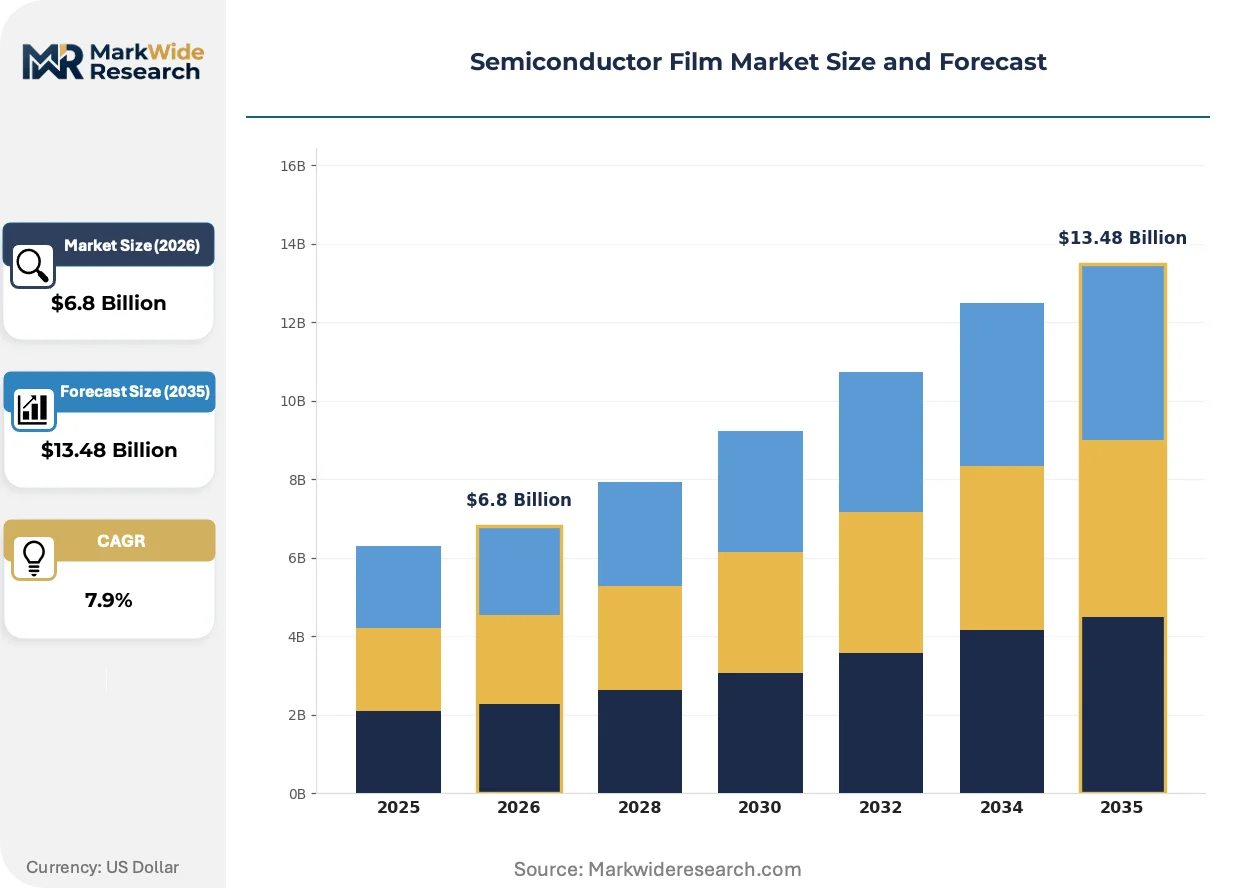
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.48 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Film Type: Copper, Polyimide, Silicon, Epitaxial Application: Displays, Solar Cells, RF Components, Semiconductor Devices End User: Consumer Electronics, Automotive, Telecommunications, Industrial Technology: CVD, PVD, Electroplating, Etching |
| Companies Covered | Nitto Denko Corporation, DuPont de Nemours, Inc., Panasonic Corporation, FUJIFILM Holdings Corporation, Toray Industries, Inc., 3M Company, Saint-Gobain S.A., LINTEC Corporation, Mitsubishi Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Film Market Evolving Landscape
Process-material convergence and regulatory chemistry restrictions are actively restructuring how semiconductor films are specified, sourced, and integrated into downstream device assembly.
Polyimide film technology is bifurcating between ultra-thin interposer routing substrates and thick-film flexible circuit carriers. Memory module assemblers in South Korea are adopting sub-10-micron specifications for high-bandwidth packaging, while automotive sensor suppliers are qualifying 25-50-micron grades for thermal cycling durability. This specification spread is compressing batch-process economics and rewarding continuous-coating infrastructure investments.
EU F-Gas Regulation and REACH substance restrictions are prohibiting specific fluorinated process aids in European film manufacturing. Formulators are pivoting toward aqueous dispersion chemistries and silicone-modified polyimide backbones to maintain dielectric performance. Display-integrated packaging applications face the steepest reformulation timelines, with ECHA SVHC candidate list monitoring now embedded in supplier quality protocols.
Buyer concentration around Seoul-Pyeongtaek memory fabs is compressing supplier negotiation cycles and elevating long-term offtake contracting. Tier-one device assemblers are consolidating qualified vendor lists to three coating-capable specialists, displacing spot-market purchasing for critical dielectric layers. This procurement consolidation is most visible in high-volume polyimide tape substrates for DRAM module assembly.
Semiconductor Film Market Segmentation
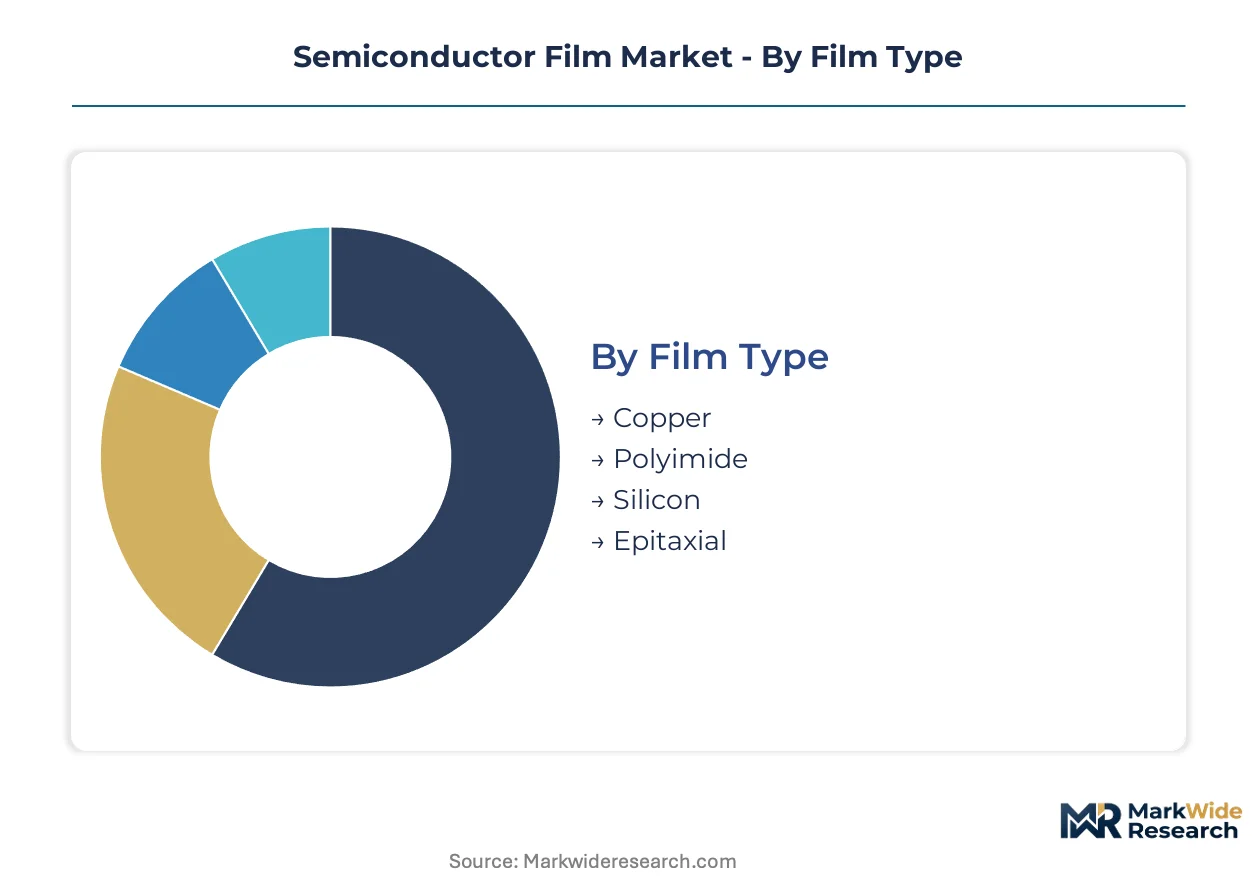
Semiconductor film segmentation reveals how material specifications, deposition technologies, and end-use requirements fragment procurement economics across distinct value pools. Buyers prioritize thermal stability thresholds, patterning precision, and regulatory compliance profiles when qualifying suppliers.
Film Type:
Margin pools concentrate in high-temperature dielectric formulations where coating-capable specialists command premium positioning through adhesive-layer integration.
- Polyimide:Aromatic heterocyclic polymer films deliver thermal stability exceeding 400°C for flip-chip bonding and wafer-level packaging. Seoul-Pyeongtaek memory fabs are consolidating procurement around sub-10-micron specifications for high-bandwidth DRAM modules, compressing supplier qualification timelines.
- Copper:Electroplated metal layers provide patterned conductivity for interposer routing and redistribution layers. East Asian supply chain efficiency gains are eroding profitability for legacy deposition specialists serving commodity interconnect applications.
- Silicon:Crystalline or amorphous semiconductor substrates enable epitaxial device layers and MEMS structures. Solar cell manufacturers in China's Jiangsu province anchor volume demand for photovoltaic-grade specifications.
- Epitaxial:Single-crystal films grown on lattice-matched substrates deliver precise doping profiles for power electronics and RF transistors. Automotive SiC device suppliers are qualifying 150mm and 200mm wafer formats for traction inverter modules.
Polyimide holds installed capacity. Epitaxial is rotating up the share rankings.
Application:
Application-driven demand splits between display-integrated packaging requiring optical transparency and RF substrates prioritizing dielectric constant stability.
- RF Components:Low-loss dielectric films with controlled permittivity enable 5G base-station filters and antenna-in-package modules. South Korea's telecommunications infrastructure buildout is concentrating procurement in Seoul-Pyeongtaek supplier clusters.
- Semiconductor Devices:Patterned films for logic and memory devices span interposer dielectrics, redistribution layers, and temporary bonding adhesives. Advanced-node foundries in Taiwan's Hsinchu Science Park are driving sub-5-micron specification adoption.
- Displays:Flexible substrate films and encapsulation barriers for OLED panels require barrier oxygen transmission rates below 10^-6 g/m²/day. Roll-to-roll coating investments in Japan's Kansai region are capturing flexible circuit substrate demand.
- Solar Cells:Anti-reflection coatings and passivation layers improve photovoltaic conversion efficiency. PERC and TOPCon cell architectures in China's Anhui province are pulling atomic-layer-deposited film consumption.
RF Components is expanding most quickly. Semiconductor Devices retains the largest absolute volume position.
End User:
End-user concentration patterns reflect how automotive qualification timelines and consumer electronics volume scale create divergent supplier economics.
- Consumer Electronics:Smartphone and wearable manufacturers drive the highest volume demand for ultra-thin flexible substrates. Apple's supply chain in Vietnam and India's Tamil Nadu is diversifying sourcing beyond legacy China-centric procurement.
- Automotive:ADAS sensors, power modules, and battery management systems require AEC-Q100 qualified films with extended temperature cycling durability. German OEMs in Bavaria are qualifying 25-50-micron polyimide grades for thermal shock resistance.
- Telecommunications:Base-station and optical networking equipment demands high-frequency stable dielectrics with low dissipation factors. Ericsson's manufacturing partners in Estonia and Poland are sourcing halogen-free alternatives under REACH compliance.
- Industrial:Factory automation and power electronics applications prioritize long-term reliability over miniaturization. Japanese machine tool builders in Nagoya are specifying thicker film formats for motor drive inverters.
Consumer Electronics holds installed capacity. Automotive is climbing the fastest.
Technology:
Technology selection determines capital intensity and environmental compliance burden, with wet-processing chemistries facing tightening emissions constraints.
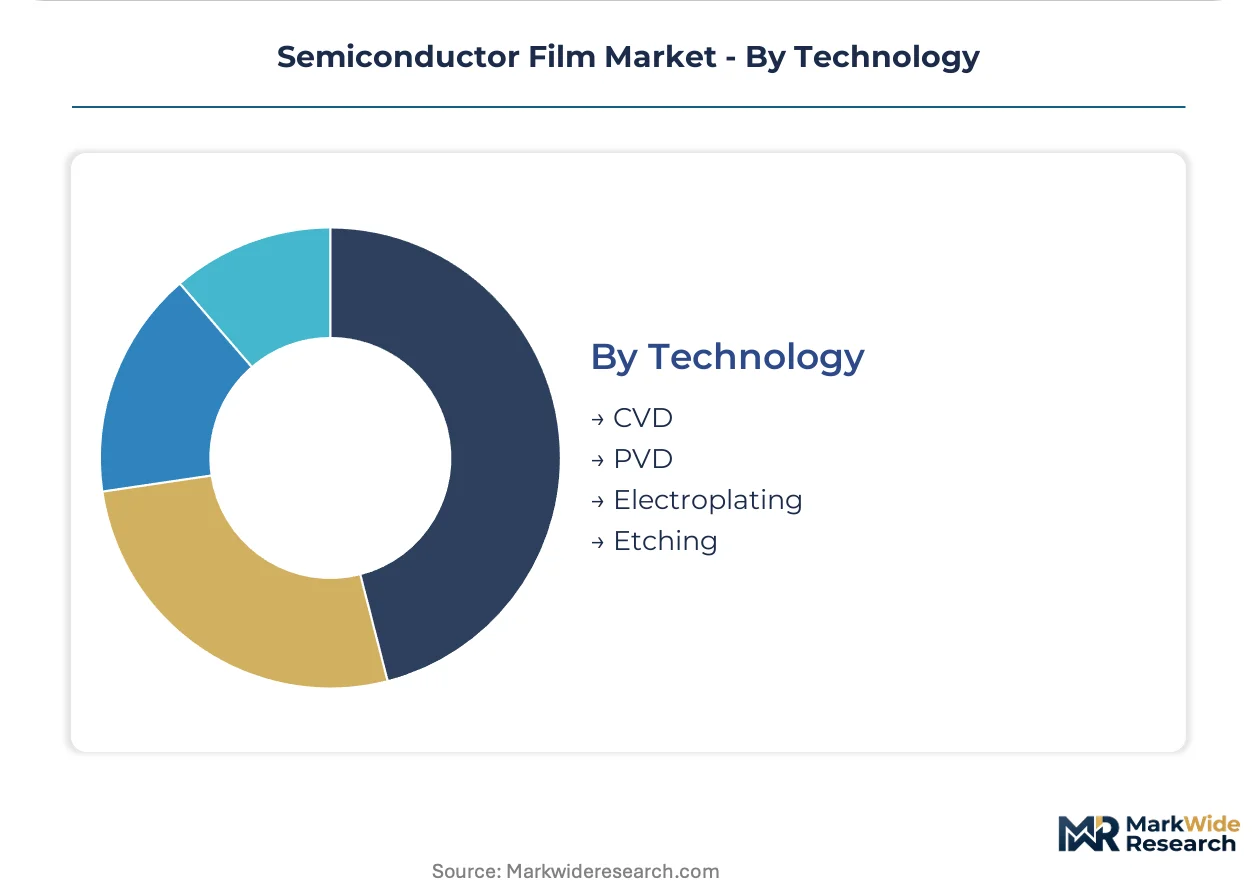
- CVD:Chemical vapor deposition delivers conformal, high-purity films for critical dielectric and barrier layers. Memory fabs in South Korea's Pyeongtaek are expanding plasma-enhanced CVD capacity for 3D NAND stack deposition.
- Electroplating:Electrochemical metal deposition provides cost-effective copper seed and via fill for redistribution layers. EPA perfluorinated compound emission rules are constraining US-based wet-processing flexibility.
- PVD:Physical vapor deposition sputters metal and ceramic films with precise thickness control. RF component suppliers in Germany's Saxony region are qualifying PVD copper-nickel-gold stacks for 5G filter electrodes.
- Etching:Wet and dry patterning processes define circuit geometries and via structures. Japan's METI subsidies are supporting domestic etching chemistry supply-chain resilience for critical semiconductor materials.
CVD holds installed capacity. PVD is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in semiconductor films tilt heavily toward net-import positions in North America and Europe, while East Asian production clusters generate substantial export surpluses. South Korea, Japan, and Taiwan collectively supply over sixty percent of specialized polyimide and copper redistribution layers consumed by advanced packaging foundries worldwide.
South Korea
Memory module assembly for high-bandwidth DRAM and 3D NAND stack deposition drives polyimide consumption in the Seoul-Pyeongtaek corridor. The Ministry of Trade, Industry and Energy administers domestic content requirements under the K-Chips Act. Samsung Electronics and SK Hynix concentrate procurement among three qualified coating specialists in the Gyeonggi-do province.
Japan
Roll-to-roll coating investments for flexible OLED encapsulation and automotive sensor substrates anchor demand in the Kansai and Chubu regions. METI subsidizes domestic precursor production for critical semiconductor materials under supply-chain resilience programs. Toray Industries and Mitsubishi Chemical maintain integrated polyimide film operations in Shiga and Mie prefectures.
United States
Defense-qualified foundries and RF component manufacturers in Arizona and Texas import specialized dielectric layers from East Asian suppliers. EPA emissions rules on perfluorinated wet-processing chemistries constrain domestic film manufacturing flexibility. Intel's advanced packaging investments in New Mexico and Oregon pull imported polyimide tape substrates for EMIB and Foveros architectures.
Germany
Automotive SiC power module suppliers in Bavaria and Saxony qualify 25-50-micron polyimide grades for traction inverter thermal cycling durability. ECHA substance restrictions and REACH compliance redirect formulation investments toward halogen-free alternatives. Bosch and Infineon consolidate qualified vendor lists for AEC-Q100 certified films serving electric vehicle platforms.
China
Photovoltaic cell manufacturers in Jiangsu and Anhui provinces consume atomic-layer-deposited passivation films for PERC and TOPCon architectures. MIIT industrial policy prioritizes domestic substitution for imported high-end polyimide used in flexible circuit substrates. Yangtze Memory Technologies and Hua Hong Semiconductor drive local sourcing requirements for 300mm wafer processing materials.
Semiconductor Film Market Competitive Landscape
Concentration sits with diversified materials conglomerates possessing integrated coating and adhesive-layer capabilities. The vendor base separates into three tiers: Japanese and Korean specialists dominating high-temperature dielectric formulations, European chemical groups supplying halogen-compliant alternatives, and diversified industrials serving commodity interconnect applications. Strategic moves center on backward integration into precursor production and geographic expansion through qualified foundry partnerships.
Within the Japanese specialist tier, Nitto Denko Corporation and Toray Industries exemplify coating-capable suppliers with integrated adhesive expertise. DuPont de Nemours, Inc. occupies a position among diversified chemical conglomerates with sustained formulation science investments. Panasonic Corporation represents the display-integrated packaging vector through materials-science division capabilities. These three anchors illustrate how procurement consolidation around Seoul-Pyeongtaek memory fabs compresses supplier negotiation cycles and elevates long-term offtake contracting.
| Leading Market Players |
|---|
| Nitto Denko Corporation |
| DuPont de Nemours, Inc. |
| Panasonic Corporation |
| FUJIFILM Holdings Corporation |
| Toray Industries, Inc. |
| 3M Company |
| Saint-Gobain S.A. |
| LINTEC Corporation |
| Mitsubishi Chemical Corporation |
| Others |
Value Network & Pricing Analysis
Sixty-day qualification timelines for advanced-node polyimide specifications concentrate procurement leverage among three coating-capable specialists in East Asia, compressing spot-market liquidity and elevating long-term contract premiums for qualified supply. This lead-time rigidity binds pricing power to adhesive-layer integration capabilities and foundry certification status.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures in the Semiconductor Film Market. Pricing stratifies across AEC-Q100 certified automotive tiers, REACH-compliant halogen-free formulations, and standard industrial grades. Cost compression in copper deposition tiers is intensifying because electroplating efficiency gains in South Korean supply chains erode legacy specialist margins. Consumer electronics assemblers exhibit highest price sensitivity due to volume scale and vendor consolidation, while automotive qualification timelines insulate AEC-Q100 suppliers from spot-market volatility.
Supply Chain Analysis
Pyongtaek port throughput and Incheon International Airport cargo lanes tether East Asian polyimide supply to global downstream demand. Manufacturing concentrates in South Korea, Japan, and Taiwan, with precursor chemistry anchored in Shiga and Mie prefectures. Raw material flows draw from dianhydride monomers, fluorinated process aids, and high-purity copper anodes. Single-source vulnerability around adhesive-coating specialists creates qualification bottleneck risk. Distribution runs through qualified foundry partnerships and consolidated vendor lists serving Seoul-Pyeongtaek memory clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for formulation customization and qualification support are expanding faster than base film hardware sales, creating recurring-revenue attach opportunities for coating-capable specialists.
For Market Incumbents: Fortify backward integration into dianhydride precursor production to defend margin position against electroplating efficiency gains eroding copper film profitability. Expand captive supply investments in Japan's METI-subsidized domestic resilience programs to offset single-source vulnerability in East Asian adhesive-coating supply. For New Entrants and Emerging Players: REACH-aligned halogen-free certification fast-tracks open procurement slots at Ericsson's manufacturing partners in Estonia and Poland seeking compliant alternatives. Target automotive sensor substrate specifications in Germany's Bavaria region where 25-50-micron polyimide grades face extended qualification timelines and incumbent capacity constraints. Lead with aqueous dispersion chemistry expertise to bypass fluorinated compound constraints constraining US-based manufacturing. For Investors and Strategic Acquirers: Long-term, this sits as a materials-science consolidation play because procurement consolidation around Seoul-Pyeongtaek memory fabs compresses qualified vendor lists to three coating-capable specialists. Acquire roll-to-roll coating infrastructure with integrated adhesive-layer capabilities and existing foundry partnerships. Monitor ECHA SVHC candidate list expansions as inflection indicators for reformulation investment cycles and halogen-free platform transitions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Captive dianhydride supply insulates margins from monomer price volatility and METI subsidy eligibility. |
| REACH-Compliant Halogen-Free Certification | ECHA-aligned formulations unlock Ericsson and Bosch procurement slots under European hazardous-material limits. |
| Roll-to-Roll Coating Capacity Expansion | Continuous-coating infrastructure rewards sub-10-micron polyimide specifications for Samsung and SK Hynix DRAM modules. |
| Long-Term Foundry Partnership Agreements | Qualified supplier status at Taiwan's Hsinchu Science Park secures sub-5-micron specification volume commitments. |
| AEC-Q100 Automotive Qualification Investment | Thermal cycling durability certification opens Bosch and Infineon traction inverter procurement in Bavaria. |
Research Methodology
Cross-validation between foundry procurement director interviews and customs trade data anchors the qualitative findings in the Semiconductor Film Market. Primary fieldwork engaged polyimide formulation scientists, memory fab supply chain managers, automotive Tier 1 qualification engineers, and coating equipment specialists. Secondary sources encompassed SEC 10-K filings from materials conglomerates, Korea Customs Service import records, ECHA SVHC candidate list updates, and METI subsidy disclosure documents. Bottom-up vendor capacity assessments and top-down end-use consumption estimates were reconciled through iterative triangulation.
Sensitivity analysis across polyimide grade tiers, deposition technology capital intensity, and regional regulatory compliance clusters shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include film type specifications, application thermal stability thresholds, end-user qualification requirements, and technology environmental compliance burden. CAGRs were derived from installed capacity expansion schedules, foundry capex disclosure patterns, and substitution elasticity between copper and polyimide interconnect solutions.
Decision-makers should treat outputs as directional under assumptions of sustained Seoul-Pyeongtaek memory cluster concentration and stable REACH substance restriction timelines; material deviation in foundry geographic diversification or fluorinated compound regulatory stringency would warrant model refresh. Practitioners should keep alternative scenarios live as EU carbon-border adjustment mechanisms and dual-use export control licensing requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Indium Gallium Zinc Oxide Market
Semiconductor Material
Indium Market
Semiconductor Material
Global Electronic Materials Market
Semiconductor Material
Metallurgical Grade Silicon Market
Semiconductor Material
Glass Substrate in Semiconductor Market
Semiconductor Material
Silicon Nitride Balls Market
Semiconductor Material
Electronic Ceramics Market
Semiconductor Material
Global Silicon Carbide (SIC) Market
Semiconductor Material
Semiconductor Silicon Material Market
Semiconductor Material
Synthetic Sapphire Market
Semiconductor Material
Semiconductor Materials Market
Semiconductor Material
Chromium Oxide Market
Semiconductor Material
India Liquid Silicon Rubber Market
Semiconductor Material
Glass Wafer Market
Semiconductor Material
Barium Titanate Market
Semiconductor Material
DCB and AMB Substrate Market