
 Semiconductor Fabrication Material Market | 2026-2036
Semiconductor Fabrication Material Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Fabrication Material Market Intelligence
The shift towards advanced logic and memory chips for AI workloads is recalibrating the demand for specific fabrication materials away from mature process nodes. Shin-Etsu Chemical Co., Ltd. leverages its dominant position in silicon wafer manufacturing to supply leading-edge foundries. DuPont de Nemours, Inc. specializes in advanced photoresists and polymers critical for sub-10nm lithography. Air Liquide S.A. controls a significant share of the high-purity specialty gases essential for deposition and etching processes.
Semiconductor fabrication materials encompass a range of high-purity substances used to build integrated circuits on silicon wafers. These materials, including specialty chemicals and gases, must meet stringent purity standards, often measured in parts per billion, to prevent device defects. Within the material types, wafers and photoresists constitute significant value segments. Demand from leading-edge foundries for materials supporting advanced photolithography and etching processes for memory chips and complex SoCs drives margin and innovation.
Environmental regulations increasingly govern the use and disposal of fabrication chemicals. Frameworks such as the EU's REACH regulation, the US EPA's rules on per- and polyfluoroalkyl substances (PFAS), and China's MEE directives on volatile organic compounds (VOCs) compel material suppliers to invest in greener chemistry. The strategic imperative for suppliers now lies in developing high-performance, compliant materials that do not compromise chip yield or reliability.
Market Dynamics
The imperative to scale transistor density for AI and high-performance computing is the central force shaping the semiconductor fabrication material market. This pressure drives a constant, capital-intensive search for novel materials compatible with next-generation lithography and device architectures like Gate-All-Around.
Growth Catalysts
- Advanced Architectures:The transition to Gate-All-Around (GAA) and other 3D transistor structures necessitates new high-purity materials for atomic layer deposition (ALD) and selective etching processes, fueling demand from leading-edge foundries.
- Automotive Electrification:Demand for power semiconductors using wide-bandgap materials like silicon carbide (SiC) and gallium nitride (GaN) is expanding rapidly, creating a significant consumption category for specialized substrates and epitaxial gases.
- National Semiconductor Policies:Government initiatives such as the US CHIPS Act and the EU Chips Act are stimulating new fab construction, which in turn creates localized demand for a complete ecosystem of bulk gases, specialty chemicals, and wafers.
Market Restraints
- Input Cost Volatility:The pricing of critical raw materials, including high-purity quartz for crucibles and rare gases like neon and xenon sourced from conflict-adjacent regions, is subject to extreme volatility, impacting supplier margins.
- Regulatory Scrutiny:Environmental regulations, particularly the EU's potential restrictions on all per- and polyfluoroalkyl substances (PFAS) under REACH, threaten to ban essential non-reactive coolants and etchants, creating significant reformulation challenges.
- Extreme Purity Requirements:As node sizes shrink, purity specifications tighten to parts-per-quadrillion levels for some chemicals, dramatically increasing production costs and limiting the number of qualified suppliers for the most advanced processes.
Strategic Opportunities
- Green Chemistry Innovation:Developing biodegradable or easily recyclable photoresists, solvents, and cleaning agents that meet stringent performance criteria offers a path to capture share as foundries adopt corporate sustainability goals.
- Advanced Packaging Materials:The shift towards chiplet-based designs and heterogeneous integration creates a substantial market for new dielectric materials, mold compounds, and substrates that enable high-density interconnects.
- Emerging Fab Ecosystems:New foundry investments in geographies like India and Germany provide an opportunity for material suppliers to establish greenfield production sites and secure long-term contracts, diversifying supply chains away from East Asia.
Industry Challenges
- Capital-Intensive Scaling:Building new plants or upgrading existing facilities to produce next-generation materials at the required purity and volume demands massive capital investment with long return-on-investment timelines.
- Metrology and Analytics Gap:The ability to detect and measure infinitesimally small contaminants is lagging behind purity requirements, making quality control and defect analysis for sub-3nm materials a major operational hurdle.
- Lengthy Qualification Cycles:Any new material or change in an existing one must undergo a rigorous and time-consuming qualification process by each chipmaker, creating a significant barrier to entry and slowing the pace of innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Fabrication Material Market |
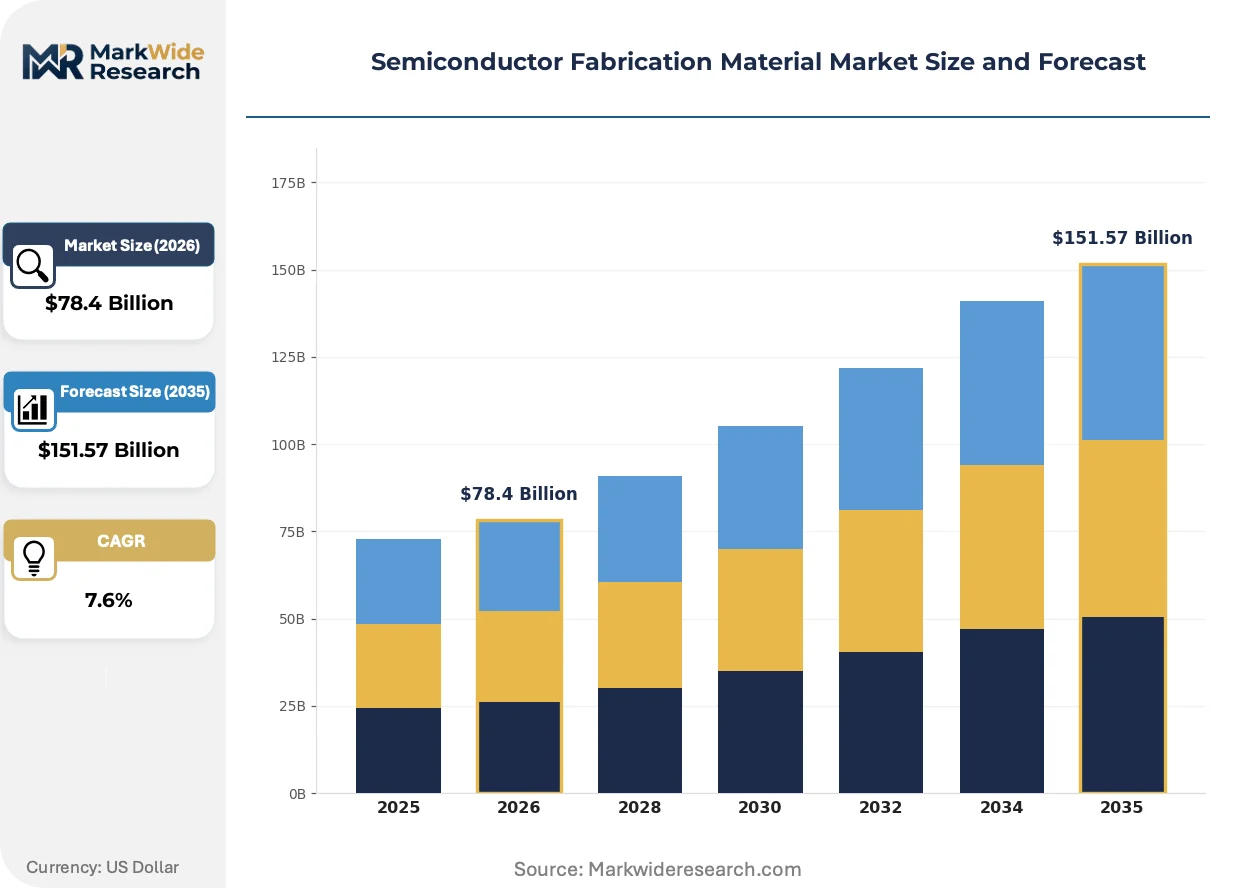
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $151.57 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Chemicals, Photoresists, Doping Agents, Wafers, Cleaning Agents, Dielectrics Technology: Photolithography, Etching, Chemical Vapor Deposition, Ion Implantation, Chemical Mechanical Planarization, Electroplating Application: Integrated Circuits, Microelectromechanical Systems, LED Chips, Sensors, Power Devices, Memory Chips End User: Foundries, Memory Manufacturers, Fabless Companies, Assembly & Test Firms, IDM Suppliers, Research Institutes |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., Merck KGaA, DuPont de Nemours, Inc., Siltronic AG, Air Liquide S.A., JSR Corporation, Toppan Printing Co., Ltd., Honeywell International, Inc., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Fabrication Material Market Strategic Shifts & Innovations
The market is defined by a fundamental tension between the relentless pursuit of atomic-scale manufacturing and the growing mandate for environmental sustainability. Material innovation focuses on enabling next-generation chip performance while simultaneously reducing the ecological footprint of the fabrication process through new chemistries and circular economy models.
Directed Self-Assembly (DSA) is a key patterning technology utilizing block copolymers to form nanoscale features. Leading-edge logic and memory producers are actively evaluating DSA to augment extreme ultraviolet (EUV) lithography for future nodes below 2nm. This technology is unifying the previously distinct fields of polymer chemistry and semiconductor lithography, creating a new class of smart materials that self-organize to create complex circuit patterns.
Broad restrictions on per- and polyfluoroalkyl substances (PFAS) proposed under the European Union's REACH framework are creating significant uncertainty. This regulatory action affects a vast array of fluorinated materials critical for etching, deposition chamber cleaning, and cooling. Material suppliers with global operations are now proactively investing in R&D for non-PFAS alternatives to de-risk their portfolios and ensure continued market access in Europe.
Foundries are evolving their material procurement and qualification by incorporating material informatics and digital twin models. This shift reduces reliance on time-consuming physical wafer testing by using computational models to predict how a new chemical or gas will perform in a specific process flow. The trend is most visible in South Korea and Taiwan, favoring material suppliers who can provide extensive digital data and simulation-ready models for their products.
Semiconductor Fabrication Material Market Segmentation
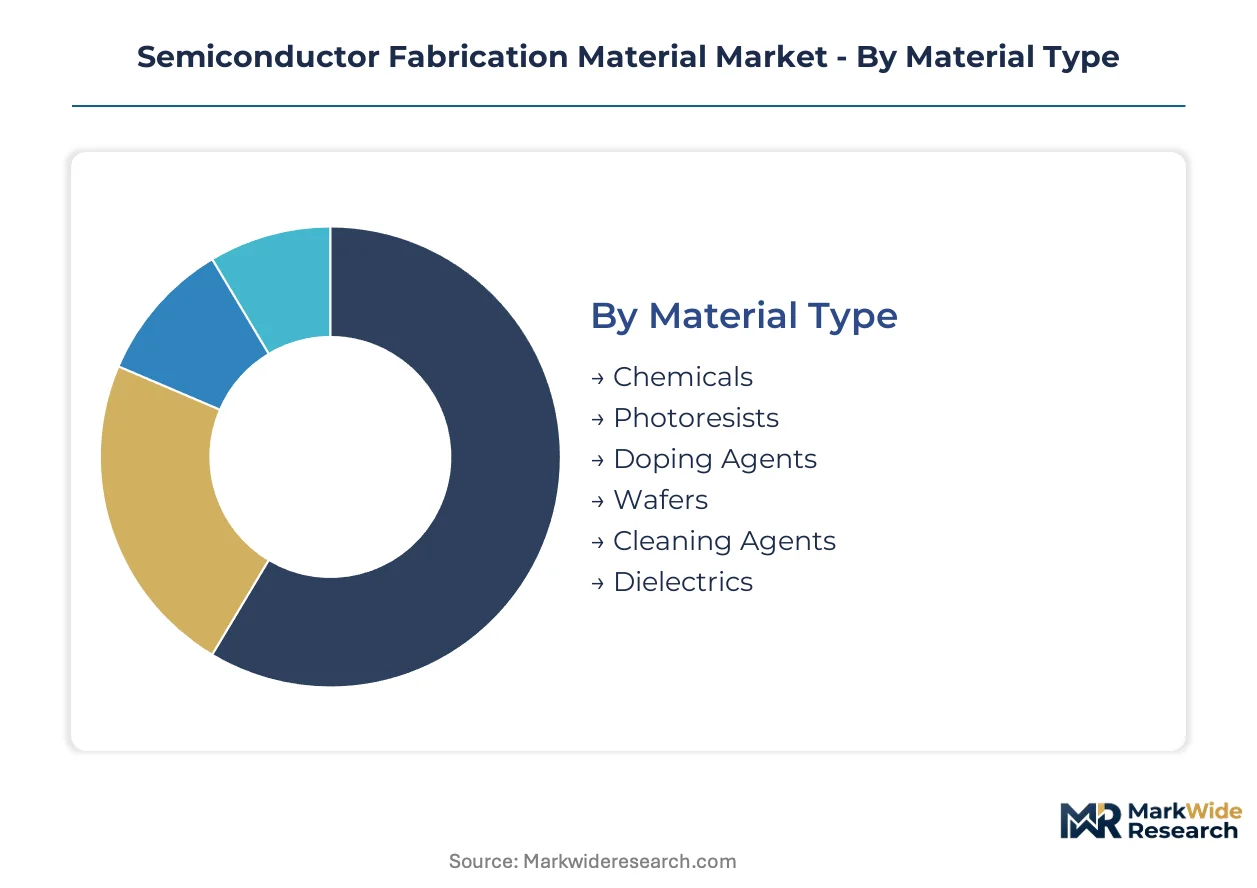
The semiconductor fabrication material market segments highlight the diverse material requirements and technological processes essential for integrated circuit manufacturing. Understanding these distinct categories provides clarity on where demand concentrates and innovation efforts focus across the value chain.
Material Type:
The material type segmentation highlights the spectrum from highly standardized bulk chemicals to custom-engineered substances tailored for specific process nodes.
- Wafers:These are thin slices of semiconductor material, typically silicon, serving as the substrate for microelectronic devices. Demand for larger diameter wafers and advanced silicon-on-insulator (SOI) wafers is critical for high-performance computing applications.
- Photoresists:Light-sensitive polymers used in photolithography to transfer circuit patterns onto a wafer surface. Advanced photoresists are crucial for enabling extreme ultraviolet (EUV) lithography at sub-10nm nodes in Taiwan.
- Chemicals:This broad category includes a variety of high-purity wet chemicals used for cleaning, etching, and other surface preparation steps during fabrication. These substances maintain device integrity.
- Doping Agents:Impurity elements like boron or phosphorus introduced into semiconductor materials to alter their electrical conductivity. These agents are fundamental for transistor functionality.
- Cleaning Agents:Specialized solutions designed to remove contaminants from wafer surfaces without causing damage. Stringent purity standards apply to these agents.
- Dielectrics:Insulating materials used to separate conductive layers within a chip, preventing electrical interference. High-k dielectric materials are vital for advanced transistor gate stacks.
Leading the category by volume: Wafers. Growing fastest: Photoresists.
Technology:
Technology segments reflect distinct stages in the fabrication process, each demanding specialized materials and precise control.
- Photolithography:This process uses light to transfer geometric patterns from a photomask to a light-sensitive chemical resist on the wafer. Advanced materials for EUV lithography drive patterning capabilities for AI accelerators.
- Chemical Vapor Deposition:A process that deposits thin films of material onto a substrate by chemical reaction of gaseous precursors. This technique is essential for creating insulating, conducting, and semiconducting layers in complex 3D structures.
- Etching:The process of selectively removing material from the wafer surface to create circuit features. Plasma etching techniques enable precise pattern transfer for advanced nodes.
- Ion Implantation:A technique used to introduce dopant atoms into a semiconductor substrate to modify its electrical properties. This method offers precise control over doping profiles.
- Chemical Mechanical Planarization:A hybrid process combining chemical slurry and mechanical abrasion to achieve a smooth, flat surface on the wafer. This step is critical for multi-layer device integration.
- Electroplating:An electrochemical process used to deposit metal layers, such as copper interconnects, onto the wafer surface. This technique forms conductive pathways within the chip.
Photolithography and chemical vapor deposition processes drive material science advancements for next-generation devices.
Application:
Application segments differentiate material requirements based on device complexity, performance specifications, and integration density.
- Integrated Circuits:Complex electronic circuits fabricated on a single semiconductor substrate, forming the core of modern electronics. Materials for integrated circuits demand extreme purity for defect reduction.
- Memory Chips:Semiconductor devices designed to store digital data, including DRAM and NAND flash. Materials for memory chips require high reliability and performance in data retention.
- Microelectromechanical Systems:Miniaturized devices integrating mechanical and electrical components, used in sensors and actuators. These systems often utilize specialized substrate materials.
- LED Chips:Light-emitting diode devices that convert electrical energy into light. Gallium nitride (GaN) and sapphire are key materials for LED chip manufacturing.
- Sensors:Devices that detect and respond to physical input from the environment. Materials for sensors prioritize sensitivity and stability across various operating conditions.
- Power Devices:Semiconductors designed to handle high voltages and currents, used in power management applications. Wide-bandgap materials like silicon carbide (SiC) are crucial for power devices.
Integrated circuits and memory chips underpin the bulk of material demand, propelled by AI and high-performance computing workloads.
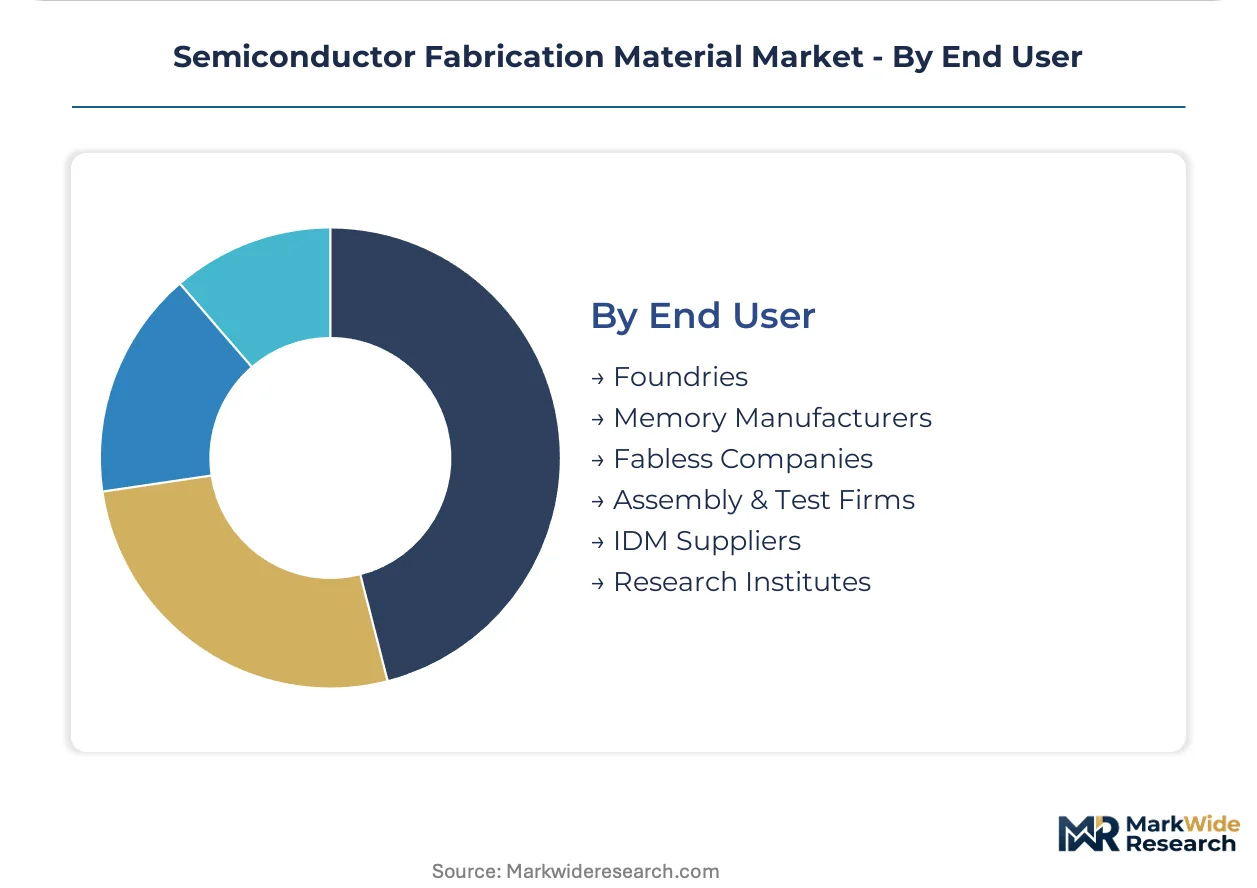
End User:
End user segments delineate material consumption patterns based on operational scale, manufacturing focus, and supply chain integration.
- Foundries:Companies that manufacture integrated circuits for other fabless companies. Foundries represent the largest consumers of advanced fabrication materials due to their scale and technology leadership.
- Memory Manufacturers:Firms specializing in the production of memory chips like DRAM and NAND flash. These manufacturers drive demand for specific materials optimized for memory cell structures.
- Fabless Companies:Businesses that design integrated circuits but outsource their fabrication to foundries. These companies influence material specifications through their design requirements.
- Assembly & Test Firms:Companies responsible for packaging and testing semiconductor devices after fabrication. They consume materials like mold compounds and bonding wires.
- IDM Suppliers:Integrated Device Manufacturers design, manufacture, and sell their own semiconductor products. These firms control their entire material procurement and usage internally.
- Research Institutes:Academic and corporate entities engaged in fundamental and applied research in semiconductor technology. These institutes drive innovation in novel materials and processes.
Foundries and memory manufacturers exert significant influence on material specifications, dictating purity standards and qualification processes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's strategic position, bolstered by significant foundry investments, drives the concentration of semiconductor material supply chains. This shift underpins the regional demand for advanced fabrication materials. Foundries in specific geographies are accelerating material consumption for high-performance computing and AI accelerators.
Taiwan
Leading-edge foundries in Taiwan demand advanced photoresists and specialty chemicals for sub-10nm nodes. The Taiwan Industrial Innovation Act provides tax incentives for R&D and manufacturing. Hsinchu Science Park remains a critical hub for material innovation and production, supporting companies like TSMC.
United States
The United States sees material demand surge from new fab construction projects, especially for silicon wafers. The US CHIPS Act incentivizes domestic semiconductor manufacturing and material supply. Arizona is rapidly becoming a key center for advanced chip production, attracting major material suppliers.
Germany
Germany's growing semiconductor ecosystem, supported by the EU Chips Act, stimulates demand for bulk gases and specialty chemicals. This policy fosters local production capabilities for critical materials. Saxony's 'Silicon Saxony' cluster in Dresden is expanding its material supply infrastructure.
South Korea
South Korea's focus on advanced memory chips and complex SoCs requires high-purity materials for deposition and etching. The national semiconductor strategy supports R&D into novel materials and processes. Gyeonggi Province, home to Samsung and SK Hynix, leads material qualification efforts.
China
China's drive for self-sufficiency in semiconductor manufacturing increases demand for domestic material sourcing. MEE directives on volatile organic compounds (VOCs) influence material reformulation efforts. The Yangtze River Delta region, including Shanghai, is developing local material supply chains.
Semiconductor Fabrication Material Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments in the semiconductor fabrication material market. The industry structure shows consolidation among leading material suppliers for advanced nodes, particularly for high-purity chemicals and wafers. Strategic archetypes include integrated chemical giants, specialized wafer producers, and gas suppliers. Companies are engaging in sustained capacity expansion and strategic partnerships to secure supply chains and accelerate material qualification for next-generation devices.
Leading material specialists, including Shin-Etsu Chemical Co., Ltd., exemplify the importance of dominant positions in core segments such as silicon wafers. DuPont de Nemours, Inc. represents advanced photoresist innovation, critical for enabling extreme ultraviolet (EUV) lithography at sub-10nm nodes. Air Liquide S.A. anchors the high-purity specialty gases segment, essential for precise deposition and etching processes in advanced fabs. These firms collectively demonstrate the sector's focus on stringent purity standards and high-performance material development. Their extensive R&D capabilities and long-standing relationships with leading foundries underscore the significant entry barriers in this capital-intensive market. Such companies continuously invest in meeting next-generation architectural demands.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| Merck KGaA |
| DuPont de Nemours, Inc. |
| Siltronic AG |
| Air Liquide S.A. |
| JSR Corporation |
| Toppan Printing Co., Ltd. |
| Honeywell International, Inc. |
| BASF SE |
| Others |
Cost & Logistics Intelligence
High-purity chemical engineers in Taiwan drive premium pricing for advanced materials, reflecting specialized expertise and limited supply. This concentrated talent pool directly influences the pricing tiers for critical fabrication materials across the industry.
Pricing Analysis
Lead-time-driven pricing structures create a premium for immediate availability of advanced materials, while spot inventory for mature nodes often receives discounts. The dominant pricing structure involves contract-based long-term offtake agreements for leading-edge materials. Price differentiation stems from extreme purity grades, often measured in parts-per-quadrillion, and the rigorous qualification status with specific foundries. Pricing softness reflects increased competition in mature process nodes for commodity chemicals. Leading-edge foundries demonstrate the least price sensitivity for their highly critical, qualified materials, whereas fabless companies are more price-sensitive for non-critical inputs.
Supply Chain Analysis
Logistics and freight costs significantly impact the final price of semiconductor fabrication materials, especially for high-purity gases requiring specialized transport. Geographic supply concentration centers in Taiwan, South Korea, and Japan for many critical materials. The industry draws from raw material dependencies including high-purity quartz for crucibles, rare gases like neon and xenon, and silicon ingots. Single-source vulnerability for highly specialized chemicals represents a structural supply chain risk. Distribution runs through direct supply relationships with major foundries, complemented by specialized distributors serving smaller fabrication facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The semiconductor fabrication material market is a vertical-integration race, with foundries pursuing backward integration into specialty gas production to secure critical inputs.
For Market Incumbents:
Extend R&D investments into developing non-PFAS alternatives, mitigating the threat of broad environmental regulatory scrutiny. Secure long-term contracts with leading foundries to solidify market share and ensure consistent demand for advanced materials. Expand capacity for silicon wafer production in strategic regions like Arizona to support new fab construction. Innovate in metrology and analytics to meet sub-3nm purity requirements.
For New Entrants and Emerging Players:
Launch via joint development agreements with research institutes to accelerate material qualification for next-generation processes. Target white-space opportunities in green chemistry solutions, focusing on biodegradable photoresists and solvents. The most penetrable segment lies within emerging fab ecosystems in geographies like India and Germany. Develop advanced packaging materials that enable heterogeneous integration for chiplet-based designs.
For Investors and Strategic Acquirers:
Re-rating potential sits with specialized material developers offering proprietary ALD precursors, given the accelerating demand for Gate-All-Around architectures. The long-term viability of this market extends throughout the next decade, driven by persistent innovation in chip manufacturing. Identify acquisition targets with strong intellectual property in novel materials for advanced photolithography. Successful qualification of novel materials for sub-2nm nodes serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Secures supply for growing fab investments in new geographies. |
| Green Chemistry R&D | Addresses environmental regulations and foundry sustainability goals. |
| Joint Development Programs | Accelerates material qualification for advanced process nodes. |
| Advanced Packaging Material Development | Enables heterogeneous integration and chiplet designs. |
| Digital Twin Integration | Optimizes material performance prediction and reduces qualification cycles. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this market analysis. Primary research involved interviews with foundry process engineers, material R&D directors, supply chain managers, and fabless design leads. This approach combined qualitative insights from industry stakeholders with quantitative validation from various secondary sources. Bottom-up and top-down triangulation ensured data accuracy across the market landscape.
The data-stream reconciliation process integrated supply-side capacity assessments with demand-side technology roadmaps to build a robust analytical framework. This framework modeled segmentation dimensions including material type, technology, application, end-user, and regional fab capacity. Compound annual growth rates were derived from historical growth patterns and projected technological advancements across the analysis window. Key forecast inputs included EUV lithography adoption rates and advanced node transition timelines.
Geopolitical tensions affecting rare gas supply, rapid shifts in lithography paradigms, and new environmental regulations are the dominant revision risks for market projections. Forecasts reflect assumptions about technological progression and market dynamics over the projection horizon. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Sapphire Ingot Market
Semiconductor Material
Fullerene Market
Semiconductor Material
North America Silicone Market
Semiconductor Material
Semiconductor Grade Neon Gas Market
Semiconductor Material
Acetylene Black Market
Semiconductor Material
Methyl Phenyl Silicone Resin Market
Semiconductor Material
Dysprosium Titanate Market
Semiconductor Material
Semiconductor Film Market
Semiconductor Material
PV Module Encapsulant Film Market
Semiconductor Material
Metallurgical Grade Silicon Market
Semiconductor Material
Dicing Die Attach Film Market
Semiconductor Material
India Liquid Silicon Rubber Market
Semiconductor Material
Semiconductor Materials Market
Semiconductor Material
Encapsulant Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
Global Thermal Paste Market