
 Polysilicon Market | 2026-2036
Polysilicon Market Size, Share, and Industry Trends Forecast 2026-2036
Polysilicon Market Intelligence
Semiconductor-grade polysilicon is redrawing competitive boundaries as chipmakers demand impurity levels below one part per billion. Tongwei leverages integrated salt-to-silicon operations to control feedstock quality. Wacker Chemie anchors European supply through decades of electronic-grade specialization. Daqo New Energy competes on manufacturing scale in Xinjiang.
Polysilicon is hyper-pure silicon produced via the Siemens process or fluidized bed reactor, with purity ranging from six nines for solar applications to eleven nines for semiconductor wafers. Solar-grade material dominates volume flows, yet electronic-grade commands outsized margins due to qualification barriers. Semiconductor-grade supply is tightening as advanced node fabrication expands. Photovoltaic-grade demand from solar panel manufacturers absorbs the bulk of new capacity additions. Purity-grade stratification is deepening, with ultra-high-purity lots carrying significant price premiums.
China's MIIT enforces GB standards on polysilicon energy consumption, while the EU's CSRD requires supply-chain carbon disclosure for imported solar components. The EPA regulates chlorosilane emissions at US production sites. Stakeholders must track how embodied-carbon regulations reshape sourcing geography and which purity tiers capture value as end-use requirements diverge.
Market Dynamics
The polysilicon market is bifurcating sharply between solar-grade commodity flows and semiconductor-grade premium supply, with purity-grade stratification now determining competitive positioning and margin capture.
Growth Catalysts
- China's dual carbon goals:National decarbonization mandates are accelerating photovoltaic deployment and tightening embodied-carbon standards across solar supply chains.
- Semiconductor fabrication expansion:Advanced node chip production is tightening electronic-grade polysilicon supply as impurity requirements fall below one part per billion.
- Fluidized bed reactor technology:Lower-energy silicon production methods are reducing unit costs and expanding capacity feasibility for new entrants.
Market Restraints
- Xinjiang supply concentration:Over 40% of global polysilicon production sits in a single Chinese province, creating geopolitical and logistics vulnerability.
- Trichlorosilane price volatility:Key chlorosilane feedstock costs swing with natural gas and chlorine markets, compressing margins unpredictably.
- Semiconductor-grade qualification barriers:Multi-year certification timelines with chipmakers lock out new suppliers regardless of technical capability.
Strategic Opportunities
- EU Green Deal carbon border adjustments:Embodied-carbon disclosure requirements for imported solar components favor low-carbon European production.
- India's PLI scheme for solar manufacturing:Production-linked incentives are attracting polysilicon investments to diversify Asia-Pacific supply geography.
- Topcon and heterojunction cell architectures:Next-generation solar technologies demand higher-purity feedstock, upgrading value capture for quality-tier suppliers.
Industry Challenges
- Electronic-grade process engineering talent:Deep expertise in eleven-nines purity control resides with a handful of specialists, constraining capacity expansion.
- Chlorosilane emissions compliance:EPA and MEE regulations require costly abatement systems that extend project timelines and capital recovery periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polysilicon Market |
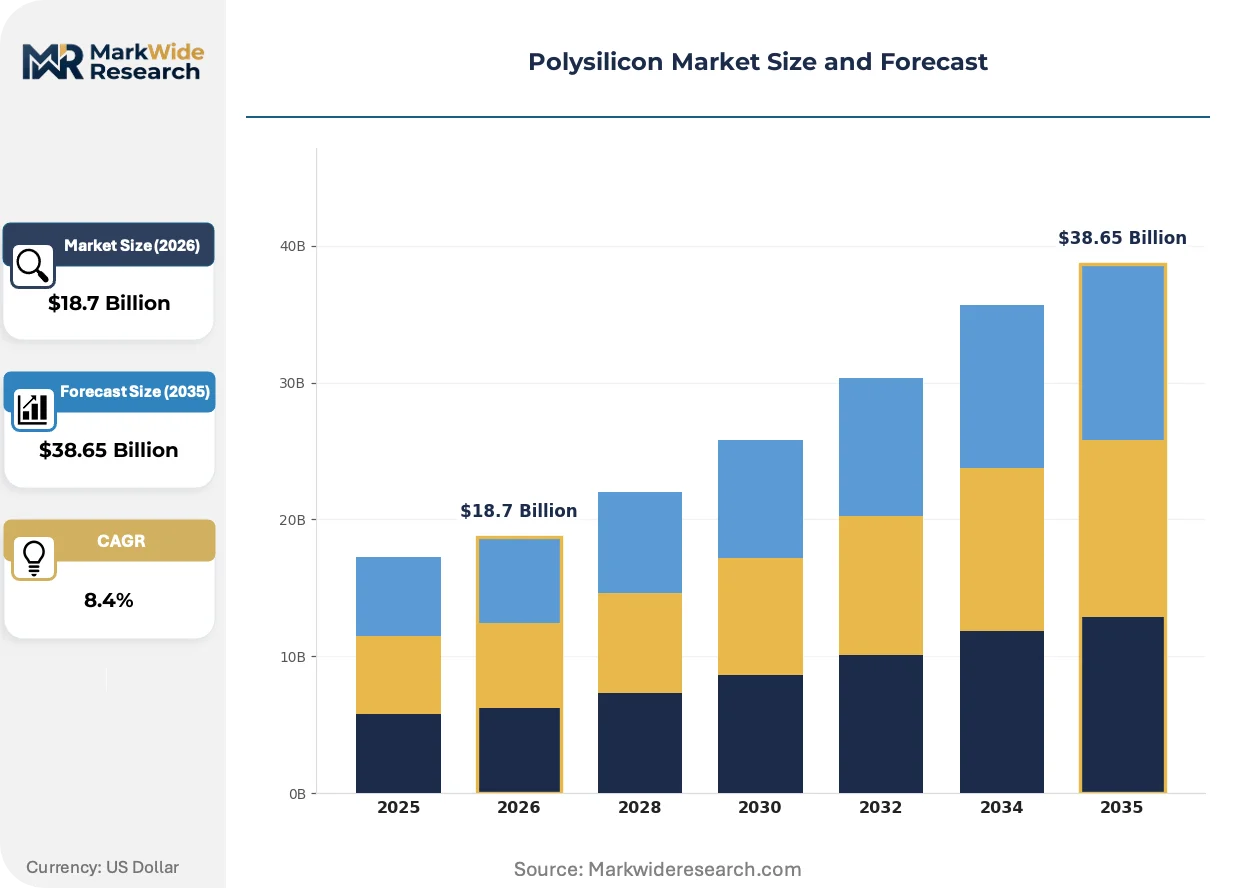
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Grade, Electronic Grade, Photovoltaic Grade, Semiconductor Grade End User: Solar Panel Manufacturers, Electronics Industry, Semiconductor Manufacturers, Research Institutions Application: Solar Energy Generation, Electronic Devices, Industrial Applications, Laboratory Use Purity Grade: Low Purity, Standard Purity, High Purity, Ultra High Purity |
| Companies Covered | Xinte Energy, Wacker Chemie, Tongwei, OCI Company, Hongyuan Energy, GCL Technology, Qinghai Lihao, REC Silicon, Daqo New Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polysilicon Market Strategic Shifts & Innovations
Polysilicon production technology is fragmenting across purity tiers, with process innovation now tightly coupled to end-use qualification requirements rather than generic scale economies.
Monosilane-based deposition is decomposing traditional Siemens process dominance in semiconductor-grade supply. Memory and logic chipmakers in Taiwan and South Korea are qualifying monosilane feedstock for sub-7nm fabrication. This technology shift is compressing the addressable market for conventional trichlorosilane routes in the highest-margin purity segment.
The EU's CSRD mandates granular supply-chain carbon disclosure for imported solar components starting with large enterprises. European module assemblers must now trace embodied emissions back to polysilicon ingot production. Low-carbon producers in Norway and Germany are capturing sourcing preference as a result.
Long-term offtake contracting is displacing spot market procurement for photovoltaic-grade material. Integrated wafer-to-cell producers in China are locking in five-to-ten-year supply agreements directly with polysilicon manufacturers. This pattern is most visible in the Xinjiang and Inner Mongolia production clusters where captive demand absorbs new capacity before it reaches open markets.
Polysilicon Market Segmentation
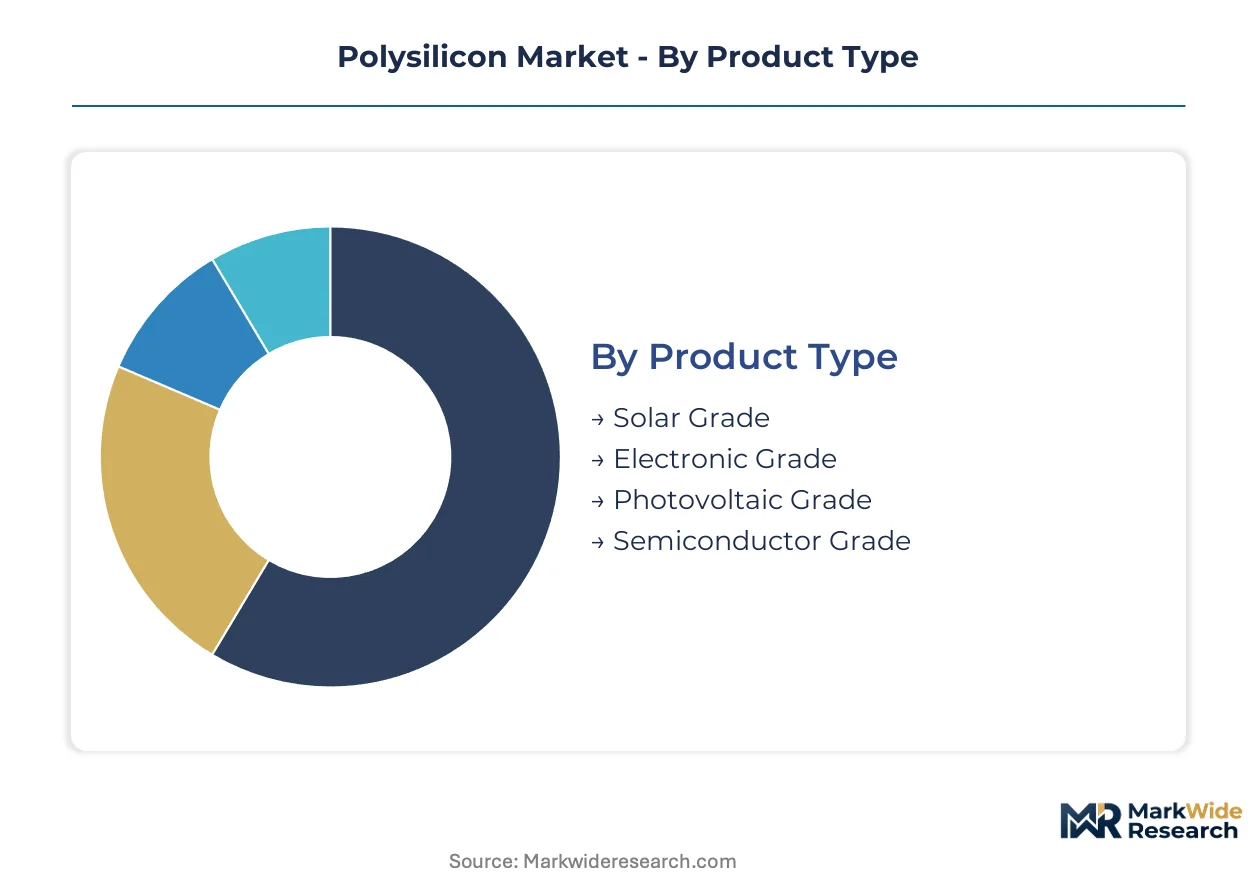
Purity-grade stratification and end-use qualification requirements fragment the polysilicon market into distinct commercial tiers. Channel flows diverge sharply between commodity photovoltaic procurement and certified semiconductor supply chains.
Product Type:
Channel routing splits between spot-market commodity flows and qualified premium supply, with purity thresholds determining contract structures and buyer relationships.
- Semiconductor Grade:Eleven-nines purity silicon for advanced node fabrication demands impurity control below one part per billion. Taiwan Semiconductor Manufacturing Company and Samsung Foundry lock in multi-year offtake agreements with qualified suppliers, creating insurmountable barriers for new entrants regardless of technical capability.
- Solar Grade:Six-nines purity material dominates volume production through the Siemens process and fluidized bed reactor routes. Chinese integrated wafer-to-cell producers in Xinjiang and Inner Mongolia absorb the bulk of new capacity through long-term contracts before material reaches open markets.
- Electronic Grade:Intermediate purity tier serves discrete semiconductor and power electronics applications with less stringent qualification timelines than sub-7nm logic fabrication.
- Photovoltaic Grade:Equivalent purity specifications to solar grade but often differentiated by carbon footprint certification for EU Green Deal compliance.
By volume, Solar Grade leads. By growth pace, Semiconductor Grade is climbing the fastest.
End User:
Customer concentration varies dramatically across purity tiers, with procurement power consolidating among integrated manufacturers while research buyers remain fragmented.
- Solar Panel Manufacturers:Tier-one module producers in China, Vietnam, and Malaysia drive procurement volume through five-to-ten-year offtake agreements. JinkoSolar and LONGi Solar negotiate directly with polysilicon producers, compressing distributor margins.
- Semiconductor Manufacturers:Memory and logic chipmakers in Hsinchu, Yongin, and Pyeongtaek qualify suppliers through 18-to-36-month certification cycles. SK Hynix and Micron Technology prioritize monosilane-based deposition routes for sub-7nm nodes.
- Electronics Industry:Discrete component and power semiconductor producers purchase through chemical distributors with shorter qualification cycles than advanced logic fabrication.
- Research Institutions:Fragmented demand from national laboratories and university cleanrooms purchases small lots through specialized chemical suppliers at significant premiums.
By contract value, Semiconductor Manufacturers lead. By volume expansion, Solar Panel Manufacturers are gaining share fastest.
Application:
Application-specific purity requirements create parallel supply chains with minimal crossover between solar commodity flows and electronic-grade certification tracks.
- Solar Energy Generation:Photovoltaic deployment absorbs over three-quarters of global polysilicon output. China's dual carbon goals and the EU Green Deal tighten embodied-carbon disclosure requirements, favoring low-carbon production in Norway and Germany.
- Electronic Devices:Smartphone, computing, and automotive semiconductor demand concentrates among Taiwan and South Korea fabrication complexes. Advanced packaging technologies are extending electronic-grade requirements into previously standard-purity applications.
- Industrial Applications:Silicones, aluminum alloys, and chemical feedstocks utilize lower-purity material with minimal qualification barriers and price-sensitive procurement.
- Laboratory Use:Reference materials and research-grade silicon command extreme premiums through specialized distributors serving national metrology institutes.
By installed capacity, Solar Energy Generation leads. By margin capture, Electronic Devices shows the steepest expansion trajectory.
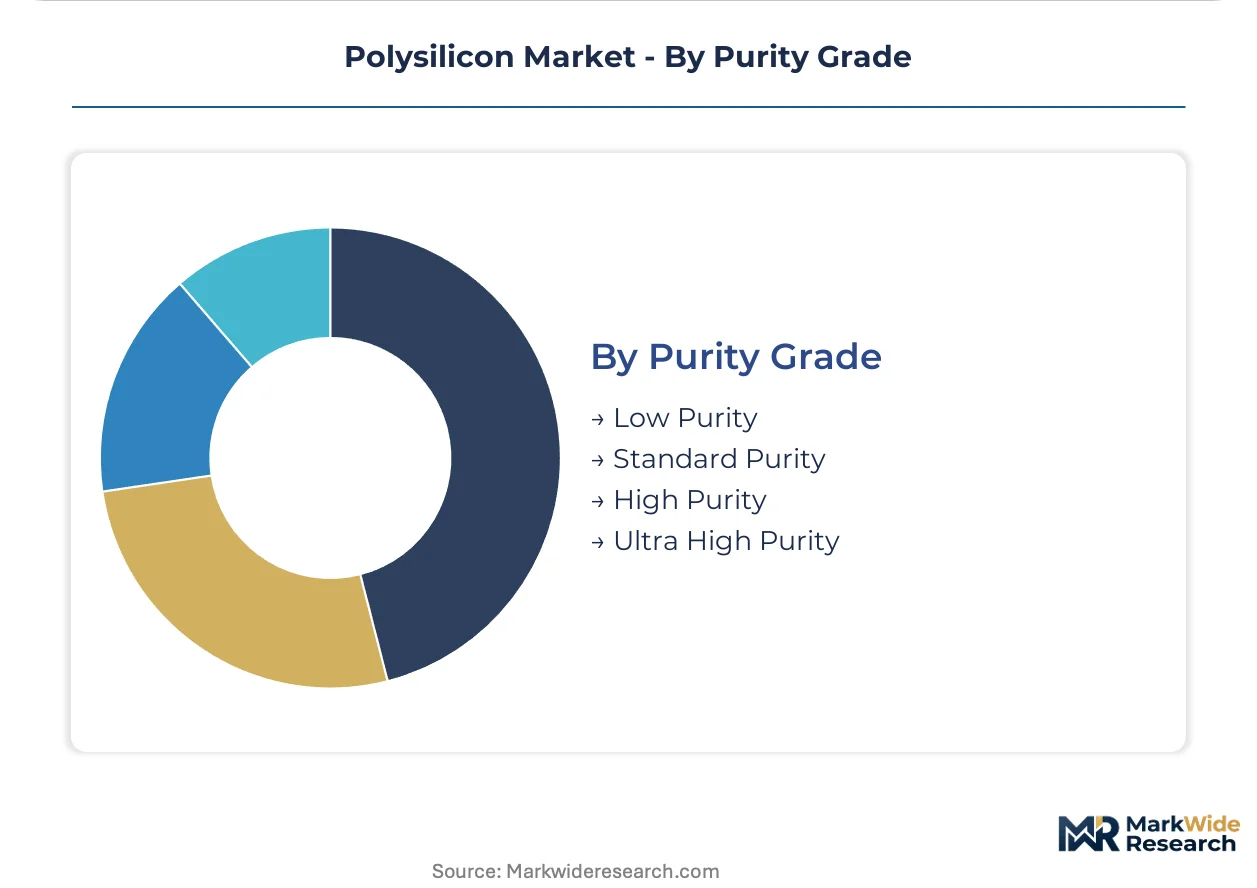
Purity Grade:
Cost-tier stratification deepens as end-use specifications diverge, with each purity increment commanding exponential price premiums and distinct supplier bases.
- Ultra High Purity:Eleven-nines silicon for EUV lithography and advanced node fabrication requires monosilane deposition and specialized handling infrastructure. ASML's lithography systems demand material with metallic impurity levels below 0.1 parts per billion.
- High Purity:Nine-to-ten-nines material serves memory fabrication and power electronics with qualification barriers lower than logic chip production but significant scale economies favoring established suppliers.
- Standard Purity:Six-to-eight-nines silicon satisfies conventional solar cell and discrete semiconductor applications with commodity pricing and minimal differentiation.
- Low Purity:Metallurgical-grade and upgraded metallurgical-grade material feeds industrial silicones and aluminum alloying with price sensitivity dominating supplier selection.
By revenue concentration, Ultra High Purity leads. By volume growth, Standard Purity is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances are tightening as polysilicon trade flows reconfigure around embodied-carbon regulations and semiconductor supply chain security. China's net export position is softening as domestic photovoltaic deployment accelerates. European and Indian import demand is diversifying sourcing away from single-origin dependency.
China
Xinjiang and Inner Mongolia host over 40% of global polysilicon capacity, feeding integrated wafer-to-cell producers through long-term offtake agreements. MIIT enforces GB standards on energy consumption intensity, pressuring high-carbon production clusters. Tongwei and Daqo New Energy anchor manufacturing in Sichuan's hydropower-rich corridor, capturing low-carbon cost advantages.
Germany
Wacker Chemie's Burghausen complex supplies electronic-grade material to European semiconductor fabricators with decades of qualification history. The EU Green Deal's carbon border adjustment mechanism favors domestic production with verified low-emission credentials. Bavaria's chemical processing infrastructure supports chlorosilane purification at scale unmatched elsewhere in Europe.
United States
REC Silicon's Moses Lake facility represents surviving domestic polysilicon capacity after trade enforcement actions reshaped the supplier base. The EPA regulates chlorosilane emissions at production sites, extending project timelines for capacity restarts. The Pacific Northwest's hydropower access attracts potential greenfield investments for solar-grade material serving domestic module assembly.
South Korea
SK Hynix and Samsung Foundry drive semiconductor-grade demand through advanced node fabrication in Yongin and Pyeongtaek. OCI Company supplies electronic-grade feedstock from domestic and Malaysian production positions. The MFDS maintains chemical purity standards for semiconductor materials, creating qualification barriers for non-established suppliers.
India
The PLI scheme for solar manufacturing is attracting polysilicon investment proposals to Gujarat and Tamil Nadu, though operational capacity remains minimal. BIS certification requirements for solar component imports are tightening quality thresholds. Reliance Industries and Adani Group are pursuing backward integration into polysilicon to supply captive wafer production.
Polysilicon Market Key Industry Players
Listed leaders compete with private specialists across purity-grade positioning and geographic footprint. The market structures around three tiers: integrated energy conglomerates with salt-to-silicon control, chemical specialists with electronic-grade certification history, and regional scale players serving commodity photovoltaic demand. Strategic moves concentrate on long-term offtake contracting and carbon footprint verification for EU market access.
Within the integrated conglomerate tier, Tongwei and Xinte Energy exemplify backward control over feedstock quality and energy supply. Wacker Chemie occupies a distinctive position as the surviving Western electronic-grade specialist with decades of semiconductor customer relationships. Daqo New Energy represents scale-driven manufacturing concentration in China's low-cost electricity corridors. These three anchors illustrate how purity-grade specialization and energy cost positioning determine competitive viability.
| Leading Market Players |
|---|
| Xinte Energy |
| Wacker Chemie |
| Tongwei |
| OCI Company |
| Hongyuan Energy |
| GCL Technology |
| Qinghai Lihao |
| REC Silicon |
| Daqo New Energy |
| Others |
Cost & Logistics Intelligence
Sixty-day polysilicon inventory cycles at Chinese integrated producers signal supply-chain tightness that amplifies pricing power for certified electronic-grade suppliers. Long-term offtake contracting now dominates procurement, compressing spot-market liquidity and embedding cost structures into multi-year agreements.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across purity tiers. Semiconductor-grade material commands premiums based on eleven-nines certification and monosilane deposition qualification, while photovoltaic-grade tracks volume scale and carbon footprint verification under EU CSRD rules. Pricing pressure stems from Xinjiang production concentration and trichlorosilane feedstock volatility. Solar panel manufacturers exhibit highest price sensitivity; memory chipmakers show lowest sensitivity due to qualification lock-in.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for European module assemblers sourcing from Xinjiang and Inner Mongolia. Production concentrates in China, Malaysia, and Germany, with raw material dependencies on metallurgical-grade silicon, chlorine, and high-purity hydrogen. Single-source vulnerability pervades the semiconductor-grade tier where Wacker Chemie and OCI Company hold decades of customer relationships. Distribution runs through direct manufacturer-to-OEM contracts, bypassing traditional chemical distributors for volume photovoltaic flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polysilicon market sits in a cyclical recovery phase driven by photovoltaic deployment acceleration under China's dual carbon goals. Inventory destocking has concluded across solar supply chains, resetting contract negotiation leverage toward producers.
For Market Incumbents: Shield electronic-grade margin pools through accelerated monosilane deposition certification with Taiwan and South Korea logic chipmakers. Deepen backward integration into chlorosilane production to neutralize trichlorosilane price volatility. Secure carbon footprint verification under EU CSRD before 2025 disclosure mandates tighten sourcing preferences.
For New Entrants and Emerging Players: Anchor in India's PLI scheme for solar manufacturing, where operational polysilicon capacity remains minimal and Reliance Industries' backward integration creates partnership openings. Target photovoltaic-grade supply to Gujarat-based wafer producers seeking domestic sourcing alternatives to Xinjiang dependency. Lead with low-carbon production credentials verified under BIS certification pathways.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated energy conglomerates seeking to monetize non-core polysilicon divisions. Long-term viability hinges on purity-grade positioning and captive energy access across the next decade. Monitor fluidized bed reactor technology adoption rates as the inflection signal separating cost-competitive scale players from stranded Siemens-process capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane | Secures feedstock cost control against natural gas volatility for Tongwei and Daqo. |
| Monosilane Deposition Certification | Unlocks sub-7nm logic chip supply contracts with TSMC and Samsung Foundry. |
| EU CSRD Carbon Verification | Enables market access for Wacker Chemie under Green Deal border adjustments. |
| Long-term Supply Agreement | Locks in five-to-ten-year offtake with LONGi Solar and JinkoSolar before capacity absorption. |
| Fluidized Bed Reactor Scale-Up | Reduces unit energy costs for new entrants competing against Xinjiang's low-power tariffs. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs and secondary validation protocols. Polysilicon procurement directors at tier-one solar module producers, semiconductor materials engineers at foundry operators, and plant managers at chlorosilane purification facilities contributed operational data. Secondary sources included customs trade databases tracking silicon tetrachloride flows, MIIT energy consumption disclosures, SEC filings from listed producers, and EU ETS carbon intensity records. Bottom-up capacity modeling and top-down demand aggregation were triangulated against disclosed production volumes.
Across the analysis window, forecasts employed segmented modeling across purity grade, end-use application, and regional production hub dimensions. CAGRs were derived from polynomial trend fitting against historical capacity utilization and forward project pipelines. Key inputs included photovoltaic deployment trajectories under national renewable targets, semiconductor wafer start forecasts from foundry capex announcements, and embodied-carbon regulatory phase-in schedules.
Material uncertainties — tariff enforcement actions, Xinjiang forced labor disclosure requirements, and monosilane technology substitution rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about qualification timeline continuity and energy cost structures. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Quartz Crucible Market
Semiconductor Material
PP Capacitor Films Market
Semiconductor Material
Europe Silicone Market
Semiconductor Material
Dicing Die Attach Film Market
Semiconductor Material
Fullerene Market
Semiconductor Material
Electronic Assembly Materials Market
Semiconductor Material
Global Polybutylene Terephthalate (PBT) Market
Semiconductor Material
Electroceramics Market
Semiconductor Material
Asia Pacific Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Neodymium Sputtering Target Market
Semiconductor Material
Gallium Trichloride Market
Semiconductor Material
Barium Titanate Market
Semiconductor Material
DCB and AMB Substrate Market
Semiconductor Material
Thermoelectric Materials Market
Semiconductor Material
Global Magnesium Oxide Nanopowder Market
Semiconductor Material
Titanium Diboride Market