
 Liquid Crystal on Silicon Market | 2026-2036
Liquid Crystal on Silicon Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Crystal on Silicon Market Intelligence
The divergence between high-resolution panels for professional visualization and lower-cost modules for consumer devices is restructuring the Liquid Crystal on Silicon Market. Sony Corporation specializes in high-pixel-density panels for its own electronics ecosystems. Himax Technologies leverages its fabless model to supply a broad range of application-specific solutions. HOLOEYE Photonics AG focuses on spatial light modulators for scientific and research institutions, a high-margin niche.
Liquid Crystal on Silicon is a microdisplay technology that combines a liquid crystal layer with a reflective silicon backplane. The underlying CMOS circuitry controls individual pixels to modulate light, enabling high-resolution displays. Reflective LCoS technology dominates due to superior brightness and contrast ratios. While 3D projection remains a stable application, head-mounted displays for augmented and virtual reality represent the fastest-growing segment.
Component and device compliance is governed by a web of regional electronics standards. These include CE marking in Europe for safety and environmental performance and FCC regulations in the United States for electromagnetic interference. In China, national GB standards dictate market access for electronic displays. Future success for manufacturers will depend on navigating the choice between high-volume consumer electronics supply chains and specialized, high-margin industrial applications.
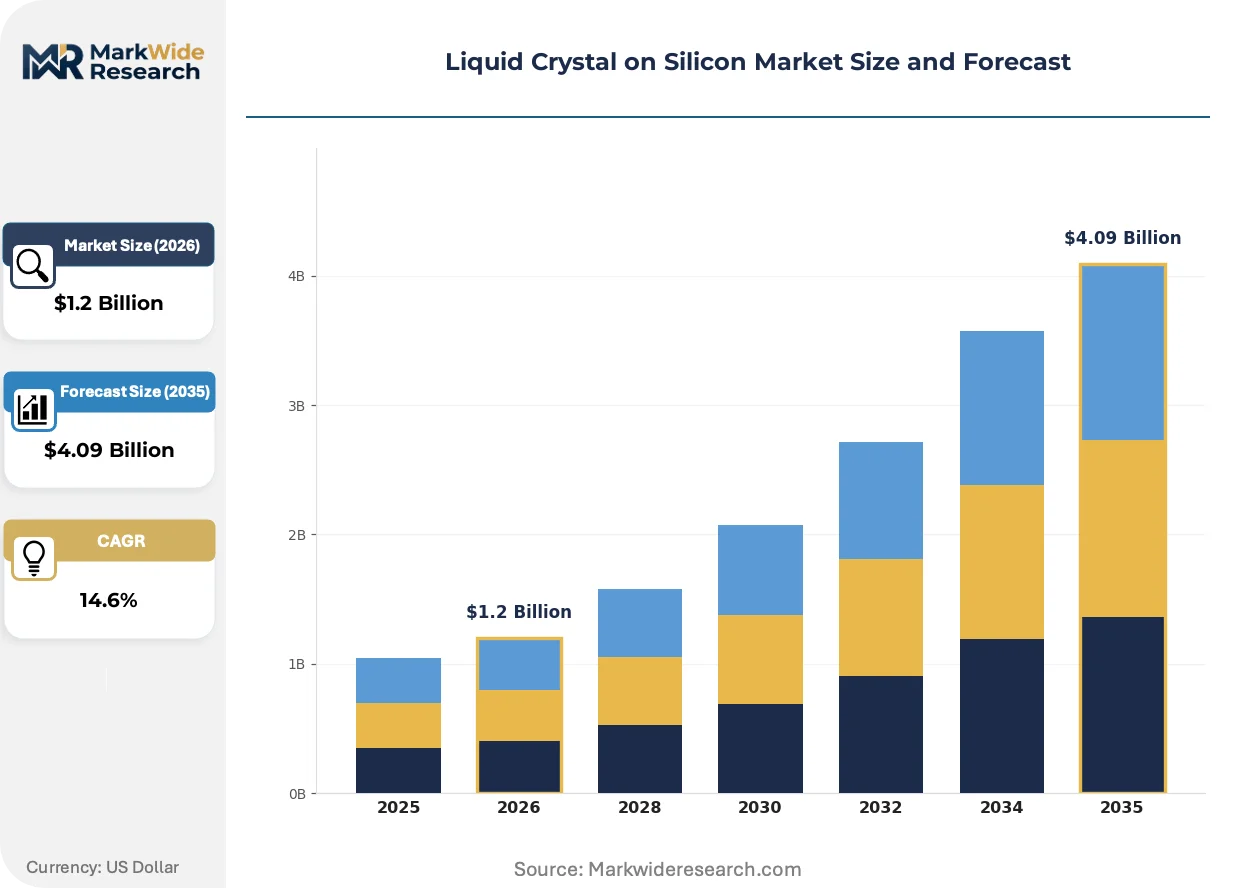
Market Dynamics
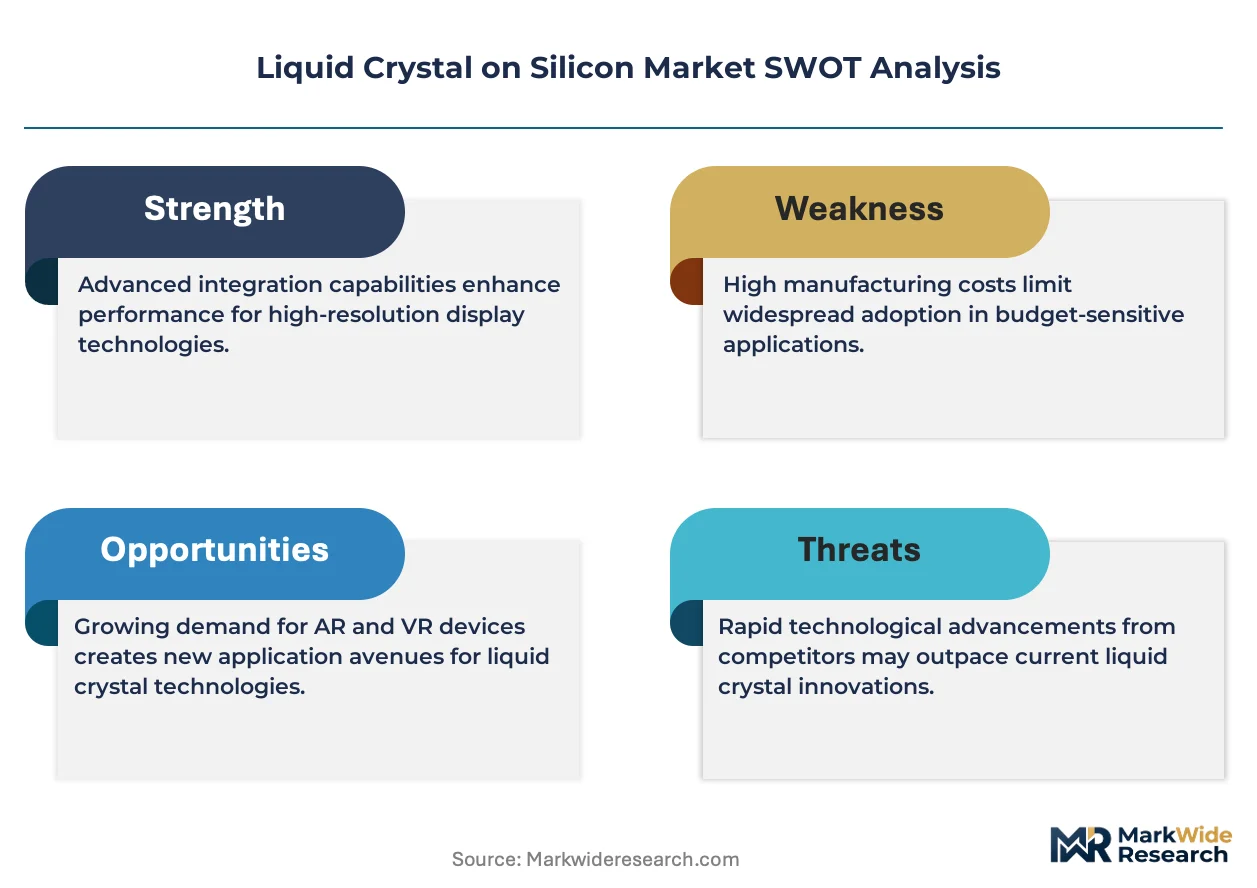
The fundamental dynamic in the Liquid Crystal on Silicon market is the strategic tension between serving high-volume, cost-sensitive consumer electronics and supplying high-margin, specialized industrial and scientific applications. This divergence dictates technology roadmaps, supply chain structures, and competitive positioning.
Growth Catalysts
- Miniaturization of Optics:The ongoing trend toward smaller and lighter optical components is a primary catalyst, enabling LCoS integration into compact devices like smart glasses and portable projectors where space and weight are critical constraints.
- Augmented Reality Adoption:Demand for high-resolution, power-efficient microdisplays for head-mounted displays (HMDs) in both consumer and enterprise augmented reality applications is expanding the addressable market for LCoS technology.
- National Industrial Policies:Government initiatives in countries like China and South Korea, aimed at fostering domestic high-technology manufacturing and semiconductor independence, provide direct and indirect support for LCoS producers through subsidies and favorable policies.
Market Restraints
- High Fabrication Costs:The manufacturing of the underlying CMOS silicon backplane is a capital-intensive process requiring advanced semiconductor foundry access, creating a high barrier to entry and constraining price reductions for high-resolution panels.
- Alternative Technology Competition:LCoS faces substitution threats from other microdisplay technologies, particularly from Micro-OLED for its superior contrast and from emerging Micro-LED for its potential in high-brightness applications.
- Brightness and Efficiency Trade-offs:A persistent technical restraint is the inherent trade-off between brightness, power efficiency, and heat dissipation, which can limit performance in daylight-readable applications or require complex thermal management solutions.
Strategic Opportunities
- Automotive Head-Up Displays:The integration of LCoS technology into augmented reality head-up displays (AR-HUDs) for vehicles presents a significant opportunity, offering a large-format, high-resolution display for projecting navigation and safety information.
- Advanced Photonic Systems:Opportunities exist in niche, high-value applications such as holographic data storage, optical computing, and dynamic beam steering for LiDAR systems, leveraging the phase modulation capabilities of specialized LCoS devices.
- Scientific and Medical Imaging:The market for spatial light modulators (SLMs) in scientific research, microscopy, and ophthalmology offers a high-margin opportunity for customized LCoS solutions that require precise light control.
Industry Challenges
- Regulatory Compliance Complexity:Manufacturers face the operational challenge of navigating a fragmented landscape of regional electronics standards, including CE marking in Europe, FCC rules in the US, and GB standards in China, increasing testing costs and time-to-market.
- Silicon Wafer Supply Chain:Dependence on a concentrated global semiconductor industry for high-quality silicon wafers creates supply chain risks, including price volatility and potential allocation constraints during periods of high demand from other electronics sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Crystal on Silicon Market |
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $4.09 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reflective LCoS, Transmissive LCoS, Hybrid LCoS, Integrated LCoS Technology: Phase Modulation, Amplitude Modulation, Polarization Control, Beam Steering Application: 3D Projection, Head-Mounted Displays, Optical Communications, Adaptive Optics End User: Defense & Aerospace, Consumer Electronics, Telecommunications, Research Institutions |
| Companies Covered | Himax Technologies, Sony Corporation, JVC Kenwood Corporation, 3M Company, Canon Inc., HOLOEYE Photonics AG, OmniVision Technologies, Hamamatsu Photonics, Syndiant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Crystal on Silicon Market Strategic Shifts & Innovations
Technological evolution is shifting the focus from LCoS as a simple display component to its role as an enabling platform for integrated photonic systems. This change is redefining product capabilities and opening adjacent markets beyond conventional projection and near-eye displays.
Phase-only LCoS, also known as a spatial light modulator (SLM), functions by precisely controlling the phase of light rather than just its intensity. Research institutions and developers of next-generation optical systems are rapidly adopting these components. This adoption is decentralizing the technology's role from a pure display device into a core engine for computational optics and structured illumination.
China's mandatory GB standards for electronic displays dictate stringent requirements for performance, safety, and energy efficiency. Compliance is a prerequisite for market access, directly impacting product design and manufacturing processes for any company selling into the vast Chinese consumer market. This forces global manufacturers to either create market-specific product versions or engineer their entire portfolio to meet these demanding Chinese regulations.
A clear behavioral shift is visible as equipment manufacturers in the AR/VR sector increasingly source complete optical engines instead of discrete LCoS chips. This preference for pre-integrated modules, which combine the LCoS panel with illumination and projection optics, offloads complex optical integration and calibration from the end-product assembler. The trend is most pronounced within consumer electronics supply chains centered in Taiwan and South Korea.
Liquid Crystal on Silicon Market Segmentation
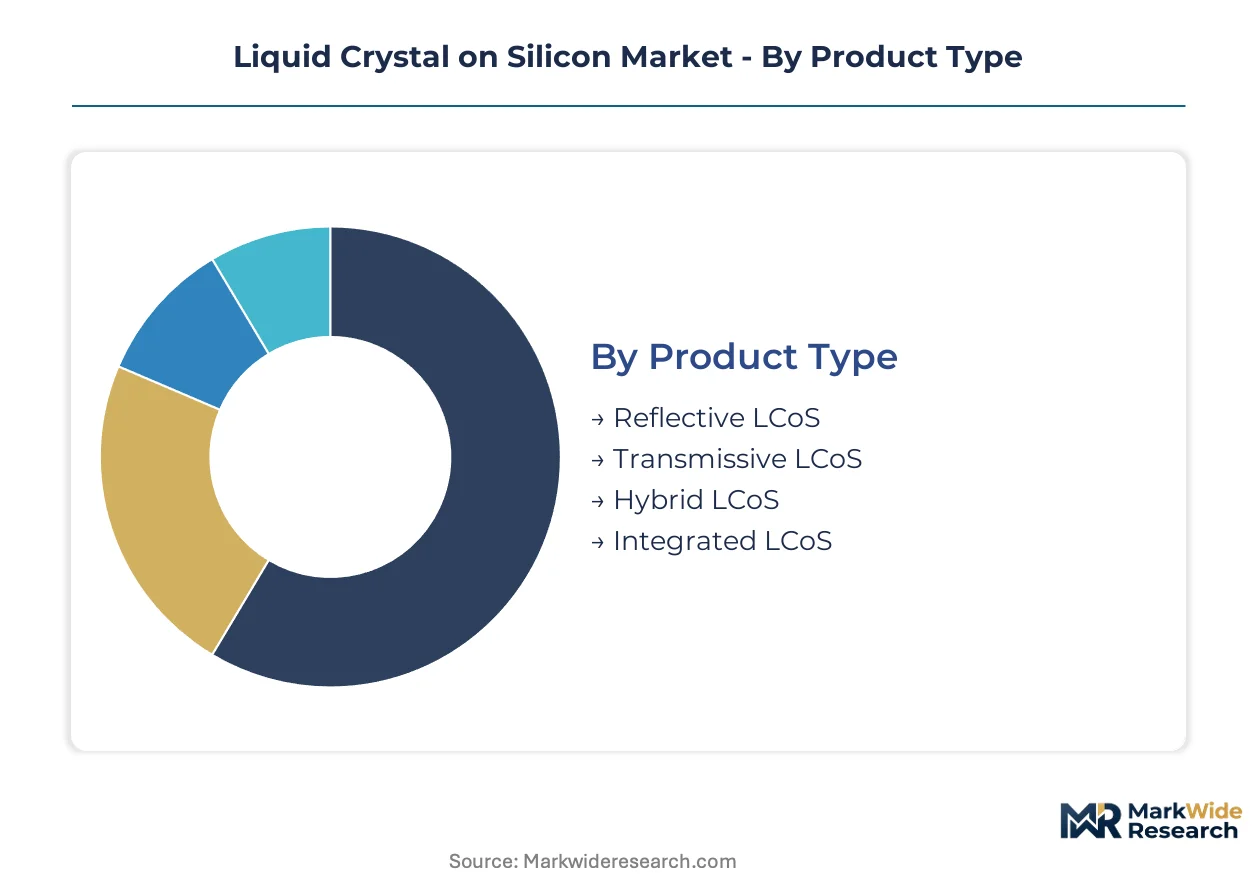
The Liquid Crystal on Silicon market segments across product type, technology, application, and end user. Understanding these distinctions helps illuminate the varied investment profiles and operational demands across the industry. Each segment presents unique technical requirements and market dynamics, influencing supply chain strategies.
Product Type:
Segments in product type reflect differing capital expenditure levels for manufacturing, with advanced reflective and integrated designs requiring substantial foundry investments.
- Reflective LCoS:This technology utilizes a reflective silicon backplane to modulate light, offering superior brightness and contrast ratios compared to other LCoS variants. Demand concentrates in high-performance augmented reality headsets, particularly in consumer electronics manufacturing centers in China.
- Transmissive LCoS:These panels allow light to pass through the liquid crystal layer, often employed in applications where a compact form factor is paramount. Demand for transmissive LCoS is notable in specialized micro-projectors and compact display engines.
- Hybrid LCoS:Hybrid designs combine elements of both reflective and transmissive approaches, seeking to balance performance characteristics for specific niche applications.
- Integrated LCoS:Integrated LCoS solutions combine the microdisplay with other optical components into a single module, simplifying integration for device manufacturers.
Most installed capacity flows through Reflective LCoS. Expansion is steepest in Integrated LCoS.
Technology:
Technological segmentation highlights the application-specific demands placed on LCoS devices, ranging from simple light modulation to complex wavefront shaping for advanced optical systems.
- Phase Modulation:Phase-only LCoS, or spatial light modulators (SLMs), precisely controls the phase of incident light, enabling advanced applications like holographic projection and adaptive optics. Research institutions and defense applications in countries like Germany and the United States drive demand for these high-precision components.
- Amplitude Modulation:Amplitude modulation LCoS devices primarily control the intensity of light, functioning as digital mirrors for conventional display and projection systems. Consumer electronics manufacturers in South Korea utilize this technology for compact projectors.
- Polarization Control:This technology manipulates the polarization state of light, crucial for specialized optical instruments and certain types of 3D displays.
- Beam Steering:LCoS devices capable of beam steering dynamically redirect light paths without mechanical components, finding use in LiDAR and optical switching systems.
Amplitude Modulation remains the dominant technology for established display applications. Phase Modulation is rapidly gaining traction in advanced photonic systems.
Application:
Application segments delineate the volume and margin characteristics of LCoS demand, from mass-market consumer devices to specialized, high-value industrial uses.
- Head-Mounted Displays:LCoS microdisplays provide high-resolution, compact visual engines for augmented reality and virtual reality devices. Demand for these displays is expanding significantly in the consumer electronics sector, particularly for new product launches by companies in Taiwan and Japan.
- 3D Projection:This application leverages LCoS panels for digital cinema, professional simulation, and advanced visualization systems, requiring high brightness and contrast. Professional visualization markets in Europe, including Germany and France, sustain stable demand.
- Optical Communications:LCoS devices enable wavelength selective switching and optical cross-connects in fiber optic networks, supporting high-bandwidth data transmission.
- Adaptive Optics:These systems use LCoS spatial light modulators to correct wavefront distortions in telescopes, microscopes, and laser systems, enhancing image clarity.
Head-Mounted Displays represent the largest volume segment. Adaptive Optics is experiencing the most significant growth.
End User:
End user categories reflect distinct customer procurement cycles and regulatory requirements, influencing product development and market access strategies for LCoS manufacturers.
- Consumer Electronics:This segment includes smart glasses, portable projectors, and compact camera viewfinders, prioritizing cost-effectiveness, miniaturization, and power efficiency. Major consumer electronics brands in China and South Korea drive substantial volume.
- Defense & Aerospace:LCoS technology finds use in head-up displays for aircraft, thermal imaging systems, and ruggedized helmet-mounted displays, demanding extreme reliability and performance. Government procurement agencies in the United States and the United Kingdom are key purchasers.
- Telecommunications:LCoS components are vital for optical switches and network management devices, supporting the infrastructure of high-speed data networks.
- Research Institutions:Universities and corporate R&D labs utilize LCoS spatial light modulators for experiments in optics, photonics, and quantum computing.
Consumer Electronics provide consistent demand for LCoS products. Telecommunications exhibits the highest expansion rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand patterns for Liquid Crystal on Silicon technology vary significantly between major economies. China and South Korea lead in high-volume consumer electronics manufacturing, while the United States and Germany prioritize high-margin industrial and scientific applications. This regional specialization influences technology development and supply chain investments.
China
China's robust consumer electronics manufacturing base drives substantial demand for LCoS in augmented reality head-mounted displays and compact projectors. The national GB standards for electronic displays dictate stringent performance and safety requirements for market access. Shenzhen and the Yangtze River Delta serve as critical hubs for LCoS panel integration and product assembly.
South Korea
South Korea exhibits strong demand for LCoS in consumer electronics and advanced display engines, supported by significant investments in next-generation AR/VR devices. Government initiatives, aimed at fostering domestic high-technology manufacturing, provide favorable policies for LCoS producers. The Seoul Capital Area is a key center for LCoS research, development, and high-tech production.
United States
The United States market focuses on high-value LCoS applications in defense and aerospace, including head-up displays and thermal imaging systems. FCC regulations govern electromagnetic interference for electronic devices, impacting LCoS product design for commercial use. Silicon Valley and Boston remain prominent centers for advanced optics research and defense technology development.
Germany
Germany represents a strong market for LCoS spatial light modulators in scientific research, microscopy, and professional visualization systems. CE marking ensures compliance with European safety, health, and environmental protection requirements for LCoS components. Jena, known as an optics hub, and Munich, with its automotive R&D, concentrate LCoS innovation.
Japan
Japan sustains consistent demand for LCoS in head-mounted displays and advanced projection systems, driven by innovation in consumer electronics. The Ministry of Economy, Trade and Industry (METI) supports domestic high-tech manufacturing through various industrial policies. Tokyo and Osaka are significant regions for LCoS research, component manufacturing, and product integration.
Liquid Crystal on Silicon Market Key Industry Players
Top-tier vendors anchor the market through integrated manufacturing capabilities, while specialized niche players differentiate through advanced technological offerings. The market structure reflects a blend of large, diversified electronics conglomerates and focused microdisplay specialists. Strategic archetypes include integrated device manufacturers, fabless LCoS suppliers, and advanced photonic solutions providers. Competitive moves frequently involve technology licensing and strategic partnerships to expand application reach.
Integrated electronics manufacturers such as Sony Corporation exemplify the approach of developing high-pixel-density panels for internal product ecosystems. Himax Technologies, operating on a fabless model, represents a key supplier of application-specific LCoS solutions to a broad client base. Within the specialized segment, HOLOEYE Photonics AG occupies a position focused on spatial light modulators for scientific and research institutions, targeting high-margin niche applications.
| Leading Market Players |
|---|
| Himax Technologies |
| Sony Corporation |
| JVC Kenwood Corporation |
| 3M Company |
| Canon Inc. |
| HOLOEYE Photonics AG |
| OmniVision Technologies |
| Hamamatsu Photonics |
| Syndiant |
| Others |
Cost & Logistics Intelligence
Global silicon wafer pricing, influenced by semiconductor industry cycles, cascades through the Liquid Crystal on Silicon supply chain. This directly impacts manufacturing costs and the final pricing tiers for LCoS modules.
Pricing Analysis
Capacity additions in China's semiconductor foundries are reshaping price floors for entry-level LCoS panels. Pricing stratifies across premium, standard, and economy tiers, driven by pixel density and customization levels for specialized applications. High fabrication costs for advanced CMOS backplanes constrain price reductions for high-resolution LCoS. Consumer electronics manufacturers in China exhibit the highest price sensitivity, while research institutions prioritize performance over cost.
Supply Chain Analysis
China's national GB standards, mandating specific performance and safety for electronic displays, reshape sourcing strategies for LCoS components. The supply chain centers on high-quality silicon wafers primarily from Taiwan and South Korea, which are then processed into microdisplays. Dependence on this concentrated global semiconductor industry for wafers presents a structural risk of price volatility. Distribution runs through direct OEM partnerships and specialized fabless suppliers, increasingly focusing on integrated optical engines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Liquid Crystal on Silicon market is transitioning into a late-cycle quality story, driven by a demand shift towards premium phase-only spatial light modulators. These advanced components enable integrated photonic systems and computational optics.
For Market Incumbents: Deepen R&D investments into phase modulation capabilities to counter substitution threats from Micro-OLED technology. Incumbents should also strengthen partnerships with major AR/VR device manufacturers in Taiwan and South Korea to supply complete optical engines. This approach helps mitigate margin pressure from high fabrication costs for silicon backplanes. Securing global certifications like CE marking and FCC regulations provides market access leverage.
For New Entrants and Emerging Players: A price-point gap exists between premium scientific-grade spatial light modulators and mass-market consumer LCoS modules. New entrants can target niche, high-value applications like advanced photonic systems and medical imaging, which demand precise light control. The most penetrable segment lies within research institutions in Germany and the United States. A go-to-market strategy focused on customized, application-specific solutions can bypass high-volume competition.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized LCoS developers possessing unique intellectual property in phase modulation. The long-term viability of the market is anchored by persistent demand from augmented reality and advanced photonic systems. Strategic acquirers should seek firms with proven integration capabilities for complete optical engines. A key signal to watch is the volume of design wins for LCoS in automotive head-up displays, indicating market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Phase-Only LCoS R&D | This secures market leadership in advanced optical systems and computational optics. |
| Expand Integrated Optical Engine Production | This simplifies integration and reduces design complexity for AR/VR device manufacturers. |
| Secure Long-Term Silicon Wafer Supply Contracts | This mitigates supply chain risks and cost volatility from global semiconductor markets. |
| Pursue Automotive AR-HUD Design Wins | This unlocks a high-growth, high-value application segment within the automotive industry. |
| Obtain Global Regulatory Certifications | This ensures market access across Europe, the US, and China for LCoS products. |
Research Approach
Multiple input streams — primary interviews with LCoS manufacturers, AR/VR device OEMs, and optical component suppliers — were reconciled with extensive secondary research. This included analysis of industry association reports, government regulatory documents like CE marking and FCC regulations, and academic journals on microdisplay technology. Both bottom-up and top-down data triangulation methods were employed to ensure data accuracy and robustness.
Data stream reconciliation informed a quantitative analytical framework, modeling market dynamics across the analysis window. Segmentation dimensions included product type, technology, application, end user, and key regional demand centers. Compound Annual Growth Rates were derived from historical trends and projected technology adoption rates. Key industry-specific inputs included head-mounted display unit forecasts and anticipated automotive AR-HUD integration volumes.
The model assumes a particular technology adoption path; alternative pathways for Micro-LED microdisplays would alter the outlook. Forecasts reflect assumptions concerning global semiconductor supply stability and AR/VR market penetration rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Optical Gratings Market
Optics
Optical Imaging Market
Optics
Advanced Optics Market
Optics
Collimating Lens Market
Optics
Fixed Focal Length Lenses Market
Optics
Fiber Optic Preform Market
Optics
Middle East and Africa Optical Imaging Market
Optics
Global Super Hi Vision Market
Optics
Photonics Market
Optics
Solid State Lasers Market
Optics
Smart Glass Market
Optics
Sports Optics Market
Optics
Optical Sensing Market
Optics
EUV Pellicle Market
Optics
Global Enhanced Vision System Market
Optics
Tunable Laser Market