
 Ambient Light Sensor Market | 2026-2036
Ambient Light Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Ambient Light Sensor Market Analysis
Silicon photodiodes are restructuring cost-performance economics across the ambient light sensor supply chain as they displace legacy cadmium sulfide photoresistors in cost-sensitive designs. ams OSRAM AG leverages its vertically integrated III-V semiconductor fabrication to sustain premium positioning in automotive-grade sensors. Texas Instruments Incorporated anchors the industrial segment with precision analog front-ends that integrate photodiode signal conditioning. STMicroelectronics competes through CMOS-embedded ambient light sensing modules that reduce bill-of-materials count for smartphone OEMs.
An ambient light sensor detects incident illuminance and converts optical signals into electrical output for automatic brightness adjustment and energy management. CMOS-based implementations achieve sensitivity below lux thresholds, enabling operation in sub-lux conditions for wearable and display applications. Integrated sensors capture the dominant volume share as smartphone and tablet OEMs prioritize space-constrained multi-function modules over discrete components. Photodiode technology leads in automotive lighting applications where wide dynamic range and fast response times meet safety-critical requirements. Module sensors represent the fastest-expanding category, driven by smart home and industrial automation demand for pre-calibrated, plug-and-play sensing units with digital interfaces.
The EU Ecodesign Directive and CE marking requirements shape product standards for lighting-integrated sensors sold across European markets. EPA Energy Star specifications and FCC Part 15 emissions rules influence design parameters for US-bound consumer electronics containing ambient light sensing. China's GB standards and MIIT regulations govern electromagnetic compatibility and performance claims for domestically manufactured sensors. Stakeholders must monitor evolving automotive functional safety standards and building energy codes as these frameworks increasingly mandate occupancy-aware and daylight-responsive control systems.
Market Dynamics
Smartphone OEMs are consolidating around CMOS-embedded multi-function modules that compress ambient light sensing, proximity detection, and color temperature measurement into single die packages, collapsing discrete component demand and rewiring supplier economics toward integrated module vendors.
Growth Catalysts
- EU Ecodesign Directive:Mandates daylight-responsive controls in commercial lighting retrofits across member states, creating pull-through demand for sensor-integrated luminaires in Germany and France.
- Automotive functional safety standards:Wide dynamic range photodiode arrays meet headlamp auto-leveling requirements under UN ECE R48, expanding sensor deployment in adaptive driving beam systems.
- Shenzhen-Dongguan electronics clusters:Concentrated PCB assembly and optical component sourcing enable rapid prototyping cycles for wearable OEMs targeting sub-lux sensitivity thresholds.
Market Restraints
- Silicon wafer input volatility:CMOS photodiode foundry capacity constraints in Taiwan and South Korea create allocation risk for fabless sensor designers during semiconductor upcycles.
- Indium gallium arsenide cost structure:III-V compound semiconductor substrates for near-infrared-enhanced automotive sensors carry 8-12x material cost premiums versus silicon alternatives.
- RoHS substance restrictions:Cadmium sulfide photoresistor phase-out timelines compress legacy supplier revenue streams while silicon replacements require redesign investment.
Strategic Opportunities
- Smart home retrofit channels:Pre-calibrated module sensors with Matter protocol compatibility enable direct-to-installer distribution bypassing traditional lighting OEM procurement.
- India BIS certification pipeline:Delayed mandatory energy efficiency standards for commercial buildings create first-mover positioning for daylight harvesting control suppliers.
- UV-C disinfection convergence:Multi-spectral ambient light sensors that add ultraviolet detection enable occupancy-aware sterilization cycles in healthcare and transit applications.
Industry Challenges
- Optical calibration talent scarcity:Precision lux mapping and temperature compensation algorithm development requires rare cross-training in photonics and embedded firmware engineering.
- Automotive ASPICE compliance timelines:18-24 month qualification cycles for safety-critical sensor modules delay revenue recognition and strain R&D capitalization.
- Legacy DALI protocol integration friction:Building automation retrofits demand analog-to-digital signal bridging that adds bill-of-materials complexity and field commissioning cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ambient Light Sensor Market |
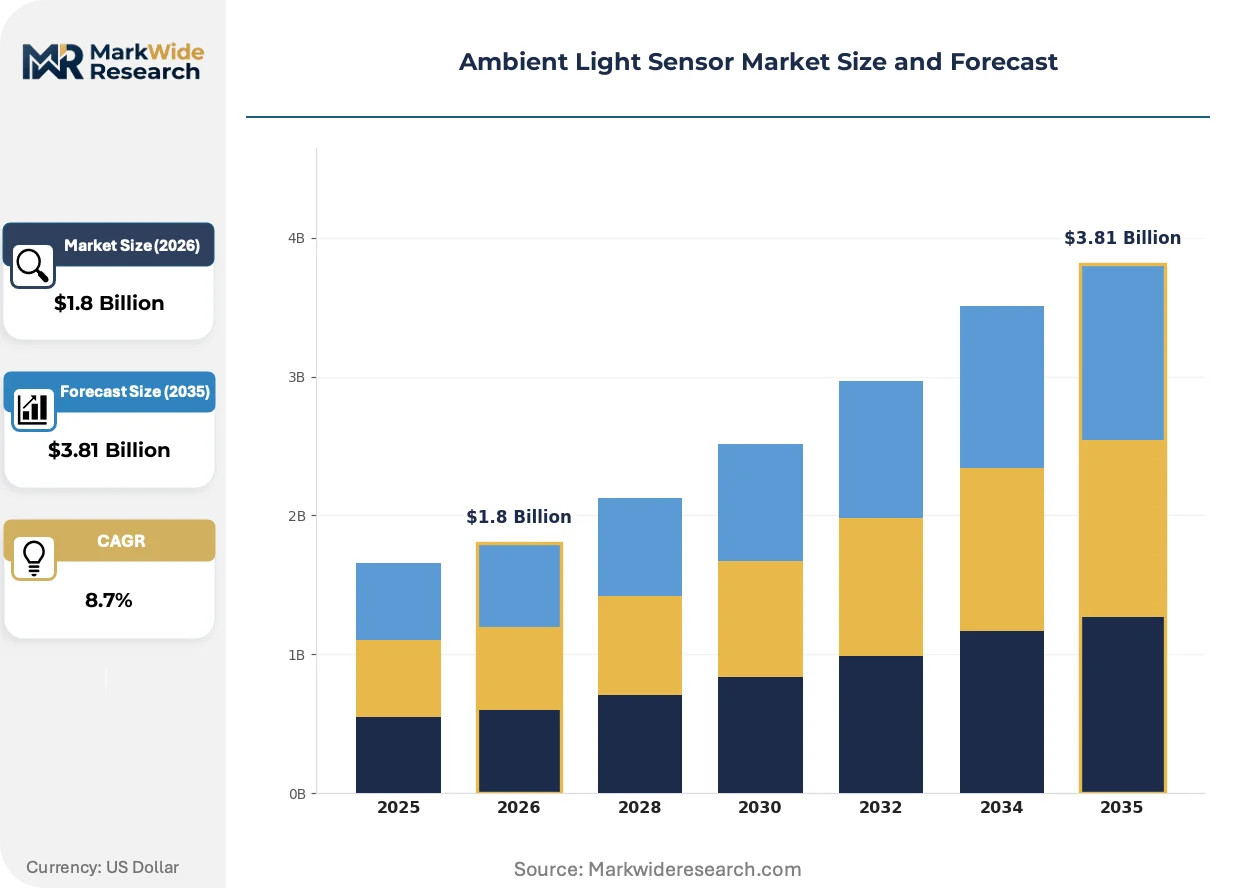
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Sensors, Integrated Sensors, Module Sensors, Smart Sensors Application: Smartphones, Automotive Lighting, Indoor Lighting, Wearable Devices Technology: Photodiodes, CMOS Sensors, Analog Sensors, Digital Sensors End User: Consumer Electronics, Automotive Sector, Industrial Automation, Smart Home |
| Companies Covered | ams OSRAM AG, Texas Instruments Incorporated, STMicroelectronics, ON Semiconductor Corporation, Vishay Intertechnology, Broadcom Inc., Samsung Electronics Co., Ltd., Analog Devices, Inc., ROHM Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ambient Light Sensor Market Emerging Trajectories
Silicon photodiode architectures are compressing cost curves while regulatory mandates harden performance requirements, forcing simultaneous innovation in miniaturization, spectral precision, and digital interface standardization.
Spectral-tuned CMOS photodiodes with integrated photopic response filtering are overtaking discrete filter-and-sensor assemblies in smartphone display management. Flagship OEMs in South Korea and China have completed platform transitions to single-die solutions. This compression is eliminating secondary optical component suppliers and collapsing module thickness budgets below 0.4mm.
The EU AI Act's risk classification framework is redefining sensor data governance for ambient light inputs used in automated decision systems. Industrial automation vendors must now document luminance data lineage and bias testing for AI-driven quality control applications. German machine builders are responding by segregating sensor data processing into edge-isolated microcontrollers with immutable audit logging.
Component distributors are unbundling optical sensing from full lighting control system procurement, enabling direct specification by electrical contractors and facility managers. WESCO and Rexel are building dedicated sensor SKU catalogs with application-specific lux range pre-selection. This channel shift is most visible in US commercial retrofit projects where ESCO financing structures now separate hardware procurement from installation labor contracts.
Ambient Light Sensor Market Segmentation
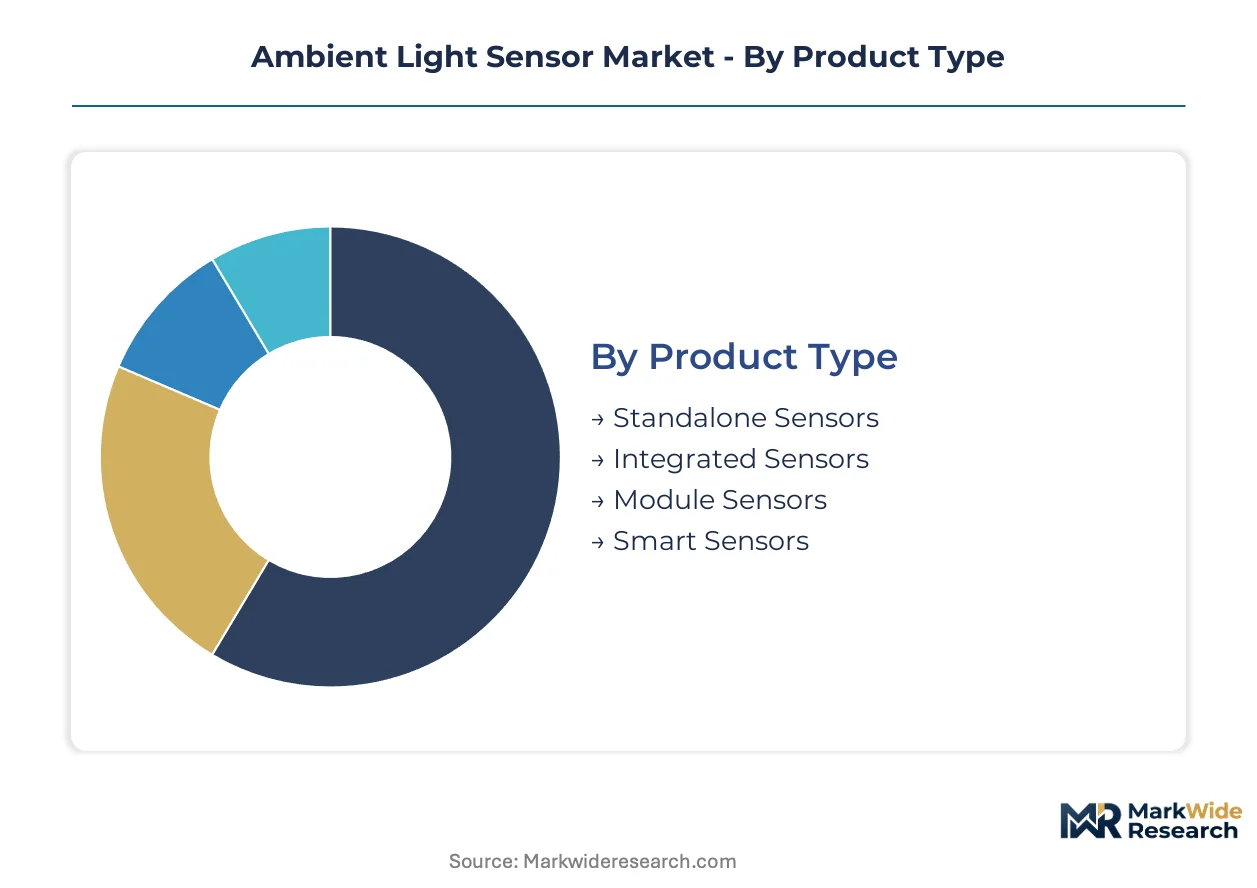
Segmentation reveals how certification requirements and integration complexity fragment procurement patterns across the ambient light sensor value chain. Different buyer categories prioritize distinct performance thresholds, from sub-lux precision in wearables to automotive functional safety compliance.
Product Type:
CE marking applies universally, while automotive-grade modules demand ASPICE process certification and AEC-Q100 stress testing that standalone consumer variants bypass.
- Standalone Sensors:Discrete photodiode or photoresistor components without signal conditioning circuitry. Procurement concentrates in cost-optimized industrial controls and legacy lighting retrofits where OEMs maintain in-house analog design capabilities.
- Integrated Sensors:Single-die CMOS implementations combining photodiode, amplifier, and ADC functions. South Korean smartphone OEMs have completed platform transitions to these solutions, collapsing module thickness budgets below 0.4mm and eliminating secondary optical component suppliers.
- Module Sensors:Pre-calibrated units with digital output and standardized interfaces. Matter protocol compatibility enables direct-to-installer distribution in smart home retrofit channels.
- Smart Sensors:Embedded processing units with on-chip algorithms for spectral discrimination and occupancy inference. EU AI Act risk classification frameworks now mandate data lineage documentation for these components in automated decision systems.
Integrated sensors sit at the top of the volume ranking, with module sensors climbing the fastest.
Application:
Cost tiers separate premium precision requirements from commodity brightness adjustment functions.
- Smartphones:Sub-lux sensitivity thresholds and sub-millimeter z-height constraints dominate specifications. Shenzhen and Dongguan electronics clusters drive volume production for both domestic Chinese brands and export markets.
- Automotive Lighting:Wide dynamic range photodiode arrays meet UN ECE R48 headlamp auto-leveling mandates. German and French OEMs specify adaptive driving beam systems requiring 18-24 month ASPICE qualification cycles.
- Indoor Lighting:Daylight harvesting controls face EU Ecodesign Directive mandates for commercial retrofits across member states. German and French markets show strongest pull-through for sensor-integrated luminaires.
- Wearable Devices:Ultra-low power consumption and minimal form factor requirements predominate. Indian wearable OEMs represent emerging demand concentration for fitness-tracker-integrated variants.
Smartphone applications command the highest shipment volumes, while automotive lighting gains share fastest.
Technology:
Margin structures diverge sharply between silicon CMOS commodity production and III-V compound semiconductor premium positioning.
- Photodiodes:Silicon architectures achieve wide dynamic range with fast response times. Automotive safety-critical applications specify these for headlamp leveling under UN ECE regulations.
- CMOS Sensors:Photopic response filtering integrates directly onto die, displacing discrete filter-and-sensor assemblies. Taiwan and South Korean foundry capacity constraints create allocation risk during semiconductor upcycles.
- Analog Sensors:Continuous voltage output suits legacy building automation with DALI protocol infrastructure. Signal bridging requirements add bill-of-materials complexity in retrofit installations.
- Digital Sensors:I2C and SPI interfaces enable direct microcontroller integration without external ADC. Industrial automation vendors favor these for edge-isolated processing with immutable audit logging.
CMOS sensors dominate production scale, with digital sensors expanding most quickly in industrial applications.
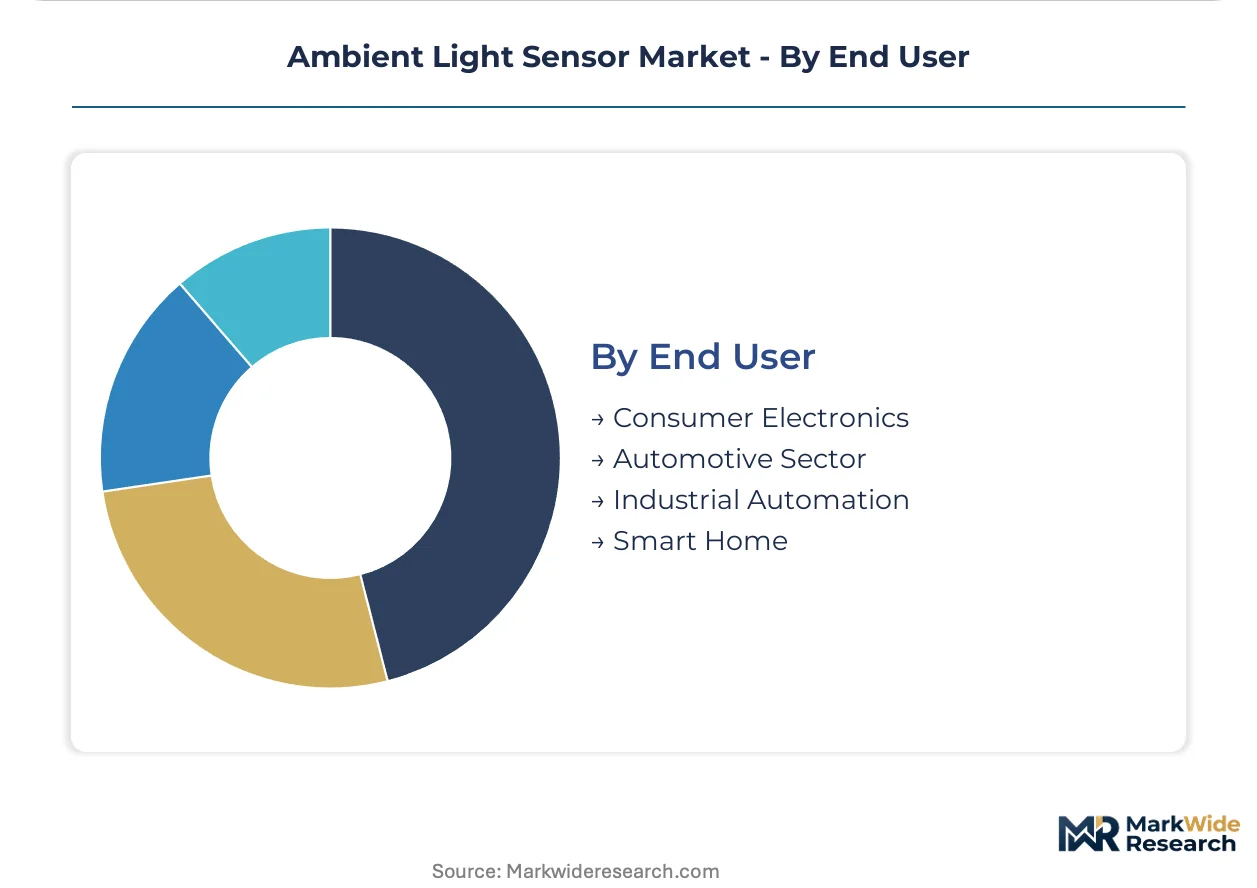
End User:
Supply concentration varies by customer sophistication, from concentrated electronics manufacturing services to fragmented electrical contractor channels.
- Consumer Electronics:High-volume procurement through concentrated manufacturing services in China. FCC Part 15 emissions compliance shapes design parameters for US-bound products.
- Automotive Sector:Tier-1 lighting suppliers enforce AEC-Q100 and ASPICE process standards. Revenue recognition stretches 18-24 months from design win to production.
- Industrial Automation:German machine builders drive demand for precision analog front-ends with temperature compensation algorithms. EU AI Act documentation requirements now extend to luminance data governance.
- Smart Home:ESCO financing structures separate hardware procurement from installation labor in US commercial retrofits. WESCO and Rexel distributor catalogs enable direct specification by facility managers.
Consumer electronics anchors volume production, with smart home applications showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen and Dongguan electronics clusters anchor production capacity for ambient light sensors serving both domestic brands and export markets. Regulatory fragmentation across major economies shapes certification requirements and procurement patterns. Industrial concentration varies sharply between semiconductor fabrication hubs and end-use assembly locations.
China
Smartphone OEMs in Beijing and Shanghai drive sub-lux sensitivity demand for wearable-integrated sensors. MIIT regulations govern electromagnetic compatibility claims for domestically manufactured components. The Yangtze River Delta and Pearl River Delta house concentrated CMOS foundry capacity and optical module assembly operations serving global consumer electronics brands.
United States
Industrial automation vendors in Michigan and Ohio specify precision analog front-ends with temperature compensation algorithms. EPA Energy Star specifications and FCC Part 15 emissions rules shape design parameters for consumer electronics. The Pacific Northwest hosts specialized distributors building dedicated sensor SKU catalogs for commercial retrofit channels.
Germany
Automotive Tier-1 suppliers enforce AEC-Q100 and ASPICE process standards for headlamp auto-leveling applications. The EU Ecodesign Directive mandates daylight-responsive controls in commercial lighting retrofits across member states. Bavaria and Baden-Württemberg concentrate machine builder demand for edge-isolated processing units with immutable audit logging.
South Korea
Flagship smartphone OEMs completed platform transitions to single-die CMOS solutions, collapsing module thickness budgets below 0.4mm. MFDS regulations align with international electromagnetic compatibility standards for domestically sold devices. Seoul Capital Area foundries face capacity allocation constraints during semiconductor upcycles affecting fabless sensor designers.
India
Wearable OEMs in Karnataka and Tamil Nadu represent emerging demand concentration for fitness-tracker-integrated variants. BIS certification pipelines for delayed mandatory energy efficiency standards create first-mover positioning opportunities. The Delhi-NCR corridor attracts daylight harvesting control suppliers targeting commercial building retrofits.
Ambient Light Sensor Market Vendor Landscape
Vertical integration dominates the current landscape as sensor vendors capture margin from optical component fabrication through module assembly. The vendor base separates into three tiers: integrated semiconductor conglomerates with captive foundry capacity, fabless design houses reliant on Taiwan and South Korean contract manufacturing, and specialized module assemblers serving regional retrofit channels. Strategic archetypes include III-V compound semiconductor specialists commanding automotive-grade premiums, CMOS-embedded solution providers collapsing bill-of-materials counts for smartphone OEMs, and precision analog front-end suppliers anchoring industrial automation specifications. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with foundry allocation agreements and distributor catalog unbundling reshaping channel economics.
Within the integrated semiconductor tier, ams OSRAM AG and STMicroelectronics exemplify divergent approaches to vertical integration. The former leverages III-V semiconductor fabrication for automotive-grade positioning, while the latter competes through CMOS-embedded modules reducing component counts. Texas Instruments Incorporated anchors the industrial segment archetype with precision analog expertise. These three represent distinct strategic postures: compound semiconductor premium positioning, consumer electronics integration leadership, and industrial precision specification respectively.
| Leading Market Players |
|---|
| ams OSRAM AG |
| Texas Instruments Incorporated |
| STMicroelectronics |
| ON Semiconductor Corporation |
| Vishay Intertechnology |
| Broadcom Inc. |
| Samsung Electronics Co., Ltd. |
| Analog Devices, Inc. |
| ROHM Semiconductor |
| Others |
Supply Flow & Price Mechanics
Silicon wafer input costs flow from Taiwan and South Korean foundries through three distinct pricing tiers, with automotive-grade III-V compound sensors commanding premiums against commoditized CMOS smartphone variants.
Pricing Analysis
Input-cost pass-through from indium gallium arsenide substrates drives 8-12x material premiums for automotive-grade sensors versus silicon alternatives. Pricing stratifies across ASPICE-certified automotive modules, CE-marked industrial units, and economy smartphone-integrated dies. Cost compression in smartphone tiers is intensifying as South Korean OEMs consolidate around single-die CMOS solutions. Wearable OEMs in India exhibit highest price sensitivity, while German automotive Tier-1 suppliers accept extended qualification timelines for safety-critical specifications.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale smartphone demand from Shenzhen and Dongguan clusters, while distributor catalogs serve fragmented smart home retrofit markets. Taiwan and South Korean foundries anchor CMOS photodiode fabrication, with China dominating optical module assembly. Raw material dependencies center on silicon wafers, III-V compound substrates, and precision optical filters. Single-source vulnerability concentrates in Taiwan foundry capacity during semiconductor upcycles. Distribution runs through concentrated electronics manufacturing services for consumer electronics and specialized electrical distributors for building automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Ecodesign Directive functions as a regulatory compounder, mandating daylight-responsive controls that pull through sensor-integrated luminaire demand across member states.
For Market Incumbents: Hedge against silicon foundry allocation risk by securing long-term wafer supply agreements with Taiwan and South Korean partners. Deepen backward integration into III-V semiconductor fabrication to defend automotive-grade margin premiums against fabless entrants. Prioritize ASPICE process certification investments to maintain Tier-1 supplier positioning as qualification timelines stretch. For New Entrants and Emerging Players: BIS certification delays in India open a window for daylight harvesting control suppliers to establish first-mover positioning before mandatory energy efficiency standards take effect. Target Matter protocol-compatible module sensors for smart home retrofit channels where distributor catalog unbundling bypasses traditional OEM procurement. Pursue direct-to-installer distribution partnerships with WESCO and Rexel to circumvent consolidated lighting control system vendors. For Investors and Strategic Acquirers: Consolidation pressure builds where optical calibration talent scarcity constrains algorithm development capabilities. Long-term viability favors vendors with captive foundry capacity or locked-in supply agreements across the analysis window. Acquisition target archetypes include fabless design houses with automotive qualification pipelines and specialized module assemblers serving regional retrofit channels. Monitor Taiwan foundry utilization rates as inflection indicator for sensor component pricing cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Lock-in | Long-term wafer supply agreements with TSMC or Samsung Foundry secure allocation priority during semiconductor upcycles. |
| ASPICE Process Certification | Achieving automotive software process maturity enables 18-24 month qualification cycles with German Tier-1 lighting suppliers. |
| Matter Protocol Integration | Pre-calibrated module sensors with interoperability certification unlock direct-to-installer distribution in smart home channels. |
| III-V Fabrication Expansion | In-house indium gallium arsenide production captures margin premiums for near-infrared-enhanced automotive sensors. |
| Optical Calibration Talent Acquisition | Cross-trained photonics and embedded firmware engineers enable precision lux mapping for sub-lux wearable applications. |
Methodological Framework
Multiple input streams — semiconductor foundry utilization data, lighting OEM procurement patterns, and regulatory filing databases — were reconciled through bottom-up and top-down triangulation. Primary interviews with CMOS sensor design engineers, automotive Tier-1 procurement managers, smart home platform architects, and building automation system integrators informed demand-side validation. Secondary sources included SEC 10-K filings from listed sensor vendors, MIIT electromagnetic compatibility certification records, EU Ecodesign Directive implementation reports, and customs trade data for optical component flows.
Data-stream reconciliation across shipment volume tracking, bill-of-materials cost modeling, and end-use demand segmentation generated value forecasts over the projection horizon. Segmentation dimensions encompassed product type, application category, technology architecture, and end-user industry vertical. CAGRs were derived from regression analysis of historical foundry capacity expansion against sensor unit demand growth, with explicit modeling of automotive ASPICE qualification timeline impacts and smartphone platform transition cycles.
Revisions become necessary when Taiwan foundry allocation constraints intensify, EU AI Act risk classification frameworks expand sensor data governance requirements, or BIS certification timelines in India accelerate unexpectedly. Forecasts reflect assumptions regarding sustained EU Ecodesign Directive enforcement and continued Matter protocol adoption in smart home channels. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
MEMS Pressure Sensors Market
Sensors and Controls
Global Refrigeration Leak Detector Market
Sensors and Controls
Flow Sensor Market
Sensors and Controls
Current Transducer Market
Sensors and Controls
Multi-Function Timer Market
Sensors and Controls
Global Space Sensors and Actuators Market
Sensors and Controls
3D Profile Sensors Market
Sensors and Controls
Asia Pacific Touch Screen Controllers Market
Sensors and Controls
Digital Radiography Sensor Market
Sensors and Controls
Global MEMS and Sensors Market
Sensors and Controls
60GHz Radar Evaluation Kit Market
Sensors and Controls
Meteorological Devices Market
Sensors and Controls
Europe Pressure Transmitter Market
Sensors and Controls
Global Proximity and Displacement Sensors Market
Sensors and Controls
Pressure Transmitter Market
Sensors and Controls
Europe Human Machine Interface Market