
 Single Core Cables Market | 2026-2036
Single Core Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Single Core Cables Market Analytics
Qualified cable engineers and certified high-voltage technicians is redrawing competitive boundaries across the single core cables industry. Prysmian Group leverages its integrated compound-to-cable manufacturing footprint to secure utility contracts in premium voltage tiers. Nexans anchors European renewable interconnection projects through specialized submarine and land-based single core expertise. Southwire sustains North American market presence via extensive distributor networks and regional copper sourcing advantages.
Single core cables consist of one conductor—typically copper or aluminum—surrounded by insulation and sheathing layers, with cross-linked polyethylene or ethylene propylene rubber delivering thermal ratings up to 90°C continuous operation. These cables transmit power or signals in configurations where electromagnetic isolation, bending flexibility, or individual phase separation matters. Low voltage and medium voltage categories dominate volume shipments, though ultra high voltage products command disproportionate margin pools due to compound formulation complexity and qualification barriers. Copper material grades lead value contribution, while aluminum gains traction in cost-sensitive utility trunk lines where weight and conductivity trade-offs favor lighter conductor economics.
IEC 60502 and IEEE 404 standards govern insulation thickness, partial discharge limits, and long-term aging tests that determine product eligibility for utility tenders. EMA and national regulators across Europe enforce REACH-compliant sheathing additives, while India's BIS certification mandates short-circuit temperature withstand verification for imported cables. China's GB standards and NMPA-equivalent quality supervision shape Asian procurement specifications. Stakeholders must weigh raw material hedge strategies against qualification timelines as grid operators tighten vendor pre-approval protocols.
Market Dynamics
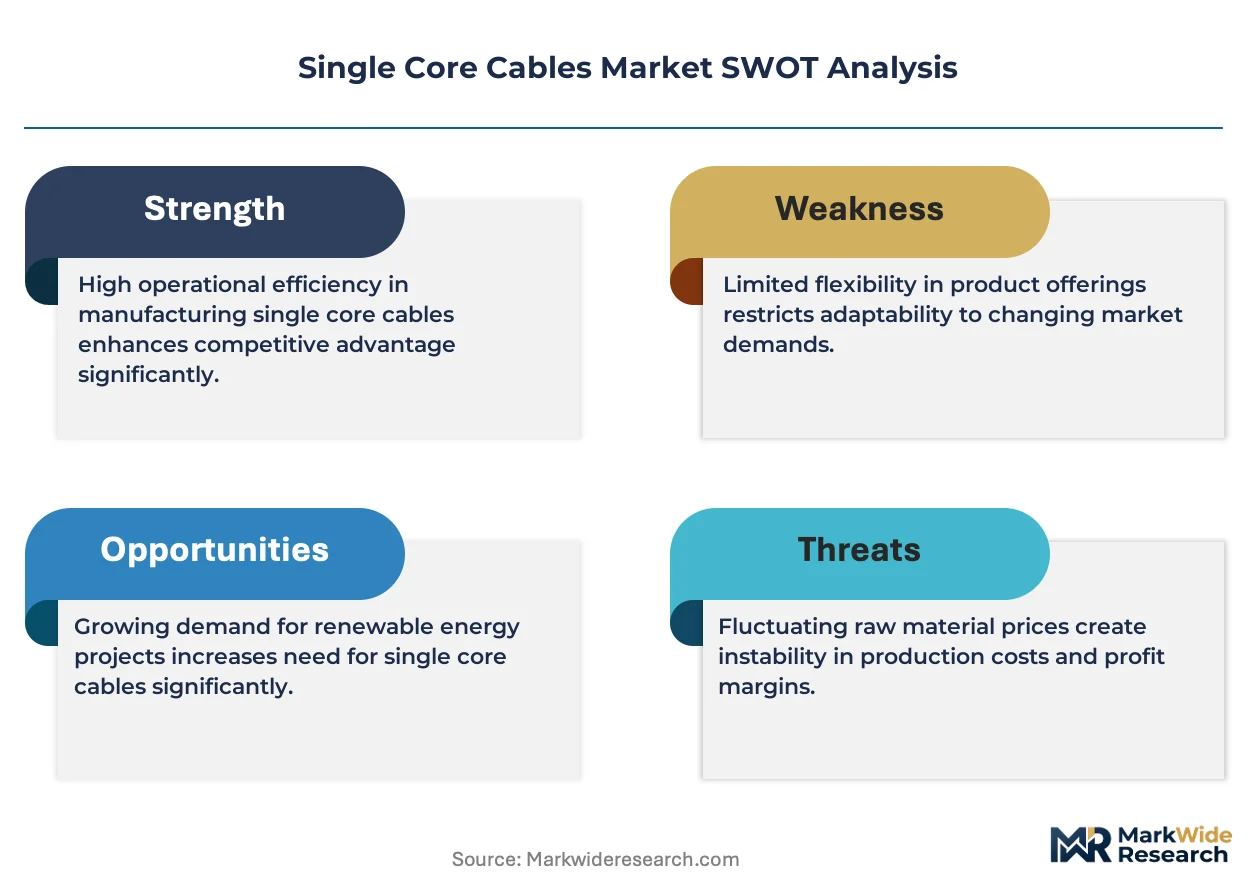
Cross-linked polyethylene insulation technology is compressing qualification timelines and redrawing vendor eligibility criteria across utility procurement frameworks.
Growth Catalysts
- Grid Modernization Mandates:Power utilities in India and Southeast Asia are accelerating conductor replacement schedules under national electrification targets, creating sustained tender volume for medium-voltage single core configurations.
- REACH-Compliant Sheathing:EMA enforcement of additive transparency rules across Europe is filtering out non-compliant imports and consolidating contract awards toward qualified compound-to-cable manufacturers.
- Renewable Interconnection:Offshore wind and solar farm developers require specialized submarine and land-based single core expertise for phase-separated high-capacity transmission.
Market Restraints
- Copper Price Volatility:LME copper fluctuations compress margin predictability for manufacturers lacking backward integration into smelting or scrap recycling operations.
- Concentrated Compound Supply:Specialty cross-linking peroxide additives for XLPE production originate from a narrow base of European and Japanese chemical suppliers, creating single-source vulnerability.
- Aluminum Conductivity Ceiling:Utility trunk lines above 220kV face technical barriers to aluminum adoption due to thermal expansion mismatches in termination hardware.
Strategic Opportunities
- Urban Electrification Corridors:Indonesian and Vietnamese manufacturing zones lack localized cable supply capacity, opening greenfield production investment windows.
- Digital Substation Integration:Convergence of fiber-optic sensing with single core cable jackets enables real-time thermal monitoring for predictive maintenance contracts.
- BIS Certification Acceleration:India's shortened import approval timelines for pre-qualified vendors create first-mover advantages in short-circuit-tested product categories.
Industry Challenges
- Certified High-Voltage Technician Scarcity:Installation and commissioning of 132kV+ single core systems requires specialized jointing expertise that training pipelines have failed to replenish.
- Legacy PVC Infrastructure Lock-In:Existing utility inventories and contractor familiarity slow XLPE transition despite superior thermal ratings, forcing dual qualification maintenance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Core Cables Market |
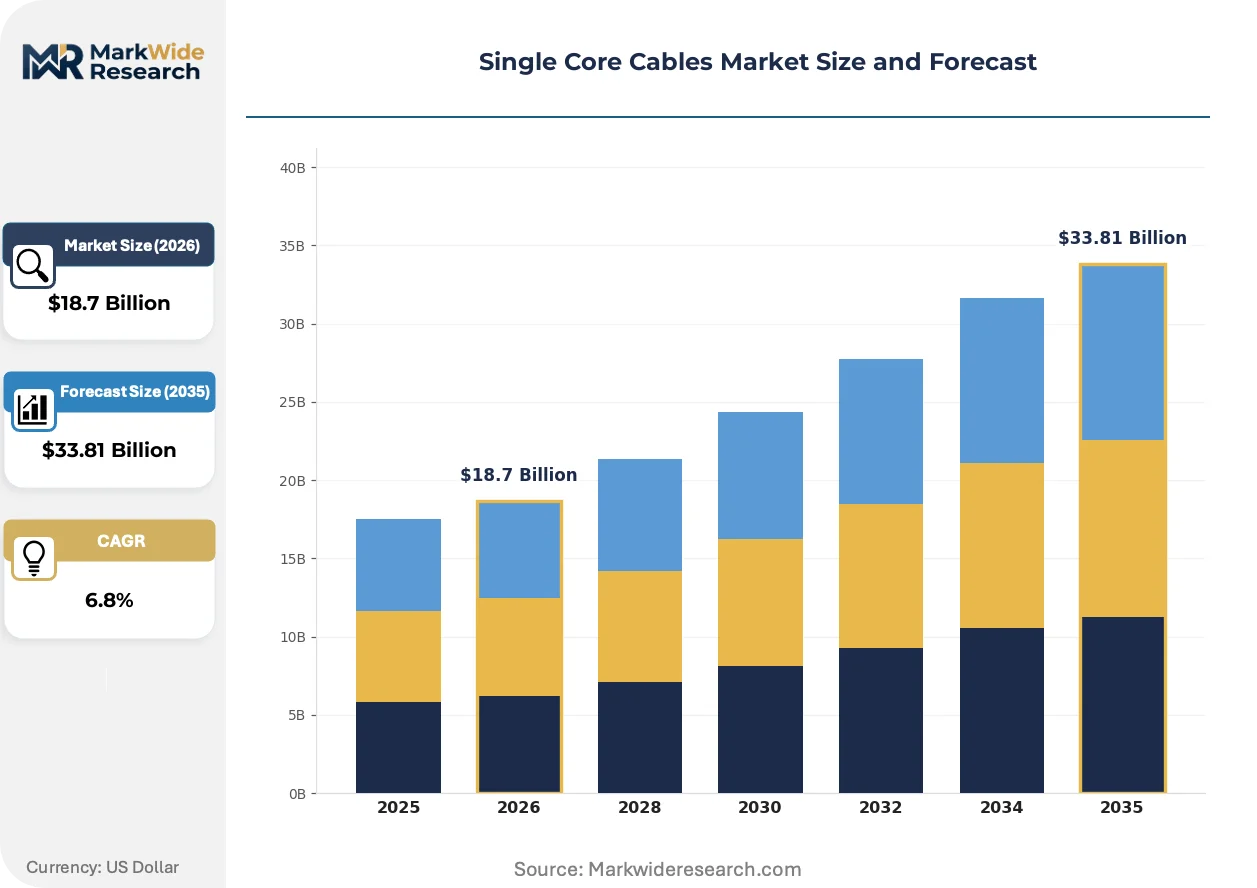
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Voltage, Medium Voltage, High Voltage, Ultra High Voltage Material: Copper, Aluminum, Fiber, Composite Application: Power Generation, Telecommunications, Construction, Industrial End User: Utilities, OEMs, Contractors, Residential |
| Companies Covered | Prysmian Group, Nexans, Leoni, Furukawa Electric, Sumitomo Electric, Southwire, Finolex Cables, General Cable, Tekima, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Core Cables Market Evolving Landscape
Material science advances and procurement digitization are compressing product lifecycles while elevating performance verification standards across voltage tiers.
Cross-linked polyethylene (XLPE) compounds with tree-retardant additives are displacing conventional PVC insulation in medium-voltage distribution networks. European and Asian utilities specify XLPE for 11kV to 33kV underground circuits where moisture resistance and thermal overload capacity justify 15-20% material cost premiums. This displacement is compressing PVC compound demand and forcing legacy insulation manufacturers toward specialty low-smoke zero-halogen formulations.
REACH enforcement by ECHA is mandating substitution of lead-based stabilizers and certain phthalate plasticizers in cable sheathing compounds. Compound manufacturers must reformulate additive packages and resubmit technical files for existing product approvals. Medium-voltage utility tenders in Germany and France now require full material disclosure, filtering out suppliers lacking European compound-to-cable integration.
Utility procurement departments are consolidating vendor panels and unbundling installation from supply contracts. Grid operators in India and Southeast Asia now separate cable procurement from EPC commissioning, forcing manufacturers to certify third-party installer networks. This unbundling is visible in state electricity board tenders where pre-approved vendor lists have contracted by 30-40% while technical qualification requirements have intensified.
Single Core Cables Market Segmentation
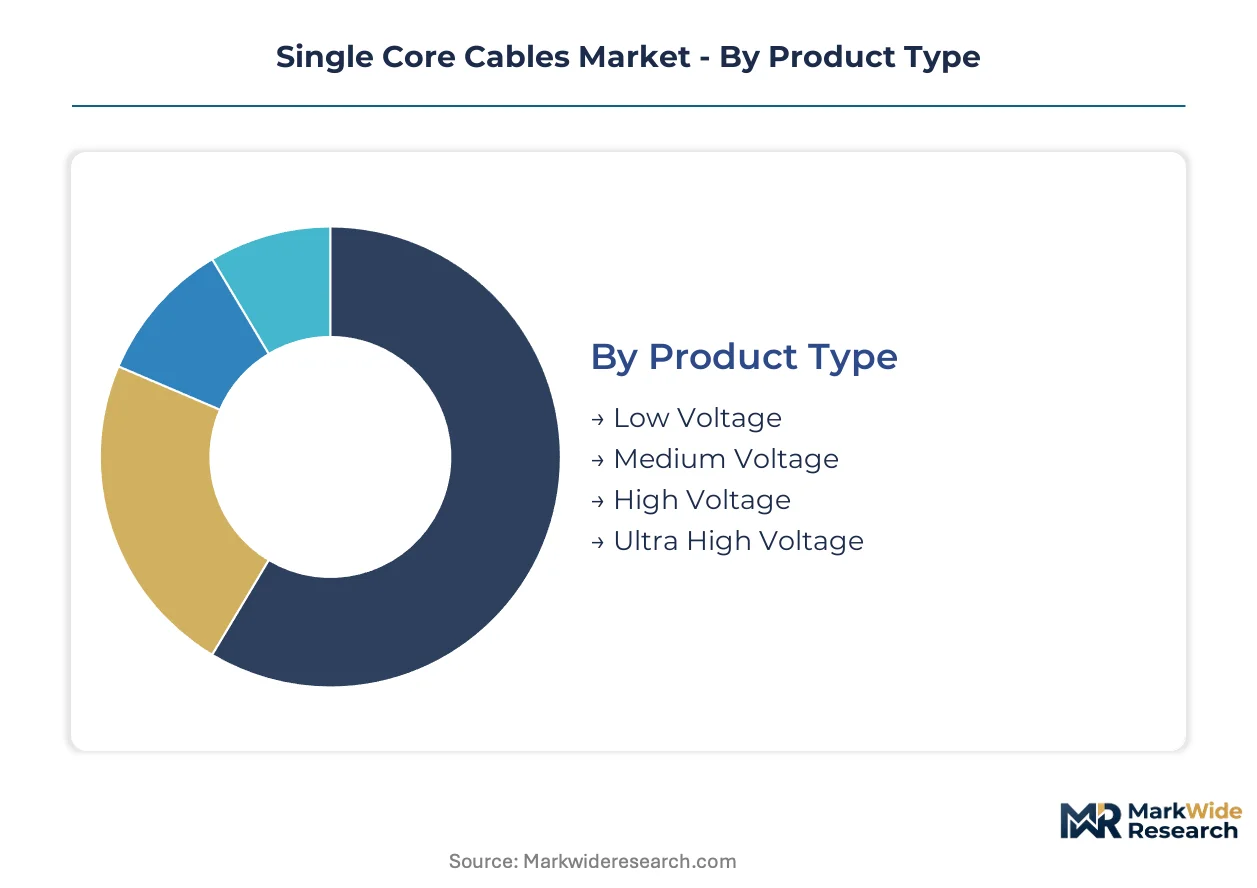
Single core cables serve distinct technical requirements across voltage tiers and material systems. Procurement patterns diverge sharply between utility-scale trunk lines and distributed building installations.
Product Type:
Domestic consumption dominates low and medium voltage categories, while high and ultra high voltage segments rely heavily on export-qualified manufacturers serving interconnection projects.
- Low Voltage:These cables handle distribution up to 1kV with PVC or XLPE insulation layers. Residential electrification in Indian urban corridors and Vietnamese manufacturing zones absorbs volume shipments as grid extension outpaces local production capacity.
- Medium Voltage:Rated 1kV to 33kV, these configurations deploy cross-linked polyethylene insulation for underground distribution circuits. European utilities specify these for renewable farm connections where ECHA REACH compliance on sheathing additives filters vendor pools.
- High Voltage:33kV to 220kV systems require specialized jointing expertise and partial discharge testing under IEC 60502 protocols.
- Ultra High Voltage:Above 220kV, these cables command extended qualification timelines and compound formulation complexity for long-distance transmission.
Low voltage holds the largest share; momentum sits with ultra high voltage as interconnection projects multiply.
Material:
Cost tier separation runs deepest here, with premium conductivity grades commanding utility tenders while lighter alternatives penetrate price-sensitive trunk line applications.
- Copper:Oxygen-free high-conductivity grades deliver thermal ratings to 90°C with superior termination reliability. Indian state electricity boards and German distribution operators specify copper for 11kV to 132kV circuits where jointing failure costs exceed material premiums.
- Aluminum:Lighter conductor economics favor utility trunk lines above 66kV where span lengths and tower loading drive specification. Southeast Asian transmission planners specify aluminum alloy cores for cost-sensitive corridor builds despite 39% conductivity penalty versus copper.
- Fiber:Optical fiber elements embedded in cable jackets enable distributed temperature sensing for predictive maintenance contracts.
- Composite:Hybrid conductor designs combine aluminum strength members with copper conductivity cores for specialized submarine applications.
Copper dominates value contribution; aluminum is climbing the fastest as transmission planners optimize for total installed cost.
Application:
Volume concentration varies by customer procurement maturity, with power generation requiring longest qualification cycles and construction tolerating shortest.
- Power Generation:Generation tie-lines demand 132kV+ single core systems with specialized termination hardware and thermal cycling resistance. Offshore wind developers in European waters specify submarine-rated single core configurations with lead-sheath moisture barriers.
- Telecommunications:Fiber-optic hybrid cables serve 5G backhaul and data center interconnects where electromagnetic isolation matters.
- Construction:Building wire and temporary power distribution favor flexible low-voltage singles with rapid deployment characteristics.
- Industrial:Process plants specify fire-resistant sheathing and oil-resistant compounds for harsh environment reliability.
Power generation commands premium positioning; construction delivers highest shipment velocity.
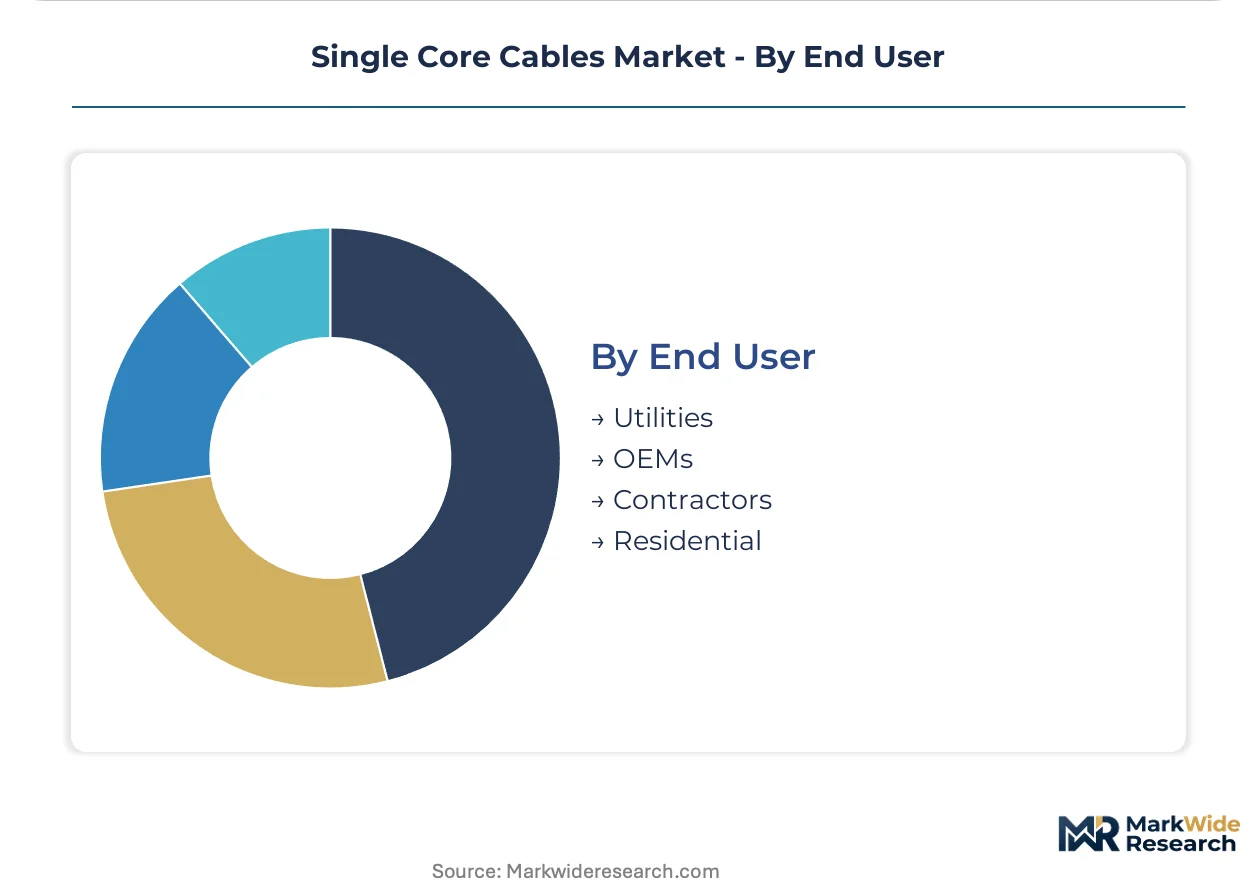
End User:
Procurement centralization distinguishes this category, with consolidated utility buying desks demanding deepest technical documentation.
- Utilities:Grid operators in India, Germany, and Vietnam unbundle supply from installation contracts and maintain pre-approved vendor lists with 30-40% contraction rates. BIS certification and IEC 60502 qualification gates determine tender eligibility.
- OEMs:Original equipment manufacturers specify single core feeds for transformer, switchgear, and generator integration with tight dimensional tolerances.
- Contractors:Installation firms procure through distributor networks with regional copper sourcing advantages and just-in-time logistics.
- Residential:Individual consumers purchase through retail electrical supply channels for renovation and extension projects.
Utilities anchor contract value; contractors drive shipment volume through fragmented project demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CEA grid modernization directives in India anchor the dominant geography for single core cable procurement, with state electricity boards unbundling supply contracts from installation services and tightening BIS certification gates for imported products.
India
State electricity boards in Maharashtra and Gujarat are accelerating 11kV to 132kV conductor replacement schedules under national electrification targets. BIS certification mandates short-circuit temperature withstand verification for all imported cables, filtering vendor pools toward pre-qualified compound-to-cable manufacturers. The Delhi-Mumbai Industrial Corridor and Chennai-Bengaluru manufacturing belt absorb disproportionate medium-voltage shipment volumes as urban electrification outpaces localized production capacity.
Germany
Distribution operators specify copper-conductor single core configurations for renewable farm connections and grid stabilization projects. ECHA REACH enforcement mandates full material disclosure on sheathing additives, consolidating contract awards toward integrated European manufacturers. The Ruhr industrial cluster and Bavarian manufacturing zones concentrate procurement activity for 20kV to 110kV underground distribution circuits.
United States
Regional transmission organizations and municipal utilities drive demand for 69kV to 345kV single core systems in renewable interconnection and aging infrastructure replacement programs. FERC Order 1000 compliance requirements shape competitive procurement frameworks for transmission projects. The Texas ERCOT grid and California ISO territory concentrate project development activity, with Southwest copper sourcing advantages sustaining manufacturer margins against LME price volatility.
Vietnam
Manufacturing zone electrification in Bac Ninh and Hai Phong industrial corridors creates tender volume for medium-voltage underground circuits as grid extension outpaces domestic cable supply capacity. The national power development plan prioritizes 110kV and 220kV transmission corridor builds connecting northern load centers to central generation assets. Ho Chi Minh City and surrounding Dong Nai province absorb low-voltage shipment volumes for commercial and residential distribution.
Indonesia
State-owned utility PLN is scaling 150kV and 275kV transmission investments across Java and Sumatra under the 35,000 MW electrification program. Local content requirements in procurement regulations favor joint venture structures for high-voltage cable supply. The Cilegon industrial estate and Surabaya manufacturing corridor present greenfield production investment windows where import dependence creates supply security vulnerabilities.
Single Core Cables Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the single core cables market, with compound-to-cable manufacturing footprints determining utility contract eligibility in premium voltage tiers. The structure concentrates procurement influence among manufacturers controlling cross-linking peroxide additive supply chains and IEC 60502 qualification histories. Three archetypes dominate: integrated compound-cable manufacturers, regional copper specialists with backward smelting integration, and project-specific submarine cable fabricators. Competitive moves center on M&A targeting compound formulation capabilities and capacity expansion in Southeast Asian manufacturing corridors.
Among European integrated manufacturers, Prysmian Group and Nexans occupy positions exemplifying the compound-to-cable archetype, with qualification histories spanning IEC 60502 and IEEE 404 protocols. Southwire represents the North American regional specialist model, with distributor network density and regional copper sourcing advantages sustaining market presence. These three anchors illustrate how procurement digitization and vendor panel consolidation are redrawing competitive boundaries across voltage tiers and geographic markets.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| Leoni |
| Furukawa Electric |
| Sumitomo Electric |
| Southwire |
| Finolex Cables |
| General Cable |
| Tekima |
| Others |
Value Network & Pricing Analysis
BIS certification gates for Indian utility tenders simultaneously filter supplier pools and stratify price premiums, with pre-qualified compound-to-cable manufacturers commanding 15-20% markups over import-dependent competitors while non-compliant vendors face disqualification regardless of price positioning.
Pricing Analysis
European procurement runs 12-18% above Southeast Asian contract levels for equivalent XLPE-insulated medium-voltage specifications, reflecting REACH compliance costs and shorter logistics corridors. Pricing stratifies across IEC 60502-qualified premium tiers, standard utility-grade offerings, and economy aluminum-conductor alternatives for cost-sensitive trunk lines. Cost compression in standard-grade categories is intensifying because of LME copper volatility and unbundled installation contracts. Contractor segments through distributor networks exhibit highest price sensitivity, while consolidated utility buying desks prioritize qualification certainty over unit cost.
Supply Chain Analysis
Strategic stockpiling of cross-linking peroxide additives dominates inventory strategy among integrated manufacturers, buffering against single-source concentration in European and Japanese chemical supply bases. Raw material sourcing draws from Chilean copper concentrate, Indonesian bauxite for aluminum alloys, and specialty polymer feedstocks from South Korean petrochemical complexes. Single-source vulnerability in peroxide additive supply creates structural risk for XLPE compound production. Distribution runs through utility-approved vendor panels and regional distributor networks with localized copper sourcing advantages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by grid modernization capital cycles, with utility tender volumes accelerating as national electrification targets compress replacement schedules across Indian and Southeast Asian state electricity boards.
For Market Incumbents: Secure backward integration into cross-linking peroxide additive supply or captive compound formulation capabilities to defend margin position against raw material volatility. Anchor procurement influence through IEC 60502 qualification histories and BIS certification maintenance, while expanding certified installer networks to capture unbundled commissioning contracts.
For New Entrants and Emerging Players: Lead with greenfield production investment in Vietnamese or Indonesian manufacturing corridors where localized supply deficits create tender eligibility windows. Target medium-voltage XLPE segments in urban electrification zones, emphasizing REACH-compliant sheathing formulations and shortened qualification timelines through pre-certification partnerships.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded cable manufacturing assets lacking compound-to-cable integration. Long-term viability hinges on qualification moats rather than scale economics, with acquisition focus on mid-tier manufacturers holding BIS pre-approval or IEC 60502 test histories. Watch for inflection when utility vendor panel contraction accelerates beyond current 30-40% reduction rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compound Formulation | Captive XLPE production secures utility tender eligibility against peroxide supply disruption. |
| Greenfield Capacity in Southeast Asia | Localized supply addresses Indonesian and Vietnamese manufacturing corridor deficits. |
| Certified Installer Network Expansion | Third-party jointing expertise captures unbundled EPC commissioning contracts. |
| REACH-Compliant Sheathing Reformulation | ECHA additive transparency rules filter European vendor pools toward qualified manufacturers. |
| Digital Substation Integration Partnerships | Fiber-optic sensing convergence enables predictive maintenance service revenue streams. |
Research Methodology
Operator-level perspectives from utility procurement officers, EPC contractors, cable manufacturing plant managers, and high-voltage commissioning technicians anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through IEC standards documentation, BIS certification registries, ECHA REACH substance databases, and utility tender archives. Customs trade data and copper concentrate import records provided material flow triangulation. Bottom-up shipment estimates from regional manufacturing clusters were cross-checked against top-down utility capital expenditure disclosures.
Sensitivity analysis tested forecast robustness across copper price scenarios, grid investment policy shifts, and qualification timeline variations. The analytical framework modeled volume and value projections across voltage tier segments, conductor material systems, and end-use applications throughout the forecast period. CAGRs were derived from trend extrapolation of utility tender volumes, renewable interconnection project pipelines, and manufacturing capacity expansion announcements. Industry-specific inputs included XLPE displacement rates from PVC infrastructure and peroxide additive supply elasticity assumptions.
Underlying assumptions cover sustained grid modernization capital allocation, stable REACH enforcement trajectories, and uninterrupted copper concentrate trade flows, with deviation risk concentrated in commodity price volatility and regulatory approval delays. Forecasts reflect these documented assumptions. Revision becomes warranted when utility vendor panel contraction accelerates beyond historical rates or when aluminum alloy conductivity improvements breach 220kV technical barriers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Asia-Pacific Premise Cable Market
Cables
India Wire and Cable Market
Cables
Cable Management System Market
Cables
Hybrid Cables Market
Cables
Ethernet Converters Market
Cables
Sensing Cable Market
Cables
Japan Cables Market
Cables
Premise Cable Market
Cables
GCC Cable Accessories Market
Cables
Cable Tray Market
Cables
Wire and Cable Materials Market
Cables
Data Center Wire and Cable Market
Cables
North America HVAC Cables Market
Cables
High-Speed Interconnects Market
Cables
Water Leak Sensing Cable Market
Cables
US Medium Voltage Cable Accessories Market